Insurers increase scrutiny of older commercial building roofs

Insurers increase scrutiny of older commercial building roofs

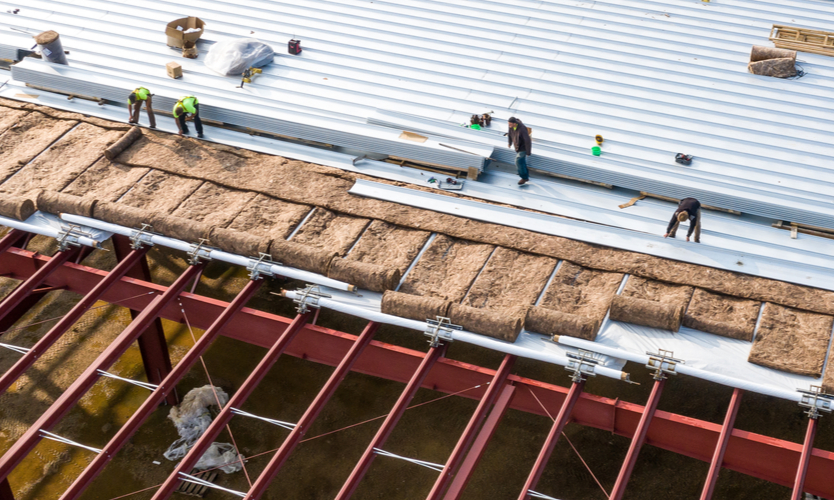
Insurers are growing their scrutiny of the age and affliction of professional setting up roofs and imposing extra restrictive terms under property procedures, authorities say.

Industrial properties with more mature roofs that haven’t been up to date and individuals positioned in areas uncovered to windstorms, severe convective storms and wildfires are observing insurance policy protection for roof hurt limited by policy provisions, they say.

And protection restrictions have accelerated in the wake of several named windstorms, tornados and hail events in new yrs, in accordance to a number of brokers.

Properties situated in the south Florida tri-county area, comprising Broward, Miami-Dade and Palm Beach front counties, are looking at the most restrictive roof protection in guidelines, explained Jeff Buyze, Fort Lauderdale, Florida-centered nationwide house apply chief at USI Insurance policy Solutions LLC.

Improvements involve covering more mature roofs on a depreciated, genuine money benefit basis rather than on a substitution price tag foundation, Mr. Buyze stated. Originally, this applied to roofs that have been more than 15 yrs previous, but insurers are now restricting payouts to true money worth on properties with roofs that are just 5 many years previous, he claimed.

The definition of roof masking has also broadened to contain roof decking, so that any harm to decking falls less than the estimate on roof covering, he claimed.

“Picture a 10,000-sq.-foot industrial authentic estate making. … The delta between substitute expense and real dollars benefit is fairly typically significant. You could be conversing about hundreds of countless numbers of pounds,” Mr. Buyze reported.

Occupancy classes looking at a lot more restrictive roof terms involve habitational accounts and community entity organization, especially municipalities and faculty districts, explained Peter Fallon, national house exercise leader at brokerage Hazard Strategies Co. Inc. in Boston.

“It’s people accounts where by … they just have not put the funds into the maintenance to make confident their roofs can endure hail and wind injury, so underwriters are indicating, ‘We are heading to have to do some thing,’” Mr. Fallon said.

Tighter roof terms are impacting admitted as perfectly as non-admitted hazards, he explained. “We’re viewing it in the regular market place, as well,” he reported.

Improvements tend to be dependent on roof age, specifically all those that are much more than 15 years outdated, Mr. Fallon reported. Where by protection applies on an real money value basis, insurers may also impose a surcharge and a better deductible, he claimed. Insurers may perhaps also include component deductibles to reflect an supplemental exposure these types of as water injury, he mentioned.

Underwriting scrutiny dependent on roof components is a emphasis in areas uncovered to windstorm, hail and wildfire, explained Michael Korn, world-wide property and maritime leader at EPIC Coverage Brokers in San Francisco.

In the circumstance of wildfire, underwriters are involved that embers can travel miles from a wildfire and land on a combustible roof and commence a hearth in a different spot, Mr. Korn mentioned.

Many roofs on buildings in California are created of wooden or with shingles, he said.

Valuations are escalating to assistance include the growing prices of roofs and to guarantee properties are insured to value sufficiently, said Randy Doss, Houston-based senior broker at CRC Insurance plan Providers Inc.

“Let’s say the norm 5 many years back was $65 a square foot for frame buildings. Nowadays they’re up to $100 or $110 for each sq. foot for body buildings to variety of offset some of those roof prices,” Mr. Doss claimed.

Variants in setting up codes in diverse states and difficulties with roofing contractors in certain states could possibly also affect the terms that are obtainable, he reported.

Values general have develop into a focal issue for the market place, precisely on roofs in high-hazard zones that are subject matter to the vagaries of wind, rain and h2o injury, said Henry Daar, Chicago-primarily based executive vice president and head of home statements at Willis Towers Watson PLC.

“Carriers don’t want to pay for the exact detail 2 times or a few instances,” Mr. Daar claimed.

In the scenario of a roof that has been beforehand subject matter to reduction but has not been fixed, insurers will both exclude from coverage pre-existing unrepaired damage or restrict what they cover to a share of the hurt, he claimed.

Other clauses restrict the quantity insurers will shell out out for so-named beauty hurt to a roof — for illustration if a hailstorm benefits in pock marks but is not identified to have triggered reduction of structural integrity, he said.

Roof statements can be expensive and based on the roof composition and constructing construction run the gamut anywhere from a $25,000 reduction to a $5 million loss, Mr. Daar stated.


Personal finance course to be required in the future for SC students to graduate high school

Personal finance course to be required in the future for SC students to graduate high school

COLUMBIA, S.C. (WIS) – To graduate high college, college students in all probability experienced to understand the Pythagorean Theorem, memorize the three branches of govt and their features, and read through a tiny Shakespeare.

But in the long run, South Carolina college students will also need to study skills like handling credit cards and submitting taxes to get their diplomas.

This impending necessity to consider a own finance course arrives soon after a multi-yr, bipartisan force at the Condition Dwelling to make certain South Carolina students are financially literate and well prepared for life soon after superior faculty.

“I consider it’s so critical to test to train some of these fundamental capabilities to these youngsters as soon as they can, so they just get off on the proper foot,” Monthly bill Joy stated.

Pleasure teaches a particular finance course at Lucy Beckham Substantial College in Mount Nice, wherever students have to acquire the system in their sophomore yr.

His lessons address units on budgeting, checking, financial savings, and much more.

“We truly educate kids how to prepare taxes, and essentially some of those people children have gone on to get ready taxes for their dad and mom. So, these are the style of type of lifestyle capabilities that I think are definitely worthwhile,” Pleasure mentioned.

Shortly, all South Carolina substantial schoolers will have to understand these competencies to graduate.

A legislation penned into the recent condition budget directs the South Carolina Section of Education and learning to establish the polices for a required substantial faculty course in particular finance by the end of September, to be authorised by the State Board of Instruction.

“We all comprehend our students want this. They will need the basis and the qualifications understanding and the schema and the fiscal literacy, somewhat than finding it out when it’s as well late,” David Mathis, the deputy superintendent for SCDE’s Division of School and Job Readiness, mentioned.

Individuals rules incorporate how the 50 percent-credit rating need will in shape in with the 24 credits essential to graduate and which graduating class will be the initial that will have to move the training course to make their diplomas.

Mathis stated they want to be equipped to provide distinctive selections for students to entire this necessity, which could incorporate getting the study course just about, as an elective, or as component of their profession and technology education and learning prerequisite.

The new individual finance prerequisite will not be in spot for the future university 12 months, as Mathis explained it could just take all over a 12 months just to build the study course benchmarks.

“Once that is carried out, we have to establish the coursework close to that. We have to safe elements and sources that districts can opt for from,” Mathis said.

The Section of Instruction will also have to perform in time for experienced progress and to practice academics on the new program.

But at the very least just one instructor, Pleasure, claimed it is truly worth it.

“Everybody dwelling in the state, I seriously imagine it is going to far better put together our young children to deal responsibly with funds,” Pleasure said.

Particular finance is a necessary course to graduate high university in far more than a dozen states, which includes most in the southeast.

Among the neighboring states, North Carolina by now has a own finance necessity in put, while Ga just passed a law this yr introducing it.

Copyright 2022 WIS. All legal rights reserved.

Discover a spelling or grammar error in this post? Simply click or faucet below to report it. Please include things like the article’s headline.

Survival: How to maintain a finance career when the market turns

Survival: How to maintain a finance career when the market turns

Roy Cohen has noticed a couple of cycles. As a vice president on Wall Avenue, he was all around for the 1987 sector crash. He was there for LTCM and the Asian disaster. And he was a professions coach at Goldman Sachs in New York Town throughout 2008. If you want to survive what may possibly or may well not be coming in Q4 2022, Cohen is nicely-put to dispense tips.

His essential to survival? Put together the ground. “If it really is the conclusion of the yr, and you might be only just contemplating about how to maintain your work and how to get promoted, then very good luck,” states Cohen. “You will need to be creating your reputation and your network above time.”

If financial institutions make cuts right after Labor Working day as Ken Moelis predicts, Cohen suggests you act now to set up the variables that could possibly put a goal on your again. Really don’t go to HR for these, he states: they will not be frank. Go to colleagues and administrators, to folks who function with you and for you. “You have to have to go out there with this concept,” suggests Cohen, “- I definitely like what I do, I am dedicated to achievements and I want to remain in this function. Do you have any tips on what I can do to enhance?”  

As we observed before, senior men and women in banking do not keep again when it will come to expanding upon their own achievements. Running administrators at Goldman Sachs have historically had no situation with describing them selves employing superlatives.  If other people are referring to on their own as “remarkable,” do you want to be regarded as just “fantastic”? Lay the groundwork now.

The other adjustment to make forward of time concerns individual paying out. Just one monetary advisor who used a 10 years operating as a trader for US and European financial investment banking companies claims it’s essential to get a grip on your own outgoings. “The greatest oversight that persons make in banking is to believe that their revenue will improve exponentially,” he tells us. “They begin out earning £100k, it rises to £1m in 10 years and they increase their private paying appropriately. They then find on their own in a massively tricky place when their position is produced redundant.”

Do not become habituated to higher paying. “After you are applied to travelling company class and being in five-star accommodations, it turns into particularly challenging to go downmarket,” suggests the trader. “You get trapped in high paying routines and you really don’t help you save or invest adequate for the upcoming.” 

If you have price savings, you can expect to have a broader array of vocation possibilities when the market turns. When Shahzad Younas labored as a portfolio trader for Morgan Stanley, he saved as considerably as he could. “I was by no means a huge spender,” explained Younas. Though colleagues splashed out on personal colleges and huge properties, Younas reported he lived modestly and paid down his debts: “I would saved simply because I wasn’t absolutely sure when I would future have an earnings.” Those people price savings enabled him to leave Morgan Stanley and to established up Muzz, a Muslim dating site backed by Y Combinator, which he aspires to flip into a unicorn.

Preserving your financial products and services occupation can signify earning judicious moves into work flourishing at that place in the cycle (eg. from investing to digital marketplaces to investing once more). If you happen to be going for knee-jerk monetary good reasons, you are going to be a lot less in a position to pick out roles presenting longevity of both earnings and potential. “If you have no savings and incredibly higher set prices, you’ll will need to take the first matter that comes your way,” states the ex-trader. “I am only capable to be a economic advisor now mainly because I am economical free of charge,” he claims. “For me this is a passion, and it pays, but I also have investments that far more than take care of my residing expenditures.” 

This is the correct evaluate of profession results, he claims: “You want to be able to do what you want to do, when you want to do it.” It can take scheduling. 

Picture by Tim King on Unsplash

Click on right here to generate a profile on eFinancialCareers. Make yourself seen to recruiters employing for positions all over the cycle. 

Have a confidential tale, tip, or remark you’d like to share? Speak to: sbutcher@efinancialcareers.com in the very first occasion. Whatsapp/Sign/Telegram also offered (Telegram: @SarahButcher)

Bear with us if you leave a remark at the base of this report: all our responses are moderated by human beings. At times these individuals may well be asleep, or away from their desks, so it may perhaps get a though for your comment to appear. At some point it will – until it’s offensive or libelous (in which situation it won’t.)

Calif. committees pass bills to expand COVID presumption

Calif. committees pass bills to expand COVID presumption

California legislative committees on Thursday and Friday handed costs that would lower the time employers have to settle for legal responsibility on some employees compensation claims and extend for another two several years COVID-19 presumptions.

The Assembly Appropriations Committee on Thursday handed S.B. 1127, would lessen to 75 times from 90 times the time companies have to accept legal responsibility on statements for certain accidents that are presumed compensable.

The invoice would also produce a new penalty of up to $50,000 if the Workers’ Payment Appeals Board concludes an employer unreasonably denied a claim for a presumptive injury. The evaluate would also permit firefighters and police officers to obtain up to 240 months of short term disability added benefits for presumptive most cancers promises, instead than the 104 compensable weeks of TD offered to other hurt staff.

Proponents say the invoice will “revise unreasonable denial penalty provisions that had been gutted through the brinksmanship reforms of 2004” and crack down obstructions in the workers payment procedure that were being “artificially manufactured in the hope that the injured worker will settle for fewer than their claim is well worth,” according to a invoice examination.

The assessment says the monthly bill will probable have a major boost on the Division of Workers’ Compensation’s funds, but the extent is undeterminable. Judges would very likely encounter increased workloads to adjudicate penalty disputes, the examination states. And it is challenging to undertaking penalty profits simply because the DWC “is not knowledgeable of proof of conclusions that unreasonable rejections of legal responsibility for claims are major to an unreasonable hold off of gains.”

The California Workers’ Compensation Institute in July introduced an assessment of the measure that suggested it could lead to far more denials and litigation on complex cases.

“Provisional denials because of to the incapability to receive required medical data, full the clinical-legal course of action, and other concerns, which include lack of cooperation with the investigation, will result in far more litigation as properly as major will increase in allotted and unallocated reduction adjustment charges linked to the investigation time period,” CWCI said.

CWCI also said some provisions in the bill are in immediate conflict with one more evaluate prior to lawmakers this year that would extend COVID-19 presumptions enacted in 2020.

Below A.B. 1751, which Senate Appropriations Committee handed on Thursday, companies would have 30 times to accept legal responsibility for COVID-19 promises submitted by initial responders, nurses and other health care staff, and 45 times to take liability for statements by other staff.

That bill would also extend to Jan. 1, 2025, the sunset date for the COVID-19 provisions now slated to expire at the conclusion of this year.

WorkCompCentral is a sister publication of Company Insurance policy. Extra tales right here.


PERSONAL FINANCE: Life insurance needs can change over time | Business

PERSONAL FINANCE: Life insurance needs can change over time | Business

It is simple for numerous of us to strategy lifetime insurance plan with a “I’ll handle that later” or a “set it and overlook it” mentality, and to suppose that you have time to sort out the facts of ample protection down the street. Yet, lifestyle insurance policy can enjoy a critical role in defending your cherished kinds financially really should you go away unexpectedly. The function safety performs in your monetary system frequently depends on your everyday living phase.

Newly married partners

More mature older people nearing or in retirement

Holley Smaldone-Cragg, CMFC, is a Money Advisor with Ameriprise Economical in Geneva. She specializes in payment-centered monetary planning and asset management techniques and has been in follow for over 35 decades. Her web-site is ameripriseadvisors.com/holley.com.

When Is Travel Insurance Worth It?

When Is Travel Insurance Worth It?

Now that Americans returning to the U.S. from abroad are no longer required to test for COVID-19 before boarding a plane, you might be wondering whether to pay up to insure your trip. Travel insurance often seems like an unnecessary cost, particularly when fares are refundable or you don’t have to pay a change fee. But there are situations when you must have it, as well as times when it’s not required but is worth paying for.

What Travel Insurance Covers

Some credit cards provide insurance, but the coverage is limited. By contrast, comprehensive travel insurance policies cover a wide range of expenses. A comprehensive travel policy typically covers damage to rental cars, trip cancellation, lost baggage and medical expenses when you’re abroad.

Most comprehensive travel insurance policies now also include cancellation and medical benefits related to contracting COVID-19. But for other COVID-related concerns, such as border closures, quarantine restrictions or fear of contracting coronavirus, you’ll likely have to pay for what’s called a “cancel for any reason,” or CFAR, upgrade. CFAR travel insurance can tack on an additional 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to the cost of travel insurance, but it offers better protection for travelers facing the kinds of interruptions that the pandemic has made commonplace.

Some plans with quarantine coverage will also pay some expenses if you have to stay in place for additional days. Coverage is typically limited; for example, you might be reimbursed $200 per day for two additional days of lodging if you’re required to quarantine abroad.

How Much Travel Insurance Costs

On average, a travel insurance policy costs $248, according to data from SquareMouth, a travel insurance comparison site. But the amount you pay for a policy depends on a number of factors—the length of your trip, the number of travelers you need to insure, and even how old you are. A better estimate is 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 11{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the total cost of a trip, experts say. You can compare plans at SquareMouth or TravelInsurance. Choose coverages that make sense for your trip, and be sure to read the fine print of any policy you consider.

Travel insurance policies generally fall into one of three tiers: basic, middle-tier and comprehensive coverage. Although basic is often the most affordable option and includes benefits such as trip cancellation and lost baggage coverage, it may require that you pay a deductible in the event of sickness or injury. Middle-tier coverage typically includes the same benefits as basic policies but adds a health insurance benefit. A more expensive, comprehensive policy may include the benefits of basic or middle-tier policies, but with a higher claim limit. Basic coverage rates average about $105, while middle-tier and comprehensive coverage average about $130 and $164, respectively, according to data from BankRate, a financial website. If you want a CFAR policy, too, that’ll be on top of those costs.

Because older travelers are generally at higher risk of health problems, policies tend to be more expensive the older you are. A 2021 analysis conducted by AdvisorSmith, a small business resource website, estimated that average prices differed from a low of $92 for a young child to a high of $805 for a 100-year-old person. The difference between a 40-year-old’s and 70-year-old’s average cost of travel insurance may come to about $100. But that doesn’t mean older folks can’t find affordable policies; shopping around and comparing plans is key.

When to Buy Travel Insurance

As of June 12, 2022, travelers returning to the U.S. no longer need to test negative for COVID in order to reenter the country, alleviating fears of being stuck in a foreign country longer than planned. But the Centers for Disease Control and Prevention advises anyone experiencing COVID-like symptoms not to travel. And there are other times when opting for travel insurance is worth the cost.

If you are concerned about severe weather upending your trip, about a possible unexpected health incident involving you or a family member, a terrorist attack, or even losing your job, travel insurance policies with basic trip cancellation coverage often cover those reasons for cancelling.

If you are traveling to a destination that has a history of more stringent COVID-related travel restrictions or has had other COVID-related concerns, consider a cancel-for-any-reason policy. Be sure to check the travel restrictions for any countries you are traveling to regularly; some countries are still requiring travel insurance in order to visit.

Plus, there’s no guarantee that the U.S. waiver of COVID testing for air travelers returning from abroad is permanent. The testing requirement is set to be reviewed again on September 10, 90 days after it was lifted. It could be reinstated if there is a new COVID variant of concern—and the highly transmissible BA.5 subvariant of the virus has been a growing threat.

When to Skip Travel Insurance

Whether to pay for a travel insurance policy and what level of coverage you get depends on your personal risk tolerance, of course. But it also depends on whether you’ll have to pay a lot out of pocket if you have to cancel or postpone your plans.

If you’re mainly worried about losing money on costly international flights, for instance, think again before you pay to insure them. That also goes for travel insurance plans offered at checkout when purchasing a plane or train ticket. Although it may seem like a small expense in exchange for the added flexibility, keep in mind that most airfares already have built-in flexibility.

Major U.S. airlines made permanent changes during the pandemic, allowing flexible bookings for most tickets. That means you won’t have to pay a fee if you need to change your flight—as long as you don’t buy the cheapest fares (Southwest allows free changes for all tickets). Also, some travel providers offer flexibility on bookings made within a certain time. For instance, the major airlines and Amtrak offer a refund in the first 24 hours after a booking if you have to cancel or change your itinerary.

Also, when an airline cancels your trip—as long as the flight is arriving at and/or departing from a U.S. airport—you are legally entitled to a refund, per U.S. Department of Transportation regulations. An airline will often automatically issue a credit or voucher for a cancelled flight, but be sure to request a refund if that is what you would prefer, as is your right. Also, if there has been a substantial schedule change (typically of two hours or more) and you decide not to take that flight, you are entitled to a refund of your fare.