What is extended replacement cost for homeowners insurance?

What is extended replacement cost for homeowners insurance?

Our goal here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” below, is to give you the tools and confidence you need to improve your finances. Although we do promote products from our partner lenders who compensate us for our services, all opinions are our own.
Extended replacement cost coverage is an optional add-on to your homeowners policy that covers unexpected increases in building labor and materials costs. (Shutterstock)

When you buy homeowners insurance, the dwelling coverage portion of your policy helps you pay to rebuild your home if it’s damaged by a covered event, such as a fire.

But is your current dwelling coverage limit really enough to rebuild your home if it’s completely destroyed? In times of rising demand for materials and labor, it might not be. Fortunately, you can purchase an extended replacement cost endorsement to ensure you’re financially protected from unexpected cost increases.

With Credible, you can easily compare homeowners insurance rates from top insurance carriers.

What is extended replacement cost?

Extended replacement cost is an endorsement to your homeowners insurance policy that changes the terms of the original policy. It provides an extra layer of protection in case you need to rebuild your home due to damage by fire, a severe storm, or another covered disaster.

Extended replacement cost increases your policy’s dwelling coverage limit by an extra 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the cost to rebuild your home. The extra coverage does come with an extra cost, but it could be well worth the additional premium if you live in a high-risk area or building or material costs are rising rapidly.

WHAT IS A HOMEOWNERS INSURANCE PREMIUM?

How does extended replacement cost work?

Many insurance carriers offer extended replacement cost coverage as an add-on to your standard homeowners insurance policy. They typically offer it in increments, as a percentage of your normal dwelling coverage limit.

For example, let’s say your home is insured for $250,000 when it’s leveled by a wildfire. Every homeowner in your community who lost their home during the fire needs to rebuild, so the demand for labor and materials rises, bringing extra costs along with it.

If it costs $275,000 to rebuild your home rather than $250,000, you’d have to come up with the difference yourself under standard replacement cost coverage. But if you have extended replacement cost coverage that adds another 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of coverage, your new coverage amount is $312,500 ($250,000 x 1.25). That’s more than enough to cover the cost of rebuilding your home.

What does extended replacement cost cover?

Extended replacement cost covers the additional costs associated with rebuilding your home after it’s been damaged or destroyed, if the loss is greater than 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your coverage limits.

It’s important to note that extended replacement cost only impacts Coverage A (dwelling coverage), which pertains to damage to your house. It doesn’t increase limits for other types of coverage that are normally included in a homeowners insurance policy, such as:

  • Coverage B — Other structures, like a detached garage or shed
  • Coverage C — Personal property, including household furnishings and personal belongings
  • Coverage D — Additional living expenses when you can’t live in your home due to a covered loss

Any additional costs above coverage in these areas are still your responsibility as the homeowner.

Visit Credible to get homeowners insurance quotes from multiple carriers in minutes.

Do you need extended replacement cost coverage?

So, how do you know if it makes sense to add extended replacement cost coverage to your homeowners insurance policy? The following questions can help you decide:

  • Do you live in an area that’s prone to natural disasters? Paying the extra premium for extended replacement cost coverage usually makes sense for people who live in areas that are prone to natural disasters, such as hurricanes, tornadoes, earthquakes, and wildfires. In these areas, there’s a higher risk of having a large number of homes in the area severely damaged or destroyed, which temporarily drives up the cost of building materials and labor.
  • In the event of a major loss, will you urgently need to rebuild? If the home in question is a vacation home, then you may not need to worry about rebuilding as quickly as possible. You can wait until rebuilding costs return to normal levels without disrupting your daily life. On the other hand, if it’s your primary residence and a major loss would leave you without a place to live, then extended replacement cost coverage can help you rebuild as quickly as possible.
  • How financially secure are you? Wealthy homeowners might be willing to accept more risk, knowing they can cover uninsured losses out of their own savings. But if coming up with an additional $25,000 to $50,000 or more to rebuild your home would cause a significant financial hardship, then paying a little extra for extended replacement cost coverage might be worth it.
  • Are construction prices rising? Global supply chain and labor shortages can drive up construction prices, even if you’re not in an area impacted by a natural disaster. Adding extended replacement cost coverage can give you peace of mind that when building costs are spiraling, you’re not responsible for covering the difference between your policy limits and construction costs in the event of a total loss.

How to determine your coverage limit for extended replacement cost

The easiest way to determine your coverage limits — both for your ordinary coverage and extended replacement cost coverage — is to work with an experienced insurance agent.

But you can also come up with your own estimates to get some peace of mind. To estimate the replacement cost of your home, multiply your total square footage by local per-square-footage building costs.

New-home construction costs average $100 to $200 per square foot, according to HomeAdvisor. If you have a 1,700-square-foot home, the cost of rebuilding could run anywhere from $170,000 to $340,000. Of course, those are based on national averages, so it’s a good idea to get localized building cost estimates from a real estate agent, insurance agent, or builders association in your community.

Once you know the replacement cost, you can multiply it by 1.10 to 1.50 (depending on the extended replacement cost you want) to determine your extended replacement cost coverage limit.

And keep in mind, you may need higher limits if you have granite countertops, custom cabinetry, hardwood flooring, marble tile, a solar roof, smart systems, eco-friendly materials, and other high-end finishes.

Other factors that can impact the replacement cost of your home include:

  • The age of the home (older homes may have moldings and carvings that are expensive to re-create)
  • The number of floors (two- or three-story homes are usually more expensive to rebuild than single-story homes)
  • The number of rooms and bathrooms
  • Exterior wall construction materials, such as siding, stucco, brick, stone, or veneer
  • The type of roof and roofing materials used
  • The age and type of heating, air conditioning, and ventilation systems
  • Home improvements or renovations
  • Other structures on the property, such as garages, sheds, and fences
  • Special features such as fireplaces, arched windows, built-ins and other custom fixtures

WHAT IS HIGH-VALUE HOME INSURANCE AND WHO NEEDS IT?

Extended replacement cost vs. other coverage options

When you buy a home, other coverage options determine the actual value of the protection you receive and affect the price of the insurance policy. Let’s look at each of these options in detail:

  • Market value — Market value is the price you could sell your home for on the open market. When you bought your home — assuming you purchased the property from an unrelated seller who wasn’t facing undue pressure to sell the home — you paid its market value. The market value of your home is usually higher than the replacement cost, since you wouldn’t have to repurchase the land to rebuild your home after a fire. You can determine the market value of your home by getting a professional appraisal or speaking to a real estate agent.
  • Actual cash value — Actual cash value is a coverage option that pays the replacement cost minus any depreciation. If you have actual cash value coverage when a fire or another covered event destroys your home, the insurance adjuster will take into account the age and condition of the home’s walls, roof, flooring, lighting, and other components when deciding how much to pay out.
  • Standard replacement cost — Standard replacement cost policies cover the cost of rebuilding a property with materials of the same quality. With replacement cost, depreciation isn’t a factor. It’s important to note that if you have an older home, you may not be able to insure it for the replacement cost value. Your replacement cost can change over time, so it’s a good idea to review your coverage limits each year, and let your insurance agent know if you improve or upgrade your home. These changes can increase your home’s estimated replacement cost.
  • Guaranteed replacement cost — Some homeowners policies provide guaranteed replacement cost coverage, which pays the full cost of replacing the home, even if rebuilding exceeds policy limits.

How much does extended replacement coverage cost?

The cost of adding extended replacement cost coverage to your homeowners insurance policy varies depending on your insurance carrier, coverage limits, and where you live. But purchasing this coverage for a home in a coastal community or an area with a high wildfire risk can cost more.

WHAT’S THE AVERAGE COST OF HOMEOWNERS INSURANCE?

How to buy extended replacement cost coverage

If you’re interested in adding extended replacement cost coverage to your homeowners policy, reach out to your insurance agent to get a quote. They may be able to add the endorsement to your policy right away, or at your next renewal date.

Most major insurance providers offer extended replacement cost coverage. If yours doesn’t, it might be worth shopping around for other policies.

Credible makes comparison shopping for homeowners insurance easy. Get quotes from top insurance carriers, all in one place.

Davos Voices: What Leaders Say About Climate Change, War | Business News

Davos Voices: What Leaders Say About Climate Change, War | Business News

By PETER PRENGAMAN, KELVIN CHAN, HELENA ALVES, Involved Push

DAVOS, Switzerland (AP) — Corporate buzzwords. Technical jargon. Bold but imprecise pronouncements about local climate change and Russia’s war in Ukraine.

The Globe Financial Forum’s once-a-year collecting of CEOs and government leaders this week in Davos, the town in the Swiss Alps, may appear to be total of critical but impersonal bulletins.

So what do Davos-goers definitely imagine? Here are some voices from the assembly that ends Thursday:

WHAT ARE YOU Doing Individually TO Combat Local climate Change?

Political Cartoons on Globe Leaders

Political Cartoons

TITLE: Co-founder of LinkedIn

Residing in Los Angeles, Blue said his loved ones has gotten into the behavior of conserving h2o, as substantially of California and the Western United States has been in a megadrought for decades. They recycle, mostly try to eat vegetarian, and push an electrical car or truck.

“One of the items that has slowed the world’s reaction to local climate modify is that there was a tale out there that it was the behaviors of individuals that produced the big difference,” he stated. “It’s not.”

Fairly, he stated consumers’ possibilities are restricted when organizations only offer methods or goods that usually are not environmentally pleasant.

Suarez states his household has a Tesla and is placing solar panels on the roof of their dwelling.

“As a community official, I feel it is my obligation to do what I can.”

TITLE: The Earth Financial Forum’s Geneva-primarily based head of climate adjust policy

Gawel’s working day position is invested on environmental safety and combating local climate alter. Outdoors of function, Gawel commutes by bicycle, makes use of community transportation and educates her two children about the atmosphere.

“My small children are sort of the greatest advocates for these forms of issues now. And the issue that I have to say that I enjoy seeing is the universities are truly training them about this. My daughter, who is 8 several years outdated, is remaining taught about wind electricity, about solar, about the problems of fossil electricity.”

Gawel claims such concerns were being “completely not one thing that was on our curriculum, at least when I was developing up.”

HOW WILL THE RUSSIA-UKRAINE Crisis Modify THE Globe?

TITLE: CEO of Kuwait-primarily based National Aviation Providers

“The Russia-Ukraine crisis, I imagine, sends a strong concept to the world that the world will no more time accept aggression and war to fix problems,” El Houry mentioned.

He additional that “world also has to take that there are many aggressors around the world that have been undertaking what they’re doing for many years and many years and have gone unpunished. And we just can’t have a double standard exactly where we only one out Russia.”

“There’s matters taking place in the Center East each day, points going on in East Asia every single day in South The usa every single working day. And we have to have to shed the light-weight on all those as well and say ‘that requirements to stop.’ I’m not choosing sides. I’m just declaring that we want to remedy those people issues as effectively.”

Suarez claimed the war has exposed how interconnected the entire world is, from the workforce to power shocks to a looming food crisis because of dropped agricultural production from Ukraine.

“As leaders, we have the accountability to make all those connections for folks, clarify why what takes place in a person put can have an impact on a different and why we should really care.”

Copyright 2022 The Involved Press. All legal rights reserved. This content might not be printed, broadcast, rewritten or redistributed.

Ranking Member’s News | Newsroom

Ranking Member’s News | Newsroom

May 26,2022

Washington,
D.C.–
Senate
Finance Committee Republicans, led by Ranking Member Mike Crapo (R-Idaho),
wrote to Internal Revenue Service (IRS) Commissioner Chuck Rettig raising
concerns and questions about the IRS’s destruction of an estimated 30 million
paper-filed documents in March 2021 reportedly due to a backlog in processing
paper documents.  A Treasury Inspector General for Tax Administration
(TIGTA) report brought the IRS’s destruction of the paperwork to light.   

Despite
repeated requests from Congress for the IRS to exercise taxpayer penalty relief
due to pandemic-related problems, the agency never disclosed that among the
measures taken to reduce the backlog was the decision to destroy 30 million
information returns.  

From
the letter:  

“The
information disclosed in the May 4 TIGTA report has surprised many in Congress
and in the tax community.  The destruction of documents ensuring taxpayers
did not underreport income or inflate a deduction is concerning.  It also
raises questions about the IRS’s ability to administer the tax code and ensure
compliance.”    

The
senators ask the IRS to clarify the potential damage to tax administration this
destruction will cause, as well as who made the decision, how the IRS will
address the consequences this decision will have for taxpayers and the
potential harm to tax revenues. 

Read
the full letter, signed by all Senate
Finance Committee Republican members, below.

____________________________________
 

Dear Commissioner Rettig: 

We are writing you regarding disturbing information that
came to light in a report issued by the Treasury Inspector General for Tax
Administration (TIGTA) and has been referenced in several news accounts.
 TIGTA released the audit report, “A Service-Wide Strategy Is Needed to
Address Challenges Limiting Growth in Business Tax Return Electronic Filing” on
May 4, 2022.  The audit states: 

This audit was
initiated because the IRS’s continued inability to process backlogs of
paper-filed tax returns contributed to management’s decision to destroy an
estimated 30 million paper-filed information return documents in March
2021.  The IRS uses these documents to conduct post-processing compliance
matches to identify taxpayers who do not accurately report their income.   

This information is deeply concerning to many, especially in
the professional tax community. 

On March 17, 2022, in an appearance before the House Ways
and Means Committee, Subcommittee on Oversight on the 2022 Filing Season, you
were quoted as expecting the backlog of unprocessed tax returns to clear before
the end of 2022.  During that hearing you said, “As of today, barring any
unforeseen circumstances, if the world stays as it is today, we will be what we
call ‘healthy’ by the end of calendar year 2022, and enter the 2023 filing
season with normal inventories.”  In written testimony submitted to the
U.S. Senate Committee on Finance in April of 2022, you wrote:   

The IRS pursued
significant actions during the 2021 filing season to address the return and correspondence
inventory.  But due to resource issues and numerous unique factors tied to
new legislation and the pandemic, we have entered the 2022 filing season with a
significant inventory of unprocessed returns and correspondence…”   

Your statements in neither hearing suggest that the actions
taken to clear the backlog or the “significant actions” pursued benefitted from
the destruction of 30 million information returns. 

A Tax Notes article noted that during the period IRS was
destroying 30 million information returns and while the COVID pandemic harmed
millions of Americans, “it [the IRS] was imposing penalties for failing to file
timely and accurate information returns, which, for all anyone knows, may have
been among the documents destroyed.”  The document destruction also
happened during a time many called for the IRS to exercise penalty
relief.  Since the summer of 2020, the American Institute of Certified
Public Accountants (AICPA) has released at least seven letters or statements
calling for some form of penalty relief from the IRS.   

Senate Republicans also asked the IRS for taxpayer relief
due to the pandemic.  In a letter dated February 10, 2022 (the February
letter), many Senate Republicans, including all Republican members of the
Senate Finance Committee, sent a letter to Treasury Secretary Yellen and you
that says,  

While recognizing
the challenges the IRS currently operates under, we find the current situation
at the IRS alarming.  Given the current circumstances, we respectfully
request the IRS consider exercising its existing authority to undertake
measures to bring immediate relief to taxpayers and reduce backlogs, during
this tax filing season….   

Among other suggested solutions, the February letter asked
that the IRS “[c]ommunicate to the public, in a clear and timely manner, the
status of IRS operations, current processing times, levels of unopened mail,
number of error resolution cases, and dates to which mail, including paper and
amended returns, has been processed.”  It is concerning that despite
repeated requests from the tax professional community and Congress, the IRS
never disclosed that among the measures taken to reduce the backlog was the
decision to destroy 30 million information returns.   

The information disclosed in the May 4 TIGTA report has
surprised many in Congress and in the tax community.  The destruction of
documents ensuring taxpayers did not underreport income or inflate a deduction
is concerning.  It also raises questions about the IRS’s ability to
administer the tax code and ensure compliance.  In order to understand how
the destruction of 30 million information returns was allowed to happen and the
ramifications for taxpayers, we respectfully ask that you respond to the
following by June 5, 2022: 

  1. Please describe specifically what information return
    documents (e.g., 1099?MISC) were destroyed, exactly how many were
    destroyed, what tax periods the destroyed documents covered, how the
    documents were destroyed and how you complied with document retention
    requirements.
     
  2. Based on the most recent IRS
    analysis of the tax gap (2011-2013), 56 percent, or $245 billion, of the
    tax gap comes from underreporting by individuals.  Also, according to
    the IRS FY 2020 Budget and Performance plan, the Automated Underreporter
    system where information return matching happens had a return on
    investment of $25.80 for every $1 spent.  What is the estimated tax
    revenue lost because 30 million information returns were destroyed instead
    of processed?
     
  3. Did the IRS assess penalties against information return
    filers for failing to timely file or submit accurate information returns
    (e.g., 26 U.S.C. §§ 6721 or 6722) when the paper information returns were
    actually in the IRS’s possession and later destroyed?  If penalty waivers
    were provided for paper information returns, were they also waived for e?filed
    information returns?  If not, why was e-filing treated differently
    than paper filing?
     
  4. Please describe in detail any other instances when the
    IRS destroyed tax documents filed, as required by law, without processing
    them.
     
  5. Please provide the legal basis
    for this decision and describe how the conclusion was made to destroy the
    documents, and provide a copy of the risk assessment completed by the
    Small Business/Self-Employed Division that evaluates what the impact these
    missing information reporting documents would have on the IRS’s
    post-processing compliance activities.  Please note and document what
    specific IRS personnel were involved in the decision to destroy the
    information returns, the date of the final decision to destroy the
    returns, and the date at which the risk assessment began.
     
  6. Has the destruction of 30
    million information returns negatively affected the ability of qualifying
    taxpayers to receive the earned income tax credit or the ability to
    accurately record withholding amounts credited on a destroyed Form 1099?
         
  7. The May 4 TIGTA report suggests that after the conclusion of a
    tax year, the IRS is not able to process information returns for that year
    “because the system used to process these information returns is taken offline
    for programming…”Please confirm
    whether or not that suggestion is accurate and if it applies to all late or
    amended information returns filed after the conclusion of a tax year. 

Thank you for your attention to
this important matter. 

Cathedral Students place second in personal finance competition – Mississippi’s Best Community Newspaper

Cathedral Students place second in personal finance competition – Mississippi’s Best Community Newspaper

NATCHEZ —Gracie Harrigill, Ethan Weadock and JB Burrell impressed judges with their self-confident smiles, outgoing personalities, experienced-on the lookout enterprise attire and — most of all— their intelligence.

In April, the a few Cathedral Significant University seniors went to Hinds Neighborhood College or university to compete with much more than 20 teams statewide in the Mississippi Particular Finance Challenge, a state tutorial competition in economic literacy.

Cathedral hardly ever had a fiscal literacy course prior to this university year and it was the students’ 1st time competing towards extra skilled colleagues who experienced been in and received the levels of competition just before.

“We did not know what we ended up obtaining ourselves into,” Harrigill explained. “We were walking in blind.”

Even so, the trio turned heads when they took next spot. Their acquire acquired them each a $250 scholarship, medals and a banner for their school.

“We misplaced only to a staff (from Germantown Superior College) that took fourth put in the whole country previous calendar year,” Burrell explained.

They came to contend armed with half of a semester of knowledge their instructor Frances Daniel experienced drilled them on. They took a qualifying test in the classroom at Cathedral to get a place in the competitors at HCC. There, they experienced to give a presentation to the judges.

They were being offered a situation research, which was a paper packet of details about a fictitious family members and their own funds. From that, the trio introduced a approach to get the fictional young children by way of college and assistance their mother and father retire with revenue in the lender.

This presentation took up a substantial share of what teams ended up graded on, so the pupils focused their effort on that.

“We came in with assurance and when we walked in we shook their hands,” Weadock explained. “They informed us we have been the initial group to shake their arms. That blew my mind.”

Harrigrill claimed when she graduates from Cathedral, she plans to analyze enterprise administration and possibly finance or marketing and advertising at Louisiana Complex College with the target of possessing a authentic estate brokerage on the coastline.

Burrell mentioned he also programs to research at LA Tech and key in chemical engineering with a insignificant in entrepreneurship. He wishes to go to Silicon Valley and perform in a technological innovation occupation.

Weadock has other programs.

“As of now, I’m registered for pre-med at Mississippi Condition University,” he said. “I do have an fascination in enterprise and entrepreneurship immediately after using this class.”

The students stated 1 of the main good reasons they competed was to make Daniels very pleased and to retain the economical literacy and economics class likely.

“Honestly, I come to feel like it need to be necessary,” Burrell mentioned, introducing they each individual elected to get it. “We figured out so much stuff that we basically need to have to know, no subject what career you decide to go into.”

Rival fintechs Revolut and Wise are still recruiting

Rival fintechs Revolut and Wise are still recruiting

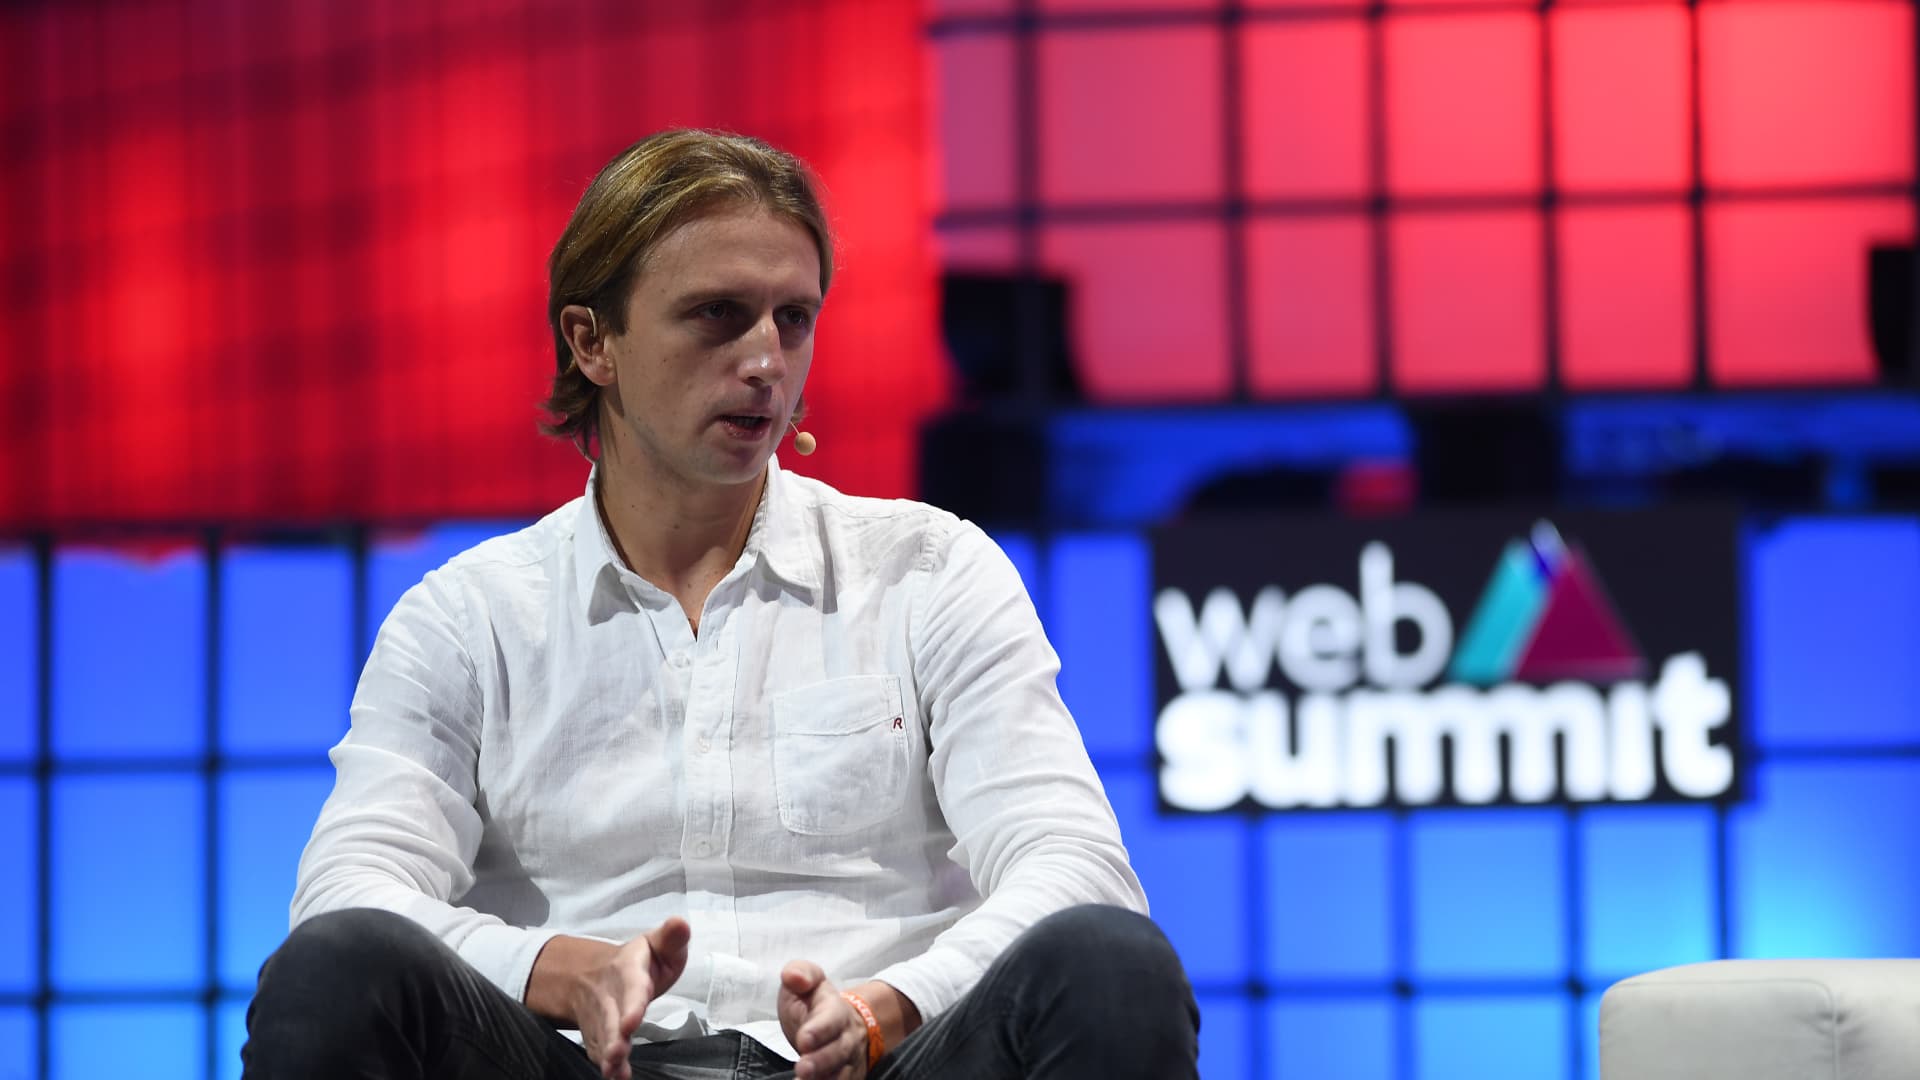
Nikolay Storonsky, founder and CEO of Revolut.

Harry Murphy | Sportsfile for Website Summit through Getty Illustrations or photos

Not all fintech unicorns are cutting work.

After Klarna introduced designs to lay off 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of its workforce Monday, some rival fintechs are producing it distinct that they have no intention of cutting work or freezing hiring.

Revolut, the $33 billion electronic banking begin-up, stated the company is “actively selecting,” with about 250 open roles listed on its internet site.

In the meantime, Smart CEO Kristo Kaarmann claimed the London-based mostly funds transfer business is in a “unique spot” to tech companies that are letting staff members go.

“Years of building Wise as a financially rewarding prolonged-phrase corporation is having to pay off now,” Kaarmann tweeted Wednesday.

“So considerably demand from customers for intercontinental banking, we won’t be able to use persons fast adequate to establish it.”

In the meantime, German digital financial institution N26 reported it has “no existing designs to reduce headcount.” The company was past valued at $9 billion.

“We are going to continue on to make strategic investments to increase our team with a emphasis on item, technological know-how, compliance and fiscal criminal offense avoidance,” an N26 spokesperson explained.

It marks a stark contrast with Klarna. The purchase now, spend afterwards firm — which allows buyers break up their buys into equal, regular monthly installments — reported it options to minimize an estimated 700 roles thanks to a souring financial local climate.

“When we established our enterprise ideas for 2022 in the autumn of last yr, it was a quite diverse world than the one particular we are in today,” Klarna CEO Sebastian Siemiatkowski advised team in a pre-recorded movie on Monday.

“Because then, we have noticed a tragic and unwanted war in Ukraine unfold, a change in consumer sentiment, a steep enhance in inflation, a highly unstable inventory marketplace and a probable recession.”

Other economical tech companies, these types of as Robinhood and Improved.com, have also taken actions to reduce jobs and rein in fees this calendar year.

Digital finance got a key strengthen from the Covid pandemic as individuals turned to online channels to make payments, apply for financial loans and trade shares. But the sector has taken a beating in 2022 as the war in Ukraine, increasing inflation and higher curiosity fees have led investors to question lofty valuations in the room.

Wise, for case in point, has misplaced nearly two thirds of its industry price considering that its July 2021 listing.

Rishi Khosla, CEO of U.K. online loan provider OakNorth, mentioned there have been “substantial bubbles” in fintech — from obtain now, fork out later on to crypto. He mentioned BNPL had been authorized to flourish mostly thanks to “regulatory arbitrage.”

“Finally, the regulation is heading to catch up with them, and therefore this the prospect is not likely to proceed,” he mentioned.

Klarna is reportedly in search of resources at a 34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} discount to its very last investment round, which valued the enterprise at $46 billion. A Klarna spokesperson dismissed this as speculation.

Asked whether or not Revolut strategies to observe match, a business spokesperson said it has no intention to do so.

Auto Services Group Limited, a Leading Provider of Digitalized Auto Services and Auto Insurance in China, Announces Merger Agreement with Goldenbridge Acquisition Limited to Become a Publicly Traded Company on Nasdaq

Auto Services Group Limited, a Leading Provider of Digitalized Auto Services and Auto Insurance in China, Announces Merger Agreement with Goldenbridge Acquisition Limited to Become a Publicly Traded Company on Nasdaq

Upon Completion of the Merger, the Merged Corporation is Predicted to Trade on Nasdaq

●     Vehicle Companies Team Minimal (“SunCar”) is a major company of digital platforms of comprehensive automotive products and services and market-broad car coverage solutions in China.

●     SunCar produced revenues of roughly US$250 million in 2021 (unaudited)1, and its income has a compounded annual development level of 32{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from 2015 to 2021. Revenues in 2021 improved by 4.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} comparing to those in 2020.

●     The proposed transactions value the combined company at an estimated company price on a professional-forma basis of about US$858 million, assuming no redemptions from the believe in account.

Shanghai, China, Might 26, 2022 (Globe NEWSWIRE) — Auto Solutions Group Constrained (“SunCar” or the “Company”), a primary service provider of digitalized automobile providers and car insurance by means of Sun Car On line Coverage Company Co., Ltd., an oblique bulk owned subsidiary in Shanghai, announced that on May well 23, 2022, it has entered into a definitive merger agreement (the “Merger Agreement”) for a company blend with Goldenbridge Acquisition Limited (“Goldenbridge”) (Nasdaq: GBRG, GBRGU, GBRGW, GBRGR), a British Virgin Islands particular reason acquisition corporation. On consummation of the transactions contemplated by the Merger Agreement, (i) Goldenbridge will reincorporate to the Cayman Islands by merging with SunCar Technologies Team Inc., a Cayman Islands exempted company and wholly owned subsidiary of Goldenbridge (“SunCar Know-how Group”), and (ii) concurrently, SunCar Engineering World-wide Inc. (“SunCar Technological innovation Global”), a Cayman Islands exempted firm and wholly owned subsidiary of SunCar Technological innovation Team, will be merged with and into SunCar, resulting in SunCar getting to be a wholly owned subsidiary of SunCar Technological know-how Group. Upon the closing of the transactions, the combined enterprise is expected to be Nasdaq-stated.

Founded in 2012, SunCar is a major supplier of electronic platforms of complete automotive expert services and marketplace-huge automobile coverage merchandise in China. The Firm supplies a person-halt, totally digitized, on-need automotive provider methods to help customers establish up their membership market and serve close consumers with higher buyer satisfaction. SunCar automobile solutions addresses in excess of 300 sorts of normal upkeep as perfectly as reserved expert services this kind of as car or truck wash, oil change, tire maintenance, motor vehicle beautification, road support, flight pickup, selected driving, VIP lounge, and many others. The Corporation also provides whole-spectrum automobile insurance policy goods by means of extremely successful insurance policy technologies apps.

SunCar has been lively in the automotive services sector for more than 10 years, attaining deep insights and powerful market understanding to differentiate and satisfy the increasing requires of motor vehicle homeowners all about China. The Company has designed up sustainable aggressive gain with a extensive B2B customer network of above 40,000 automobile service suppliers in in excess of 2,500 districts and counties, processing more than 76 million orders of products and services in the previous 5 years. The Enterprise has also engaged with in excess of 70 insurance plan organizations, building 6.2 million insurance coverage policies as a result of more than 47,000 product sales companions in the previous five many years.

All the services and insurance coverage insurance policies are processed via around 700 unbiased digital methods automatic by an close-to-stop system. The very secured SunCar Cloud and Multi-Tenant SaaS bear millions of transactions just about every thirty day period with productive and stable efficiency.

The Business constantly would make lengthy-time period investments in know-how and presents modular and revolutionary user experiences for its business clients as perfectly as their end buyers.

China’s automotive industry is escalating quick with strong tailwinds, leaving a substantial but remarkably fragmented right after-gross sales and vehicle insurance policies sector. SunCar performs an significant role in integrating, digitizing and redistributing the tailor-made support to each individual consumer in almost just about every corner of China.

With the immediate growth of electric powered motor vehicles (“EV”), the automotive business is shifting to a more powerful concentration on services practical experience by way of online electronic purposes. SunCar is now carefully engaging lots of emerging and proven players in the EV benefit chain to blaze a path in the emerging EV company industry.

Management Estimates

“With our core mission to search for a substantial-effects and technological know-how-driven company, I was incredibly happy to locate SunCar. We’re pretty amazed by the organization overall performance as perfectly as the systems supporting comprehensive on-demand from customers expert services and on-line insurance. Considering that the automotive marketplace is starting off to set additional emphasis on car or truck owner services, we think that SunCar is decided to expand more substantial in this substantial and attractive marketplace.” mentioned Yongsheng Liu, Chairman of Goldenbridge. “I glimpse forward to this partnership that will enable us to collaboratively create higher price for all.”

Ye Zaichang, founder of SunCar, commented: “SunCar has been growing with China’s automotive marketplace for a decade. We’ve turned our prosperity of insights and experience into technologies-driven solutions, encouraging our clients fulfill their close customers’ demand from customers with comprehensive on-demand products and services. Our modern insurance policy technology has distributed products from significant insurers to clients highly successfully. With the electrification of automotive field, SunCar has actively invested in and closely engaged with emerging and founded electric cars players to produce new company lines and excellent user experience. We are delighted to companion with Goldenbridge given that we share the similar visions about the marketplace and the technologies. We are very assured that the Goldenbridge workforce can assistance us understand our formidable small business vision and thrive in the prolonged run.”

Essential Transaction Terms

Underneath the phrases of the Merger Settlement, Goldenbridge’s wholly owned subsidiary, SunCar Technological know-how Group, will purchase SunCar Technological innovation Group, ensuing it staying a outlined organization on the Nasdaq Capital Industry. The present-day administration workforce of SunCar will carry on to operate the Business immediately after the transaction. Upon effectiveness of these types of transactions, SunCar’s shareholders and management (“SunCar Shareholders”) hope to acquire 80 million common shares of SunCar Technological innovation Group. Shares held by this kind of SunCar Shareholders will be issue to lock-up agreements for a period of time of 12 months next the date the transactions shut, matter to specific exceptions. Other than that, specified key individuals of the Company are suitable to receive more regular Shares matter to the Company reaching specified functionality milestones.

The proposed transactions contemplated by the Merger Agreement benefit the combined enterprise at an believed equity worth on a pro-forma basis of close to US$858 million, assuming no redemptions from the belief account.

The description of the transactions contained herein is only a summary and is skilled in its entirety by reference to the Merger Arrangement relating to the transactions, a copy of which will be furnished by Goldenbridge with the SEC as an exhibit to a Recent Report on Sort 8-K.

Advisors

Maxim Team LLC is acting as M&A and money advisor to Goldenbridge. Loeb & Loeb LLP is performing as legal advisor to Goldenbridge. Pryor Cashman LLP is performing as legal advisor to SunCar. Chain Stone Money Restricted (CTM) is acting as financial advisor to SunCar.

About SunCar

SunCar, together with its affiliates, deliver company shoppers with digitalized, extensive, on-demand and plug-in aftermarket automobile products and services and car insurance answers to greater serve their conclude prospects. Started in 2012, SunCar is now a leader in China’s car services marketplace. SunCar’s remedies and digital programs related more than 1,100 customers and 47,000 profits partners. The Organization engages with in excess of 40,000 suppliers and 70 coverage businesses, addresses about 2500 districts and counties, and serves stop clients in most cities in China. All the companies are dispersed at all times via around 700 sub-techniques on the SunCar Cloud, assisting its shoppers improved react to their customers’ needs.

About Goldenbridge Acquisition Restricted

Goldenbridge Acquisition Minimal is integrated in the British Virgin Islands as a blank test business for the function of entering into a merger, share exchange, asset acquisition, share invest in, recapitalization, reorganization or very similar business blend with one or more enterprises or entities. Goldenbridge’s initiatives to establish a potential concentrate on small business will not be confined to a specific sector or geographic location, even though Goldenbridge supposed to focus on opportunities in the artificial intelligence and any other related technological innovation improvements sector.

Forward-Looking Statements

This press release has, and particular oral statements designed by associates of Goldenbridge, SunCar, and their respective affiliate marketers, from time to time may well consist of, “forward-hunting statements” inside the meaning of the “safe harbor” provisions of the Non-public Securities Litigation Reform Act of 1995. Goldenbridge’s and SunCar’s real success may vary from their expectations, estimates and projections and consequently, you really should not count on these ahead-seeking statements as predictions of potential events. Phrases such as “aims,” “expect,” “estimate,” “project,” “budget,” “forecast,” “anticipate,” “intend,” “plan,” “may,” “will,” “could,” “should,” “believes,” “predicts,” “potential,” “might” and “continues,” and very similar expressions are intended to determine such forward-wanting statements. These ahead-searching statements consist of, without limitation, Goldenbridge’s and SunCar’s anticipations with regard to long run efficiency and anticipated fiscal impacts of the company blend, the gratification of the closing situations to the enterprise mix and the timing of the completion of the business enterprise mix. These ahead-seeking statements contain important risks and uncertainties that could trigger true results to differ materially from expected results. Most of these things are exterior the manage of Goldenbridge or SunCar and are complicated to forecast. Factors that might induce this sort of discrepancies incorporate, but are not limited to: (1) the occurrence of any function, adjust or other situations that could give rise to the termination of the Merger Settlement relating to the proposed small business combination (2) the outcome of any authorized proceedings that may be instituted towards Goldenbridge or SunCar adhering to the announcement of the Merger Agreement and the transactions contemplated therein (3) the inability to total the organization blend, including because of to failure to get acceptance of the shareholders of Goldenbridge or other situations to closing in the Merger Agreement (4) delays in acquiring or the lack of ability to receive important regulatory approvals needed to comprehensive the transactions contemplated by the Merger Settlement (5) the occurrence of any function, alter or other circumstance that could give increase to the termination of the Merger Arrangement or could in any other case bring about the transactions to fail to shut (6) the lack of ability to receive or keep the listing of the write-up-acquisition company’s standard shares on Nasdaq following the business enterprise mix (7) the chance that the business blend disrupts recent programs and functions as a end result of the announcement and consummation of the organization combination (8) the potential to figure out the expected positive aspects of the small business combination, which may perhaps be afflicted by, among the other matters, opposition, the means of the merged organization to improve and take care of growth profitably and retain its key staff members (9) charges similar to the company blend (10) alterations in applicable legal guidelines or rules (11) the possibility that SunCar or the merged business may perhaps be adversely impacted by other economic, company, and/or competitive aspects and (12) other threats and uncertainties to be discovered in a registration assertion on Kind F-4 (the “Form F-4”) to be filed by SunCar Technological innovation Team (when obtainable) relating to the business blend, which includes all those discovered less than the “Risk Factors” heading therein, and in other filings with the Securities and Exchange Commission (“SEC”) built by Goldenbridge and SunCar. Goldenbridge and SunCar warning that the foregoing record of factors is not distinctive. Goldenbridge and SunCar warning readers not to spot undue reliance upon any ahead-wanting statements, which talk only as of the date produced. Neither Goldenbridge or SunCar undertakes or accepts any obligation or endeavor to launch publicly any updates or revisions to any ahead-wanting statements to replicate any alter in their respective anticipations or any modify in occasions, problems or situations on which any such assertion is dependent, subject to relevant law. The info contained in any site referenced herein is not, and shall not be considered to be, aspect of or integrated into this push launch.

Crucial Data

SunCar Technological know-how Team Inc. (“SunCar Engineering Group”), Goldenbridge Acquisition Confined (“Goldenbridge”), and their respective directors, government officers and workforce and other individuals may possibly be deemed to be individuals in the solicitation of proxies from the holders of Goldenbridge’s everyday shares in respect of the proposed transactions described herein. Details about Goldenbridge’s directors and executive officers and their ownership of Goldenbridge’s common shares is set forth in Goldenbridge’s Annual Report on Type 10-K filed with the SEC, as modified or supplemented by any Variety 3 or Sort 4 submitted with the SEC considering the fact that the day of such submitting. Other data regarding the interests of the members in the proxy solicitation will be bundled in the Sort F-4 pertaining to the proposed transactions when it results in being obtainable. These paperwork can be acquired free of charge of charge from the resources indicated below.

In relationship with the transactions explained herein, SunCar Know-how Group will file appropriate materials with the SEC together with on the Form F-4. Promptly just after the Sort F-4 is declared efficient, Goldenbridge will mail the proxy statement/prospectus and a proxy card to every single stockholder entitled to vote at the unique meeting relating to the transaction. Traders AND Security HOLDERS OF GOLDENBRIDGE ARE URGED TO Go through THESE Supplies (Like ANY AMENDMENTS OR Health supplements THERETO) AND ANY OTHER Related Documents IN Connection WITH THE TRANSACTIONS THAT GOLDENBRIDGE/SUNCAR Technologies Group WILL FILE WITH THE SEC WHEN THEY Become Obtainable Simply because THEY WILL Include Important Information and facts ABOUT GOLDENBRIDGE, SUNCAR AND THE TRANSACTIONS. The proxy assertion/prospectus and other appropriate resources in link with the transactions (when they grow to be offered), and any other documents submitted by Goldenbridge with the SEC, could be received totally free of demand at the SEC’s website (www.sec.gov).

For inquiries with regards to SunCar, make sure you contact

SunCar
c/o: Shanghai Feiyou Trading Co., Ltd.
Lingshi Highway, No. 656, Suite 209
Shanghai, China
Attn: Ms. Li Chen
Electronic mail: chenli@4008801768.com

For inquiries regarding Goldenbridge Acquisition Limited, make sure you get hold of

Yongsheng Liu
Chief Govt Officer and Chairman
Goldenbridge Acquisition Confined
Tel: +86 (186) 0217-2929

1 In accordance to the unaudited economical statements of SunCar.