This platform is helping professionals understand personal finance in terms of time instead of money

This platform is helping professionals understand personal finance in terms of time instead of money

Working professionals now have substantial expectations and aspirations for the kind of lifestyle they want to lead. Workers these days are interested in talking about principles like early retirement and fiscal independence. But to make it legitimate, a selected amount of awareness and initiatives in the suitable path are necessary. Also, obtaining a crystal clear comprehending of how issues will pan out in phrases of time is really significant when it comes to being familiar with personalized finance.

On the other hand, neglecting conversations on individual finance and only hoping for the ideal can turn out to be even worse. Let’s encounter the simple fact- Payment/payment models by companies are deliberately structured to shell out the workforce accurately what it takes to retain them. But at the end of the working day, you cannot blame them. The dilemma is, how lengthy would 1 approach to perform with these organizations, battling to come across a very good operate-daily life balance.

There are ample and extra illustrations globally the place get the job done finishes up becoming one’s whole daily life and not a aspect of it. You just really don’t understand, and inside a blink of an eye, 1 yr gets to be five, and five gets to be 20. And lifetime goes on. Provided the present-day situation and awareness gap around personal finance training, it is not at all surprising that a broad the greater part in the US are not certain if they will ever have plenty of to sustain on their own if they were being to depart their not so fascinating however superior shelling out careers.

Consider if there was a way for you to figure out not only your web value but the precise holistic cost of your way of life, weaved with each other to variety a uncomplicated and comprehensive measure of your financial overall health. It could possibly seem like a thought from the long run, but ChroniFI would make this doable. In a complex planet of all factors materialistic, ChroniFI will help its buyers to plot their system to monetary independence and create a happy existence.

Even more to the pandemic, a rising range of operating experts have started to introspect about the actual reason of their everyday living. Men and women with average to substantial shelling out work opportunities are looking for a further feeling of objective. Amidst this acute behavioral change, conversations all-around the concept of private finance are at an all-time large.

ChroniFI offers intuitive functions that are missing in the market now: 

There are a good deal of firms with budgeting apps and numerous extra apps that are into investing and asset administration. The issue is that there are no strong gamers in the place of furnishing behavioral coaching in a private finance context. The present program has a big missing piece when it comes to instruction and educating end users about what own finance suggests together with its implications for their long run. On the other hand, ChroniFI focuses on the most essential element that is time, in its present context.

The system allows customers recognize how their possibilities, preferences, and actions proper now can influence their economical overall health. This crucial insight empowers them with the self-confidence that they need to make a practical and effectively-planned path to economic independence. Apparently, the insights are so thorough that users can assure they make the right choices with no compromising enjoyment along the way.

By carefully adhering to ChroniFI’s calculations, you can see just the place your latest job or the task you aspire to take fits into the context of your lifetime and what you want for it. All this information and facts aids you to simplify your existing position in the more substantial scheme of factors and appraise how significantly is enough and when is the proper time to move on for superior.

A number of several years back again, scheduling an early retirement was fully intuitive and experienced higher stakes. With the support of engineering, ChroniFI decreases the degree of uncertainty and danger noticeably. The user-helpful platform features a holistic dashboard with intuitive equipment that allows buyers to better fully grasp their finance. Users can examine comprehensive calculations in conditions of various variables these kinds of as their earnings, expenditures, and overall income move cycle to see if they are in alignment with their long term aims. In short, the platform simplifies a user’s fiscal wellbeing down to easy numbers expressed in models of time.

The platform has been developed for any individual who would like to are living a meaningful existence and enhance for time rather of dollars. Fundamentally, the technological innovation delivers a turnkey answer for expert pros who are determined to arrive at Economical Independence and Retire Early (Fire).

In contrast to other resources that only observe paying & predict a hypothetical portfolio development, ChroniFI adds benefit to the life of its people by analyzing their behavioral metrics. So, if a user needs to know the effect of a distinct shelling out pattern on their path to Fiscal Independence, ChroniFI has them coated.
Created in association with ChroniFI

New Zealand’s jobs law will cause ripples beyond its shores

New Zealand’s jobs law will cause ripples beyond its shores

The pandemic made one truth hard to ignore: the people we need the most are often the ones we value the least. While many people were furloughed or laid off during lockdowns, “essential workers” like drivers, carers and warehouse employees had to keep working because the economy couldn’t cope without them. Yet in many countries, these jobs are characterised by long or unpredictable hours, low pay and insecurity.

In New Zealand, a new law currently going through parliament aims to make bad jobs better. It represents a huge shift in the trajectory of the country’s labour market — one whose success or failure will have ripple effects on policy well beyond its shores.

New Zealand has long been a poster child for labour market deregulation. Sweeping reforms in 1991 dismantled the old system of national pay awards and led to a flexible economy with high employment rates by international standards. In 2020, the World Bank named New Zealand the easiest country out of 190 in which to do business. But productivity and wage growth have been weak. New Zealanders work longer hours than average in OECD countries but produce less per hour.

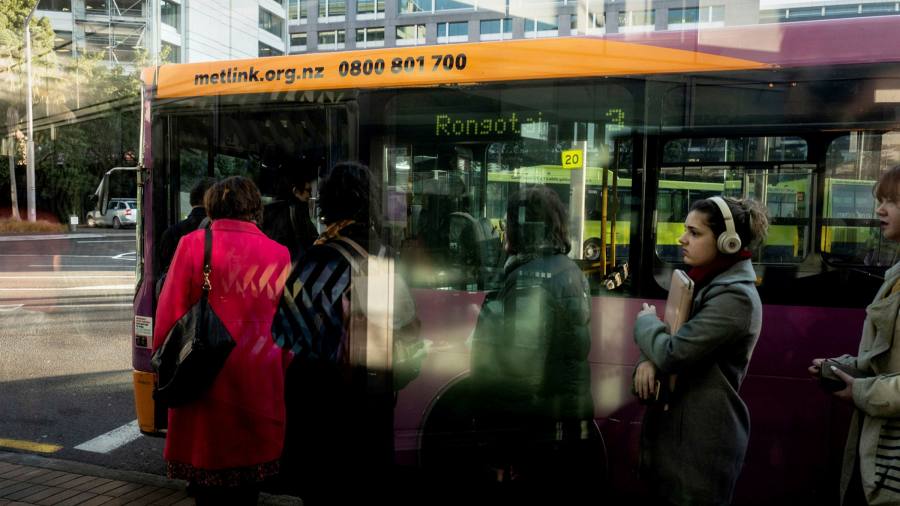
New Zealand’s Labour government believes part of the problem is that employers in some sectors have ended up in a “race to the bottom”. They are competing by cutting labour costs rather than improving quality or technology. Craig Renney, director of policy at the New Zealand Council of Trade Unions, says bus drivers are a good example. “It got to the point where we couldn’t get bus drivers, we were importing them from overseas, but no one was getting a better service,” he told me.

This dynamic isn’t unique to New Zealand: the UK’s HGV driver shortage last year, which prompted the government to announce emergency visas for migrant workers, was caused at least in part by an erosion in drivers’ pay and working hours.

In March, the New Zealand government introduced the “fair pay agreements” bill. It aims to get employers and unions to negotiate agreements which would set a minimum floor for pay and conditions across whole sectors or occupations. If a tenth of workers who would be covered or 1,000 of them (whichever is fewer) say they want an FPA, union and employer representatives will negotiate one and put it to a vote. If there is ultimate stalemate, the Employment Relations Authority will decide the terms.

Unions argue the system will stop good employers from being undercut by bad ones and help workers in sectors which are hard to organise. They plan to focus first on bus drivers, security guards, childcare workers and “bottle shops”. As well as pay, they will focus on minimum standards for training, working hours and safety measures.

But employers’ groups are fiercely opposed. They say fair pay agreements will reduce flexibility and drag New Zealand back to the 1970s at a time when they are already grappling with inflation. Kirk Hope, chief executive of BusinessNZ, the main business lobby group, has argued FPAs will “take away control from Kiwi workers and give it to faceless officials in [the capital] Wellington”.

Who is right? A detailed OECD study in 2019 concluded that sectoral collective bargaining systems can lead to better employment, productivity and wages than systems where agreements are only made at the individual company level. But the devil is in the detail: inflexible sectoral agreements can harm productivity while the best ones (more common in Scandinavian countries) provide broad frameworks which also leave “considerable scope for bargaining at the firm level”. A decent level of trust between the negotiating parties also makes a difference.

New Zealand’s attempt to perform a handbrake turn in its labour market will be closely watched by other countries with similar problems. If it leads to better quality jobs and more constructive labour relations, expect to see calls for the model to be replicated. The UK’s Labour party has already promised to implement a similar policy if it is elected. If, on the other hand, the new law results in sclerosis and rows, the disappointment will be felt by beleaguered unions well beyond New Zealand.

Whether or not fair pay agreements are the right answer, New Zealand is at least asking the right question: how do we make sure the changing world of work does not leave some people behind in gruelling jobs? This type of work is not going away. Indeed, some occupations, like social care, are set to be among the fastest-growing in the economy. Any attempt to shape the future of work must focus on carers just as much as coders.

sarah.oconnor@ft.com

Do You Need Workers Compensation Insurance for Small Business?

Do You Need Workers Compensation Insurance for Small Business?

The advantages of workers’ compensation insurance plan significantly outweigh its price. Do you need to have workers’ payment coverage? The reply may be much more elaborate than you comprehend.

For example, do you want to go over distant workers? Do you want workers’ comp advantages for aspect-time employees? What about subcontractors who function for you?

Modest small business proprietors know how to avert accidents at get the job done. Continue to, mishaps materialize. And that helps make workers’ compensation insurance a person of the most vital styles of company insurance policies.


What Is Workers’ Payment Insurance?

Also acknowledged as workman’s comp, workers’ payment insurance policies is coverage for personnel if they are hurt or turn into unwell at function. In the vast majority of states, smaller corporations are required to have it if they have workforce.

Why You Need to Take Out Workers’ Comp Insurance

Let us say you’re a small enterprise operator from Texas. Workers’ comp insurance coverage is not essential there. In Arkansas, if you have fewer than 3 employees, you don’t need to have it. In Alabama, it is essential if you have 5 or much more employees.

No subject what your condition necessities are, you must acquire out workers’ payment insurance coverage to guard your organization:

  • An staff who is hurt or becomes sick at operate can sue you, in search of misplaced wages and payment of health care expenses
  • For the exact same reason, you really should protect element-time staff and subcontractors. Very little would prevent them from suing you for missing wages and payment of health-related bills should they become injured or come to be ill at your company. You can include them to your workers’ compensation coverage offer. It’s your security internet towards lawful prices and the expenditures of healthcare treatment.
  • In most states, personnel comp is needed for organizations, even if there is only just one worker.
  • Even if your workforce no more time performs at the company, you require to include remote staff. Distant workers are undertaking responsibilities similar to their employment all through function hrs and need to have protection.

What You Require to Know about Workers Compensation and Remote Personnel

As a smaller small business operator with remote employees, you will need to acquire methods to make sure their operate natural environment is safe and sound. Ever more, an insurance enterprise may perhaps involve you to make a bodily inspection of the distant staff office before supplying workers’ compensation coverage.

The most popular workers’ compensation promises reported by remote employees are slips, excursions, and falls. They also report ergonomic injuries thanks to the very poor styles of workstations.

As the manager or manager, you must consider measures to be guaranteed the office of the remote employee is harmless and ergonomically appropriate. Despite the fact that they are operating remotely, you are expected to have workers’ payment insurance plan for them.

What Does Employees Payment Coverage Protect?

Why do you require a worker’s compensation coverage? In most states, workers’ payment legislation have to have that you offer it as company insurance policy.

Here’s what the workers’ payment method handles:

Health care Expenses

An insurance policies business aids go over healthcare fees connected with office injuries. The workers’ comp profit allows go over health-related expenses and costs connected to staff injuries or place of work mishaps. Coverage will involve professional medical treatment, bodily remedy, and ongoing assist.

Lost Wages

Workers’ comp protection will provide the wounded bash with misplaced wages, very similar to lengthy-term disability gains.

Loss of life Gains

If an employee dies owing to a work-similar damage, accident or illness, the workers’ comp insurance plan plan will shell out dying gains.

Accidents and Ailment to Workers Although at Perform

Accidents and Sickness to Part-time Employees and Subcontractors

Look at with your insurance policy enterprise to see if you can buy protection and include portion-timers and unbiased contractors to your workers’ comp policy. It adds a amount of money security to your organization in the event a worker will become ill or wounded on the position while at your task website.

What is Not Coated by Staff Compensation Insurance coverage?

Business standard legal responsibility insurance plan, standard legal responsibility, specialist liability insurance, a small business owner’s plan and property coverage cover your company and its solutions or providers.

What does worker’s payment go over? Workers’ compensation protection is for workforce though they’re doing work. At other situations, they are included by wellbeing insurance.

One of a kind activities can transpire in the workplace – and away from the office. Some matters just aren’t provided under workers’ compensation protection.

  • COVID-related health problems and health care expenditures – Examine with your insurance plan company and condition. During the pandemic, coverage was expanded to involve COVID-linked health problems, particularly for entrance-line employees these types of as nurses, medical practitioners and unexpected emergency personnel (law enforcement, fire). In most states, the time body for that coverage has ended. Ordinarily – not all through a pandemic – “routine generally spread illnesses” are not lined. That’s because it is difficult to establish exactly where and when the staff got the sickness.
  • Portion-time staff members and subcontractors are not lined except if you precisely include that coverage. Only Arizona precludes organizations from including those people classes of workers to the coverage for a office personal injury or ailment.
  • Accidents that take place at work functions, these as a softball game or picnic, if participation is voluntary. (If you want staff to be covered at operate functions, point out it in creating that attendance is mandatory.)
  • Accidents that come about, these kinds of as a struggle amongst two staff that materialize for personal reasons not relevant to perform.
  • A operate-related injuries or sickness or function-similar accident that requires place due to the fact an worker is intoxicated or underneath the influence of unlawful medications. Of course, it ought to be firm coverage that personnel are not permitted to be at perform under those situations. A signed arrangement of that really should be in your worker files.

How Substantially is Smaller Business Employees Comp Coverage?

You may be ready to “umbrella” workers’ payment coverage underneath your organization owner’s coverage. There are a number of components that alter the workers’ compensation insurance cost – payroll, sort of function carried out, and claims heritage.

For example, usually, the expense is $1 to $1.56 for each and every $100 of (gross). That price varies by point out and can change each year. The variety of operate is aspect of the calculation, applying 700 class codes for kinds of positions. People two components are calculated. Then, the whole will be multiplied by 1 to calculate workers comp prices, if you have had no statements. The multiplication element will change dependent on your quantity of promises.

Staff Payment Insurance Needs in the U.S.

Legislation fluctuate but in standard, you’re essential to get workers’ comp insurance policies if you have personnel. There are some exceptions, as beforehand observed. If you are essential to receive staff comp and you don’t, you could confront felony legal prices.

How to Get Modest Company Personnel Payment Insurance coverage

You can established up and purchase workers comp insurance policies on-line, with just a handful of clicks.

  1. Examine the prerequisites in your condition and start coverage with the initially personnel you seek the services of if necessary.
  2. Community with other business entrepreneurs to get recommendations.
  3. Opt for an insurance organization that delivers broad protection in the organization insurance policies earth, and is expert with worker compensation coverage.
  4. Get a workers’ compensation estimate from quite a few carriers and review the possibilities.
  5. Make a preference and enroll in a coverage.

Image: Depositphotos


Extra in: Insurance plan


B&G profit off on higher input costs

B&G profit off on higher input costs

PARSIPPANY, NJ — Inflation and supply chain restoration proved demanding as soon as once more for B&G Foodstuff, Inc. in the first quarter of fiscal 2022.

Web money at B&G Foodstuff in the first quarter ended April 2 totaled $23.66 million, equivalent to 34¢ for each share on the common stock, down 12{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from $26.88 million, or 42¢ for each share, in the similar interval a 12 months back. B&G explained the most current quarter involved a $7.1 million gain related to the sale of property.

Internet profits greater 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $532.41 million from $505.13 million.

On May well 6, a day immediately after earnings were being produced, shares of B&G shut at $24.37 on the New York Stock Exchange, down virtually 13{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from the near of $27.90 on Might 4, the day in advance of earnings were issued.

“Our first quarter was closely impacted by serious input expense improves across big parts of our portfolio coupled with ongoing industrywide supply chain disruptions that, even though increasing, have continue to been a drag on the enterprise,” Bruce C. Wacha, main economical officer, explained all through a Could 5 convention phone with analysts. “The destructive pressures have been offset in part by our pricing initiatives that consist of listing value increases, trade commit reductions, product body weight-outs, and the impression of item blend. These initiatives that we have taken to make improvements to net pricing have been made to be similarly as significant. Having said that, thanks to the lag result on implementation, our margins have been compressed in the quick term. We be expecting identical ranges of margin compression in the second quarter owing to the enter cost raises.”

Mr. Wacha said net income of Cream of Wheat enhanced by $2.8 million, or 15.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, throughout the initially quarter. He stated the brand benefited from price tag and volume, pushed in element by ongoing sturdy desire throughout the brand’s portfolio, notably for Cream of Rice goods.

In the meantime, web income of Ortega improved by $3.6 million, or 9.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, lifted by enhanced output potential from a new taco sauce line in Hurlock, Md. Potent progress also was famous in Maple Grove Farms, which saw profits raise by $1.2 million, or 6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, Mr. Wacha reported.

In the Eco-friendly Giant model, net sales of shelf-steady solutions rose by $3.9 million, or 11.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, while web revenue of frozen items fell $700,000, or .7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, in the course of the quarter.

Internet gross sales in the company’s spices and seasonings company fell $15.1 million, or nearly 15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, in the initial quarter when compared with a calendar year ago, but remained up extra than 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from the 1st quarter of 2020, Mr. Wacha explained.

“We have made sizeable investments in our Ankeny, Iowa, spices and seasonings facility and we are beginning to see meaningful advancements in our fill fees for this crucial classification of our enterprise,” he claimed. “We anticipate that our improvements will greater permit us to improve our possibility in the spices and seasonings group this calendar year.”

B&G Meals revised its complete-12 months fiscal 2022 altered EBITA steering to a range of $348 million to $358 million, down from early steering of $358 million to $368 million. Internet product sales direction for the full yr was lifted to a selection of $2.10 billion to $2.14 billion, up from before assistance of $2.07 billion to $2.13 billion. 

Tenth of SMEs see crowdfunding as their preferred finance option

Tenth of SMEs see crowdfunding as their preferred finance option

The majority of smaller- and medium-sized enterprises (SMEs) are hunting for a dollars injection and more than a tenth explained crowdfunding is their desired finance solution, a report has uncovered.

Bibby Monetary Services’ yearly SME Self-assurance Tracker study of 500 United kingdom SME owners and selection makers has discovered that 81 for each cent would look at some form of hard cash injection from exterior sources to assist their business enterprise.

12 for each cent mentioned they planned to opt for crowdfunding as their most important way to raise funds this year.

Go through a lot more: SMEs look for growth funding as Covid recovery carries on

The best a few options have been: organization loans (34 per cent) credit score playing cards (30 for each cent) and overdrafts (29 for each cent). This was followed by govt loans (21 for every cent), bill finance (19 for each cent), non-public fairness (14 for each cent) and asset finance (13 per cent).

Pretty much two-fifths (15 for every cent) of organizations count on external finance to support their functions and 17 for each cent have a repeated want for external finance simply because of substantial cashflow issues.

About a quarter (28 per cent) of SMEs claimed exterior finance is not significant but that they use it to permit organization development and provide clean cashflow. In the production marketplace, about a 3rd (34 for every cent) of firms reported this is the case.

Read through additional: CBI urges SMEs to use fintech for growth

The report also uncovered that the the greater part of SMEs (82 for each cent) now come to feel self-confident about their prospects this calendar year, 38 for every cent – or 2.1 million – describe them selves as ‘just about breaking even’.

SMEs are most worried by inflation (42 for every cent), conflict in Europe (37 for every cent), offer chain disruption (33 for each cent), ongoing problems from the pandemic (33 for every cent) and cashflow (26 per cent).

Read through extra: SMEs could facial area road blocks to rumoured new govt financial loan plan

Browse a lot more: Fintechs simply call for authorities help for non-financial institution SME lending

“UK firms deal with a heady cocktail of concerns that threaten to influence development forecasts for 2022 and further than, like soaring inflation, expertise shortages, and a expense-of-living disaster not viewed on such a scale in the 21st century,” said Derek Ryan, United kingdom taking care of director of Bibby Monetary Expert services.

“While our report highlights a stoic resilience amongst the Uk SME neighborhood, lots of are still having difficulties to hold their heads earlier mentioned water and functioning on a working day-to-working day basis, rather than hunting in advance to advancement.

“SMEs confronted the pandemic with fortitude and now they will have to proceed to adapt and change to carefully regulate the growing expenses of carrying out business enterprise.

“It’s evident that cashflow worries and payment troubles proceed to plague firms, and it is now far more critical than at any time that they have obtain to performing funds to support working day-to-working day functions, and to repay personal debt taken on at the height of the pandemic.

“But they simply cannot thrive by yourself it’s crucial they obtain help from the personal and community sectors, and we’d urge policymakers to intently appear at broader tax cuts and energy grants to support SMEs and to make certain they keep on to enjoy a pivotal position in the UK’s economic recovery.”

What Millennials should know about personal finance planning

What Millennials should know about personal finance planning

Millennials, the demographic cohort that can make up 34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the country’s inhabitants, have experienced a ringside check out of the world’s digital transformation. Their demands have expanded to in good shape their here-and-now solution to lifestyle, and so have the suggests to satiate individuals wants. No matter whether it’s a mundane task or a major lifestyle conclusion, advantage will come as second mother nature to them. While the earth may be at their feet (or fingertips), there’s no denying that it has also led to an info overload in all areas of daily life now, like individual finance conclusions.

Economic literacy has turn into much more essential than ever, all many thanks to the uncertain moments imposed on us by the pandemic. But it is similarly significant to be in a position to slice by way of the muddle and make knowledgeable navigation as a result of economic scheduling. FinTech has surely assisted make finance a lot more obtainable and also relatable for the Millennials currently. There are numerous funds aimed to give millennial buyers with the right launchpad into the entire world of wealth development. Let’s acquire a nearer look at how Millennials can go about their particular finance organizing.

An early headstart to maximise returns

The rule of thumb to attain highest returns on one’s investments is to commence early. This is the smartest way to increase your discounts and achieve a sizeable corpus to fulfill your life’s milestones. Millennials have the time factor on their aspect that they ought to leverage and get an early headstart on their investments. Inflation is soaring at a brutal tempo and currently clocked a 17-thirty day period high at 6.95{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} previous month. Your child’s increased education and learning may possibly feel much off, but insert another 20 several years to this hike and issue in schooling inflation which stands at 11-12{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} appropriate now, you are going to have to have at minimum Rs 1 crore to afford the school price.

Therefore, every single working day that you hold off translates to this value heading up and a loss of returns. The economical sector has taken cognizance of the need to make expense less complicated and a lot more relatable for Millennials now. Even if you established apart Rs 10,000 just about every thirty day period for financial investment, you will be in a position to accomplish your financial plans above time. In point, regardless of whether or not you have a relatives correct now, you ought to know that you can commence investing for your kid as shortly as he or she turns three months previous. Apart from this, investing early for yourself will also pay back you off in your old age, getting rid of the will need for dependency on any individual.

The increasing want for a resilient fiscal strategy

Millennials appreciate to are living in the minute. On the other hand, the strain of the contemporary-day way of life is a severe fact for them that casts the shadow of its repercussions on their upcoming. Particularly immediately after the Covid outbreak, the require for a economically secure future has developed manifold for an ordinary Millennial. The important ingredient to safeguarding on your own and your cherished types from this sort of uncertainties is insurance. Wellbeing emergencies are on the increase like by no means in advance of, and on prime of that, towering clinical inflation only adds to this menace. The lifestyle of a Millennial is punctuated with a nerve-racking but sedentary way of living, therefore dashing up the arrival of illnesses like diabetic issues, hypertension and coronary heart ailments.  As per the Intercontinental Diabetic issues Federation, just about every 1 in 12 Indians is diabetic, which is the next-greatest quantity in the entire world.

It is usually mentioned that the finest time to buy insurance plan was yesterday, the future ideal time is currently. At a time when even a single health-related exigency is adequate to wipe out your difficult-acquired discounts, it is wiser to make investments in a resilient fiscal technique that prepares you for better for this kind of a situation. This applies to owning robust coverage through both equally, well being and time period coverage. The most typical misunderstanding that Millennials have is that do youthful individuals even need to have insurance plan?

The respond to is a resounding indeed. As for every the Indian Heart Affiliation, heart illnesses strike Indians at an previously age than other demographics without having any warning. Insurance policies shields you at each stage of your daily life. In simple fact, the before you invest in, the far better it is. Apart from conserving much more, you also get a plan with assorted options conveniently, which might get tough after you contract a illness or get older. Coverage should be a Millennial’s major investment decision in order to defend all the other investments.

Leverage the electricity of diversifying and compounding

The market is inundated with a myriad of investment options. Buying the appropriate expenditure equipment to park your money is essential, but can also be difficult. For that reason, you need to deploy the tactic of portfolio diversification below. Current market volatility, inflation, fuel price tag rise – there are a number of things that management the marketplace. So, you must look at options that adequately cover you for hazard as properly as reap adequate returns. Dependent on your life’s stage and needs, you can faucet into the electrical power of compounding by investing in products that give you the upside of market place-connected returns. You also need to allocate your resources proportionately into credit card debt and equity. There are quite a few selections that permit you ample adaptability to switch between the two as for each your needs. Having said that, if you are a hazard-averse investor, you can nonetheless get great returns by investing in solutions that warranty a set revenue and set returns on investments more than a selected period of time.

Digitisation has designed expenditure a large amount less difficult for the Millennials, so it is vital to gauge the strengths and weaknesses of every single selection. It’s critical to start performing backwards nowadays to execute your economic aims tomorrow.


Linkedin


Disclaimer

Sights expressed higher than are the author’s own.


Conclusion OF Report