How Dems May Accidentally Hit Americans With Big Health Insurance Bills Before Midterms

How Dems May Accidentally Hit Americans With Big Health Insurance Bills Before Midterms
  • Hundreds of thousands of Individuals could see significant hikes in following year’s insurance plan rates correct just before the November midterms.
  • That is if Democrats are unsuccessful to lengthen subsidies in a new financial investing monthly bill.
  • Manchin appears noncommittal on extending the assist, even while he backed it in the earlier.

Democrats could be stumbling into a chaotic predicament just before the November midterms that handful of are conversing about. Millions of Americans are established to see their healthcare charges surge in 2023 with far more pandemic support fading away.

That is due to the rising likelihood Democrats by no means regulate to resurrect pieces of their social spending and weather package, which stalled out in the evenly-divided Senate for the reason that of resistance from Sen. Joe Manchin of West Virginia.

The Biden stimulus legislation beefed up subsidies to minimize regular high quality charges and make personal person health insurance policies options far more cost-effective under the Affordable Treatment Act (ACA). Democrats intended to prolong the plan in their defunct Establish Back again Better invoice, location apart generous new funding to aid these with no employer-dependent insurance policy get protection in the wellness insurance coverage marketplace. 

Federal unemployment help expired last yr and increased ACA subsidies may possibly experience the similar fate on December 31. The following open Obamacare enrollment window kicks off November 1, this means voters would discover about soaring insurance costs only a 7 days right before the midterms as they get started browsing available programs for 2023 or get notified by insurers. 

“It would just be a substantial top quality shock,” Larry Levitt, govt vice president for wellness plan at the nonpartisan Kaiser Family Basis, advised Insider, introducing people today buying personal insurance policies on the exchanges would fork out an ordinary of $800 additional for every year for protection.

“Democrats encounter a prospective political headache if they really don’t extend the excess quality subsidies,” Levitt stated. “Persons will be discovering out about top quality improves correct ahead of the midterm elections. It will absolutely mirror improperly on Democrats. The ACA is their leading domestic achievement of the very last decade.”

A few million men and women will drop overall health coverage without the need of the bulked-up federal support, according to an evaluation introduced past thirty day period from the Robert Wooden Johnson Foundation. Others will be pressured on to less expensive programs carrying deductibles that are occasionally 30x better — a soar from $200 to $7,000 in these circumstances. That’s the total enrollees owe right before the insurance company starts off shelling out for medical treatment. 

The scale of premium raises will fluctuate owing to elements like age, earnings, and point out. But the voters dealing with eye-popping costs upcoming 12 months tend to be older  — the very group that turns out in greater quantities through midterm elections.

“It’s those people individuals who are comparatively middle-cash flow, and who are also aged that are heading to experience the major hit if the subsidies expire,” Emily Gee, the vice president and health care plan coordinator at the liberal-leaning Heart of American Development, informed Insider.

In Manchin’s dwelling point out of West Virginia, some could working experience a calamitous boost in their healthcare expenditures. A 60-yr previous married West Virginian couple earning $75,000 will see their regular top quality skyrocket by $2,700 if Obamacare subsidies conclusion, according to estimates from healthcare policy qualified Charles Gaba.

A comparable couple in Arizona would encounter a $942 regular monthly premium hike, for each Gaba’s projections. An equivalent Ga few would see their monthly premiums soar by $1,200. These states are up for grabs in November with extremely aggressive Senate races underway.

Gee added lawmakers will have to act by midsummer to make sure states and insurers have sufficient time to set up their enrollment durations, a sophisticated method stretching months. “It can be not like there is a change that you can flick in late August or late in the fall to turn on the subsidies,” she mentioned.

A swerving Manchin

Ron Wyden Joe Manchin

Sen. Joe Manchin (D-WV) speaks to Sen. Ron Wyden at the Capitol last thirty day period.

Anna Moneymaker/Getty Illustrations or photos


Manchin advised NBC News in early February that he is “often been supportive” of ensuring men and women have entry to very affordable insurance by holding the subsidies. But he appears to be to be backtracking, throwing a wrench in any effort to lock in a important part of Democrats’ wellbeing agenda developed to repair the law’s affordability troubles.

Insider approached Manchin twice this 7 days. Both times he struck a noncommittal tone on whether the Obamacare subsidies really should type aspect of a slimmer Democrat-only package. “My main factor is fighting inflation,” he claimed on Monday, alongside with securing “tax reforms.”

On Thursday, he claimed: “You will find just far too considerably going on. We are chatting about almost everything.”

Spokespeople for Manchin declined to remark even more. Without having his vote, Senate Democrats are blocked from reviving a skinnier version of the legislation in the confront of unified GOP opposition in the 50-50 Senate.

He has sketched out a package evenly split involving new expending and deficit-reduction, along with eco-friendly energy and short-expression fossil fuel actions in the wake of the war in Ukraine. Manchin has also mentioned a main precedence of his is reining in prescription drug charges. It really is not apparent what other initiatives in good shape his narrow requires, but other Democrats say they’re functioning powering the scenes to get him onboard.

“Keeping down rates will be and has been a significant priority for me,” Sen. Ron Wyden of Oregon, chair of the Senate Finance Committee, informed Insider.

A Senate Democratic aide drew a comparison to the 2014 midterm elections when rising premiums became a last-minute situation in some races. In Louisiana and Iowa, top quality hikes handed Republican Senate candidates a different hammer to use against Democrats at the time.

“You might be seeking at relatively a repeat of that,” the aide advised Insider, granted anonymity to discuss candidly. “It certainly would not be helpful.”

The GOP Senate candidates received in the two states that 12 months: Sen. Joni Ernst clinched the seat in Iowa. So did Sen. Monthly bill Cassidy in Louisiana.

Democrats lost command of the Senate in 2014, only to recapture it previous calendar year. They deal with sizeable headwinds heading into the drop, and spiking rates could be another popping up in the remaining extend. With the Senate and House majorities in participate in, Republicans will likely not be inclined to slash a offer.

“I you should not see any prospect of Republicans aiding Democrats get out of this box,” Levitt said.
Bantam Bagel exit weighs on Lancaster Colony performance

Bantam Bagel exit weighs on Lancaster Colony performance

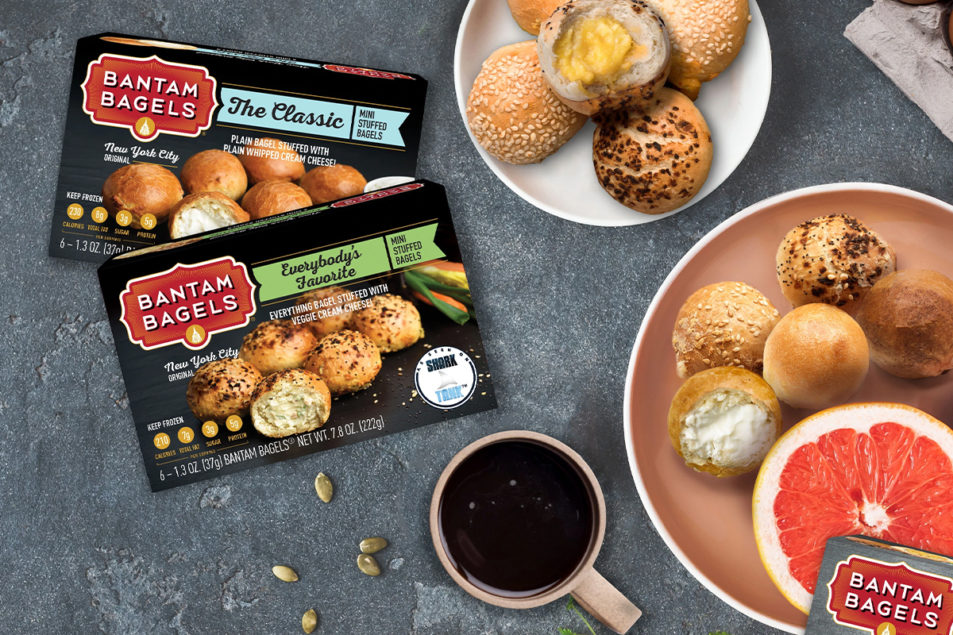
WESTERVILLE, OHIO — A continuation of elevated charges for raw products, packaging, freight and labor, coupled with restructuring and impairment charges associated to the exit of the Bantam Bagels company, dragged down quarterly earnings at Lancaster Colony Corp.

Lancaster Colony in the 3rd quarter ended March 31 sustained a decline of $4.48 million, which in contrast with revenue of $28.9 million, equivalent to $1.05 for every share, in the exact same time period a year back. The most new quarter integrated a noncash restructuring and impairment charge of $22.7 million for the Bantam Bagels business enterprise.

Web sales, in the meantime, ongoing to craze upward, climbing 13{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $403.49 million from $357.25 million a 12 months back.

“Net profits advancement in the Retail phase was pushed by pricing throughout the portfolio, ongoing volume gains for our licensing system and solid profits for our Sister Schubert’s supper rolls,” David A. Ciesinski, president and main govt officer, said for the duration of a Could 5 conference get in touch with with analysts. “The 7.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} net profits expansion in Retail compares to a sturdy gross sales get of 17.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in last year’s 3rd quarter. Retail income volume measured in lbs declined 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, but comps to sturdy quantity expansion of around 12{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in the prior calendar year quarter and what’s more, demonstrates the choice to exit decide on noncore products. Excluding these rationalizations, our 3rd-quarter Retail net product sales volume grew 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.”

Mr. Ciesinski stated Lancaster’s licensing method ongoing to perform very well in the quarter, with Buffalo Wild Wings and Chick-fil-A sauces accounting for a lot more than 8 share factors of Retail internet income growth. On a two-calendar year stack foundation for the quarter, retail gross sales for the company’s certified sauce platform have far more than tripled, escalating to $89 million from $29 million, he claimed. That fast advancement, though, has occur at a cost, as the firm has confronted incremental co-producing cost and margin pressure, he reported.

To tackle the climbing costs Lancaster has undertaken “a centered list of discrete steps,” Mr. Ciesinski said. Measures taken in the 3rd quarter included the construction and start out up of a sauce capability enlargement venture at 1 of the company’s Columbus, Ohio-based mostly facilities, as well as the opening of a new Columbus-dependent warehouse site. Lancaster also is increasing the use of its interior manufacturing facilities the place its capacity predicament will allow, he explained.

Yet another important action taken for the duration of the quarter was the conclusion to exit the Bantam Bagels organization, which Lancaster acquired for $34 million in October 2018. At the time of the acquisition, Mr. Ciesinski explained New York Metropolis-based mostly Bantam Bagels and its frozen mini stuffed bagels and mini stuffed pancakes as “a fast-rising firm that provides us with an entry into the huge and increasing frozen breakfast class.” Founded in 2013 as a retail shop, Bantam Bagels experienced an existing relationship with Starbucks, an additional beneficial that Mr. Ciesinski thought positioned the small business for long run enlargement.

But less than 4 a long time afterwards, primarily based on the economical underperformance of the organization with no foreseeable path to profitability, Lancaster created the decision to exit the company just after pursuing various strategic alternate options, such as a prospective sale.

“Early for the duration of the pandemic, the foodservice industry was seriously impacted by store closures and visitors declines,” Mr. Ciesinski said. “During this period of time, numerous restaurant operators created decisions to streamline their menus for functioning efficiencies. And during this interval, Bantam Bagels was discontinued at their premier buyer exactly for this explanation. This discontinuation and the sustained impression of the pandemic modified the economics of the small business. Irrespective of investments to assistance the progress of Bantam Bagels in the retail phase and our very best endeavours to exchange the decline of the important purchaser in the foodservice phase, we were not able to establish a credible pathway to profitability for the business. For that reason, we created the prudent, but tricky, choice to exit the enterprise.”

Lancaster claimed it is now pursuing the sale of the equipment made use of to deliver Bantam Bagels and expects to have entirely exited the organization by the stop of June.

In the 9 months finished Dec. 31, Lancaster Colony’s net revenue was $60.54 million, or $2.20 for each share, down 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from $110.61 million, or $4.02 per share. Internet gross sales were $1.22 billion, up 13{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from $1.08 billion. 

5 ways technology can accelerate your auto finance business

5 ways technology can accelerate your auto finance business

Pandemic, inflation, rising prices, product shortages, source chain difficulties and regulatory compliance — these challenges have an affect on all industries, and automotive finance is no exception. 

All effective automobile finance small business leaders know they will have to go on to grow through improve and business enterprise disruption to remain aggressive. Our exploration identified that in advance of the COVID-19 pandemic, leaders in technological know-how adoption and innovation had been escalating two times quicker than people with an aversion to modify. That rate improved to 5 instances quicker in the course of the pandemic.  

Industry leaders understand that disruption simply cannot limit their capacity to adapt, and that know-how can help rework problems into alternatives. But where by to start off? 

Listed here are the prime five strategies to speed up your automotive finance small business with technologies to swiftly regulate to modify as a final result of organization possibility or exterior elements: 

1. Go digital 

The to start with and most clear phase is to make a commitment to go electronic. As we all know, electronic transformation accelerated tremendously in the auto finance marketplace around the previous two yrs.  

Lots of loan companies that utilized paper and guide processes pre-pandemic were forced to go electronic. And most have recognized that digitization is in this article to continue to be. Whilst vehicle finance lenders possess several stages of electronic maturity, we’re however seeing far as well numerous manual processes that could gain from automated technologies. Likely electronic optimizes workflows, mitigates hazard, saves time and revenue, and enhances the customer experience.  

2. Adhere with requirements

When custom made technological innovation might have been a differentiator in the previous, that legacy technological innovation will maintain you again competitively currently and in the long run.  

Swift changes in the field, enterprise versions, buyer conduct and know-how put vital requires on knowledge infrastructure and very custom-made legacy technology. You can clear up individuals problems by modernizing know-how. Platforms are the automobile to modernization as they are created for standardization.  

Popular platforms you use often might contain Salesforce, Amazon, Microsoft 365 and Apple. In essence, a system supplies a set of normal infrastructure deployed in a dependable fashion across all programs functioning on that platform.  

Consider of a platform as a group of residences that all had various custom-made styles and create techniques to core foundational factors. And feel of households crafted with standardized foundational components. Equally are configured in distinctive means however, the types that are standardized are simpler to sustain with the ability to swap out parts and improve significantly speedier and much easier.  

Like building a dwelling, a system serves as a foundation that you establish on. In the auto finance marketplace, you can construct and run small business apps on the platform in a smooth, safe and scalable style. A platform can make everything quick to use and enables clients of any size to change operations, get started businesses, develop into new markets, combine portfolios and leverage emerging technological innovation. 

Data Network Internet
© Can Stock Photograph / kentoh

3. Undertake evergreen IT

Evergreen IT signifies your technologies is under no circumstances out of date or out of date it is repeatedly transforming and evolving.  

A fantastic example is the mobile cellular phone operating program. When cell phones initially came out for the mass marketplace a couple of decades ago, you never ever really upgraded your mobile phone. Phone manufacturers at the time weren’t really targeted on an improve route.  

These days, that’s a distinctive tale. Whether you use an Apple iphone or an Android product, you get rapid updates just about every couple of months. 

Continual updates are a thing you must be expecting from your fintech application spouse.  

For example, you’ll want to guarantee your auto finance software spouse embraces evergreen IT, which updates your technologies products and solutions routinely and seamlessly — month-to-month if not daily — for some performance. Annual releases of updates won’t keep you on the forefront of regular change.  

4. Shift to the cloud and SaaS

Our upcoming recommendation is to increase your small business by way of engineering is moving to cloud and computer software-as-a-assistance (SaaS) technology. It is important to realize the difference cloud and SaaS are not the similar.  

In a cloud-hosted product, the vendor is only accountable for building and deploying the infrastructure and technological know-how. Then, you are liable for maintaining the software, applying the upgrades, screening, protection, etcetera. The vendor builds it and then you control the rest.  

A accurate SaaS provider will take care of the protection, redundancy, backups, catastrophe restoration, governance and variations.  

SaaS is also is suitable for all business measurements, from smaller startups utilizing spreadsheets to large countrywide organizations moving from on-prem IT systems. Smaller sized organizations generally think they really do not have the technological abilities, staffing or income to profit from the benefit of a SaaS cloud-primarily based platform whilst more substantial providers speculate if SaaS can meet up with their demands when it comes to scalability, overall performance and complexity. 

SaaS is perfect for all automobile finance lenders, no matter of size, income volume or electronic maturity. And you only spend for what you use.  

5. Harness facts

The final recommendation is to harness details to guard your future. We’re extra related now than any other time in history, and this craze is anticipated to expand exponentially as connectivity and overall performance details matures and turns into more extensively offered.  

Authorities predict that by 2030, 95{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of all new autos offered globally will be related. Accessibility to in-automobile knowledge sets the stage for added earnings alternatives this sort of as distant diagnostics, on the web service scheduling, and more than-the-air (OTA) purchasing that makes it possible for program advancements to manifest through the internet. 

Obtain to serious-time facts with related automobiles will also accelerate the change to predicted financing models, this sort of as going absent from classic possession to shell out-for-use or shared-ownership financing styles. 

Ray Wizbowski is the Chief Advertising Officer for Solifi 

Personal Finance Tips for the Millennial Working Moms -Devika Praveen

Personal Finance Tips for the Millennial Working Moms -Devika Praveen

For Millennials Moms, motherhood isn’t straightforward and viewed as significantly more durable as compared to earlier generations, much more so for working mums. Working moms don lots of hats, and their lives are in a point out of regular flux, loaded with each day troubles. Nonetheless, with a little bit of thorough imagining and scheduling, fiscal worry need to have not be 1 of those people.

Nevertheless many millennial operating mothers are anxious and stressed, they’re reclaiming regulate where by they can: remaining proactive and impartial, investing independently, mastering the artwork of the side hustle and setting up prosperity on their possess conditions.

Primary but prudent monetary setting up can assist functioning mothers by strengthening the monetary future of their young children. So, on this Mother’s Day, whilst having fun with your time with your little one and getting ready to resume your experienced everyday living, here are a handful of fiscal planning assignments you have to have to zero in on:

Budgeting is essential: Budgeting is all about calculating spendings and observing in which each individual rupee is heading – a basic toolkit for remaining in charge of your income rather of pondering exactly where it went.

Trying to keep funds useful for an crisis: Having an unexpected emergency fund can assistance a large amount. When dealing with real emergencies, the last detail you will need is to fear about it is how you’ll pay back for it. In circumstance if you struggle with personal savings, commence with a purpose of location aside a nominal amount and then function your way up to a thirty day period of expenses, then a few, and then construct up to 6 months of charges in this kitty.

Acquiring a credit card debt payoff strategy: Assuming you have debt (financial loans), then figure out a plan to dispose it given that it hinders with prosperity generation. Study the greatest avenues, strategy that works most effective for you, and then put into action to a system.

Investing for the very long term: Devote as considerably as you can and as early as you can. You can start with your retirement (of course, now!) fund if investing appears as well complicated. Never go away absolutely free income on the desk.

Setting up a credit rating: Completely imperative to take treatment of your expenditures on time every time. Period! Meticulously examine any credit score will increase that are proposed to you by everyone and determine based on have to have instead than need.

Place on your respiration mask initially: Remember to strategy for your extensive phrase long run (previous-age) and along with your child’s education fund. You are comparably vital and setting up for your foreseeable future security shall assure that you do not become a financial stress to your young children.

Benefit from federal government applications and tax gains: Do your research properly and check out with your financial institution for the readily available plans and tax rewards for moms and dads/woman child and many others.

Get ample protection for you and your family members: Regardless of whether you are a single functioning mother or not, assure enough wellness and life insurance. Your employer could be offering a group address, nonetheless for highest benefits in the course of a medical unexpected emergency, it is prudent to have your own overall health address. A time period existence insurance policy assures that your family’s money requires are taken treatment of in situation of your untimely demise.

Eventually!

Other than all the beforehand described savvy economical moves, set apart some hard cash for your recreational workouts. Never forget about to make place to delight in what you gain. Gift oneself with that new e-book, a spa day, or a night time out with close friends. 

Keep in head, a healthful intellect is a essential to accomplishment and for that, it is important to unwind as perfectly. Nonetheless, this ought to be accomplished right after firming up your economical prepare and other critical bills.

Just take these methods and have a delighted Mother’s Day every day of the calendar year!!

Disclaimer: The sights expressed in the short article higher than are those people of the authors’ and do not essentially stand for or replicate the views of this publishing property. Unless of course in any other case noted, the creator is composing in his/her private potential. They are not intended and should really not be imagined to stand for formal thoughts, attitudes, or policies of any company or establishment.


Payrolls rise by 428,000 as unemployment rate holds at 3.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

Payrolls rise by 428,000 as unemployment rate holds at 3.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

U.S. task advancement remained robust in April as the unemployment level held around its pre-virus minimal, even further underscoring the even now-restricted domestic labor market.

The Labor Division produced its every month careers report for April Friday morning at 8:30 a.m. ET. Listed here have been the main metrics from the print, in comparison with consensus details compiled by Bloomberg:

  • Non-farm payrolls: +428,000 vs. +380,000 envisioned and a revised +428,000 in March

  • Unemployment fee: 3.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. 3.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} predicted, 3.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in March

  • Regular hourly earnings, thirty day period-above-thirty day period: .3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. .4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} anticipated and a revised .4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in March

  • Ordinary hourly earnings, 12 months-more than-yr: 5.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. 5.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} expected, 5.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in March

The U.S. economic climate has brought back again payrolls each thirty day period so significantly in 2022, and April’s payrolls gains still represented progress properly-earlier mentioned pre-pandemic trends. All through 2019, payroll expansion had averaged about 164,000 per month. And nevertheless payroll gains have been also marginally downwardly revised for February and March, these will increase were still stable on a historic foundation. In February, work grew by 714,000, as opposed to the 750,000 beforehand claimed, whilst March employment was upwardly revised by 3,000 to achieve 428,000.

Providers-based employers have introduced again some of the most positions yet again in April, as providers hastened to employ back workers permit go throughout the pandemic to satisfy renewed consumer demand from customers. Employment in the leisure and hospitality market increased by 78,000 in April, slowing just a little from March’s 100,000. Training and health products and services companies brought again a little a lot more work opportunities in April compared to March at 59,000. Transportation and warehousing payroll gains elevated a great deal much more markedly in April compared to March, growing by 52,000 in contrast to 9,500 all through the prior month.

In the goods-manufacturing sector, payroll development was tiny adjusted month-on-thirty day period, with positions rising by 66,000 in April. This was in convert led by hiring in production, where payrolls grew 55,000.

Meanwhile, the unemployment level held constant in April at 3.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, or just a hair earlier mentioned February 2020’s level of 3.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from prior to the pandemic. That, in flip, had been the lowest degree for joblessness considering the fact that 1969. And this came as the labor force participation charge unexpectedly dipped to 62.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from March’s 62.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, suggesting a smaller sized share of the population was possibly employed or actively trying to find do the job.

“Nearly 500,000 workers made a decision to depart the workforce in April. The big decline is a about prospect for organizations that are experiencing just one of the tightest labor marketplaces in many years,” Peter Essele, Head of Portfolio Management for Commonwealth Economical Community, explained in an email Friday early morning. Now, there are 11.5 million job openings and only 5.9 million unemployed, causing a significant mismatch in labor source and need that is fueling wage growth. A additional decline in the participate price could exacerbate the labor offer scarcity, resulting in additional wage pressures that will inevitably flow through to wide-based mostly inflation.”

Wages also climbed yet all over again, albeit at a slower month-to-month and once-a-year pace in comparison to March. On a thirty day period-more than-month basis, average hourly earnings greater by .3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, slowing from March’s upwardly revised .5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} improve. And on a yr-above-year basis, common hourly earnings ended up up 5.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

The latest increases in payrolls and wages and minimize in the unemployment price, however, have not given rise to a commensurate improvement in the economical wellbeing of many Americans. With inflation managing at 40-year highs, value raises for client products have outpaced earnings development. The U.S. Purchaser Cost Index (CPI) final rose at an 8.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} yr-on-calendar year price in March or the quickest considering that 1981, in accordance to the Bureau of Labor Figures.

“So numerous people appeared to be banking that if we could get unemployment down to 1st quarter 2020 ranges, almost everything would be fine,” Giacomo Santangelo, economist at the work platform Monster, stated in an e-mail earlier this 7 days. “What we are acquiring now is although the unemployment circumstance has improved on a macroeconomic scale, people are struggling with soaring charges that are threatening their typical of residing.”

Amid persistent inflation, the Federal Reserve previously this 7 days opted to increase fascination prices even further and declared the begin of quantitative tightening, or rolling assets off the central bank’s $9 trillion balance sheet. At his post-Fed assembly push meeting, Fed Chair Jerome Powell expressed optimism that the moves would be successful in addressing some of the demand-aspect components contributing to inflation and that, mixed with some easing in offer-facet constraints, these would assistance put a cap on mounting price ranges.

“Wages are running high, the maximum they’ve run in pretty some time. And they are a person fantastic instance … of how tight the labor marketplace really is,” Powell explained during his press convention Wednesday. “The reality that wages are working at the highest level in numerous decades. And that’s simply because of an imbalance amongst offer and demand from customers in the labor current market.”

“So we imagine via our policies, by way of even further therapeutic in the labor industry, increased fees, for illustration of emptiness filling and things like that, and more individuals coming again in we might like to consider that source and demand will occur back again into harmony,” he added. “And that, consequently, wage inflation will reasonable to nonetheless higher stages of wage raises, but kinds that are a lot more steady with 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} inflation. Which is our expectation.”

Emily McCormick is a reporter for Yahoo Finance. Adhere to her on Twitter: @emily_mcck

Go through the newest financial and business news from Yahoo Finance

Comply with Yahoo Finance on Twitter, Instagram, YouTube, Fb, Flipboard, and LinkedIn

What is a homeowners insurance premium?

What is a homeowners insurance premium?

Our goal here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” below, is to give you the tools and confidence you need to improve your finances. Although we do promote products from our partner lenders who compensate us for our services, all opinions are our own.

Here’s what you need to know about homeowners insurance premiums and how they work. (Shutterstock)

Homeowners insurance is vital because it can protect your home against various perils, such as fires, windstorms, break-ins, and other unexpected events. The price you pay for this insurance — your home insurance premium — varies based on multiple factors, including your home’s location, your insurance provider, your coverage amount and other considerations.  

Here’s what you need to know about homeowners insurance, and some tips on how to lower your premiums.   

Credible makes it easy to compare homeowners insurance quotes from various providers.

What is a homeowners insurance premium?

Your homeowners insurance premium is what you pay to an insurance provider to keep your policy active. What this insurance covers depends on your individual policy. 

That said, a standard homeowners insurance policy usually covers the following, according to the Insurance Information Institute: 

  • Your home’s structure
  • Your personal belongings
  • Liability coverage for any damage you or your family members cause to others
  • Living expenses if you have to temporarily relocate because of damages to your property.

The amount of home insurance you need depends on several factors, such as the value of your home and personal belongings, how much liability coverage you need, and how much it’ll cost to rebuild your home. 

How much is the average homeowners insurance premium?

The average cost of homeowners insurance across the U.S. in 2019 was $1,278 per year, or $106.50 per month, according to data from the National Association of Insurance Commissioners (NAIC). But depending on where you live and the coverage amount you need, the price you pay could be lower or higher than the national average.

Home insurance prices vary widely by state. For instance, Louisiana residents paid an average of $1,954 for home insurance in 2019, while Oregonians paid an average of $755. One possible reason for this difference is that Louisiana is more prone to natural disasters, like hurricanes, which makes insuring homes riskier for insurance companies.

These states had some of the most expensive average home insurance premiums in 2019, according to NAIC data:

  • Florida — $2,026
  • Louisiana — $1,954
  • Texas — $1,925
  • Oklahoma — $1,877
  • Mississippi — $1,577

These states had some of the least expensive average home insurance premiums in 2019:

  • Utah — $754
  • Oregon — $755
  • Wisconsin — $762
  • Idaho — $819
  • Nevada — $828

How do insurers calculate your homeowners insurance premium?

When you apply for homeowners insurance, an insurer usually considers these factors:

  • Location — Where you live has a huge impact on the price you pay for home insurance. Insurers typically review these factors about your location to assess your risk level: crime rates in your neighborhood, how prone the area is to extreme weather events (such as hurricanes or wildfires), your neighbors’ claims history, and how close your home is to a fire hydrant.
  • Square footage — Since larger homes tend to cost more to repair or rebuild than smaller homes, you’ll likely pay more to insure a larger home.  
  • Age of your home — The age of your home is also a huge factor. In general, the older your home, the more likely it is to need repairs. As a result, older homes usually cost more to insure.
  • Building materials — The cost to repair or replace your home’s building materials can also influence how much you pay for home insurance.
  • Claims history — If you’ve filed several home insurance claims in the past, your premiums may increase when you renew your policy or purchase a new one.
  • Credit-based insurance score — Most states allow insurers to use an insurance scoring model. This takes your credit history into account to assess how likely you are to file a claim. If you have a high insurance score and good credit, it could help you qualify for a lower insurance rate.
  • Deductible amount — Your deductible is the amount of money you pay before your insurance kicks in. The higher your deductible, the lower your insurance premium will be. But the downside is that you’ll pay a higher out-of-pocket expense if you file a claim.
  • Coverage amount — When choosing a policy, you should buy enough coverage to replace your home in the event it gets destroyed. The higher the amount of coverage you need, the higher your insurance premiums will be.
  • Discounts — Insurance companies offer several discounts, such as new homeowners discounts, claims-free discounts, safety feature discounts, and loyalty discounts. If you qualify, you can save money on your premiums.

What to know about homeowners insurance rate changes

The price of insuring your home can go up or down based on individual factors, such as a change in your insurance score, as well as factors beyond your control, like inflation. For instance, if the cost of building materials goes up, insurers may increase your premiums. But if you add certain features to your home, your premiums could decrease.

Why your homeowners insurance premiums might increase 

Why your homeowners insurance premiums might decrease

  • You bundled your home and auto insurance. Most insurers will give you a discount for purchasing auto insurance and home insurance together.
  • You added features to your house. You may receive a discount for adding certain safety features to your home, like a security camera system, alarm system, or automatic sprinkler system.
  • You installed a new roof. Insurance companies may give you a discount for installing a new roof, or one that’s made of specific material. For example, some insurers give customers a discount for installing certain types of metal roofs.

With Credible, you can compare homeowners insurance quotes from multiple providers, all in one place.

Ways to lower the cost of homeowners insurance

If the price of your homeowners insurance has increased or you believe it’s too high, here are five steps you can take to lower your premiums:

1. Shop around

Different insurance companies offer different rates and coverages.To get the best deal, compare rates and policies from at least three insurance companies. You can get free home insurance quotes online or by speaking with an insurance agent. When shopping, make sure to compare policies that have similar coverages.

2. Improve home security

You can get several discounts on your premiums for installing safety features that can reduce the risk of a criminal breaking into your home, or alert you about a potential disaster. These include video doorbells, camera monitoring, fire alarms, and smoke detectors. Check with your insurer to see what discounts are available.

3. Maintain good credit

Most states allow insurers to review your credit to assess how likely you are to file a claim. If you have good credit, you’re more likely to qualify for a lower premium. Two of the most important factors you should focus on are your payment history and total debt — combined, they account for 65{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your FICO Score.

By paying all your bills on time and paying down debts, you can typically maintain a healthy credit score. And if you don’t have good credit, adopting these two credit-building habits could boost your credit score over time.

Another way to maintain good credit is to make sure your credit reports contain accurate information. You can view your credit reports from the three major credit reporting agencies — Equifax, Experian, and TransUnion — for free by visiting AnnualCreditReport.com. If you see any errors, you can dispute them directly with the corresponding credit bureau.

4. Pay in full

When you purchase home insurance directly from an insurance company, you usually have two options: Pay in full or make installment payments. If you choose to pay the cost of your annual premium upfront, you may receive a discount.

5. Bundle multiple insurance types

Do you have other insurance policies, like auto insurance, boat insurance, or motorcycle insurance? Some insurers may offer you a discount if you choose to purchase your home insurance and other types of insurance policies from them, instead of from several companies.

How to pay your homeowners insurance premium

You can pay your homeowners insurance premium in two ways: through an escrow account or by paying your insurance provider directly. If you pay via escrow, the cost of your home insurance gets added to your monthly mortgage payments. Your lender uses the funds to pay your homeowners insurance on your behalf.

If you choose to pay your home insurance provider directly, you can usually make monthly, quarterly, or yearly payments. Though it depends on the insurance company, you can typically make these payments via a bank draft or credit card.

What happens if you don’t pay your home insurance premium?

Most lenders require you to have homeowners insurance to protect the value of your loan. If you don’t pay your home insurance premiums, your insurance policy could lapse. When this happens, your lender may purchase a homeowners insurance policy on your behalf, and this new policy could be much more expensive.

Allowing your home insurance to lapse is risky because it leaves your home unprotected. If an unfortunate event happens, like a fire or windstorm that damages your home, you’ll have to pay for the cost of repairs or replacement out of your own pocket. Plus, your current insurer or a new one will likely charge you a higher premium.

Visit Credible to compare homeowners insurance quotes from different insurers in minutes.