Aon PLC noted elevated whole profits, organic and natural profits and gain for the fourth quarter of 2021, but the $1 billion dollar termination payment it paid in the third quarter associated to its unsuccessful bid to acquire Willis Towers Watson PLC dragged down earnings for the year.
In 2022, the brokerage expects to see fees rise as wages improve and travel and enjoyment prices increase two many years immediately after the starting of the COVID-19 pandemic, but it expects to see money added benefits if desire premiums rise.
Aon reported fourth-quarter earnings of $3.08 billion, a 3.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} improve more than the similar time period the prior 12 months. On an natural basis, which excludes the effect of mergers and acquisitions and foreign exchange fluctuations, income greater 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
Rival brokerages have also documented powerful natural and organic income growth for the fourth quarter as insurance prices ongoing to increase in 2021.
Income for Aon’s main coverage brokerage business enhanced 11{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $1.85 billion, up 12{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on an natural basis reinsurance earnings rose 12.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $222 million, up 13{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on an organic and natural foundation overall health consulting revenue fell 13. 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $651 million but enhanced 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on an organic and natural basis, reflecting the sale of its retiree health treatment exchange company and retirement and investment profits grew 1.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $364 million, up 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on an organic and natural foundation.
Internet money greater 63.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $873 million as functioning fees fell and profits greater owing to the sale of the retiree health and fitness trade, which was initially agreed on as part of its unsuccessful hard work to buy rival Willis Towers Watson.
For the complete 12 months, Aon claimed earnings of $12.19 billion, up 10.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and web cash flow of $1.31 billion, down 35.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Aon paid out a $1 billion termination cost in the third quarter related to the scuttled Willis deal, which fell apart in July due to antitrust fears.
On the lookout ahead, Aon expects to see an boost in shell out-associated expenditures this 12 months and will probably reward from mounting interest premiums, the brokerage’s major monetary executive reported on a conference connect with with analysts Friday.
Aon expects to broaden its earnings margin this yr “and as we seem to 2022 we also assume investments in colleagues, some ongoing resumption of (journey and entertainment expenses) and investments in extended-time period advancement,” mentioned Christa Davies, the brokerage’s main economic officer.
But Aon expects wage inflation to be offset by efficiencies, she claimed.
If curiosity prices rise, it will be “very positive” for Aon for the reason that its fiduciary financial investment income will rise by $60 million every time there is a 100 basis issue enhance in small-term desire charges and the company’s pension liabilities will be diminished, among other matters, Ms. Davies explained.
NEW DELHI — India’s government on Tuesday unveiled its yearly spending plan, which proposed a substantial expending improve for highways, road and airports, but a lesser improve for rural advancement and employment.
The $530 billion finances for the fiscal calendar year starting on April 1 place forth by Prime Minister Narendra Modi’s governing administration calls for a key financial commitment in infrastructure, but critics explained it would do way too very little to address urgent troubles facing the state. Among the the huge types: soaring unemployment, declines in residence revenue and private expending, and mounting discontent more than financial inequality that the pandemic has made additional obvious.
The coronavirus has hobbled India’s economy, robbing it of momentum desired to provide positions for its young and quickly-developing do the job force. It has also worsened longer-term troubles that have been now dragging down progress, these types of as significant debt, a absence of competitiveness with other international locations and plan missteps.
“You have to expand much a lot quicker on a sustained foundation. Which is what we never have,” stated Priyanka Kishore, the head of India and Southeast Asia for Oxford Economics, a analysis firm.
Persons across the board have witnessed an erosion of their true incomes, said Sunil Kumar Sinha, the principal economist at India Scores, a credit score ratings agency. “The profits growth is not even matching up to the charge of inflation in the overall economy,” he explained.
As a result, numerous center-course Indians have set off buying washing equipment, substantial-display televisions and kitchen area appliances, merchandise they once splurged on in the course of the pageant period. Demand from customers is also cooling off in poorer, rural locations, professionals say.
The govt experienced believed that India’s economy would develop 11 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for the 12 months that ends upcoming month. It has now reduced that estimate, to 9.2 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. The estimate for the coming year is 8 to 8.5 per cent.
A purchasing mall in Kochi, Kerala Condition, in December. The financial slowdown prompted several middle-course Indians to place off key expenses. Credit score…R S Iyer/Linked Press
These numbers occur on the back again of a deep contraction of 7.3 per cent in the calendar year that finished in March 2021, when Mr. Modi imposed a nationwide lockdown to curb the unfold of the coronavirus. Hundreds of 1000’s of persons missing their work opportunities and went again to their villages, trying to eke out a living from meager farm plots.
The government’s ambitious vaccination application served bring back some momentum, but Mr. Modi’s unwillingness to shell out large has held back development, economists say.
The new budget calls for a 35 percent increase in shelling out, primarily on infrastructure linked jobs. The governing administration stressed that the emphasis on design would extend the financial state.
“The approach is driven by 7 engines, specifically streets, railways, airports, ports, mass transportation, waterways and logistics infrastructure,” Nirmala Sitharaman, Mr. Modi’s finance minister, claimed whilst presenting the budget in Parliament. “All 7 engines will pull forward the economic system in unison.”
But the proposal is a lot less generous on rural work packages, and did not give something economists have extensive urged: an city employment plan to enable each day wage laborers in the country’s huge cities.
Economists are specially worried about the gradual rate of career generation, as millions of people are continue to out of work or have presented up their research fully.
Right before the pandemic strike, India was lifting thousands and thousands of folks out of poverty. It took the nation decades to have an economic climate substantial enough to hire extra than 400 million men and women, mentioned Mahesh Vyas, the chief govt of the Middle for Checking Indian Economy. Now, the country has an added 187 million people who have to have work, he said, a tall buy in the latest conditions.
The deep scarring to the financial state is specifically obvious in the stats for employment and work. The centre estimated that only 38 p.c of the country’s doing the job-age population was utilized in 2020.By June 2021, the quantity experienced dropped to 34.6 percent, it claimed.
“That implies folks do not have food items on the table,” stated Ms. Kishore, of Oxford Economics. “People are not even searching simply because they are so discouraged.”
Migrant personnel in New Delhi seeking to return residence in May perhaps 2020, when a national pandemic lockdown led to hundreds of countless numbers of missing careers.Credit score…Rebecca Conway for The New York Occasions
The desperation has been spilling out onto the streets just as Mr. Modi and his bash face a vital test in state elections in the coming months.
Previous 7 days, hundreds of applicants for railway work opportunities burned coach coaches to protest what they stated ended up the Modi government’s unfair recruitment tactics. Extra than 12 million people today applied for 35,281 employment.
“Protests due to the fact of the railways positions is a reflection of irritation amid the youth as the govt has moved considerably way too gradually, virtually dithered, in supplying the careers it promised in 2019,” Mr. Vyas mentioned.
A big share of the government’s spending will be lifted from borrowing and taxes, together with these on gas and fertilizers, which have contributed to climbing rates of food stuff and crucial commodities. A further major concern for economists is the government’s attempts to keep its deficits in manage by reducing the paying out on social techniques and welfare.
They have prolonged argued for higher taxes on companies and the country’s rich to permit the authorities to devote extra in this kind of parts, a demand that wasn’t tackled in the funds.
The expending system involves approval by the Parliament in advance of it goes into result in April.
Dr. Sinha stated that the government’s target on infrastructure expending may possibly deliver gains in the medium to long term, but that just one of the most vital pieces that was lacking from the funds was a extensive program to provide again usage.
“The trouble with this kind of expending is that it will have a truthful quantity of gestation time period,” he claimed. “But the problem that the financial system is dealing with at the present instant is that family sentiments, family incomes, every little thing is less than strain.”
“Something needs to be done to place revenue in the pockets,” he reported.
An posting to produce a Martha’s Winery housing bank will go on the city assembly warrant with a damaging recommendation from the Edgartown finance committee, following a unanimous vote by the committee this week.
“I want to look at this by a economical lens . . . And I am worried,” stated committee member Leslie Baynes, who led a joint meeting with the selectmen Wednesday, a recording of the assembly demonstrates.
“I believe as a committee that we should really not vote for this. I think it’s fraught with danger,” Mr. Baynes continued. “I have nonetheless to see the effect on infrastructure Islandwide, and the profits that’s likely to be lifted is just astromonical. We are all worried about the housing circumstance and almost everywhere you change, the fingers stage to it.”
Finance committees in every Island town per year go as a result of a system of examining warrant article content and generating recommendations. The tips are not binding.
The housing financial institution short article will go on each and every town meeting warrant this spring, and is aimed at supporting laws to deliver to the point out legislature. A coalition to produce the housing financial institution is nevertheless doing the job on the draft laws.
Coalition coordinator Laura Silber attended the Wednesday meeting.
The housing lender discussion was brief but pointed, with Mr. Baynes saying he concurred with select board member Margaret Serpa, who dissented last thirty day period when the board voted 2-1 to set the short article on the warrant.“I consider it was put incredibly perfectly by Margaret,” Mr. Baynes claimed.
Estimates show the premier share of funding for an Islandwide housing financial institution would come from Edgartown.
Mr. Baynes also elevated concerns about what he claimed would be the creation of a “huge bureacracy.” Modeled just after the Martha’s Vineyard Land Lender, the housing bank would contain elected commissioners and appointed town advisory boards with the energy to shell out tens of millions gathered from a true estate transfer charge to develop very affordable housing tasks.
“I have been dwelling below since 1969 and record has demonstrated me that we really do not do as well effectively with regional entities,” Mr. Baynes claimed.
“Living in this article all these many years I am really involved. This town has been pretty excellent to me and a aspect of me suggests that to recommend this at this point in time would be a disservice to the group.”
Committee member Paul Pertile echoed Mr. Baynes.
“I agree with you,” he reported. “I as well fear about the total of profits and what it would do to actual estate in city.”
He concluded: “You’re heading to have to enable the voters decide. That’s the essential.”
Record-low housing inventory, high prices and low mortgage rates made an interesting backdrop for the 2021 real estate market. Millions fought tooth and nail to close on homes throughout the year, but millions more were unsuccessful in their attempts.
The 2021 housing market was booming, but that doesn’t mean buying a house was a breeze. In fact, 66{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Americans who started last year with intentions to buy were unsuccessful, according to NerdWallet’s 2022 Home Buyer Report. With a lofty 26 million planning to buy homes this year, according to the survey, the lessons from failed 2021 attempts may contain guidance for this year’s shoppers.
More than one-third (35{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) of Americans who planned to buy a home in 2021 but didn’t do so say they postponed or canceled those plans due to the pandemic or related effects. Of course, there’s very little individual buyers can do about the broad public health and economic impacts we’re all experiencing, but that doesn’t mean all hope is lost.
People are also reading…
Studying the most common barriers to buying in 2021 may give prospective homeowners the edge they need to close a deal this year.
1. Competitive offers close deals
Low inventory amid high demand makes for a competitive market, and in that regard, 2022 will be similar to 2021. One-fourth (25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) of Americans who planned, but failed, to buy a home in 2021 say they made an offer on at least one home but didn’t ultimately go under contract.
A competitive offer isn’t only the highest offer. Sure, money talks, and you’re more likely to be successful if you can outbid the competition. But there are other ways to make your offer stand out.
Make the transaction look as easy as possible by keeping it simple and convenient for the seller. Demonstrate your ability to pay with a mortgage preapproval, suggest a speedy closing and let the seller choose the date, and offer to buy the home as-is after it’s professionally inspected. Your real estate agent can help you write an offer that gets moved to the top of the pile, without putting you at undue risk.
2. Available homes may not be perfect homes
The greater the housing shortage, the more flexible potential buyers will need to be.
One-fourth (25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) of unsuccessful buyers in 2021 say they held off on their plans because they couldn’t find a home that met their needs. There’s a good chance the line between wants and needs, for many in this group, isn’t clearly defined.
Before you begin shopping, make a list of all of the features you’d like to have in a home. Then, mark those that aren’t truly necessary. The more features you can compromise on, the more likely you are to end up with a home of your own. This doesn’t mean you need to be willing to stuff a family of five into two bedrooms, but maybe you can do without a two-car garage or a finished basement.
3. Buying in 2022 will still be tough
Nearly one-fourth (24{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) of unsuccessful buyers last year say they held off on their buying plans because they think it will be easier to buy in 2022. But the forces that made homebuying a challenge in 2021 will largely continue in 2022.
The rate of price growth may level off somewhat in the coming year, but prices aren’t likely to reverse course and come down dramatically. And the shortage of homes on the market isn’t likely to experience a dramatic change either. According to the same survey, of the potential home sellers who want to put their home on the market this year, 89{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} say something is holding them back — including concerns about being able to find or afford a new home themselves.
If you hope to buy this year, brace yourself for a challenge. Realistic expectations can insulate you from disappointment and help you build contingency plans for when you find yourself battling it out with other potential buyers.
4. Current home prices could bust budgets
It’s tempting to borrow more money or overextend yourself to get under contract. Don’t. Nearly one-fourth (24{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) of last year’s successful buyers say they walked away from the market because they couldn’t afford the homes that were available.
Be fastidious when setting your homebuying budget, with the resolve that you’ll stick to it when the going gets tough. Stretching too far to buy a home only to find yourself house poor can be a recipe for sleepless nights under your new roof. A home affordability calculator can get you started in the right direction, accounting for all of your existing expenses along with those that come with homeownership.
5. Borrowing for a home isn’t a sure thing
Qualifying for a mortgage generally takes an adequate and consistent income, a manageable amount of existing debt and a credit history that makes you a good risk for lenders. While 16{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of unsuccessful 2021 home buyers cited not being able to qualify for a mortgage, it’s possible some of them didn’t actually apply and merely assumed they would be denied.
Buying a home is most often a long-term goal, and it can take years to get your income and credit in shape enough to get a mortgage. Aim for a credit history that showcases on-time payments, keep debt levels down and save up a down payment to make your mortgage application most attractive. Keep in mind, a healthy down payment will reduce the total cost of your home loan by saving you in interest and private mortgage insurance (required on mortgages that have less than a 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} down payment).
There are also programs available for first-time buyers that can make it somewhat easier to qualify for a home loan.
Check out more of this week’s best money reads from experts:
50 college majors that earn the least money
50 college majors that earn the least money
Career choices are often based on personal interests, experience, and potential income—and more and more, they require at least a college degree. What undergraduates choose to major in during college can be a strong indicator of what an individual’s financial future looks like—and it’s not always rosy news.
Stacker researched the 50 college majors that earn the least money, using PayScale’s 2020 College Salary Report. This report, released in 2021, surveyed 3.5 million college graduates and 835 bachelor degrees ranked by mid-career median salary, or the fitted salary one makes after working in the field for over 10 years. By definition, a fitted salary combines the base annual salary or hourly wage, bonuses, profit sharing, tips, commissions, overtime, and other forms of cash earnings.
Stock compensation was not included when considering the annual salary of each college major, but can be a significant portion of pay for specific executive and high-tech jobs. Further, a wage for the noted college major does not include the cash value of retirement benefits or the amount of other noncash benefits, including health care and other ancillary benefits. PayScale’s salaries do not directly reflect those of the U.S. Bureau of Labor and Statistics (BLS). For most of the majors, BLS salaries are higher, even though the level of education required is the same.
Additionally, several low-paying teaching majors on the list confirm the plight of educators who graduate but can’t make ends meet on a minimum salary. Between rising student debt and inflation, it is likely many who majored in the noted subjects have second jobs to pay the bills.
Read on to find out the 50 college majors that earn the least money.
Pastoral ministers help people in times of spiritual distress and lead religious organizations. But people don’t pay for spiritual counsel, other than tithes, and therefore there are no typical ways to drive up earnings.
Legal assistants may hope to become lawyers, who typically earn significantly higher salaries. However, without a law degree, legal assistants are only legally allowed to perform certain tasks, which caps the value of their services.
Applied management workers evaluate the success of different business practices and work to implement better and more efficient modes of decision-making and operations. While some who work in this profession may assist corporations like banks or tech firms, others may assist nonprofits or companies in industries that tend to pay less.
Monkey Business Images // Shutterstock
#42. Vocal performance (tie)
– Early career pay: $38,900
– Mid-career pay: $55,300
While some vocal performance majors may go on to perform in sold-out arenas, many end up working in less lucrative careers. These include positions at churches, such as worship pastors and directors of music ministry, which come with decidedly lower salaries.
DGLimages // Shutterstock
#42. Tourism and travel (tie)
– Early career pay: $40,600
– Mid-career pay: $55,300
California State University touts high figures when promoting its travel and tourism major, including that one in every nine U.S. jobs depends on the industry, and that travel and tourism support over 8 million jobs nationwide. According to the school, some in management positions have the potential to earn more than $100,000 annually, including those working as a convention and visitors bureau director or a wedding planner. But typical pay is closer to half that figure.
All jobs depend on having clients, and this includes religious jobs. Bible studies and theology professionals face challenging headwinds in the United States in this respect. Fewer Americans than ever report themselves as religious.
There are several special education career paths to take after majoring in the subject, aside from teaching. Prospects of becoming a residential manager, preschool director, or direct support professional is why some choose the undergraduate major, then get their master’s degree. Working with the disabled is in high demand, due to teachers retiring and more students needing help.
Olesia Bilkei // Shutterstock
#37. Family studies (tie)
– Early career pay: $35,900
– Mid-career pay: $54,500
Family studies professionals help tutor, develop, and supervise children. Some competition they face in commanding high salaries? Teenage babysitters, whom parents may feel more comfortable paying lower wages.
Students looking to major in ceramics will learn about the science behind materials, plus sculpture and drawing skills. Courses in personal style development, wheel-throwing techniques, firing and kiln operation, oxidation, ceramic murals, mixed media, and slips and glazes are usually required to graduate. Many with a degree in ceramics become professional potters, teachers, artists, or sculptors.
Community development workers perform a wide array of tasks, from zoning and building inspections to budgets. However, they are typically paid by the government, so their salaries are capped within a certain range.
Pormezz // Shutterstock
#31. Health and human services
– Early career pay: $41,500
– Mid-career pay: $53,700
Health and human services encompasses a vast array of jobs. On the higher end of the pay scale, these include jobs such as public health directors. But many other jobs included in health and human services typically have lower pay rates, such as social workers and correctional treatment specialists.
Manager may sound like a high-ranking title, but an office manager’s responsibilities are inherently clerical. This means they oversee other administrative activities in an office, and even when supervising, act in an assistant capacity to the executives and other workers in an office.
Majoring in history teacher education likely means most graduates will teach the subject in elementary, secondary, or postsecondary schools. Being a history teacher, like other instruction degrees, requires those who major in the subject to become state-certified after student teaching. History teachers may work with special education teachers to make learning more accessible for students with learning difficulties, and can work with debate teams, for example, because of their knowledge of current events.
Youth ministers work with children and teens to coordinate related activities at a church or religious organization. Churches typically operate as nonprofits, and therefore the salaries of their workers, including youth ministers, lack the ability to respond to the market and offer higher salaries.
Majoring in elementary education means teaching and instructing young students. Majors in the program must choose a specific subject to study, including either math, history, science, or English. Some who major in the subject consider careers as guidance counselors, juvenile correction officers, long-term substitute teachers, online instructors, preschool teachers, or adjunct professors.
Voice and opera students preparing to perform on a professional level after graduation must learn theatrical techniques and stage repertory through courses including diction, foreign languages, music theory, and humanities. While receiving private instruction during the undergraduate curriculum, students also perform in choral ensembles. Students who choose not to sing opera after studying the major can easily transition into other careers, including teaching art, drama, or music, or becoming a musical director or composer.
Igor Bulgarin // Shutterstock
#19. Human services (tie)
– Early career pay: $36,600
– Mid-career pay: $50,700
Although careers in human services vary widely, their common denominator is that they help people who would likely be unable to help themselves. As such, these jobs, which range from family court advocates to crisis support workers, serve overall a population with limited resources who may not be able to compensate them highly.
YP_Studio // Shutterstock
#18. Elementary teaching (tie)
– Early career pay: $34,400
– Mid-career pay: $50,700
Elementary teaching majors will teach kindergarten through eighth grade. Courses in classroom management and curriculum and instruction help prepare future graduates to teach. A core group of classes, including English, mathematics, history, social studies, foreign languages, and science are required for all elementary teaching majors, who must become certified in the state they work in.
Monkey Business Images // Shutterstock
#17. Baking and pastry arts
– Early career pay: $36,000
– Mid-career pay: $50,600
These days, it seems that everyone is a food blogger. And this means that more people than ever are likely to be trying their hands at baking and pastry-making at home, reducing the need for specialized bakers.
hryshai olena // Shutterstock
#16. Human services management
– Early career pay: $43,500
– Mid-career pay: $50,500
Human services management jobs are a specific role for those interested in helping or managing others in social work or related fields. Although the average salary is not extremely high, these positions pay more than nonsupervisory roles in the same field. Many of these roles require additional licensing.
After majoring in middle school education, graduates go on to teach students in grades 5 through 9. Teaching that specific age group entails taking undergraduate courses in a breadth of subjects, including English, science, mathematics, and social studies. Washington University in St. Louis suggests those majoring in middle school education may consider adding a concentrated study in their curriculum, since middle schools are interdisciplinary and teachers who have expertise in more than one content field may have an advantage in the job market.
SpeedKingz // Shutterstock
#11. Educational psychology
– Early career pay: $34,600
– Mid-career pay: $47,600
Educational psychologists typically work with schools to support the education and development of children. While some may be employed by private schools that draw from a significant tuition and donor base to pad staff salaries, others may work for public schools, which typically have more limited resources to draw upon.
Students who major in early childhood and elementary education prepare to teach in both preschool and after-school programs, as well as kindergarten through sixth grade. Graduates must become certified to instruct students in whatever state they choose for work. With further schooling, some graduates of the major go onto to become administrators, such as principals, superintendents, directors of curriculum, and college deans.
Iam_Anupong // Shutterstock
#9. Rehabilitation counseling
– Early career pay: $38,000
– Mid-career pay: $46,100
Rehabilitation counselors typically work to serve people living with disabilities. These services can range from mental health to physical health to practical life-skills training, and can be performed everywhere from detention centers to unemployment offices. Recipients typically do not pay for such services, and as such the salaries of rehabilitation counselors are limited.
Outdoor education professionals help people enjoy the great outdoors. However perfect they may be for the outdoors enthusiast, some of these jobs are run by the government, which means they are capped within a certain pay bracket.
Rawpixel.com // Shutterstock
#6. Child and family studies
– Early career pay: $34,100
– Mid-career pay: $43,600
Childcare is one of the lowest-paying professions in the United States. One reason may be that many teenagers and other younger adults will work as babysitters and tutors to make side money, which makes it more difficult for professionals to demand higher wages.
A child’s cognitive, emotional, and language development occur in the first five years of life, making early childhood education critical in an adolescent’s academic career. However, it is one of the lowest-paying majors on the list, further proving that those who enter the field are likely more concerned about the community than salary.
Monkey Business Images // Shutterstock
#4. Mental health
– Early career pay: $35,200
– Mid-career pay: $42,500
Mental health is a field that encompasses many different settings. Some mental health specialists may work in assisted living facilities, helping residents with dementia, while others may work with working professionals stressed and depressed about their jobs. Those working in private practice theoretically have no caps to their salaries, while those working in institutions may be more constrained by salary caps.
Addiction counselors work to help those who are struggling with alcohol and substance abuse disorders. While some counselors may work at private rehabilitation clinics where fees allow the clinics to pay staff generously, many others work in the public sector, helping people in facilities run by state, local, and federal government.
Motortion Films // Shutterstock
#1. Metalsmithing
– Early career pay: $38,300
– Mid-career pay: $38,400
Many workers with degrees in metalsmithing find work as jewelers. Those working in the retail trade tend to make the most.
Career choices are often based on personal interests, experience, and potential income—and more and more, they require at least a college degree. What undergraduates choose to major in during college can be a strong indicator of what an individual’s financial future looks like—and it’s not always rosy news.
Stacker researched the 50 college majors that earn the least money, using PayScale’s 2020 College Salary Report. This report, fresh with 2021 data, surveyed 3.5 million college graduates and 835 bachelor degrees ranked by mid-career median salary, or the fitted salary one makes after working in the field for over 10 years. By definition, a fitted salary combines the base annual salary or hourly wage, bonuses, profit sharing, tips, commissions, overtime, and other forms of cash earnings. Ties are broken by early career salary.
Stock compensation was not included when considering the annual salary of each college major but can be a significant portion of pay for specific executive and high-tech jobs. Further, a wage for the noted college major does not include the cash value of retirement benefits or the amount of other noncash benefits, including health care and other ancillary benefits. PayScale’s salaries do not directly reflect those of the U.S. Bureau of Labor and Statistics (BLS). For most of the majors, BLS salaries are higher, even though the level of education required is the same.
Additionally, several low-paying teaching majors on the list confirm the plight of educators who graduate but can’t make ends meet on a minimum salary. Between rising student debt and inflation, it is likely many who majored in the noted subjects have second jobs to pay the bills.
Read on to find out the 50 college majors that earn the least money.
Students looking to major in ceramics will learn about the science behind materials, plus sculpture and drawing skills. Courses in personal style development, wheel-throwing techniques, firing and kiln operation, oxidation, ceramic murals, mixed media, and slips and glazes are usually required to graduate. Many with a degree in ceramics become professional potters, teachers, artists, or sculptors.
Viktor Gladkov // Shutterstock
#48. Vocal performance
– Early career pay: $42,600
– Mid-career pay: $58,000
While some vocal performance majors may go on to perform sold-out arenas, many end up working in less lucrative careers. These include positions at churches, such as worship pastors and directors of music ministry, which come with decidedly lower salaries.
DGLimages // Shutterstock
#47. Pastoral ministry
– Early career pay: $38,700
– Mid-career pay: $58,000
Pastoral ministers help people in times of spiritual distress and lead religious organizations. But people don’t pay for spiritual counsel—other than tithes—and therefore there are no typical ways to drive up earnings.
All jobs depend on having clients, and this includes religious jobs. Bible studies and theology professionals face challenging headwinds in the United States in this respect. Fewer Americans than ever report themselves as religious.
Legal assistants may hope to become lawyers, who typically earn significantly higher salaries. However, without a law degree, legal assistants are only legally allowed to perform certain tasks, which caps the value of their services.
PhuShutter // Shutterstock
#41. Special education
– Early career pay: $41,300
– Mid-career pay: $57,000
There are several special education career paths to take after majoring in the subject, aside from teaching. The prospect of becoming a residential manager, preschool director, or direct support professional is why some choose the undergraduate major, then get their master’s degree. Working with the disabled is in high demand due to teachers retiring and more students needing help.
Family studies professionals help tutor, develop, and supervise children. Some competition they face in commanding high salaries? Teenage babysitters, whom parents may feel more comfortable paying lower wages.
Health and human services encompass a vast array of jobs. On the higher end of the pay scale, these include jobs such as public health directors. But many other jobs included in health and human services typically have lower pay rates, such as social workers and correctional treatment specialists.
Majoring in history teacher education likely means most graduates will teach the subject in elementary, secondary, or postsecondary schools. Being a history teacher, like other instruction degrees, requires those who major in the subject to become state-certified after student teaching. History teachers may work with special education teachers to make learning more accessible for students with learning difficulties and can work with debate teams, for example, because of their knowledge of current events.
Applied behavioral science is essentially the study of why people behave in certain ways. If it sounds broad, that’s because it is. Graduates often pursue career opportunities in the fields of human resources, human services, and consumer science, among others.
Youth ministers work with children and teens to coordinate related activities at a church or religious organization. Churches typically operate as nonprofits, and therefore the salaries of their workers, including youth ministers, lack the ability to respond to the market and offer higher salaries.
BRAIN2HANDS // Shutterstock
#24. Elementary education
– Early career pay: $40,000
– Mid-career pay: $53,800
Majoring in elementary education means teaching and instructing young students. Majors in the program must choose a specific subject to study, including either math, history, science, or English. Some who major in the subject consider careers as guidance counselors, juvenile correction officers, long-term substitute teachers, online instructors, preschool teachers, or adjunct professors.
wavebreakmedia // Shutterstock
#23. Voice and opera
– Early career pay: $34,500
– Mid-career pay: $53,300
Voice and opera students preparing to perform on a professional level after graduation must learn theatrical techniques and stage repertory through courses such as diction, foreign languages, music theory, and humanities. While receiving private instruction during the undergraduate curriculum, students also perform in choral ensembles. Students who choose not to sing opera after studying the major can easily transition into other careers, including teaching art, drama, or music, or becoming a musical director or composer.
Igor Bulgarin // Shutterstock
#22. Conflict resolution
– Early career pay: $44,400
– Mid-career pay: $53,200
Whether it’s on an international scale or between two individuals, where there is conflict, there is a need for conflict resolution. Conflict resolution specialists and mediators often require advanced degrees and many years of experience to be established in the field.
Human services management jobs are a specific role for those interested in helping or managing others in social work or related fields. Although the average salary is not extremely high, these positions pay more than nonsupervisory roles in the same field. Many of these roles require additional licensing.
fizkes // Shutterstock
#19. Baking and pastry arts
– Early career pay: $37,500
– Mid-career pay: $53,000
These days, it seems that everyone is a food blogger. And this means that more people than ever are likely to be trying their hands at baking and pastry-making at home, reducing the need for specialized bakers.
Although careers in human services vary widely, their common denominator is that they help people who would likely be unable to help themselves. As such, these jobs, which range from family court advocates to crisis support workers, service overall a population with limited resources who may not be able to compensate them highly.
After majoring in middle school education, graduates go on to teach students in grades five through nine. Teaching that specific age group entails taking undergraduate courses in a breadth of subjects, including English, science, mathematics, and social studies. Washington University in St. Louis suggests those majoring in middle school education consider adding a concentrated study in their curriculum, since middle schools are interdisciplinary and teachers who have expertise in more than one content field may have an advantage in the job market.
SpeedKingz // Shutterstock
#11. Mental health counseling
– Early career pay: $36,100
– Mid-career pay: $50,000
Becoming a licensed mental health counselor requires time, study, and practice—years of it. Professionals can focus on working with specific populations, like children, military veterans, or people with addiction. And there is no shortage of need for these services. More than 15 million people in the U.S. live in mental health care health professional shortage areas.
Students who major in early childhood and elementary education prepare to teach in both preschool and after-school programs, as well as kindergarten through sixth grade. Graduates must become certified to instruct students in whatever state they choose for work. With further schooling, some graduates of the major go on to become administrators, such as principals, superintendents, directors of curriculum, and college deans.
Child care is one of the lowest-paying professions in the United States. One reason may be that many teenagers and other younger adults will work as babysitters and tutors to make side money, which makes it more difficult for professionals to demand higher wages.
MiniStocker // Shutterstock
#6. Rehabilitation counseling
– Early career pay: $39,200
– Mid-career pay: $46,400
Rehabilitation counselors typically work to serve people living with disabilities. These services can range from mental health to physical health to practical life-skills training and can be performed everywhere from detention centers to unemployment offices. Recipients typically do not pay for such services, and as such, the salaries of rehabilitation counselors are limited.
Outdoor education professionals help people enjoy the great outdoors. However perfect they may be for the outdoors enthusiast, some of these jobs are run by the government, which means they are capped within a certain pay bracket.
Rawpixel.com // Shutterstock
#4. Early childhood education
– Early career pay: $36,100
– Mid-career pay: $45,400
A child’s cognitive, emotional, and language development occur in the first five years of life, making early childhood education critical in an adolescent’s academic career. However, it is one of the lowest-paying majors on the list, further proving that those who enter the field are likely more concerned about the community than salary.
Monkey Business Images // Shutterstock
#3. Mental health
– Early career pay: $36,900
– Mid-career pay: $45,000
Mental health is a field that encompasses many different settings. Some mental health specialists may work in assisted living facilities, helping residents with dementia, while others may work with working professionals stressed and depressed about their jobs. Those working in private practice theoretically have no caps to their salaries, while those working in institutions may be more constrained by salary caps.
U.S. businesses included again much far more positions than envisioned in January even as Omicron circumstances surged at the beginning of the new 12 months.
The Labor Division produced its January work opportunities report Friday at 8:30 a.m. ET. Here were being the most important metrics from the print, as opposed to consensus estimates compiled by Bloomberg:
Non-farm payrolls: +467,000 vs. +125,000 envisioned and a revised +510,000 in December
Unemployment level: 4.{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}vs. 3.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} anticipated, 3.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in December
Average hourly earnings, thirty day period-over-thirty day period: .7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs..5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} predicted and a revised .5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in December
Normal hourly earnings, 12 months-more than-calendar year: 5.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. 5.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} predicted, 4.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in December
The January work opportunities report marks the initial to replicate a fuller affect from the Omicron variant. The very contagious variant 1st found in the U.S. in late November had only just begun to distribute by the time of the December jobs report survey time period. Close to the time of the January study time period in the middle of the month, new each day COVID-19 instances in the U.S. experienced soared to a report.
Even now, task development held up a lot additional robustly than expected at the commence of the calendar year. Moreover, payrolls gains for December ended up sharply upwardly revised, more pointing to momentum in the labor industry heading into the new year. Non-farm payrolls grew by 510,000 in December, the Labor Office mentioned in its revision on Friday, or nicely previously mentioned the 199,000 previously documented last thirty day period.
And the renewed bounce in COVID-19 cases was predicted to weigh primarily seriously on the higher-get in touch with solutions sector, which has remained extremely susceptible to increasing bacterial infections ranges. Nevertheless career progress in leisure and hospitality industries remained beneficial for January, with payrolls rising by 151,000 compared to the 163,000 introduced back in December. Retail trade payrolls accelerated to see a increase of extra than 60,000 employment in January from the 40,100 in December.
Heading into Friday’s report, estimates for the headline January print on non-farm payrolls ran the gamut as top rated Wall Avenue economists tried to forecast the most up-to-date virus-relevant velocity bump to the labor market’s recovery. But the top consequence from the January careers report exceeded even the optimum estimate. At the higher close, various economists polled by Bloomberg anticipated 250,000 jobs to return in January. Even so, a selection of pundits also saw job progress turning detrimental for the initial time since December 2020, with at the very least 1 economist forecasting a drop of 400,000 payrolls for January.
But several also pointed out that the most recent positions report would serve as an imperfect indicator of the fundamental strength in the labor industry because of to Omicron-associated disruptions. The Labor Section counts persons paid in the course of the study time period, or the week including the 12th of the month, as utilized for the headline payrolls determine. People on unpaid go away owing to disease or if not, even so, are excluded from the headline payrolls rely.
“The 467,000 achieve in non-farm payrolls in January is even stronger than it appears, as it arrived regardless of the spike in absenteeism driven by the Omicron virus wave and was accompanied by sizeable upward revisions to the gains more than the previous couple of months,” Andrew Hunter, senior U.S. economist for Cash Economics, reported in a take note on Friday. “The headline acquire appears to make a mockery of our fears that Omicron would weigh closely on the payrolls figures, with leisure and hospitality work rising by a reliable 151,000. Irrespective of thousands and thousands of workers getting to self-isolate, there were being also sturdy gains in experienced and organization services, retail and transportation and warehousing.”
Other metrics in the most up-to-date careers report also held up as strongly or extra strongly than envisioned. However the unemployment level edged up to 4.{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, it remained only slightly higher than the pandemic-period very low of 3.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from December, which had been the cheapest because February 2020. And the labor power participation amount unexpectedly improved to 62.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, or the greatest degree because March 2020, in a indicator that a lot more persons have been returning to the workforce from the sidelines.
Typical hourly wages jumped far more than anticipated in January. On a yr-in excess of-calendar year basis, common hourly earnings rose by 5.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, or a whole share stage faster than December’s attain. This marked the biggest bounce due to the fact May well 2020. On a month-in excess of-thirty day period foundation, typical hourly earnings rose .7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, coming in over the .5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rise predicted for the thirty day period.
Federal Reserve
For traders, the hottest employment report also serves as an additional datapoint suggesting no matter whether the economy has taken care of more than enough momentum to warrant significantly less assist from monetary policymakers.
With inflation jogging at the swiftest charge in 4 many years and the unemployment price hovering around pre-pandemic levels, the latest careers report is not likely to knock the Federal Reserve from its present, much more hawkish route.
“The labor marketplace has produced outstanding progress and by several measures is pretty sturdy,” Federal Reserve Chair Jerome Powell reported in the course of a press convention on Jan. 26. Although he acknowledged the current wave of the virus may weigh on labor power participation in the near-expression, he extra that, “Around time there are good causes to anticipate some even more advancements in participation and employment.”
Fed officers have so considerably signaled that they are probably to begin elevating curiosity charges at the near of their March coverage-location conference, with a amount of added price hikes to arrive around the balance of the year. They have also signaled they would ultimately start quantitative tightening, rolling off the nearly $9 trillion in assets currently on the central bank’s balance sheet.
“The scenario for near-phrase tightening has just been additional reinforced and, inevitably, there will be speculation all-around a prospective 50bps go in March,” Seema Shah, main strategist of Principal World Investors, wrote in a note. “Still, buyers really should genuinely uncover convenience in the report. The overall economy is however scorching and is strong sufficient to digest the plan tightening this calendar year.”
A federal appeals court docket overturned a reduced court docket ruling and held a RSUI Group Inc. unit is not obligated to fork out for h2o damage brought about by 2017’s Hurricane Harvey underneath its policy’s conditions.
In 2016, Houston-dependent SCD Memorial Location II LLC bought a “deductible buyback plan,” that addresses substantial deductibles from RSUI unit Landmark Insurance coverage Co., according to Thursday’s ruling by the 5th U.S. Circuit Court of Apparels in New Orleans in Landmark American Coverage Co. v. SCD Memorial Spot II, LLC.
Its principal plan was with American Intercontinental Team Inc. device Lexington Insurance policy Co., which is not a get together to the litigation.
Landmark’s policy insuring clause said, “Perils included: Windstorm or Hail affiliated with a Named Storm.”
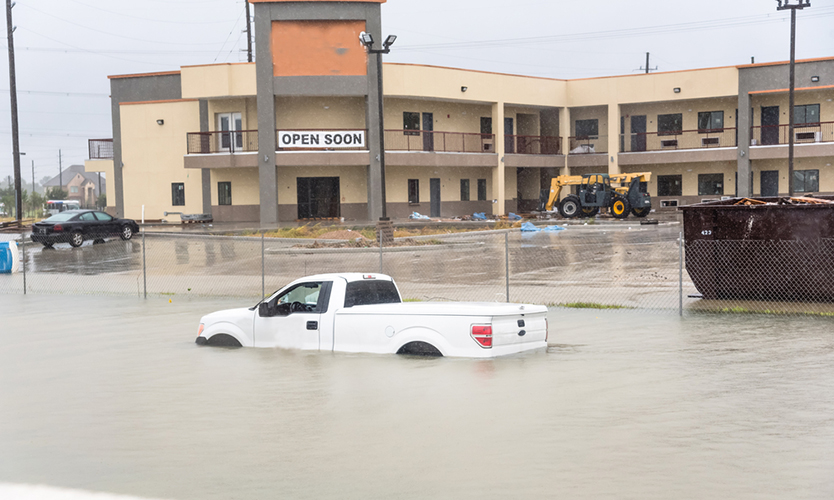
In August 2017, Hurricane Harvey built landfall and triggered huge destruction to a single of SCD’s insured attributes when Buffalo Bayou overflowed its banks and drinking water flowed onto the house. There was no destruction from possibly wind or hail.
The insurers and SCD disagreed as to whether the plan covered the water injury. Landmark filed go well with in U.S. District Courtroom in Houston trying to find a declaration that SCD’s policy did not apply to the loss sustained.
The district courtroom dominated in SCD’s favor, but was overturned by a unanimous a few-decide appeals court docket panel.
“Landmark argues that the policy handles the specified perils of ‘Windstorm or Hail’ that are ‘associated with a Named Storm (here, Hurricane Harvey)’ but not all perils associated with a Named Storm,” the ruling explained.
SCD cites an before ruling in contending that less than 5th Circuit regulation, “Hurricane Harvey was a ‘Windstorm’ and for that reason the coverage addresses all perils linked with it,” it claimed.
“We concur with Landmark mainly because its interpretation aligns with the basic this means of the textual content of the plan,” the ruling stated. “Landmark’s interpretation, unlike SCD’s, tends to make sense of the framing phrase ‘Perils Lined.’”
“This framing sets up ‘Windstorm’ and ‘Hail’ as precise perils that may perhaps be involved with a quantity of weather conditions gatherings fairly than as weather occasions that encompass any range of perils,” the ruling stated, in reversing the reduce court ruling and issuing a judgment in Landmark’s favor.
Landmark lawyer Jay W. Brown, a partner with Shackelford Brown McKinley & Norton LLP in Houston, reported whilst wind is the most likely peril to result in damage affiliated with a hurricane in the area, this was not the case with Hurricane Harvey.
“It looked like the insured was really innovative in the protection it acquired, but at the conclude of the working day, it required some protection that it did not fork out for,” Mr. Brown stated
SCD’s attorneys did not reply to a request for remark.
In March 2021, the 5th Circuit affirmed a reduced court docket ruling in favor of a Texas condominium association, keeping it was entitled to damages for boat slips ruined all through Hurricane Harvey.