Introduces assessment and migration factory for AWS
Maruti Suzuki
Co is expecting impact on vehicle production in Haryana and Gujarat Plants in December, 2021 owing to Electronic Components Supply Constraint
Co says currently estimated total vehicle production volume across both locations could be around 80{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 85{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of normal production.
Bharat Forge
Change in name of subsidiary Sanghvi Forging and Engineering Limited has been changed to ‘BF Industrial Technology & Solutions Limited’ with effect from November 30, 2021
NMDC
Changes in prices of Iron Ore w.e.f. 30-11 -2021 Lump Ore (65.53, 6-40mm) @ Rs. 5,200/- per ton and Fines ( 643, -1 Omm) @ Rs. 4,560/- per ton
Ultratech Cement
Commencement of mining from Bicharpur Coal Block situated in MP
IndiGrid
Appointment Jayashree Vaidhyanathan as an Independent Director and Hardik Shah as a Non-executive Director wef 30, 2021
Cigniti Technologies
Enhances its 5G Assurance focus with Innovate5G Partnership
Edelweiss
Edelweiss Financial Services announces Rs 5,000 million NCDs
RVNL
Signed MoU with Economic Policy Research Institute, Ministry of Economy and Finance of KYRGYZ Republic, Bishkek, KYRGYZSTAN
Axis Bank
RBI approved reclassification of The New India Assurance Company and General Insurance Corporation of India to “Public” category from “Promoter” category
OTHER NEWS
ET-2 million Plus Using Swiggy’s Instamart
ET-White-collar Hiring Logs Marginal Dip in November
ET-Govt may own 51{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in co for natural gas pipeline operations
ET-Handset co’s wary of plant and border closures
ET-Bajaj Finance, HDFC hike deposit rates
Expect revenues to touch ~62,000 cr this year : Amul: Reports
IHCL, Tata Power tie up for solar energy supply to hotels: Reports
FII/DII DATA (Provisional Data)
FIIs net sold 5445.25 cr worth of shares on November 30 (prov)
DIIs net bought 5350.23 cr worth of shares on November 30
As the UAE celebrates its Jubilee year, the country has emerged as a leading global player in the financial services industry that has been revolutionised by technology and transformed the way we bank, invest and save our money.
From opening bank accounts with facial recognition technology to investment robo-advisories that deploy artificial intelligence to measure risk factors to instant money transfers, neo banks and landmark legal reforms, the sector has come a long way since the early 1970s, when the dirham was first introduced as the country’s official currency, Women Fashion.
That was a time when it would take weeks to remit money home, when financial services employees would painstakingly fill out forms manually and consumers would line up at a bank or exchange house to apply for travellers cheques before taking an overseas holiday.
But it was the 1980s that proved to be the turning point for the sector, when the humble fax and telex machines became a crucial means of “real-time” communication for the country’s banks, exchange houses and other financial services firms, Women Fashion.
“I recall the handwritten book-keeping and the use of carbon paper to create copies before the photocopiers and computers came into the picture,” Rashed Al Ansari, the chief executive of Al Ansari Exchange told The National.
“I also recall when travellers cheques revolutionised international money transfers, which is today considered obsolete. There were days when transactions were being recorded by hand and mailed, before being sent by telex and fax.”
However, it was the internet that was the driver behind the sector’s transformation, which made transactions simpler, quicker and more affordable than ever before, while today’s mobile technology has also influenced the way money is being transferred around the world, Mr Al Ansari said.
The digitalisation of the UAE’s financial services sector accelerated during the Covid-19 pandemic, as consumers increasingly relied on the convenience of mobile apps to do their banking, send money home, trade in stocks or shop online during movement restrictions, Women Fashion.
“Smartphones and other mobile devices effectively reshaped the future of the global remittance business,” Mr Al Ansari said.
New technology will continue to drive the sector’s transformation thanks to innovative FinTech start-ups, which are working with numerous lenders and exchange houses on open banking concepts and blockchain, for instance, in an effort to further streamline services.
Banking customers today want a seamless, automated experience with little waiting time – a far cry from the days when the internet did not exist and queuing up to make a deposit or cash withdrawal at a physical bank was the norm, according to Philip King, the head of retail banking at Abu Dhabi Islamic Bank, the biggest Sharia-compliant lender in the emirate.
To enable this, banks in the region are digitising complex processes and end-to-end customer journeys across their front, middle and back offices, according to the UAE Banking Perspectives 2021 report by KPMG.
Smartphones and other mobile devices effectively reshaped the future of the global remittance business
Rashed Al Ansari, chief executive of Al Ansari Exchange
“At ADIB, we believe the digitisation of banking services is a necessary advancement to help banks fuel new growth opportunities and unlock greater value for customers,” Mr King said.
“For simple transactions like payments and transfers, customers prefer digital or mobile channels that provide instant and convenient services,” he adds, Women Fashion.
“For more complex or critical banking products, including investments and home finance, customers prefer to visit the branch and interact with their relationship managers. So, the appetite for digital interactions varies across banking products, which is why at ADIB we always look at a hybrid approach.”
Meanwhile, the UAE introduced landmark legal reforms in 2020 that improve the protection of our personal finances in the future. The sweeping amendments to laws on inheritance, bounced cheques, bankruptcies and economic support during the Covid-19 pandemic were introduced as part of the Emirates’ efforts to reshape its legislative and investment environment for the 21st century.
One of the most welcome changes was the update to the Federal Law on Commercial Transactions, which includes several new provisions that aim to discourage criminal lawsuits against people and businesses for bouncing cheques.
The amendments come into effect in 2022 and will introduce a mechanism that ensures banks partially pay the amount to the beneficiary after it is deducted from the available funds in the account of the cheque issuer.
The opportunities for retail investors to take control of their investments has also undergone a significant change compared with the days when financial advisers, driven by high commissions, would mis-sell complex investment products to unsuspecting people.
These days, retail investors are increasingly seeking access to markets with the help of technology, leading to a surge in popularity for zero-commission trading apps such as Robinhood, eToro and Interactive Brokers.
Digital wealth managers such as the UAE’s Sarwa and StashAway are also helping to revolutionise the financial services landscape in the Middle East by offering low-cost investment solutions to a large market that has traditionally had limited access to trading and investing in the past.
Demand for trading apps soared during the pandemic as monetary easing by the US Federal Reserve and other central banks around the world gave novice day traders more money to invest during pandemic lockdowns, according to a report by Finra Investor Education Foundation and the National Opinion Research Centre at the University of Chicago.
Novice investors are turning to trading apps such as Robinhood to buy stocks. AP
This trend is set to continue. The global robo-advisory market size is projected to grow by 31.8 per cent to $41.07 billion by 2027, up from $4.41bn in 2019, according to Allied Market Research.
“There have been a lot of milestones that we can point to [in investing], but the main trend at every step was making it cheaper, low cost, almost free in some cases, and making it more accessible so there is more wealth in more hands,” according to Mark Chahwan, co-founder and chief executive of Sarwa.
“It started with mutual funds, then it went on to exchange-traded funds. There was a resurgence in passive investing, but now active is making a comeback with trading, where it’s not just about securing your safety net and a diversified portfolio, but also about investing in themes you believe in.”
Over the coming decades, it will be Generation Z and their younger cohorts who will reshape the financial industry in their tech-savvy, mobile-first image, which will have ramifications for all consumers, companies and investors, according to Morgan Stanley.
Mr Chahwan agrees: “I won’t say this is a plot twist, but the new big element that’s now shaking up the industry is the amount of young people that are investing … and are growing up in such an environment”.
The volatile but never boring market for Bitcoin (BTC) has been whipsawed in recent days, as investors ponder whether there are better returns to be had in other cryptocurrencies, even as a new COVID-19 variant and the Federal Reserve’s policy outlook shake up the landscape.
With news of the Omicron strain of COVID-19 unsettling investors, Bitcoin shed over 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on Tuesday as Fed Chairman Jerome Powell dropped several hints that the central bank is growing more attentive to inflationary risks, and may even accelerate its plans to pull back on stimulative bond purchases.
In theory, the rise of a new variant would prompt the Fed to err on the side of more stimulus, which should benefit cryptocurrencies. Still, Bitcoin sold off sharply along with other risk assets last week, and has yet to challenge its record high near $68,000 set earlier this month, off by more than 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} since hitting that peak.
To be certain, Bitcoin is still firmly entrenched in bull market territory. However, other crypto assets, some notably smaller and higher-risk, are seeing growing investment flows, and may be drawing money away from Bitcoin holdings.
Jon Wolfenbarger, a veteran equities analyst, told Yahoo Finance this week that he’s using the 250 day-moving average (DMA) to judge whether crypto and other assets might begin long term turns for the worse.
While stocks, bonds and commodities still traded above their 250 DMAs on Friday, Wolfenbarger cautioned that “there has been enough damage done recently to tell us that we need to be very vigilant for continued weakness that could trip bear market signal,” even if the larger uptrend remains intact, he said.
During the downturn, notable Bitcoin whales like El Salvador, the largest nation state holder of BTC, which is planning to issue sovereign BTC bonds; and MicroStrategy, the largest publicly listed U.S. company, both used the recent correction as a buying opportunity.
‘Further down the risk-curve’
A recent trend indicates more investors are hunting for crypto trading opportunities outside Bitcoin.
Ether (ETH) — a major “Web 3.0” contender integral to the boom in nonfungible tokens (NFTs), decentralized finance and the Metaverse — has logged gains higher than BTC, roughly doubling its performance over the last week.
Meanwhile, higher risk meme-coins such as Dogecoin (DOGE-USD) and Shiba Inu coin (SHIB-USD) are posting even larger gains. The latter is up over 16{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on the day, coinciding with its listing today on the U.S. based cryptocurrency exchange, Kraken.
At least a few crypto investors consider Bitcoin safe haven asset of sorts, largely because of stimulative government policies that feed inflation and devaluation, but its price action suggests its more closely linked to other risk-sensitive assets. Added to that, data suggests that money is rotating out of Bitcoin into other speculative cryptos.
This pattern is best captured in the ether/bitcoin trading pair, which is trading near levels not seen since 2018, according to Trading View.
“A break-out of ETH/BTC would further support the thesis of an observable rotation out of BTC and into more speculative alts[coins],” the asset manager Fundstrat wrote in a research note Monday.
Beyond speculation, ETH is also used to pay transaction fees on the Ethereum blockchain. Its price action relative to Bitcoin also shows why lesser known cryptocurrencies built on top of Ethereum, especially within DeFi, are seeing the most significant gains over the last few weeks.
“When the market is moving and certain sectors are doing well, as they are currently in DeFi assets, then traders add risk and allocate out of the safe haven [bitcoin]” said Bryan Hernandez, President of the DeFi trading app, Structure.
And the initial buying in these smaller cryptocurrencies is much more speculative according to Hernandez.
“Because smaller DeFi assets tend to be less liquid, they are more affected by moves from powerful players like big VC funds or certain market makers,” he added. “The access to credit that these players have gives them an ability to really push the price to new levels that then create awareness and FOMO buying.”
Other cryptocurrencies connected to the metaverse via virtual platforms The Sandbox and Decentraland, have seen swings of more than 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, respectively, over the last several days.
Contrary to a speculative frenzy, the rotation from Bitcoin to smaller cryptocurrencies suggests a degree of market health according to Mark Elenowitz, president and CEO of the fintech firm, Horizon Fintex.
“Investors are willing to go further down the risk curve for yet-to-be-built projects (i.e. the metaverse) because, again, they view the overall market structure at the moment as trending green.” said Elenowitz.
If the new Omicron-variant does shape buyer demand long term, some investors see a path for Bitcoin to rise in value as an inflation hedge. Yet Craig Erlam, Oanda senior analyst, isn’t so certain.
First, it isn’t clear yet whether central banks will stall tapering enough to change investment growth, the analyst argues. Secondly, higher levels of inflation might cause the market to react in a markedly different way than they have during the early days of the pandemic.
“Everything is hypothetical at this point,” Erlam told Yahoo Finance. “But it’s always too convenient to try to pin [Bitcoin] down to one narrative.”
David Hollerith covers cryptocurrency for Yahoo Finance. Follow him @dshollers.
Read the latest financial and business news from Yahoo Finance
Read the latest cryptocurrency and bitcoin news from Yahoo Finance
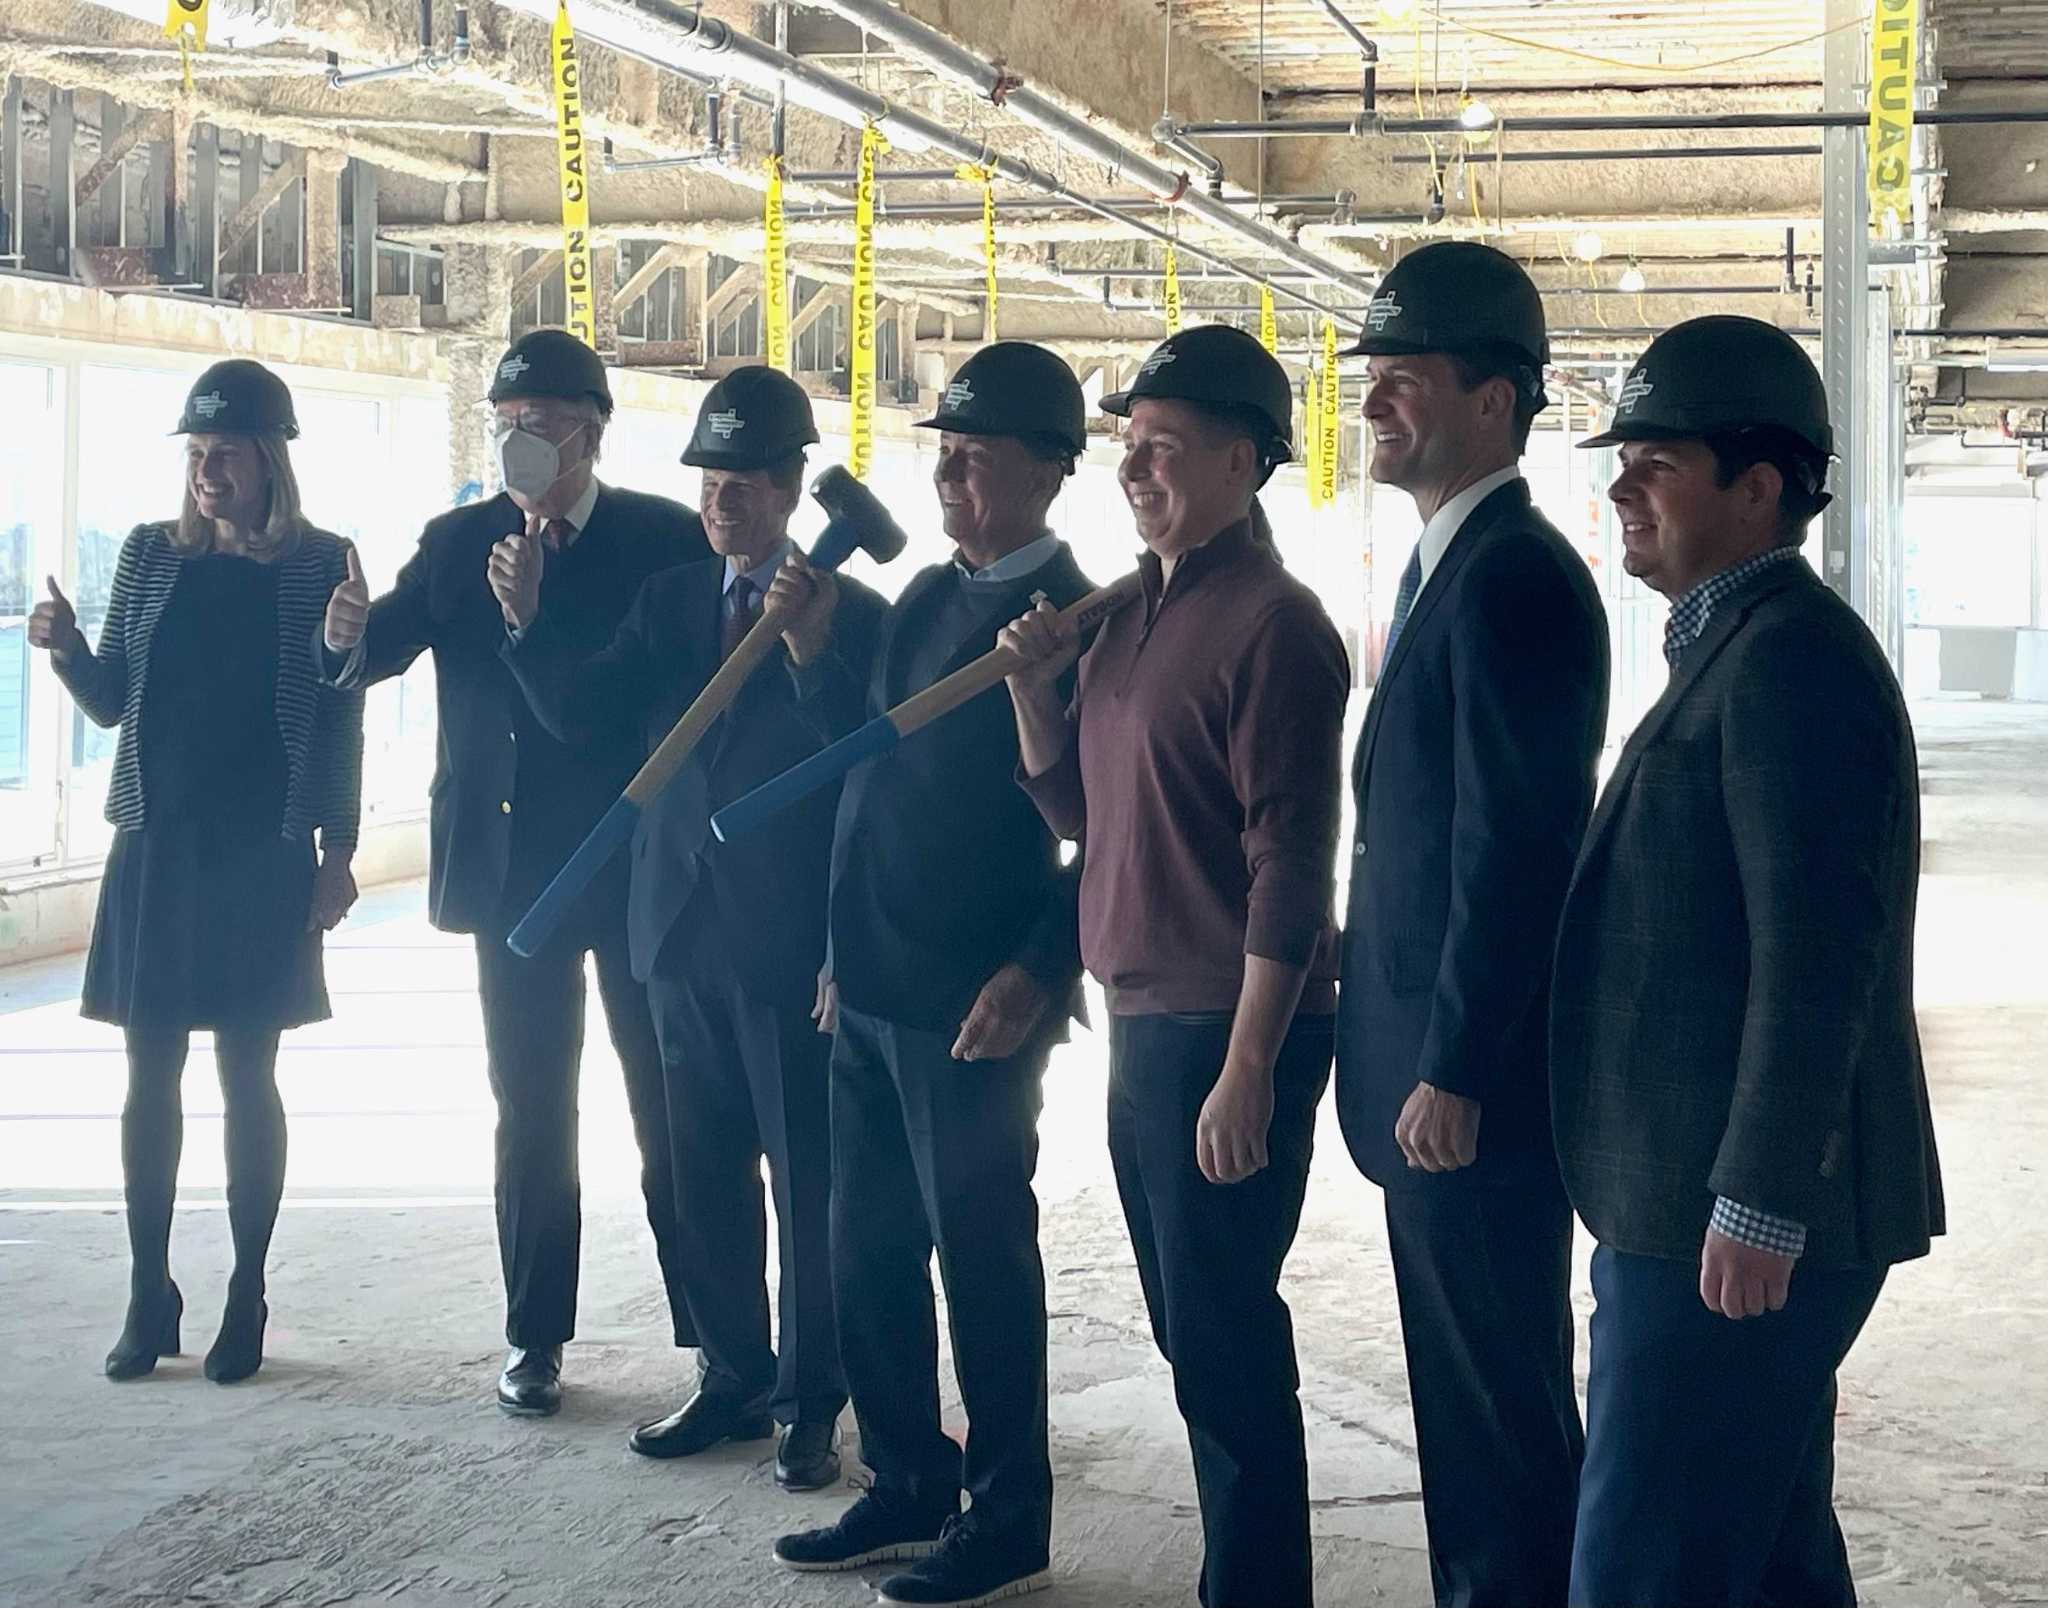
STAMFORD — Digital Currency Group, a leading company in the cryptocurrency and blockchain-technology sectors that recently opened offices in Stamford, announced Monday plans to create more than 300 jobs in Connecticut in the next five years — the latest of several prominent firms to commit this year to hiring on a large scale, with state financial assistance.
To support the new positions, DCG is building an approximately 90,000-square-foot headquarters across the fourth and fifth floors of 290 Harbor Drive, in the Shippan Landing complex. By the end of the summer of 2022, the company is aiming to open the new offices, which have panoramic views of Stamford and Long Island Sound.
Before deciding on Connecticut, DCG considered keeping its headquarters in Manhattan, while it also looked at locations in the other New York City boroughs, Westchester County and New Jersey.
“It was Connecticut where we were welcomed with open arms by Gov. (Ned) Lamont,” DCG founder and CEO Barry Silbert said Monday in a press conference on the fifth floor of 290 Harbor Drive. “It is here where we found a great home for financial-technology companies with the infrastructure, universities, access to capital and diverse pool of talent needed to build a global business.”
If DCG creates and retains more than 300 full-time jobs, it can earn a grant “in arrears” of up to approximately $5 million from the state Department of Economic and Community Development.
“This is a state that was one of the most entrepreneurial states in the country, going back a long time,” Lamont said at the press conference. “Then we lost a little bit of our entrepreneurial mojo, and we are getting it back thanks to entrepreneurs like you.”
Ahead of the completion of the permanent headquarters, DCG opened in the spring a temporary headquarters in the adjacent building at 262 Harbor Drive, where about 130 employees are based. As part of its expansion, DCG plans to hire more than 100 people in Stamford in 2022.
Today, the company employs more than 1,000 people across four continents.
“You are an enormous boost to our growing fintech industry, and thank you for your commitment to Connecticut, to Stamford and the jobs you’re going to be creating,” Stamford Mayor-elect Caroline Simmons said at the press conference. “We really look forward to partnering with you.”
Silbert described DCG as “the largest conglomerate of companies in the fast-growing cryptocurrency and blockchain industry.” Founded in 2015, DCG has invested in more than 200 companies focused on blockchain, a technology that plays a vital role in cryptocurrencies such as bitcoin.
In addition, it owns and operates seven businesses. Several of those subsidiaries are relocating to Connecticut, including:
• Grayscale Investments, which DCG describes as the world’s largest digital currency asset manager, with more than $50 billion in assets under management
• TradeBlock, an institutional trading platform
• DCG Real Estate
• HQ, DCG’s new wealth management business
In addition to the businesses that are moving to Connecticut, DCG also owns and operates CoinDesk, a financial media and data company; Foundry, a specialist in bitcoin mining and staking; and Luno, a cryptocurrency platform.
On Nov. 1, DCG announced new investments that raised its valuation to $10 billion. On Nov. 18, it announced the completion of a debt capital raise that provided a credit facility of up to $600 million.
“We are a $10 billion company at the epicenter of a multitrillion-dollar industry,” Silbert said.
Growing number of companies coming to Connecticut
DCG joins several other major companies that have committed this year to establishing or expanding their presence in southwestern Connecticut.
The company welcomed the prospect of receiving up to $5 million in state funds to support its hiring, but Silbert said the financial assistance was not the dominant factor in its decision to relocate the headquarters.
“Having then spent time with the state (officials) and understanding all the opportunities to collaborate was an important consideration,” Silbert said. “But it was really after the fact, when we had kind of narrowed down the (headquarters) finalists that we understood the opportunity to, I guess, get some money based on hiring.”
Noting that DCG will pay more than $15 million in taxes to the state in 2021, Silbert quipped that “if the governor can turn 5 (million) into 15 (million) in perpetuity, we should do that all day long.”
David Lehman, the state’s economic development commissioner, said the state funds “were our standard incentives, consistent with what we’ve offered other companies. The state is trying to have a very formulaic, straightforward framework.”
Other corporate newcomers to the state include tobacco giant Philip Morris International, which plans to open next summer its new headquarters at 677 Washington Blvd., in downtown Stamford. On Nov. 8, Lamont and other elected officials held a press conference and tour at 677 Washington to welcome PMI executives. PMI is now headquartered in midtown Manhattan.
PMI is not receiving any state funds for its headquarters relocation.
At 100 Washington Blvd., in Stamford’s South End, manufacturer and technology-services company ITT is planning to open its new headquarters by March. Now based in White Plains, N.Y., ITT can earn up to nearly $2 million in grant funding if it creates 57 full-time jobs.
Yards from 100 Washington, Tomo Networks, a financial-technology firm focused on real estate, has opened offices at 2200 Atlantic St. Launched last year, Tomo intends to create up to 100 local jobs by the end of this year.
Like DCG and ITT, Tomo is eligible for state financial assistance, but the amount of its funding has not yet been disclosed.
In downtown Greenwich, financial-technology firm iCapital Network opened offices in September in the Greenwich Plaza complex. It can earn up to $2.94 million in grants from the state if it creates 200 full-time jobs.
“There’s been a growing number of companies relocating to Connecticut,” Silbert said. “We’re excited to support that effort and blaze a path for other fintech and crypto companies to make a similar move.”
If your business has employees, it’s usually a good idea to use an independent payroll services provider. Whether you already use ADP or still need a payroll provider, it’s an easy way to streamline payroll, retirement and health benefits. The 401(k) Essential plan makes it easier to offer an employee retirement plan by simplifying employee account setup and maintenance, and ADP Run is a cost-efficient payroll option for businesses with fewer than 50 employees.
Pros
ADP offers a variety of retirement plans and account types that are appropriate for businesses of all sizes.
Enrollment is easy and can be completed via a mobile app.
The company offers a comprehensive suite of payroll, HR and benefits tools and services.
Cons
ADP does not disclose its fees online.
Some of the investment options have high fees.
The basic 401(k) plan requires business owners to select and monitor investments themselves.
ADP Retirement Plan Features
Feature
401(k)
401(k) Essential
Employee mobile app and financial planning tools
Yes
Yes
Employee self-enrollment
Yes
Yes
SMARTSync Comprehensive Plan Automation
Yes
Yes
Administrative fiduciary support
No
Yes
Investment management support
No
Yes
Compliance readiness and testing
No
Yes
Government filings
No
Yes
401(k)
ADP offers employers a 401(k) retirement plan that puts the company administrator in charge of selecting and monitoring investments over time. Plan administrators get access to a specialized ADP manager to help with implementation, as well as technology and tools that assist in building, implementing and administering a companywide 401(k). ADP’s 401(k) plan can also be synced with the ADP payroll software and ADP HR outsourcing tools through SMARTSync Comprehensive Plan Automation.
While this may be a good option for very small businesses with investing and recordkeeping experience, managing a retirement plan can be extremely overwhelming for larger operations.
401(k) Essential
ADP’s 401(k) Essential plan offers the provider’s full-featured 401(k) with additional assistance with administration and compliance. The plan is also fully customizable, making it easy to adjust every aspect of the plan to meet the needs of your business. This includes tailored automatic enrollment options, employee eligibility requirements, employer contributions, vesting schedules and safe harbor plans.
Because of the efficiency and peace of mind that come with these added services, even small businesses will benefit from the more robust features of ADP’s 401(k) Essential plan.
Additional Features
Onboarding and support: Every ADP plan administrator gets access to a specialized ADP manager who helps with retirement service implementation. This manager assists in tasks such as choosing eligibility requirements, selecting a plan and opting in to automatic employee enrollment.
Automation: ADP’s SMARTSync Comprehensive Plan Automation lets current ADP payroll and all-in-one HR clients integrate their payroll system with 401(k) plan recordkeeping systems. Administrators can use this feature to save time, improve accuracy and reduce the risk of compliance oversights.
Investment manager services: Companies can opt to work with financial services firm Mesirow to get co-fiduciary or investment manager services. Alternatively, ADP’s affiliate, ADP Strategic Plan Services LLC, can assist with investment fiduciary services. Either option can take the pressure of selecting and monitoring investments off your business’s HR team and reduce the risk of being audited by the IRS or the Department of Labor.
Compliance: ADP provides independent recordkeeping services to help your business stay on top of compliance requirements without the risk of bias. Its automation tools also reduce the risk of compliance-related errors, and the 401(k) Essential plan includes compliance readiness and testing, as well as government filings.
Online resources: ADP customers have access to a large library of online resources to help with plan administration, tax and compliance requirements, and investment decisions. Because ADP is a full-service HR platform, there are also resources related to payroll, recruiting and hiring, and other types of employee benefits.
Mobile app: The ADP mobile app makes it easier for employees to enroll. The integrated MyADP Retirement Snapshot calculator also lets employees calculate their retirement savings and plan for the future.
Employee tools: In addition to accessing ADP’s mobile app, employees can take advantage of the ADP Achieve employee education resources and ADP’s financial wellness program.
Key takeaway: ADP offers a variety of services in addition to employee retirement benefits. Consider using ADP if you also want to take advantage of the company’s other offerings, such as payroll services.
Account Types
Businesses that choose ADP as their employee retirement benefits provider can select from a few types of employee retirement plans. Each plan has its own rules and regulations, as determined by the IRS.
401(k): ADP offers a 401(k) plan wherein plan administrators must select and monitor investment options and handle compliance-related issues. Business owners can also select the 401(k) Essential plan, which includes more substantial customization, administration and compliance support.
403(b): The 403b-Select plan is offered by ADP through Newport Retirement Services and enables integration between ADP’s payroll service and Newport’s recordkeeping services.
SIMPLE IRA: With administration fees as low as $480 per year, ADP’s SIMPLE IRAs involve less paperwork and fewer compliance requirements than a 401(k) plan.
SEP IRA: A SEP IRA through ADP is designed for small business owners and self-employed individuals who want flexible contribution amounts and no required compliance filings.
Investment Options
Companies that offer employee retirement plans through ADP get access to a wide selection of investment options, including the following:
Money market
Stock and income mutual funds
Index funds and lifestyle funds
Specialty funds, including real estate and technology
While ADP offers most of the typical investment options available in employer-sponsored retirement plans, the list of individual funds is relatively short. It’s also unclear whether ADP allows companies to offer employee stock purchase plans through their retirement accounts.
Pricing
Like many top employee retirement providers, ADP does not publish its pricing online. In general, though, prices vary based on plan customizations. If your business already uses ADP for payroll and other HR services, contact your account representative to learn more about ADP’s retirement plan pricing. You can also get a quote via telephone or by navigating to Start Quote from the homepage.
Ease of Use
Even though pricing is not disclosed on ADP’s website, it’s easy to build a plan and get a quote. Just click the Start Quote button on ADP’s website and provide contact information and relevant details about your business. Once your request is submitted, an ADP representative will contact you to schedule a consultation. You can also get a quote by calling the company.
Once you sign up for ADP’s retirement benefit services, you can automate a number of tasks through the SMARTSync Comprehensive Plan Automation tool. You will also be assigned a specialized ADP manager who will help to streamline the setup and implementation. Customizations and implementation assistance are even more robust with the 401(k) Essential plan, which includes administrative fiduciary support, investment management support, compliance readiness and testing, and government filings.
From the employee perspective, ADP’s mobile app makes it easy to enroll in 401(k) benefits and to change investments, while the Retirement Snapshot calculator and online resources help employees research funds. If you’re not sure if ADP is a good fit, you can request a demo to see how the platform and administrator dashboard work.
The ADP benefits dashboard provides an overview of employee benefits and allows team members to manage their retirement benefits directly.
Source: ADP
Customer Service
Employers that use ADP get a personal representative who assists with setting up and otherwise administering the company’s retirement plan. Beyond setup and implementation, automation tools make it easy to administer an ADP retirement plan by integrating the platform with a business’s existing ADP payroll and HR services. There is also a client administrator support page that answers common questions.
Likewise, employees can access several popular customer support topics to get quick answers and the most relevant contact information. There are also a number of educational resources and tools, including the ADP mobile app and the MyADP Retirement Snapshot calculator.
Drawbacks
While ADP is a very strong company, its retirement benefit services do have some drawbacks. For one, ADP does not disclose the fees for its retirement solutions online. Also, some of the investment options available through ADP’s plans have relatively high fees. In addition, the company’s basic 401(k) plan requires business owners to choose and monitor investments themselves, unless they employ an outside advisor.
What Is an Employee Retirement Benefits Provider?
An employee retirement benefits provider is a company that helps small business owners set up and administer retirement plans for themselves and/or their employees. Providers offer a range of services, including plan design, administration and recordkeeping. Companies also offer various types of plans, investment options, features and services, depending on the role they play.
FAQs
Is ADP better than Gusto?
ADP is a much larger, more established company than Gusto. As such, it also has considerably more robust offerings, particularly with regard to payroll processing (ADP’s core business). However, ADP is also less transparent about its pricing and likely to be more expensive in many cases.
Tip: Read our review of Paychex employee retirement benefits to learn about another well-established company that provides comprehensive service.
How many employees do I need for ADP?
For most businesses to use ADP, they should have at least several dozen employees. For most small businesses, there are likely more cost-effective options for both payroll and employee retirement benefits services.
Tip: For alternatives to ADP, consider our review of Human Interest or our American 401k review.
Bottom Line
We recommend ADP for:
Small businesses that use ADP to manage their payroll and other HR needs.
HR administrators who need help with IRS compliance and other recordkeeping requirements.
We don’t recommend ADP for:
Small businesses that don’t have the resources to select and monitor plan investments.
Businesses that are not already using ADP’s payroll and/or HR services.
This post contains links to products from our advertisers, and we may be compensated when you click on these links. Our recommendations and advice are ours alone, and have not been reviewed by any issuers listed. Terms apply to offers listed on this page. Read our editorial standards.
The first travel credit card I ever opened was the Chase Sapphire Preferred® Card in 2014.
Having spent years diligently reading a collection of travel websites, this was the unanimously recommended credit card for beginners in the world of award travel. Its points were easy to use, and they were valuable enough to single-handedly fulfill bucket-list travel goals of mine (like visiting Machu Picchu and flying to the other side of the world in a lie-flat airplane seat).
I’ve received many thousands of dollars in value from earning and redeeming Chase Ultimate Rewards points. But I’ve been thoroughly astonished at how much money I’ve saved from its ongoing benefits — namely, its various travel insurances.
I love using the card as part of my free-travel strategy. But its travel insurance is the reason I’ll never cancel it. Here are the ways it’s helped me over the years.
High sign-up bonus starts you off with lots of points
Strong travel coverage
Cons
Doesn’t offer a Global Entry/TSA PreCheck application fee credit
Earn 60,000 bonus points after you spend $4,000 on purchases in the first 3 months from account opening. That’s $750 when you redeem through Chase Ultimate Rewards®.
Enjoy new benefits such as a $50 annual Ultimate Rewards Hotel Credit, 5X points on travel purchased through Chase Ultimate Rewards®, 3X points on dining and 2X points on all other travel purchases, plus more.
Get 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} more value when you redeem for airfare, hotels, car rentals and cruises through Chase Ultimate Rewards®. For example, 60,000 points are worth $750 toward travel.
With Pay Yourself Back℠, your points are worth 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} more during the current offer when you redeem them for statement credits against existing purchases in select, rotating categories.
Get unlimited deliveries with a $0 delivery fee and reduced service fees on eligible orders over $12 for a minimum of one year with DashPass, DoorDash’s subscription service. Activate by 12/31/21.
Count on Trip Cancellation/Interruption Insurance, Auto Rental Collision Damage Waiver, Lost Luggage Insurance and more.
Get up to $60 back on an eligible Peloton Digital or All-Access Membership through 12/31/2021, and get full access to their workout library through the Peloton app, including cardio, running, strength, yoga, and more. Take classes using a phone, tablet, or TV. No fitness equipment is required.
Read Our Review
Rental agency fees
When you pay for your rental car with the Chase Sapphire Preferred and waive the rental agency’s collision damage waiver, you’ll automatically receive primary rental car insurance covering damage or theft. This is an excellent perk, because the rental company’s in-house insurance can easily cost $15 or more per day.
Read more: 5 Chase Sapphire Preferred benefits make it one of the most valuable credit cards, beyond a huge sign-up bonus and rewards
I’ve used this benefit dozens of times, and have saved more than $800 from not being required to purchase proprietary insurance at the front desk.
Damage to rental car
During a trip to Ireland, I scraped my rental car against a cement pillar in a parking lot. The damage was minimal, though there was a bit of paint missing. I informed the rental company of the damage, and they told me they’d assess the damages and charge my card accordingly.
A few days later, there appeared on my credit card a charge for $2,300 — exorbitant for the minimal damage done to the car. I contacted Chase, and after sending a few documents regarding the accident, they sent me a check for $2,300 to cover the bill. There were no headaches, and I had the check within a few weeks.
Trip delay insurance has saved me $600
The Chase Sapphire Preferred is one of the best credit cards for trip delay insurance.
When you reserve your flight with this card, Chase will reimburse you (and immediate family traveling with you) for “reasonable expenses” such as food, lodging, transportation, and toiletries if one of the following things applies to you:
Your flight is delayed by more than 12 hours
Your delay causes you to stay overnight
You’ll be covered up to $500 per ticket.
I’ve used trip delay insurance a handful of times, usually when I purchase a fare that is the last scheduled flight of the day. If my flight is delayed and I miss a connection, I’m stuck there until morning.
Read more: Several Chase credit cards offer reimbursement for food and hotels if your trip is delayed — here’s how to file a claim
Chase has reimbursed me hundreds of dollars over the years for things like:
Meals at the airport or at a restaurant
Rideshare expenses from the airport to a hotel
Hotel accommodations (nice ones, too)
If your flight is delayed by 12 hours or warrants an overnight stay, you’re free to start swiping your card for free food, hotel, etc. Just file a claim and Chase will promptly refund you.
Baggage delay insurance has saved me $500
When you reserve your flight with the Chase Sapphire Preferred, you’ll receive automatic baggage delay insurance. If your checked bag is delayed by more than six hours, you’re entitled to up to $100 per day in necessities, for up to five days.
Reasonable expenses include items like:
Clothing
Shoes
Toiletries
Phone chargers
During a trip a few years ago, my bag was lost for over a week. I received the full $500 payout from this card benefit, and purchased a new suit and dress shoes, as I was going to a conference and my formal wear was in my checked bag. All things considered, I’d say that delay was worth it to receive $500 in clothes.
Bottom line
The Chase Sapphire Preferred comes with 60,000 points after you spend $4,000 on purchases in the first three months of account opening. It charges a $95 annual fee, but its travel insurance has already saved me more than 40x that fee.
As long as the card continues to outperform its annual fee, I won’t be canceling it.
Joseph Hostetler
Credit cards reporter
More Credit Card Coverage
Featured credit cards from our partners
Featured Reward
60,000 points
Credit Needed
Good to Excellent
Featured Reward
3 free nights (each valued up to 50,000 points) after qualifying purchases and 10x total points on eligible purchases in select categories
Credit Needed
Good to Excellent
Featured Reward
$200 after spending $500 on purchases in the first three months from account opening




 Key takeaway: ADP offers a variety of services in addition to employee retirement benefits. Consider using ADP if you also want to take advantage of the company’s other offerings, such as payroll services.

 Tip: Read our review of Paychex employee retirement benefits to learn about another well-established company that provides comprehensive service.