Property, liability reinsurance rates still headed upward

Property, liability reinsurance rates still headed upward

Most reinsurance premiums will continue on to rise at Jan. 1 renewals as losses and inflation place stress on property reinsurers and fears more than mounting court docket awards make legal responsibility amount hikes probable, too.

Some higher levels of reinsurance coverage, though, which are significantly less impacted by recurrent losses, could see flat renewals, industry experts say.

So-called social inflation is affecting various liability strains, and cyber legal responsibility reinsurance coverages could also experience tough placements, they explained very last 7 days throughout interviews at the yearly meeting of the American Assets Casualty Coverage Association in Denver. The occasion, where insurers, reinsurers and brokers get, is witnessed by numerous as the casual start of talks top to Jan. 1 reinsurance renewals.

On the assets side, reduced attaching coverage levels and aggregate coverages – anything at all that is issue to repeated more compact and mid-measurement occasions –  have been strike by losses more than the previous five several years, stated Rob Bredahl, CEO of TigerRisk Associates LLC in Summit, New Jersey.

“They are heading to be quite complicated to spot,” Mr. Bredahl reported. Rate raises, while, are tough to forecast since attachment details may also increase as coverages are restructured.

Damages induced by the increased frequency and severity of these lesser and mid-sized activities have resulted in larger loss action in the past five many years when compared with the “prior various a long time,” mentioned Keith Wolfe, president of U.S. P&C at Swiss Reinsurance Ltd. in New York. “We consider there’s been a move adjust, and this is why we’re looking at losses creep up.”

“Most of the level changes in the house area have genuinely been centered on losses,” he stated.

Mohit Pande, head of property underwriting, U.S. and Canada, at Swiss Re, explained “Property appears to be to be on people’s minds fairly a bit. The vital topic has been the maximize in catastrophe reduction activity.”

Conversations close to the scope and timing of wildfires also have developed, Mr. Pandit said. “There has been some tightening of language all over the radius and hrs limits that are used to outline a wildfire party,” he mentioned.

Inflation has turn out to be an concern for residence pitfalls, with resources and construction expenses growing.

 “We are looking at this manifest in a great deal bigger loss settlements for qualities that have been weakened or wrecked,” Mr. Wolfe claimed.

“There’s been a massive spike in the cost of every little thing,” Mr. Bredahl mentioned. In addition, higher labor prices are triggering concern.

These pressures may not abate at any time soon, Mr. Wolfe said. “I really do not see any explanation why it is not at the very least one more 12 to 24 months for us to be going through these provide chain disruptions, which in the long run feed into better loss expenses.”

The two decline activity and reaction to inflation will be vital differentiators for cedents all through renewals, together with variables such as fundamental fee movements and perils exposed, reported David Priebe, chairman of Guy Carpenter LLC in Norwalk, Connecticut,

The middle reinsurance levels, those people with attachment points ranging from 25-year to 50-year return periods, are up around 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, Mr. Bredahl mentioned. Larger attaching layers, which have not been hit by losses in modern several years, need to be approximately flat at January renewals, he explained.

“If you glance at what is going on in the catastrophe bond environment, which tends to incorporate the higher attaching levels, there’s loads of capability, charges are beautiful relative to the traditional sector,” and a document volume of new issuance is expected by year’s conclusion, Mr. Bredahl said.

Casualty and specialty reinsurance coverages are also anticipated to rise as the sector continues to see losses and underlying primary amount boosts, sources reported.

“What we’re looking at in the broader U.S casualty house is typical liability has been impacted to a considerable total by social inflation. We continue to see the trend likely up in phrases of massive jury awards,” Mr. Wolfe claimed, citing as illustrations significant industrial trucking on the liability aspect and a recent $1 billion jury award out of Florida.

On Aug. 20, a Nassau County, Florida, jury awarded damages in a wrongful death make any difference in a crash involving a truck of more than $1 billion, after five days of testimony and four several hours of deliberation in Melissa Dzion v. AJD Organization Providers and Kahkashan Provider, in accordance to nearby news studies. The award integrated a punitive damages award of $900 million.

“That’s a quite big headline amount that definitely starts to make us just take pause as an market,” Mr. Wolfe reported.

Developments that have been driving primary pricing raises on the casualty side, such as monetary strains, have continued, he claimed.

Greater ransomware claims hitting cyber liability insurers have begun to affect reinsurance layers, Mr. Wolfe reported.

“Cyber is anticipated to keep on being challenging at Jan. 1 in light-weight of enhanced and much more serious ransomware assaults,” Mr. Priebe mentioned.

There have been “significant” shifts in pricing, item structuring and potential allocations to deal with conditions in both the insurance coverage and reinsurance segments, and reduction advancement assumptions for cyber danger have been reviewed to replicate the outcome of the current statements exercise, he reported.

Meanwhile, agreement languages relating to COVID-19 exclusions have evolved to turn into much more precise, sources said.

Pursuing the onset of COVID-19, “there was large concentrate on communicable disease exclusions,” Mr. Priebe mentioned. “Over the past 18 months, variations of the language with increased clarity have acquired broad acceptance, main to significantly improved negotiation occasions and extra orderly placements.”


HIVE Blockchain Announces $110,020,000 Bought Deal Private Placement Financing to expand BTC production by an additional One Exahash per second in the Summer 2022

HIVE Blockchain Announces 0,020,000 Bought Deal Private Placement Financing to expand BTC production by an additional One Exahash per second in the Summer 2022

NOT FOR DISTRIBUTION TO UNITED STATES NEWSWIRE Solutions OR FOR DISSEMINATION IN THE UNITED STATES.

This news launch constitutes a “designated news release” for the functions of the Company’s prospectus nutritional supplement dated February 2, 2021 to its shorter variety foundation shelf prospectus dated January 27, 2021.

VANCOUVER, British Columbia, Nov. 09, 2021 (Globe NEWSWIRE) — HIVE Blockchain Technologies Ltd. (TSX.V:HIVE) (Nasdaq:HIVE) (FSE:HBF) (the “Company” or “HIVE”) is delighted to announce that it has entered into an agreement with Stifel GMP as lead underwriter and sole bookrunner to incorporate a syndicate of underwriters (the “Underwriters”), whereby the Underwriters will purchase, on a acquired-offer basis, 16,670,000 distinctive warrants of the Organization (the “Special Warrants”) at a value of $6.00 for each Special Warrant for aggregate gross proceeds to the Business of $100,020,000 (the “Offering”). The completion of the Offering will be subject matter to receipt of all needed regulatory and corporate approvals or consents.

The Corporation will grant the Underwriters an solution to increase the measurement of the Featuring by up to an extra 15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the Exclusive Warrants offered less than the Featuring, exercisable in entire or in section, at any time and from time to time up to 48 hrs prior to the Closing Day (as hereinafter outlined).

Each and every Unique Warrant shall entitle the holder thereof to acquire, matter to adjustment in particular situation and the Penalty Provision (as defined down below), and without payment of further thought, just one (1) device of the Enterprise (every single a “Unit”) on the training or considered exercise of each Exclusive Warrant. Every Unit shall consist of one (1) prevalent share of the Firm (a “Unit Share”) and one-50 percent (.5) of 1 typical share purchase warrant (each total prevalent share purchase warrant, a “Warrant”). Each Warrant will entitle the holder thereof to obtain just one frequent share of the Corporation (a “Warrant Share”) at a rate of $6.00 per Warrant Share for a period of time of 36 months following the closing of the Offering. The Unique Warrants will be exercisable by the holders thereof at any time following the Closing Day for no further consideration. All unexercised Special Warrants shall be considered exercised on behalf of, and with out any required action on the element of, the holders (which include payment of added consideration) on the previously of:

(i)

the second company day following the day on which a last receipt is obtained from the British Columbia Securities Commission (the “BCSC”), as principal regulator on behalf of the securities regulatory authorities in each Province of Canada, besides Québec , for a (last) small variety prospectus qualifying the distribution of the Unit Shares and Warrants to be issued on training of the Unique Warrants (the “Qualification Date”) and

(ii)

4:59 p.m. (Toronto time) on the date which is four months and a working day adhering to the Closing Day (the “Qualification Deadline”).

In the celebration the Qualification Date has not happened on or ahead of the day that is 45 days adhering to the Closing Day (the “Penalty Date”), every single outstanding Particular Warrant shall thereafter entitle the holder to obtain, on the physical exercise or considered exercise of just about every Unique Warrant, for no additional thought, 1.1 Units (the “Penalty Provision”).

The Enterprise anticipates the net proceeds of the Supplying will be applied for a program of data centre enhancement and miner / ASIC acquisition to boost hashrate by on just one Exahash for each 2nd, performing money needs and other normal company needs.

In thing to consider for their products and services, the Underwriters will get a money fee equivalent to 6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the gross proceeds of the Giving.

The securities described herein have not been, and will not be, registered under the United States Securities Act of 1933, as amended (the “U.S. Securities Act”), or any condition securities legislation, and accordingly, may possibly not be made available or offered in just the United States except in compliance with the registration needs of the U.S. Securities Act and applicable point out securities specifications or pursuant to exemptions therefrom. This press launch does not represent an offer to market or a solicitation to invest in any securities in any jurisdiction.

About HIVE Blockchain Systems Ltd.

HIVE Blockchain Systems Ltd. went public in 2017 as the very first cryptocurrency mining firm with a eco-friendly power and ESG technique.

HIVE is a advancement-oriented technology stock in the emergent blockchain marketplace. As a business whose shares trade on a major stock exchange, we are setting up a bridge in between the digital currency and blockchain sector and conventional money markets. HIVE owns state-of-the-artwork, environmentally friendly energy-powered facts centre amenities in Canada, Sweden, and Iceland, where by we resource only environmentally friendly electricity to mine on the cloud and HODL both of those Ethereum and Bitcoin. Because the beginning of 2021, HIVE has held in secure storage the the vast majority of its ETH and BTC coin mining benefits. Our shares present buyers with publicity to the functioning margins of digital forex mining, as very well as a portfolio of cryptocurrencies such as ETH and BTC. Due to the fact HIVE also owns tricky assets these kinds of as details centers and superior multi-use servers, we consider our shares supply traders an eye-catching way to acquire exposure to the cryptocurrency area.

We stimulate you to stop by HIVE’s YouTube channel below to understand far more about HIVE.

For much more facts and to sign up to HIVE’s mailing list, make sure you go to www.HIVEblockchain.com. Adhere to @HIVEblockchain on Twitter and subscribe to HIVE’s YouTube channel.

On Behalf of HIVE Blockchain Systems Ltd.
“Frank Holmes”
Government Chairman

For more information and facts you should make contact with:

Frank Holmes
Tel: (604) 664-1078

Neither the TSX Undertaking Trade nor its Regulation Companies Service provider (as that term is described in guidelines of the TSX Undertaking Exchange) accepts accountability for the adequacy or accuracy of this news release

Ahead-Wanting Facts

Other than for the statements of historical reality, this information launch consists of “forward-searching information” within just the which means of the relevant Canadian securities legislation that is primarily based on expectations, estimates and projections as at the day of this news launch. “Forward-seeking information” in this information release incorporates, but is not confined to, statements with respect to facts about the Featuring and the use of proceeds, potential dilution and application of the Penalty Provision company objectives and objectives of the Business and other forward-hunting data about the intentions, programs and foreseeable future steps of the get-togethers to the transactions described herein and the phrases thereon.

Things that could bring about real effects to differ materially from people described in these forward-seeking details consist of, but are not minimal to, the volatility of the digital currency marketplace the Company’s capacity to correctly mine digital forex the Enterprise may perhaps not be able to profitably liquidate its latest electronic currency stock as demanded, or at all a materials decline in electronic forex price ranges may have a sizeable detrimental impact on the Company’s functions the volatility of electronic forex price ranges continued outcomes of the COVID-19 pandemic might have a materials adverse influence on the Company’s overall performance as offer chains are disrupted and avert the Business from carrying out its expansion ideas or running its property and other related challenges as far more completely set out in the registration statement of Corporation and other documents disclosed under the Company’s filings at www.sec.gov/EDGAR and www.sedar.com.

The forward-searching details in this news launch reflects the recent expectations, assumptions and/or beliefs of the Business dependent on info currently offered to the Firm. In connection with the ahead-searching facts contained in this information release, the Enterprise has created assumptions about the Company’s potential to comprehensive the Featuring the timing thereof and associated issues. The Enterprise has also assumed that no considerable gatherings take place outside of the Firm’s standard training course of organization. Though the Company thinks that the assumptions inherent in the forward-hunting information and facts are acceptable, ahead-wanting details is not a assure of long run overall performance and appropriately undue reliance should not be set on these details due to the inherent uncertainty therein.

Letter to Biden makes bid for supply chain relief partnership

Letter to Biden makes bid for supply chain relief partnership

WASHINGTON — Grain millers have reached out to President Joe Biden searching for a associate in the mission to reduce massive US supply chain issues propelling prices larger amid expanding shortages of crucial elements these kinds of as gluten, emulsifiers, and soybean oil, alongside with packaging. 

The North American Millers’ Association, alongside with other key provide chain stakeholders in the agricultural, foodservice, trucking, warehousing, production, retail, development and energy sectors, printed an open up letter to Mr. Biden on Nov. 3. 

5 provide chain alternatives outlined in the letter could be executed straight away to relieve labor and transportation shortages, the undersigned mentioned.

“As business leaders and happy Us residents, we are firmly fully commited to this country’s economic restoration,” the letter stated. “We are doing work to usher in a return to normalcy and striving to help all Americans enjoy a better way of lifestyle by giving them with access to the vital products and solutions and materials they need.” 

  The coalition called to start with for the development of a younger driver pilot program that would allow businesses to create a two-stage, security-targeted apprenticeship method in which competent drivers ages 18 to 20 who fulfill rigorous security, training, and know-how necessities could then operate in interstate commerce. The letter also questioned Mr. Biden to shepherd collaboration in between sector, state and nearby companions, and the US Departments of Transportation and Labor to endorse source chain careers usually and commercial truck driving specifically. Highlighting the stability, very good gains and larger-than-normal wages extended-haul motorists get “can strengthen the life of quite a few unemployed and underemployed Individuals by providing them prospects for development whilst boosting the financial system,” the letter explained.

 “With 49 states and the District of Columbia now making it possible for drivers under the age of 21 to get their industrial driver’s license and function intrastate, this pilot software will offer a real prospect to handle current and upcoming driver shortages by endorsing a job pathway in trucking and creating a skilled, certified, and really-qualified rising transportation workforce,” the letter claimed.

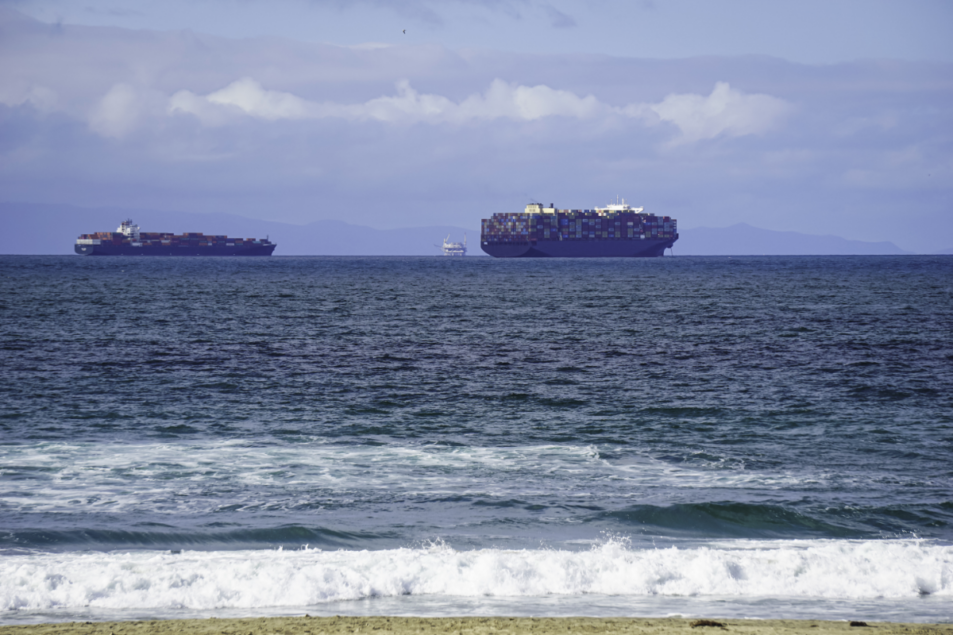
 The coalition then resolved the backlog scenario at US ports that features dozens of cargo ships anchoring off Southern California ready months to be unloaded.   The White Household on Oct. 13 declared that the Port of Los Angeles would operate all-around the clock in an effort and hard work to reduce bottlenecks.  But the speedy effects were muted, some transportation analysts claimed, taking into consideration many of the firms buying up intermodal containers had no motorists in area for right away shifts. In its Nov. 3 letter, the coalition encouraged ongoing investigation into inefficiencies at US ports and information sharing to ensure powerful use of resources and gear there. 

Subsequent, the letter dealt with pandemic insurance policies, specially vaccine mandates, in mild of the isolated mother nature of lengthy-haul drivers’ get the job done. Even though generating it distinct the undersigned groups were being fully commited to vaccines as a resource in the combat towards the distribute of COVID-19, the letter requested Mr. Biden to consider enhanced versatility vis-a-vis mandates. 

“We are concerned a mandate will cripple an previously strained provide chain,” the teams said. “We estimate businesses included by the mandate could lose 37{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of motorists at a time when the nation is currently small 80,000 truck drivers. We question for overall flexibility for transportation and provide chain important employees, especially truck drivers who invest most of their time in their trucks and have small contact with colleagues and consumers.” 

Finally, the letter sought extensions to hours-of-provider improvements implemented very last 12 months in the early months of the pandemic, and asked Mr. Biden to take into consideration delivering more flexibilities that may perhaps be wanted for the timely delivery of vital merchandise and that make perception from a safety and operational standpoint. In unique, the letter famous the great importance of this sort of regulatory flexibility at ports open 24 several hours.

Ninety-six associations signed the open letter to Mr. Biden. Provided from the agriculture sector ended up the Agricultural Vendors Association, the Agriculture Transportation Coalition, the American Farm Bureau Federation, the American Feed Business Association, the Countrywide Grain and Feed Affiliation, the National Sorghum Producers and several others. 

Together with NAMA, quite a few associations of industry experts in the milling, baking and ingredient sectors signed the letter, such as the American Bakers Association, the Independent Bakers Affiliation, the American Frozen Food stuff Institute and the Institute of Shortening and Edible Oils.

Smooth Sailing For MIT Sloan Grads

Smooth Sailing For MIT Sloan Grads

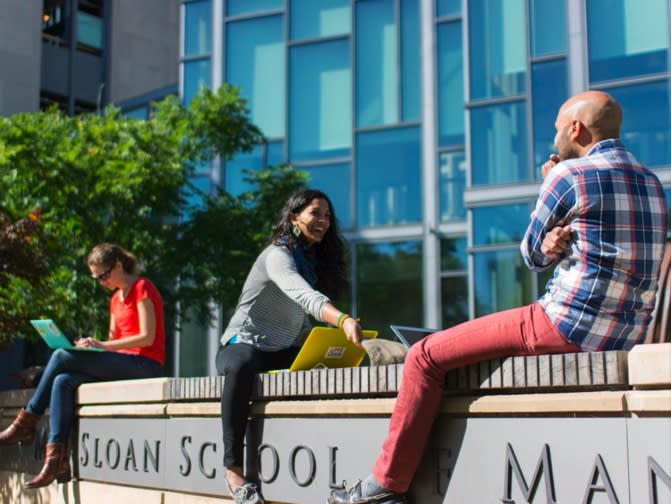
Ninety-six percent of MIT Sloan Class of 2021 MBAs had job offers by three months after graduation. Sloan photo

MIT Sloan School of Management MBAs didn’t experience the same severity of employment downturn in 2020 as most of their peers. With the release of the school’s 2021 jobs report, any hint of a pandemic pause in Sloan MBA prospects has been firmly put to rest.

Though median salaries and bonuses were flat this year at $150,000 and $30,000, other compensation, reported by more than 70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the class, skyrocketed from a median of $11,000 to $34,000, powering an 8.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} jump in total compensation to $195,600 from $180,223. That’s a much healthier rate of pay increase than last year’s 3.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and even better than the strong 7.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} that the Class of 2019 enjoyed.

Susan Brennan, assistant dean for the MIT Sloan Career Development Office, notes in the forward to the just-released report that the average base salary for Sloan’s MBA Class of 2021 increased to $148,075, while its “other” mean jumped significantly, to $65,064 from $52,947. “This year’s outcomes highlight the value of the MIT Sloan MBA, especially in times that call for agile business leaders who solve complex problems with ingenuity,” Brennan says.

JOB ACCEPTANCES GROW MORE THAN 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

Placement rates for MIT Sloan grads barely fell off last year during the worst months of the Covid-19 pandemic, though internships were another story (more on that below). For context, in 2019, nearly 96{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of MIT’s 403 grads received job offers by three months after graduation, down slightly from 2018 (97{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), while 93.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} accepted, down from 93.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Last year, amid coronavirus, the percentage of offers to the 314 grads who were actively seeking work dropped only slightly, to 95.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from 95.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and those accepting fell to 91.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Of the 407 MBAs graduating from MIT this year, 95.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} received offers within three months of graduation, a mild improvement, while 94.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} accepted — a better than 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} increase.

Top industries for MIT’s 2020 MBAs were consulting (31.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), technology (27.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), and finance (18.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}); a year before, consulting and tech were tied at 30.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Healthcare in 2020 was flat at 5.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, while manufacturing industries as a whole grew to 18.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the class, from 15.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2019. This year, consulting (28.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and tech (25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) were down a bit while finance saw a resurgence (21.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}). But the big news is the higher percentage of full-time offers in pharmaceuticals/healthcare/biotechnology, which grew to 9.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the class from 6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. (See page 2 for a list of top employers of Sloan MBAs over the years.)

We are grateful to our faculty, employers, alumni, students, and partners across the MIT Sloan community for creating and engaging in the uniquely Sloan experience that drives these great outcomes, through world-class curriculum, labs, centers and initiatives, and professional development and networking activities,” Brennan says.

342 COMPANIES HIRED SLOANIES FULL-TIME OR FOR SUMMER WORK

Of the 405 total graduates in the Class of 2020, 57, or 14.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, were sponsored and planned to return to their companies; that was up from 46 (11.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) in 2019. Fewer planned to start their own business, however: just 14, or 3.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, down from 6.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2019. This year, 76 Sloanies (18.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) were sponsored and returning, and 17 (4.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) were planning to become entrepreneurs.

Where do Sloanies go to work? Largely the Northeast — Boston and New York — though a larger portion chose the West than in 2020 — 29.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from 27.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Most of those (15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) went to the San Francisco Bay Area, home of Silicon Valley. The person with the largest reported salary — $230K — chose to stay local in Boston. This year, the Northeast once again claimed most Sloan grads (40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), but the lure of the West (28{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and San Francisco (15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) continued to be strong — and the earner of the top reported salary of $275K lives in the SF Bay Area.

As it is every year, growth potential was the top reason Sloan MBAs accepted their position, down slightly to 40.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from 43.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} (and 44.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2019). Sustainability, which had grown by leaps and bounds in 2019 as a cause for Sloan MBAs to take a job, then cratered from 4.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 0.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} last year, notably bounced back in 2021, to 2.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

“Sloanies are motivated by potential for impact and opportunities to make their ideas matter,” Brennan says. “Graduates found these opportunities with companies who have long-standing hiring relationships with MIT Sloan, as well as companies hiring at MIT Sloan for the first time. The Classes of 2021 and 2022 accepted opportunities at 342 companies, pursuing pathways for impact and advancement at leading and growing organizations across the country and around the globe.” She adds that 48.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Class of 2021 grads who accepted positions went to work with employers who hired three or more Sloan MBAs for full-time roles or internships, while 53.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the organizations that hired Sloanies this year did so for the first time.

MIT Sloan is the second M7 school to release its employment report so far this year; read about Chicago Booth’s Class of 2021 employment outcomes here.

MIT Sloan photo

Internships were hard to come by last year for MBA students at every school. At MIT Sloan, everyone from the careers office to school alumni had to pitch in. More than 100 startup opportunities were created on Orbit, the entrepreneurship opportunity platform of the Martin Trust Center for MIT Entrepreneurship; and more than 60 MIT research opportunities were formed with MIT faculty, research centers, and initiatives, including Covid-19 Alliance, Healthcare and Innovative Financing, and MIT Sloan LATAM Office. Meanwhile, 34 MBAs received support for their internship through the Internship and Faculty Project Fund, created in response to the pandemic.

For the MBA Class of 2021, the top internship industries were finance (26.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), technology (25.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), and consulting (16.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), with 31{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} accepting internships at MIT’s top hiring companies. This summer, the school’s careers office was surely still deeply involved, but no longer scrambling. For the MBA Class of 2022, the top internship industries were finance (26.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), tech (25.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), and consulting (21{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), with pharma/healthcare/biotech (7.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) “remaining a key industry for internship-seeking students, rounding out our top four industries,” Brennan says.

DON’T MISS MIT MAKES IT LOOK EASY: SLOAN MBAs GET SALARY BUMP IN 2020 and CHICAGO BOOTH’S 2021 JOBS REPORT SHOWS BIG BUMP IN MBA COMPENSATION

The post 2021 MBA Jobs: Smooth Sailing For MIT Sloan Grads appeared first on Poets&Quants.

Learn to teach finance classes

Learn to teach finance classes

Centre for Money Literacy

Released: 11/8/2021 5:08:19 PM

Center and large college educators in New Hampshire intrigued in honing their personal finance educating skills, or newcomers to the subject, can attend a no cost, on line, asynchronous course provided by the Economical Literacy Academy at the Heart for Fiscal Literacy at Champlain School, Get Auto Tips.

This graduate-amount program, which has been acknowledged by the White Household, will give New Hampshire educators who complete it the competencies and curricular resources to provide personal finance into their lecture rooms, mentioned John Pelletier, director of the Champlain heart.

“New Hampshire calls for that an economics study course be taken by every single student as a superior university graduation prerequisite and further more involves that this training course incorporate some own finance information, Pelletier explained. “In addition, Next Gen Own Finance study signifies that in New Hampshire, 9 percent of high educational institutions need a standalone private finance class as a graduation need and an additional 74 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} give a standalone personal finance program elective. There is a distinct will need for much more qualified individual finance authorities in New Hampshire.”

The initially 20 educators accepted for every of two sessions, will obtain a full scholarship. The first session operates asynchronously from Jan. 17 via March 11, and the second session operates from March 14 by way of Could 6. Software deadlines are Dec. 10 for the very first session and Feb. 11 for the second.

This course, which awards contributors 3 graduate-stage credits, is a continuation of the Champlain Fiscal Literacy Academy’s nationally acknowledged educator instruction system conducted in-person from 2011-2019 for approximately 300 educators. A generous grant from nameless donors and Next Gen Own Finance has authorized the center to present this system once more.

Pelletier reported that the class was regarded not only by the White Household, but also the Consumer Economic Protection Bureau, the FDIC, the U.S. Section of the Treasury and by President Obama’s Advisory Council on Financial Ability.

He pointed out also that the graduate training course has been the subject of two reports demonstrating the impact of the instruction. 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the 40 scholarships will go to instructors in Vermont, and the rest to educators in New York, Maine, New Hampshire, Massachusetts, Rhode Island and Connecticut.

Educators can sign up at ccoacademics.champlain.edu/eflacademy.

Champlain Higher education Center for Economic Literacy is committed to improving the individual finance information of our nation’s learners and older people, so much more People make seem selections about expending, credit rating, credit card debt, investments, and sophisticated financial predicaments these kinds of as getting a house and saving for retirement.

Visit : https://ahjedlvjmxsd.com/

What Do States Require for Commercial Auto Insurance?

What Do States Require for Commercial Auto Insurance?

If your company uses vehicles for work, commercial auto insurance is one of the most critical business insurance policies to obtain. Just as with personal vehicles, commercial vehicles are required to carry a minimum amount of insurance. If you’re driving without the appropriate insurance, you could be ticketed and fined – not to mention inadequately covered if there’s an accident and someone files a claim.

Here’s what you need to know about the legalities of commercial auto insurance and what your state requires.

Is commercial auto insurance required?

Every state has its own auto insurance requirements for commercial vehicles. In a few cases, you’ll see the same minimum requirements as there are for personal vehicles, but for the most part, commercial limits are higher than personal limits. 

Remember that the state requirement is the minimum amount the state mandates you carry. It’s critical to discuss your coverage with your insurance agent to make sure you have enough coverage, since many business owners would be subject to lawsuits if they’re not appropriately insured. 
Did you know?Did you know? Many of the best liability insurance providers have their own minimum coverage limits, which may be higher than state limits, when it comes to commercial auto insurance.

What do states require for commercial auto insurance?

The type of vehicle you have may impact a state’s commercial auto insurance requirements. Passenger vehicles usually have one type of requirement, while freight and cargo vehicles have another. You’ll be subject to stricter requirements in most states if you transport hazardous materials.  

What happens if I drive outside my state?

If you transport people or materials across state lines, your state insurance goes with you. In most instances, if the state limits where the car is registered are less than the state limits where you’ll be driving, the insurance carrier will match the limits, so you meet the legal requirements. 

Some states have interstate coverage requirements you must meet if you cross state borders when transporting people or goods. Make sure to stay within coverage territories, and note that limits may change once you drive into Mexico or Canada. 

Did you know?Did you know? Commercial auto insurance doesn’t cover medical expenses if an employee is driving and gets hurt. You’ll need workers’ compensation insurance for your employees’ medical expenses.

Understanding coverage limits

There are two different ways that states can require coverage. 

Per person, per accident and property damage

The first coverage type sets per person, per accident and property damage individual limits. When reviewing your coverage limits in this scenario, you may see three numbers that represent your total coverage, similar to your personal auto insurance. Each number covers an accident differently. For example, you might see coverage limits that look like this: 25/50/10. Those numbers represent dollar amounts multiplied by 1,000. 

  • The first number, 25, is really $25,000; this is for bodily injury coverage per person. This is the total amount the policy will pay for a person injured in an accident you cause. 
  • The second number, 50, is the total amount the insurance company will pay for all injuries in the accident. So, if you hit a car with four people in it, the policy will pay only up to $50,000 for the aggregate total of injuries. 
  • The last number, 10, represents the policy’s property damage coverage. In this case, the policy will pay up to $10,000 in property damage to another car or structure you hit. 

Combined single limit (CSL) coverage

In the second type of coverage requirement, the amount of coverage is listed as a single limit, known as a combined single limit. This is most the insurance company will pay per accident.  

Commercial auto requirements by state

Take a look at your state’s requirements in the compilation below. 

Alabama commercial auto insurance requirements

Alabama’s requirements are based on whether or not you are carrying passengers or nonhazardous materials. 

Requirements based on seating capacity:

  • 1-5 people: 25/50/10
  • 5-20 people: 50/200/30
  • 21 or more people: 100/500/50

Requirements if transporting nonhazardous materials: 

Learn more about Alabama motor carrier regulations

Alaska commercial auto insurance requirements

Alaska’s requirements are the same whether you are transporting property or people: 

  • $500,000 bodily injury 
  • $200,000 property damage

Learn more about the Alaska commercial motor vehicle law

Arizona commercial auto insurance requirements

Arizona’s requirements are contingent on whether it’s a passenger vehicle and the types of materials being transported. 

For passenger vehicles, it depends on the number of people the vehicle can hold.

  • 1-8 people: $250,000 CSL; $250,000 uninsured motorist
  • 9-15 people: $750,000 CSL; $300,000 uninsured motorist
  • 16 or more people: $5 million CSL; $300,000 uninsured motorist

If the vehicle transports nonhazardous materials, the vehicle’s weight comes into play. 

  • 20,001-26,000 pounds: $300,000 CSL
  • More than 26,000 pounds: $750,000 CSL

The requirements are different for hazardous materials carriers: 

  • $1 million to $5 million CSL, depending on the substance

Learn more about Arizona’s financial responsibility law

Arkansas commercial auto insurance requirements

Arkansas requirements are contingent on how many passengers are being transported and which types of materials are carried. 

For passenger vehicles, the individual bodily limit is $50,000, but the aggregate amount goes up for more passengers.

  • 1-12 people: 50/80/30
  • 13-20 people: 50/120/30
  • 21-30 people: 50/160/30
  • 31 or more people: 50/200/30

There are different requirements for vehicles carrying materials. 

  • Nonhazardous materials: 50/100/30
  • Hazardous materials: $1 million to $5 million CSL, contingent on specific materials

Learn more about Arkansas’ laws on passenger and freight transport

California commercial auto insurance requirements

California laws vary the insurance requirement based on the number of passengers, weight of the vehicle, and types of materials being transported. 

Passengers:

  • 1-7 people: $750,000 CSL
  • 8-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

Weight of the vehicle:

  • Less than 10,000 pounds: $300,000 CSL
  • 10,000 pounds or more: $750,000 CSL

Materials being transported:

  • Household goods: 250/500/100 or $600,000 CSL
  • Petroleum and petroleum waste products: 500/1,000/200 or $1.2 million CSL
  • Hazardous substances: $1 million to $5 million CSL, depending on the substance

Learn more about California’s motor carrier regulations

Colorado commercial auto insurance requirements

Colorado laws determine limits based on the number of potential passengers, movers, towing carriers and property carriers.

When it comes to passengers:

  • 1-8 people: $500,000 CSL
  • 9-15 people: $1.5 million CSL
  • 16-32 people: $3 million CSL
  • 33 or more people: $5 million CSL

For home or vehicle movers:

  • Less than 10,000 pounds: $300,000 CSL
  • 10,000 pounds or more: $750,000 CSL
  • Towing carriers: $750,000 CSL

For nonhazardous material transport based on vehicle weight:

  • Vehicles under 10,000 pounds: $300,000 CSL
  • Vehicles 10,000 pounds or more: $750,000 CSL

Learn more about Colorado motor vehicle laws

Connecticut commercial auto insurance requirements

Connecticut laws are contingent on the vehicle’s seating capacity, whether or not property is carried intrastate, and whether or not the vehicle is used in livery. 

For transporting passengers in a non-livery capacity:

  • 1-7 people: 50/100/10 or $100,000 CSL
  • 8-12 people: 50/150/10 or $150,000 CSL
  • 13-20 people: 50/200/10 or $200,000 CSL
  • 21-30 people: 50/250/10 or $250,000 CSL
  • 31 or more people: 50/300/10 or $300,000 CSL

For livery transport: 

  • 1-14 people: $1.5 million CSL
  • 15 or more people: $5 million CSL

For property carriers within the state:

Learn more about Connecticut’s motor carrier regulations.

Delaware commercial auto insurance requirements

Delaware has requirements based on the type of passenger transport offered.

For Delaware passenger carriers:

  • Taxicabs: $25,000 bodily injury; $10,000 property damage
  • Limousines and charter buses: $100,000 bodily injury; $50,000 property damage
  • School buses: $1 million CSL; 100/300 personal injury protection

Learn more about Delaware’s motor vehicle laws.

District of Columbia commercial auto insurance requirements

Washington, D.C., has different limits for taxicabs and carriers with various seating capacities.

  • Taxicabs: 10/20/5
  • Carriers with a seating capacity of up to 15 people for the WMATC authority: $1.5 million CSL
  • Carriers with unrestricted seating capacity for the WMATC authority: $5 million CSL

Learn more about the District of Columbia’s laws.

Florida commercial auto insurance requirements

In Florida, the law limits depend on whether it’s a passenger vehicle or a property transport vehicle. 

For Florida passenger vehicles:

  • Buses: 100/300/50 or $300,000 CSL

For property carriers, contingent on vehicle weight:

  • 26,000-34,999 pounds: $50,000 CSL
  • 35,000-43,999 pounds: $100,000 CSL
  • 44,000 or more pounds: $300,000 CSL

Learn more about Florida’s financial responsibility law.

Georgia commercial auto insurance requirements

Georgia has limits depending on the seating capacity and carrier type. 

For limousine drivers: 

  • 1-12 people: 100/300/50
  • 13 or more people: 100/500/50

For intrastate motor carriers: 

Learn more about Georgia’s passenger carrier laws

Hawaii commercial auto insurance requirements

Hawaii differentiates requirements based on whether the vehicle is a passenger vehicle or a transport vehicle. 

For passenger vehicles:

  • 1-7 people: 100/200/50
  • 8-25 people: 100/500/50
  • 26 or more people: 100/1,000/50

For other types of transport:

  • Property carriers: 250/750/250

Learn more about Hawaii’s motor vehicle insurance information

Idaho commercial auto insurance requirements

Idaho has different limits based on the size of passenger vehicles, whether the vehicle is carrying materials or property, and hazardous material transport. 

For passenger vehicles:

  • 1-24 people: $1.5 million CSL
  • 25 or more people: $5 million CSL

For property carriers:

  • Nonhazardous materials: $750,000 CSL
  • Hazardous materials: $1 million to $5 million CSL, depending on the substance

Learn more about Idaho’s motor vehicle laws.

Illinois commercial auto insurance requirements

Illinois breaks down its law to cover passenger carriers in one fashion while covering property carriers differently. 

For passenger vehicles:

  • 10-13 people: $1 million bodily injury; $100,000 property damage
  • 14-20 people: $1.5 million bodily injury; $100,000 property damage
  • 21-30 people: $2 million bodily injury; $100,000 property damage
  • 31 or more people: $3 million bodily injury; $100,000 property damage
  • Medical transport vehicles and other for-hire transport: $250,000 bodily injury; $50,000 property damage or $300,000 CSL

For those who transport property:

  • Property carriers: $750,000 CSL
  • Tow truck operators: $500,000 CSL
  • Hazardous substance carriers: $1 million to $5 million CSL, depending on the substance

Learn more about the Illinois vehicle code

Indiana commercial auto insurance requirements

Indiana’s limits depend on the size of the passenger vehicle and the type of freight carrier it is.

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL
  • Contract carriers transporting railroad employees: $5 million CSL

For other types of vehicles:

  • Fleet vehicles under 10,000 pounds: $300,000 CSL
  • Fleet vehicles 10,001 pounds or more: $750 CSL
  • Hazardous substances: $1 million to $5 million CSL, depending on the substance

Learn more about Indiana’s fleet statutes

Iowa commercial auto insurance requirements

Iowa has different limits for passenger vehicles and freight carriers. 

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL
  • Taxicabs with fewer than 7 passengers: $1 million CSL

Freight carrier rules are as follows: 

  • Vehicles under 10,000 pounds: $300,000 CSL
  • Vehicles 10,001 pounds or more: $750,000 CSL
  • Hazardous substances: $1 million or $5 million CSL, depending on the substance

Learn more about Iowa’s motor carrier insurance law

Kansas commercial auto insurance requirements

Kansas requires the same of passenger vehicles as it does for property transporters.

  • Passenger vehicles: 100/300/50
  • Property transports: 100/300/50

Learn more about Kansas’ motor carrier regulations.

Kentucky commercial auto insurance requirements

Kentucky separates passenger vehicles from the transport of goods. It further divides goods into general property, petroleum products and hazardous materials. 

For passenger vehicles:

  • 1-7 people: 100/300/50
  • 8 or more people: 100/600/50

For property and materials:

  • Vehicles 18,000 pounds or less: 100/300/50
  • Vehicles over 18,000 pounds: 100/600/50
  • Carriers of petroleum or petroleum products under 10,000 pounds: 100/300/50
  • Carriers of other hazardous materials: $1 million CSL

Learn more about Kentucky’s commercial vehicle law

Louisiana commercial auto insurance requirements

Louisiana breaks down the requirements based on passenger buses, trucks and tow trucks. 

  • Passenger buses: 250/500/10
  • Trucks: 250/500/10
  • Passenger-carrying vehicles: 250/500/10
  • Tow trucks: $500,000 CSL

Learn more about Louisiana’s motor vehicle law.

Maine commercial auto insurance requirements

Maine breaks down limits based on passenger vehicle seating capacity, interstate vehicles, property carriers and rentals.

For passenger vehicles:

  • School bus seating 1-30: $500,000 CSL
  • School bus seating more than 30: $1 million CSL
  • Interstate vehicles seating 1-3 people: 50/100/25 or $125 CSL
  • Intrastate vehicles seating 4-7 people: $300,000 CSL
  • Intrastate vehicles seating 8-15 people: $750,000 CSL
  • Intrastate vehicles seating 16-30 people: $1.5 million CSL
  • Intrastate vehicles seating more than 30 people: $2 million CSL

For interstate passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For property carriers:

For rental vehicles:

  • Rental cars: 50/100/25
  • Rental trucks: 50/100/25 or $125,000 CSL

Learn more about Maine’s financial responsibility law

Maryland commercial auto insurance requirements

Maryland breaks down its limits for intrastate passenger vehicles, cabs and hazardous property transport.

For passenger vehicles:

  • 1-7 people: 50/100/20 or $120,000 CSL
  • 8-15 people: 75/200/50 or $250,000 CSL
  • 16 or more people: 75/400/100 or $500,000 CSL
  • Taxicabs: 25/50/10

For hazardous property transport:

  • $1 million to $5 million CSL

Learn more about Maryland’s transportation laws.

Massachusetts commercial auto insurance requirements

Massachusetts has a combined single limit for passenger vehicles contingent on the vehicle’s seating capacity. 

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL
  • Sightseeing or charters with seating for fewer than 32 people: $1.5 million CSL

Learn more about Massachusetts law

Michigan commercial auto insurance requirements

Michigan defines limits based on seating capacity and freight type. 

For passenger vehicles: 

  • 1-9 people: $1 million CSL
  • 10-15 people: $2 million CSL
  • 16 or more people: $5 million CSL plus property protection
  • Limousines: $1 million CSL
  • Taxicabs: $300,000 CSL

For freight:

  • Vehicles 10,000 pounds or over with nonhazardous materials: $500,000 CSL
  • Vehicles 10,000 pounds or over with hazardous materials: $1 million CSL
  • Vehicles under 10,000 pounds with nonhazardous materials: 100/300/50 or $1 million CSL

Learn more about Michigan’s motor bus law and its Limousine, Taxicab, and Transportation Network Company Act

Minnesota commercial auto insurance requirements

Minnesota maintains regulations based on the number of passengers and substances carried. 

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For property carriers:

  • Nonhazardous materials: 100/300/50
  • Hazardous materials: $1 million to $5 million CSL, depending on the substance

Learn more about Minnesota’s Motor Carrier Financial Responsibility Law.

Mississippi commercial auto insurance requirements

Mississippi looks at whether a vehicle is a passenger vehicle or freight vehicle and follows federal financial responsibility laws. 

For passenger carriers:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For freight carriers:

  • Under 10,000 pounds with nonhazardous materials: $300,000 CSL
  • 10,000 pounds or more with nonhazardous materials: $750,000 CSL
  • Vehicles with hazardous materials: $1 million to $5 million CSL, depending on the substance

Learn more about Mississippi’s financial responsibility law.

Missouri commercial auto insurance requirements

Missouri considers whether passenger vehicles are interstate or intrastate and the type of property being transported.

For passenger vehicles:

  • Interstate for 1-15 people: $1.5 million CSL
  • Interstate for 16 or more people: $5 million CSL
  • Intrastate for 1-12 people: 100/300/50
  • Intrastate for 13 or more people: 100/500/50

For other commercial vehicles:

  • Tow trucks: $500,000 CSL
  • Interstate 10,000 pounds or more: $750,000 CSL
  • Intrastate except hazardous waste: 100/300/50
  • Transport of hazardous materials: $1 million to $5 million CSL, depending on materials

Learn more about Missouri’s transport and tow truck laws.

Montana commercial auto insurance requirements

Montana considers the vehicle type and whether it carries passengers or cargo. 

For passenger vehicles:

  • 1-7 people: $100,000 CSL
  • 8-15 people: $500,000 CSL
  • 16-26 people: $750,000 CSL

For property carriers of nonhazardous materials: 

  • Under 10,000 pounds: $100,000 CSL
  • 10,000 pounds or more: $500,000 CSL

For tow trucks:

  • Class A: $300,000 CSL
  • Class B: $500,000 CSL
  • Class C: $750,000 CSL

Learn more about Montana’s motor carrier insurance law.

Nebraska commercial auto insurance requirements

Nebraska laws depend on the type of passenger vehicle and whether it’s carrying goods. 

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL
  • Taxis and limousines: $500,000 CSL

For carriers of household goods:

Learn more about Nebraska’s motor carrier safety rules and regulations

Nevada commercial auto insurance requirements

Nevada even sets requirements for horse-drawn vehicles as well as different cargo carrier types. 

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL
  • Taxicabs and horse-drawn vehicles: 250/500/50

For property carriers:

  • Nonhazardous materials: $500,000 to $750,000 CSL, depending on cargo specifics
  • Hazardous materials: 300/2,500/1,000 or 300/2,500/5,000, depending on cargo specifics

Learn more about Nevada’s motor carrier laws

New Hampshire commercial auto insurance requirements

New Hampshire only specifies laws for passenger vehicles:

  • 1-7 people: 100/700/100
  • 8-12 people: 100/1,500/100
  • 13 or more people: 100/5,000/100

Learn more about New Hampshire’s motor vehicle laws.

New Jersey commercial auto insurance requirements

New Jersey has rules for passenger vehicles and tow trucks. 

For passenger vehicles:

  • 1-12 people: 25/100 bodily injury; 10/25 property damage
  • 13-20 people: 25/200 bodily injury; 10/25 property damage
  • 21-20 people: 25/400 bodily injury; 10/25 property damage
  • 31 or more people: 25/600 bodily injury; 10/25 property damage
  • Limousines: $1.5 million CSL
  • Jitneys (buses): 10/100/5 

For tow trucks:

  • Up to 26,000 pounds: $750,000 CSL
  • 26,000 pounds or more: $1 million CSL
  • Garage keepers liability: $100,000 CSL

Learn more about New Jersey’s motor vehicle law

New Mexico commercial auto insurance requirements

New Mexico breaks down regulations by passenger vehicles and cargo vehicles. 

For passenger vehicles: 

  • 1-6 people: $1 million CSL
  • 7-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For cargo vehicles:

  • Household goods: $750,000 CSL
  • Towing services: $750,000 CSL
  • Hazardous materials transport: $5 million CSL

Learn more about New Mexico’s motor carrier rules

New York commercial auto insurance requirements

New York has different requirements for passenger vehicles and cargo vehicles. 

For passenger vehicles:

  • 1-12 people: 100/300/50
  • 12 or more people: 100/500/50

For contract cargo carriers:

  • Property carriers: 100/300/50
  • Hazardous materials carriers: $1 million or $5 million CSL, depending on materials 

Learn more about New York commercial vehicle requirements

North Carolina commercial auto insurance requirements

North Carolina looks at passenger vehicles and property carriers differently. 

For passenger vehicles: 

  • 1-15 people: $1.5 million CSL
  • 15 or more people: $5 million CSL
  • School buses: $1 million to $1.5 million CSL
  • Taxis: 100/300/50

For property carriers of household goods:

  • 26,000 pounds or less: 100/300/50
  • Over 26,000 pounds: $750,000 CSL

Learn more about North Carolina’s motor vehicle regulations

North Dakota commercial auto insurance requirements

North Dakota differentiates between passenger vehicles, fleets and freight vehicles.

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For freight vehicles:

  • Fleet vehicles under 10,000 pounds: $300,000 CSL
  • Nonhazardous freight of 10,001 pounds or more: $750,000 CSL
  • Hazardous freight: $1 million to $5 million CSL, depending on substance

Learn more about North Dakota’s carriage of persons law

Ohio commercial auto insurance requirements

Ohio follows the federal regulations for passenger vehicles and hazardous materials. 

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For cargo carriers:

  • Intrastate carriers: $750,000 CSL
  • Hazardous materials: $1 million to $5 million CSL, depending on substance

Learn more about Ohio’s motor carrier regulations

Oklahoma commercial auto insurance requirements

Oklahoma breaks down regulations based on passenger carrier size and the type of property transported. 

For passenger vehicles:

  • 1-6 people: $100,000 CSL
  • 7-9 people: $750,000 CSL
  • 10-15 people: $1 million CSL
  • 16 or more people: $5 million CSL

For property carriers:

  • Under 10,000 pounds: $300,000 CSL
  • 10,000 pounds or more: $750,000 CSL
  • Household goods: $750,000 CSL
  • Restricted property: $350,000 CSL
  • Hazardous materials: $1 million to $5 million CSL, depending on the specifics

Learn more about Oklahoma’s motor carrier and private carrier regulations

Oregon commercial auto insurance requirements

Oregon keeps the coverage for passenger carriers and cargo carriers simple.

  • All Oregon passenger carriers: $750,000 CSL
  • All Oregon property carriers: $750,000 CSL

Learn more about Oregon’s motor carrier liability laws

Pennsylvania commercial auto insurance requirements

Pennsylvania differentiates passenger vehicles based on capacity and has a single requirement for property carriers. 

For passenger vehicles:

  • 1-15 people: 15/30/5 
  • 16-28 people: $1 million CSL
  • 29 or more people: $5 million CSL

For property carriers: 

Learn more about Pennsylvania’s financial responsibility laws.

Rhode Island commercial auto insurance requirements

Rhode Island looks at the type of passenger carrier being insured and whether a property carrier is a public carrier.

  • Public motor vehicles: $1.5 million bodily injury; $100,000 property damage
  • Common and contract: 250/500/25
  • Public livery: $300,000 CSL or 250/500/100 split limit
  • Jitneys: $300,000 CSL or equivalent split limit

Learn more about Rhode Island’s financial responsibility laws.

South Carolina commercial auto insurance requirements

South Carolina has different rules for passenger vehicles depending on whether they are interstate or intrastate. It also breaks down freight carriers based on weight. 

For passenger carriers:

  • 1-15 people (interstate): $1.5 million CSL
  • 16 or more (interstate): $5 million CSL
  • 1-7 people (intrastate): 25/50/25
  • 8-15 people (intrastate): 25/100/25
  • 16 or more people (intrastate): 25/300/25

For property carriers:

  • Nonhazardous freight under 10,000 pounds (intrastate): $500,000 CSL
  • Hazardous freight under 10,000 pounds (intrastate): $5 million CSL
  • Nonhazardous freight 10,000 pounds or more (interstate): $750,000 CSL
  • Hazardous freight 10,000 pounds or more (interstate): $5 million

Learn more about South Carolina’s financial responsibility laws

South Dakota commercial auto insurance requirements

South Dakota follows the federal guidelines for passenger and freight vehicles. 

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For freight carriers:

  • Fleet vehicles under 10,000 pounds: $300,000 CSL
  • Nonhazardous materials vehicles 10,000 pounds or greater: $750,000 CSL
  • Hazardous materials: $1 million or $5 million CSL, depending on substance

Learn more about South Dakota’s financial responsibility laws

Tennessee commercial auto insurance requirements

Tennessee follows the federal guidelines for passengers and hazardous materials. 

For passenger vehicles: 

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For property carriers:

  • Nonhazardous under 10,000 pounds: $300,000 CSL
  • Nonhazardous 10,000 pounds or more: $750,000 CSL
  • Hazardous materials: $1 million or $5 million CSL, depending on substance

Learn more about Tennessee’s financial responsibility laws

Texas commercial auto insurance requirements

Texas looks at the seating capacity of passenger vehicles and whether property transports have hazardous materials. 

For passenger vehicles:

  • 16-26 people: $500,000 CSL
  • 27 or more people: $5 million CSL

For property carriers: 

  • Household goods 26,000 pounds or less: $300,000 CSL
  • Household goods over 26,000 pounds: $500,000 CSL
  • Hazardous materials: $1 million or $5 million CSL, depending on substance

Learn more about Texas’ motor carrier insurance requirements

Utah commercial auto insurance requirements

Utah follows federal guidelines for passenger vehicles but has its own rules for freight carriers. 

For passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For freight carriers: 

  • Nonhazardous vehicles under 10,000 pounds: $300,000 CSL
  • Nonhazardous vehicles 10,000 pounds or more: $750,000 CSL
  • Hazardous materials: $1 million or $5 million CSL, depending on substance

Learn more about Utah’s requirements for motor carriers.

Vermont commercial auto insurance requirements

Vermont sets different rules for school buses and other passenger vehicles. 

For passenger vehicles: 

  • 1-7 people: 50/100/50
  • 8-12 people: 50/250/50
  • 13-20 people: 50/300/50
  • 21-30 people: 50/350/50
  • 31 or more people: 50/300/50

For school buses:

  • 1-9 people: 100/300/50
  • 10 or more people: 300/500/50

Learn more about Vermont’s financial responsibility laws

Virginia commercial auto insurance requirements

Virginia separates the requirements for taxicabs and passenger vehicles. It also has rules that separate intrastate from interstate cargo. 

For passenger vehicles:

  • 1-6 people: $350,000 CSL
  • 7-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For property carriers:

  • Vehicles more than 7,500 but less than 10,000 pounds: $300,000 CSL
  • Vehicles 10,000 pounds or more: $750,000
  • Intrastate property carriers: $750,000 CSL

Learn more about Virginia’s insurance regulations

Washington commercial auto insurance requirements

Washington breaks down insurance requirements based on how many passengers a vehicle can hold and whether it’s hauling household goods or hazardous materials. It also separates auto transportation companies. 

For passenger vehicles:

  • 1-15 people: 100/300/50
  • 16 or more people: 100/500/50
  • Private nonprofit bus transportation for 1-15 people: $500,000 CSL
  • Private nonprofit bus transportation for 16 or more people: $1 million CSL

For trucks hauling goods:

  • Nonhazardous materials on truck under 10,000 pounds: $300,000 CSL
  • Nonhazardous materials on truck 10,000 pounds or more: $750,000 CSL
  • Hazardous materials on truck under 10,000 pounds: $300,000 CSL
  • Garbage and refuse collection: $1 million to $5 million CSL, depending on the substance

Learn more about Washington’s motor carrier insurance regulations

West Virginia commercial auto insurance requirements

West Virginia breaks down the rules between interstate and intrastate vehicles. 

For intrastate passenger vehicles:

  • 1-5 people: 100/200/25
  • 6-12 people: 200/500/25
  • 13-20 people: 200/600/50
  • 21-30 people: 200/750/50
  • 31 or more people: 200/900/75

For intrastate property carriers: 

  • Nonhazardous property: 200/600/100

For interstate passenger vehicles:

  • 1-15 people: $1.5 million CSL
  • 16 or more people: $5 million CSL

For interstate property carriers:

  • Vehicles less than 10,000 pounds: $300,000
  • Vehicles 10,000 pounds or more: $750,000
  • Hazardous materials: $1 million or $5 million CSL, depending on specifics

Learn more about West Virginia’s motor carrier rules

Wisconsin commercial auto insurance requirements

Wisconsin has various rules that break down vehicle types based on passengers and property. 

For passenger vehicles based on capacity:

  • 1-7 people: 100/300/50
  • 8-12 people: 100/350/50
  • 13-20 people: 100/400/50
  • 21-30 people: 100/450/50
  • 31 or more people: 100/500/50
  • School buses with 37 or more people: $1 million CSL

For passenger vehicles for hire that aren’t school buses:

  • 10,000 pounds or less: $300,000 CSL
  • More than 10,000 pounds with up to 15 people: $1.5 million CSL
  • More than 10,000 pounds with 16 or more people: $5 million CSL

For exclusive intrastate passenger carriers:

  • 15 or fewer passengers: $500,000 CSL
  • 16 or more passengers: $1 million CSL

For property carriers:

  • Nonhazardous vehicles 10,000 pounds or less: $300,000 CSL
  • Nonhazardous vehicles more than 10,000 pounds: $750,000 CSL
  • Hazardous transport: $1 million or $5 million CSL, depending on the substance

Learn more about Wisconsin’s motor carrier insurance regulations.

Wyoming commercial auto insurance requirements

Wyoming sets standards as a combined single limit for bodily injury and property damage. 

  • Bodily injury/property damage: $750,000 CSL

Learn more about Wyoming’s financial responsibility requirements