G-20 finance leaders eye ways to support pandemic recovery

G-20 finance leaders eye ways to support pandemic recovery

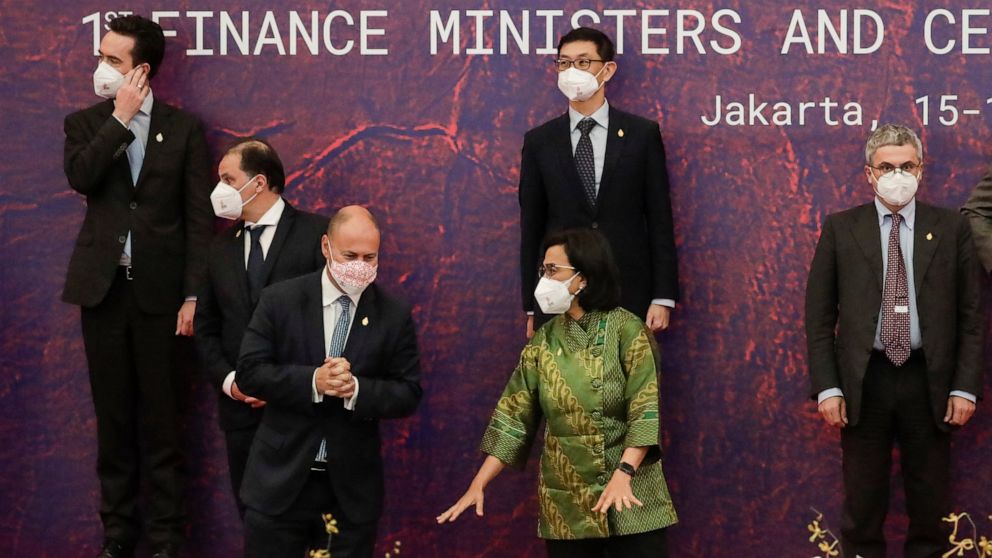
Indonesian President Joko Widodo instructed economical leaders of the Group of 20 industrial economies that international locations will have to stay away from tensions and cooperate to assist a restoration from the pandemic

JAKARTA — Countries need to stay clear of tensions and cooperate to help a restoration from the pandemic as it lingers in many areas of the world, Indonesian President Joko Widodo instructed a gathering of leading money leaders of the world’s biggest economies Thursday.

“The wintertime is coming,” Widodo stated in welcoming finance ministers and heads of central banking companies of the Group of 20 industrial nations.

“The pandemic is far from more than, and the world economy is struggling,” he mentioned. “During this situation, no one state could recover on your own. All countries are interconnected, no just one is isolated.”

The G-20 economic gathering arrives as a lot of economies are treading a precarious route between raising expenses of borrowing to amazing inflation and encouraging to guidance recoveries from the pandemic.

Anxieties above likely conflict in Ukraine are an additional unwelcome source of uncertainty, Widodo said, warning against antagonisms at this time.

“It is not the time to produce new tensions that could affect global recovery, let by yourself jeopardize the globe peace as we’ve presently witnessed in Ukraine,” he mentioned. “It is required that every single party puts an finish to rivalry and frictions.”

Officials ended up attending the conferences the two in man or woman and on line, specified problems with vacation and quarantines because of to outbreaks, primarily of the omicron variant of coronavirus, that are plaguing many countries.

Host Indonesia is among the a lot of international locations in Southeast Asia that have endured severe waves of infections, however vaccinations have aided quell the worst of outbreaks.

The fourth most populous country with 274 million folks, it has claimed almost 5 million instances and 145,622 deaths. In the previous month, 690,518 new circumstances have been noted.

Indonesia is the world’s 10th most significant financial system and is positioned in the fastest increasing location — at least right before the pandemic swept the planet, disrupting company and vacation though killing practically 6 million persons.

Surging costs for foodstuff and vitality are amongst the problems the monetary leaders confront as they go over how to very best nurture a worldwide financial restoration, Indonesian Finance Minister Sri Mulyani Indrawati instructed G-20 contributors.

“Inflation possibility stays skewed to the upside, driven by provide chain disruption, labor current market mismatches, wage pressure, and increased electricity prices,” she mentioned, incorporating that these types of challenges have been “more persistent than beforehand anticipated.”

The Global Monetary Fund has forecast that planet financial growth will slow to 4.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2022 from 5.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2021, adhering to a 3.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} contraction in 2020.

Mulyani emphasised the have to have for coordination among nations around the world in distinctive stages of restoration.

The U.S. Federal Reserve is pulling again on massive guidance for markets and firms, making ready to increase interest fees as quickly as subsequent month to neat inflation that jumped to 7.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in January — the maximum level in 40 a long time.

Customer rates rose to a document 5.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in the 19 countries that use the euro final month and to a approximately 30-year significant in the United Kingdom.

Indonesia’s central financial institution has also moved to control inflation. But some other economies have but to bounce back again from the havoc induced by the pandemic.

“Countries’ domestic macroeconomic coverage may perhaps also result in adverse impacts for other economies,” Mulyani mentioned. “In this regard, world-wide coordination, which include a discussion on exit technique will be crucial.”

Meanwhile, she pointed out that making sure countries have equitable obtain to vaccines stays an urgent priority for restricting new virus variants and ending the pandemic.

———

AP Organization Writer Elaine Kurtenbach in Bangkok and Edna Tarigan in Jakarta contributed.
US accuses financial website of spreading Russian propaganda

US accuses financial website of spreading Russian propaganda

WASHINGTON — U.S. intelligence officials on Tuesday accused a conservative money information internet site with a major American readership of amplifying Kremlin propaganda and alleged five media retailers concentrating on Ukrainians have taken way from Russian spies.

The officials explained Zero Hedge, which has 1.2 million Twitter followers, revealed articles established by Moscow-controlled media that were then shared by stores and individuals unaware of their nexus to Russian intelligence. The officials did not say no matter if they imagined Zero Hedge knew of any back links to spy businesses and did not allege immediate back links between the website and Russia.

Zero Hedge denied the statements and claimed it tries to “publish a extensive spectrum of sights that go over each sides of a presented tale.” In a reaction posted on the internet Tuesday morning, the web page mentioned it “has under no circumstances worked, collaborated or cooperated with Russia, nor are there any links to spy companies.”

It’s unclear irrespective of whether U.S. endeavours are altering Putin’s habits. And devoid of releasing far more proof of its conclusions, Washington has been criticized and reminded of past intelligence failures this kind of as the debunked allegations that pre-war Iraq experienced weapons of mass destruction.

Zero Hedge has been sharply crucial of Biden and posted stories about allegations of wrongdoing by his son Hunter. When probably finest recognized for its protection of markets and finance, the site also handles politics with a conservative bent.

In its response on line, the web site accused the AP of publishing a “bizarre strike piece” and stated authorities officials ended up making an attempt to distract from “our sights of the present dismal US economic scenario.”

“The base line is that these hit piece accusations that we somehow function with or for the Kremlin are absolutely nothing new: we have regularly confronted related allegations above the many years, and we can unquestionably validate that all of them are ‘errors,’” the site said.

In new months, Zero Hedge has printed a lot of article content that accused the U.S. of fomenting panic about Ukraine, which now faces the chance of an invasion by additional than 130,000 Russian troops massed on quite a few sides of the nation. Some of all those article content are listed as getting penned by people affiliated with the Strategic Culture Basis.

Current posts stated as authored by the foundation and revealed by Zero Hedge consist of people with the headlines: “NATO Sliding To War From Russia In Ukraine,” “Americans Have to have A Conspiracy Principle They Can All Concur On” and “Theater Of Absurd… Pentagon Requires Russia Clarify Troops On Russian Soil.”

In an e-mail despatched prior to its on the web reaction, the web page stated there “is no relationship in between Strategic Cultural Foundation (or the SVR) and Zero Hedge, and moreover this is the initially time we hear somebody allege that the Basis is linked to Russian propaganda.”

“They are 1 of our hundreds of contributors — unlike Mainstream Media, we test to publish a wide spectrum of sights that protect equally sides of a given tale,” the site claimed.

Disinformation has prolonged been utilized by Putin from adversaries, including the United States, and as a single instrument in regional conflicts to accompany cyberattacks and the movement of army forces. Washington and Kyiv have for months highlighted the problem of Russian affect in Ukrainian media.

Intelligence officials on Monday named two internet websites they claimed have been directed by the Strategic Culture Foundation. 3 other internet websites are alleged to have ties to the FSB, Russia’s federal security company.

“These web-sites allow the Russian government to secure support amid the Russian and Ukrainian populations,” a single official mentioned. “This is the major vector for how the Russian government will bolster help domestically for an invasion into Ukraine.”

Officers explained for the very first time what they say are direct communications concerning Russian spies and the editors or directors of the media stores. They did not release documents of the communications.

FSB officers experienced directed Konstantin Knyrik, the head of NewsFront, to publish stories exclusively harming to Ukraine’s impression, U.S. officers alleged. They said Knyrik has been praised by senior FSB officers for his do the job and asked for derogatory information that he could use towards the Caucasian Knot, a web page that handles information in the typically Muslim republics of southern Russia and neighboring nations around the world these types of as Georgia.

The editor of PolitNavigator despatched experiences of posted articles or blog posts to the FSB, an official said. And the taking care of editor of Antifashist allegedly was directed at the very least the moment by the FSB to delete product from the web page.

PolitNavigator’s editor, Sergey Stepanov, said Washington turns a blind eye to what he says are Ukraine’s anti-democratic actions and in its place labels people who issue them out “anti-Ukrainian propagandists” and “agents of the FSB.”

“I would like to feel that American journalism will increase above the hysteria provoked by officials,” he extra.

The Strategic Lifestyle Basis is accused of managing the sites Odna Rodyna and Fondsk. The foundation’s director, Vladimir Maximenko, has achieved with SVR handlers a number of periods considering that 2014, officials alleged.

Numerous of the sites have compact social media followings and might not surface influential at to start with glance, mentioned Bret Schafer, a senior fellow at the German Marshall Fund’s Alliance for Securing Democracy. But falsehoods or propaganda narratives generally begin tiny prior to they are amplified by bigger actors, he stated.

“You see the narrative enter the data space, and it is very difficult to see where it goes from there,” he mentioned.

A manifesto printed on Zero Hedge’s site defends its use of anonymous authors and proclaims its purpose is “to liberate oppressed expertise.” Many content articles are published underneath the identify Tyler Durden, also a character in the motion picture “Fight Club.”

The web page was an early amplifier of conspiracy theories and misinformation about the COVID-19 pandemic. An Involved Press investigation established the site played a pivotal position in advancing the unproven principle that China engineered the virus as a bioweapon. It is also posted posts touting normal immunity to COVID-19 and unproven treatment plans.

Zero Hedge was also cited in a latest report by the Institute for Strategic Dialogue that examined how much-proper extremists are harnessing COVID-19 misinformation to expand their get to. Twitter briefly suspended Zero Hedge’s account in 2020 but reinstated it a couple months afterwards, declaring it “made an error in our enforcement action in this situation.”

The U.S. relocating to title the web page could advise some individuals who appear across its written content on-line, Schafer claimed.

“My guess is that most of the men and women who are faithful Zero Hedge followers normally are inclined to distrust the U.S. federal government anyway,” he explained, “and so this announcement is most likely not heading to undermine most of Zero Hedge’s core guidance.”

———

Involved Press journalists Lynn Berry in Washington, Angela Charlton in Paris and David Klepper in Providence, Rhode Island, contributed to this report.

What should be in a finance super app?

What should be in a finance super app?

Dare I say it, but this calendar year is shaping up to be the year of the finance “super app.” Given that the beginning of the yr, I have found no considerably less than seven firms talking about making a super application.

Now, let me be crystal clear below. I am not chatting about a tremendous application like WeChat and Alipay in China. All those providers offer just about every little thing inside an application, from getting groceries, scheduling journey, trip-hailing, as nicely as each form of fiscal supplying you could imagine of.

Some people today have mentioned that The us is not a put to embrace tremendous applications. And that is likely accurate if we assume about the China design in which these tremendous applications are extra like finish ecosystems akin to the iOS or Android operating program.

But I believe there is a genuine opportunity for a foremost fintech (or financial institution) to create a tremendous app for finance. As I have now claimed, quite a few have started off on this journey.

Which brings up the essential problem: what must be provided in a finance super application?

Given the recent breakthroughs in open banking and embedded finance, we have the technologies to make a definitely compelling super application.

In this article are 20 matters I would like to see involved:

  • Digital bank account with debit card – all the common choices readily available today.
  • Higher yield savings account – higher yield signifies trying to keep pace with the Fed Funds Price.
  • Peer to peer payments – be capable to interface with various p2p payment networks.
  • Established price savings plans – with individual buckets to park this money.
  • Buy Now Fork out Later on – built-in BNPL performance.
  • Procuring – this could be built-in with BNPL but must consist of most common outlets.
  • Loyalty programs – there must be a central location to handle these.
  • Prompt transfers to outside financial institution accounts – why is this not normal now?
  • Shopper loans – the tremendous application will have adequate info to offer immediate mortgage approvals.
  • Credit rating playing cards – provide a assortment of rewards and no payment playing cards.
  • Overdraft safety – no overdraft expenses and the skill to accessibility up to $100 quickly.
  • Inventory investing – this is no for a longer time optional for a major finance app.
  • Crypto trading – ought to be capable to buy and provide the key crypto tokens.
  • Financial debt management – Assistance consumers control all their credit card debt for optimum desire cost savings.
  • Acquired Wage Accessibility – entry section of your paycheck early to spend for emergency costs.
  • Credit constructing and monitoring – give a pathway to setting up a credit rating score.
  • On-ramp to DeFi – this is probable some time absent but I believe it will be required of a finance super application in the long run
  • Join outside the house investments – the super application should be capable to see all/most of your investment decision accounts.
  • Open up banking connections – see all the areas in which your financial institution account information has been shared.
  • See total money photograph – dashboard with KPIs to give you a apparent photograph of web really worth and how your fiscal existence is trending.

This last level is specifically interesting to me. Most firms currently evaluate a array of essential performance indicators, and many of the compact enterprise apps have handy dashboards that exhibit the business’s wellbeing at a look. But we really don’t genuinely have an equal thought for consumer finance crucial efficiency indicators past a credit score rating.

I would like to see the finance super application deliver far more economical intelligence. It should response how lots of weeks or months we can deal with with our savings, how our totally free cash stream is trending, full financial commitment returns (if any), how our debt load is trending, and extra.

Who is closest to establishing the finance tremendous application?

We are however far absent from any enterprise coming near to the features I described earlier mentioned.

PayPal is probably closest, but they only have all-around 50 percent of the characteristics I would like to see. SoFi, fresh new off internet hosting the Superbowl in their shiny new stadium, has possible as they have in all probability the broadest offerings of the new breed of fintechs.

Chime, the largest electronic bank in the U.S., has a extended way to go with a constrained element set to day.

MoneyLion is also a organization I am seeing carefully as they preserve incorporating new characteristics often.

In Europe, Revolut has the broadest established of options, so we don’t want to count them out in this article.

Digging deeper into the finance super application

FT Partners unveiled an fantastic report titled The Race to the Super App earlier this thirty day period. It implies two different versions or avenues to a finance super application.

For my vision of the tremendous application, only a single of their designs makes sense but what I preferred about this report is that it delves into the choices of every single significant fintech in the place.

We are likely to have many finance tremendous applications ultimately. I really don’t consider this is a winner requires all group. There are probably to be 2-3 companies that get critical traction and a number of other people with enough consumers to make their enterprise worthwhile.

I also consider the fintech providers will be in a position to cost for this service. A subset of capabilities should really be free of charge to encourage mass adoption, but a finish aspect established could be so worthwhile that a regular price will be feasible.

One particular closing observe. A person business does not want to establish all this features in-property. There could be partnerships where a 3rd celebration gives the procedures, but it resides within the super application from a user point of view. With this in intellect, it could very well be a financial institution that makes the ultimate finance super app in the very long run. But as of right now, fintechs have the direct. The race is on.

Stitch raises $21M for its API infrastructure and embedded finance platform

Stitch raises M for its API infrastructure and embedded finance platform

Open up finance proceeds to be a important topic in the entire world of fintech as firms tap APIs to obtain customers’ fiscal accounts and provide a gamut of integrated and embedded fiscal products and services. In the most up-to-date advancement, Stitch — a single of the prominent gamers setting up and functioning these APIs in Africa — confirmed to TechCrunch that it has lifted $21 million in Sequence A funding.

This news follows the $4 million Stitch lifted out of stealth in February 2021, a prequel to the $2 million extension round it secured 4 months in the past, bringing its seed spherical to $6 million. In complete, Sew has elevated $27 million to date.

The South African API fintech enables corporations to establish, improve, and scale fiscal solutions. For each a statement launched by the business, it ideas to develop a “financial graph” ecosystem across Africa with the new funding.

The firm describes the monetary graph as an infrastructure for money making blocks that allow firms to publish code as soon as, start in multiple markets and scale a lot quicker centered on interoperability throughout areas, companies, banking companies, and other styles of economic accounts.

“We type of look at the broader monetary ecosystem as a bunch of diverse nodes–bank accounts, retailers these kinds of as fintechs or end-consumers–which are all intrinsically related,” Stitch CEO Kiaan Pillay stated to TechCrunch in an interview. “Often, we believe about the reality that these connections between geographies and institutions really don’t exist however. And a lot of what we check out to do is to bridge those connections and to make these connections ubiquitous.”

Stitch sights this graph in three phases. The initially is what it introduced from stealth: the pure infrastructural engage in of connecting financial and bank accounts with an API. The second seeks to receive retailers and businesses to build use circumstances and apps on leading of that infrastructure. And the final is getting stop customers to website link their accounts by means of these companies.

“On the large degree, individuals moving from money to digital for the quite initial time will cause much more fragmentation. Our check out is that encompassing this all in 1 network or graph assists to open up the place up and break down the silos,” stated Pillay. “And the way we in the end feel about that is that people today can very easily move dollars between many applications concerning several geographies and establishments.”

Stitch’s delivers remedies for e-commerce organizations, marketplaces & platforms and its leading clientele, fintechs. As with other many years, African fintechs outperformed other startups in increasing venture funds, particularly in a record-breaking 2021 where by they raised 50-60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of complete VC funding for every reports. Their relevance can not be overstated and infrastructural gamers these kinds of Stitch, Mono, Okra, Plaid and OnePipe —all who lifted cash within just the earlier calendar year, some in seed and some others, Sequence A — are pivotal to that collective development of driving monetary inclusion and relieve of payments across the continent.

These business customers use Sew for use instances these kinds of as KYC & onboarding, personalized and company money administration, lending, wallet prime-ups and e-commerce checkouts. The platform’s info, and identity goods enable companies to entry client transaction histories and balance info, validate account facts, and complete fraud checks. The payments products allows bank-to-bank transfers for a person-click fork out-ins and payouts.

Some consumers consist of wallet-based organizations these kinds of as Chipper Money and Luno embedded finance providers like ImaliPay subscription platforms like FlexClub and payment aggregators like Yoco.

Stitch

Sew

Impression Credits: Stitch

In April 2021, Sew introduced its payments solution in South Africa and seen a 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month-on-thirty day period growth in payments volume the pursuing 6 months. In October, Stitch expanded the payment product or service to Nigeria and, at the time, was on keep track of to facilitate $10 million in month-to-month payments by December.

On the contact, Pillay, who co-started Sew with Natalie Cuthbert and Priyen Pillay, did not give any update on this metric but reported Stitch experienced viewed a 104{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} thirty day period-on-thirty day period progress in payments worth considering the fact that launching the product or service previous April. And in Q4 2021, the platform witnessed a 44{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} thirty day period-on-thirty day period client advancement and a 72{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month-on-month increase in joined economic accounts.

“We’re very pleased of the partners and customers we have below as we go on to deepen the payments merchandise and glimpse at regular and recurring payments, which are interesting attribute sets for us,” explained Pillay.

“We lately experienced a couple clients go are living in Nigeria, which has been pretty exciting for us. We just offer you payments there but are keen to deepen the merchandise. We will search at introducing data and identification this yr, as perfectly as deepening the payments established in the same way to how we have it in South Africa.”

New York-dependent extensive-time period financial commitment company The Spruce Dwelling Partnership led this spherical of funding. The spherical also welcomed participation from new and current buyers like PayPal Ventures, TrueLayer, firstminute funds, The Raba Partnership, CRE Enterprise Funds, Village World, as well as fintech founders and corporations this kind of as TrueLayer, founders of Chipper Money, Quovo and Unit, and Guillaume Pousaz’s Zinal Expansion.

“We have been adhering to startups in Africa for many years. Our diligence was pretty clear that this is one of the most talented groups on the continent, and we are enthusiastic to be a component of what they are developing at Stitch,” said Ben Stein, co-founder of The Spruce Residence Partnership.

Pillay says increasing dollars from VC corporations and operators that have scaled fintech goods throughout several geographies offers the organization “something very special” as it enters its future progress period. The funding, Stitch claimed, will permit it to expand its workforce throughout places of work in Cape City, Johannesburg and Lagos, start new product or service choices and enter new marketplaces throughout the continent.

Kiplinger’s Personal Finance: Financial companies with the best digital tools | Business News

Kiplinger’s Personal Finance: Financial companies with the best digital tools | Business News

If you take care of your finances on your phone or pc, you know how vital it is to do the job with an establishment with person-pleasant electronic equipment. Kiplinger’s Private Finance recently reviewed apps and websites to come across the money businesses with the ideal electronic applications.

The bank’s mobile application and web site are the most person-friendly of the bunch, combining easy navigation, an desirable interface and a handy set of capabilities for bank clients.

Account balances are displayed neatly and prominently on the property web page, and you can drill down into every single account to see a listing of modern transactions and other information.

A single noteworthy application characteristic: Rather than tapping a button to finish sure transactions, this sort of as transferring money or depositing a check, you drag the button across the display.

Most effective card issuer: American Convey

The company’s cellular application and website are basic to navigate yet provide a good deal of characteristics and operation.

Persons are also reading…

It’s quick to come across and use a chat box that provides automatic answers to your queries, as perfectly as stay obtain to client assistance associates. Your assertion stability, whole equilibrium and payment due are featured prominently at the prime of the dwelling webpage, and current transactions are shown under.

Evidently marked buttons consider you to web pages for statements, payments, viewing and redeeming benefits balances, and running these types of tasks as replacing a broken or stolen card and altering account notifications. And consumers in the Membership Rewards application can type by means of card gains on the app and use on-the-go equipment.

Ideal mortgage loan financial institution: U.S. Lender

By way of U.S. Bank’s site and cell app, you can see existing hold out situations to communicate to a client assistance consultant on the cellular phone and ask for to have a rep connect with you if you’d rather not hold out on keep.

Prospects can also “co-browse” with lender representatives, letting shoppers to share their monitor so they can navigate the web page or app with each other. And final summer months, the bank launched a person-way video clip of the agent so that clients can see the individual with whom they are talking.

In response to an influx of property finance loan buyers who necessary economic accommodations as the pandemic induced the economic system to crater, U.S. Lender extra the capacity for clients to make payments by means of its help-program web portal. And all of the essential resources keep their very own.

Geico will get the nod as our electronic winner among the insurers, with a clean up, effectively-made application and website that present great options for the two consumers and noncustomers.

As a Geico consumer, you can use the application to pull up digital insurance ID cards on the go, get roadside aid, post pictures to get an estimate of car problems inside of about 20 minutes, make payments, and chat with a digital assistant about billing, guidelines and other concerns.

Go to Kiplinger.com for extra on this and related cash subjects.

‘I feel scared; I get angry’

‘I feel scared; I get angry’

Inflation is very seriously switching Ligia Murillo’s obtaining styles — and she’s upset about it. “Prices are out of management,” Murillo, 55, of Norwalk, Conn., explained to Yahoo Finance. “I’m constantly wanting for gross sales. I stopped purchasing steaks. I purchase hen it’s considerably less high-priced.”

Like hundreds of thousands of persons, Murillo’s paying for ability has shrunk as inflation — at a 40-year high — proceeds to effect almost every category of goods and services.

“I am offended,” Murillo mentioned. “I’m offended with the governing administration because they are not spending plenty of interest [to] the actual predicament we are living in.”

Murillo, who owns a modest household-cleansing services, states she and her spouse not long ago lower their fees by switching their household insurance policies and canceling their neighborhood newspaper subscription. She states they almost never store for discretionary things like apparel anymore.

‘People are reacting to bigger prices’

Modern details indicators people are commencing to slice again on some of the items that have gone up the most in value.

“You’re beginning to see a drop in spending across a amount of groups exactly where costs have enhanced noticeably,” Omair Sharif, founder of Inflation Insights, explained to Yahoo Finance.

“Over the very last 6 months, paying on beef goods, in authentic conditions right after inflation altered, have long gone down over 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in just the very last 6 months by itself. Persons are reacting to bigger charges and cutting again on objects the place prices have gone up a lot, and we can see that in the facts,” he extra.

In 2022, customers be expecting “to spend additional on groceries, utilities, and at-home principles though numerous sign they will spend much less on discretionary items and out-of-property occasions” according to NielsenIQ’s most current Purchaser Outlook survey.

The significant surveys and knowledge sets don’t nevertheless independent in accordance to profits levels. Nevertheless, commentary through PayPal’s (PYPL) hottest earnings call gave a glimpse into how some decreased-revenue shoppers are working with inflation.

“We’ve noticed weak spot all-around expending in our decrease-cash flow cohorts, and picture for us, the proportion of our person foundation is fairly similar to what you see just like in the U.S. in general,” CFO of PayPal John Rainey explained for the duration of the contact.

‘How do seniors and people today with kids survive this?’

Meals, housing, and gasoline make up a major chunk of customer investing — expenses which are tough to get all over, significantly when it will come to rent.

“The issue is it is difficult to slash back again on items like shelter. If you will need to pay back hire, that is not likely to improve. So that type of stress falls far more on folks who are in the decreased-money distribution,” explained Sharif of Inflation Insights.

Murillo claims “by the grace of God” she and her husband really do not only count on her household-cleaning cash flow. They very own a few little rental homes close by. She and her spouse haven’t raised rents to industry worth considering the fact that prior to the pandemic simply because their tenants pay out on time and have children.

“I sense fearful, I get indignant, I get sad. How do the seniors and individuals with small children survive this?” she questioned.

Ines is a marketplaces reporter masking stocks from the Nasdaq.

Comply with her on Twitter at @ines_ferre

Examine the latest economic and enterprise information from Yahoo Finance

Observe Yahoo Finance on Twitter, Instagram, YouTube, Fb, Flipboard, and LinkedIn