How the pandemic changed the rules of personal finance : Planet Money : NPR

How the pandemic changed the rules of personal finance : Planet Money : NPR
How the pandemic changed the rules of personal finance

In the last half of past 12 months, we heard a lot of converse (and we at NPR did a ton of chatting) about the Fantastic Resignation, aka the Massive Give up. This was a craze that started proper all around the starting of the COVID-19 pandemic, and observed — anecdotally, at the very least — big quantities of folks leaving their positions voluntarily. There was some controversy about the Significant Stop, not the the very least simply because some reporting on the craze built it seem as although a lot of of these personnel had decided to go away the labor pressure eternally.

But the tough details — notably here in the US — suggests that in truth the labor power participation fee, which plunged at the beginning of 2020, recovered quite speedily. That included employees close to retirement age. Which implies that men and women weren’t essentially quitting get the job done completely, but were, relatively, just switching careers — in a lot of scenarios leaving employment that paid well but demanded extensive hours, and finding work that perhaps compensated fewer but gave them more command over their lives. In other words and phrases, it was much less the Excellent Resignation and far more the Good Reshuffle.

That is absolutely the summary that Jill Schlesinger attained. Schlesinger is a accredited financial planner and a business enterprise analyst at CBS News. She’s also the author of a new ebook, The Great Funds Reset, which draws on her experience chatting with callers to her private finance podcast, Jill on Funds. A lot of of those callers have been taking into consideration their have Massive Quit, but they were not absolutely sure regardless of whether they could do it, or how to go about it.

The Great Money Reset book cover

Schlesinger suggests issues about switching employment with a look at to accomplishing superior perform-everyday living harmony aren’t unheard of in the personal finance globe, but they grew to become a whole lot more widespread through the pandemic. She describes herself as inundated. And she suggests that is the 1st in a selection of huge variations that she thinks will affect the personal finance environment going forward.

“Amid the pandemic, people who identified as my present had been trying to find extra command more than their time and do the job situations,” she claims. “With the advantage of time and the quiet of the pandemic, quite a few concluded that they want to function fewer or in another way, delight in a lot more overall flexibility in their work opportunities, operate at a less demanding career, or shift to a new vocation. They do not always wish to forgo the comforts of lifetime, but they are willing to make at minimum some economic sacrifices in get to do it.”

It really is not only about the figures

Fiscal sacrifice! That is not a phrase you hear much in the personalized finance entire world. That is for the reason that, for the most portion, particular finance experts and planners are concentrated on growing belongings, with an eye on a lengthy-time period time horizon: retirement. In that earth, the principle of economic sacrifice won’t really fit. Schlesinger thinks the pandemic has transformed that since buyers have been built acutely mindful that they may not make it to retirement, and it really is a fantastic plan to feel about how to enjoy some of that revenue now. To component that into the money organizing procedure, Schlesinger suggests, advisors are likely to have to get to know their consumers improved.

“What is actually difficult for a whole lot of money planners is they never like to get into the psychological things,” Schlesinger says. The best — and most costly — planners do, of system: they see their clients as advanced human beings, who have diverse desires and messy lives. Most of the fiscal products and services market, nevertheless, is geared in direction of treating people as widgets that are anticipated to have a sure daily life span, punctuated by a precise retirement position. You can find not significantly place for the human component there. Schlesinger states excellent economic planners have been currently turning versus that solution before the pandemic hit.

“They realize that you can not just hand a consumer a record and say, remember to populate the belongings, liabilities, earnings bills,” Schlesinger suggests. “You essentially have to learn about who they are. And I believe that the pandemic has accelerated that craze.”

The reserve fund is the most crucial issue

Schlesinger suggests that just before the pandemic, she would give persons some quite typical guidance about their revenue. She would start by telling them about the three mainstays of personalized finance.

“I would say to persons, you happen to be just starting off out. Here is what you have to do: You want an unexpected emergency reserve fund, you need to have to pay off your debt, and you will need to try to put revenue into retirement. And I would normally give individuals factors equivalent fat.”

People observed the knowledge of paying out off debt and saving for retirement, of system. The crisis reserve fund? That was a more difficult sell.

“Men and women would yell at me and say, ‘How can you convey to persons to preserve 6 to 12 months of their residing bills in an account which is having to pay no curiosity?’ Due to the fact keep in mind in the course of the pandemic and early times, it really was {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} desire,” she states. But the pandemic underlined the value of getting some kind of income cushion. “The people today I spoke to who experienced emergency reserves, had funds that they could faucet into, went via the pandemic in a really distinctive way than people who were being relying on stimulus checks and prolonged unemployment positive aspects.”

Now, she claims, she even now touts the a few mainstays, but currently the crisis fund will get substantially much more awareness. And not just from her. “I imagine write-up pandemic, extra individuals understand that obtaining an crisis reserve fund — possessing access to cash that you can rely on — has become range 1, two, and a few.”

All people wishes to discuss about estate planning now

For most economical planners, the hardest element of discussions is conversing about the stop match. People are delighted to discuss retirement all working day long. Following all, they’re anticipating a superior time, when they can journey, or see household, and do all the factors they’ve set off executing for forty many years. But speaking about what takes place to their revenue and their property when they die? No a person ever wanted to discuss about that in advance of the pandemic.

They do now.

“I no longer have to combat with people today about obtaining estate scheduling,” Schlesinger claims. “It is really been a interesting shift.”

Schlesinger suggests COVID-19 place stop-of-lifestyle criteria on to the entrance burner for a great deal of people today. She read an primarily agonizing tale from just one caller, who advised her about a blowup about a spouse and children organization. “Anyone died and there was a tiny company concerned and there was no instruction. Like, ‘what are we doing with this enterprise? Well, father would’ve required us to preserve it, but mom genuinely requirements the income.'”

A household battle erupted because the mum or dad who died remaining no recommendations. Presumably not what the parent experienced wished to go away as their legacy. And certainly not what the grieving relations wanted to go by way of.

“Most people is familiar with somebody who has a awful estate story,” Schlesinger claims. The upside is that all those people paid focus to people stories. Now they want to explore estate arranging. But those people are difficult conversations that pressure folks to make difficult possibilities, and the challenge now, Schlesinger says, is essentially receiving her consumers to place these designs in spot.

The triggers have improved

It wasn’t unheard of for people to make major modifications in their life before the pandemic, of class, but Schlesinger says it was not especially frequent. Most individuals had a career and predictable trajectory to retirement that they did their finest to stick to. There ended up generally only a handful of everyday living gatherings that could change people from that trajectory. Divorce and death were being the massive kinds, she suggests, but the pandemic brought a great deal a lot more triggers to the fore: Psychological wellbeing adverse function situations isolation.

“You are residing this really bare, stripped down lifestyle, and you happen to be with your thoughts, and you might be hearing about awful things and it really is seriously terrifying,” she states, noting that in that context, out of the blue a large amount of the selections we built in purchase to arrive at a faraway money objective didn’t appear to be to make perception. “And probably that’s the moment you say, ‘why do I reside a thousand miles away from my mother and father? Why have I decided on to do the job so tough that essentially I am not confident I definitely like my task but I know I actually appreciate my little ones, and I do not genuinely feel I want to do the job this way any longer.'”

The huge barrier to generating change — even when it would seem the obvious decision — is panic. But the way Schlesinger sees it, the pandemic forced adjust on a big number of people. And they had to experience people fears.

“I just was so overcome by the range of people who ended up fearful. But who, once that anxiety began to dissipate, seriously noticed possibility amid all this chaos. And I am not speaking about marketplace prospect, I am talking about lifetime prospect. What is it that I truly think I wanna do?”

She claims individual finance specialists and economic planners are heading to have to have to occur to phrases with the fact that, in a unusual way, the pandemic made people today sense they essential to consider command around their lives in a much more lively way, and to advocate for their far more instant demands and wants. Now it truly is okay to seem at your job ambitions and your monetary plans for retirement and all the rest of it and say … What about me? Exactly where does my in-the-instant pleasure healthy into this?

Schlesinger has designed significant, daring shifts in her very own daily life in the previous: she gave up a valuable fiscal planning occupation to come to be a author, journalist, and podcaster — so she understands what is at stake. But it was the working experience of a good friend of hers, Maureen, that truly introduced house to her the worth of being familiar with what the authentic motivations are for making variations in your lifestyle. And how to respond to them.

Maureen came to Schlesinger a several several years back for assistance dealing with a large possible life change — a divorce. It was a rough problem to contend with. But not prolonged following, things bought even harder. “Maureen was identified with a very fatal most cancers and she experienced a 4 month horrible health issues and died on November 30th,” Schlesinger says. “Absolutely everyone has a momentous occasion that shakes up your lifestyle. Most people does. And you experience the strain. You truly feel emotions I imagine even in myself as I went by way of that celebration with her, my possess capacity to recognize how the possibilities we make subject, was amplified. And what I can tell you is that when you have the ability to program in advance and use that to open up up pathways for oneself, it really is genuinely helpful.”

Lighten up a minimal

Wild investing approaches have been all around for as very long as markets have existed, but the pandemic coincided with some of the craziest, which includes the meme stock explosion and the crypto trend. Schlesinger thinks this had considerably to do with individuals getting locked down, without having substantially to do, though there was a whole lot of money sloshing about the method.

“When I say a ton of revenue sloshing all around the technique, recall that we had trillions of dollars of excess financial savings that designed up. Mostly that came from the higher, best internet worthy of persons, but a great deal of folks have been awareness personnel working at house who bought stimulus checks and had a good deal of time to futz all over and experienced a couple bucks in their accounts.”

She suggests the communities that fueled this sort of investing were not new, but they exploded throughout the pandemic, and they will likely diminish the moment COVID and its variants recede. But they won’t go absent. And which is ok. It is even okay to devote some time on your decision of subreddit and surf the occasional meme inventory or crypto asset wave. So extended as you do it responsibly.

“I am not constitutionally against folks using flyers,” Schlesinger states. “I signify, have enjoyable, but you should not have enjoyment and hazard the farm. Have enjoyable and say, ‘All suitable, I put 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of my overall investments in some nuts stuff. That’s enjoyment.'”

In other terms, private finance will not have to be all asset allocation, revenue optimization, estate arranging and taxes. It can be enjoyment much too — if you select. Which is a new rule that all people can get down with.

Jill Schlesinger’s new book is The Fantastic Revenue Reset. It can be out now.
Camp Lejeune Ads Surge Amid ‘Wild West’ of Legal Finance, Tech

Camp Lejeune Ads Surge Amid ‘Wild West’ of Legal Finance, Tech

A historic range of probable claimants and a new period in authorized marketing and advertising have turned the Camp Lejeune tainted drinking water litigation into a possible history-setter for the quantity invested and spent on promoting.

Far more than $145 million had been put in on tv and social media advertising and marketing by year’s conclusion, according to advert information reviewed by Bloomberg Legislation.

Insiders forecast that number could easily double, in portion due to the fact as a lot of as 500,000 veterans or their family members who lived at the North Carolina foundation involving the 1950s and 1980s could be eligible to file a claim—and for the reason that Congress has presently authorized a payout of far more than $6 billion.

That promises overall would quickly eclipse the former substantial-water mark, set by the approximately 300,000 lawsuits introduced in a circumstance against a 3M subsidiary that produced allegedly faulty earplugs for US soldiers.

Each the 3M and Camp Lejeune instances have been turbocharged by a mass tort advertising market that has advanced in new years from the door-knocking of Erin Brockovich forms into a large-tech, targeted procedure on social media and Tv set.

A person popular participant in the industry referred to the marketplace final slide as the “wild west,” but claimed it was maturing at outstanding speed. Its ability to flood the airwaves has been financed by significant traders who look at mass torts as an significantly lucrative asset class, and are likely to bet even more revenue on related circumstances to diversify their holdings.

Hedge money or litigation finance firms give money to order the ad time—with hopes of major returns centered on how effectively the lawsuits carry out. Lawyers take the circumstances on a contingency price, generally a percentage of any settlement or damages award.

“Camp Lejeune was the hook to get these institutional asset professionals into the asset course,” Luke Darkow, a principal at Chicago-based mostly Victory Park Money Advisors, which has produced these kinds of investments, stated in an job interview. “But I think the revenue is right here to stay.”

Momentum Building

The push to compensate Camp Lejeune victims dates to the 1980s, when drinking water systems at the Marine foundation and education floor were discovered to consist of most cancers-producing chemicals—the result of fuels and other contaminants seeping into the water provides.

Lawsuits in excess of the contamination languished for yrs.

In 2016, a federal decide dismissed a consolidated scenario introduced towards the government by 900 former foundation residents, ruling that their suits were being filed much too late below North Carolina law.

But in August, Congress handed the Promise to Address In depth Toxics Act. The legislation allows veterans search for damages if they were being exposed for at the very least 30 times to the toxic drinking water amongst August 1953 and December 1987.

About 15,000 Camp Lejeune disability claims had been submitted with the Department of Navy as of late December, according to a office spokesperson. The Navy has 6 months to adjudicate each individual claim candidates unhappy with the final decision can then sue.

Specified the timing of the law’s passage, a new tide of lawsuits is expected to strike in March. The window to file statements closes in August 2024.

Advertising is the main approach to find claimants, and it’s handled by an ecosystem of lawyer-unique ad organizations identified as lead turbines. They come across shoppers, and some sign them up through their very own call facilities. Some even retrieve customer professional medical records.

Then they offer the cases to law corporations at a value that adjusts based on how several attorneys are promotion for the scenario and what’s likely on in the litigation.

“As the mass tort progresses, a lot more and additional attorneys get associated, there is much more marketing, and the expense goes way up,” mentioned Ed Lott, who runs direct generator Zero Danger Instances, which he said served recognize about 5,000 3M clientele.

Right before the law was passed, Camp Lejeune claims could be procured by regulation firms for about $1,000, Darkow claimed. That has considering that enhanced to $5,000 or additional, driven up by the higher desire and growing fees of advertisements.

Almost $112 million was expended on Television adverts looking for Camp Lejeune victims in 2022. That equals a lot more than double the shelling out on the subsequent closest mass tort, asbestos, in accordance to X Ante, which tracks ad investing using Kantar CMAG info.

More substantial Cases Additional Prevalent

Some plaintiffs’ attorneys say mass tort circumstances are developing larger sized because of superior ways to focus on possible victims by way of social media.

“Five or seven decades in the past, a tort like 3M would have been 50,000 claimants,” Adam Gerchen, CEO of Keller Postman LLC, a mass tort legislation firm battling 3M and symbolizing more than a thousand Camp Lejeune purchasers, reported at a New York litigation finance conference in September. “Now it is [more than] 275,000 claimants because of innovations close to electronic promoting and origination, the engineering to take up that variety of quantity, and cash.”

In the Camp Lejeune situation, thousands of previous citizens of the base and their families have congregated on Fb groups, which built targeting them rather quick. By way of early December, far more than $32 million had been spent on social media and world-wide-web ads in search of Camp Lejeune claimants, according to Pathmatics, an promotion exploration agency.

The greatest spender on social media and internet-based adverts was Lacuna Ventures, a subsidiary of publicly traded Troika Media Group, a New Jersey-based mostly marketing agency. It put in just about $17 million directing potential consumers to a web site, camplejeunevictims.com. That was much more than seven moments the future most significant spender, in accordance to knowledge from Pathmatics.

Troika Media Team did not reply to requests for remark for this tale.

Steve Nober, who operates just one of the country’s greatest lawful marketing agencies, mentioned the rush of advertisers and legislation companies to get in on the case was unlike everything he had ever found.

“It’s a land seize,” Nober explained to attendees at the convention final drop.

In an interview with Bloomberg Law, Nober explained he started his California-based organization, Shopper Attorney Internet marketing Team, 12 years ago because legal entrepreneurs weren’t monitoring what portion of their spending was prosperous. He’s considering that expanded his organization to involve a contact heart for customer consumption, a public relations purpose, and a health-related documents division.

“Nobody in the authorized place was undertaking direct-response advertising and marketing, measuring response and getting clever about permitting money only run the place you’re viewing reaction,” he mentioned. “I contact it Moneyball for legal promoting.”

The firm now has 400 staff, and tends to make Television set ads and 30-moment infomercials for legal professionals out of a Los Angeles studio. But spectacular returns are drawing additional and a lot more severe buyers to the promoting area, he explained.

“I refer to the mass tort industry as the wild, wild West,” Nober claimed at the meeting. “It’s maturing really promptly. It appears to be like it’s gradual movement, but we’re likely to glance again at this period of time and see how quickly the finance planet caught up to what’s happening in mass torts.”

He also predicted additional innovations to appear.

Camp Lejeune promises advertisements have flooded Television set, radio, and social media.

One could be fueled by a new organization product produced in Arizona right after that state’s Supreme Court adjusted laws to allow for exterior investors to very own parts of regulation corporations. Beforehand, like in nearly each and every other point out, only lawyers have been permitted to very own regulation corporations and get portions of authorized charges.

That experienced limited marketing firms’ returns to an upfront payment in exchange for locating mass tort clientele. Now, advertising and marketing corporations and litigation funders established in Arizona will be ready to share in the real verdicts or settlements from situations.

Those groups have been fascinated in the new composition to gain increased returns, reported Lynda Shely, an ethics law firm in Arizona who’s served companies navigate the new constructions. “We have had a whole lot of desire in this from the two marketing firms as nicely as litigation funders,” she stated.

Two executives from Nober’s business submitted paperwork last yr to variety a new legislation firm small business there that would be co-owned by Richard Meadow, who runs the mass torts observe at New York-based Lanier Legislation Firm, just one of the most notable mass torts regulation companies in the place.

Neither Nober nor Meadow returned messages trying to find comment on the new business.

Elizabeth Chamblee Burch, a College of Ga School of Legislation professor who’s researching a book on the lead-generation organization, questioned no matter if allowing legislation firms to instantly partner with economical buyers could guide to conflicts.

Lawyers in that arrangement would have a fiduciary responsibility each to their shoppers and their traders, and Burch explained it’s unclear how to solve disputes involving individuals two. An investor, for occasion, may well want to settle a circumstance but a plaintiff could want to consider it to trial.

“It muddies the h2o for the lawyer’s incentives too considerably,” Burch stated. “I appreciate to see authorized innovation. I want plaintiffs to have entry to justice and I want them to know they have a claim. It’s all essential, but I don’t know that this is heading to be a internet good, and I have really serious doubts that it is.”

Marketing Worries

Mass tort entrepreneurs have been dogged in the previous by criticisms, which include for selling the exact same shopper to multiple regulation firms. In one infamous scenario, two folks employed to procure purchasers for a lawsuit trying to get payment from BP’s 2010 Gulf Coastline oil spill have been sentenced to prison following distributing 40,000 fake names.

There are continue to many unique mass tort legal professionals who operate in traditional ways—finding clients, verifying their statements, and working their scenarios to a settlement or trial all in-house.

Morris Bart has been marketing on Tv set in the deep South since the 1980s. His 100-attorney agency spends all over $25 million on marketing a calendar year, only jogging ads in which his offices are based—Louisiana, Mississippi, and Alabama. Bart’s 3M earplug Tv set campaign ran in between January and March of 2019 and garnered around 1,500 clients. A group of 20 of the firm’s lawyers are liable for managing the instances to their stop, he stated.

“We like to do it the old college way,” Bart reported in an job interview, “so that clientele can occur to our actual physical offices and see us.”

Nevertheless, it can be a high-possibility enterprise. The regular mass tort scenario lasts more than five yrs, Bart stated, and even then it’s a coin toss if plaintiffs will gain their situation or have to accept a settlement that will not even recoup expense expenditures.

There is also substantially to be acquired. The payout that Congress authorized has no caps on service fees that legal professionals can demand for their work in Camp Lejeune cases—despite a yr-end energy by some lawmakers to impose them.

By now, there have been reviews of some attorneys demanding 40 p.c or much more of any payout. And the disputes are possible to be a lot easier to take care of because the law restricts the federal government from mounting a traditional protection in courtroom.

The US Chamber of Commerce, a longstanding critic of the mass tort bar, states the absence of caps offers attorneys a fiscal incentive to file as many Camp Lejeune promises as achievable.

The large-small business lobbying group is also warning veterans that filing a lawsuit could go away them even worse-off financially. Which is due to the fact a provision in the regulation demands veterans who received payment for their health-related complications from other govt healthcare packages to repay it if they acquire a Camp Lejeune settlement.

Lott, a longtime guide generator, said the critical to being profitable in his marketplace is simple: Be genuine in your advertising and marketing. For Camp Lejeune victims, the takeaway is to check out all the expensive advertisements with a grain of salt.

“Don’t lie to legal professionals, and do not lie to the purchaser, the probable shopper. That goes on all the time,” Lott reported. “They’ll say you can make $10 million on your case, that type of promoting, and which is just not genuine.”

—With reporting by Tiana Headley

Youngstown hires deputy finance director | News, Sports, Jobs

Youngstown hires deputy finance director | News, Sports, Jobs
&#13
&#13

YOUNGSTOWN — The city of Youngstown stayed in-dwelling with the employing of its deputy finance director, picking Richard Harvey, who has expended the past 22 decades functioning for its group development agency.

“He arrives with a broad total of awareness and experience and has a terrific comprehending of how we work right here,” Finance Director Kyle Miasek claimed.

Also crucial, Miasek said, is Harvey has applied the identical fiscal ledger process at the neighborhood improvement company that the finance division makes use of, and is incredibly familiar with town functions.

Harvey was amid seven candidates the city’s civil assistance commission deemed capable based on his operate knowledge and education and learning.

Harvey was ranked initial by the fee with Thaddeus “Ted” Szmaj, the h2o department’s controller and business office supervisor, finishing next.

Harvey and Szmaj ended up the only candidates interviewed for the career, Miasek reported, and Szmaj decided to eliminate himself from the process simply because “it would build an practical experience gap in the water office.”

Miasek included: “We felt based on interior candidates we did not have to have to go out further more and meet up with with the other candidates.”

Harvey started doing the job for the city’s CDA in November 2000 as a economic assistant. Soon after earning a bachelor’s diploma in business administration from Youngstown State College, he was promoted to CDA’s fiscal officer, a task that was previously identified as comptroller.

“The new career is a broader reach for me,” Harvey mentioned. “The CDA is in its very own pond, and now I’ll be functioning with all of the other departments. I’ll get to spread my wings and be extra associated. The tasks are broad, but the focus will be on central getting when it’s put with each other.”

Harvey said he’ll also find out what Miasek does mainly because “you usually will need a person to be in a position to step in in scenario of an unexpected emergency or if some thing else happens.”

Harvey’s once-a-year wage greater from $55,034 as CDA fiscal officer to $88,534 as deputy finance director.

The work formally has been vacant because March 2021. But the situation could effortlessly be regarded unfilled due to the fact January 2018 when Miasek was promoted to interim finance director from deputy director. Miasek served on an interim basis for more than three several years without a deputy.

In addition to managing central obtaining, the job description called for the deputy finance director to aid with making ready and monitoring the town price range, to examine and evaluate economical reviews, to keep an eye on and support with grants, to generate and keep special projects and to provide as a liaison among the city and the Regional Money Tax Agency, which collects the city’s 2.75 p.c earnings tax.

Harvey “is likely to master metropolis budgeting, labor negotiations and support me with my responsibilities,” Miasek stated. “He’s heading to be a large team player.”

The city essential qualified candidates for the task to have at minimum a bachelor’s diploma in accounting, financing or connected area and 5 decades of get the job done knowledge in community finance, accounting or connected industry, if possible with authorities accounting and budgeting knowledge. Licensed public accountants or individuals with a master’s diploma in finance, accounting or linked field had been “desired,” according to the work description.

Among the the five other candidates who used for the work were being two former Canfield officials who resigned rather than confront self-discipline for violating that city’s code of carry out.

They were the only two applicants with master’s levels. None of the applicants were being CPAs.

Wade Calhoun, the previous Canfield city manager, resigned his job that paid out about $119,000 on a yearly basis on Aug. 27, but was on paid out administrative leave till Oct. 31.

Kristen Ansevin, Canfield’s ex-assistant deputy director of finance, resigned her posture Sept. 7. The work paid $74,200 each year.

Canfield officials have refused to examine details connected to the two resignations except to say they had been administrative and not prison.

&#13 &#13
&#13

&#13
&#13

Present-day breaking news and extra in your inbox

&#13
&#13

&#13
&#13
&#13
&#13
&#13
&#13
&#13

British finance minister sticks to tax-hiking plans, pledges post-Brexit reforms

British finance minister sticks to tax-hiking plans, pledges post-Brexit reforms

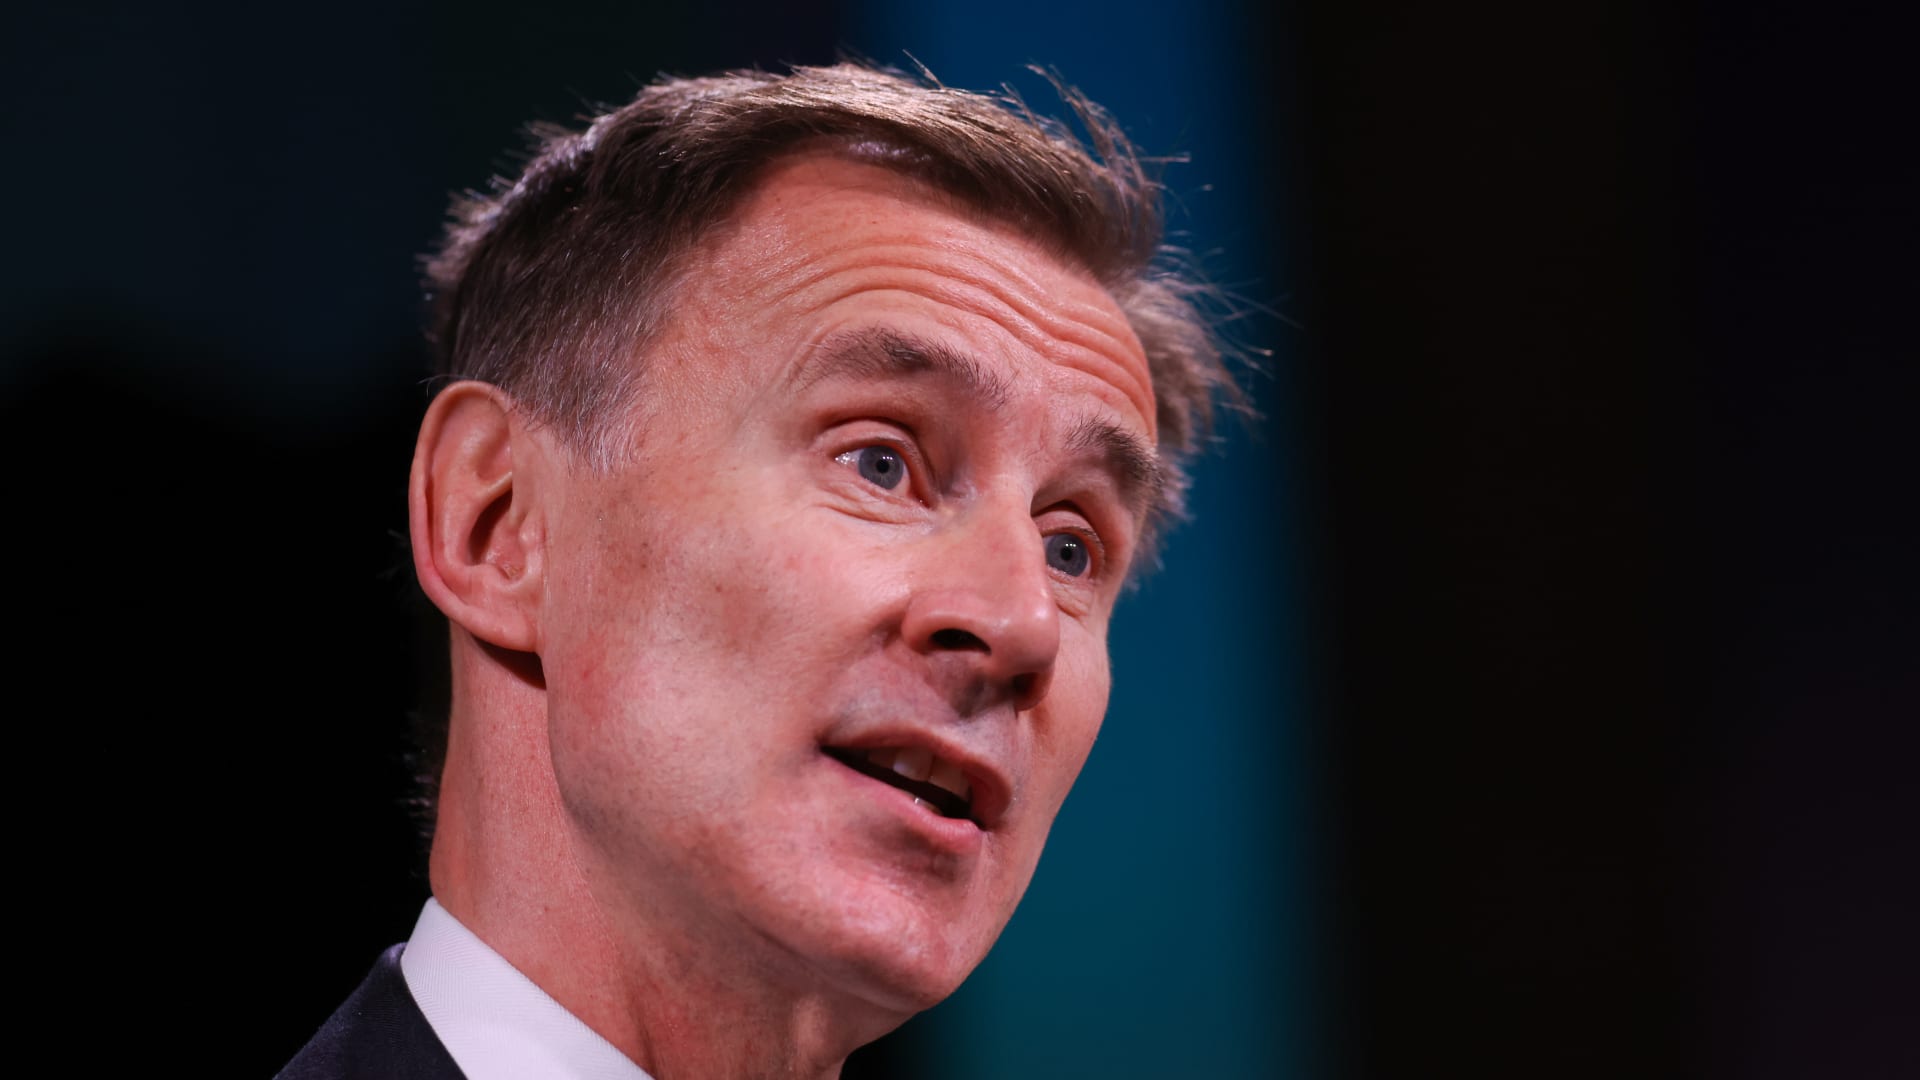
Jeremy Hunt gave a speech Friday to lay out designs for economic development in the U.K.

Bloomberg / Contributor / Getty Illustrations or photos

LONDON — British Finance Minister Jeremy Hunt on Friday signaled he is pushing ahead with tax hikes, whilst stressing the need to have to build Brexit into a “catalyst” for U.K. progress.

“The most effective tax cut correct now is a reduce in inflation,” Hunt reported in a speech tackled to tech giants, which include Amazon, Google and Meta, as he appears to be like to dispel economic “gloom” in the U.K.

Optimism in the U.K. economic system has been in “limited offer” in modern months, Hunt reported.

Hunt informed businesses that they were crucial for the U.K. outlook, but additional that “Britain is critical for your long term far too” and requested for their assistance to make the place “the world’s next Silicon Valley.”

Graph to show how pound sterling moved as Jeremy Hunt spoke.

The Finance Minister pressured the importance of making the U.K. a spot where by organizations want to do business enterprise.

He underscored that Britain requirements to have “very little much less than the most competitive tax regime of any big place,” despite restoring the planned rise in corporation tax from 19{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} immediately after it was scrapped by previous Finance Minister Kwasi Kwarteng.

Hunt’s latest remarks ended up extra about improving the image of Britain’s economic situation than about giving new procedures, in accordance to Susannah Streeter, senior expense and markets analyst at Hargreaves Lansdown.

”Jeremy Hunt shrugged off his firefighter graphic for that of a development employee, identified to enable rebuild Britain’s economy. But there is no fast dry concrete offered to provide an immediate solution to the stagnation the British isles is languishing less than,” Streeter wrote in an analyst notice.

Depth is “sorely lacking,” she additional, indicating “the architects of this plan obviously uncertain how it will be compensated for.”

The British pound was down .25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} towards the greenback, hitting $1.237 adhering to the speech. It recovered some of its losses from when Hunt began talking, but pulled absent from the six-7 days significant struck on Thursday. 

Hunt’s speech comes as the U.K. inflation rate most just lately achieved 10.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in December, perfectly earlier mentioned the Bank of England’s concentrate on of 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. The financial institution subsequent meets to choose monetary plan on Feb. 2.

U.S. Inflation Reduction Act problems

Jeremy Hunt reported the U.K. govt has “some fears” about the U.S. Inflation Reduction Act in a Q&A session that adopted his speech Friday.

The controversial Inflation Reduction Act is a historic local climate and tax deal that would channel billions of pounds into programs built to tackle climate adjust and speed up the U.S. transition to net-zero carbon emissions.

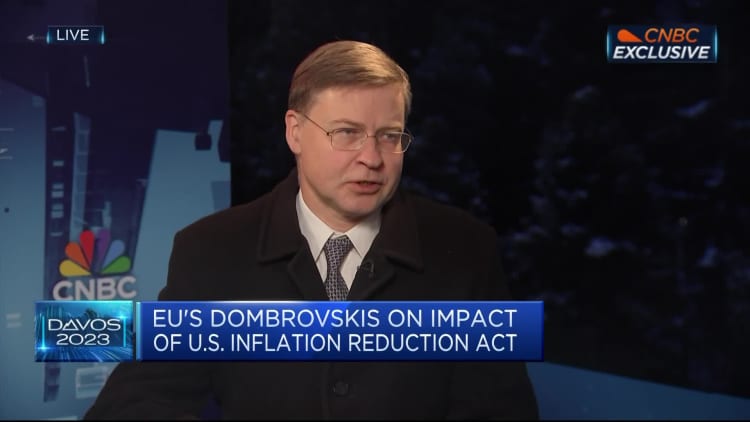
“We imagine in free of charge trade, and we believe that if we are likely to get to web-zero, which is very important, we will be far more efficient if we exploit the aggressive edge that we have, that the United States has, that Asian nations, that EU international locations have,” Hunt stated, alluding to problems expressed on Jan. 19 by European commissioner for trade, Valdis Dombrovskis, that the act’s measures had been “discriminating from EU businesses.”

“Are we nervous about the very long time period upcoming of our clear electricity industries? Completely not,” Hunt additional.

EU remains concerned about U.S. Inflation Reduction Act, trade commissioner says

Hunt’s comments echo those of his German counterpart Christian Lindner, who advised CNBC that he is “worried about the outcomes owing to the Inflation Reduction Act” in November.

“Our typical tactic must be that benefit partners need to continue to be favored trade companions,” he explained.

Polygon’s MATIC Value Rises as Covo Finance Joins Its Ecosystem

Polygon’s MATIC Value Rises as Covo Finance Joins Its Ecosystem

ATLANTA, Jan. 27, 2023 /PRNewswire/ — Polygon’s Matic rate has recently seasoned a substantial rise in value. 1 possible purpose for the surge in Polygon’s selling price is the expanding curiosity in decentralized finance (DeFi) assignments. Polygon is quickly getting a go-to destination for DeFi projects searching to build on a quickly and productive blockchain network. The network’s low transaction costs and substantial throughput make it an ideal selection for DeFi tasks, and quite a few tasks are migrating to Polygon from other blockchain networks.

Covo Finance Debuts its Decentralized Perpetual Trade on Polygon

The current start of Covo Finance on the Polygon network is continually finding MATIC local community consideration. Covo Finance is a decentralized location and perpetual swap exchange that allows users to trade Bitcoin, Ethereum, and other well-liked cryptocurrencies straight from their crypto wallets. The platform provides reduced-price swap trades and leveraged trading of up to 50x, creating it a common preference for traders wanting for an option to centralized exchanges.

Covo Finance features a special investing working experience for end users, as it is 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} decentralized. It permits people to trade Bitcoin (BTC), Ethereum (ETH), and other preferred cryptocurrencies specifically from their crypto wallets with no needing to hold their property in the custody of a centralized trade. The included protection owing to decentralization is a key attract for traders and traders searching for safer choices to centralized exchanges.

1 of the important attracts of Covo Finance is the liquidity benefits software. Customers who give liquidity to the system will get a 70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} reward from all leverage buying and selling and investing expenses. Liquidity is added in a multi-asset pool referred to as COVOLP, which contains 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} stablecoins and 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of other currencies (such as Bitcoin, Ether, Matic, and Chainlink). This pool acts as a counterparty to traders on the Covo system, and income for trades for leverage is sourced from the liquidity pool.

Covo Finance also provides low-payment swap trades and leveraged trading of up to 50x, permitting for even even larger investment returns. In addition, the system has a utility and governance token called COVO, which rewards buyers with different incentives. 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the created protocol charges will be accessible as benefits in Matic, and stakers can also earn esCOVO tokens, which can be staked or vested and transformed to COVO over 365 times.

Polygon Matic DeFi Ecosystem on The Rise in 2023

The start of Covo Finance on the Polygon blockchain is a important milestone for the DeFi house. It demonstrates the probable of decentralized finance and presents a very simple-to-use platform that places consumer income safety at the forefront. Covo Finance presents an excellent prospect for buyers and traders who want to devote and trade cryptocurrencies with no fearing their cash getting hacked or compromised. With the launch of Covo Finance, Polygon (MATIC) is set to turn out to be a hub for decentralized finance assignments, and the selling price of MATIC is expected to continue to increase as additional buyers and traders flock to the system.

Find out Far more or Trade crypto futures with 50X Leverage.

Media Make contact with:

Company: Covo Finance
Electronic mail: [email protected]
Web site: https://covo.finance

Symbol: https://mma.prnewswire.com/media/1991102/Covo_Finance_Emblem.jpg

Resource Covo Finance

Layoffs, funding delays reported at Solera Auto Finance

Layoffs, funding delays reported at Solera Auto Finance

Solera introduced Solera Automobile Finance at the NADA Demonstrate in March 2022 and predicted to get to 20 states by the conclude of the year. By August, it had achieved 39 states and was doing work with far more than 2,000 dealerships.

Solera Car Finance experienced been intense in trying to get business enterprise, the next Solera Auto Finance gross sales supervisor reported. The business had achieved a charge of $25 million a thirty day period in loans, “and that is when they hit the brakes on all the things,” he mentioned.

“Solera Automobile Finance’s entry into the automotive lending room was a good results and nicely obtained by sellers,” Casas claimed in the assertion. On the other hand, she reported the existing credit rating natural environment and client outlook “necessitates we take a more prudent strategy for the time staying.”

The first supervisor believed Solera Car Finance started to slide at the rear of in funding discounts in the tumble.

A normal supervisor at a southern U.S. unbiased dealership, who requested not to be discovered presented his Solera business partnership, explained how the initial financial loan he despatched to Solera Car Finance flopped close to that time.

He explained Solera had agreed in Oct to get a mortgage for a BMW 4 Sequence. The offer was “100 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} superior to go” and contracted, he said — but then Solera Vehicle Finance shortly thereafter declared it wouldn’t fund the deal.

“Any deal that has been returned is in accordance with the applicable vendor settlement involving Solera Auto Finance and the particular person seller,” Casas explained.

The 1st Solera Automobile Finance sales supervisor said the enterprise sent sellers their funding for October’s bargains in November. It planned to protect the November financial loans in December, but “they never received all over to that,” he said. (One particular supplier shopper who “complained sufficient” was reimbursed for his November business enterprise, but that was the exception, the manager stated.)

“Solera Auto Finance proceeds to fund deals,” Casas wrote in response to allegations of drop funding delays.

The 2nd profits supervisor explained reps had been barred from asking internally when their vehicle suppliers would acquire the revenue owed them.

“Product sales representatives normally experienced direct make contact with with and access to Underwriters and Funding employees,” Casas responded.

In spite of its funding delays, Solera Auto Finance nonetheless wanted to collect additional financial loans from dealerships and their clients, according to the 2nd revenue manager. “We had been even now instructed to drive for contracts,” he stated.

Casas claimed the financial institution “adapted its underwriting benchmarks to the latest macroeconomic situations and the business enterprise will keep on to evolve as adjustments come about in the automotive lending place.”

The company instructed reps to tell sellers funding would occur, the second manager claimed. Having said that, it would hold out 30 to 60 days prior to creating the seller total, he claimed.

“It is gross mismanagement,” he claimed.