10 User-Friendly Personal Finance Tech Tools

10 User-Friendly Personal Finance Tech Tools

Private finance is a intricate element of lifestyle. For example, you can not just get your money, subtract bills, and see what is still left. Confident, which is where by it commences. But plenty of further, nuanced things also component into a balanced budget and productive prosperity generation method. Therefore, it can help immeasurably to insert at the very least a number of personalized finance tech applications to your toolbox.

As inflation carries on to bite down on budgets and a economic downturn looms, it’s vital to method your own funds with a extensive mentality. The finest way to do that is by equipping yourself with the suitable applications.

With that in mind, below are some tips for the finest personal finance tech equipment that deliver person-pleasant and efficient guidance for performance-minded people.

1. Veteran.com keeps you up to date.

Usually the best individual finance solutions modify to your particular wants. If you commit far too significantly, a expending tracker is useful. If you are a saver, a retirement app is a fantastic in shape.

In some cases the applicability of a particular finance instrument can be even extra precise — as is the scenario with Veteran.com. The armed forces-focused web-site offers a broad array of methods for both latest navy members and veterans.

Alongside with blogs and assets on education, work opportunities, and housing, the well-liked web page has an overall portion dedicated to cash and finance. This features navy pay charts, an up to date army shell out calculator, and even a VA Disability calculator.

As veterans and lively users of the armed forces navigate their particular funds, the website can deliver a regular stream of handy data.

2. Acorns aids with personal savings.

Running to help save income is one of the most popular personalized struggles at any time. Trying to do so when inflation costs are high can really feel unattainable. The temptation to shell out dollars on requirements and desires alike can be difficult to get over. Empty financial institution accounts and crowded credit card statements can leave you feeling pressured.

Enter Acorns. The monetary technological know-how company enables buyers to invest seamlessly in their future. Its on the internet application and banking tools are user-friendly, holding things uncomplicated and uncomplicated at every single move. At the very same time, they are backed by authorities from significant investment firms like BlackRock and Vanguard.

The revolutionary financial institution delivers various equipment to enable folks dominate their funds and build towards a improved long run. One particular of these applications is the company’s computerized price savings and investment decision option. This rounds up every single transaction that usually takes spot, placing the further dollars into effectively-balanced, professional-developed portfolios. As a outcome, the final result is superior monetary awareness and a sluggish-but-steady trickle into your personal savings.

3. Mint provides you a economical snapshot.

Some persons require targeted particular finance tech applications. Other folks will need extensive alternatives. If you find that you’re in the latter category and an eclectic fintech stack isn’t supporting, you could want to test the Mint app.

Mint is an software with a higher popularity. It can backlink to multiple checking accounts, integrating your assets into a solitary dashboard. This offers you a unified economic snapshot that can help you see constructive and unfavorable tendencies before they get out of hand.

The strong software program alternative can also categorize transactions, forecast investing patterns, and create price range suggestions. This offers a continual stream of insights that can foster beneficial money practices.

4. Particular Capital is thorough finance defined.

Another software identical to Mint is Own Cash. The prosperity management application presents a in depth and insightful money overview.

At the time again, this piece of fiscally-minded computer software has the electric power to carry with each other a number of money information sets. You can url up distinct own examining and cost savings accounts to create an amalgamated snapshot of your current finances.

Alongside with aiding with budgeting and hard cash stream, Personalized Funds also presents a price savings planner and net really worth choices. The former helps develop and observe price savings targets. The latter gives you an correct watch of your net truly worth at any minute.

The application also has in depth retirement personal savings alternatives, this sort of as a retirement planner and a price analyzer. These assets can aid keep track of any peaceful or hidden charges to your very long-expression financial savings. You can even evaluate if you are preserving more than enough for foreseeable future academic fees and can periodically carry out an investment checkup.

5. Position Revenue provides you comparables.

Evaluating your own accomplishment to some others is a unsafe exercise. You really don’t want to stoke avoidable levels of discontentment or jealousy. And but, there are instances when observing how you stack up in opposition to others can present valuable information and facts.

Status Cash is the great resolution for people moments. You can input your different money owed and property into the app. From there, it analyzes them and then supplies comparables to other people in equivalent instances.

Wholesome doses of peer-to-peer comparisons can be a wonderful way to remain motivated. Consequently, it can also offer point of view and support workaholics and the hyper-bold let on their own some perfectly-acquired relaxation.

6. GoodBudget goes back again to budgeting roots.

Funds can come to feel frustrating. When which is the circumstance, occasionally the best alternative is a simple one. Which is where GoodBudget comes into the photograph.

The personalized finance instrument focuses on the strategy of relatable and consumer-helpful funds. In simple fact, it embodies the digital variation of one of the oldest and most grounded varieties of personal finance: the envelope program. That is a form of monetary organization that utilizes envelopes to divide and track cash, generating a organic barrier to overspending in the procedure.

GoodBudget gives you an app-driven envelope system alternative. Customers can divide their revenue into various “envelopes” that assist keep track of how significantly money they have still left in every single group. To be good, the consequence is very similar to most budgeting apps. For individuals who battle with partitions of figures and charts, even though, an obtainable visual like envelopes can make all the variance.

7. Prism will help you keep track of your expenses.

Own budgets are likely to aim on cash flow, bills, and financial savings. It will help calculate what you owe other people and how substantially you want to set apart for a wet day. But it does not actually pay out off your costs. Which is an additional stage that is effortless to forget — in particular if you have a ton of unique expenses to attend to on a regular foundation.

Prism is an application that assists eliminate the worry of the bill-pay cycle. Compared with more detailed options on this checklist, like Mint and Own Money, this is a fintech device devoted to a single exercise, and a person exercise only: spending your charges.

The app connects you with your several creditors. It syncs up accounts and tracks what you owe. These are then introduced in the Prism app, wherever you can see what you owe, when, you owe it, and to whom it must go.

8. Etrade helps manage investments.

If you already have a firm grasp of simple individual finance and you are searching to acquire the upcoming stage, you may want to contemplate Etrade. The financial prosperity management software package facilitates fingers-on buying and selling and expense. This turns an if not challenging activity into a really obtainable type of particular finance.

Etrade doesn’t acquire commissions and has a extensive selection of diverse financial commitment product possibilities. These incorporate the two energetic brokerage accounts as nicely as retirement alternatives. In possibly situation, if you want to remain concerned in your retirement organizing, Etrade presents you fast and quick accessibility at all situations.

9. Vanguard attributes automatic investing tools.

Vanguard is yet another retirement and financial investment-focused private finance alternative. The dependable brand name presents automatic investing instruments and reliable assist.

A vital factor that draws in several buyers to the prosperity management instrument is the truth that it is trader-centered — and that is not just referring to a purchaser support initiative. Vanguard is actively owned by those people who commit in Vanguard cash. As a consequence, this offers them a collective focus on mutual prosperity generation and effective asset management. Add its suite of complete fintech instruments, and it’s an uncomplicated choice for numerous in research of simple-to-use individual finance solutions.

10. Due will get top marks for producing prosperity.

It would be a gross oversight to neglect Because of on this listing. Lots of peg the common economical device as the internet’s amount one particular retirement useful resource. Forbes rated it as a top rated finance weblog with outstanding assets for these hunting to crank out wealth. Entrepreneur Magazine referred to as it one particular of the finest sites on the interweb to glean retirement info.

Due is the fantastic combination of methods and applications for private finance management and prosperity technology functions. The internet site has many finance-focused merchandise, from annuities to lifestyle coverage and past. It also has a wealth of information and facts in the variety of an ever-increasing website and a lengthy record of detailed guides that revolve around dollars and its administration.

Whether it is the need to have for quality fintech applications or a resource to advise your use of people applications, Due is the a person-prevent store for thriving particular finance.

Particular finance is constantly significant. In the course of economic and fiscal crises, it’s notably intelligent to acquire handle about your earnings, fees, and investments.

To sum up, use the checklist above to identify the greatest personalized finance tech tools to fill in your individual money shortcomings. Do you have to have a specific solution for some thing like shelling out bills? Or is a extra detailed application in buy? Think about your problem, make your collection, and then devote in taking your private finances to the following stage.

The submit 10 User-Helpful Own Finance Tech Tools appeared to start with on Owing.

The views and views expressed herein are the sights and viewpoints of the author and do not always mirror those people of Nasdaq, Inc.
What 5 key personal finance issues mean for you

What 5 key personal finance issues mean for you

As Individuals head to the polls, quite a few essential personal finance concerns are weighing on voters’ minds and wallets.

This week, the Federal Reserve enacted its fourth consecutive .75 share position interest level raise to struggle inflation, triggering further stock marketplace losses.

In the meantime, recession fears are growing, with 84{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Individuals worrying how a extended economic downturn may affect their funds, in accordance to a MassMutual report released Thursday.  

Much more from Individual Finance:
What the Fed’s .75 share position curiosity amount hike usually means for you
Democrats warn that Social Safety, Medicare are at stake
What ‘millionaire tax’ plans on the ballot in California and Massachusetts indicate for best earners

“The over-all financial system has been so important, and I feel it truly is influencing the elections,” stated lawyer Marc Gerson, member chair of the tax division at law firm Miller & Chevalier in Washington D.C.

Some difficulties appear on condition ballots, but federal plan depends on which occasion controls Congress. Although Republicans are favored to earn the Household, the Senate hinges on a handful of aggressive races.

Below are five of the most pressing problems this election period — and how Tuesday’s final results may possibly have an effect on your wallet.

1. Democrats cite threats to Social Protection, Medicare

As Election Day strategies, Democrats are telling voters that Social Safety and Medicare could be at hazard if Republicans take manage of Congress.  

“They are coming immediately after your Social Security and Medicare in a big way,” President Joe Biden reported in a speech Tuesday in Hallandale Beach, Florida.

The Inflation Reduction Act enacted Medicare reforms to decrease prescription fees for retirees. Having said that, Republicans could try to halt these changes, Biden reported.

He also pointed to probable pitfalls to Social Security, based mostly on plans from sure Republicans, including Sens. Rick Scott of Florida and Ron Johnson of Wisconsin. But each lawmakers have denied intentions to damage the program.

Scott has named for reauthorizing Social Safety and Medicare every single 5 several years in Congress, when Johnson implies revisiting the systems annually.   

2. Republicans force for even more tax cuts

3. Least wage hikes on the horizon

4. A achievable huge gain for unions

Coming out of the pandemic, union support is at a document substantial. Additional than 70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Us citizens approve of labor unions, a Gallup poll recently found.

The final result of a ballot evaluate throughout the midterm election could speed up that expansion: Voters in Illinois will make a decision whether or not to supply personnel with the elementary right to organize and deal collectively.

If the provision will become regulation, “it will reveal solid well known guidance for labor legal rights in a big, essential condition,” said Daniel Galvin, an associate professor at Northwestern University whose analysis spots involve workers’ rights and labor politics. “It would also sign to the rest of the country that the appropriate to cut price collectively ought to be observed as a essential correct worthy of constitutional defense.”

5. ‘Millionaire tax’ in California and Massachusetts

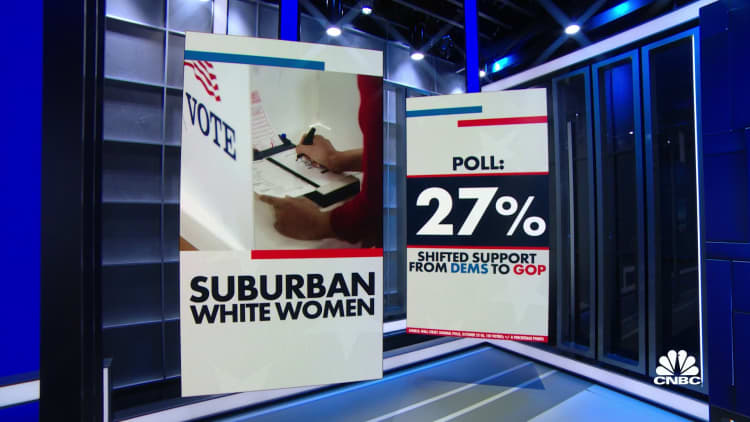
Polls show Republicans poised to win in midterms

3 Things Personal Finance ‘Experts’ Get Wrong

3 Things Personal Finance ‘Experts’ Get Wrong
Young woman listening to podcast on her headphones while drinking coffee.

Graphic supply: Getty Visuals

We protect a lot of guidance from personal finance gurus right here at The Ascent. In numerous conditions, these people are plugged into the shelling out and personal savings practices of Us citizens, and often, they themselves have been way down in the depths of personal debt and dire money instances, so they have wisdom to impart. In addition, assistance from finest-offering authors and radio exhibit hosts tends to be a great deal additional accessible than facts from teachers, like economists. That said… are personalized finance gurus generally supplying you the appropriate facts?

Recently, the podcast Freakonomics Radio (a individual most loved of yours actually) questioned the problem, “Are Particular Finance Gurus Providing You Negative Suggestions?” In this episode, the Freakonomics crew spoke to Yale College economist James Choi, who performed a study of suggestions presented in 50 guides by particular finance authorities vs . knowledge espoused by economists, and mentioned the variations when it arrived to saving income, taking care of personal debt, receiving a house loan, and additional. Let’s get a glance at some of the loudest opinions in the world of own finance and see how they stack up to tips from economists.

Explore: This credit card has a rare $300 welcome bonus

Far more: These {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR credit score cards manufactured our very best-of record

Warn: optimum funds back again card we’ve viewed now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR for 15 months

1. Your cost savings fee should really be continual!

It really is a widespread refrain between individual finance professionals: aim to conserve a selected proportion of your profits, no make any difference what age you are, what work you have, or what phase of lifetime you are in. According to Choi’s conclusions from studying economic theory, it really is off base when you look at issues like cash flow vs . paying above one’s life time. When you are youthful, you very likely will not likely make as substantially cash as you will in middle age, and so it could be challenging, or downright extremely hard to regulate your costs and fees even though also conserving that specified share of your cash flow. In the meantime, you could possibly also have some rather massive costs as a more youthful human being. Perhaps you want to get married and have a large wedding ceremony in your 20s or 30s. It’s possible you want to get a dwelling, which arrives with a higher upfront value.

As you get more mature, you will now have done these massive highly-priced things, and you may also possible be building a lot more money at operate. This frees up much more of your earnings to preserve. That explained, if you get in the routine of conserving funds at an early age, it will undoubtedly be much easier to preserve at it as you get older (and make extra dollars). Furthermore, you can choose advantage of the wonder that is compound desire.

2. Do not get an adjustable-rate home finance loan!

Quite a few own finance gurus recommend towards adjustable-price home loans (ARMs). From an psychological standpoint, this will make feeling. Right after all, when you get a fixed-level property finance loan, you will never have to worry about your mortgage loan payment transforming over the lifetime of the mortgage. And if inflation is up and soaring, like it is correct now, this can be a very good matter. But ARMs normally appear with a lower desire level to start out with, and you are going to keep that for a period of time. For example, if you get a 5/1 ARM, you are going to have that minimal beginning desire charge for the very first five a long time right before it starts switching each yr. And what if inflation is reasonable above the system of your loan? You could be getting rid of revenue with a preset-charge home loan, except if you happen to be currently maxing out your spending budget to purchase a property (which isn’t the best notion).

So think about finding an ARM, and if you don’t want to choose the probability of your payment rising following that first interval of set desire, refinance to a fixed-rate loan in advance of it really is above. Right now, finding into a house by working with an ARM should really preserve you money, as the normal amount for a mounted-level property finance loan is 7.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} as of this composing, although the regular amount for a 5/1 ARM is 5.96{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

3. Snowball your financial debt payoff!

For every Choi’s analysis, about fifty percent of the particular finance writers whose guides he read espoused the snowball strategy for having to pay off credit history playing cards and other significant-fascination debt, when half advocated the additional mathematically effective approach, the personal debt avalanche. Economists like the debt avalanche system way too, because you will expend a lot less cash shelling out off your financial debt by focusing on the money owed that have a better curiosity fee first.

However, having to pay off the smallest total initial and performing your way up presents you some early wins, which can compel you to continue to keep heading, and preserve paying out matters off. I a short while ago received out of credit card debt using the snowball technique, and it was in truth incredibly mentally and emotionally enjoyable, inspite of probable costing me a lot more revenue over-all due to me not prioritizing increased-desire financial debt payoff first.

Does any of this matter?

So, figuring out that some of the most cherished views of individual finance experts are off-foundation from an economic standpoint, does any of it genuinely matter? Most likely not. And Choi acknowledges this, based on the availability of assistance from particular finance gurus vs . from tutorial economists and the simple fact that a lot of folks locate it easier to abide by a straightforward directive like, “help save 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your money no issue what,” or “keep away from adjustable-price mortgages.”

In the long run, we have all received to handle our personal cash, and test to do our ideal to lower through the sounds and come across the ways that work for us and that we will stick with. The odds are very good that you are going to come across good results with some technique promoted by a preferred individual finance expert, by way of their web page, guide, or podcast. And that is completely ok.

Notify: greatest money again card we have noticed now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2024

If you might be employing the incorrect credit or debit card, it could be costing you severe income. Our pro enjoys this best choose, which functions a {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until finally 2024, an crazy cash back again charge of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all somehow for no yearly charge.

In actuality, this card is so great that our pro even utilizes it personally. Click on below to study our total evaluate for free and implement in just 2 minutes.

Browse our no cost evaluation

We’re firm believers in the Golden Rule, which is why editorial viewpoints are ours on your own and have not been formerly reviewed, authorised, or endorsed by included advertisers.
The Ascent does not go over all delivers on the industry. Editorial content material from The Ascent is independent from The Motley Idiot editorial information and is established by a distinctive analyst team.The Motley Fool has positions in and suggests Avalanche. The Motley Fool has a disclosure coverage.

The sights and opinions expressed herein are the sights and views of the writer and do not necessarily mirror these of Nasdaq, Inc.

What is generational wealth and how can you create it? [Column]

What is generational wealth and how can you create it? [Column]

In a current survey from Ameriprise Monetary, more than 3 out of 4 People (78{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) mentioned they have taken at least a single action to establish generational prosperity (Ameriprise Revenue and Family members examine: Cash & Family members: A new study on generational wealth). But what particularly constitutes “generational wealth” — and how can you achieve it?

The most typical answer (44{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), in accordance to study respondents, is prosperity in excess of $500,000 that is passed down to beloved ones. Relying on your economical predicament, 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} a million bucks might or may possibly not audio like a good deal of cash. But one detail is obvious: no issue how significantly you intend to 1 day bestow on your spouse and children and friends, it aids to have a prepare.

If you, like the majority of study respondents (68{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), say passing generational prosperity onto your heirs is significant to you, below are some items to retain in mind: Procedures for increasing generational prosperity

Be a strategic saver

Fairly than leaving wealth accumulation to chance, strategic savers set ambitions and perform to actively increase their personal savings. They make common contributions to price savings accounts. Active conserving curbs expending and influences earning behavior. They may well defer purchases, operate lengthier, pursue greater-shelling out work, or make other decisions (and sacrifices) to make certain their price savings ambitions are met.

Commit in stocks

Buyers who are really serious about cash flow expansion utilize the stock current market. Most industry experts advise a obtain-and-keep solution to optimize earnings about time. A threat-adjusted, diversified, and well balanced portfolio can aid investors fulfill their investment decision aims.

Invest in authentic estate

Historically, house values have amplified about time, producing homeownership a major process of wealth accumulation. Investors may possibly also diversify their portfolios with Genuine Estate Expenditure Trusts (REITS) and other purchases of house.

Go alongside money wisdom

Money values are yet another essential asset to move alongside to heirs. Quite a few people uncover it effective to explore their financial conclusions with their adult small children and stepchildren. Clear interaction can assistance establish reasonable expectations and stay away from surprises and conflicts when it comes time to go together your property.

Think about ‘Giving Whilst Living’

Programs for sharing generational prosperity can include things like giving now instead than waiting around to hand down assets following demise. Beneficiaries are frequently grownup kids but can also consist of charitable companies. Offering in the current can satisfy the wish to enable now and allow you to see the impact of your generosity. That stated, it shouldn’t arrive at the possibility of your fiscal safety, so make certain you have the usually means necessary right before crafting a check to your favourite cause.

Developing generational prosperity is a lifelong procedure. Together the way, an knowledgeable money advisor can support you establish a economical approach and established achievable goals aligned to your estate setting up wants. Your advisor can work with you and your estate planning attorney to guarantee your will facilitates your needs for sharing generational wealth.

Bronwyn L. Martin is a Money Advisor and Chartered Financial Expert with Martin’s Economic Consulting Group, a fiscal prosperity advisory follow of Ameriprise Monetary Solutions LLC. in Kennett Square and Havre de Grace, Md. She specializes in fee-primarily based fiscal arranging and asset management methods and has been in observe for more than 22 a long time. To contact her: www.ameripriseadvisors.com/bronwyn.x.martin

Where to Find the Best Bond Market Deals

Where to Find the Best Bond Market Deals

The bond marketplace fills two primary roles for traders.

To get started, bonds deliver earnings. (Or, at the very least most do. The huge greater part of bonds shell out semiannual coupon payments.)