Are we on the brink of a corporate credit crisis?

Are we on the brink of a corporate credit crisis?

A version of this story first appeared in CNN Business’ Before the Bell newsletter. Not a subscriber? You can sign up right here. You can listen to an audio version of the newsletter by clicking the same link.


New York
CNN
 — 

Everyone seems to be in a bit of a debt bind at the moment: The US government has run out of credit to spend, high inflation and interest rates have taken a big bite out of debt-laden tech companies that expected pandemic-era growth to continue and US credit card debt reached nearly $1 trillion in the fourth quarter of 2022, according to TransUnion.

Last year was bad for credit on all counts as Covid-zero policies in China, Russia’s war on Ukraine and the associated energy crisis and high inflation led to turbulent markets, pushed up borrowing rates and slowed the global economy.

Economists are hoping that this year brings better news, but 2023 is unlikely to provide the clean break investors are hoping for. Governments have diminishing fiscal options to deploy after piling on debt during the pandemic and individual borrowers face a prolonged period of elevated interest rates.

Profit pressures on corporate borrowers, meanwhile, are intensifying at an especially rapid pace as business costs remain elevated while consumer demand wanes amid the prospects of an economic downturn.

High borrowing costs and an uncertain economic outlook mean that companies are trading in the prospect of rapid growth for smaller debt loads. Fourth-quarter earnings reports show that the pace of debt reduction accelerated to -1.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for the year, from -0.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in the third quarter, according to Bank of America.

But businesses that don’t have cash to pay down debt loads may face the music in 2023. Economists at S&P Global Ratings forecast that speculative-grade (perceived to have a lower level of credit quality compared to more highly rated, investment-grade, companies) corporate default rates in the US and Europe will double this year alone.

So are we on the brink of a corporate credit crisis?

Before the Bell spoke with Ruth Yang, managing director and global head of thought leadership at S&P Global Ratings to discuss what lies ahead for the corporate credit market.

Before the Bell: What’s your big picture view of the credit economy right now?

Ruth Yang: There’s no easy way out, we have a very narrow pathway forward. If we have a shallow and short recession, then the risk for defaults is also shallow and short. But if we have a longer recession — even if it’s shallow — and growth continues to slow, we’re going to see defaults start to rise and credit markets struggle.

Corporations still have cash cushions on their balance sheets but they’re getting eaten away, we’re running out of time and the pathway is narrowing. As it narrows exogenous macro shocks present larger risks to the credit markets. It could be the destabilization of crypto, or the tension between energy security and the cost of energy and climate change or US-China relations and supply chain problems.

All of these things are going to come at costs and the impact is really magnified because we don’t have a lot of margin for error. We don’t have a lot of room to maneuver and we have a lot at risk.

How are you seeing credit headwinds playing out in investment strategies?

‘Higher for longer’ interest rates isn’t just about borrowing costs. Something I’ve noticed is that it’s also impacting funding strategies in general. Private equity investors and others are no longer as focused on total return and are less willing to fund companies that are cash-flow negative in the short term. They’re going to be a lot more focused on cash-flow-positive companies across the board. We think that will change sector-based investment strategies — technology and health care are notoriously cash-flow negative and will have more trouble finding funding.

Who will lead the way in these possible funding changes?

Private equity fuels an enormous part of our economy and the ability to get funding is going to lead the way in corporate earnings reports. The maturity wall for debt is still a few years down the road but if we’re still in a ‘higher for longer’ state in two or three years we’re going to have to fundamentally change how we fund companies. The business models of companies that are able to raise funds will also change. There will be slower growth with thinner margins and that’s going to change how people look at their investment opportunities.

▸ Investors who find themselves infatuated with inflation rates will receive a nice Valentine’s Day treat on Tuesday with the release of January’s Consumer Price Index. Last week, Federal Reserve Chairman Jerome Powell made headlines and lifted markets as he said that 2023 would bring more disinflation.

“We expect 2023 to be a year of significant declines in inflation. It’s actually our job to make sure that that’s the case,” said the central bank chief in a question-and-answer session at the Economic Club of Washington, D.C.

Wall Street will watch closely to see if prices continue to drop in the first inflation report of the year and if sticky service inflation finally begins to deflate.

Analysts are predicting some bad news, however. They forecast that headline CPI increased by 0.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month over month in January, according to Refinitiv data. That would be an acceleration from the recent pace.

That outlook mostly reflects an increase in energy prices, driven by higher gasoline prices. Data from AAA shows that gas prices rose by 4.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in January.

Analysts from Bank of America also predict that core services likely rose by 0.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from December, owing largely to a 0.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} increase in shelter costs.

▸ The Producer Price Index, which measures the change in input for companies, is due out on Thursday. When producers face input inflation, the increases in their production costs are passed on to retailers and consumers — so this data is considered a leading indicator of inflation.

Price increases upstream from the consumer during January are also expected to have accelerated from December. The monthly core number is forecast to rise to 0.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from 0.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, with the core year-on-year number rising to 5.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from 5.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, according to Refinitiv.

▸ Nearly three-quarters of S&P 500 companies have released fourth-quarter earnings and the season is winding down, but there are still some big names reporting this week.

Palantir and Avis report on Monday.

On Tuesday Coca-Cola, Airbnb, Marriott and GoDaddy report.

Wednesday brings earnings news from Cisco, Shopify, AIG, Kraft Heinz, Fidelity, Biogen and Roblox.

DoorDash, Paramount Dropbox, Hasbro and DraftKings come Thursday.

The week closes out with Deere & Company, AutoNation and AMC on Friday.

If you bought booze ahead of the Super Bowl on Sunday, you may have gotten a better deal if you skipped beer and went straight for the hard stuff.

Beer prices this year have jumped 11{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from a year earlier, while wine and spirits are up 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, respectively according to a new Wells Fargo Super Bowl Food Report.

Party guests may have also enjoyed the switch. Spirits were more popular than beer last year for the first time ever, according to a new Distilled Spirits Council of the United States (DISCUS) report last week.

Spirits sales rose in the United States (for the 13th straight year) in 2022, and now represent 42.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the total US alcohol market share. This is the first time spirits supplier revenues have surpassed beer, which holds a 41.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} market share.

Driving the growth were increased sales of American whiskey and tequila.

“More than 60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the spirits sector’s total revenue was from sales of high-end and super-premium spirits, mainly led by Tequila and American Whiskey,” said Christine LoCascio, DISCUS chief of public policy and strategy in a statement last week. “While many consumers are feeling the pinch from inflation and reduced disposable income, they are still willing to purchase that special bottle of spirits, choosing to sip a little luxury and drink better, not more.”

Still, vodka led the way in the United States, with $7.2 billion in sales last year, about the same as in 2021.

But it appears Wall Street likes to invest sober — those gains haven’t shown up in the broader market just yet. Constellation Brands (the company behind Svedka Vodka, Casa Noble Tequila and High West Whiskey), Brown-Forman (Jack Daniel’s, Herradura, Woodford Reserve, el Jimador and Finlandia) and Diageo (Johnnie Walker, Crown Royal, J&B, Smirnoff, Baileys, Ketel One and Captain Morgan) are all under-performing the S&P 500 so far this year.
7 Best Finance Podcasts | Acorns

7 Best Finance Podcasts | Acorns

No matter if you are hunting to increase your financial investment know-how or for suggestions to pay off financial debt, particular finance podcasts can support you strengthen your money administration expertise. 

Listed here are some finance podcasts to take into consideration examining out: 

Given that its start, millions of persons have downloaded the Gain Your Leisure podcast. The economical podcast addresses company ideas and highlights entrepreneur good results tales. It also offers behind-the-scenes insights into the leisure and sporting activities industries. 

Hosted by Rashad Bilal and Troy Millings — an elementary college instructor and a fiscal advisor that have been pals given that they ended up youthful young children — the podcast breaks down money topics into simple-to-comprehend principles. 

Emlen Miles-Mattingly introduced the Minority Money Podcast to handle disparities in fiscal well being among the minority teams.

Miles-Mattingly has spent two decades doing the job in the economical services marketplace, and is at the moment working towards earning a qualified economical planner (CFP) credential. 

The podcast focuses on a holistic watch to monetary wellness. Previous episodes have showcased guest industry experts that coated matters like shifting vocation paths in your 40’s, taking care of increasing inflation prices and vacation hacking with credit score card benefits. 

3. So Income, Farnoosh Torabi

Farnoosh Torabi is a person of the most effective-identified private finance gurus in the state.  As an creator, she aided people today make budgets and spend for their futures, and later manufactured frequent appearances on morning speak exhibits to share cash management guidelines. These days, Torabi is the editor-at-significant of CNET Money and founder of the So Funds podcast. 

So Cash capabilities perfectly-identified authors and media personalities to share their expertise and individual encounters on all the things from career enhancement to improving tax effectiveness — all as a result of a lens of inclusivity.  

Jamila Souffrant, a licensed money instruction teacher, introduced the Journey to Start podcast in 2016. Final calendar year, the podcast experienced around two million downloads, and it is been highlighted in publications like Forbes, Revenue Magazine, and Company Insider. 

The Journey to Launch podcast focuses on aiding men and women accomplish economic independence and boost their internet really worth. By the podcast, listeners can learn how to create an actionable strategy to attain their monetary targets. 

Earlier episodes have showcased folks who have reached terrific effects, these as shelling out down six-figures of credit card debt or launching a million-dollar company, to share their stories and suggestions. Past guests include entrepreneurs Ramit Sethi, Tori Dunlap and Tasha Booth. 

5. How to Revenue, Matt Altmix and Joel Larsgaard

Some private finance podcasts can be scary for men and women that are new to cash management several focus on complex and sophisticated money subjects like actual estate financial investment trusts (REITs) or tax efficiencies, and newcomers could be confused. 

That’s where by the How to Dollars podcast comes in. It focuses on the foundational capabilities folks have to have to strengthen their monetary literacy, from creating an unexpected emergency fund to having edge of employer retirement contribution matches. 

By offering jargon-totally free own finance assistance, the hosts tackle a variety of matters to empower individuals to take care of their funds with self-confidence. 

In the Women That Invest podcast, Kaur and Gupthan make Wall Road fewer overwhelming for new investors. The podcast gives important details about the stock current market and investing so that women can achieve fiscal independence. Podcast episodes go over every thing from safeguarding your cash for the duration of a recession to overviews of trade-traded funds (ETFs) and mutual resources. 

Kair and Gupthan avoid jargon and have a laid back again strategy to their clearly show as a consequence, they have a strong subsequent of ladies seeking to improve their investing know-how. 

Although most podcasts have episodes that are 30 minutes or extended, Nicole Lapin’s Revenue Rehab podcast has a diverse method. Most episodes are much less than 15 minutes in length, building them a fantastic preference for folks just easing into personalized finance that are wanting for bite-sized tips and actionable advice. 

Lapin, a very best-providing particular finance writer and accredited expenditure fiduciary (AIF), works by using her personalized experiences with debt and imposter syndrome to give steerage to her listeners. In past episodes of her podcast, she tackled matters like setting and trying to keep fiscal resolutions, the great importance of credit history scores, paying out off student financial loans and the execs and negatives of purchase-now, pay out-afterwards packages. 

Tuning in

No make a difference where you are in your economic journal — no matter if you might be deep in credit card credit card debt or are searching to improve your financial commitment returns — there is most likely a individual finance podcast out there that can aid.

6 alternate careers for Accounting and Finance professionals

6 alternate careers for Accounting and Finance professionals

In this article are 6 alternate professions for Accounting and Finance experts. Examine below now.

Alternate occupations for Accounting and Finance experts

By India Now Web Desk: A person of India’s primary companies of accounting and finance upskilling certifications, I am frequently questioned about choice career opportunities for men and women with backgrounds in these fields. I have an understanding of the relevance of delivering students with a effectively-rounded education that equips them with the techniques and understanding they will need to succeed in present day career marketplace. When regular roles these types of as accounting, money examination, and audit are undoubtedly crucial, the expertise and awareness gained by way of an accounting and finance education and learning, and certifications like CPA, can also be applied to a vast variety of other industries and positions.

Administration CONSULTING

A person option vocation prospect is administration consulting. Quite a few consulting firms, especially those that specialise in method, count closely on economical evaluation and modelling. The ability to comprehend and analyse economic facts, as effectively as converse sophisticated strategies evidently, is hugely valued in this discipline.

Consulting corporations normally use individuals who maintain certifications these types of as CPA, simply because of their skills in money investigation and modelling, as well as their potential to converse advanced concepts correctly.

Investment BANKING

Another possibility for accounting and finance specialists is a profession in financial commitment banking. Their skills in fiscal examination and modelling are extremely valued by financial commitment banking companies, as very well as their ability to work underneath stress and meet up with restricted deadlines. A occupation in financial investment banking can be quickly-paced and challenging, but it can also be really worthwhile for people who are up to the activity.

One of the best techniques to break into the lucrative career of financial investment banking and management is to get certified in a study course like the CFA or CPA. These will take your expertise and expertise to the future level, offering you an helpful edge about your levels of competition.

Corporate FINANCE

One extra profession choice is company finance. Corporate finance gurus enable firms make monetary decisions, these types of as how to elevate cash and how to invest it. They are often dependable for generating financial styles, examining money info, and determining regions where the company can boost its economic overall performance.

They may perhaps also be concerned in strategic arranging, budgeting, and forecasting. Corporate finance pros need to be element-oriented and have sturdy analytical abilities, as perfectly as the means to operate perfectly less than pressure.

ENTREPRENEURSHIP

Just one of the best professions that finance and accounting specialists can select nowadays is entrepreneurship. The lack of talented accountants has resulted in incredible expansion in this field. Accredited CPAs can start out their individual exercise, finding small business from clients across the earth. They can also make a foray into the discipline of FinTech, which has been expanding at a large charge lately. Monetary advisory or coaching is an additional solution that can verify immensely advantageous.

All in all, excellent education and learning in finance and accounting opens up various doorways for you. This is even truer for professionals who are competent CPAs or hold other these certifications. They can easily transition into roles in the IT sector, government work opportunities or even operating with non-revenue.

Risk Administration

Threat Management is yet another profitable vocation prospect that F&A specialists have. Truthfully, the scope for individuals in the finance and accounting sector is limitless.

Obtaining labored toward building the ecosystem for finance and accounting in India for the earlier 12 a long time has designed me realise that alternatives in this market prolong well past classic roles. Each individual business, regardless of whether it is Human Resources, Genuine Estate, Information and facts Technologies, Source Chain Management or Education and learning requires skilled and proficient accounting industry experts.

Knowledge ANALYTICS

One more alternate profession option is in details analytics. With the escalating volume of details currently being created by enterprises and organisations, the demand for pros who can assess and interpret this info is on the rise. Data analytics experts use statistical and quantitative methods to analyse and interpret info, and they assistance organisations make knowledge-pushed decisions.

The techniques in fiscal investigation and modelling are really precious in info analytics as well. A info analyst in finance assists discover styles, developments, and insights in economic info, and assists corporations make facts-driven selections. This can incorporate tasks like making fiscal models, analyzing monetary knowledge, and pinpointing areas wherever the corporation can enhance its money functionality. In addition, with the rise of large information and machine mastering, the industry of data analytics is also speedily evolving and necessitates a talent established in info visualization and programming, producing it an remarkable and dynamic vocation option.

In summary, I would like to say that the accounting and finance sector is incredibly broad and adaptable. The expertise and awareness obtained by means of instruction in accounting and finance can be applied to a huge selection of other industries and positions. With a history in accounting and finance, men and women have a extensive array of profession opportunities accessible to them. It’s all about how you leverage your competencies and understanding to produce a effective vocation path.

– Varun Jain, CEO & Co- Founder, Miles Education and learning.

Zambian finance minister criticises creditor delays in debt restructuring

Zambian finance minister criticises creditor delays in debt restructuring

Zambia’s finance minister has criticised prolonged conversations about the country’s credit card debt restructuring, which have incorporated a Chinese contact for multilateral lenders this kind of as the Globe Lender to be involved in the approach, warning that the recovery of Africa’s 2nd-major copper producer was staying held back.

Situmbeko Musokotwane mentioned in an interview that “time is of the essence” to finish a restructuring of about $13bn of external debt this calendar year, three many years right after the southern African nation defaulted on it. Problems about delays have mounted considering the fact that China, the biggest creditor in the talks, previous thirty day period identified as for the Environment Bank and equivalent establishments to be provided in the restructuring.

Questioned regardless of whether he supported the notion floated by Beijing, he replied: “Discussions at bigger stages like these just make our scenario even worse, because what we are searching for is urgent methods, not discussions that could drag out the make any difference.” He extra: “We need to all just aim on and get the debt [relief] delivered.”

China is Zambia’s one biggest creditor, with about $6bn of infrastructure loans unfold amongst various Chinese financial institutions. About $3bn is owed to holders of all the country’s US dollar bonds.

Beijing’s demand from customers to include multilateral lenders would upturn a many years-outdated rule in sovereign lending that they must be exempt from credit card debt restructuring simply because they act as loan providers of final resort and cost very little fascination.

China previous yr agreed in principle to give Zambia reduction in tandem with other formal creditors by means of a G20 process acknowledged as the frequent framework.

But given that then, specific designs for a restructuring have stalled and left President Hakainde Hichilema’s government not able to obtain a $1.3bn IMF bailout or to resume spending its money owed.

China signalled its most current objection in January when a spokesperson for its foreign ministry said that “the critical to easing Zambia’s financial debt burden . . . lies in the participation of multilateral financial establishments and industrial creditors in the credit card debt reduction efforts”.

As effectively as conflicting with present policies, the need also signifies that Beijing objects to primary tenets of Zambia’s personal debt restructuring rather than haggling in excess of particular conditions.

On a vacation to Zambia very last month US Treasury secretary Janet Yellen termed China a “barrier” to a offer.

Multilateral growth loan providers make up less than $3bn of about $7bn of exterior credit card debt that Zambia excluded from the restructuring previous 12 months.

Lusaka has asked the remaining creditors to agree to reduce the in general price of their claims by about fifty percent, or a lot more than $6bn, either by way of having direct losses on principal or decreasing interest rates and extending reimbursement.

Beijing is identified to be reluctant to set any precedent for having direct haircuts on its financial loans to creating nations. But analysts have reported Chinese banks could lower their costs reduced adequate to meet up with Zambia’s debt reduction goal and continue to obtain more than Lusaka would pay multilateral lenders.

Right until official lenders agree to certain phrases, Zambia can’t easily protected a offer with personal bondholders. “We are involved about the delays, and we would have favored this to have occurred substantially a lot quicker,” Musokotwane explained.

But Zambia considered it was building progress with creditor engagements and could display its fiscal ideas ended up on observe, he said, introducing: “For the yr just finished, it has been just one of the ideal fiscal performances in many years,” with revenues and paying on target.

But this year’s finances and govt strategies to secure social spending assumed the personal debt restructuring would acquire position this calendar year, he included. “There are human beings guiding this . . . all this involves that the burden on our shoulders have to be eliminated.”

Some lenders have questioned the financial assumptions behind Zambia’s targets for credit card debt aid, such as a need to slash financial debt to underneath 90 per cent of exports by 2027, with some suggesting the degree could be larger. Others have explained it would be fairer for international traders in Zambia’s nearby currency bonds, currently excluded from the restructuring, to also acquire haircuts.

Any inclusion of domestic bonds in the restructuring would “would chance unravelling macroeconomic stability” and will not be considered, Musokotwane mentioned.

This article has been amended because very first publication to make clear that Situmbeko Musokotwane criticised delays in discussions about debt restructuring among Zambia’s creditors. He did not reject a Chinese phone to include things like multilateral loan providers in the personal debt restructuring, as at first said.

Local developers purchase historic Bush House Estate | Local Business News

Local developers purchase historic Bush House Estate | Local Business News

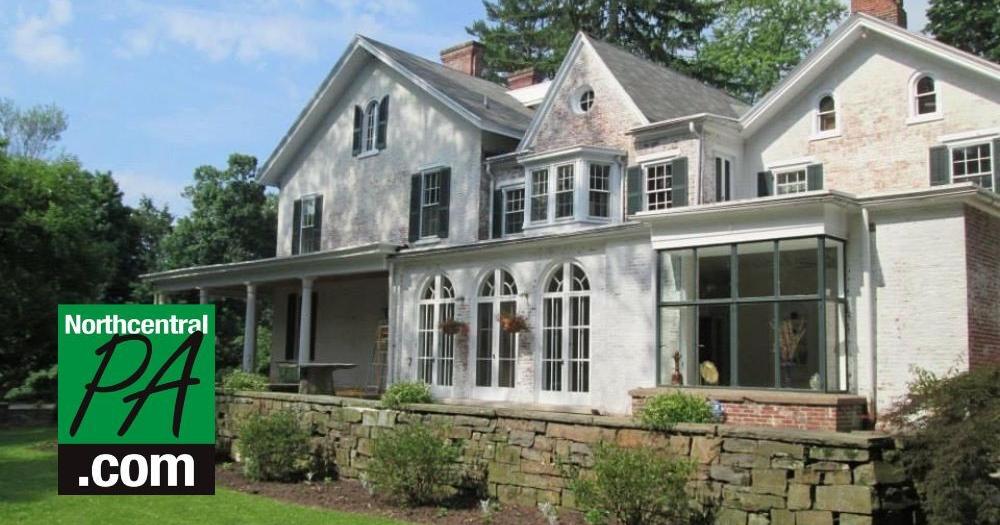
Muncy, Pa. — The entrepreneurs of the Bush Property Estate declared on Tuesday that they are now below new possession.

“This is a bittersweet announcement considering the fact that the property has been in our household because 1945. This will be a new chapter in our life and the lifestyle of the property that we have liked,” wrote Carmen and Charlie Bush in the announcement. 

The property has lately been ordered by FAMVEST, LLC, according to proprietor Carmen Bush. FAMVEST, based mostly in Condition School, are the exact developers who are getting the Lycoming Shopping mall. 

The new sale of the historic household that hosts weddings and other situations features 2.68 acres, in accordance to county data. 

What the home will be utilised for beginning in 2024 is uncertain at this place. “Make sure you be certain that the Bush Home Estate is in no risk of demolition and the new entrepreneurs intentions are to boost the house and make it even far more gorgeous,” the write-up read through. 

The estate, which was created in 1847 by the Rev. D.R. Dickinson and his wife Margaret of New York Town, is on the National Historic Sign up. It is referred to as “Margaret Hall” on the register. 

The house was owned by numerous households above the decades until finally Congressman Alvin Bush obtained it in 1945, in accordance to the Bush Dwelling Estate web page. 

Carmen and Charlie Bush had the enterprise for 10 several years. Carmen claimed she will keep on handling the home and events for marriage ceremony time by means of October. Anybody wondering about having an party there this year is encouraged to make contact with Carmen to explore availability. 

In the put up, the Bushes explained they “approach to delight in an untethered (& quite nicely deserved) life style in the future.”

 “We are thankful to a lot of people for these 10 many years of becoming in small business. It has been a pleasure and enjoyment conference people celebrating specific activities taking place in their daily life and other organizations that we labored with to make their occasions profitable,” the article go through. 

Keep your information nearby

Obtain to impartial, local information is crucial, do you agree?

We do the job hard to deliver well timed, related information, for totally free. 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your contribution to NorthcentralPa.com goes straight to helping us address news and gatherings in the location.

Thank you for indicating that local news issues!


I make all of our money but my husband insists on controlling it

I make all of our money but my husband insists on controlling it

Pay Dirt is Slate’s money advice column. Have a question? Send it to Lillian, Athena, and Elizabeth here. (It’s anonymous!)

Dear Pay Dirt, 

I’m the breadwinner of the family. My husband has not been able to hold a full-time job for the last 10 years. He claims it was to support my career, but he was never able to find a job when I said I would follow him. I have a decently paying job, and we have two children. The problem is my husband has complete control of the finances. He will not give me access to the saving account which holds all our savings, and which my paycheck has helped build. I have tried talking to him several times, but he makes excuses that I was living beyond my means when I was a graduate student, and that he is better with money. I don’t have any bad habits—I don’t get my nails or hair done on a regular basis, and hardly buy anything without discussing it with him. He thinks I will spend all the money if I find out about it. I only want to know how much money we are saving since I have two young children and need to think about my future. Am I wrong in asking for access to the savings account?

—Right or Wrong

Dear Right or Wrong,

I’m trying to give your husband the benefit of the doubt here: I hope he has been managing the household while you’ve been building your career, and that he’s a great and loving partner beyond this financial issue. But completely controlling the finances and limiting your access to joint bank accounts is concerning. Both of these traits are listed as financially abusive behaviors.

I firmly believe all partners should have access to some of their own (separate) money in a marriage, especially stay-at-home parents. But this isn’t just about your husband’s “walking around money.” He’s not earning any of the money while also not giving you access to joint accounts. He is treating you like a naughty child (based on your spending habits over a decade ago?), not an equal partner who earned the money he’s controlling.

I’m concerned that your husband’s refusal to even show you your account balances hides some deeper financial issues: gambling, addiction, financial infidelity, or significant debt. I hope it’s not true, but there may be nothing in your savings account. The best-case scenario is that he’s been diligently saving and is simply anxious because he still has some outdated image of you as a graduate student who splurged. But he doesn’t get to use his nervousness as an excuse to keep you in the dark about your own money. I think you need to look at what you’re getting out of this marriage—do you feel that he’s using you for your income and is using access to your money to control your behavior? Are there other signs he might be concealing a gambling habit or addiction?

If you are the joint owner of the bank accounts where your paychecks are deposited, you can go to the bank in person and request information and account access with your ID. It’s your right to access accounts in your name. Finding out the balances and recent transactions will give you better insight into whether your husband is actually nervous about you potentially overspending or if something bigger is happening. Pull your free credit reports from annualcreditreport.com to make sure there are no other surprises.

If, for some reason, your paychecks are being deposited to an account you are not listed on, you can open a new account and change your direct deposit form at work to have all or part of your paycheck deposited there. You can also insist your husband add you as a joint holder to your main accounts. There’s no reason you shouldn’t have access to the money you worked for (which is marital property). If your husband is responsible for paying household bills, you obviously have to discuss this with him. His reaction to this news will tell you a lot—does he only seem concerned about making the bills get paid? Or does he react aggressively or violently? Or does he just seem worried about his security as the financially dependent partner?

In the best case, where he is willing to give you more insight into the finances but is just worried about you overspending, you’ll likely benefit from convincing him to attend a few joint sessions with a financial planner or a financial counselor. Not only will you get a third party to help mediate these discussions, but you’ll also get a better sense of where your financial goals are for your children.

Want more Pay Dirt every week? Sign up for Slate Plus now.

Dear Pay Dirt,

I am a veteran teacher of 22 years, and like many educators right now I am fed up with the state of education in this country, sick of being disrespected, and have a cohort full of students with myriad needs not being met by insufficient mental health resources. My own mental health is in tatters, I want a change, and I’m feeling ready to leave the classroom.

But… I need the pension. Right now, according to my age and years of service, I qualify for a pension of approximately 20 percent of my current salary. I would need to stay 12 to 13 more years in order to get the maximum annual pension, which would be 80 percent of the average of my last three years’ salary. Our current financial resources are OK but not stellar—we own a home in a valuable neighborhood where we’ve lived for 12 years, and it’s now worth a lot more than what we paid for it. My spouse was unemployed for almost two years and supporting a family of four on one teacher’s salary consumed any savings we had. He has been back to work since the summer of 2020 and we’ve managed to pay down our credit card debt, but we don’t have much in our emergency savings and we’re not putting anything away for our kids for college.

How much of a financial hit would my family be taking if I were to leave teaching and do something else? I know I will still qualify for some social security, but I believe it gets reduced if you are receiving a pension. I feel like it would be irresponsible of me to leave, and I feel stuck.

—At Least I Still Get Summers Off

Dear Summers Off,

I’m sorry that many veteran teachers like yourself are fed up with cracks in the public school system. Unfortunately, I can’t tell you how much of a financial hit your family would take if you left to do something else without knowing your alternative career options. But know that your teaching skills are valued in the private sector and government jobs. First, you should research the compensation for careers you could transition into. Once you’ve got some options on the table, you’ll get a better idea of what kind of hit you would take without your full pension.

It’s worth noting that some former teachers who stay in the same pension system in a public sector job get to continue building it—it may be tied to your state or county and be portable. So explore those options if you want to leave the classroom but stick with your pension. But even if you don’t get to port your pension to a new employer, you can use the smaller payout as part of your overall retirement income plan (as long as you’re vested). For example, if you switch to an employer with a 401(k) and can max your contribution for the rest of your working career, you might be in good shape. You would get a combination at retirement age: social security, a reduced pension, and your 401(k) withdrawals.

If you want to understand how much social security you’re currently entitled to and how much has been withheld, create an account on the Social Security Administration website, download your statement, and use their benefits planner. You’re right: Certain pensions may reduce your social security payout. You’ll need to understand if the Windfall Elimination Provision (WEP) applies to you; WEP minimizes the amount of social security you receive if your employer doesn’t withhold it from your paycheck. But if your pension amount is low, WEP will only reduce your social security payment by half of your pension.

Once you have a good idea of the likely compensation and retirement structure of possible other careers, it’s worth booking a few hours with a fee-only financial advisor specializing in retirement planning (specifically one familiar with your pension system). The WEP calculations are complicated, and an advisor will have the software to do them. A few hours with an expert will likely give you the precise information you need to know when and for how much money you can afford to leave teaching.

Dear Pay Dirt,

I realize I’m getting a little ahead of myself and that no one can predict the future. But the current wacky housing market is really throwing off our family’s plans. We (me, husband, and 2-year-old) are living in a two-bedroom townhome that has already gotten a bit too small for us (we didn’t know when we bought it in 2019 that we’d soon need extra space to work from home full-time). Our plan was to wait until our daughter was close to going to school (i.e., when we’re no longer paying the equivalent of our mortgage for daycare each month) to buy a larger single-family house in a neighboring town, which we like better than our current town.

I really don’t want to have to switch school districts later (my parents switched me from public to private school my freshman year and I had a really hard time with it). So we have a few years, but if interest rates don’t decrease by then… what’s one to do? Just wait and HOPE that interest rates go back down? I’ve heard people say that the right time to buy a new house is when you need a new house, but if you literally can’t afford a new mortgage that you otherwise would have been able to afford just a couple of years ago, when interest rates were lower, I don’t see this as practical advice. My parents also like to remind us that interest rates were 16 percent when they bought their home in the 1980s, but their home also cost $55,000, not in the $300,000s. Our new home will likely be a bit more expensive than our current home, but we’d also be saving on daycare and homeowners association fees by then.

—Our Five-Year Plan Is Shot

Dear Five-Year Plan,

If I could predict the future of interest rates and the housing markets with the level of certainty you seek, I would be very, very rich. Even professionals don’t have a crystal ball when it comes to forecasting (just a lot of computer terminals). In 1966, Nobel prize-winning economist Paul Samuelson joked that the markets had “predicted nine out of the last five economic recessions.”

While the current interest rates are high compared to the past decade, your parents are correct that they are still low on a historical level. Housing prices, however, have risen at a rate that has outpaced inflation and salary growth. Nothing is particularly fair about the current housing market, but interest rates are the most responsive part. Instead of going only up like the price of cereal, interest rates wiggle around based on many factors.

I’ll inject some of my dismal science here: Saying that a recession is on the horizon doesn’t sound optimistic, but in a buyer’s housing market, there are some positives to recessions. The forecasted recession will likely put downward pressure on housing prices (a trend that has already begun). And that starts a cascade effect: Cooling house prices will bring down inflation. Once inflation is under control, the fed will slow down its interest rate hikes. Once the fed funds rate comes down, mortgage interest rates will follow. It’ll just take a little time, which you have. Your plan for buying a house when your daughter is school-aged makes a lot of sense. Don’t worry about what interest rates and housing prices will be like in three to five years. If interest rates and prices are still high, you can either buy a more modest house or stretch the budget and aim to refinance down the line. Either way, worrying now won’t help—you’ll cross that bridge when you come to it.

Dear Pay Dirt,

My friends and I (five of us total, two of whom are married to each other if that’s relevant) want to purchase a house and land together and live there together, maybe building more houses on that land so we’d each have our own one day. From a financial perspective, what should we be considering here when we start this process? Should it be set up like a co-op, with shares of a whole? Does everyone just go on the mortgage? We will not be coming in with equal resources or spending an equal amount of time at the house, especially at the beginning, so figuring out maintenance is also something we’re not sure how to divide.

Also, we do not need any advice on the people parts of this, we’ve been friends and roommates in various configurations and are good at resolving interpersonal issues!

—Millennial Commune Aspirers

Dear Millennial Commune,

Yay for building intentional communities with chosen family. You have a few different options when approaching the legal structure of this purchase—each with its own benefits and drawbacks. It can be challenging to find a lender willing to finance a group of unrelated people wanting to buy a house (especially if it is not an investment property). Sometimes, lenders will require each borrower to qualify for the purchase individually, which can be a tall order for a larger house or piece of land or if one person has fewer assets and worse credit.

It’s best to figure out the legal structure and co-ownership agreement before you even start looking for a property and lender. The most accessible option is to create an LLC or another corporate entity like an S corporation that acts as the “umbrella” for the group. This will require you to outline each person’s initial capital, ownership percentage, and roles in the operating agreement. Make sure you understand the differences between joint tenancy and tenants-in-common.

Even if you’re good at handling interpersonal conflicts as friends and roommates, the stakes go up when you have a property (and debt) involved. Creating legal documents that outline how you will govern future situations is essential. This can either be done as a “cohabitation agreement,” or as part of the incorporation documents for a legal entity like an LLC or S corp.

You want to address how the following issues will be handled:
—An owner needs to sell to relocate
—An owner has a change in family status (marriage, divorce) or dies
—How equity and expenses are divided when there are land improvements, especially on
—Individual land or when done with “sweat equity”
—Borrowing against the property value
—An owner cannot pay their portion of expenses
—How many votes an owner is entitled to in decisions (one per person? or by shares?)

Cooperatives can be an excellent option for co-owning property, but you will want to explore which flavor of co-op makes the most sense. The most common are Market Equity or Shared Equity co-ops. In this case, a housing corporation will own the property, and each owner will buy a share (or multiple shares) of that corporation rather than part of the building itself. This means when the market value of the property goes up, the value of each person’s shares goes up, and they gain equity. The advantage of this method is that each individual or couple could take out a mortgage for just their slice of the co-op.

If your primary concern is keeping the co-op affordable and accessible to your friends without as many resources, you can consider a Group Equity co-op. Group equity would involve an entity (such as an LLC, a trust, a nonprofit corporation, or S corp) owning the property, and each person living there is an owner and/or board member of that company. Everyone pays rent to the entity that owns the property. Group equity co-ops are rarer but have a big advantage: there are ways for folks to enter and exit the co-op more easily and affordably. But because the equity stays with the entity that owns the co-op, you don’t build equity on an individual level. A final type of co-op falls in between the above: a limited equity co-op, common in Resident-owned Communities. Any increases in equity are split between the individual owners and the combined entity that owns the land.

If you decide to go with a co-op, I recommend hiring a co-op financing consultant to help you navigate the process of financing and setting up incorporation documents. While it will be an additional expense, it will save you lots of time and money down the line. When a group equity housing co-op I lived at was refinanced in 2008, we hired a consultant from NASCO to help us prepare our books and balance sheets for banks (who struggled with understanding how 25 unrelated adults owned two houses). Even if you don’t use a consultant, I recommend you check out the Foundation for Intentional Communities and National Association of Housing Cooperatives resources on forming and structuring your community. Good luck in going forth and building your 21st-century commune dreams!

—Lillian

More Advice From Slate

We recently held an early birthday party for our toddler. We are quiet people and typically avoid throwing big parties, but my partner is leaving for the next year for work and we wanted an opportunity to visit with friends and family before their departure. I was blunt on the invitation: no gifts. We have a variety of reasons for this request.