How changes in supply chain finance disclosure could impact shippers

How changes in supply chain finance disclosure could impact shippers

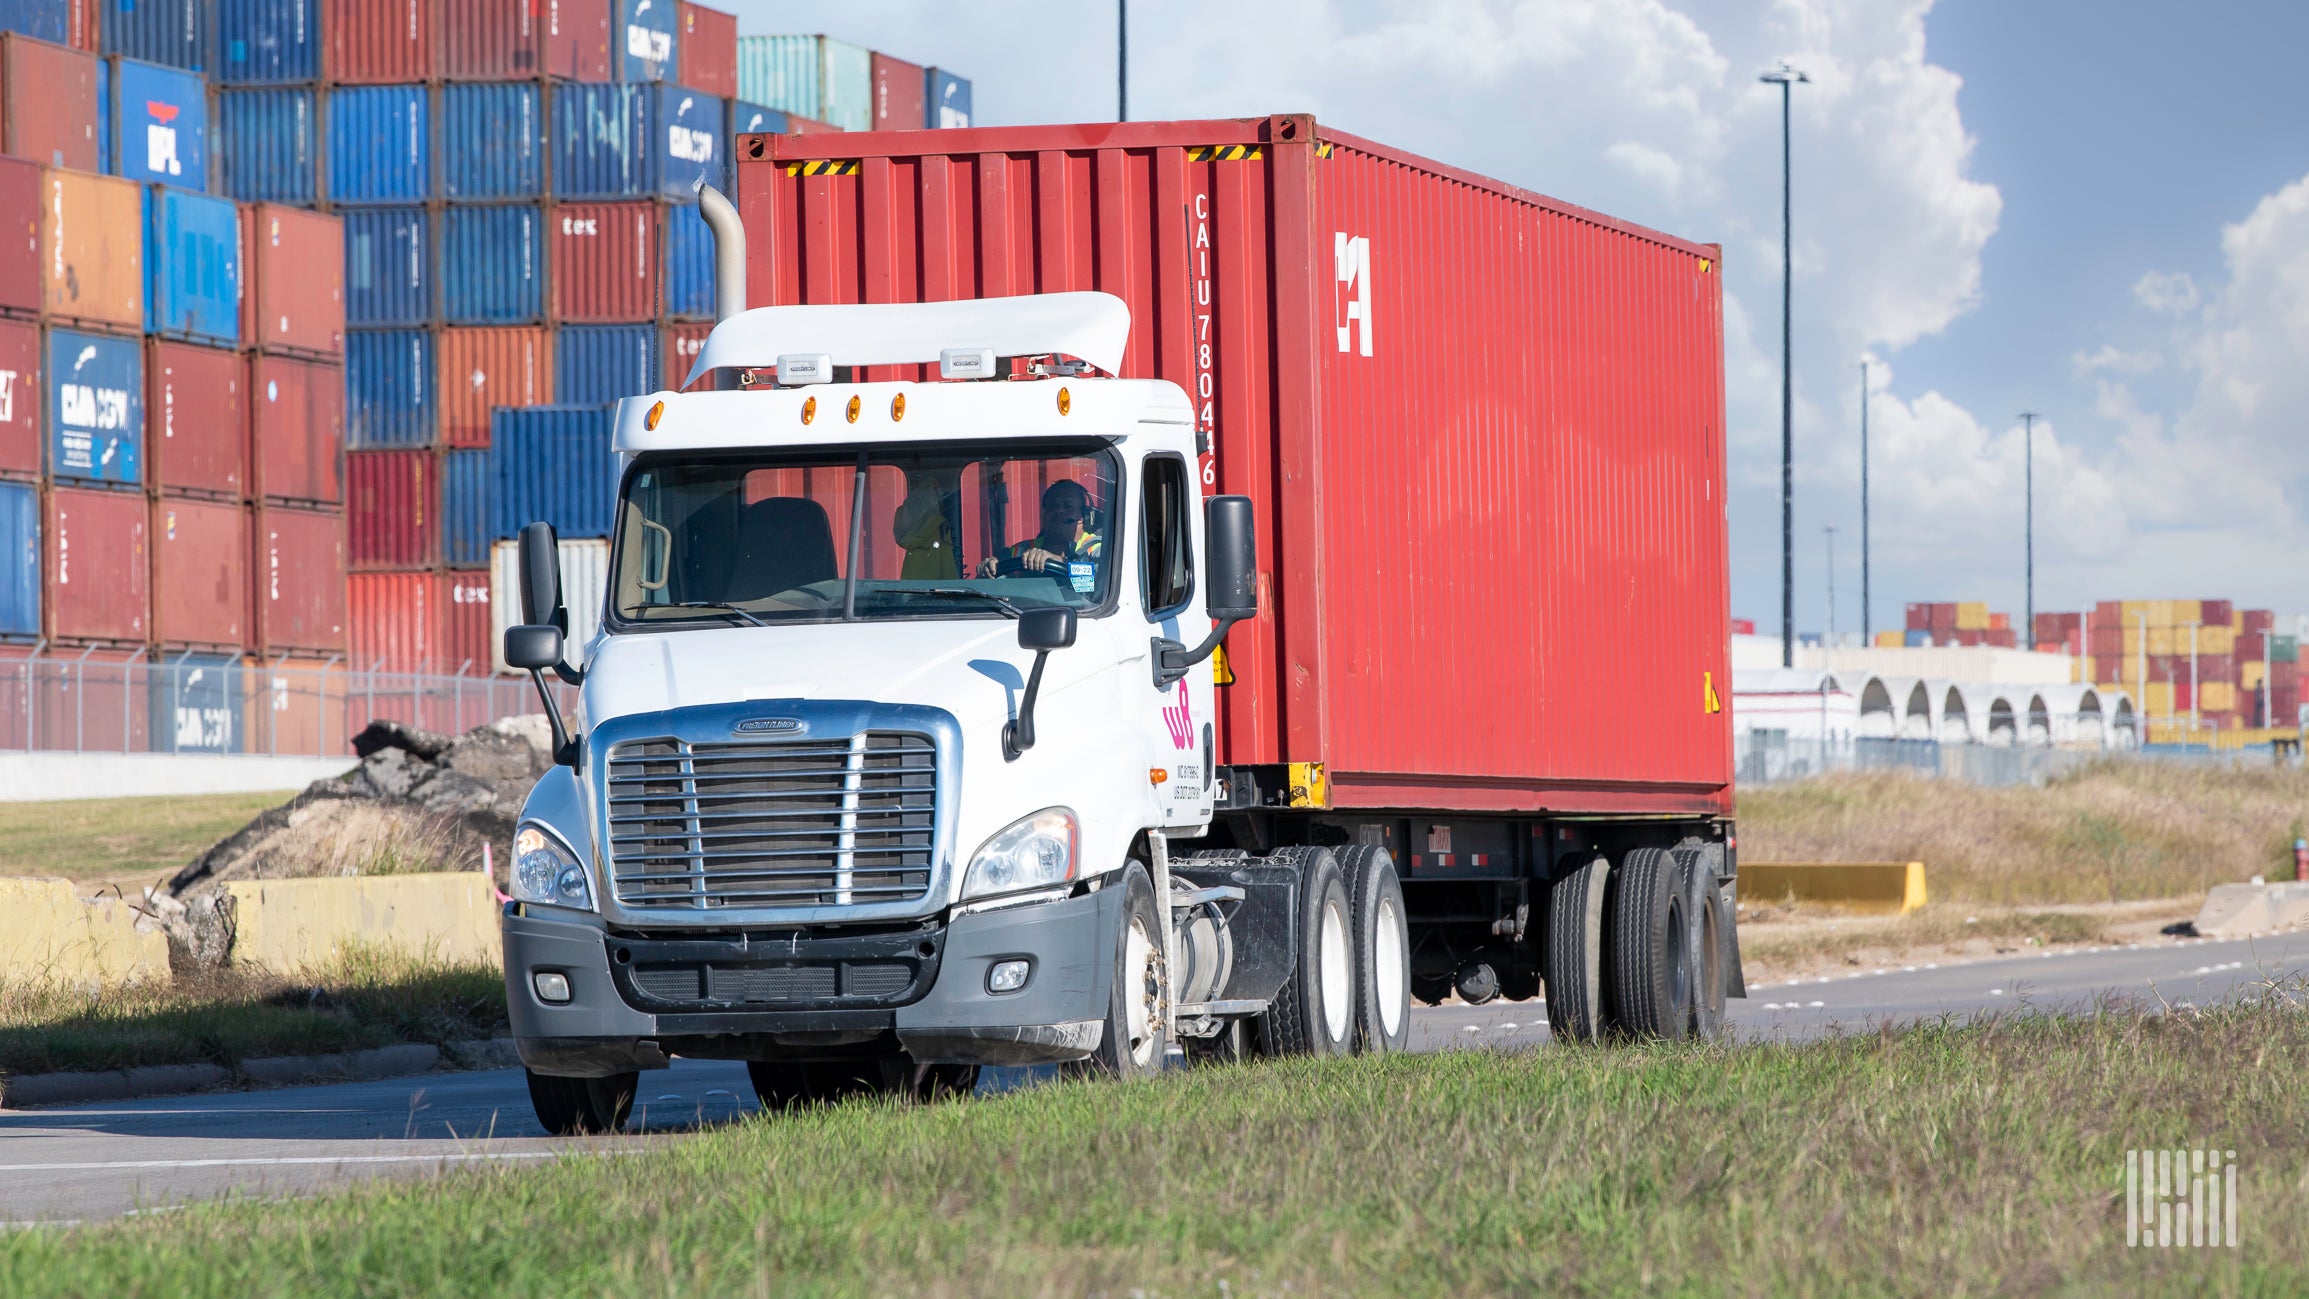
A latest rule adjust necessitating the disclosure of the use of offer chain finance applications could change how buyers and suppliers, both of which are regarded shippers in the freight environment, run and how traders perceive them.

Source chain finance, or reverse factoring, is a limited-expression arrangement letting customers to use the total payment window of an invoice whilst suppliers get paid out promptly. A 3rd occasion, typically a lender or other economic institution, pays an invoice accredited by a customer ahead of the owing date but at a discounted amount. The buyer repays the fiscal establishment the full total of the bill at a later on date. The lender retains the unfold — the variance in between the complete volume and the sum compensated by the financial institution, which was discounted at prevailing curiosity premiums.

The instrument increases money move for both consumers and suppliers.

The buyer is ready to push payments out as a great deal as six months to a 12 months, and the supplier can be quickly compensated on sales. Each suppliers and potential buyers optimize dollars movement by utilizing a 3rd party’s equilibrium sheet. Additional, big consumers frequently have stronger credit history profiles than their suppliers. The plans enable a smaller sized corporation providing items to a more substantial firm to fundamentally entry funding at a reduced price tag.

The transaction is a sale of the supplier’s receivables and not deemed personal debt for the consumer.

For a long time customers ended up not essential to divulge their use of provider finance plans. Nevertheless, a new Economical Accounting Expectations Board (FASB) rule for the fiscal yr setting up following Dec. 15 will demand customers to disclose payment terms of the transactions, ensure the amounts of the invoices in the software, disclose any guarantees or property pledged and offer a description of the place individuals obligations will surface on the stability sheet (less than accounts payable for most).

Nonetheless, FASB’s ruling stopped quick of demanding end users to classify the quantities as limited-phrase personal debt.

Headwinds to supply chain finance packages

Throughout the pandemic, inventory charges jumped as warehouse rents and labor charges stepped greater. Also, some corporations have taken on far more house to shop extra products. Several find them selves keeping stock for a longer period, which includes goods that stay unfinished owing to offer constraints. Cash conversion cycles have been extended as clients are taking longer to pay. It’s not uncommon to see purchaser bad debt expense increase on the draw back of the financial cycle.

Layer in incremental charge inflation in the variety of interest amount hikes and supplier finance plans are starting to be additional stressed. As fascination fees increase, the expenses to fund these transactions enhance. Banking institutions use marketplace desire premiums and the buyer’s credit history rating to figure out how considerably they will low cost a payment to a supplier.

The rule transform could alter how some prospective buyers (shippers) operate now that the magnitude of their utilization of source chain finance is regarded.

The extension of payment cycles, or days payable outstanding, have favorably impacted dollars stream metrics. In reality, functioning hard cash flow expansion has outpaced profits development “at a significantly more rapidly rate” more than the past ten years, KeyBanc (NYSE: Vital) analyst Adam Josephson told purchasers in a Tuesday take note.

Some of the paper and packaging providers he follows, like Ball Corp. (NYSE: BALL), have recorded compound annual development premiums in operating income movement two instances increased than that of sales over the past decade. Of those companies, some have extended times payable remarkable by more than a few moments.

“This style of funding is becoming progressively costly thanks to rising desire prices (from formerly traditionally minimal concentrations), and the financial institutions/fiscal intermediaries that provide it aren’t obligated to continue on performing so it’s an uncommitted line of credit history, as opposed to other sorts of financial institution financing,” Josephson claimed.

He explained tightening credit rating markets could induce financial institutions to decrease exposure by minimizing remarkable credit rating to the packages.

“In a tightening credit score environment and presented the risk that some firms could working experience credit score rating downgrades, we believe there’s a real danger of less these kinds of financing starting to be accessible in the months/decades forward,” Josephson ongoing. “If banks ended up to do that, the purchaser and provider would be compelled to revisit their payment arrangement, potentially at an inopportune time.”

Provider finance programs juice a company’s free hard cash move, which is usually utilised to make acquisitions or fund a share repurchase or dividend system. A lot of buyers take into account a company’s ability to deliver cash in addition to its earnings performance when producing financial commitment conclusions. An unwinding of extensions in times payable superb would affect valuation multiples.

“With the international financial state deteriorating and corporate earnings slipping, we hope investors to pay out increasing interest to balance sheets and funds stream statements and a lot less interest strictly to earnings statements, and we feel this is exactly the sort of subject that buyers really should and will turn into more and more attuned to,” Josephson reported.

More FreightWaves article content by Todd Maiden

Small volatility makes it possible for freight marketplaces to deteriorate

How to get better at personal finance in 2023 and beyond

How to get better at personal finance in 2023 and beyond


Financial state on the edge

Experts’ very best information for weathering inflation, occupation uncertainty and a doable economic downturn in 2023

Right after a year of headline-producing inflation and fears about a opportunity economic downturn, enhancing individual funds is at the major of many New Year’s resolution lists.

Stabilizing or improving your money standing is not anything that can be finished right away, professionals warning, but environment clear ambitions and taking techniques around time to satisfy them can go away you in a much better location and able of weathering prospective economic downturns.

In this article are some guidelines and tactics for having your individual funds in order and setting your self up for economical achievement in the new calendar year:

Think about what you want to help save for

Absolutely everyone has diverse aims in lifestyle, which include economic aims, so there is no just one-dimensions-fits-all monetary plan. Individualizing your personal savings program based mostly on your objectives can support you accomplish them with out putting also substantially strain on yourself.

TIAA indicates breaking down your conserving ambitions into three groups:

  • Ambitions you want to reach in a lot less than a calendar year, this kind of as a summer time excursion or live performance tickets

  • Ambitions you want to arrive at in significantly less than a ten years, such as a property renovation or a new car or truck

  • “Lifetime” ambitions, such as retirement.

As soon as you’ve set distinct aims and deadlines for when you want to get to them, you can choose the volume you’ll will need to conserve and divide by the range of months remaining to see how substantially you should really help save month-to-month.

Bear in mind the ‘50/30/20 rule’

Location a budget is a sensible way to regulate your cash, and currently being strategic in carrying out so can support set you up for both equally small-expression stability and very long-expression good results.

TIAA recommends following “the 50/30/20 rule of thumb.” The rule suggests you really should put a most of 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your income into “necessities” — this sort of as rent, food and utilities — and no far more than 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} into “discretionary” costs — this kind of as streaming services subscriptions or a gymnasium membership.

That leaves at least 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your earnings to place towards financial savings.

Do not neglect your crisis fund

Savings aims and a price range are sound techniques to maintain your private finances in superior form, but experts be aware you just cannot overlook to help you save for the surprising.

Placing component of your price savings into an “emergency fund” to include sudden costs these as medical expenses or property repairs indicates you won’t have to max out a credit history card or dip into your other price savings when an unexpected emergency does come up.

Intuit endorses aiming to have “anywhere concerning 6 months and a year’s well worth of savings” in your emergency fund. TIAA advises placing a aim of obtaining adequate in crisis personal savings to “cover 3-9 months of your residing expenditures.”

Choose edge of work rewards these types of as 401(k) matching

Your wage, paid time off and overall health insurance are very likely the initially factors that arrive to brain when you assume of position positive aspects. But quite a few companies supply even more, and not having gain of what is made available can depart funds on the desk.

Even if conserving for retirement isn’t high on your priority record, for case in point, opting into a 401(k) application by just making the minimum amount contribution to get matching resources from your employer can assist set you up for long term achievement at small value in the present. It can also have tax pros, Investopedia notes.

Your organization might also have other applications this sort of as incapacity insurance coverage or lifestyle insurance policies offered at very little to no charge to you. Having these procedures in your back again pocket can aid dull the economic impacts of an unexpected everyday living party.

Be sensible with your credit cards, and enjoy your credit rating

Credit playing cards can be a useful financial tool, but they require to be made use of sensibly.

You want to show that you have credit readily available and are capable of persistently earning payments, but you really do not want your stability or balances to get much too large. Intuit recommends “keeping your credit rating utilization ratio” under 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to not have an adverse effect on your credit rating score.

The team also emphasizes the value of checking your credit rating rating and credit score report. Many credit card organizations permit you to examine your credit history rating any time with no impacting your score. Checking your credit report on a yearly basis will also up your likelihood of catching fraud or blunders that could negatively impression your credit rating score.

This tale was at first revealed January 5, 2023 6:00 AM.

Linked tales from Charlotte Observer

Profile Image of Mary Ramsey

Mary Ramsey is a assistance journalism reporter with The Charlotte Observer. A indigenous of the Carolinas, she analyzed journalism at the University of South Carolina and has also labored in Phoenix, Arizona and Louisville, Kentucky.

Best Canadian Credit Cards And Personal Finance Products For 2023 Announced By creditcardGenius and moneyGenius

Best Canadian Credit Cards And Personal Finance Products For 2023 Announced By creditcardGenius and moneyGenius

MONCTON, NB, Jan. 3, 2023 /CNW/ – The most effective credit history playing cards and particular finance items for 2023 have formally been declared by sister sites creditcardGenius and moneyGenius.

WeyMedia (CNW Group/Weymedia Inc)

WeyMedia (CNW Team/Weymedia Inc)

The credit rating card types on creditcardGenius have expanded to greater signify Canadian company homeowners. The 3 new categories are:

moneyGenius ranks more than 36 groups, doing the job relentlessly to come across the most trusted and worthwhile fiscal merchandise that could help you save (and gain) Canadians the best amount of dollars probable.

Painstakingly analyzed using a refined math-based algorithm or element-primarily based ranking process, the reliable rankings are bolstered by an at any time-escalating hard cash again system named GeniusCash. The initiative was released with an unparalleled Tesla giveaway, formally handed off to Tony Yip in November.

Continuing the spirit of providing again, moneyGenius has a short while ago launched the Mountain Of Prizes giveaway, with multiple tiers of prizes well worth about $20,000.

“Private finance education is only acquiring much more significant as Canadians wrestle in the facial area of a tricky economy,” claimed Stephen Weyman, Co-Founder of moneyGenius and creditcardGenius. “Our objective is to supply readers with unbiased, dependable data and reward them for taking control of their finances. We hope to give back even far more in 2023.”

Sneak peek of the very best credit card and personalized finance winners:

Category

Winner

Best Cash Back again Credit rating Card

Amex SimplyCash Most well-liked

Most effective Equilibrium Transfer Credit rating Card

MBNA Legitimate Line Mastercard

Finest No Charge Credit Card

Amex Inexperienced

Very best Credit rating Card

Amex Cobalt

Finest Discounts Account

KOHO Earn Fascination

Finest Chequing Account

Scotiabank Best Bundle

Ideal Tax Program

Wealthsimple Tax

For full aspects, see Very best Credit score Playing cards 2023 and Income Awards 2023.

About WeyMedia Inc:

Reliable by above 320,000 viewers and subscribers just about every month, WeyMedia is a main Canadian individual finance firm that delivers nicely-investigated written content and economic resources to the every day customer. moneyGenius was introduced in 2010 to provide Canadians with the instruments to make each dollar count, and creditcardGenius was released in 2017 to generate the only credit card matchmaker that right away compares 126+ attributes of almost 200 Canadian credit cards. Their hard cash back rewards system, named GeniusCash, gives money back for everyone applying and accredited for featured products.

Media contact:
Nikita Garner
1-506-305-6866
nikita@moneygenius.ca

Cision

Cision

See authentic content to obtain multimedia:https://www.prnewswire.com/news-releases/greatest-canadian-credit-playing cards-and-own-finance-products and solutions-for-2023-announced-by-creditcardgenius-and-moneygenius-301712626.html

Source Weymedia Inc

Cision

Cision

See initial written content to down load multimedia: http://www.newswire.ca/en/releases/archive/January2023/03/c5497.html

Finance World Celebrates Slowing Growth in New Jobs Report

Finance World Celebrates Slowing Growth in New Jobs Report

The drops in both of those new jobs and wage expansion contained in a Office of Labor report introduced on Friday elicited cheers from money world insiders.

“This is a actually marvelous work opportunities report in loads of subtle methods,” tweeted Neil Irwin, Axios’s main economic correspondent. He claimed, “Job development is comfortable-landingish” — polite econ-converse for declaring growth is decreasing steadily.

“This seems to be like the proper path of vacation re: work,” New York Instances economic reporter Jeanna Smialek reported on Twitter, previously mentioned a chart depicting a steady decline in employment. “But it is probably not *as much* of a slowdown as the Fed would like, nonetheless,” Smialek hedged, adding that “[Federal Reserve] Chair Powell is seeking for noteworthy cooling in wages” — the dip in wage expansion depicted in the work opportunities report seemingly not steep more than enough.

Many others reacted to the news with even less restrained enthusiasm. “Wage development … slowed a ton,” tweeted Harvard economics professor Jason Furman, declaring that it represented the “best rationale for hope on moderating inflation.”

Even President Joe Biden welcomed the news, declaring that “this moderation in occupation progress is correct,” just after acknowledging that “average every month task gains have appear down from above 600,000 a month at the finish of past yr to nearer to 200,000 a thirty day period.”

Past year, amid the economic recovery subsequent the dips of the pandemic, the central bankers of the U.S. Federal Reserve launched a campaign of some of the steepest interest level hikes in years in an try to tamp down inflation. By making cash much more costly to borrow, amount hikes can cut down inflation by slowing down the economy and driving up unemployment.

“While bigger interest premiums, slower development, and softer labor market problems will bring down inflation, they will also deliver some discomfort to households and companies,” Federal Reserve Chair Jerome Powell mentioned in August. “These are the unfortunate expenditures of minimizing inflation.”

Not all gurus concur. Some argue that the drugs of charge hikes and their attendant charges to staff, including increased unemployment and reduced wages, can be worse than the inflationary sickness. Other dissenting industry experts say the main, underlying will cause of inflation — a pandemic, offer-chain crisis, corporate concentration, climate crisis straining agriculture — are not tackled by tighter financial policy and that the pandemic-related inflation was often going to be transitory.

At stake in the discussion is tens of millions of Americans’ positions. To tame inflation, previous treasury secretary and economist Larry Summers has referred to as for a year of 10 percent unemployment, significantly previously mentioned what we have now and which would see thousands and thousands of persons put out of perform. The Fed, for now, seems to be heeding that tips, albeit on a more compact scale — a scale that could expand based on which facet of the discussion prevails.

Sen. Elizabeth Warren, D-Mass., has warned that the Fed’s charge hikes “risks triggering a devastating economic downturn.” Warren’s assessment was echoed by the Fed’s very own investigation, which this summer warned that, in a past case in point, aggressive desire amount hikes in rapid succession resulted in the melancholy of 1920. The United Nations has also identified as on the Fed to cease its amount hikes, warning that it hazards a “global recession.” The Intercontinental Financial Fund issued a comparable warning, as did a Globe Lender paper.

Rate hikes can be an helpful resource towards inflation relying on its triggers, but it is considerably from the only a single. The inflation presently besetting the U.S. is getting driven by forces over and above the handle of the Fed, like provide chain issues and Russia’s invasion of Ukraine, Warren argued. (Economist Thomas Ferguson identifies the identical will cause as very well as a different 1: severe climate events ensuing from local weather improve.)

Alternatively of price hikes, Warren suggested several other strategies to deliver down inflation, together with fighting corporate rate gouging with aggressive antitrust policies, bringing a lot more mom and dad into the workforce by subsidizing youngster treatment, strengthening supply chains by ending tax breaks for firms that offshore work, and bringing down drug prices by making it possible for Medicare to negotiate them.

“As with any health issues, the proper medication commences with the right diagnosis,” Warren has explained. “Unfortunately, the Fed has seized on intense rate hikes — a major dose of the only medication at its disposal — even although they are largely ineffective against quite a few of the fundamental triggers of this inflationary spike.”

Warren has requested Powell, the Fed chair, how a lot of job losses the central lender is prepared to acknowledge in its war on inflation. The Fed has no very clear response.

In a press launch asserting even more charge hikes previous thirty day period, the Fed specified the inflation charge it was aiming for — 2 per cent — but, in phrases of work, only vaguely claimed to search for the “maximum.”

In contrast to the 2 p.c figure, the president of the New York Fed not too long ago mentioned unemployment could attain 5 p.c this calendar year — representing millions of men and women dropping their careers. Inspite of the Fed’s well-known mandate to go after each the maximum employment and cheapest inflation attainable, the priority would seem noticeable.

Inflation has been steadily falling since July, buoying hopes that the “pain to households” that Powell warned about may well subside. For now, even though, it appears the Fed’s aggressive war on inflation is just starting, inspite of rising warnings that it could induce a economic downturn.

An alarming but little-noticed report released by the St. Louis Fed on December 28 found that marginally around 50 percent of U.S. states are going through “recession-like conditions” that provide as a essential indicator for a coming countrywide recession.

“Huge downward revision to November wage growth,” Dean Baker, an economist at the Middle for Financial and Policy Investigate, said of the new employment report. An before report had prompt wages had been soaring again, but the discovering was corrected in the most current report after greater details grew to become readily available. Dean known as on the Federal Reserve to “hold the rate hikes please.”

What’s ahead for climate finance in 2023

What’s ahead for climate finance in 2023

U.S. regulators laid the groundwork very last year to handle the threats that climate transform poses to the global money technique.

This year could see individuals attempts bear fruit.

Achievements will rely on how swiftly organizations such as the Securities and Exchange Commission can finalize the weather-linked guidelines they outlined in 2022, as effectively as the level of resistance they deal with in Congress and the courts. The final result could fundamentally reshape how the U.S. economic climate responds to the repercussions of a warming earth.

Final year was the “year of proposing and arranging,” said monetary regulation specialist Todd Phillips, founder of Phillips Plan Consulting LLC, a progressive consulting business. And so this 12 months “we should enjoy the positive aspects.”

Below are the major troubles to look at on local weather-fueled financial danger in 2023.

SEC principles

The SEC very last yr proposed three regulations that purpose to give investors with more clarity into companies and their climate-associated money risks, as effectively as expenditure possibilities that purport to account for social and environmental issues.

Some significant issues moving forward are when people rules will be finalized and enforced — and what the finished variations will search like.

Possibly the most contentious rule would require public firms to disclose their greenhouse fuel emissions, as very well as their local weather-similar hazards, options and techniques. The new technique would overhaul the company disclosure course of action.

The other two principles intention to set guardrails all over what forms of financial commitment items can be categorized as eco-friendly sustainable or environmental, social and governance (ESG) funds. These styles of products and solutions have exploded in acceptance as expenditure companies race to satisfy community demand for sustainable expenditure solutions, sparking fears that some money are mislabeled to entice extra buyers.

Now that the weather disclosure and ESG rules’ comment durations have finished, the SEC’s present work involves operating via the hundreds of submitted reviews, producing a last rule and creating a case for why they are equally essential and legally defensible.

The SEC did not respond to thoughts about the timeline relocating ahead. Local climate disclosure authorities and advocates say there’s no way to say when the agency will end and enforce the procedures. But some feel it is probably to happen this yr.

“I would be expecting to see it sometime this yr. I know the SEC is striving to do a good deal, but they’ve indicated in the earlier that this is a seriously large priority for them. And if it’s a significant precedence, they are also likely to want to be the kinds to protect it [in court] in the course of the Biden administration,” explained Corinne Snow, counsel at Vinson & Elkins LLP who focuses on environmental regulation and regulatory compliance.

There are numerous components that complicate the timeline. For starters, SEC Chair Gary Gensler has embarked on an ambitious rulemaking agenda — proposing 26 new principles in the initial 8 months of 2022 — when in contrast to his predecessors, in accordance to the agency’s Business office of Inspector Normal. The intensive workload has the potential to slow the agency’s progress.

But the most important obstacle is the sheer quantity of responses the company has gained on these issues. While a lot of investors, outdoors teams and Democratic lawmakers are in favor of the rules, the company has confronted intense pushback, far too. The opposition possible will lead to authorized worries, which have the prospective to delay implementation even immediately after the ultimate rule is released.

Performing in the agency’s favor: a growing consensus among the traders, regulators and firms close to the entire world that local weather change poses sizeable monetary dangers that advantage supplemental clarity.

“I really don’t see that slowing down,” mentioned Kristina Wyatt, senior vice president of world wide regulatory disclosure at carbon accounting corporation Persefoni, who earlier was a senior counsel for climate and environmental, social and governance at the SEC.

Climate steerage

The a few significant banking regulators more than the last yr proposed close to-similar direction that lays out how they be expecting important U.S. banks — with extra than $100 billion in belongings — to control their publicity to weather adjust (Climatewire, Dec. 5, 2022).

The proposal makes distinct that the Federal Reserve, Workplace of the Comptroller of the Forex and the Federal Deposit Insurance Corp. want the largest creditors to evaluate and limit their publicity to climate impacts and the thoroughly clean electrical power changeover.

That’s the circumstance, the FDIC stated, mainly because climate adjust poses a “clear and substantial hazard to the U.S. economical method and, if unmitigated, may possibly pose a in close proximity to-time period risk to protected and seem banking and money security.”

Each individual agency issued its have request for remark. Whilst the OCC and FDIC’s remark intervals ended in February and June, respectively, the Federal Reserve’s won’t wrap up until eventually future thirty day period.

The following step for these regulators will be performing by the reviews and releasing a remaining model of the advice to make very clear potential expectations.

Fed circumstance evaluation

The Fed also is established to do a little something else — kicking off its very first-ever exercising intended to gauge major banks’ preparedness for the economical realities of a warming environment.

Central lender officers mentioned in September that starting in 2023 it would involve the country’s 6 biggest financial institutions to undergo “pilot weather situation evaluation,” which are meant to supply clarity into how the loan providers are considering about climate-fueled threats (Climatewire, Sept. 30, 2022).

Fed officers have emphasized that the physical exercise would not have direct repercussions for the creditors, which include Lender of America Corp., Citigroup Inc., Goldman Sachs Team Inc., JPMorgan Chase & Co., Morgan Stanley and Wells Fargo & Co.

Continue to unidentified, even so, are when the assessments will get started and what they could possibly entail. The Fed said the training would finish in late 2023, but other details are however up in the air.

Some outside the house industry experts assume the Fed will style numerous local weather situations, these as a foreseeable future in which no significant measures are taken to curb global warming. The banks then would assess how their equilibrium sheets would carry out in those people hypothetical conditions.

CFTC

The Commodity Futures Buying and selling Fee might also get it in on the motion.

The company, which regulates U.S. derivatives markets, said in June it designs to choose a nearer look at the $1 billion voluntary carbon marketplace that allows companies to offset their planet-warming emissions by investing in environmentally friendly tasks.

CFTC Chair Rostin Behnam has acknowledged the markets’ capability for fraud and other abusive procedures as organizations race to eco-friendly their functions and reputations — and in some conditions order offsets that really don’t final result in the emissions reductions they market.

What Behnam has not claimed is how the company may get concerned. But the agency held a daylong function in June to obtain perception from gurus and it issued a formal request for community comment (Climatewire, June 3, 2022).

The remark period of time shut in August.

Although the CFTC hasn’t delivered supplemental data about how it’s contemplating about the issue, Phillips Plan Consulting founder Phillips, a previous director at Citizens for American Progress and legal professional at the FDIC, said he expects the agency would release a proposal that builds off the community input.

“The question is, are they heading to just deal with the offset sector, or are they heading to tackle the trouble of offsets themselves,” Phillips explained.

Personal Finance: A look ahead to 2023

Personal Finance: A look ahead to 2023

Most forecasters would relatively overlook 2022. Almost never have so numerous prognosticators been so incorrect as they had been in handicapping the calendar year just finished, which must serve as yet another reminder not to depend far too closely on small-operate predictions in constructing extensive-phrase expense portfolios.

Even now, what entertaining would New Year’s be without having an intrepid preview of coming points of interest? With an considerable dose of humility, below goes.

— Inflation. With couple of exceptions, most economists missed this one particular. A surge in need blended with source chain disruptions caused inflation to warmth up in 2021, but most experts, such as the Federal Reserve, expected price tag disruptions to be “transitory.” As an alternative, 2022 proved to be even hotter. The Philadelphia Fed survey of Expert Forecasters predicted that CPI inflation would ordinary 2.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2022. The true variety is nearer to 7.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and its stubbornness necessary a drastic change in Fed coverage.

Count on inflation to decline through 2023 but not reach the Fed’s 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} target by year’s conclusion, ending up all around 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} by December. Though costs are moderating in durable items and strength, some factors of the CPI like rents, expert services and wages tend to be “sticky” and will just take lengthier to tame.

— Desire costs. At the time the Fed acknowledged the persistence of inflation, it acted aggressively, increasing benchmark fascination charges from .25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} involving March and December, the premier one-year proportion enhance on report. Also, the central financial institution has been allowing its massive stability sheet to shrink as bonds in its portfolio mature, further tightening financial circumstances.

Having said that, the work is not finish. Curiosity rates keep on being underneath the Fed’s chosen inflation measure, which implies that true rates are even now detrimental. Fees will have to rise above the inflation amount and stay bigger for a substantial interval, suggesting extra hikes in February and March, then keeping regular for the rest of the year. Even though markets have fallen sufferer to bouts of magical thinking, the Fed has continuously affirmed its resolve not to repeat the problems that led to the stagflation of the 1970s.

— Recession. Given the properly-documented stubbornness of inflation, the Fed’s steps are probable to guide the U.S. into a economic downturn by mid-2023. Apparently, if it takes place, it would be the most greatly expected downturn in heritage.

Odds are the economic downturn will be rather benign, as the problems are absent for a serious shock like the insolvency in the banking technique top to the 2006 monetary crisis. In reality, the recession could show so delicate that GDP stays flat or declines only somewhat for the total yr 2023 though unemployment rises to 4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}-5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. In the combination, households still have personal savings in the bank, but surging credit rating card balances and larger retail funding costs will retard client shelling out, which tends to make up two-thirds of the financial system.

— Inventory sector. Wall Street analysts choose not to discuss their 2022 market place anticipations, for excellent reason. Folks that forecast inventory costs play an essential function in society: earning weather conditions forecasters glimpse prescient. Goldman Sachs, for case in point, forecasted the S&P 500 to get 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} through 2022, a significantly cry from the double-digit losses finally sustained. In their defense, the foundation circumstance was for reduce interest premiums and transitory inflation that may well have supported additional robust returns but did not happen.

Predicting the degree of stock prices would be similarly futile in 2023, but we can take take note of some headwinds. Better curiosity prices and slowing demand from customers will pinch corporate earnings, estimates of which are arguably too optimistic now. This would increase downward strain on stocks into the new 12 months.

The far better news is that the stock market place normally bottoms ahead of the close of a recession and some of the most rapid gains take place when sentiment is most pessimistic. If certainly the economic climate is rising from economic downturn by 12 months finish, shares might have currently sniffed out the nascent recovery and begun pricing in far better development for 2024. The bottom line for buyers is that chance will be afoot.

— Bitcoin. Severely?

(Disclaimer: the previous should really not be considered as a suggestion to invest in or provide any stability. Seek the advice of your expenditure advisor ahead of investing in Dutch tulip bulbs, Cabbage Patch Dolls or cryptocurrency).

— Politics. Most likely the major hazard for the yr ahead is not inflation or the stock industry but Congress. When each houses passed an omnibus expending invoice very last 7 days steering clear of a authorities shutdown, some members are currently rehearing for the biennial Theater of the Absurd that includes the credit card debt ceiling. An archaic relic from WWI, Congress should periodically boost the statutory debt limit enabling the U.S. Treasury to elevate the income Congress has now used. Failing to do so would precipitate a catastrophic default, but in modern yrs some customers have leveraged this danger to extort attention to their possess priorities. These kinds of brinksmanship previously price tag the U.S. its the moment pristine AAA credit rating ranking. An additional episode could exacerbate a moderate economic downturn into a crash landing and possibly erode the preferential status of the greenback. This horror demonstrate is scheduled to open sometime around September. This is hoping it gets lousy assessments and closes early.

Some of these broad themes may well aid advise traders in rebalancing portfolios or underweighting sure sectors. But it bears repeating that although forecasts are a pleasurable New Year’s custom, they are often completely wrong, and the essential to lengthy-term investing accomplishment is retaining consistency and self-discipline in the deal with of uncertain periods.

Christopher A. Hopkins is a chartered financial analyst and co-founder of Apogee Prosperity Companions.