

Business News, Strategy, Finance and Corporate Insight

Business News, Strategy, Finance and Corporate Insight

India has been battling with pressured banking property (NPAs) for decades. The historic “reform” for resolution of this kind of pressured assets, called Insolvency and Personal bankruptcy Code (IBC) of 2016, is flailing as recoveries are nosediving. At the end of March 31, 2022, whole recoveries from the “resolution” and “liquidation” outcomes beneath the IBC dropped to 16.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the “admitted claims” or debts. This is reduce than 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} recovery less than the Bureau of Industrial and Economic Reconstruction (BIFR) mechanism.

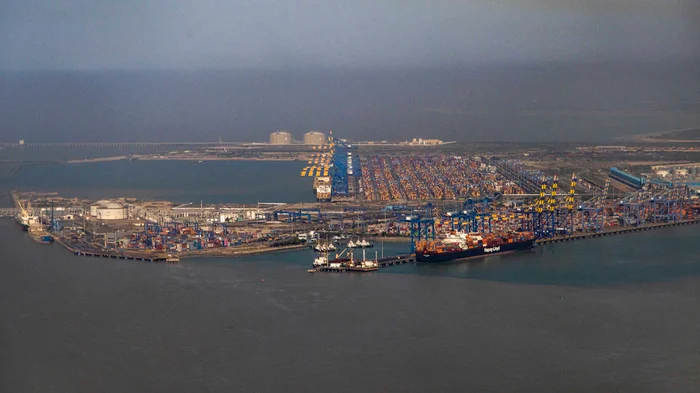
Now a new category of pressured asset has emerged in Could 2022, referred to as “stressed Public Private Partnership (PPP) assignments at the key ports”.

This is exactly how the Ministry of Ports, Delivery and Waterways described the problem it is experiencing, although issuing new “guidelines for early Resolution of Trapped Public Personal Partnership (PPP) assignments at Major Ports” on Could 11, 2022.

PPP port assignments abandoned

The ministry’s tips were being occasioned by abandonment of sanctioned PPP initiatives by private associates, possibly at the execution stage or soon after professional operations. The ministry available two explanations for this: (i) initiatives abandoned through the execution stage for the reason that of different good reasons like aggressive bidding, optimistic projections and unexpected alterations in business enterprise and (ii) deserted through the execution or immediately after becoming operational as personal partners defaulted on their financial loans, forcing lenders to declare their financial loans non-executing assets (NPAs) and go for IBC proceedings.

The new rules give “mechanism for resolution” of these pressured PPP projects.

In accordance to this, the concessioning authority (in this circumstance community ports) would get more than the deserted jobs after paying for the operate performed or by taking above 90{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of loans of its private spouse if the projects ended up deserted at the execution phase. For those people scenarios currently going through IBC proceedings, the concessioning authority (public ports) will be permitted to participate in it, take in excess of the PPP assignments and then place it to “re-bidding”.

The resolution system is, therefore, practically nothing but nationalisation of PPP projects abandoned by non-public players. Offered that the IBC is yielding only 16.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} (a haircut of 83{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), this means the Indian general public will conclude up shelling out for the failures of non-public PPP gamers (“socialisation” of private sector loss).

Aside from, the haircut would present up as NPAs of public sector banking institutions (PSBs), which will then be written off as a subject of regimen. The NPA produce-offs have skyrocketed considering the fact that 2015. RBI knowledge displays the produce-offs jumped from ₹1.2 lakh crore all through the 10 a long time of UPA (FY06-FY15) to ₹10.1 lakh crore in the 6 a long time of NDA-II (FY16-FY21) — a quantum soar of extra than 8 periods!

As a result of this resolution system, the ministry hopes “unlocking the blocked cargo handling capacity of about 27 MTPA (million tonnes for every annum)”. It significantly hopes for early resolution of 5 “long standing disputes on pressured property at a variety of key ports” — two PPP initiatives at the Deendayal Port (previously termed Kandla port) and 1 each and every at Mumbai, Thoothukudi and Visakhapatnam ports.

Not a shocking improvement

The ministry acknowledged that even with quite a few coverage initiatives, incentives and because of diligence, the survival of a number of PPP jobs is at chance. One of this was an elaborate (234 pages) “New Model Concession Agreement — 2021 for Community-Personal-Partnership (PPP) Projects at Important Ports” unveiled in November 2021, which was to reward (i) 80 “on-likely projects with expenditure of in excess of ₹56,000 crore” and (ii) “31 tasks of around ₹14,600 crore to be awarded on PPP till FY25”.

A considerable provision of this was flagged by the minister, Sarbananda Sonowal, on the occasion, called “Change in Cargo owing to Change in Legislation or Unexpected Events”. This is exclusively meant to defend private partners in PPP initiatives from “external and unforeseen factors” that has forced it to carry the new resolution system.

Dubious background of PPPs in freeway sector

This is not the to start with time PPP assignments have landed India in issues.

During the UPA regime (2004-14), when the PPP was taken up in a huge way in making countrywide highways, a lot of assignments were being abandoned, primary to a construct-up of the NPA disaster in the early a long time of the NDA-II authorities. Former chief financial advisor (CEA) Arvind Subramanian famously called it the “twin stability sheet problem” — in excess of-leveraged private companies and undesirable bank loan-saddled PSBs.

The UPA had virtually deserted PPP projects to the end of its tenure. It would be instructive to revisit the PPP fiasco of that era, extra so for the role viability hole funding (VGF) played in individuals PPP jobs.

VGF is an upfront payment to non-public players in the PPP projects by governments (Centre and states) to incentivise constructing infrastructure. As for each the VGF plan spelt out in November 2022 for social and economic assignments, the central and condition governments would present (i) VGF of up to 80{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the overall venture expenditures (each and every contributing 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and (ii) VGF of 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the operational price (every sharing 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) for the initially 5 decades of operations.

What this usually means is that the governments will fund 80{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of PPP tasks and then also fund 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of operational cost of these projects for the 1st 5 years. The rest is to be paid out by personal partner of the PPP assignments. This is why the PPP projects are extremely rewarding.

Through the UPA period, the Setting up Commission helmed PPPs, which include composing the model contracts and granting of a VGF of 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} by the central governing administration. An “internal paper” of the Preparing Commission and RTI replies uncovered the murky goings on in PPPs in 2010.

These files confirmed that for 20 freeway projects underneath scanner, PSBs experienced given a mortgage of ₹25,940 crore devoid of collaterals to the personal partners even though the sanctioned charge of these initiatives was just ₹13,646 crore. That is, the financial loans supplied have been practically double the price of the projects. Numerous PPP assignments were abandoned and saddled PBSs with big NPAs. Why did PSBs give 200{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} financial loans with out collaterals and then landed on their own with NPAs remains an abiding thriller.

There is much more.

In all freeway initiatives a VGF of 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} had also been supplied to personal companions by the central federal government. Taken together, the bank bank loan and VGF were being much excessive than the venture charges.

For uncomplicated understanding, enable us say a PPP project of ₹100 crore was sanctioned. The central authorities compensated ₹40 crore of VGF upfront. The private husband or wife went to a PSB and took a financial loan of ₹200 crore (double the venture cost). In all, it gained ₹240 crore for a ₹100-crore venture. This indicates the private husband or wife did not need to convey a penny of its individual (the motive why it is staying owed) and bought an extra volume of ₹140 crore (₹240 crore minus ₹100 crore) to divert to its other jobs. When the undertaking is abandoned, or the personal loan is defaulted banks are keeping up to ₹200 crore of NPAs.

This was not the only trigger of worry.

The Gurgaon Expressway toll booths ended up dismantled in 2012. One particular of the most important reasons was excessive profiteering by under-reporting quantity of motor vehicles that handed by means of the toll booths taken care of by the personal husband or wife. The other irritant was the substantial visitors jams at possibly facet of toll booths. The very same was the scenario with the DND flyway in Noida, which was dismantled in 2016.

NDA revives PPP and VGF

Instead of becoming cautious, the NDA-II federal government revived both of those PPPs and VGF in a major way. In 2014, it announced ₹1 crore of VGF for each individual 1 MW of solar vitality vegetation. In 2015, it gave “one time fund infusion” to numerous of the freeway projects that were being trapped — around and earlier mentioned the 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} VGF the non-public companions had now received.

Just before and immediately after the pandemic hit, the central federal government aggressively pushed for VGF for personal clinical schools (not non-public hospitals), in the funds and in formal communications. It questioned states to give unencumbered land, tax concessions and other money support, which it could reclaim from the Ayushman Bharat (PM-JAY). It also requested states to hand in excess of (community) district hospitals to those people personal healthcare schools for working and upkeep.

Now VGFs for PPP projects are climbing up.

In FY15, the VGF was ₹596 crore — the Parliament was knowledgeable by the governing administration. The Union Cupboard accredited VGF outlays of ₹1,400 crore for FY21, ₹1,500 crore for FY22, ₹1,600 for FY23, ₹1,700 crore for FY24 and ₹1,900 crore for FY25 at its meeting in November 2020.

But there is no thorough research in India of how quite a few projects have been built below the PPP product, how a great deal resources the central and state governments have paid out for it and how considerably NPAs have been designed up by these jobs.

These are the crucial to know the performance of PPP product. Right up until then, 1 can count on extra about “stressed” PPP projects.
Small firms struggle to access finance while a tenth turn to P2P

Small firms struggle to access finance while a tenth turn to P2P

More compact corporations struggled to obtain finance in the very first quarter, when around a tenth (12 for every cent) that utilized for funds did so by means of peer-to-peer lending platforms or via crowdfunding.

The Federation of Compact Businesses’ (FSB) Modest Business enterprise Index (SBI) located that much less than one in 10 (nine for each cent) compact companies used for finance in the initially quarter, the most affordable proportion since the SBI documents commenced.

The number of permitted applications reached a document lower of 43 for each cent.

Of individuals that used for finance, 7 per cent did so by means of P2P lending platforms and 5 for each cent by way of crowdfunding. The bulk (61 for each cent) sought standard overdraft or financial loan merchandise and a quarter (25 for each cent) applied for asset-dependent finance, these kinds of as invoice finance.

Out of the number of companies that did control to protected finance, 42 for every cent strategy to use it to regulate cashflow, whilst 21 for each cent mentioned they would use the cash for products updates (21 for each cent), 19 for every cent intend to grow, and 4 for each cent want to recruit.

Quite a few lesser enterprises were being seeking finance to assistance with cashflow difficulties. The vast majority (61 for each cent) of compact companies reported they were being impacted by the late payment of invoices more than the to start with quarter of this calendar year, and 26 for each cent explained the propensity for is growing.

A person in 10 (11 for each cent) of modest corporations system to near, provide or downsize their enterprise over the coming calendar year, equating to far more than half a million businesses.

Read through much more: New FSB chair hails benefits of P2P

Browse more: FSB calls for authorities motion amid late payments crisis

“Lenders pulling up the drawbridge for tiny companies will threaten our by now faltering economic restoration,” claimed Martin McTague, nationwide chair of the FSB.

“Businesses are born just about every day throughout the British isles – a lot of need funding to get off the floor, making sure they reach a stage where by they are rewarding and building prospects.

“A large amount of those who’ve labored tirelessly to adapt, endure and prosper over lockdowns need to have finance too, empowering them to get their companies to the next degree, driving our financial restoration and the transition to internet zero in the system.

“A huge chunk of what very little finance is getting accessed is currently being utilized to take care of cashflow challenges as our late payment disaster worsens, rather than for significantly-necessary investment decision and innovation.”

McTague reported the government must speed up shipping and delivery of the FSB’s proposal to make audit committees immediately accountable for supply chain apply to deal with this “worrying trend”.

Examine additional: Business enterprise insolvencies enhance amid spiralling inflation

“Culture change is what’s essential listed here – creditors taking an objective tactic to modest business enterprise finance and massive corporates putting greatest supply chain practice at the heart of environmental, social and governance programmes,” he reported.

“The consequence would be get-gain: energy in corporate supply chains and a flourishing small company neighborhood driving economic expansion from the floor up.”

The Single Greatest Investing Lesson I Ever Learned | Smart Change: Personal Finance

The Single Greatest Investing Lesson I Ever Learned | Smart Change: Personal Finance

In 2020, Morgan Housel unveiled The Psychology of Cash. I consider it justifies to be on the Mount Rushmore of investing publications, in particular for individuals who consider heritage and behavioral psychology are critical features for investing.

In the reserve, Housel has a area describing the stock marketplace as a field the place several online games that have almost nothing to do with each other are being performed at when. To quote from the ebook, “Few matters matter more with dollars than comprehending your have time horizon and not currently being persuaded by the actions and behaviors of people taking part in distinct games than you are.” This is why this basic idea has lifelong impacts on your cash and why it really is the ideal investing lesson I at any time figured out.

Image source: Getty Photos.

Understanding a stock’s cost

A stock’s selling price at a presented time is basically a illustration of the consensus worth established by buyers and sellers. But lots of of these players’ motives and motives for purchasing or providing the stock are absolutely distinctive from yours.

Persons are also reading…

For illustration, you have retail investors and institutional traders. Retirees and school young ones. Long-phrase buyers with multi-ten years time horizons and working day traders. Shorter-sellers and individuals who only continue to be on the very long aspect. Selections and futures traders and those people who only get shares in shares. The checklist goes on and on. Housel’s place is that several of these game titles have conflicting influences above the price motion of a given stock. And for that rationale, the rate of a stock rarely resembles its long-time period intrinsic value.

The tug-of-war in between greed and concern

At particular instances, the value of a stock can be dominated by greed, and at other instances, it can be dominated by concern. In present-day brutal bear industry, that implies you have some traders who may possibly dump perfectly excellent growth shares and transfer into worth merely since they are fearful and would instead personal a steady business with a superior harmony sheet and beneficial no cost hard cash move than just take a threat on a firm whose worth comes from what it could be truly worth in long run several years and not what it is worthy of nowadays. As a final result, we keep on to see thrilling progress firms with a good deal of prospective get offered off heavily in the brief phrase thanks to stress.

On the flip side, a whole lot of worth shares and oil and fuel shares had been arguably underappreciated in 2020 and 2021, though some development shares noticed their valuations get ahead of them selves. In these many years, we noticed investors choose far more pitfalls and solid out companies with minimal advancement. We observed a disregard for the geopolitical great importance of utilities, strength stocks, and defense stocks in favor of bets on the upcoming significant factor.

Authentic-earth illustrations

The position in this article is that you can acquire clarity by remembering that a lot of the cash in the inventory current market is enjoying a entirely different recreation than you are. When you understand that, it’s easy to see why an fantastic business like Amazon can slide by in excess of 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in a pair of weeks for tiny more than a mediocre earnings report and broader industry volatility.

Let us choose the illustration a phase more with a inventory like Shopify (NYSE: Shop). Shopify closed the 2019 calendar 12 months at just underneath $400 a share gained tons of momentum through the pandemic as e-commerce grew and the gig economic system went into whole impact ballooned to a sector cap of around $200 billion and an all-time-superior price tag per share of $1,762.92 on November 19, 2021 and has due to the fact slid to its current selling price of around $335 for each share.

Shopify inventory embodies several different games currently being performed at at the time. On the one hand, you have prolonged-term buyers who consider in Shopify’s skill to add new merchants, have current merchants upgrade to additional high-priced programs, and have those retailers earn far more funds which positive aspects Shopify. Then you have a sequence of folks who had been only shopping for Shopify as a shorter-term “pandemic play” and don’t care about the fundamental company — which was a huge purpose why Shopify inventory ran up much too considerably, far too fast in 2021.

But currently, you have nevertheless a different game being performed — the recreation of dropping endurance by offering progress stocks that make tiny to no gain and in search of deal with in safer names. After an trader realizes these conflicting online games, it starts off to make sense why a inventory like Shopify can go from growth to bust. It doesn’t make the selling price action in both direction ideal it just can help describe why it happened in the very first place.

A lesson from Warren Buffett

Warren Buffett is an fantastic illustration of an trader who knows just what match he is taking part in. Buffett has continuously admitted he is unlikely to outperform a raging bull industry mainly because he will not make investments in many development stocks and sticks generally to value. But he nevertheless believes he will outperform the S&P 500 over time — which has been true around his long-expression monitor record.

Berkshire Hathaway’s portfolio might glimpse overly conservative as it includes a whole lot of insurance coverage corporations, banking institutions, oil and gasoline stocks, and buyer staples companies. But for Buffett, these are the kinds of businesses he would like to make investments in. It really is his sport, and he’s playing the inventory sector according to his personal guidelines and chance tolerance.

An person investor has no command above the broader inventory industry. So, imposing regulate above our investment choices and type is the most effective way we can sense snug and obtain direction when stock prices appear to increase and drop randomly.

The silver lining

For lengthy-time period investors in shares like Shopify, the whipsaw price action of 400{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} gains followed by 80{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} losses in just a two-calendar year period of time can be complicated and annoying. It can be tricky to know a truthful cost for a enterprise when conflicting motives are tugging at its inventory value. On the other hand, there is a silver lining.

Around time, fundamentals generally acquire out. One glimpse at the stock charts of productive firms like Nike or Apple, and you can expect to speedily see that market-offs are basically par for the course for a profitable extensive-expression investment decision. The splendor of prolonged-expression investing is that it is a single of the number of games wherever the odds are in your favor. The stock sector tends to slide a lot quicker than it goes up but goes up much more than it goes down. The common compound annual development level of the S&P 500 with dividends reinvested given that 1965 has been all-around 10.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Which is a substantial tailwind for long-time period investors to reward from compound interest.

By investing in top quality companies that you realize and permitting time be an ally, an investor stands a better opportunity of ignoring the sounds of the sector and concentrating on what matters most.

10 stocks we like better than Shopify

When our award-profitable analyst group has a stock tip, it can fork out to hear. Right after all, the publication they have run for above a 10 years, Motley Idiot Inventory Advisor, has tripled the current market.*

They just discovered what they believe that are the 10 very best stocks for traders to purchase appropriate now… and Shopify wasn’t one particular of them! Which is appropriate — they think these 10 stocks are even improved buys.

*Stock Advisor returns as of April 7, 2022

John Mackey, CEO of Complete Foodstuff Market, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. Daniel Foelber has positions in Shopify and has the adhering to solutions: prolonged September 2022 $600 phone calls on Shopify and brief January 2024 $600 calls on Shopify. The Motley Fool has positions in and recommends Amazon, Apple, Nike, and Shopify. The Motley Idiot recommends the following alternatives: prolonged January 2023 $1,140 phone calls on Shopify, extended March 2023 $120 phone calls on Apple, brief January 2023 $1,160 calls on Shopify, and shorter March 2023 $130 phone calls on Apple. The Motley Idiot has a disclosure policy.

Standing Finance Committee approves additional $3b expenditure

Standing Finance Committee approves additional b expenditure


News


Finance Minister Colm Imbert during the Standing Finance Committee in Parliament on May 13. - Photo courtesy Parliament
Finance Minister Colm Imbert for the duration of the Standing Finance Committee in Parliament on Might 13. – Photograph courtesy Parliament

THE Standing Finance Committee of the Property of Reps authorized a sum of $3,081,703,900 in supplementary allocations for fiscal 2022, when it sat on Might 13.

The allocations address 80 heads of expenditure, some of which are governing administration ministries.

This approval took location forward of a 1.30 pm sitting of the Household of Reps on Monday when Finance Minister Colm Imbert will go a movement to undertake the committee’s report on these approved expenditures. After passing this motion, Imbert will open up debate on the Finance (Supplementation and Variation of Appropriation) (Fiscal Yr 2022) Invoice.

The presentation of this bill is recognized as the mid-12 months overview. The invoice will offer with issues contained in the committee’s report.

In advance of the committee approved an allocation of $95,357,000 for his ministry, Rural Progress and Neighborhood Governing administration Minister Faris Al-Rawi reported component of that allocation involved a sum of $50 million for the Neighborhood-Dependent Environmental Protection and Improvement Programme (CEPEP)

He spelled out that 92 for every cent of that $50 million is for the payment of CEPEP workers’ wages. Al-Rawi said there are at the moment 319 CEPEP contractors and 9,000 personnel in Trinidad.

He extra his ministry does not offer with the payment of CEPEP employees in Tobago. Al-Rawi noticed that Tobago House of Assembly (THA) Youth Advancement Secretary Terence Baynes has duty for CEPEP there.

“I have no remedy to give him.”

On May perhaps 10, Baynes reported extra than 40 CEPEP staff in Tobago had been fired.

Al-Rawi also said the ministry is undertaking an audit to establish the resources at the 14 regional government firms in Trinidad and what monies could be owed to them.

Couva North MP Ravi Ratiram claimed this was proof of bias against UNC-led businesses.

Al-Rawi replied, “There is anything essentially wrong below with comprehension.”

He claimed $130,000 was presented to each individual company to undertake routines below the ministry’s countrywide cleanse up marketing campaign. These routines have taken put at the Diego Martin Regional, Port of Spain Metropolis and Siparia Regional Organizations to day.

Agriculture Minister Kazim Hosein welcomed a $120,040,800 supplementary allocation to carry on his ministry’s work. Hosein mentioned a sum of $3.2 million in that allocation will be made use of to address challenges connected to the praedial larceny squad.

Other supplementary allocations approved ahead of the committee conference finished all-around 8 pm incorporated $97,033,000, $390,000,000, $67,000,000 and $20,000,000 for the Works and Transportation, Social Improvement and Family members Solutions, Activity and Group Enhancement and Tourism, Tradition and the Arts Ministries respectively

3 ways to save after buying a car | Smart Change: Personal Finance

3 ways to save after buying a car | Smart Change: Personal Finance

Believe it or not, there are ways to improve your car deal even after the ink is dry on the sales contract.

While you can’t lower the price of your car, you can usually cancel the extras you might have felt pressured to buy in the finance office. You can also shop for a lower interest rate and cheaper insurance.

As a result of the pandemic and related supply chain problems, dealers have fewer cars to sell. Demand for cars is high, so they’re loading each sale with extra products.

“I’ve seen as much as $6,000 of crap added to a Honda Civic” sale, says Christopher T. Smith, a California attorney who handles auto-related complaints for the firm of Glassey Smith — and a former car dealer himself. “Many people sign without reading the contract and only find out about them when they get home and read the contract.”

You may very well have read the contract and signed anyway, as many dealers make these extras a condition of sale.

People are also reading…

Common add-ons are the extended warranty — sold for between $2,000 and $7,000 for luxury cars — and gap insurance, costing as much as $1,000 at a dealership but available elsewhere for about $200, Smith says.

Most insurance products — extended warranties, wheel and tire coverage, “protection packages” — can be canceled, Smith says. Other add-ons are in a “gray area,” such as alarms and maintenance plans, and will be more difficult to cancel or have removed from the car.


While you can’t lower the price of your car, you can usually cancel the extras you might have felt pressured to buy in the finance office, as well as shop for a lower interest rate and cheaper insurance.


1. Request a refund

Most people finance their car so the extras are built into the loan, says Matt Jones, marketing director at TrueCar. Therefore, if you’re able to remove additional products, the refund is deducted from the loan balance. Your monthly payment doesn’t go down, but you pay off the loan more quickly.

If you cancel within 30-60 days, you’ll receive a total refund. If you wait longer, there might be a small processing fee and the refund will be prorated.

Before canceling an extended warranty, Jones says to “give it a good long thought.” The warranty is transferable and will sweeten the deal when selling to a private party. But if the warranty hasn’t expired and you’re going to trade in your car, cancel it “so you don’t leave any money on the table.”

The cancellation process

Not surprisingly, the dealership may not make it easy to cancel these lucrative contracts. The finance manager who sold you the extras “has a $200 incentive not to let you cancel,” Smith says. That’s because they’ll lose the commission they get for talking you into buying it.

Here are the steps to take to cancel your extended warranty and any other insurance plans you might have purchased:

  1. Review your contract. If you have the contract, look for the section on cancellation. In some cases you’re required to submit a written form and possibly have your car’s mileage verified by the dealer.
  2. Check online. Most manufacturers will have the terms of cancellation on their website. They can be hard to find but are often located in the FAQ section. If a written form is required for cancellation, it might be available for download from the website.
  3. Expect pushback. If you call the finance manager to cancel, they might try to drag their feet until their commission is secured, Smith says. Instead, go up the chain of command and contact the finance director or the dealership’s office manager.
  4. Document everything. Keep notes and records of who you spoke with and what needs to be done. Make copies of all the forms that are required.
  5. Set reminders. Don’t assume a friendly assurance from the dealership means that they’ll cancel the contract. Verify that your request has been met. In your calendar, set a date to follow up.

2. Refinance for a lower rate

If you financed through the dealership without first shopping for a loan, you might find you’re being charged an interest rate that’s higher than one you might have gotten on your own. The good news is that you can refinance your car loan at any time and possibly get a lower interest rate.

It’s easy to shop lenders to refinance a car and see the various rates offered. If your credit score improves, you can always try again later. Remember that the interest rate adds extra cost to the loan over time. Lowering the rate by even a percentage point will be a big savings.

3. Reassess your insurance carrier

When you buy a new car, it’s a good time to review your insurance coverage and carrier. You might need (or be required to have) higher coverage on your new car. Competing insurance companies might charge less than your current company and even add a new-customer discount to sweeten the deal. Comparing car insurance rates and coverage could be worth your time.

And while you’re checking for quotes, you can price out gap insurance and compare that with the coverage the dealer sold you. This will also mean you won’t have to pay interest on the insurance you were being charged in the car loan.

Before you commit to a new carrier, give your current insurer the opportunity to beat your new price, especially if you have a local agent.

Floridians see personal finance class requirement as a positive for students

Floridians see personal finance class requirement as a positive for students

Residents throughout north central Florida are optimistic about the probable impacts of a new law demanding a particular finance class for graduation.

Gov. Ron DeSantis not too long ago signed the evaluate that will involve superior college students to complete a half credit history course on particular finance just before graduation.

The regulation seeks to rectify a absence of economic literacy in the condition, as perfectly as prepare pupils for the difficult financial problems that may lay ahead. The need will choose effect for ninth quality college students moving into the 2023-24 school year.

“I believe I could have applied a class like this in high faculty,” Jenn Pearce, a resident of Putnam County stated. “When I obtained out of superior college, there was no fiscal class that prepared me for the real world. I struggled. I received into a lot of credit history card credit card debt. I acquired audited as soon as in my 20s because I messed a little something up in my taxes. It was a whole lot of trial and mistake.”

In accordance to the law, the new particular finance course would teach monetary techniques this sort of as balancing a checkbook, finishing loan apps, computing desire rates, contesting incorrect billing statements and computing federal revenue tax. It also calls for instruction about knowing forms of investments and forms of financial institution accounts provided.

The regulation produced Florida the 11th state to undertake a economic literacy need as a stand-by itself program, in accordance to CNBC.

Duane Hayslett, 41, stated he’s tried to educate primary economic concepts to his two daughters, who are both of those enrolled at Buchholz Large School in Gainesville.

“I went to cosign a lease for my daughter, and she did not know considerably about everything when it arrived to cosigning or anything like that,” Hayslett explained.He said he thinks a financial literacy study course would be most helpful.

“It need to be some thing that offers them the opportunity to get an strategy of what to anticipate when they go out on their individual,” Hayslett stated.

Scott Chapman, 40, of Cedar Key, reported he’s happy his daughters, who are 8 and 11, will benefit from the change.

“I believe it’s absolutely superb,” Chapman explained. “Because for the earlier number of several years, actually it appears to be, ‘go rack up $150,000 in university student financial debt, then determine it out and pay back it every time — with interest. You’re not taught about that in school.”

Chapman has bought and sold firms during his everyday living and has credited his success to having a robust knowledge of money setting up. He said he whilst is instructing his daughters about conserving – for case in point, by permitting them to make their have funds by means of dog going for walks – a structured class would help them study the fundamental principles, like what a credit history score is and why it matters.

The new personal finance course will swap an elective, transforming the graduation requirement of eight elective credits to 7½.

Logistics on how the regulation will really take condition in lecture rooms will be worked out as the state offers additional info on curriculum benchmarks, according to Jackie Johnson, director of communications for the Alachua County Community Educational institutions district.

Johnson mentioned the board doesn’t have numerous considerations about it other than making certain there is plenty of experienced staff to educate these courses.

“That’s always a concern that 67 districts are all hunting for instructors who are capable to teach financial literacy at specifically the very same time,” she reported.

Mildred Russell, a member of the Alachua County Faculty Board, claimed she does not see any will need to use supplemental personnel since of the many existing financial literacy courses presently in put.

They involve Buchholz High’s Academy of Entrepreneurship, which at the moment gives a extensive curriculum on particular finance and company development as aspect of its magnet plan.

Wendy Rosche, a trainer in the plan, stated she is eager to aid put into practice these changes as they arrive and would like to educate a private finance class if she has space in her program.

“To me, it is not just about budgeting it is really about job readiness,” she stated. “It’s about the entire photograph of using your next action in lifestyle and considering, ‘What do you want? What are your values?’”

Rosche mentioned she helps to orchestrate pupil involvement in Junior Achievement, a system in which substantial schoolers check out neighborhood elementary faculties to teach them money concepts.

“I assume kids often locate this applicable,” she mentioned. “They want to master how to deal with income. I have under no circumstances seen a class that did not love mastering about economic literacy.”

Rosche explained she hopes the course will also help youngsters who are on the lookout into college make wise monetary choices in the schools they select in conditions of tuition and housing. The ordinary pupil bank loan debt in Florida was $38,160 in 2020, according to Education and learning Data Initiative.

“We have a whole lot of men and women and a ton of resources to provide this for our youngsters,” Rosche claimed. “I’m optimistic.”