Zambia’s finance minister has criticised prolonged conversations about the country’s credit card debt restructuring, which have incorporated a Chinese contact for multilateral lenders this kind of as the Globe Lender to be involved in the approach, warning that the recovery of Africa’s 2nd-major copper producer was staying held back.
Situmbeko Musokotwane mentioned in an interview that “time is of the essence” to finish a restructuring of about $13bn of external debt this calendar year, three many years right after the southern African nation defaulted on it. Problems about delays have mounted considering the fact that China, the biggest creditor in the talks, previous thirty day period identified as for the Environment Bank and equivalent establishments to be provided in the restructuring.
Questioned regardless of whether he supported the notion floated by Beijing, he replied: “Discussions at bigger stages like these just make our scenario even worse, because what we are searching for is urgent methods, not discussions that could drag out the make any difference.” He extra: “We need to all just aim on and get the debt [relief] delivered.”
China is Zambia’s one biggest creditor, with about $6bn of infrastructure loans unfold amongst various Chinese financial institutions. About $3bn is owed to holders of all the country’s US dollar bonds.
Beijing’s demand from customers to include multilateral lenders would upturn a many years-outdated rule in sovereign lending that they must be exempt from credit card debt restructuring simply because they act as loan providers of final resort and cost very little fascination.
China previous yr agreed in principle to give Zambia reduction in tandem with other formal creditors by means of a G20 process acknowledged as the frequent framework.
But given that then, specific designs for a restructuring have stalled and left President Hakainde Hichilema’s government not able to obtain a $1.3bn IMF bailout or to resume spending its money owed.
China signalled its most current objection in January when a spokesperson for its foreign ministry said that “the critical to easing Zambia’s financial debt burden . . . lies in the participation of multilateral financial establishments and industrial creditors in the credit card debt reduction efforts”.
As effectively as conflicting with present policies, the need also signifies that Beijing objects to primary tenets of Zambia’s personal debt restructuring rather than haggling in excess of particular conditions.
On a vacation to Zambia very last month US Treasury secretary Janet Yellen termed China a “barrier” to a offer.
Multilateral growth loan providers make up less than $3bn of about $7bn of exterior credit card debt that Zambia excluded from the restructuring previous 12 months.
Lusaka has asked the remaining creditors to agree to reduce the in general price of their claims by about fifty percent, or a lot more than $6bn, either by way of having direct losses on principal or decreasing interest rates and extending reimbursement.
Beijing is identified to be reluctant to set any precedent for having direct haircuts on its financial loans to creating nations. But analysts have reported Chinese banks could lower their costs reduced adequate to meet up with Zambia’s debt reduction goal and continue to obtain more than Lusaka would pay multilateral lenders.
Right until official lenders agree to certain phrases, Zambia can’t easily protected a offer with personal bondholders. “We are involved about the delays, and we would have favored this to have occurred substantially a lot quicker,” Musokotwane explained.
But Zambia considered it was building progress with creditor engagements and could display its fiscal ideas ended up on observe, he said, introducing: “For the yr just finished, it has been just one of the ideal fiscal performances in many years,” with revenues and paying on target.
But this year’s finances and govt strategies to secure social spending assumed the personal debt restructuring would acquire position this calendar year, he included. “There are human beings guiding this . . . all this involves that the burden on our shoulders have to be eliminated.”
Some lenders have questioned the financial assumptions behind Zambia’s targets for credit card debt aid, such as a need to slash financial debt to underneath 90 per cent of exports by 2027, with some suggesting the degree could be larger. Others have explained it would be fairer for international traders in Zambia’s nearby currency bonds, currently excluded from the restructuring, to also acquire haircuts.
Any inclusion of domestic bonds in the restructuring would “would chance unravelling macroeconomic stability” and will not be considered, Musokotwane mentioned.
This article has been amended because very first publication to make clear that Situmbeko Musokotwane criticised delays in discussions about debt restructuring among Zambia’s creditors. He did not reject a Chinese phone to include things like multilateral loan providers in the personal debt restructuring, as at first said.
In the last 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of final 12 months, we heard a whole lot of communicate (and we at NPR did a whole lotofconversing) about the Terrific Resignation, aka the Massive Quit. This was a development that began suitable all-around the beginning of the COVID-19 pandemic, and observed — anecdotally, at least — significant figures of individuals leaving their work voluntarily. There was some controversy about the Big Stop, not the minimum since some reporting on the craze produced it audio as while many of these employees experienced resolved to leave the labor pressure endlessly.
But the difficult info — particularly listed here in the US — suggests that in reality the labor force participation charge, which plunged at the starting of 2020, recovered pretty quickly. That involved employees near to retirement age. Which suggests that persons weren’t actually quitting function entirely, but ended up, fairly, just switching employment — in many circumstances leaving jobs that compensated properly but demanded very long hrs, and obtaining jobs that most likely paid out considerably less but gave them much more handle in excess of their lives. In other terms, it was significantly less the Wonderful Resignation and a lot more the Terrific Reshuffle.
That’s surely the summary that Jill Schlesinger arrived at. Schlesinger is a qualified economical planner and a company analyst at CBS News. She’s also the author of a new e-book, The Excellent Revenue Reset, which attracts on her working experience speaking with callers to her individual finance podcast, Jill on Revenue. Numerous of those callers have been looking at their personal Huge Give up, but they weren’t absolutely sure whether or not they could do it, or how to go about it.
St. Martin’s Press
Schlesinger claims questions about switching work with a see to acquiring improved get the job done-lifetime harmony are not unheard of in the particular finance earth, but they became a good deal much more typical during the pandemic. She describes herself as inundated. And she claims that is the to start with in a quantity of huge adjustments that she thinks will impact the personalized finance environment going ahead.
What does that suggest? The information, evaluation and neighborhood discussion identified right here is funded by donations from individuals. Make a reward of any amount during the Wintertime Member Push to support this resource for anyone.
“Amid the pandemic, men and women who termed my present had been seeking more command around their time and function conditions,” she says. “With the gain of time and the silent of the pandemic, many concluded that they want to get the job done less or in different ways, enjoy more overall flexibility in their employment, do the job at a much less demanding occupation, or change to a new vocation. They really don’t automatically desire to forgo the comforts of daily life, but they are eager to make at the very least some monetary sacrifices in order to do it.”
It can be not only about the numbers
Financial sacrifice! That is not a phrase you listen to a lot in the individual finance world. That’s due to the fact, for the most component, particular finance professionals and planners are targeted on increasing assets, with an eye on a lengthy-term time horizon: retirement. In that world, the idea of monetary sacrifice won’t genuinely in good shape. Schlesinger believes the pandemic has adjusted that for the reason that buyers have been created acutely knowledgeable that they could not make it to retirement, and it is really a superior idea to feel about how to get pleasure from some of that income now. To variable that into the financial setting up method, Schlesinger claims, advisors are heading to have to get to know their consumers far better.
“What is actually hard for a great deal of economic planners is they will not like to get into the emotional stuff,” Schlesinger suggests. The very best — and most high-priced — planners do, of system: they see their purchasers as complicated human beings, who have numerous requires and messy life. Most of the fiscal solutions industry, nevertheless, is geared in direction of managing persons as widgets that are anticipated to have a certain everyday living span, punctuated by a unique retirement issue. You will find not considerably area for the human factor there. Schlesinger states good economical planners ended up previously turning towards that technique in advance of the pandemic hit.
“They understand that you cannot just hand a customer a listing and say, remember to populate the assets, liabilities, money costs,” Schlesinger says. “You basically have to discover about who they are. And I believe that the pandemic has accelerated that development.”
The reserve fund is the most important point
Schlesinger claims that ahead of the pandemic, she would give men and women some very common advice about their revenue. She would start by telling them about the a few mainstays of personal finance.
“I would say to folks, you happen to be just starting out. This is what you have to do: You need an emergency reserve fund, you have to have to pay back off your credit card debt, and you have to have to try out to put cash into retirement. And I would frequently give those factors equal weight.”
Men and women noticed the wisdom of paying out off financial debt and conserving for retirement, of study course. The crisis reserve fund? That was a more challenging sell.
“People today would yell at me and say, ‘How can you explain to people today to continue to keep six to 12 months of their dwelling charges in an account that’s having to pay no desire?’ For the reason that don’t forget during the pandemic and early days, it genuinely was {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} fascination,” she says. But the pandemic underlined the value of acquiring some variety of dollars cushion. “The individuals I spoke to who experienced unexpected emergency reserves, experienced money that they could tap into, went by the pandemic in a pretty diverse way than men and women who were being relying on stimulus checks and extended unemployment advantages.”
Now, she suggests, she nevertheless touts the 3 mainstays, but now the crisis fund receives a great deal additional consideration. And not just from her. “I believe article pandemic, far more people today understand that acquiring an crisis reserve fund — getting obtain to revenue that you can count on — has grow to be amount just one, two, and three.”
Anyone would like to chat about estate planning now
For most financial planners, the most difficult part of discussions is chatting about the close video game. People today are delighted to go over retirement all day lengthy. Just after all, they’re anticipating a fantastic time, when they can travel, or see household, and do all the issues they have place off accomplishing for forty yrs. But speaking about what happens to their cash and their property when they die? No one particular ever wished to talk about that right before the pandemic.
They do now.
“I no for a longer time have to combat with folks about getting estate scheduling,” Schlesinger states. “It’s been a intriguing change.”
Schlesinger suggests COVID-19 put finish-of-lifetime factors on to the front burner for a lot of persons. She read an in particular painful story from 1 caller, who instructed her about a blowup about a household enterprise. “A person died and there was a modest small business associated and there was no instruction. Like, ‘what are we carrying out with this small business? Perfectly, dad would’ve desired us to hold it, but mother really needs the revenue.'”
A family fight erupted because the dad or mum who died remaining no recommendations. Presumably not what the mum or dad had preferred to go away as their legacy. And undoubtedly not what the grieving relatives wished to go by.
“Everybody is aware of somebody who has a awful estate tale,” Schlesinger claims. The upside is that those people men and women compensated interest to people stories. Now they want to go over estate scheduling. But these are difficult discussions that power people to make hard possibilities, and the challenge now, Schlesinger says, is really obtaining her customers to put those ideas in location.
The triggers have transformed
It wasn’t unheard of for men and women to make massive adjustments in their life ahead of the pandemic, of program, but Schlesinger claims it was not particularly prevalent. Most men and women experienced a occupation and predictable trajectory to retirement that they did their greatest to stick to. There were normally only a handful of daily life events that could shift people from that trajectory. Divorce and loss of life were the huge kinds, she suggests, but the pandemic brought a good deal extra triggers to the fore: Psychological overall health adverse perform activities isolation.
“You happen to be residing this extremely bare, stripped down existence, and you are with your ideas, and you happen to be hearing about terrible points and it can be truly frightening,” she says, noting that in that context, abruptly a good deal of the selections we manufactured in order to reach a faraway economical goal did not look to make perception. “And perhaps that’s the instant you say, ‘why do I are living a thousand miles away from my moms and dads? Why have I preferred to work so challenging that basically I am not positive I actually like my career but I know I truly really like my little ones, and I never truly imagine I want to function this way anymore.'”
The massive barrier to creating alter — even when it appears the noticeable preference — is dread. But the way Schlesinger sees it, the pandemic compelled change on a substantial range of men and women. And they had to encounter those people fears.
“I just was so overcome by the quantity of persons who had been fearful. But who, the moment that worry started out to dissipate, really saw prospect amid all this chaos. And I’m not conversing about industry chance, I am speaking about everyday living prospect. What is it that I seriously consider I wanna do?”
She claims individual finance professionals and money planners are likely to want to appear to conditions with the fact that, in a unusual way, the pandemic manufactured individuals feel they wanted to consider handle in excess of their lives in a a lot more energetic way, and to advocate for their much more speedy wants and desires. Now it can be all right to search at your career objectives and your economic ideas for retirement and all the relaxation of it and say … What about me? In which does my in-the-minute contentment match into this?
Schlesinger has made large, daring shifts in her personal everyday living in the past: she gave up a worthwhile money arranging vocation to grow to be a writer, journalist, and podcaster — so she understands what is actually at stake. But it was the encounter of a close friend of hers, Maureen, that really introduced dwelling to her the worth of comprehension what the authentic motivations are for earning variations in your existence. And how to reply to them.
Maureen arrived to Schlesinger a number of yrs back for advice working with a significant prospective daily life modify — a divorce. It was a hard situation to contend with. But not extensive right after, things bought even harder. “Maureen was identified with a incredibly lethal cancer and she experienced a 4 month horrible illness and died on November 30th,” Schlesinger states. “Every person has a momentous function that shakes up your lifestyle. Everyone does. And you experience the anxiety. You truly feel feelings I feel even in myself as I went by that occasion with her, my personal capability to fully grasp how the choices we make issue, was amplified. And what I can notify you is that when you have the capability to plan in progress and use that to open up up pathways for you, it’s actually effective.”
Lighten up a small
Wild investing tactics have been all-around for as very long as marketplaces have existed, but the pandemic coincided with some of the craziest, like the meme inventory explosion and the crypto craze. Schlesinger thinks this experienced considerably to do with people remaining locked down, without the need of much to do, although there was a lot of revenue sloshing all over the program.
“When I say a large amount of funds sloshing all-around the procedure, keep in mind that we had trillions of dollars of excess price savings that crafted up. Mostly that came from the upper, best internet truly worth persons, but a ton of men and women have been information staff functioning at home who bought stimulus checks and had a lot of time to futz close to and experienced a several bucks in their accounts.”
She says the communities that fueled this kind of investing were not new, but they exploded in the course of the pandemic, and they will very likely diminish at the time COVID and its variants recede. But they will not likely go absent. And that’s okay. It is even all right to commit some time on your preference of subreddit and surf the occasional meme stock or crypto asset wave. So lengthy as you do it responsibly.
“I am not constitutionally in opposition to people taking flyers,” Schlesinger states. “I mean, have enjoyment, but don’t have entertaining and hazard the farm. Have exciting and say, ‘All right, I put 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of my total investments in some crazy stuff. Which is enjoyable.'”
In other phrases, personalized finance won’t have to be all asset allocation, earnings optimization, estate arranging and taxes. It can be pleasurable also — if you choose. Which is a new rule that absolutely everyone can get down with.
Obtaining engaged kicks off a single of the most remarkable instances in daily life. Amidst all the celebrations, nonetheless, partners really should be preparing to merge their finances.
“It’s crucial to have a conversation about financial debt in advance of receiving married, as it is a typical problem for several couples,” Levon Galstyan, accredited public account at Oak See Legislation Group, states.
“7 out of 10 individuals enter relationship with debt, so it’s critical to examine present personal debt, curiosity fees, timelines and the sacrifices that could need to have to be made,” he suggests.
Not sure wherever to begin? Here’s a nearer seem at financial debt immediately after relationship and a few critical points to go over for the duration of a economic test-in with your fiancé.
How Do Debts Impression Spouses After Marriage?
You usually will not be liable for credit card debt that your partner obtained right before you got married (and vice versa) but that won’t mean it will never affect you. Credit card debt payments effects a person’s disposable profits and what they’re ready to contribute toward shared charges.
On top of that, any credit card debt administration issues another person has created throughout the very last seven to 10 several years can negatively impression impression their credit score score.
“Your credit rating score is a critical facet of monetary scheduling, as it can effects your ability to invest in a automobile, hire an condominium or purchase a home,” Galstyan says.
If a single spouse’s credit score is bad, the other husband or wife can end up overextended. Credit score problems can also impede a couple’s route to ambitions like obtaining a household.
It is only fair that both companions are knowledgeable of the entire fiscal landscape right before the wedding ceremony day – no a single needs to be blindsided.
Remarkably, 3 out of fivepeople stated they would take into consideration placing off relationship to steer clear of inheriting a partner’s personal debt, according to a 2021 study commissioned by National Debt Relief and conducted by OnePoll.
Premarriage Fiscal Check out-in Subjects
A premarriage financial verify-in can be awkward and nerve-racking.
“Instead of straight away diving into the discussion about revenue, acquire the time to individually write down your money objectives for the close to long term, these types of as just one yr and 5 several years from now,” Galstyan suggests.
From there, you can share your plans and changeover into a discussion about how you will take care of fantastic money owed to attain them. While it is important to disclose any and all money owed through this chat, 3 styles are entitled to a little bit of additional consideration: scholar loan, credit rating card and tax personal debt.
University student Financial loans
Student loans typically depict sizable debt and can have a considerable influence on a couple’s funds. Look at that close to 42.8 million debtors have federal scholar bank loan financial debt and the regular stability for every borrower is $37,787.
To comprehend the influence of student loans on your long term with your wife or husband, Galstyan suggests inquiring queries these kinds of as:
How significantly college student personal loan debt does each particular person at this time have, such as the complete volume of all financial loans, moreover the interest charges and regular monthly payments?
How extended will it just take to pay out off the scholar financial loans and is possibly individual consolidating them or employing an revenue-driven reimbursement plan?
How do you system on shelling out off the university student loans and will you be prioritizing spending them off about other economic ambitions?
Will you be combining your funds or preserving them individual just after marriage? How will that impact having to pay the loan(s) off?
Is possibly particular person preparing on having out more pupil financial loans to continue on their training in the potential?
Credit score Card Credit card debt
Credit score card financial debt is one of the major a few most worrisome payments for Us residents, according to the 2021 Countrywide Credit card debt Relief study. It is really no wonder – the typical American owes $4,285 to $6,617 on their credit history playing cards.
To avoid probable issues, Galstyan recommends inquiring:
How significantly credit score card credit card debt does each individual at present have and what are the fascination rates linked with each individual card?
How considerably is every single man or woman at this time paying out toward their credit history card financial debt and how extensive will it just take to pay it off?
How does each person prepare on spending off the credit history card financial debt and will they be consolidating it or applying a personal debt management prepare?
Will you be combining your finances or keeping them separate just after marriage? How will that effect your credit history card payments?
How does each man or woman strategy on employing credit playing cards in the long term – and will you includeany expending limitations and ideas for paying off balances in entire each thirty day period?
Tax Returns
“It’s also important to consider how improvements in your profits, deductions and filing status will effect your tax liability, and to request the information of a tax qualified if essential,” Galstyan claims.
Make confident you disclose any remarkable tax debts both particular person owes. The authorities is generally prepared to do the job with taxpayers to settle the personal debt or established up a payment system.
You and your wife or husband can do the job collectively to determine out the most effective training course of action, which may well include finding assist from a monetary advisor or tax credit card debt reduction specialist.
Dig Further Into Your Revenue Beliefs
“After you have gone over these essentials, choose time to dig deeper with your likely lifetime partner. Financial debt can damage associations, but lousy cash patterns can wreck your whole life,” Howard Dvorkin, CPA and chairman of Credit card debt.com, suggests in a push launch.
“Couples searching towards marriage want to master about their partner’s income stories from childhood. Had been they advised selected points about cash that make it challenging for them to conserve, shell out correctly or prevent personal debt? These forms of discussions will assist couples program for more substantial monetary milestones like youngsters, homeownership and retirement,” he suggests.
The yr 2023 has begun on a strong and beneficial observe immediately after the turbulence of 2022. According to a Forbes Advisor survey (opens in new tab), 43{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Individuals are optimistic their funds will strengthen this yr as we glance to improve our financial protection and prosperity. Let’s discover some personal finance recommendations centered on the Year of the Rabbit.
What is the 12 months of the Rabbit? The Chinese rejoice their new yr on various dates. The Chinese calendar is based on solar and lunar cycles. The lunar calendar describes the 12-yr repeating cycles of the Chinese zodiac and is named immediately after an animal each and every 12 months. On Jan. 22, the Lunar New 12 months started in earnest. It is also known as the 12 months of the H2o Rabbit (opens in new tab).
Most animals in the Vietnamese zodiac are the very same as people in the Chinese zodiac. However, this year has distinctive variances (opens in new tab) considering the fact that the Vietnamese will celebrate the Calendar year of the Cat, though other Asian countries, this kind of as China, Taiwan, Singapore, Indonesia and Korea, will celebrate the Calendar year of the Rabbit. Tibetan and Mongolian cultures also celebrate the Lunar New 12 months one thirty day period later on, in February.
Subscribe to Kiplinger’s Individual Finance
Be a smarter, greater educated trader.
Help you save up to 74{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}
Sign up for Kiplinger’s Totally free E-Newsletters
Financial gain and prosper with the ideal of skilled tips on investing, taxes, retirement, own finance and much more – straight to your e-mail.
Gain and prosper with the finest of expert assistance – straight to your e-mail.
Some of the special traits of the cat incorporate velocity and acuity. Cats are quickly and sharp with every single depth because they will see factors you could not commonly recognize. They shift with pace and are smart and straightforward. They have a rapid considered method that allows them to carry out a ton of get the job done promptly.
The 12 months of the Rabbit requires generous worthwhile of earlier sacrifices. All the seeds of effort and hard work that you have sown will bear fruit and pay back off. Their sweetness is dependent on your purest intentions.
According to Chinese astrology, the rabbit symbolizes prosperity, peace, longevity and hope. The rabbit is the fourth animal in the Chinese zodiac and the luckiest of all animals. It symbolizes elegance, mercy, alertness, tolerance, intelligence and swiftness. Men and women born in the Calendar year of the Water Rabbit are peaceful and calm. They shy away from arguments and love wonderful points. They are artistic and pay awareness to facts. Rabbits are wise animals, and you can use their attributes to program for a prosperous fiscal foreseeable future.
Here’s how to use the rabbit’s personality to obtain increased monetary prosperity in 2023:
Sacrifice and Plant a Seed.
Fiscal liberty will remain a mirage if you expend all the things you earn. Debt owing to overspending will go away you pressured. Overspending can protect against you from attaining your economical objectives.
It would be very best if you ended up clever, like a rabbit. Sow seeds in terms of personal savings and investments to program for money resilience. Limited-time period preserving and lengthy-expression investing can enable you protect and construct prosperity. You can boost the total of funds you contribute to your retirement portfolio. Luck will come to people who have invested their methods.
Spend Focus to Information.
If you want to scale up, you will have to live like a rabbit or a cat. You must be warn and pay back interest to the specifics, these kinds of as variable interest premiums on any exceptional liabilities, these as lines of credit and credit history card debt. Command your credit history card financial debt by paying the superb equilibrium ahead of the interest accrues.
As you receive, make a regular budget with all the particulars. You should include things like the amount of money of income you get paid and how you expend it. Abide by your spending budget information and steer clear of minimal diversions. Tiny loses right here and there can switch into considerable losses. A spending budget can assistance you adhere to your aims and force you toward economic steadiness. Alertness aids you to know when you are drifting away from your plans.
Be Individual in Investing.
As you think about investing in stock marketplaces, you want a rabbit’s endurance to increase your investment decision portfolio. The most successful investors acknowledge that tolerance is the most difficult talent to master and observe. You need to devote in investigation and execute thanks diligence just before earning financial commitment choices. Investing with no patience can direct to unfavorable outcomes.
Use Your Intelligence to Make Gains.
Rabbits and cats are smart animals entire of intelligence and swiftness. The Chinese idiom “a crafty rabbit has a few burrows,” factors to diversifying your profits sources. Attempted-and-legitimate approaches, this kind of as diversification and dollar-price tag averaging, support you keep centered on your long-term targets and aims. Consistency is essential — be particular to align your chance potential and chance tolerance, as the most tough element of investing can be staying invested. Comprehension how to offer with possibility can imply the change concerning finding by in retirement and receiving forward.
While rabbits are some of the swiftest animals, you will need quiet to achieve a balanced life style. Calmness builds your self esteem and simplicity. In 2023, you ought to be inform to your ambitions and go swiftly absent from your interruptions.
This posting was penned by and provides the views of our contributing adviser, not the Kiplinger editorial staff. You can look at adviser information with the SEC (opens in new tab) or with FINRA (opens in new tab).
In the 3 months considering that artificial intelligence software ChatGPT was introduced to the earth, staff have currently harnessed it to make their lives a lot easier. Professionals in fields together with authentic estate, overall health treatment and finance say they conserve time and work far more proficiently employing AI.
This is how these employees described using the tool in their day-to-day positions.
Compose me a genuine estate listing
Mala Sander, a best real estate agent for the Corcoran Team who focuses on the Hamptons, has been using ChatGPT on a regular basis for the earlier pair of months to assist her compose authentic estate listings and devise marketing and advertising approaches for attributes.
“I requested it to generate me advertisement copy about a household in Bridgehampton with a pool and tennis courtroom on two acres and I outlined the other functions I wanted to emphasize,” she told CBS MoneyWatch. “And it would weave this excellent duplicate into something that you could actually use.”
She works by using ChatGPT to change the tone of listings way too. “I will say issues like, ‘write this toward a millennial audience’ or ‘make it amusing.'”
Major Hamptons real estate agent Mala Sander makes use of ChatGPT to help her write listings.
The Corcoran Group
Her regime these days is to have her group create the initially draft of a listing “and crunch it through to see if ChatGPT can edit it down and make it far more concise,” she stated.
On a whim, she asked the bot to generate her a promoting plan for just one of her listings. It shipped. It gave her a breakdown of a campaign that would include digital, print and social outreach, she explained to CBS MoneyWatch.
“It talked about every little thing from direct mail to on line electronic marketing to social media, and it even came up with some percentages that could be best,” Sander reported.
Obtaining worked as an agent for the past 20 a long time, Sander is quite capable and productive devoid of ChatGPT.
“But it is valuable,” she explained. “It truly is like speaking to an additional man or woman, nearly like possessing get the job done therapist to say, ‘Am I relocating in the ideal direction with this or should really be searching at some other issues?'”
Elia Mazor, internet marketing manager for The Glazer Team at Corcoran, explained he also utilizes ChatGPT to compose listings and produce other information.
“From time to time you get writer’s block, so I use ChatGPT for a little bit of inspiration and to give a distinct tone,” he reported.
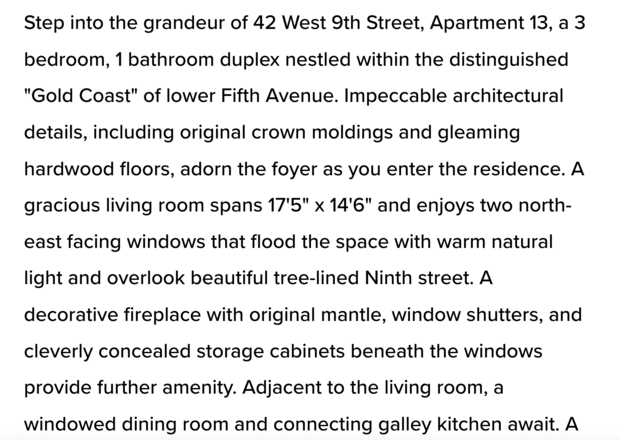
Mazor stated ChatGPT helped his crew publish the description of a new apartment listing on West 9th Street in Manhattan’s Greenwich Village.
The Glazer Workforce
Fiscal planner’s assistant
Accredited economic planner Michael Reynolds works by using the chatbot to enable him draft web site posts that educate his clients about economical files like wills and trusts.
He tells ChatGPT the subject matter he wishes to address, and enters a prompt like: “ChatGPT, create an introduction on why estate setting up is crucial.”
It spits out paragraphs that Reynolds then edits in his very own voice.
CFP Michael Reynolds mentioned ChatGPT aids him make content a lot quicker.
Elevation Economic
In a latest posting on estate preparing, Reynolds relied on ChatGPT to hook readers by driving house the message that “estate planning is an act of adore for these you leave behind.”
“I asked ChatGPT to make clear that and it set together a couple paragraphs on why it is really thoughtful and considerate to do these issues,” Reynolds claimed.
The system took about 20 minutes. If he’d labored on the post on your own, it would have taken closer to two hrs, he explained.
He will not use the instrument to enable customers make financial conclusions — that’s however a position completely for people, according to Reynolds.
“Money organizing is so nuanced, individualized and individual. It is difficult to imagine applying ChatGPT to spit out tips without the need of it understanding the shopper. I see it staying additional beneficial in building educational substance to nutritional supplement what I am accomplishing,” he mentioned. “We you should not just crunch numbers we coach people today, listen to their worries and assistance them discuss as a result of emotional scenarios. The artistic, empathetic get the job done we do as people is irreplaceable as of today.”
Nick Meyer, a further monetary planner who generates shortform videos on TikTok, mentioned he employs it as a commencing point to arrive up with suggestions for new material.
“I use it in its place of Google lookup to get matter ideas, or to edit what I have now penned,” he mentioned. It also assists him make his videos humorous.
“I can insert a few traces of a script and say, ‘Make this more comedic, insert a joke on this line, or make it much more concise,” Meyer said.
“Gobs” of clinical information
Board-accredited unexpected emergency doctor Harvey Castro is advising electronic wellbeing companies on how to ideal combine ChatGPT into the wellbeing treatment sector.
He states just one great software is creating and translating client discharge instructions — policies for them to abide by immediately after a professional medical check out.
An specialist in unexpected emergency medication, if he ended up questioned a dermatology-relevant dilemma he was not sure about, Castro said he’d enter the query into ChatGPT for a lot more info. In the earlier, he relied on other scientific lookup engines and means like MDConsult, now termed ClinicalKey.
“I could form it in and it would give me gobs of data. So it is really a dietary supplement,” Castro explained.
Medical practitioners are also employing it to enter a patient’s signs and have it return a differential prognosis — a list of possible ailments related to the presenting signs or symptoms, in accordance to Castro.
“That is currently happening currently,” he mentioned.
Microsoft revamps lookup engine with AI technological know-how
01:58
Review buddy
Rushabh Doshi, a second-12 months medical pupil at Yale College Faculty of Medication, likes to use ChatGPT to generate sample queries whilst he scientific tests for the U.S. Clinical Licensing Evaluation.
Take a look at prep companies have confined exercise questions, and ChatGPT can deliver new kinds on any subject dependent on the prompt he feeds it.
Yale med pupil Rushabh Doshi uses ChatGPT for medical information and facts and training.
Courtesy of Rushabh Doshi
It aids him get ready for some affected person interactions, as well, but makes use of it strictly for medical education and learning and not affected person treatment.
“If there is a client coming in with a disease I am not common with, I can go to ChatGPT and browse up on it,” he mentioned.
It also gives him information that assists him conduct much more complete affected individual evaluations. “I check with it to give me a guidebook of the styles of questions to talk to to make sure I am executing a comprehensive client job interview.”
Finance work opportunities are developing and just one role within just the economical work opportunities market that is attracting a substantial quantity of candidates is accountancy. These are the most in demand finance employment in the earth according to new investigation. In addition, auditing is the most in need finance career between aspiring employees. These are patterns that relate to the U.K. employment sector.
A new review from CMC Markets, an on-line trading system, analysed regular Google searches making use of Ahrefs for jobs in the money field to see which profession is the most in demand from customers.
Queries for ‘auditor’ ranked range a single on the list with 222,500 month-to-month Google lookups. Persons are seeking 5,000 situations on ordinary a thirty day period for ‘auditor jobs’ and 500 moments for ‘auditor careers’. There are now 785 auditor jobs in the finance sector on Without a doubt.
Actuarial careers arrived closely guiding as the second most sought-following work in finance with a put together 166,600 queries for every month for ‘actuary careers’ and ‘actuary jobs’. An actuary was the only job within the insurance plan sector to make it into the major ten. There are now 1,030 actuary work opportunities within the finance sector on Indeed.
The 3rd most desirable finance career is corporate banking which amassed a complete of 96,280 Google searches per month, 1,200 of which ended up for the research term ‘corporate banking jobs’. There are at the moment 3,748 corporate banking positions on Without a doubt.
Another banking career took the fourth spot with financial institution teller totalling 43,250 Google searches just about every month, 12,000 of these regular monthly searches ended up for ‘bank teller jobs’. At present, there are only 35 bank teller jobs on Certainly.
In fifth place came forensic accounting with 39,650 Google queries per thirty day period and the sixth most in demand occupation in finance was a compliance officer with 35,170 regular Google lookups.
Regardless of getting one particular of the ten most attractive finance careers, forensic accounting only yields 64 position openings in the United kingdom, in accordance to In fact. On the other hand, there are at the moment 6,685 compliance officer openings in the United kingdom on Without a doubt.
With 29,080 Google searches a month, a client advisor was the seventh most searched for finance profession and there are 811 work openings for consumer advisor roles on Indeed.
Mortgage officers and branch professionals occupied the eighth and ninth position on the checklist with 22,950 and 18,560 every month Google queries respectively. There are 1,744 roles on In truth for the two loan officers and department managers in the U.K. The research discovered that the tenth most in need occupation in finance is a danger manager with 17,430 regular Google searches. There are at this time 5,259 task openings on In truth for chance supervisor roles in the U.K. Michael Hewson, chief marketplace analyst at CMC Marketplaces tells Digital Journal: “Despite the scarcity of work opportunities in some industries, it would seem that there is a obvious desire inside of various sectors of the finance planet. It is intriguing to see that a substantial proportion of this selection is manufactured up of queries connected to the banking sector. And as a entire, economical occupations are being searched for 2,935,840 periods per thirty day period on Google.