A provision in Delaware’s corporate legislation allowing for captives to cover Aspect A directors and officers liability risks will open more possibilities for policyholders and was crafted with the latest D&O court rulings in mind, the state’s prime captive regulator stated.
The legislation will help captive homeowners to protected D&O in coverage in a tricky sector in which fees have improved significantly over the earlier two a long time, said Steve Kinion, director of Delaware’s Bureau of Captive & Economic Insurance policy Solutions.
He was talking at Small business Insurance’s Earth Captive Discussion board, held in Miami previous week.
“There are some exclusions in the monthly bill, which is a person of the initially situations that I know of where by company regulation dictates what a captive insurance plan plan can and can’t say,” he reported.
Delaware SB 203, which was signed into legislation past week, will allow captive insurers in any domicile to give Aspect A D&O protection for Delaware businesses. A lot more than 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of publicly traded firms are included in Delaware.
Prior to the evaluate, Delaware and most other states did not allow for businesses to indemnify directors and officers for specified forms of lawsuits, like derivative lawsuits submitted by shareholders alleging misconduct by corporation officials. In its place, companies bought Aspect A D&O coverage from professional insurers to safeguard their administrators and officers from this sort of fits.
A handful of other states have language in their company rules that imply that Aspect A can be presented by means of a captive but none particularly point out that captives can be used, Mr. Kinion claimed.
The Delaware regulation specially addresses so-named Caremark statements, which relate to a 2019 Delaware Supreme Courtroom ruling that identified that business administrators at an ice cream maker at the center of a fatal listeria outbreak had been liable in a D&O accommodate, he stated.
The regulation excludes coverage for conditions these kinds of as the Dole Meals scenario, in which the Delaware Supreme Courtroom dominated very last year that a D&O plan really should protect a loss similar to an fundamental scenario where fraud was alleged.
“There’s far more restrictive language in SB 203 that applies to captive insurers than when compared to the professional sector,” Mr. Kinion reported. “That was a general public plan final decision that was produced.”
The statute also bars protection for own fraud by administrators and officers, but the exclusion only applies soon after a non-appealable final decision has been reached in a scenario, he stated, noting that much more than 95{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of D&O scenarios settle prior to this kind of conclusions.
The regulation also features provisions to make sure an arm’s size marriage concerning a captive and a policyholder, this kind of as the necessity for an unbiased claims administrator, Mr. Kinion reported.
Although captives providing Facet A protection for Delaware corporations do not have to be domiciled in the state, there may well be some advantages to domiciling the captive in Delaware to steer clear of likely conflicts with regulations in other states, he claimed.
Delaware, even though, lets the development of branches of captives formed in other states, Mr. Kinion mentioned. In addition, captive entrepreneurs can tailor their possess protection by applying a fronting arrangement and then reinsuring the risk in a captive.
OMAHA, Neb. (AP) — Warren Buffett’s organization positioned a exceptional guess on a technological know-how corporation late very last year and it has already paid out off in a large way.
Berkshire Hathaway uncovered in paperwork filed with regulators on Monday that it bought in the vicinity of 15 million shares in match publisher Activision Blizzard through the last a few months of 2021.
The obtain arrived not long prior to Microsoft’s announcement in January that it was getting Activision for $68.7 billion, sending the stock soaring. Activision’s shares are up 22.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} so significantly this 12 months.
Berkshire estimated that its 14.7 million shares in Activision Blizzard, the maker of Sweet Crush and Call of Duty, ended up value roughly $975 million at the conclusion of 2021. At the shut of investing Monday, they ended up really worth $1.19 billion.
Political Cartoons
The financial commitment by Buffett’s firm was a stunning move by the famously tech-averse trader. Buffett has lengthy avoided investing in tech organizations for the reason that he says it is much too difficult for him to choose the lengthy-time winners in that sector.
The other adjustments to Berkshire’s around $330 billion portfolio uncovered Monday have been extra common for Buffett, such as expanding an financial investment in oil giant Chevron, eliminating a stake in Teva Prescribed drugs and trimming its investments in various other drugmakers.
Buffett and other Berkshire officials don’t remark on these quarterly inventory filings, and the experiences do not point out no matter if either 1 of Berkshire’s two other financial investment managers manufactured the moves. Buffett normally handles all the company’s more substantial investments value far more than $1 billion apiece such as its key stakes in Apple, Bank of The us and Coca-Cola, so the measurement of the Activision Blizzard investment indicates Buffett built that decision.
Berkshire ongoing rebuilding its Chevron expenditure in the fourth quarter when it picked up practically 10 million shares, but the stake of 38.2 million shares stays smaller sized than the 48.5 million shares it held when it initially uncovered the investment decision a 12 months ago. Berkshire sold off a significant chunk of its Chevron financial investment in the to start with 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of very last calendar year.
Buffett’s organization offered off the 42.8 million Teva shares it held and trimmed its holdings in other pharmaceutical firms Bristol Myers Squibb, Abbvie and Royalty Pharma.
Berkshire also removed a $266 million expense in Sirius XM all through the quarter.
It revealed a new investment decision in Brazilian fintech NU Holdings that went general public in December. Buffett’s corporation held 107 million shares of NU Holdings at the conclusion of the calendar year.
In other moves, Berkshire minimize down its investment in skilled solutions business Marsh & McLennan and trimmed its holdings in Mastercard, Visa and Charter Communications.
Aside from investments, Berkshire owns additional than 90 companies outright, such as Geico insurance, BNSF railroad, and numerous main utilities. The conglomerate also owns producing, furniture, shoe, jewelry, chocolate, underwear and brick providers.
Copyright 2022 The Linked Press. All legal rights reserved. This content may perhaps not be posted, broadcast, rewritten or redistributed.
Dare I say it, but this calendar year is shaping up to be the year of the finance “super app.” Given that the beginning of the yr, I have found no considerably less than seven firms talking about making a super application.
Now, let me be crystal clear below. I am not chatting about a tremendous application like WeChat and Alipay in China. All those providers offer just about every little thing inside an application, from getting groceries, scheduling journey, trip-hailing, as nicely as each form of fiscal supplying you could imagine of.
Some people today have mentioned that The us is not a put to embrace tremendous applications. And that is likely accurate if we assume about the China design in which these tremendous applications are extra like finish ecosystems akin to the iOS or Android operating program.
But I believe there is a genuine opportunity for a foremost fintech (or financial institution) to create a tremendous app for finance. As I have now claimed, quite a few have started off on this journey.
Which brings up the essential problem: what must be provided in a finance super application?
Given the recent breakthroughs in open banking and embedded finance, we have the technologies to make a definitely compelling super application.
In this article are 20 matters I would like to see involved:
Digital bank account with debit card – all the common choices readily available today.
Higher yield savings account – higher yield signifies trying to keep pace with the Fed Funds Price.
Peer to peer payments – be capable to interface with various p2p payment networks.
Established price savings plans – with individual buckets to park this money.
Buy Now Fork out Later on – built-in BNPL performance.
Procuring – this could be built-in with BNPL but must consist of most common outlets.
Loyalty programs – there must be a central location to handle these.
Prompt transfers to outside financial institution accounts – why is this not normal now?
Shopper loans – the tremendous application will have adequate info to offer immediate mortgage approvals.
Credit rating playing cards – provide a assortment of rewards and no payment playing cards.
Overdraft safety – no overdraft expenses and the skill to accessibility up to $100 quickly.
Inventory investing – this is no for a longer time optional for a major finance app.
Crypto trading – ought to be capable to buy and provide the key crypto tokens.
Financial debt management – Assistance consumers control all their credit card debt for optimum desire cost savings.
Acquired Wage Accessibility – entry section of your paycheck early to spend for emergency costs.
Credit constructing and monitoring – give a pathway to setting up a credit rating score.
On-ramp to DeFi – this is probable some time absent but I believe it will be required of a finance super application in the long run
Join outside the house investments – the super application should be capable to see all/most of your investment decision accounts.
Open up banking connections – see all the areas in which your financial institution account information has been shared.
See total money photograph – dashboard with KPIs to give you a apparent photograph of web really worth and how your fiscal existence is trending.
This last level is specifically interesting to me. Most firms currently evaluate a array of essential performance indicators, and many of the compact enterprise apps have handy dashboards that exhibit the business’s wellbeing at a look. But we really don’t genuinely have an equal thought for consumer finance crucial efficiency indicators past a credit score rating.
I would like to see the finance super application deliver far more economical intelligence. It should response how lots of weeks or months we can deal with with our savings, how our totally free cash stream is trending, full financial commitment returns (if any), how our debt load is trending, and extra.
Who is closest to establishing the finance tremendous application?
We are however far absent from any enterprise coming near to the features I described earlier mentioned.
PayPal is probably closest, but they only have all-around 50 percent of the characteristics I would like to see. SoFi, fresh new off internet hosting the Superbowl in their shiny new stadium, has possible as they have in all probability the broadest offerings of the new breed of fintechs.
Chime, the largest electronic bank in the U.S., has a extended way to go with a constrained element set to day.
MoneyLion is also a organization I am seeing carefully as they preserve incorporating new characteristics often.
In Europe, Revolut has the broadest established of options, so we don’t want to count them out in this article.
Digging deeper into the finance super application
FT Partners unveiled an fantastic report titled The Race to the Super App earlier this thirty day period. It implies two different versions or avenues to a finance super application.
For my vision of the tremendous application, only a single of their designs makes sense but what I preferred about this report is that it delves into the choices of every single significant fintech in the place.
We are likely to have many finance tremendous applications ultimately. I really don’t consider this is a winner requires all group. There are probably to be 2-3 companies that get critical traction and a number of other people with enough consumers to make their enterprise worthwhile.
I also consider the fintech providers will be in a position to cost for this service. A subset of capabilities should really be free of charge to encourage mass adoption, but a finish aspect established could be so worthwhile that a regular price will be feasible.
One particular closing observe. A person business does not want to establish all this features in-property. There could be partnerships where a 3rd celebration gives the procedures, but it resides within the super application from a user point of view. With this in intellect, it could very well be a financial institution that makes the ultimate finance super app in the very long run. But as of right now, fintechs have the direct. The race is on.
Peter Renton is the chairman and co-founder of LendIt Fintech, the world’s initially and biggest electronic media and situations organization targeted on fintech. Peter has been crafting about fintech given that 2010 and he is the writer and creator of the Fintech A single-on-A person Podcast, the initial and longest-running fintech job interview sequence. Peter has been interviewed by the Wall Street Journal, Bloomberg, The New York Instances, CNBC, CNN, Fortune, NPR, Fox Company News, the Financial Situations, and dozens of other publications.
When Alli Williams married her partner in 2019, she realized she would be marrying into about $150,000 of scholar mortgage financial debt.
Now, a few many years later, she and her partner have gotten on the identical money web page with their budgets and lender accounts, and they’ve compensated off not only his pupil loans but also their credit score playing cards and their truck. Williams experienced turn into credit card debt-free independently when she was 25, and now, at 30, the few are credit card debt-totally free alongside one another.
“Paying out off financial debt is not the challenging portion,” Williams says. “Running your cash is the more durable component.”
Williams, a South Carolina-dependent cash coach and operator of FinanciALLI Focused, says that when she and her spouse acquired engaged in 2018, that was the to start with time they established a combined budget. They maintain their spending very low and gain from residing in a lower-value area, and they’ve been strategic about working with percentages of windfalls to fork out off debt and to conserve. But the actual essential, she claims? Recurrent interaction and test-ins about cash.
Income can be a quite personal and — at situations — nerve-racking ingredient of a romantic partnership. Dealing with debts, financial institution accounts, credit cards and expenditures together isn’t really only a logistical problem, it is also a new avenue for potential conflict. If just one fifty percent of a couple likes to help save income though the other particular person is a compulsive spender, that pair will likely have to have to have some complicated conversations to stay away from resentment in the prolonged run. For all those conversations, there are professionals who can give steerage and perception.
Men and women are also reading…
Benefits of a financial advisor for partners
Very similar to a therapist, a financial advisor or funds coach can produce a risk-free room for couples to examine troubles and plan for their futures alongside one another.
Liz and Dan Carroll, an Oregon-primarily based couple and homeowners of Conscious Money Coaches, have been married for 31 yrs. They use their personal success with cash management to deliver actionable advice to their shoppers, these as educating them how to create extended-phrase funds plans collectively.
“Everybody is a very good candidate for at least an once-a-year test-in with a income mentor,” Liz states. “And just like with the compound curiosity you get with investing, the previously you start off the greater.”
If you and your partner choose to perform with a qualified monetary advisor as a substitute of a dollars mentor, make positive to decide on a single that operates as a fiduciary, which indicates they’re obligated to place your interests ahead of financial gain. Nonfiduciary economic advisors make commissions from products they sell to their clientele, so they could force clientele to invest in or make investments in solutions that aren’t essentially helpful.
What choices do couples have for handling their money with each other?
There is no a person-measurement-matches-all remedy to controlling your finances, especially if you are element of a few. Some partners favor to have all of their dollars combined, other people like to retain their funds wholly individual, and some prefer a hybrid of the two. No issue the tactic, couples can use joint accounts to regulate shared bills and conserve for unique aims.
The Carrolls really don’t advocate that married couples separate their finances, nonetheless. Even if one particular husband or wife has debt or a very low credit rating score, they suggest that both of those partners consider on the duty of operating by economic stumbling blocks as a staff.
“Placing it with each other produces in general accountability,” Liz suggests.
“Couples generally convey their individual burdens and strengths into a relationship,” Dan provides. “So if you’re going into a partnership, you have to take that you are going to take the superior with the negative.”
A idea from the professionals: Produce a price range just for ‘fun money’
Joint funds never automatically imply that you have to eliminate your autonomy. Williams and the Carrolls use a procedure in their associations that they say results in a sense of independence while being aligned on their funds: budgeting “pleasurable revenue” into person accounts for every human being.
“It’s like our ‘no questions asked’ cash,” Williams claims. “It is funds the place we don’t have to check in with just about every other prior to we expend it, like my partner paying out $10 at Chick-fil-A, or me paying out dollars at Amazon or Concentrate on. We use Ally Bank’s buckets attribute for our personal accounts, and we technically every single have accessibility to the two, but we really don’t want to test it.”
The Carrolls use a comparable solution for their pleasurable dollars.
“It’s continue to a line merchandise on the spending plan where by all the things comes into one particular bucket, and then some goes out into the enjoyment investing accounts,” Dan suggests. “We extremely suggest that each and every partner receives an equal amount of money, and then they can do whatsoever they want with it. It produces freedom for both of those men and women.”
Funds administration and interaction are foundational competencies for any committed intimate partnership, and, as Dan Carroll can attest, people competencies spill above into other places.
“It really is unanimous from the opinions we get from our clients that conversing through revenue will help the entire partnership.”
The posting For Valentine’s Day, Few Your Finances at first appeared on NerdWallet.
Get the most current neighborhood business information sent Totally free to your inbox weekly.
We planned our excursion to Turks & Caicos quite very last minute, just a few of times in advance of departure. I needed to share my working experience with the entry necessities, given that they’re kind of straightforward, but also variety of challenging. I didn’t see a complete ton about this on the internet in advance of our pay a visit to, so with any luck , my knowledge can support many others, How News Today.
Turks & Caicos entry prerequisites
At the time we planned our vacation, there have been four main entry demands for Turks & Caicos (allow me emphasize that travel limitations are frequently shifting, so examine the Turks & Caicos’ formal website page for recent restrictions):
All readers 16 yrs of age and more mature need to be absolutely vaccinated (nevertheless there’s no requirement to be boosted)
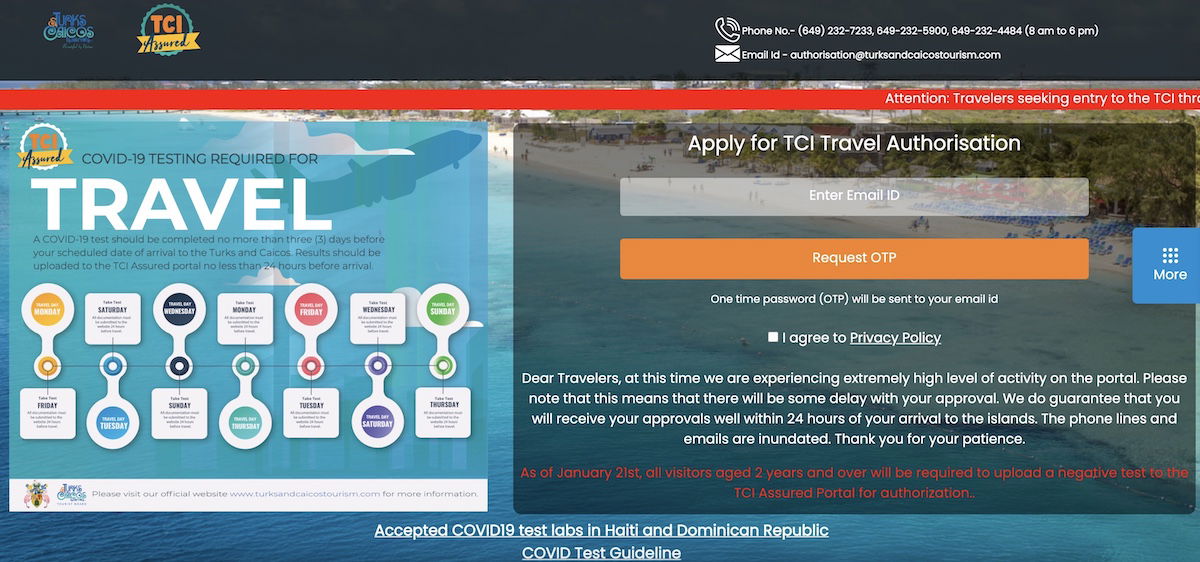
A adverse COVID-19 test end result is expected within just 3 times of vacation possibly a PCR or swift antigen take a look at is sufficient, and kids below two yrs previous are exempt from this necessity
Unique COVID-19 healthcare insurance policies that addresses any expenditures you could incur as a consequence of acquiring coronavirus
A done vacation authorization type, submitted at the very least 24 hrs in advance of your trip
The need to be totally vaccinated is really simple, and needing a take a look at pre-journey was also uncomplicated, presented that a immediate antigen does the trick (and those people are uncomplicated to get with speedy benefits). So let me communicate a bit about the pre-vacation Turks & Caicos journey authorization, the insurance need, and my experience on arrival, How News Today.
Turks & Caicos travel coverage
Turks & Caicos demands journey insurance policy that covers coronavirus clinical fees and complete hospitalization, health professionals visits, prescriptions, and air ambulance. The adhering to are the proposed insurance policy providers:
Travelex
Seven Corners
TripMate
Aura
HTH Planet Extensive
Allianz Worldwide Aid
Generali Insurance policies
World-wide Rescue
HDI World-wide
Travel Guard
Journey Insured International
Trawick
Arch RoamRight
Apex Journey Limited
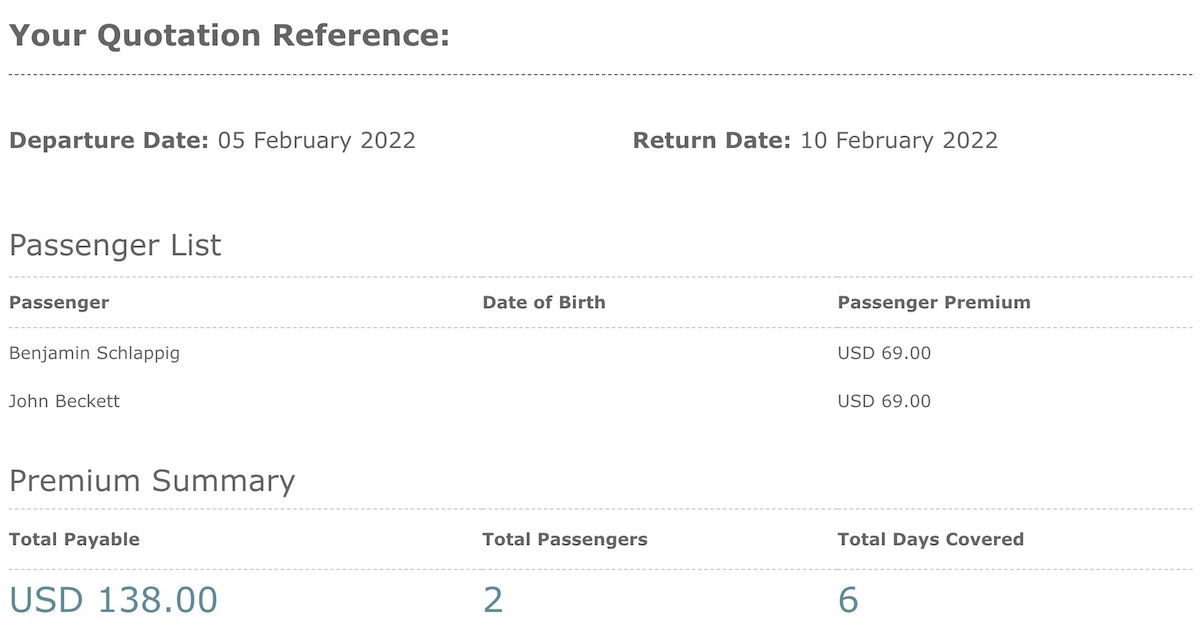
Just after doing some Googling, I made the decision to go with Aura insurance policies, and the course of action of finding insurance coverage was very simple. The business expenses $9.80 for each human being for every day, but the minimum price is $69 for every individual for each excursion.
On the moreover aspect, finding insurance policies was easy — it took only a couple minutes, and I was issued a plan promptly.
Sad to say credit score card insurance coverage won’t qualify for this necessity, so this does incorporate to the price of a journey to Turks & Caicos. Then all over again, other nations around the world charge bigger entry charges.
Turks & Caicos vacation authorization
Turks & Caicos necessitates all website visitors to complete a journey authorization prior to journey. It’s recommended that you submit this at the very least 24 hours prior to journey, however it is observed that “shorter periods can be accommodated, How News Today.”
The genuine facts requested with the vacation authorization was approximately what you’d expect. I initial had to sign up and then get a a person time password.
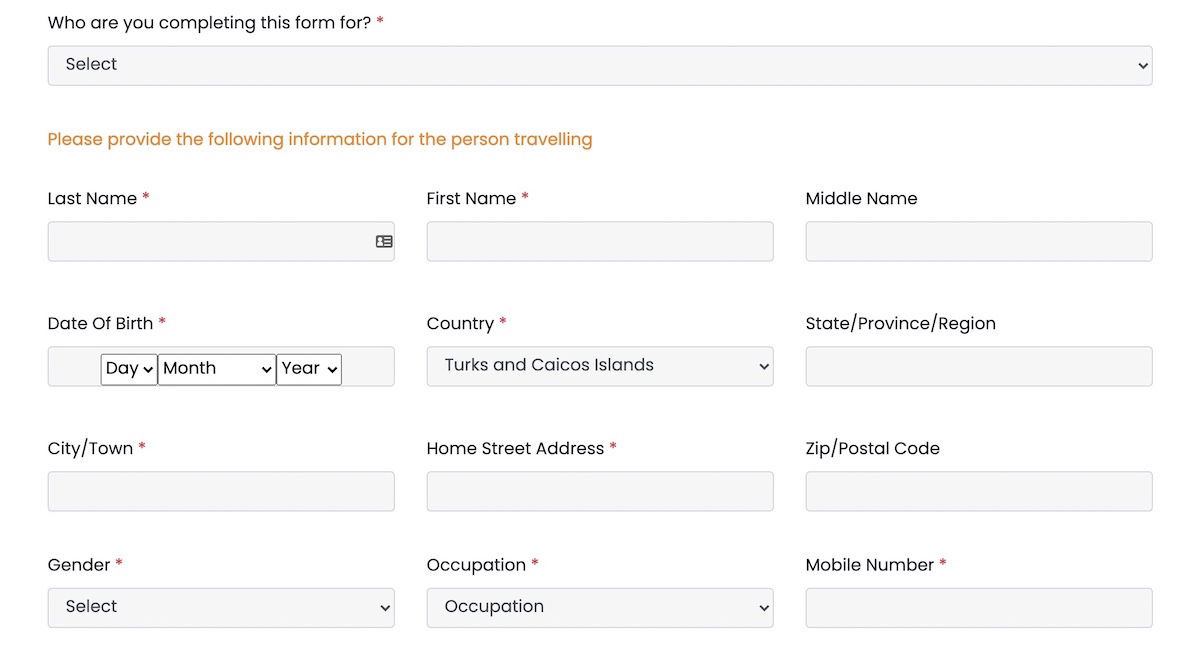
I then had to deliver personalized info, which includes my title, day of birth, deal with, profession, and more.
Oddly you are questioned if you have any family members traveling with you, but then you have to have to fill out a independent variety for them anyway, so I just experienced to supply the very same info twice.
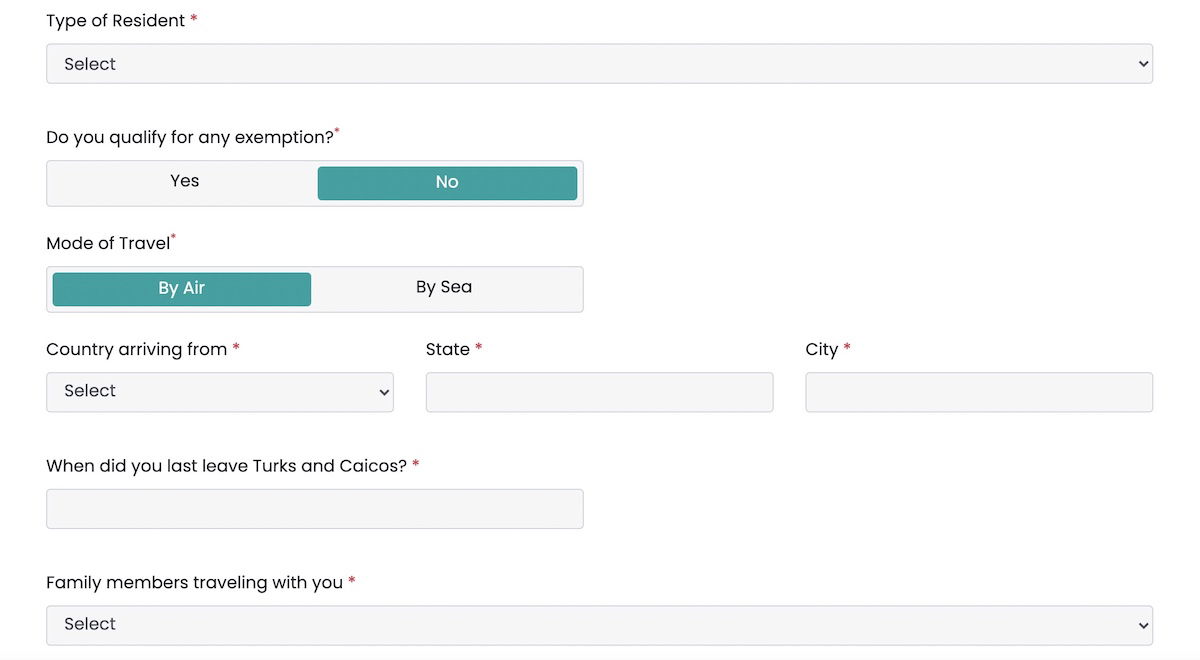
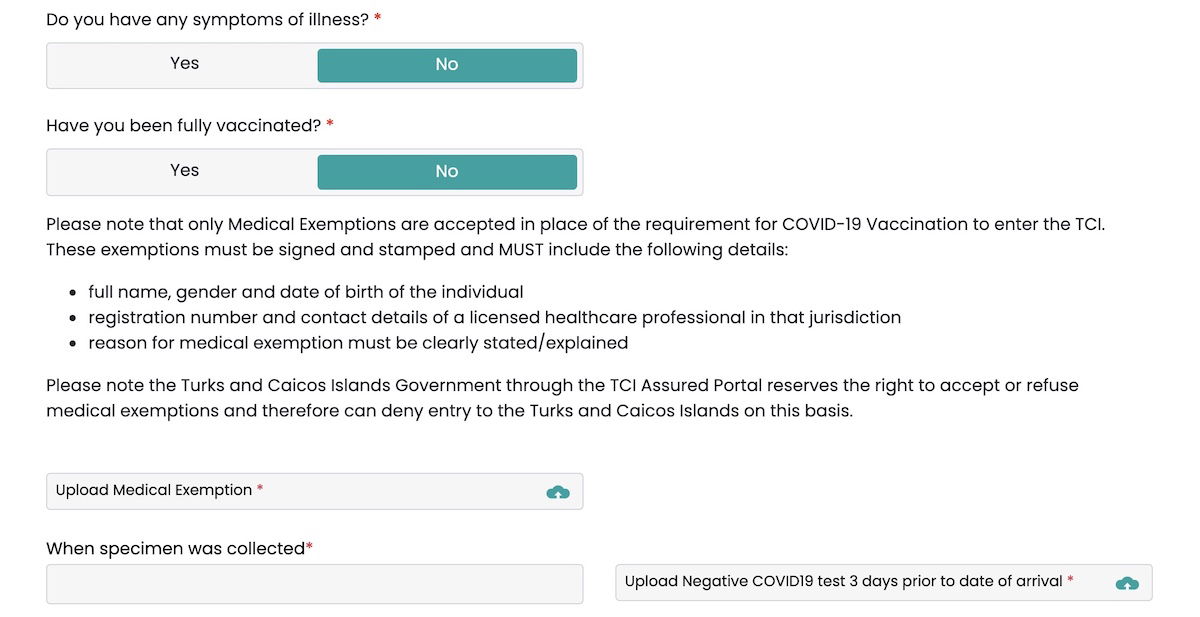
Then I had to fill out a well being questionnaire, and was asked to add pictures of my vaccine card, unfavorable coronavirus test, and travel insurance policies.
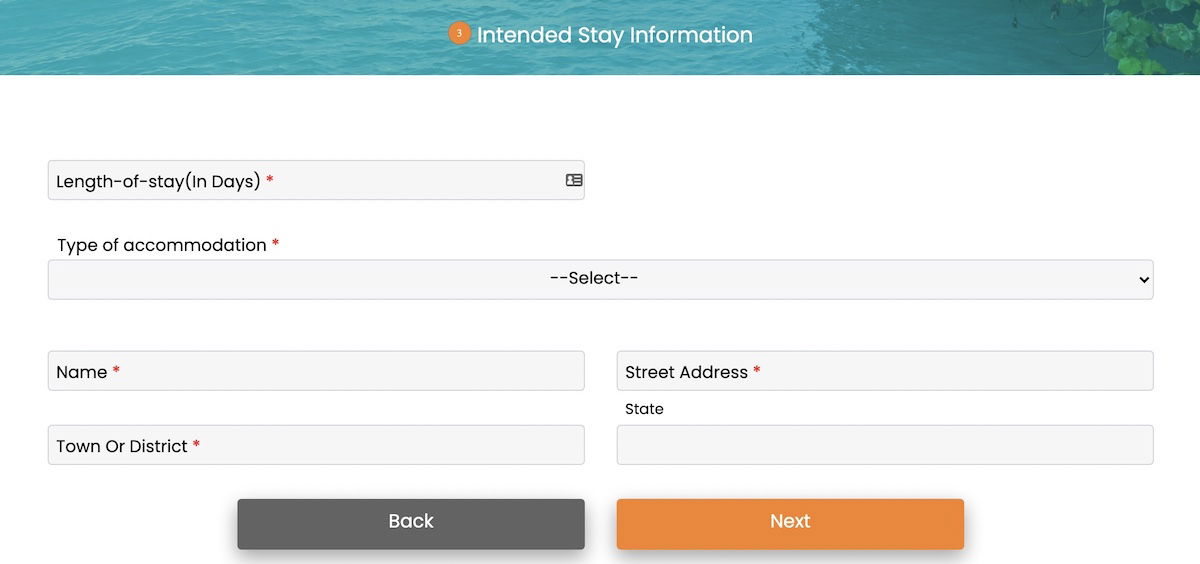
Finally, I was questioned about how lengthy and where by I was preparing on remaining in Turks & Caicos.
I submitted the kinds all over 26 several hours prior to our flight from Fort Lauderdale to Providenciales.
Just about an hour after submitting these documents, I acquired an e mail confirming that all the things experienced been accredited. Despite this authorization, I nevertheless experienced to give all of these paperwork though checking in for my flight.
Turks & Caicos arrivals experience
Fortuitously when we arrive in Turks & Caicos there were no other planes that landed all around the exact same time, so there was pretty much no wait there.
Right before getting to the precise immigration officer, we experienced to after again clearly show our vaccine playing cards, evidence of negative exams, and our travel authorizations. This was all quick adequate.
1 swift factor to be aware — we genuinely lucked out that there was no hold out at immigration, while I have also read of a lot of people today obtaining to hold out an hour or much more right after immigration, relying on how a lot of other flights arrive around the exact same time.
That’s why I believe it is at the very least value currently being knowledgeable that Turks & Caicos has a VIP arrivals services. For $75 for every particular person you can get a rapid keep track of by immigration. That would have been a full waste of money in our situation, but if you arrive at a well known time and would normally have to hold out an hour, I’m confident that’s a price quite a few folks would be keen to shell out.
An additional factor to note, while we’re at it. When you land at Providenciales Airport there are no private taxis available for use. The only options are shared vans that will likely prevent at several resorts. This is not necessarily that inefficient (it possibly additional 15 minutes to our driving time), but if you want a personal transfer you will have to arrange it in progress.
Base line
Turks & Caicos is open to vaccinated site visitors, even though there are some hoops to bounce via. You want to get tested inside of three days of travel (immediate antigen exams are ok), you need to invest in vacation insurance plan (which will charge all-around $10 for each particular person for every working day), and you have to have to fill out a pre-vacation authorization sort (preferably 24 hrs just before departure).
None of this was a big inconvenience, and we also lucked out that we arrived at a time when the airport was empty, so there was no wait at immigration.
If you’ve traveled to Turks & Caicos, what was your expertise with the entry prerequisites?
The investing information presented on this web page is for academic purposes only. NerdWallet does not offer advisory or brokerage companies, nor does it advise or recommend investors to purchase or market unique shares, securities or other investments.
A person of the least complicated approaches to regulate your cash better this yr is to hit the stick to button on some finance influencers. With out obtaining to do a lot operate at all, you are going to get a standard dose of own finance know-how in your social media feed, e-mail inbox or your queue of podcasts.
We talked to some of our beloved Black monetary professionals about the Wonderful Resignation, acquiring a residence in a aggressive housing market and regardless of whether investing in crypto is a fantastic thought.
1. Bola Sokunbi
We asked Bola Sokunbi (founder of Clever Woman Finance) what suggestions she’d give to task hunters:
“While you appear for operate, even even though your income could possibly be restricted ideal now, one particular point you have control in excess of is crafting a economic strategy for financial savings, credit card debt reimbursement, investing, and so on. You can also spend this time while you glance for perform to focus on budgeting and running the income and methods you have obtainable to you now. Don’t be frightened or ashamed to do the job down below your talent set or for much less spend for a momentary period of time, if you will need to have profits coming in ideal absent.”
2. Dasha Kennedy
Dasha Kennedy (The Broke Black Female) stated folks should embrace remote opportunities, irrespective of whether that is freelance operate or networking on the web:
“Don’t underestimate your means to use the competencies you’ve uncovered from your previous employer to gain revenue as a freelancer.
“If you are nonetheless in search of full-time work, proceed to community remotely. I believe that that the foreseeable future of perform is heading to be digital. The latest work local weather has forced quite a few businesses to obtain talent in unconventional ways these types of as social media, digital events and online occupation fairs.
“There’s at present a wave of people utilizing their transferable competencies to change professions and go into perfectly-having to pay, distant-dependent positions that are the full reverse of their earlier [jobs]. Ideal now is the excellent time to know when to pivot.”
Far more: If your work doesn’t give you purposeful perform, you owe it to on your own to sign up for the ‘Great Reshuffle’
3. Mandi Woodruff-Santos
Mandi Woodruff-Santos
mandimoney.com
We asked Mandi Woodruff-Santos (of MandiMoney) on what to take into account prior to shifting jobs:
“Just due to the fact the Excellent Resignation is taking place and a large amount of men and women are quitting, it does not always signify that this is the most effective time to give up for you.
“You’ve obtained to sit down with by yourself and ask by yourself, what is it about this position that is preserving you here? Am I receiving paid my current market charge? Do I feel like I have a great occupation progression in advance of me below?
“If the answers are no, then it could pretty effectively be time for you to go on. Also, proper now, it is hella competitive. So, if you want to stop appropriate now and get started wanting for jobs, get ready for a incredibly, yeah, really crowded market. There is a lot of individuals on the lookout suitable now. It’s not heading to be as quick or as straightforward as it might have been a number of years back for an individual on the lookout to soar ship.”
If you do have a career, Woodruff-Santos is a significant proponent of taking benefit of your retirement accounts:
“It’s not hot. It’s not remarkable. But for most Us residents, primarily most operating People in america, the 401(k) is it. 401(k) is bae, as I like to say, and not more than enough people today are even on the lookout at their 401(k)s. What am I investing in? Am I maxing it out for the calendar year? That’s what people ought to be asking by themselves.”
Also see: ‘Backlash is real’: Certainly, your workplace is probably racist — but how do you even get started to tackle this issue?
4. Michelle Singletary
Michelle Singletary (columnist at The Washington Submit) claimed “feelings are not points,” so if you approach to depart the workforce, leave with a fiscal plan: “Be sure you know how you can control your funds if you are likely to be in amongst jobs.
“If you’re retiring, be sure to do a retirement spending plan. And I imply genuinely crunch the figures. So quite a few people who retire early conclusion up possessing to go again to perform since they underestimated the charge of living, considering that retirement usually means you devote considerably less. You are going to even now have to eat and in all probability will try to eat out. You are going to continue to want to trip. You’ll nevertheless have housing fees, car or truck repairs, and so on.”
Also, she reported, possible homebuyers want to spending plan carefully, also.
“If you are in the sector for a home, really do not lose your perspective on what you can pay for. Don’t just use the qualifications the loan company takes advantage of. Sure, on their paper, you may perhaps seem to be equipped to pay for that home but they are employing your gross earnings. They may well not consider your need to have to go away space in your funds to conserve for an emergency fund, retirement or college or university costs for any youngsters you have.
“When my spouse and I shopped for our first residence, we didn’t purchase as a great deal dwelling as the lenders claimed we capable for. We realized we wished to aggressively help save for our retirements — and we have. We realized we didn’t want to consider on debt to send our kids to higher education — and we did not and neither did they. We realized we preferred to spend off our home finance loan in advance of we retire — and we will. We couldn’t have accomplished all that if we acquired a property finance loan that wouldn’t go away a lot area for these priorities.
Read through: ‘Mortgage charges jumped to the greatest degree considering that the emergence of the pandemic’: People in america are pessimistic about buying a household
“And most importantly, don’t think about yourself a failure if you can’t compete and nevertheless have to lease. Never pay attention to individuals who say you are throwing your cash away. You are not. You are receiving some thing for that lease — a roof above your head.”
5. Kenneth Chavis IV
Kenneth Chavis IV (senior prosperity manager at LourdMurray) mentioned housing prices will just maintain likely up. “If you lease and prepare to do so for a although, make positive you issue in long run rent hikes into your funds and shelling out options. Relying on the metropolis you dwell in, your rent could maximize 10-20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on your subsequent lease, so you will want to be fiscally well prepared for this fact.
Kenneth Chavis IV
LourdMurray
“For people that are hunting to purchase a house, owning a house is often significantly additional pricey than men and women expect, so be guaranteed that the dimensions, locale and facilities of the residences you are looking at match your income and spending budget. If you approach to invest in a house extra than a few months out, it is most effective to program for a 5-10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} boost in your home acquire price for the exact household.”
And Chavis claimed house sellers aren’t the only winners in today’s competitive marketplace.
“The labor marketplace is very related to the housing market place correct now — it’s a historically excellent time to be a vendor! As workers, we are, of class, ‘sellers’ of our skills, time and the like. So, I would recommend any individual who is searching for get the job done or considering leaving their latest position to be selective and come to feel empowered to negotiate for particularly what you want, regardless of whether it be better flexibility, far more payment, more paid time off, etcetera.”
6. Rianka R. Dorsainvil
Rianka R. Dorsainvil
2050WealthPartners.com
Rianka R. Dorsainvil (co-founder of 2050 Prosperity Associates) reminds investors that crypto is just one of quite a few techniques to reach your economic aims:
“Although the cryptocurrency area can provide a community come to feel, know that staying an investor is an particular person sport. 1st, identify what your monetary plans are, and then use expenditure automobiles that will enable you attain people goals.
“Beware of the temptations to ‘get abundant fast.’ Though cryptocurrency is legitimizing, I advise consumers to tactic investing with a prolonged watch. And I’d suggest having a nicely-proven discounts/slush fund right before dipping your toe into the marketplaces.”
7. Lauryn Williams
Lauryn Williams (founder of Well worth Winning) is aware of a factor or two about likely speedy. She is an Olympic medalist in each the women’s 4x100m race and two-woman bobsled. Williams mentioned investing isn’t one of those people issues that people today require to race into:
“I believe there is a great deal of distracting information on in the media right now about investing, and it can be very harmful to people mainly because a large amount of people are operating on some foundational aspects of their finances, these kinds of as having to pay down debt and creating an crisis fund, and all they are hearing all the time is, ‘if you are not investing, you are not serving to on your own, you are not earning your funds operate for you.’ I feel it’s actually vital that men and women have a baseline emergency fund in location ahead of they start out investing, and then, use the instruments that are easy and commonly obtainable, like your 401(k).
“I always inform my customers that investing is the moving walkway that can help you get wherever you want to go. You really don’t want to be fancy. You really do not need to be selecting shares. You really do not want to be undertaking all these different matters that the distractors are indicating you will need to do.”
Read through: ‘Black history is American history’: How to educate yourself and do the job toward racial fairness this month (and further than)
Additional about the influencers
Kenneth Chavis IV is a accredited money planner and a senior prosperity manager at LourdMurray. Chavis has been quoted in countrywide finance media publications and interviewed on the Black Information Channel on retirement arranging, investing, tax organizing and the economy.
Rianka R. Dorsainvil is a certified economic planner, as properly as the co-founder and co-CEO of 2050 Prosperity Companions, a digital, cost-only comprehensive economic arranging agency committed to serving business people, first-generation wealth-builders, and flourishing professionals in their late 20s, 30s, and 40s. She also hosts “2050 TrailBlazers,” a podcast and instructional system aimed at addressing the deficiency of range in the economical scheduling career.
Dasha Kennedy is the creator of the award-profitable fiscal advocacy group, The Broke Black Female. As a digital local community chief, she gives culturally appropriate fiscal literacy assets to around 70,000 Black girls to combat the racial and gender prosperity gap. Kennedy empowers her group to take a private accountability approach towards monetary security even though she advocates for financial justice on their behalf.
Michelle Singletary writes The Colour of Money for The Washington Publish, a twice-a-week particular finance column that appears in dozens of newspapers across the state. She is also the creator of 4 publications on private finance.
Bola Sokunbi is a qualified economical instruction teacher, finance pro, bestselling creator, speaker, and founder of Clever Girl Finance, a economical instruction system and local community for gals empowering them to realize monetary wellness and reside existence on their possess phrases.
Lauryn Williams is a accredited monetary planner and founder of Well worth Profitable, a virtual, price-only financial setting up organization. Williams and her team enable youthful pros get the solutions to the financial inquiries that make any difference most to them. She also hosts Well worth Listening, a podcast encouraging listeners to get started acquiring monetary conversations and choose manage of their cash tales.
Mandi Woodruff-Santos is an inclusive prosperity-developing advocate, vocation mentor and co-host of the well-known podcast Brown Ambition. She’s a frequent contributor to Yahoo Finance Are living. Observe her on Instagram and TikTok @mandimoney.
Much more From NerdWallet
Alana Benson writes for NerdWallet. E-mail: abenson@nerdwallet.com.
Elina Geller writes for NerdWallet. E mail: egeller@nerdwallet.com. Twitter: @themissmiles.
Meghan Coyle writes for NerdWallet. E-mail: mcoyle@nerdwallet.com. Twitter: @inkwaves.
Rosalie Murphy writes for NerdWallet. E-mail: rmurphy@nerdwallet.com.