BANGKOK (AP) — Japanese beverage large Kirin Holdings claimed Monday it has made a decision to withdraw from its joint venture in Myanmar.
Kirin, owner of the San Miguel, Extra fat Tire and Lion brand names, said its board designed the selection to “urgently terminate” the partnership with Myanma Economic Holdings Plc, a military-affiliated enterprise, following locating it would be tough to immediately stop the undertaking in the way Kirin needed to.
The business announced more than a year ago that it was not happy with a Feb. 1, 2021, military services takeover that violated its company benchmarks and human rights plan.
The military services ousted the elected govt of Aung San Suu Kyi triggering mass nonviolent protests nationwide. When the military and law enforcement responded with deadly pressure, armed resistance arose in the towns and the countryside in a intense wrestle for ability.
Political Cartoons
But Kirin had been making an attempt to retain its beer enterprise in the region and get MEHL to promote its stake, expressing it required to guidance its personnel and aid the state. Now, Kirin intends to sell its 51{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} stake, but not to MEHL, Kirin said.
The business stated it hopes to finish its withdrawal by June. No names of opportunity potential buyers of its stake were disclosed.
Human rights activists urged Kirin to “divest responsibly” and stay away from payments to the armed service administration and MEHL. Some opponents of the armed forces experienced urged the Myanmar general public to boycott solutions made by the undertaking, Myanmar Brewery.
Previously, Kirin sought business arbitration in a dispute with MEHL over its system to unwind the joint undertaking. MEHL experienced petitioned for liquidation of the undertaking, which Kirin said violated the joint undertaking agreement and was an “unjustified movement.” A court a short while ago ruled against MEHL’s petition, citing a technicality.
A response from the Myanmar firm was not immediately obtainable.
Myanmar Brewery, founded in 1995, provides beers underneath the Myanmar, Kirin Ichiban, Andaman Gold and Black Shield manufacturer names. It was unclear if the brewery would proceed to make Kirin Ichiban following the enterprise ends.
Kirin claimed it was recording an impairment reduction for 2021 on its business enterprise in Myanmar of 68 billion yen ($580 million).
It is one particular of the handful of Japanese businesses that have signaled they will go away the nation subsequent final year’s coup. Japanese firms are active in manufacturing and genuine estate and aided establish an industrial zone to the south of its premier city, Yangon.
Copyright 2022 The Linked Press. All rights reserved. This materials might not be posted, broadcast, rewritten or redistributed.
Open up finance proceeds to be a important topic in the entire world of fintech as firms tap APIs to obtain customers’ fiscal accounts and provide a gamut of integrated and embedded fiscal products and services. In the most up-to-date advancement, Stitch — a single of the prominent gamers setting up and functioning these APIs in Africa — confirmed to TechCrunch that it has lifted $21 million in Sequence A funding.
This news follows the $4 million Stitch lifted out of stealth in February 2021, a prequel to the $2 million extension round it secured 4 months in the past, bringing its seed spherical to $6 million. In complete, Sew has elevated $27 million to date.
The South African API fintech enables corporations to establish, improve, and scale fiscal solutions. For each a statement launched by the business, it ideas to develop a“financial graph” ecosystem across Africa with the new funding.
The firm describes the monetary graph as an infrastructure for money making blocks that allow firms to publish code as soon as, start in multiple markets and scale a lot quicker centered on interoperability throughout areas, companies, banking companies, and other styles of economic accounts.
“We type of look at the broader monetary ecosystem as a bunch of diverse nodes–bank accounts, retailers these kinds of as fintechs or end-consumers–which are all intrinsically related,” Stitch CEO Kiaan Pillay stated to TechCrunch in an interview. “Often, we believe about the reality that these connections between geographies and institutions really don’t exist however. And a lot of what we check out to do is to bridge those connections and to make these connections ubiquitous.”
Stitch sights this graph in three phases. The initially is what it introduced from stealth: the pure infrastructural engage in of connecting financial and bank accounts with an API. The second seeks to receive retailers and businesses to build use circumstances and apps on leading of that infrastructure. And the final is getting stop customers to website link their accounts by means of these companies.
“On the large degree, individuals moving from money to digital for the quite initial time will cause much more fragmentation. Our check out is that encompassing this all in 1 network or graph assists to open up the place up and break down the silos,” stated Pillay. “And the way we in the end feel about that is that people today can very easily move dollars between many applications concerning several geographies and establishments.”
Stitch’s delivers remedies for e-commerce organizations, marketplaces & platforms and its leading clientele, fintechs. As with other many years, African fintechs outperformed other startups in increasing venture funds, particularly in a record-breaking 2021 where by they raised 50-60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of complete VC funding for every reports. Their relevance can not be overstated and infrastructural gamers these kinds of Stitch, Mono, Okra, Plaid and OnePipe —all who lifted cash within just the earlier calendar year, some in seed and some others, Sequence A — are pivotal to that collective development of driving monetary inclusion and relieve of payments across the continent.
These business customers use Sew for use instances these kinds of as KYC & onboarding, personalized and company money administration, lending, wallet prime-ups and e-commerce checkouts. The platform’s info, and identity goods enable companies to entry client transaction histories and balance info, validate account facts, and complete fraud checks. The payments products allows bank-to-bank transfers for a person-click fork out-ins and payouts.
Some consumers consist of wallet-based organizations these kinds of as Chipper Money and Luno embedded finance providers like ImaliPay subscription platforms like FlexClub and payment aggregators like Yoco.
Sew
Impression Credits: Stitch
In April 2021, Sew introduced its payments solution in South Africa and seen a 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month-on-thirty day period growth in payments volume the pursuing 6 months. In October, Stitch expanded the payment product or service to Nigeria and, at the time, was on keep track of to facilitate $10 million in month-to-month payments by December.
On the contact, Pillay, who co-started Sew with Natalie Cuthbert and Priyen Pillay, did not give any update on this metric but reported Stitch experienced viewed a 104{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} thirty day period-on-thirty day period progress in payments worth considering the fact that launching the product or service previous April. And in Q4 2021, the platform witnessed a 44{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} thirty day period-on-thirty day period client advancement and a 72{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month-on-month increase in joined economic accounts.
“We’re very pleased of the partners and customers we have below as we go on to deepen the payments merchandise and glimpse at regular and recurring payments, which are interesting attribute sets for us,” explained Pillay.
“We lately experienced a couple clients go are living in Nigeria, which has been pretty exciting for us. We just offer you payments there but are keen to deepen the merchandise. We will search at introducing data and identification this yr, as perfectly as deepening the payments established in the same way to how we have it in South Africa.”
New York-dependent extensive-time period financial commitment company The Spruce Dwelling Partnership led this spherical of funding. The spherical also welcomed participation from new and current buyers like PayPal Ventures, TrueLayer, firstminute funds, The Raba Partnership, CRE Enterprise Funds, Village World, as well as fintech founders and corporations this kind of as TrueLayer, founders of Chipper Money, Quovo and Unit, and Guillaume Pousaz’s Zinal Expansion.
“We have been adhering to startups in Africa for many years. Our diligence was pretty clear that this is one of the most talented groups on the continent, and we are enthusiastic to be a component of what they are developing at Stitch,” said Ben Stein, co-founder of The Spruce Residence Partnership.
Pillay says increasing dollars from VC corporations and operators that have scaled fintech goods throughout several geographies offers the organization “something very special” as it enters its future progress period. The funding, Stitch claimed, will permit it to expand its workforce throughout places of work in Cape City, Johannesburg and Lagos, start new product or service choices and enter new marketplaces throughout the continent.
Last year, Aimy Steele discovered something she had never seen before in the world of personal finance advice: lessons that felt culturally relevant to her, and inclusive of her experiences.
Steele is no stranger to that world, and she’s extremely familiar with the financial gurus who have become the faces of paying down debt, budgeting and saving. She met Dave Ramsey after completing one of his programs and has avidly followed the teachings of David Bach and Suze Orman. But as a Black woman, Steele found that the advice from the traditional personal finance industry never felt truly relatable.
“We can’t compare our stories and our oppressive experiences with that of our white counterparts, and then still say, ‘But I’m supposed to be doing the exact same thing they’re doing,’” Steele says. “If I don’t see someone who looks like me, then I don’t explicitly link my fate to them.”
So Steele, 42, took matters into her own hands. She signed up for dfree, a faith-based personal finance program specifically designed for the Black community. Created in 2005 by DeForest B. Soaries, Jr. — a retired pastor of First Baptist Church of Lincoln Gardens in New Jersey — dfree walks participants through training courses and connects them with financial professionals. For three months, Steele logged into the program weekly from her dining room table, listening to facilitators discuss homeownership and debt elimination in the face of oppression. She felt much less alone.
And she isn’t alone. Many people of color have long felt left out of the traditional personal finance space. Experts say that much of the industry approaches advice as though all people are on equal footing. But systemic barriers have led the median wealth of white families to rise to about $184,000 while that number remains much lower for families of other or multiple races — at just around $23,000 for Black families and $38,000 for Hispanic families, the communities facing the biggest wealth gaps.
For years, dfree participants have been meeting up weekly in Black churches, sororities and community organizations across the country to learn about paying off debt, insurance and more, all while blending in conversations around racial inequality. Steele recently brought the program to her own church and became certified to facilitate the course. She says her dfree experience wasn’t only transformative because of the financial advice she took away, but also because the program acknowledged the discrimination Black Americans have faced for years.
“Hearing people talk about the fact that there is oppression validates what we have been feeling, thinking and knowing but could not articulate,” Steele says.
So do we throw all traditional personal finance advice out the window? Of course not. Countless people have changed their lives thanks to mainstream money tips. But making room for new faces, new products and new ideas in a world that has been so white-dominated for years is a necessary step — and it’s happening. There’s a movement growing outside mainstream finance narratives that highlights control and empowerment, and it’s being led by people of color, willing to reach an audience in whatever way they can. Getting there is the tricky part.
‘Trauma can last generations’
Money; Courtesy of Rahkim Sabree
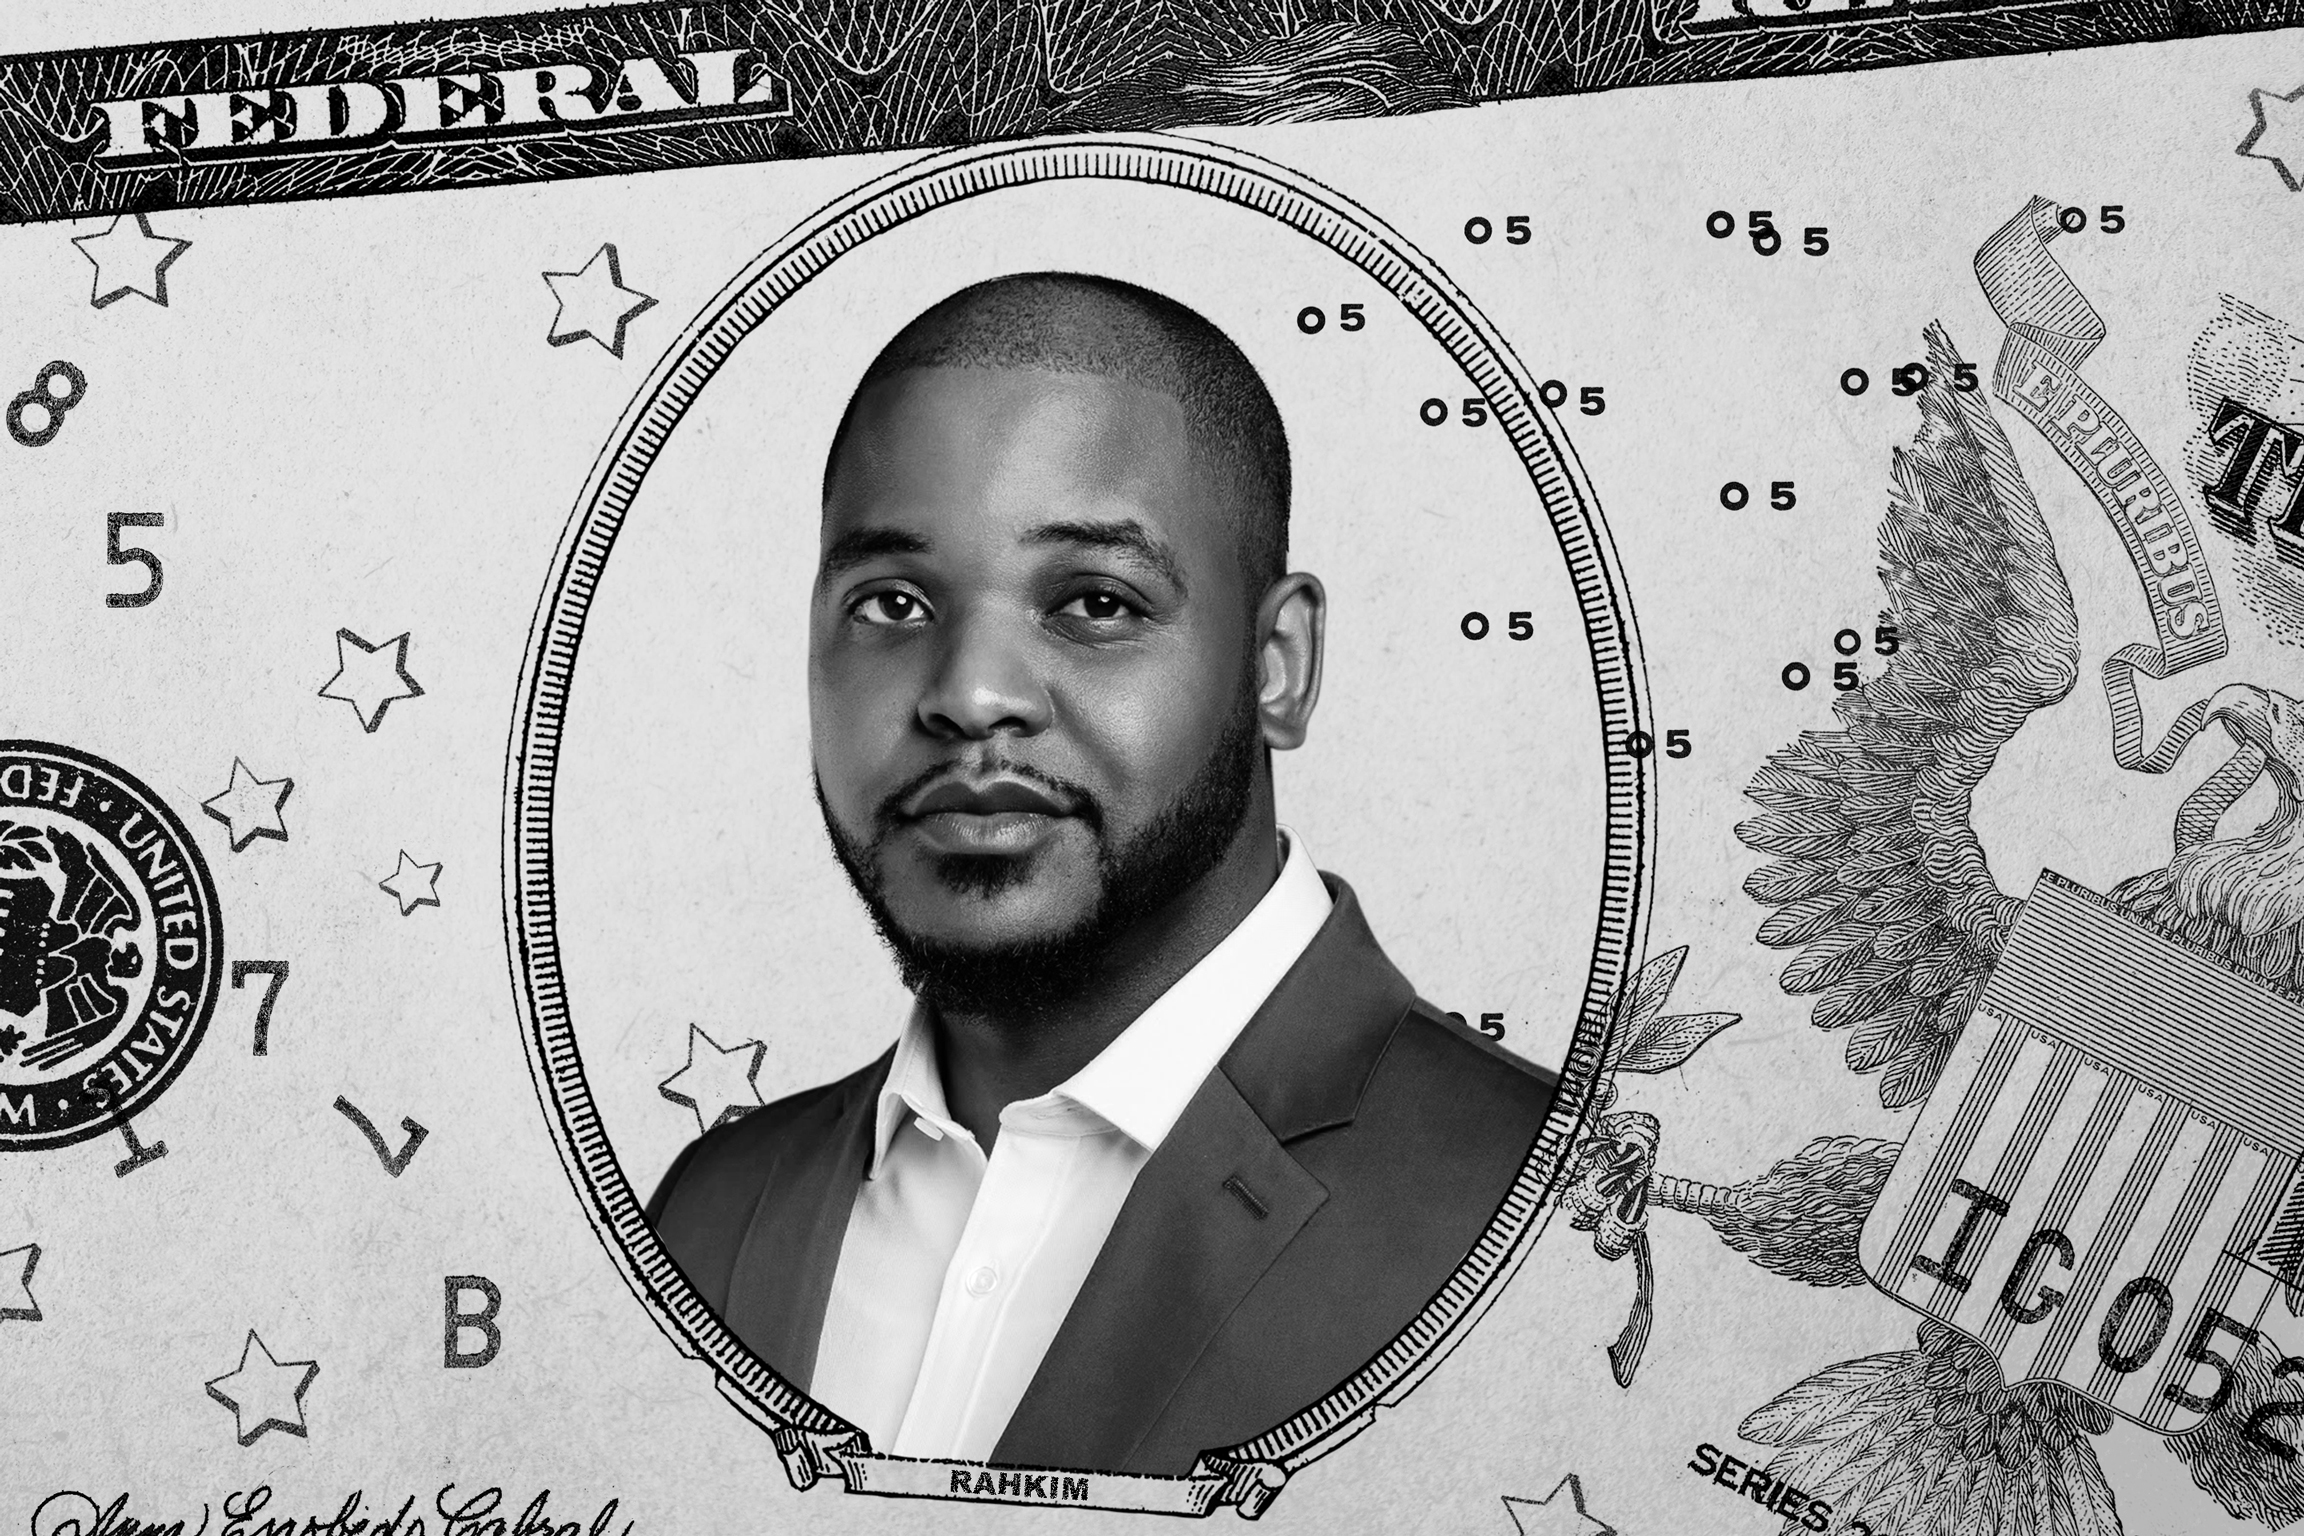
Rahkim Sabree distinctly remembers rushing home ahead of his siblings to tear an eviction notice off the front door before it was seen. There were times he couldn’t afford laundry, and food stamps didn’t always cover the groceries he loaded onto the conveyor belt.
“Situations like that are traumatic,” says the 31-year-old financial coach. “I never wanted to be poor again.”
As he grew up, he sought out as many sources as he could on building wealth, including Robert Kiyosaki’s well-known book “Rich Dad Poor Dad.” But he found that many of the financial texts he read didn’t acknowledge the financial trauma Black people have experienced in this country. That trauma, like the loss of $3 million after a bank created for emancipated slaves collapsed in the 1870s, reverberates throughout the community today, he says.
“When you work so hard to build up capital just to have it taken from you, that creates a trauma and that trauma can last generations,” Sabree says. “Grandma says don’t put your money into banks because they’re crooks, dad says don’t put your money in the banks because they’re crooks — and so you never put your money in the bank.”
Financial education for the Black community has to be unique to the Black community, says Sabree, who helps people work through their own financial trauma, which he says can range from an eviction or bankruptcy to having someone tell you credit cards will ruin your life. Part of the solution, he says, is to point Black people to Black-owned businesses and banks they can trust, like Greenwood, a mobile banking platform designed for Black and Latino customers that was co-founded by rapper Killer Mike. Greenwood provides monthly grants to Black and Latino-owned businesses and produces personal finance educational content targeted at these communities.
Distrust goes beyond banks and touches investing, insurance, credit cards and more, Sabree adds.
Racial inequality has seeped into nearly every aspect of our financial lives. At work, claims of racial discrimination are often the most filed claims but have the lowest percentage of success, and the wage gap shows no signs of shrinking. Meanwhile, Black borrowers are far more likely to be saddled with student loans than their white counterparts. One report found that 20 years after graduation, a typical white borrower has paid off 94{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of their balance on average, while the typical Black borrower had paid off just 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. When it comes to housing, our culture of homeownership was constructed on policies that led to discriminatory practices that still exist today, says Jacob Faber, an associate professor at New York University’s Robert F. Wagner School of Public Service.
“We’re told almost from birth that the best way to build wealth is home ownership,” Faber says. “However, the opportunities to not only buy homes but also accumulate wealth through home ownership is deeply unequal.”
Real estate agents, for example, may steer home seekers to particular areas based on their race, and there’s a major racial gap in home appraisals. Last year, a white man and a Black woman shared that after replacing their photos with pictures of only white family members — and removing books by Black authors — their home appraisal jumped more than 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
“The reality of the lingering effects of discrimination and racism and their economic impacts are irrefutable,” says Soaries, the creator of dfree as well as New Jersey’s first male African-American Secretary of State. “The question now isn’t how this was formed, but what kind of strategies can be effective in helping people close the gap.”
Ads by Money. We may be compensated if you click this ad.Ad
Get the financial advice you need, without leaving your home.
An Online Financial Advisor can help you develop a sound and effective economic plan that works for you. Click below to learn more.
Get Started
New faces, new voices
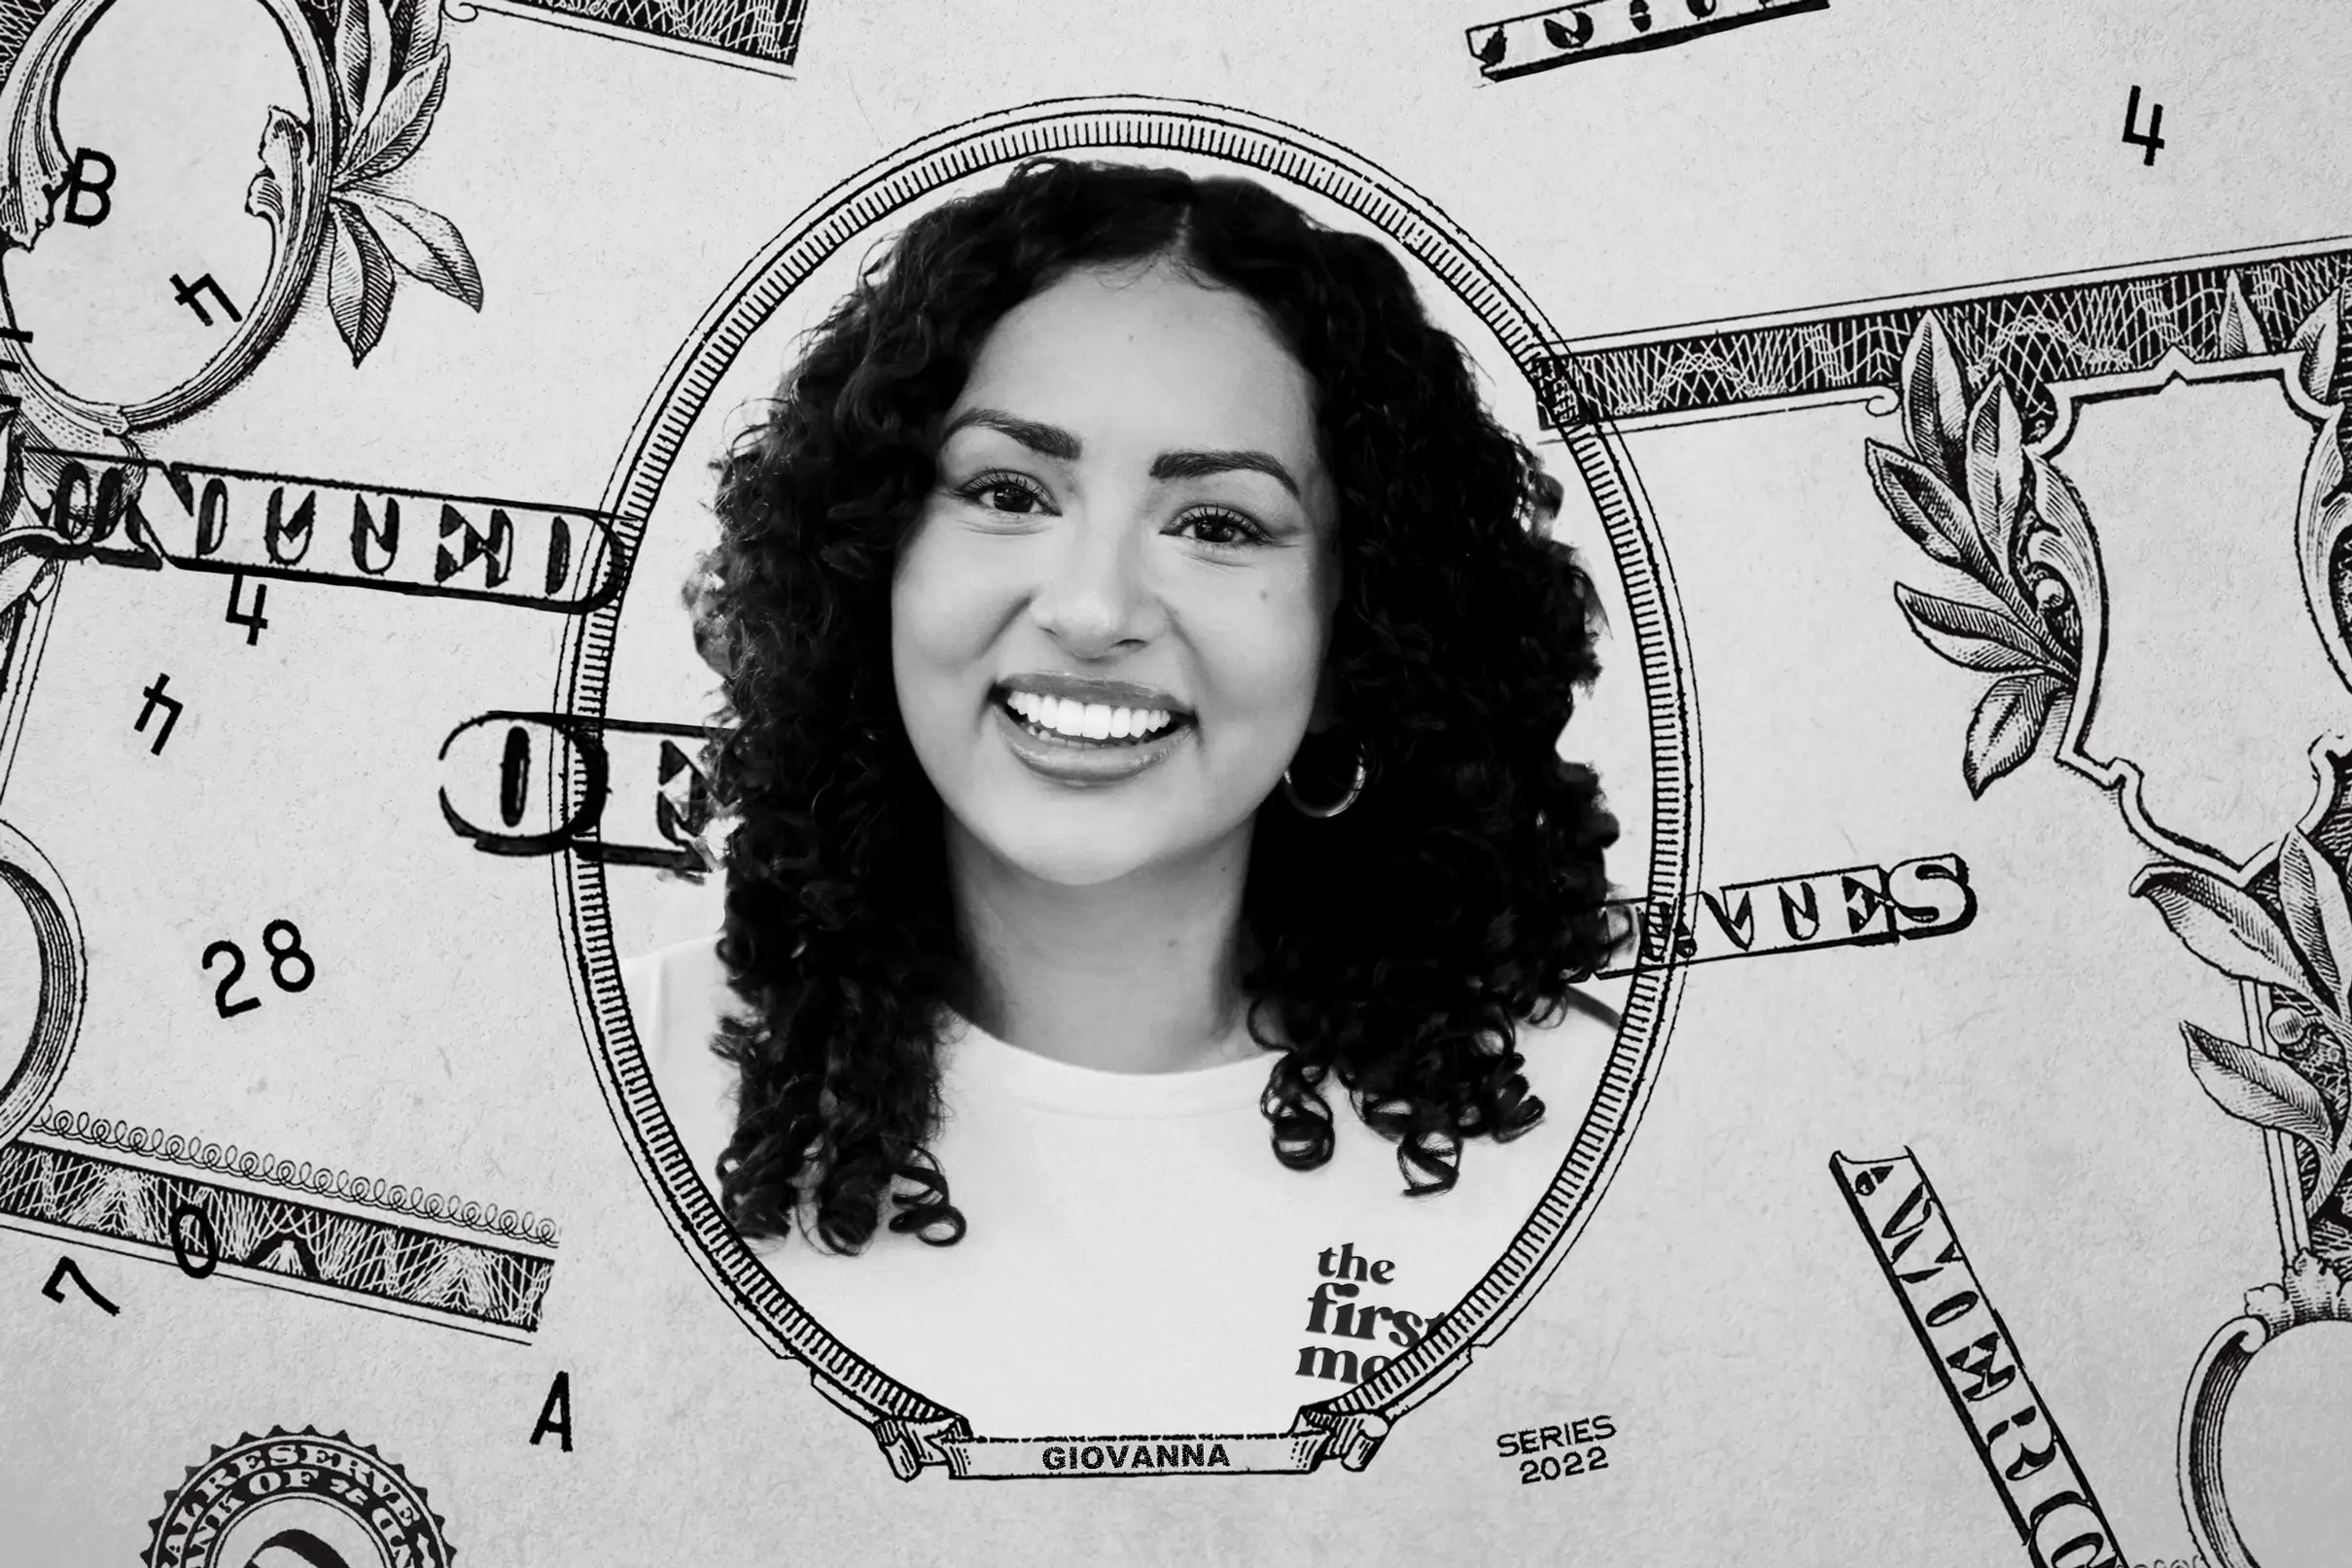
Money; Courtesy of Giovanna Gonzalez
The world of personal finance advice has always felt “not for me,” says Noemi Ibarra, a 24-year-old Latina woman based in Chicago.
Ibarra is a first-generation American, and her family has struggled with poverty ever since her parents immigrated to the U.S. from Mexico nearly 30 years ago. So when Ibarra graduated college and landed a full-time job, she was scared to invest her money.
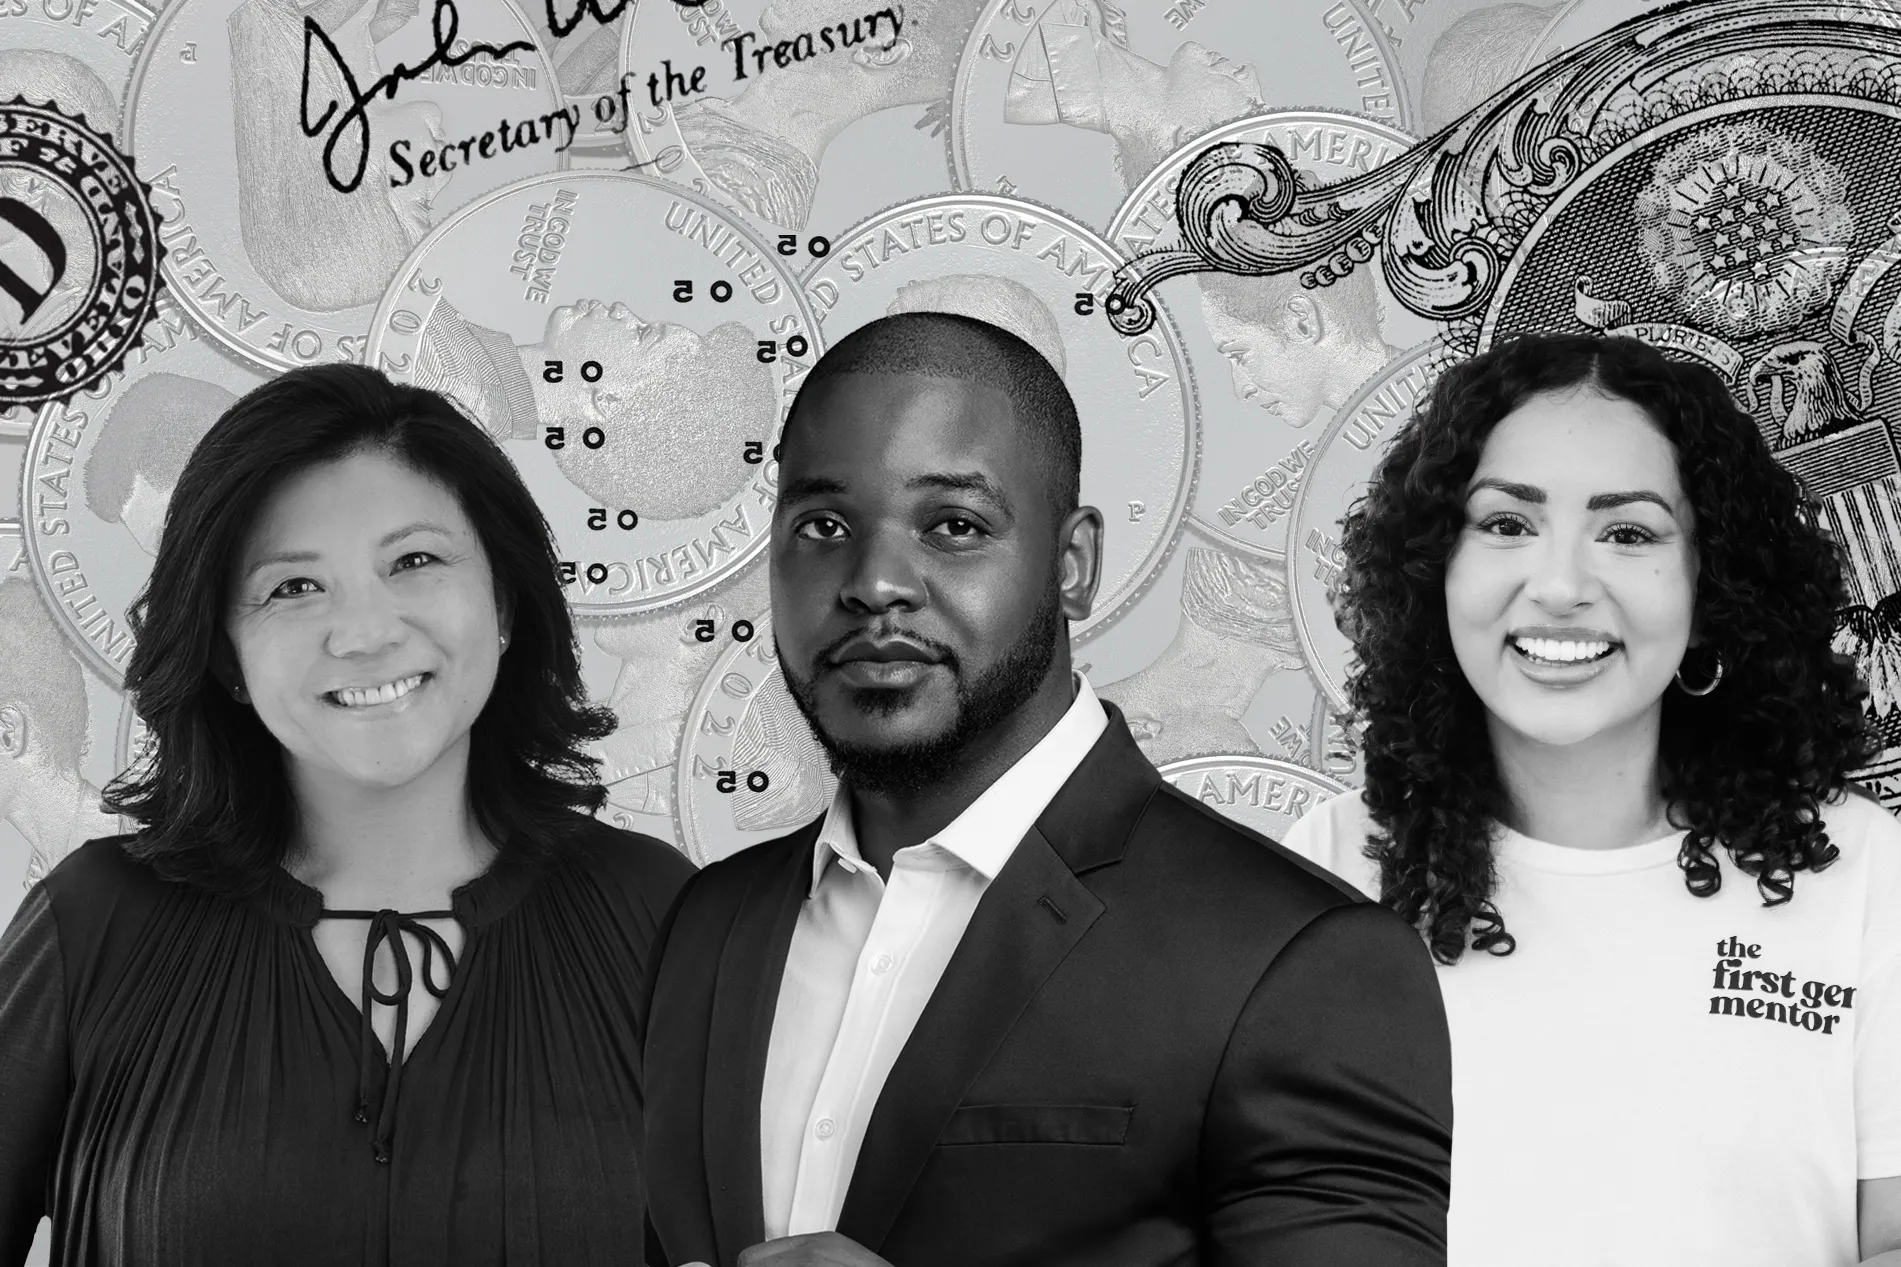
“I didn’t know who to turn to,” Ibarra says. But then she found someone she could relate to: Giovanna Gonzalez, another first-generation Latina woman who has garnered more than 180,000 followers on TikTok with the account name “thefirstgenmentor.” Finding online mentors of color like Gonzalez has made Ibarra say she feels more confident that she, too, can build wealth.
Financial advice on social media has exploded over the last several years, for better or worse. The internet is especially popular for young people to get money advice, with 41{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Z respondents to a 2021 Fidelity survey saying that they turn to social media influencers to educate themselves on investing.
Money experts of color are breaking into the online financial scene. The Budgetnista Tiffany Aliche runs a Facebook group of more than 480,000 members who are mostly Black women, which provides a natural starting place for members to relate to each other. Kiersten and Julien Saunders tackle “the deeply personal side of money through the lens of the Black American experience” via their Rich and Regular blog, podcast and YouTube series.
Delyanne Barros has more than 320,000 followers between Instagram and TikTok. The attorney launched her money coaching business just before the pandemic to share what she had learned about investing with everyone, especially other Latinos, she says.
These newcomers are much needed in the finance world. Gonzalez says she read over 50 personal finance books, but didn’t find that they address issues that hit close to her home, like planning for parents’ retirement and setting financial boundaries with families — concerns she says are specifically pervasive in Latinx communities, but families rarely talk about.
“Money is very taboo in our community,” Gonzalez says.
So she decided to do her part to help others, sharing videos with captions like “Struggling to set financial boundaries with your Latinx family? Try saying this” with advice from a licensed therapist. That particular video is a favorite of Anna Gamez’s, who says she struggles with this exact issue.
“Now I feel really comfortable going into conversations with family and friends,” Gamez, a 31-year-old job recruiter, says.
But not everyone does, or should, get their personal finance advice from social media. The financial advisor landscape needs to change as well, says Vaneesha Boney Dutra, an associate professor of finance at the University of Denver. Eighty-two percent of personal financial advisors are white, according to 2021 data from the Bureau of Labor Statistics. Because advisors looking for clients tend to start looking within their own circles, many of their clients also tend to be white, Dutra says.
“The industry is ignoring a very large piece of the population,” she adds.
The Onyx Advisor Network is trying to change that. Created by two financial advisors, Onyx is a network that focuses on helping “historically underrepresented advisors” start, scale and sustain their businesses by giving them tools, coaching and a network of advisors.
“We want to make sure that the industry looks a lot more like our country,” says Dasarte Yarnway, co-founder of Onyx, which announced its launch plans in December.
Yarnway didn’t even know financial advising was a career he could pursue until he landed his first job at a financial firm. He’s hoping that with platforms like Onyx, more financial advisors of color will see success, and in turn, help those who come after them to do the same.
Ads by Money. We may be compensated if you click this ad.Ad
Online Financial Advisors can guide you toward smart investments and sound economic planning.
We can all benefit from the help of experts, especially when it comes to finances. Reach out to an Online Financial Advisor by clicking below.
Get Started
Changing the financial world for future generations
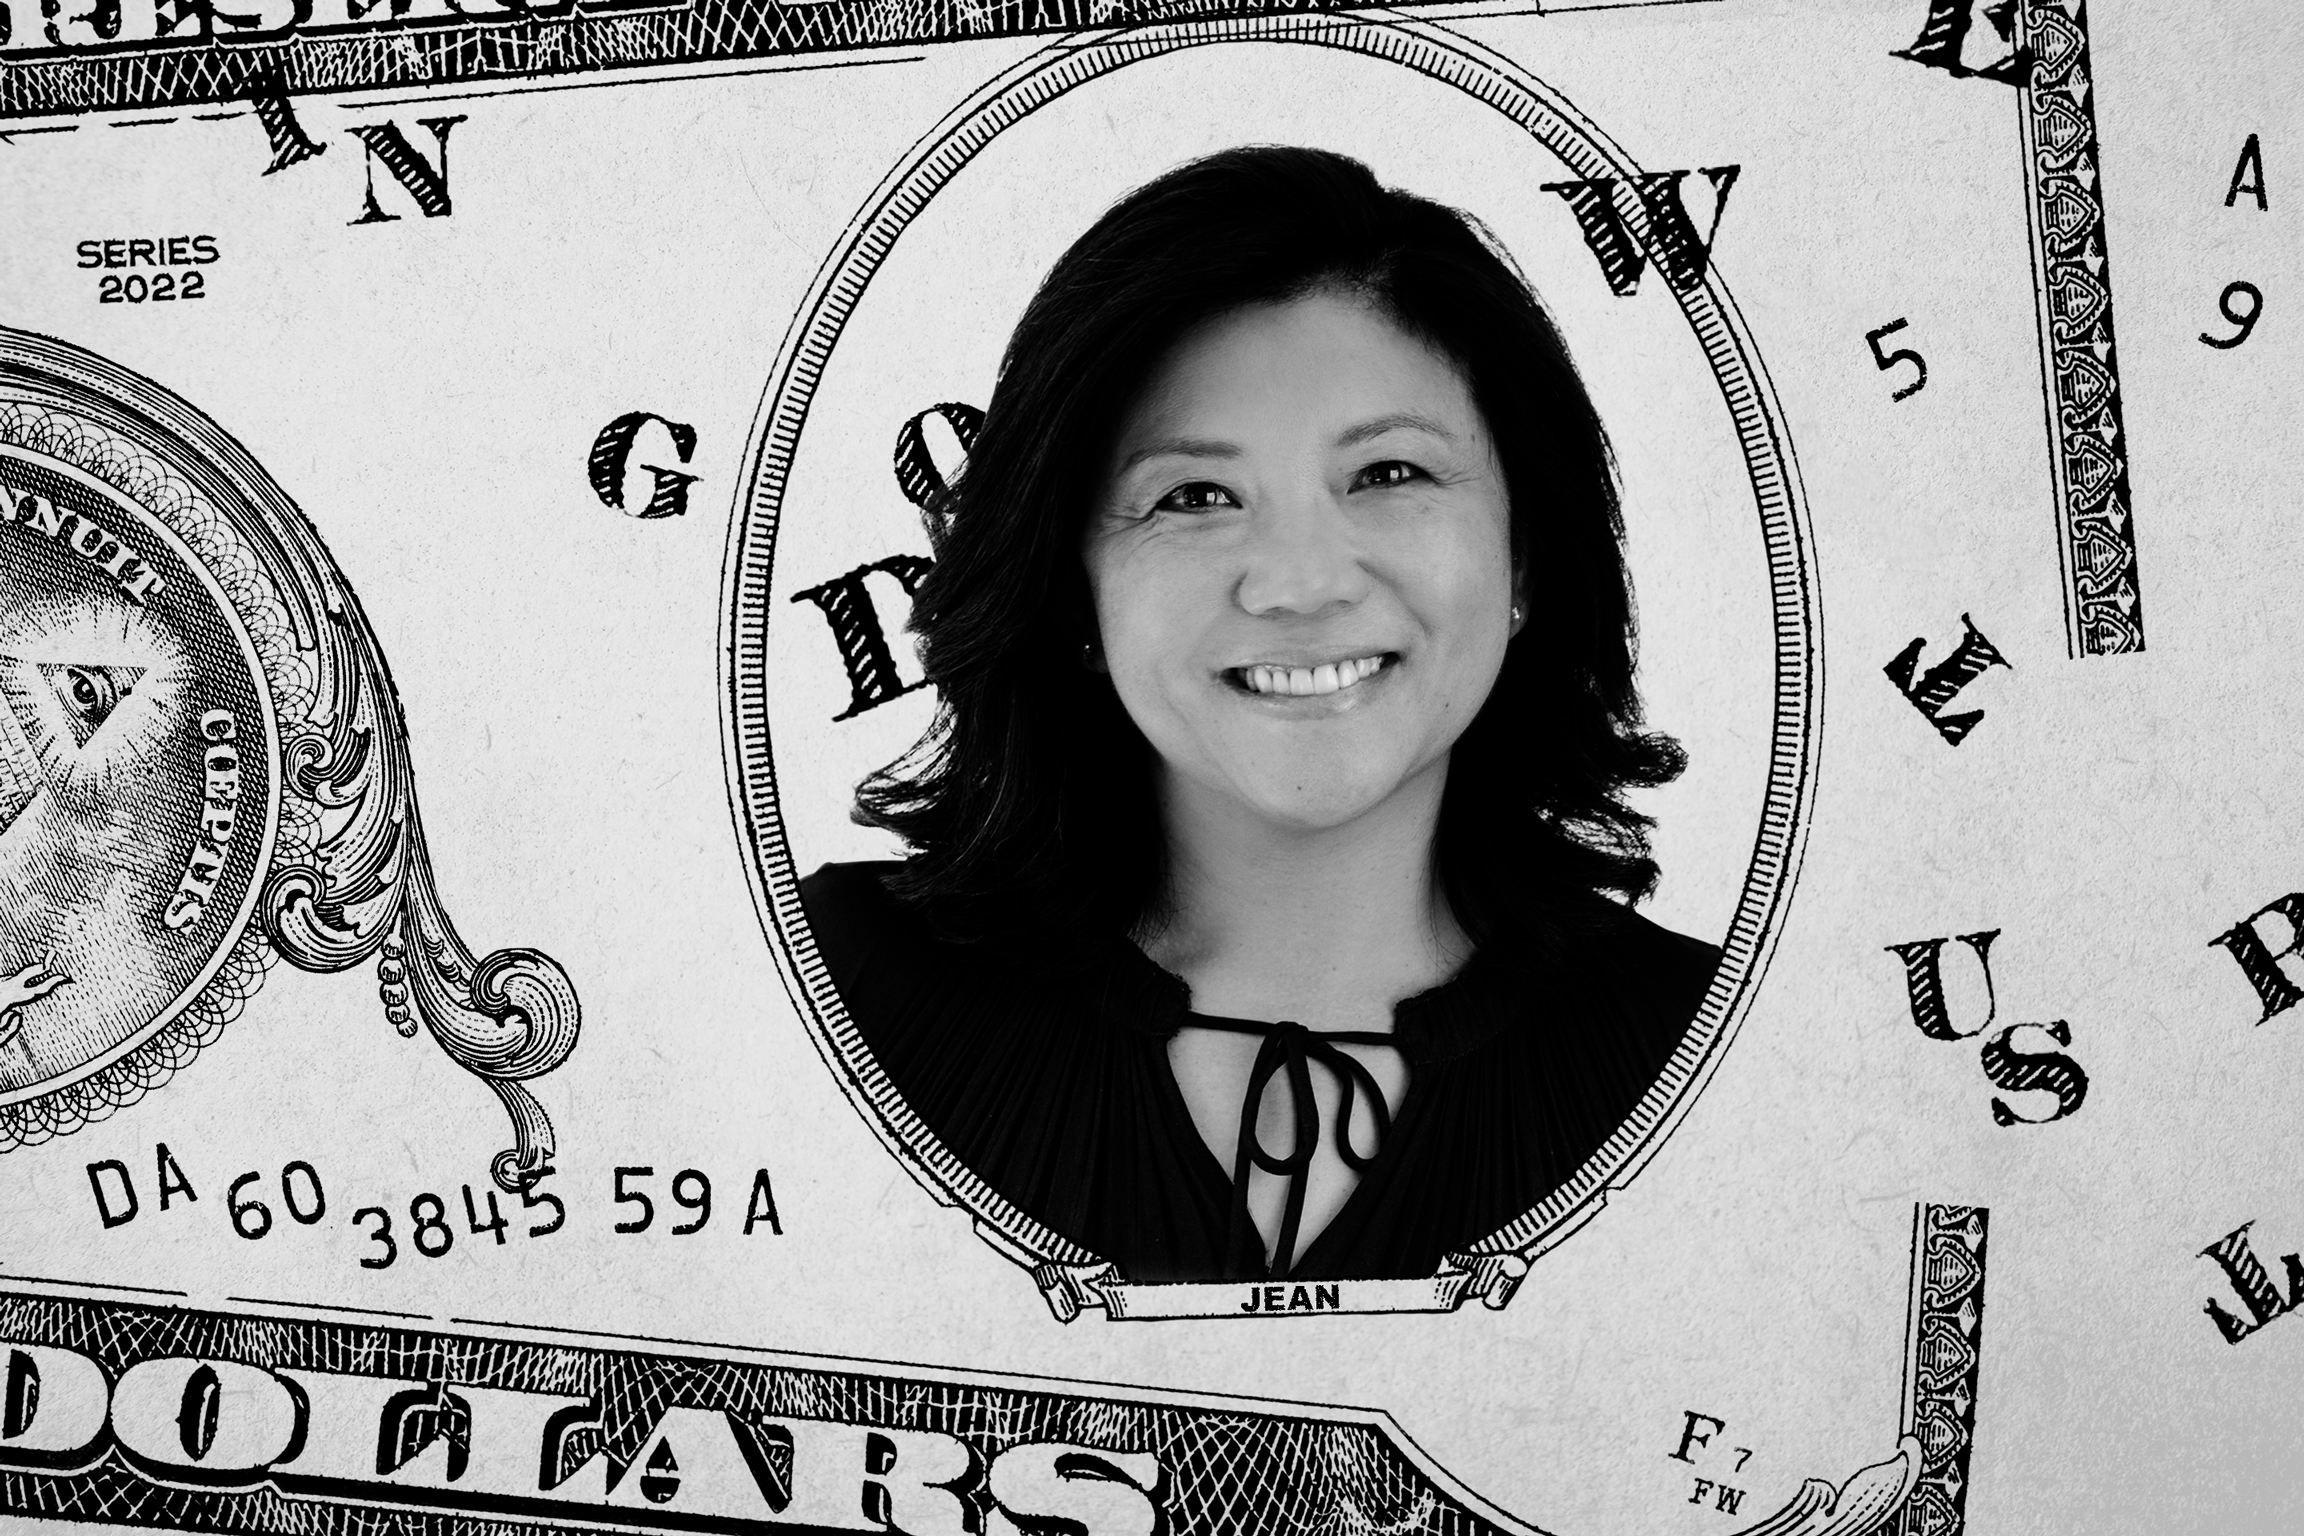
Money; Courtesy of Jean Smart
Yemi Rose says he has always felt that traditional personal finance content does not speak to him.
“So many things default to white,” Rose says.
With his company OfColor — a financial wellness software platform that partners with employers and focuses specifically on helping employees of color — he hopes to help fill the gap. The platform connects employees with budgeting and savings tools, financial coaches of color and educational content geared towards non-white communities.
“People of color are not a monolith and there’s so much variation and nuance there,” Rose says. “But at the very least we try to attack what has been the traditional invisibility of people of color in personal finance.”
Beyond representation, there’s been a boom in financial tools and products specifically designed to help people of color better their finances. It’s an important change: the one-two punch of diverse racial representation in the personal finance space, as well as tools and products built specifically with these communities in mind.
Jean Smart can’t pinpoint exactly when she knew she had to leave her stable job at financial services giant UBS to start Penelope, which brings 401(k)s to small businesses, a majority of which are minority-owned.
“It was 1,000 cuts,” Smart says. They included seeing the disparities highlighted by the COVID-19 pandemic and the murder of George Floyd. Then, anti-Asian racist events came to light, and Smart says for the first time ever, she asked her mother not to leave her house for fear of her safety.
During that chaos, Smart, a Korean-American woman, found that clients she had helped during her 20-year career in the financial industry didn’t seem to need her help as much as other communities of color who were hurting. She quit her job and turned to those people instead, wanting to help them in the best way she knew how with a new team full of people of color and first- and second-generation immigrants.
So many retirement savings tools are difficult to understand — especially for a small business owner who is juggling tons of tasks at once. Penelope aims to bring them a more streamlined approach to saving for retirement with a 401(k) subscription model that cuts through the jargon, Smart says.
Smart is hopeful about the future. She named her company after someone who embodies why it’s so important to her to help make the financial industry more inclusive: her 10-year-old daughter Penelope.
“I think it’s going to get better,” Smart says. “I have to.”
Newsletter
To celebrate our 50th anniversary, we’ve combed through decades of our print magazines to find hidden gems, fascinating stories and vintage personal finance tips that have withstood the test of time. Dive into the archives with us.
Newsletter
Subscribe successful!
You will now receive Money’s newsletter at
Reply anytime to let us know how we can improve. Enjoy!
Make sure we land in your inbox, not your spam folder. We just sent you a welcome email. Sometimes email clients send our first email to a spam or promotions folder. If you don’t see us in your inbox, check these folders, then drag and drop the welcome email into your inbox.
LONDON–(Small business WIRE)–The pandemic in basic, and the outbreak of Omicron a short while ago, have developed a a lot broader awareness of travel insurance policies. “What occurs if I get Covid during vacation?” is for sure the most commonly questioned query by vacationers throughout the world. The reply is in reality, incredibly basic: “Insurance”.
Several vacation insurance policies companies are now offering travel insurance packages that consist of the clinical coverages of Covid-19. But would it gain travelers in gentle of the new Omicron variant or any variant that might probably surface? And how to come across the most effective on the internet travel insurance among so several choices out there? Adhere to these top strategies advised by Travelner specialists – a leading-course vacation agency – to get travel insurance policies on the web that can totally guard you and your cherished kinds when touring abroad.
Come across a credible provider to get vacation insurance policies online
It is indisputably vital to look at your insurance policies provider’s believability ahead of processing any further transaction considering the fact that it will immediately have an affect on your positive aspects. “The finest way to thoroughly examine your insurance coverage company is by hunting at their point out licensing, promises approach, and problems. And really don’t be afraid to inquire the supplier about how they deal with promises and how they get there at a declare award “, mentioned Tyler Wong of Travelner. These concerns will aid you decide on which coverage business can assistance you to get journey insurance coverage on-line and help you in the event of an crisis.
Really don’t ignore to check your provider’s terms and disorders to make sure that the procedure is transparent and dependable. An insurance coverage company’s money strength is a legitimate evidence of its capability to protected your rewards in case of any incidents. Travelner is proud to be a strategic spouse with Trawick Insurance coverage – proposed by Forbes as 1 of the ideal online travel insurance coverage providers so that we can make certain travelers can thoroughly encounter their holiday seasons when touring with us.
Examine options, rates, and added benefits of inexpensive on line journey insurance coverage offers
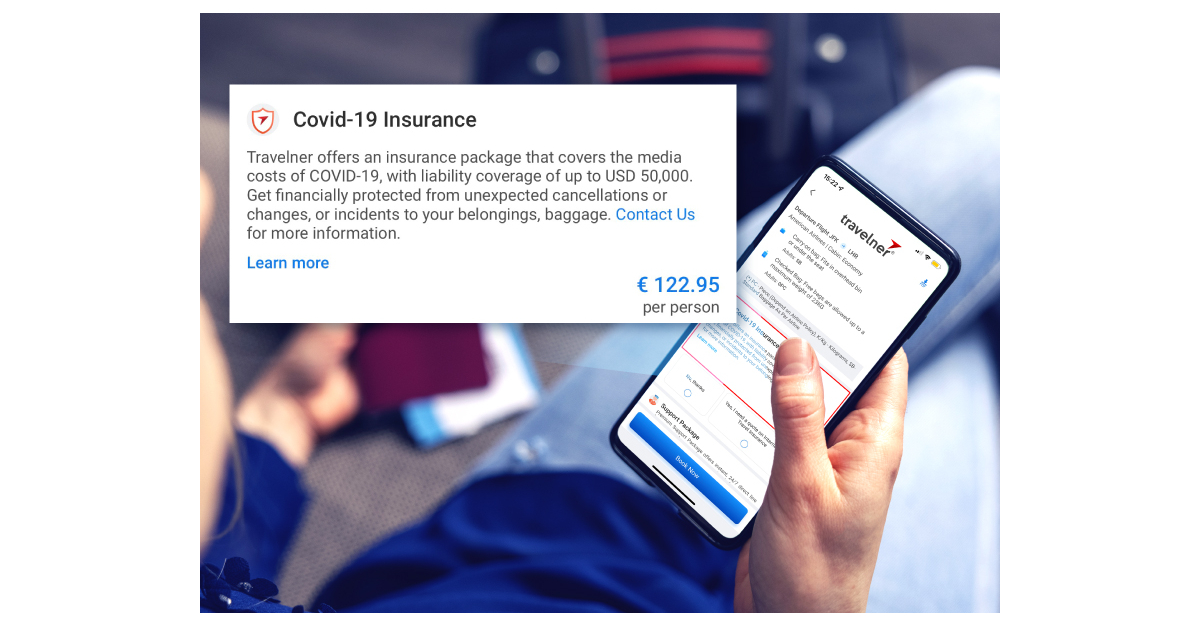
Though most journey insurance plan packages do contain Covid-19 medical expenses, some of them may well not. For that reason, Travelner industry experts advise travelers must read the policies cautiously and seem out for people that exclude pandemics. Travelner is at the moment offering a travel coverage package that covers health care fees for COVID-19, SARS-CoV-2, and any mutation or variation of SARS-CoV-2.
Most journey coverage ideas with health-related added benefits now deal with Covid like any other health issues. So when evaluating selling prices to find the very best on line journey insurance policies, make guaranteed that you are thinking about packages with the very same ideas and positive aspects. Keep in intellect that low-priced on-line journey insurance coverage does not necessarily mean it is the very best alternative for your trip abroad. What’s more, note that to make a claim, you have to have experienced journey insurance plan before starting to be unwell due to the fact coverage is made for unexpected concerns.
Examine on the claims method of the travel insurance coverage company
People frequently forget the great importance of promises method transparency, when in actuality, it is one particular of the determining things to distinguish between an normal and the ideal on-line journey insurance coverage organization. An perfect claims course of action must be transparent and entirely guided so that you really should know who and how to make contact with to make an coverage assert.
With Travelner’s insurance policies, travelers can relaxation certain that the declare treatment is clearly instructed and all assert forms can be located easily on the Travelner internet site. No much more cumbersome method to get your relatives and you fully protected from the pandemic when traveling abroad with our insurance plan deal.
After almost two years, the pandemic has brought major life changes clouding the path to a stable retirement for many individuals. Americans are struggling with key decisions on investments and estate planning strategies, according to a recent Hearts & Wallets report, while the National Institute for Retirement Security says more than half of Millennials and Gen Xers are more worried about their retirement security than before COVID hit.
Add in significant changes in the employment market, with women being disproportionally affected than men and unprecedented numbers of workers taking part in the “great resignation” along with continued market volatility, and it’s no wonder retirement security feels unattainable for many.
But there is hope. Making some smart money moves right now can get you on solid footing for your retirement. Don’t know where to start? Professional advice — whether from a local financial professional or one offered through your workplace, a phone-based or virtual financial professional, or even digital advice tools — can help.
Where to start depends on your personal goals and how the pandemic may have impacted your progress. Here’s what to consider:
If you quit your job as part of the ‘Great Resignation’ …
… You’ll need to make sure the career change doesn’t derail your retirement plan. Think twice before cashing out of your previous workplace retirement plan, which can cost you big in taxes and penalties. Once you’ve landed in your next role, opt into the workplace retirement plan as soon as you’re eligible, contributing at least enough to get an employer match — more if you can. And carefully consider the options for your old 401(k) or similar savings plan.
If your new plan provides access to professional advice, take advantage of it. Or consider speaking to someone outside of the workplace who can provide you advice based on your entire situation.
If you put off milestones, such as buying a house or getting married during the pandemic …
… It’s time to get back on track, but be careful not to overspend to make up for lost time. A financial professional can help look at your current financial picture to create a financial strategy that will help you reach both your short- and long-term goals, or readjust them, as needed.
For newlywed (or soon-to-be-married) couples, a financial professional can serve as a third party to help you set financial goals and navigate the sometimes-tricky waters of combining — or not combining — your finances as you begin building a life together and planning for the future. Financial professionals can also help you make sure you’re adequately protecting yourself from a variety of risks.
If you want advice but aren’t ready for an in-person meeting …
…The virtual environment provides you with a wonderful opportunity to redefine how you would like to interact with your future financial professional. Many workers have come to appreciate the hybrid or completely remote work environment during the pandemic. Consider a professional advice model where you can engage by phone to talk about retirement planning or other financial challenges you’re facing.
If stimulus checks and a less active social life have boosted your savings account …
…You’ll want to make sure you’re reviewing and making progress on your financial goals. If you’ve paid down debt, built adequate emergency savings and are maxing out your retirement savings, you may want to look at your financial wish list — maybe starting a business, buying a second home or retiring early. Either way, you may also want to put your extra cash in savings into investments that match your goals.
Unsure what to do first? If all you need is investing guidance, digital tools can be a good place to start. We have a calculator and be sure to check out the suite of tools on this resource center page. A financial professional can help you prioritize and achieve your goals and, if appropriate, help you allocate your investments.
If COVID forced you into retirement …
… Professional advice can help you stretch your nest egg as far as possible. A financial professional can work with you to determine your best withdrawal strategy, after factoring in the size of your retirement savings, the types of accounts you have (taxable or non-taxable), Social Security and other income sources, and your expenses. They can also talk to you about whether it makes sense to consider working part time or using a guaranteed income product to ensure you never run out of money in retirement.
Remember, regardless of how you arrived at your current situation, taking the right steps now can help you feel confident that a financially secure retirement is in your future. Start today with getting the advice you need.
This article was written by and presents the views of our contributing adviser, not the Kiplinger editorial staff. You can check adviser records with the SEC or with FINRA.
President, Retail Advice and Solutions, Prudential
Brad Hearn is the president of Retail Advice and Solutions, which brings together the extraordinary face-to-face advice expertise of Prudential Advisors with Prudential’s Hybrid Advisory team and digital advice capabilities – creating a single organization with end-to-end accountability for delivering holistic financial advice and solutions across the entire advice continuum.
The corporation and law organization names proven over are produced mechanically based mostly on the textual content of the write-up. We are strengthening this attribute as we continue to exam and acquire in beta. We welcome responses, which you can give working with the opinions tab on the correct of the site.
February 11, 2022 – For the vast majority of modern-day business, a perfectly-created and trustworthy supply chain is the foundation for operational good results. This implies that all parts thereof — from sourcing to manufacturing to distribution — get the job done together reciprocally so that all parts of an close-solution fulfill needed specifications and well timed arrive at their places. In flip, this enables other members in the chain to fulfill their very own specific calls for and fulfill their respective obligations.
But what comes about when a portion of the offer chain encounters an sudden hold off, for case in point, a uncooked material shortage, unscheduled manufacturing unit shutdown, transportation issues, or production troubles? Disruptions at just one component of the supply chain can, and frequently do, build ripple outcomes that improve in magnitude and severity even more up the chain, culminating in hold off or absence of the end-solution in just one or far more necessary marketplaces. This can guide to a vary of unanticipated economical (and reputational) implications for a number of, if not all, associates of that source chain.
Compounding offer chain disruptions across the world
Register now for Free unrestricted accessibility to Reuters.com
Sign-up
According to a current report, U.S. enterprise leaders rated enterprise interruption including source chain disruption as the No. 1 threat for stateside corporations in 2022. This comes as no shock, as recent world-wide activities have prompted, and continue on to trigger, significant — and compounding — disruptions across industries.
COVID-19 pandemic. The pandemic, specially in the to start with 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of 2020, spurred federal government orders across the world that compelled facility closures throughout industries, from time to time for months. Even wherever complete closures ended or ended up not necessary, companies ongoing to impose capacity limits and quarantine needs that curtailed operations and facility occupancy. This unparalleled event led to ubiquitous provide chain difficulties that afflicted practically all industries.
Wintertime Storm Uri. In February 2021, a weeklong winter storm (unofficially referred to by media outlets as Winter season Storm Uri) battered the Point out of Texas and prompted blackouts, highway closures, reduction of water services, and facility closures throughout the state. In addition to currently being a major transportation hub, Texas is the house of numerous significant industries, including oil and gasoline, semiconductor manufacturing, and aerospace and protection, several of which experienced unexpected disruptions as a final result of the storm. The world wide scarcity in semiconductors is envisioned to expense the automotive sector by itself $210 billion in dropped revenues.
Suez Canal blockage. In March 2021, the huge container vessel At any time Presented was grounded for more than six times in the Suez Canal, a important waterway for world transport and transportation. It is estimated that far more than 350 vessels ended up backed up for the duration of that time which includes container ships, bulk carriers, and oil tankers, adding substantial supplemental vacation time to tightly scheduled routes. This 6-working day blockage created provide chain delays that rippled throughout industries globally.
These activities only exacerbated the ubiquitous source chain difficulties created as a end result of the ongoing COVID-19 pandemic.
Provide chain disruptions, and disruptions of this magnitude and scale in particular, can have a devastating influence on a business’ envisioned earnings and other money metrics frequently with minimal-to-no warning. In simple fact, in accordance to the “Allianz 2022 Threat Barometer Report,” 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of firms mentioned they experienced endured a massive influence from the latest offer chain troubles. So, what steps can businesses get to lower these economic impacts? The response may possibly be identified in their insurance policies applications.
Ample insurance coverage can fill the hole
In the wake of a fragmented provide chain, companies should really search to their business interruption insurance plans to determine if they could have protection for resultant monetary losses.
Company interruption insurance coverage usually supplies coverage for money losses seasoned by the insured to the extent physical decline of or problems to the insured’s home pressured it to terminate, suspend, or minimize regular operations. Firms that acquire enterprise interruption insurance policies along with their house insurance policies guard them selves not only from the expenditures tied to fixing the harm or decline at problem, but also the economic losses that arise from related operational impacts.
Company interruption insurance policy assumes that an insured threat straight impacted the insureditself. But what occurs if a crucial member of your supply chain experiences its personal disruption? Due to the fact conventional business enterprise interruption insurance is normally restricted to losses involved with the insured’s possess injury or loss, this line of protection may not be responsive. So, what now?
The good thing is, most business interruption insurance is acquired in conjunction with a comparable but meaningfully unique kind of coverage: contingent business enterprise interruption. Contingent enterprise interruption coverage is created to safeguard a organization from the economical effects of the termination, suspension, and/or reduction of its standard business functions as a outcome of one or a lot more members of the supply chain suffering from bodily reduction of or problems to its house.
Working with Winter Storm Uri as an example, consider a state of affairs wherever a member of a offer chain knowledgeable a pipe burst that destroyed its machinery therefore triggering a hold off in generation of a critical component of the source chain’s conclude-product or service. Other customers of the source chain may possibly be ready to protected payment for their losses beneath their contingent organization interruption coverages, even while the assets destruction did not occur at their respective properties. Contingent business enterprise interruption coverage is a likely priceless ingredient of a business’ insurance policy program in the wake of this sort of supply chain disruptions.
Broader provide chain coverage
As an effectively regular supplying throughout the coverage business, most enterprises obtain contingent business enterprise interruption insurance policies. But in the deal with of an unanticipated supply chain disruption, is this more than enough?
As functions like the COVID-19 pandemic, the Suez Canal blockage, and Winter season Storm Uri have demonstrated, provide chain disruptions can have an endless array of will cause. Whilst contingent company interruption coverage can supply a significant line of defense, it is commonly limited to coverage for disruptions triggered by decline of or problems to residence, for illustration, flooding, hearth, or wind destruction. But what transpires if a source chain disruption is caused by a different variety of possibility? In this sort of circumstances, regular contingent business interruption insurance coverage may well not utilize.
Thankfully, a lot of insurance coverage businesses present broader coverage precisely customized to offer chain challenges. Offer chain insurance policy typically operates the same way as common contingent enterprise interruption coverage, but it encompasses added hazards. For example, offer chain insurance plan may well also go over disruptions as a consequence of labor strikes and shortages, generation difficulties, war or political unrest, and disruptive civil motion.
Depending on a business’ hazard profile, obtaining this broadened protection may perhaps be worthwhile. It is notably significant to take a near glance at all members of the provide chain and discover risks inherent to their corporations.
Is a supplier situated in a country that is not politically secure? Are crucial raw elements issue to adverse impacts from weather difficulties? Is a organization notoriously contentious with labor unions? These kinds of queries are value taking into consideration when identifying if source chain insurance policy is warranted.
Summary
As modern world functions have shown, provide chain disruptions can arise at any time, and can have devastating economic impacts on all associates of the offer chain. Accordingly, it is important to operate with trusted brokers, possibility administration professionals, and protection counsel to critique the impacted business’ coverage method and ensure selection makers realize the scope of coverages accessible. Even though contingent business interruption insurance policy can establish priceless in the wake of a provide chain disaster, most effective techniques dictate that firms meticulously assess their threat profile and look at whether broader source chain protection could be proper.
Ashley B. Jordan is a normal contributing columnist on insurance coverage legislation for Reuters Authorized Information and Westlaw These days.
Register now for Free unlimited entry to Reuters.com
Register
Opinions expressed are those people of the creator. They do not replicate the views of Reuters Information, which, below the Trust Ideas, is committed to integrity, independence, and liberty from bias. Westlaw Today is owned by Thomson Reuters and operates independently of Reuters Information.