Unemployment claims tick up as job market cools down

Unemployment claims tick up as job market cools down

Comment

Matt Miller thought he was getting a promotion when he met with his boss on Tuesday. Instead, he got laid off.

Business at the Pennsylvania art industry firm where he worked had been brisk up until a few months ago. But lately jitters about the crashing stock market and a possible recession had many regulars tapping the brakes on new purchases.

“Over the last 3 months, sales dropped 50 percent, then 50 percent again, until they were basically at zero,” said Miller, 32, who is worried about future job prospects. “Most of our clients were in real estate or tech, and they’ve just disappeared. They don’t want to spend $10,000 on a painting if they’re worried things are going to crash in a few months.”

The labor market, until now a pillar of economic resilience, is showing cracks.

Job growth is slowing, unemployment claims are ticking up and several big companies, including Apple and Meta, are putting hiring plans on hold. There are signs that more firms are slashing jobs in industries as varied as tech, advertising, health care, finance and law.

Convenience store chain 7-Eleven laid off 880 corporate workers in Texas and Ohio, following its purchase of a rival chain, a company spokesperson said an email. Ford Motor Co. is planning to cut 8,000 positions in the coming weeks, Bloomberg reported. Meanwhile, electric carmaker Rivian is cutting 700 positions, delivery start-up Gopuff is laying off 1,500, and mortgage lender LoanDepot is slashing 4,800 jobs this year, according to reports.

“What had been universally positive labor market news is certainly less so now,” said Liz Ann Sonders, managing director and chief investment strategist at Charles Schwab. “The anecdotes are starting to stack up of companies laying off workers or freezing hiring or limiting job postings.”

Workers are picking up extra jobs just to pay for gas and food

The number of active job postings across multiple online platforms has declined nationwide for five straight weeks, according to an analysis by Julia Pollak, a labor economist at ZipRecruiter.

Meanwhile, first-time filings for unemployment benefits rose by 7,000 last week and are up 51 percent from mid-March, although they are still near historic lows, Labor Department data show.

The cooling of the hot labor market is, in many ways, exactly what policymakers have been trying to engineer. Next week, the Federal Reserve is expected to raise interest rates for the fourth time this year in hopes of slowing the economy enough to control inflation without leading to widespread job losses or recession. The Fed expects the unemployment rate to gradually rise from a near 50-year low of 3.6 percent to 4.1 percent by 2024 — with the hope that most of the slowdown comes in the form of fewer job postings and hirings instead of job cuts and layoffs.

But achieving that balance can be tough. Labor economists say they’re increasingly worried that the picture could quickly sour.

“Things have slowed down — in some places, pretty sharply,” said Guy Berger, principal economist at LinkedIn. “There’s nothing right now that looks like we’re experiencing a recession, but at some point we can easily tip into rising layoffs and unemployment. The range of [layoff] anecdotes and where they’re coming from is getting broader.”

Mixed messages on economy raises questions on recession risks

This latest reckoning follows two years of torrid jobs growth, marking the fastest labor market recovery in history. Nearly all of the 20 million jobs lost in the early weeks of the pandemic have been recovered. U.S. employers created more than 6 million jobs in the past year alone, and job openings continued to outpace job-seekers by nearly two to one in May.

But a broader slowdown in other parts of the U.S. economy is beginning to have ripple effects on the job market.

The most pronounced cool-down, Berger said, has been in the tech industry which experienced rapid growth during the pandemic. Tech hiring has fallen 9.1 percent in the past month, compared to 5.4 percent dip in hiring across all industries, according to data from LinkedIn.

The number of tech firms and start-ups laying off workers has picked up in recent weeks. Netflix, Tesla and Coinbase have all announced job cuts or hiring freezes. Vimeo, the online video platform and one-time tech darling, announced this week it was laying off 6 percent of its staff.

“We are making this decision in order to ensure we come out of this economic downturn a stronger company,” Anjali Sud, the company’s chief executive, said in a memo to employees. “The reality is that the challenging economic conditions around us have impacted our business. We must assume that these conditions will remain challenged for the foreseeable future, and that we aren’t immune.”

Recession fears can be self-fulfilling: If families and businesses begin pulling back because they’re nervous about their financial futures, that can be enough to trigger a downturn. Until now, Americans have continued to spend heavily, particularly on services as well as food, gas and other necessities, even as prices go up. But economists warn that could quickly change if job losses pick up — or Americans begin to cut spending because they worry they could lose their jobs.

Silicon Valley braces for tech pullback after a decade of decadence

Neal Kemmerer lost his job at a robotics company in Lafayette, Ind., four weeks ago. Since then, he’s applied for at least 300 jobs — and gotten one interview.

Far more frequently, he’s notified that positions he’d applied to have been suspended or closed, he said. It’s a far cry from January, when he had his pick of four job offers.

“I’m a single dad of two, so I’ve been desperately applying to 75 to 100 jobs a week,” said Kemmerer, 38. “But there is nothing around here anymore.”

He was making $60,000 a year as a site leader for Starship Technologies, which makes food-delivery robots. But most of the openings he’s finding now are in manufacturing for companies like Subaru and Caterpillar, and the wages max out at $19 an hour, or less than $40,000 a year, Kemmerer said.

During the pandemic, many workers saw their earnings rise for the first time in years. However wage growth is beginning to taper off, particularly with rising inflation factored in. Average hourly earnings have risen more than 9 percent in the last two years, while prices are up about 15 percent in that same period.

“The waters are pretty steady right now but there is a bit of churn up ahead,” said Nick Bunker, director of economic research at Indeed’s Hiring Lab. “The Fed is still hiking interest rates. It’s unclear how unsteady the ride might get.”

Katherine Loanzon, a legal recruiter in New York City, says there’s been a marked slowdown in hiring, especially among firms that specialize in corporate law. Mergers and acquisitions are down, as are initial public offerings.

Some major law firms, she said, have frozen hiring even though they continue to list postings on their websites. Others are suspending pay raises and taking much longer to hire attorneys.

“People are much more careful than [during] 2021’s corporate hiring frenzy,” said Loanzon, managing director at Kinney Recruiting. “We haven’t seen layoffs yet but … that’s usually the next step.”

Seven ways you can financially prepare for a recession

Some of the very workers who were ceremoniously courted and hired in 2021 are among those being laid off now.

Pete Basgen was happily employed at a tech firm last fall when he was approached by recruiters at a live-stream software firm with a 40 percent pay increase and the promise of building his own creative strategy team. He took the position in November and managed to hire a handful of employees before he — along with most of his team — was laid off last month. Executives at the San Francisco firm were worried that business would quickly dry up if there was a recession, he was told.

“They poached me from my last job, offered me a very big salary and a whole lot of equity, then laid me off,” he said, adding that he wasn’t at the company long enough for the stock benefits to kick in.

Many of the companies he’s talking to now, he said, are eager to hire consultants or contract workers, but wary of bringing on a full-time salaried employee.

“It feels like a very different economy than it was in November,” the 37-year-old said.

Ethan Engel lost his data analytics job in Phoenix this month after the international insurance firm he was working for canceled an 18-month contract halfway through. All 60 people on the data-digitalization project got laid off.

“From what we heard, it was because they saw this recession coming, and that was the end of it,” said Engel, 24. “There wasn’t really a whole lot of new work coming in.”

Engel has spent the past three weeks applying for dozens of jobs in data analytics, defense, aerospace, banking and insurance, but has yet to land a single interview.

On Tuesday, he signed up to become an Amazon delivery driver. If he gets the job, it’ll come with a 30 percent pay cut.

“I finally had to say, ‘Ok, I need to find any kind of work,’” he said. “I need to have some money coming in.”

DOJ resolutions under False Claims Act rise in H1

DOJ resolutions under False Claims Act rise in H1

The U.S. Section of Justice’s resolutions under the Untrue Statements Act, which totaled much more than $500 million throughout this year’s to start with half, have outpaced action in the similar period of time in 2021, but a lot of of them have been “relatively modest,” says a legislation business in a report issued Wednesday.

The FCA will allow personal get-togethers to file whistleblower, or qui tam, actions alleging that defendants defrauded the federal authorities.

Gibson Dunn & Crutcher LLP reported much more than $393 million in resolutions in its equivalent mid-12 months 2021 report.

The law organization says in this year’s report that “it stays to be seen no matter if DOJ will match the recoveries acquired all through 2021, which incorporated blockbuster settlements stemming from the opioid crisis.”

The U.S. Office of Justice said it attained much more than $5.6 billion in settlements and judgments from civil situations involving fraud and false statements in opposition to the authorities under the FCA for the fiscal year ended Sept. 30, 2021.

Gibson Dunn reported some of the most notable settlements this yr replicate ongoing fallout from COVID-19, and a new DOJ initiative all-around cyber fraud.

These consist of:

– In February Arlington, Virginia-centered Zen Answers Inc. agreed to pay back $31,000 in damages and civil penalties to settle DOJ allegations it violated the FCA, by getting additional than one Paycheck Security Plan personal loan in 2020.

– The DOJ said in April that Tampa, Florida-centered Doctor Partners of The usa LLC and its chief clinical officer would pay $24.5 million to resolve allegations they had violated the FCA by billing federal healthcare systems for unnecessary clinical tests and services, having to pay illegal renumeration to its health practitioner workforce and making a false assertion in connection with a financial loan obtained by means of the Paycheck Defense Method.

– In March, Cape Canaveral, Florida-based mostly Complete Well being Solutions LLC explained it would fork out $930,000 to solve allegations it violated the FCA by falsely representing to the U.S. State Dept. and the Air Power that it experienced complied with deal necessities connected to the provision of their healthcare expert services in Iraq and Afghanistan.

The DOJ said in its statement this was the first resolution of a FCA circumstance involving cyber fraud given that the start of its Civil-Cyber-Fraud initiative.

In July, the Justice Department stated rocket engine maker Aerojet Rocketdyne agreed to pay back $9 million to take care of allegations it misrepresented its compliance with cybersecurity demands in federal contracts, under FCA litigation filed by a whistleblower.


Government finance statistics: long-term debt securities – Products Eurostat News

Government finance statistics: long-term debt securities – Products Eurostat News

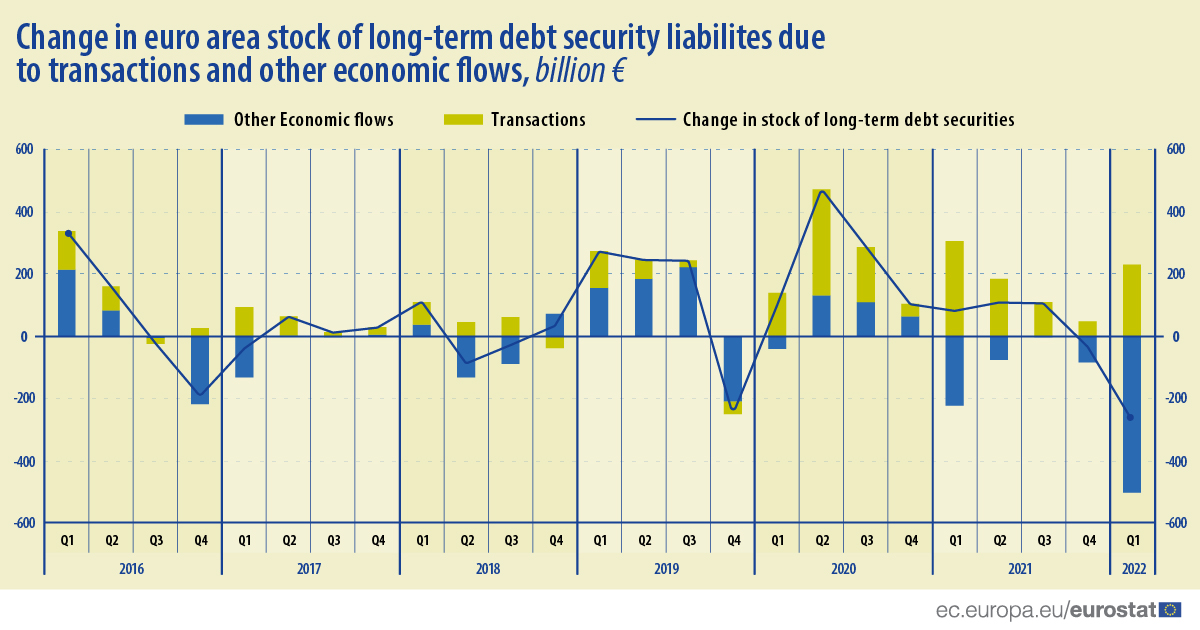
The standard federal government financial accounts deal with transactions in economical assets and liabilities as nicely as the inventory of financial assets and liabilities. In the very first quarter of 2022, the marketplace benefit of the outstanding lengthy-term personal debt securities in the euro region lessened by about €501 billion thanks to a lower in worth in the economical marketplaces. This is mostly the end result of increased curiosity fees observed. This would make the personal debt securities issued in the past, when curiosity fees had been reduce, less desirable to investors, resulting in a decrease in value. At the end of the first quarter of 2022, prolonged-expression debt securities built up about 71{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the overall liabilities of euro region governments.

This info comes from info on quarterly govt finance revealed by Eurostat nowadays. The post presents a handful of results from the more specific Data Explained posting.

Bar chart:change in euro stock of long-term debt security liabilities due to transactions and other economic flows (billion €)

Supply dataset: gov_10q_ggfa 

The remarkable amount of money of liabilities modifications either owing to transactions (primarily due to net issuance, but also owing to accrued curiosity) or owing to other economic flows (primarily value alterations also regarded as keeping gains or losses). As long-expression personal debt securities are traded on the fiscal markets, the worth of these devices modifications regularly around time. At the end of the initially quarter of 2022, the benefit of personal debt securities issued by governments in the euro area declined (by €501 billion) quicker than the internet issuance of new long-expression debt securities (around €231 billion). This resulted in a €270 billion lower inventory exceptional at the conclusion of the quarter as as opposed to the starting of the quarter and a holding reduction for collectors. 
 
For additional facts: 

Methodological notes: 

  • In the European Program of Accounts (ESA 2010), most assets and liabilities are valued at market place benefit. This implies that the stock of money assets and liabilities fluctuates thanks to transactions, but also thanks to “other flows”, notably revaluations (nominal holdings gains and losses). 
  • Prolonged-phrase financial debt securities are part of the standard government gross credit card debt as lined in the Maastricht financial debt definition stipulated in the Excessive Deficit Process. Consequently, stock data on lengthy-time period personal debt securities are also revealed at encounter benefit, which does not just take into account most price tag adjustments. The inventory at experience price can differ noticeably from the inventory at market value.

To speak to us, you should visit our Consumer Assistance website page.
For press queries, be sure to speak to our Media Assist.


AHEAD program and more in Shreveport business news

AHEAD program and more in Shreveport business news

3 Times You’ll Regret Claiming Social Security Early | Personal-finance

3 Times You’ll Regret Claiming Social Security Early | Personal-finance

When it arrives to signing up for Social Safety, you get a choice. You can decide to get gains at comprehensive retirement age (FRA), which is when you get your entire monthly benefit primarily based on your wage history, or you can signal up at an before or later age.

If you hold off your submitting past FRA, your Social Protection positive aspects will boost on a long-lasting foundation. But if you sign up in advance of FRA, your rewards will be completely lowered.

The extent of that reduction will depend on how early you indicator up. The soonest you can file for Social Protection is age 62, and if you go that route, you are going to be hunting at a 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} reduction in added benefits, depending on your specific FRA. If you indicator up for positive aspects at age 65, you’ll be on the lookout at a scaled-down reduction — more like 6.67{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 13.34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, dependent on your FRA.

People today are also reading…

  • Condition laws on abortion, transgender concerns have businesses balking on coming to Oklahoma, development official claims
  • Update: Lady dies immediately after taking pictures at Center of the Universe, Tulsa law enforcement say
  • 4-12 months-old’s physique recovered after drowning in Arkansas River
  • Letter: Nor surprising that organizations never want to invest in Oklahoma
  • TPS board reverses course, approves plan merchandise
  • Ginnie Graham: You should not enable the public college bullies gain
  • Trustworthy by Venables, improved by an offseason of modify, Ethan Downs is all set for his opportunity
  • New federal report highly crucial of Oklahoma’s use of pandemic aid cash for education and learning
  • With Tulsa’s COVID risk upgraded and instances growing, regional ER leaders force precautions, vaccination
  • Todd Drummond, son of ‘Pioneer Female,’ enters 2022 with substantial anticipations
  • Michael Total: How a ‘neglected’ space south of downtown Tulsa is lastly obtaining a next chance
  • OSU wrestler AJ Ferrari accused of sexual assault, no longer on the group
  • Guerin Emig: Joking or not, Mike Gundy spoke what Significant 12 allies considered when he warned of OU, Texas subterfuge
  • Actress Sophia Bush turns marriage ceremony highlight on Tulsa’s Greenwood local community
  • Assistant Oklahoma solicitor standard arrested right after Broken Arrow police chase, crashes

Picture source: Getty Photographs.

But all told, boasting Social Protection before FRA commonly suggests locking in a lower advantage for everyday living. And you may well regret going that route if these variables use to you.

1. When you never have much retirement personal savings

If you have a generous nest egg, the revenue you get from Social Safety may possibly only be secondary. In that circumstance, you might be in a placement exactly where you can probably manage a strike to your benefits.

But if you never have substantially income socked absent for retirement, then you may possibly require all the earnings you can get from Social Security. Submitting early could place you in a hard placement wherever you are not able to control even your primary bills.

2. When you’re even now doing work

The moment you achieve FRA, you can gain any amount of cash without the need of it impacting your Social Safety added benefits. But if you declare rewards prior to FRA and are nevertheless operating, you may risk owning some of that revenue withheld if your wages exceed the earnings-exam restrict.

That limit modifications each individual 12 months. In 2022, you can get paid up to $19,560 a year with no affecting your gains. But from there, you are going to have $1 in Social Security withheld for each $2 of earnings higher than that threshold. So if you are nevertheless operating, you may regret filing for positive aspects early simply because you may perhaps not get to hold them in total, but you are going to nevertheless slash them owing to not waiting around until finally FRA.

3. When you reside a lengthy daily life

If you will not be expecting to are living pretty extended, then declaring Social Security ahead of FRA could make sense, due to the fact it could consequence in a greater quantity of total lifetime money. But if you count on to dwell a long existence, then submitting early will commonly mean shortchanging yourself on life span gains as properly as monthly rewards.

What’s the appropriate simply call?

Some persons have no alternative but to claim Social Security early, these kinds of as if they reduce their work opportunities in their early or mid-60s and want the revenue. But if the higher than eventualities use to you (or if you imagine they’re going to utilize to you in the situation of living a extensive existence), then it could fork out to hold out until eventually FRA comes to signal up for gains. Executing so could imply preventing not just a reduction, but a entire world of money anxiety to stick to.

The $18,984 Social Safety bonus most retirees fully ignore

If you are like most Us citizens, you are a several years (or much more) driving on your retirement cost savings. But a handful of minimal-acknowledged “Social Safety strategies” could enable ensure a improve in your retirement money. For example: one particular straightforward trick could pay you as a lot as $18,984 much more… every single 12 months! Once you study how to improve your Social Security rewards, we assume you could retire confidently with the peace of mind we’re all immediately after. Merely click listed here to discover how to master additional about these methods.

The Motley Fool has a disclosure plan.

Credit cards that offer the best travel insurance coverage

Credit cards that offer the best travel insurance coverage

Ideal for vacation incident insurance

Chase Sapphire Reserve

Coverage facts: $1 million in coverage

(Credit score: AnnaStills/Adobe Inventory)

Most effective for travel accident insurance coverage (organization)

Ink Organization Endless Credit score Card

Coverage aspects: $500,000 in protection

(Credit: Seventyfour/Adobe Inventory)

Finest for luggage insurance plan

Chase Sapphire Favored Card

Coverage information: $3,000 in dropped baggage protection

(Credit rating: jumlongch/stock.adobe.com)

Ideal for luggage insurance (company)

Ink Enterprise Limitless Credit Card

Coverage aspects: $3,000 in missing luggage coverage $500 in delayed baggage coverage for each trip.

(Credit: byeolsan – stock.adobe.com)

Very best for journey hold off/cancellation coverage

Chase Sapphire Desired Card

Coverage particulars: $20,000 for every excursion in cancellation coverage $500 per ticket in vacation delay protection

(Credit: Ekaterina Pokrovsky/inventory.adobe.com)

Finest for trip hold off/cancellation insurance coverage (organization)

Ink Small business Endless Credit score Card

Protection aspects: $10,000 for every excursion in cancellation coverage $500 for each ticket in journey hold off coverage

(Credit: Nikolay N. Antonov/Adobe Stock)

Greatest for overall journey insurance plan coverage

Chase Sapphire Most popular Card

Protection facts: $500,000 in journey accident protection $3,000 in missing luggage protection $500 per excursion in delated baggage coverage $20,000 for every journey in cancellation protection $500 for every ticket in trip hold off protection

(Credit score: Seventyfour/Adobe Inventory)

Ideal for general vacation insurance policies coverage (organization)

Ink Company Unlimited Credit Card

Coverage information: $500,000 in journey accident coverage $3,000 in lost baggage protection $500 per journey in delayed baggage protection $10,000 for every journey in cancellation coverage $500 for each ticket in journey hold off protection

(Credit history: prostooleh/Adobe Stock)

There are a great deal of factors to take into account when picking out a credit history card, but even though you’re sizing up interest costs and rewards, it is also crucial to think about the protections your card can offer you, specifically if you use your card to travel.

Recently, WalletHub launched a report for which they examined 92 credit score playing cards from the 10 major issuers to determine out which playing cards offer you the best protection when traveling for the two own and small business functions. They looked at several places of protection as they as opposed the cards’ travel insurance policies offerings.

Travel incident coverage

The average policy consists of $250,000 of death and dismemberment protection for the major cardholder and authorized buyers and their spouse or domestic spouse. The best playing cards, WalletHub states, offer up to $500,000 of demise and dismemberment coverage, which extends further than the primary cardholder to not only their spouse/husband or wife, but also any dependent youngsters and in some cases even much more distant loved ones members, this kind of as mother and father-in-regulation.

Baggage insurance coverage

WalletHub located the average credit history card with vacation insurance coverage provided $3,000 of dropped luggage coverage, but no coverage for delayed luggage. Meanwhile, the very best policies provide not only $3,000 of coverage for shed baggage, but $500 for delayed luggage, which aids reimburse the cardholder for required private and business products they ought to substitute in advance of their bag comes.

Journey hold off/ cancellation coverage

The ordinary credit card doesn’t present any form of hold off or cancellation coverage, the report observed. Nevertheless, some insurance policies offer as a lot as $20,000 for every journey if it is cancelled or slash brief and up to $500 if a journey is delayed much more than 12 hrs.

In the slideshow higher than, we’ll appear at WalletHub’s options for the credit history cards with the strongest coverage choices for both personalized and enterprise vacationers.

Associated: