USI Affinity Travel Insurance Services Named to Forbes Advisor’s List of Best Travel Insurance … | News

USI Affinity Travel Insurance Services Named to Forbes Advisor’s List of Best Travel Insurance … | News

PHILADELPHIA, March 24, 2022 (Globe NEWSWIRE) — USI Affinity right now introduced that its vacation insurance coverage division, USI Affinity Journey Insurance policies Companies, has been named to Forbes Advisor’s annual checklist of the Most effective Vacation Insurance policies Organizations for the third yr in a row. USI Affinity been given a top ranking on this year’s record based on policy positive aspects and obtainable coverage choices most essential to vacationers. In its analysis, Forbes Advisor scored 46 guidelines to discover the ideal journey insurance designs making use of details supplied by Squaremouth, a journey insurance coverage comparison service provider. The 2022 rankings were being based mostly on every single plan’s score for added benefits and common prices for several outings and traveler profiles. The advantages that had been scored bundled healthcare fees, health-related evacuation, Covid protection, pre-present ailment exclusion waivers, “cancel for any reason” coverage, vacation interruption, vacation hold off time necessities, baggage delay time prerequisites, baggage reimbursement, hurricane and temperature protection requirements, and fiscal default of a vacation supplier. “USI Affinity is very pleased to as soon as yet again be regarded by Forbes Advisor this yr. For the duration of the very last two a long time, the journey insurance plan industry has been enormously impacted by the coronavirus pandemic, like so quite a few other industries,” said USI Affinity’s Travel Insurance plan Division Leader, Daria Porreca. “Throughout this time, we have worked diligently to adapt and respond to switching polices although assembly the evolving wants of vacationers. In addition, our longstanding associations with our provider associates have allowed us to develop a suite of goods that can benefit a variety of distinct traveler profiles. We seem ahead to ongoing advancement, solid partnerships and options to serve both equally our faithful and new prospects as journey proceeds to rebound in 2022.” USI Affinity Vacation Insurance plan Solutions also had plans showcased on 4 other 2022 Greatest-Of lists by Forbes Advisor: Greatest Covid-19 Journey Insurance coverage, Greatest Terminate for Any Explanation Vacation Insurance plan, Most effective Senior Vacation Coverage and Best Cruise Insurance coverage. Forbes Advisor is a reliable place for impartial income and business enterprise guidance, news and critiques, committed to aiding consumers make smart conclusions and pick out the proper items with relieve. To perspective Forbes Advisor’s total list of the Finest Travel Coverage Organizations of 2022, visit their rankings webpage. About USI Affinity For over 75 many years, USI Affinity has formulated, marketed and administered plans to deliver special positive aspects in coverage protection, cost and assistance. USI Affinity marketplaces and administers insurance policy courses for about 440 companies nationwide, representing more than 22 million association, union and alumni users. USI Affinity is a division of USI Insurance plan Services. For a lot more info about USI Affinity, you should stop by www.usiaffinity.com.

###

Attachment

Forbes Advisor

Daria Porreca USI Affinity 610-537-1336 daria.porreca@usi.com Timothy Denton USI Insurance Solutions 914-747-6339 timothy.denton@usi.com

Copyright 2022 GlobeNewswire, Inc.

BlackRock’s Gargi Chaudhuri Details Career, Investing Advice

BlackRock’s Gargi Chaudhuri Details Career, Investing Advice
  • Gargi Pal Chaudhuri oversees technique at the $2.2 trillion iShares Americas unit at BlackRock.
  • Chaudhuri shares how she overcame a lack of illustration through her 20-12 months occupation.
  • She also claims that “bite-sized” means are important to setting up wealth and economic literacy.

Gargi Pal Chaudhuri is 1 of the most popular ladies in finance these days.

But when Chaudhuri initially stepped on to the investing flooring at Merrill Lynch two a long time ago, she fully meant for her summer season internship there to be just a different short stint on her way to earning a PhD in psychology. Then Merrill Lynch extended her a entire-time supply to keep on, which she made the decision to take for the “future number of a long time” in advance of pursuing her aspiration of graduate college.

Twenty several years later, Chaudhuri oversees expense method for BlackRock’s iShares Financial commitment Tactic Americas, with around $2.2 trillion in assets under administration — and all devoid of a graduate diploma.

“I fell in adore with the sector, to be extremely truthful,” Chaudhuri admitted in an interview with Insider. “I graduated in 2001 and the


Federal Reserve

experienced a big part in the markets at that stage … acquiring a entrance-row seat to monetary coverage and how it performs out in the sector has just been completely outstanding.”

Even ahead of Wall Street, as a twin accounting and psychology main in college or university, Chaudhuri experienced always been fascinated by the economic rules of source and need in a detached form of way. But soon after witnessing these market forces up shut and own even though operating on a bond trading desk, she was marketed on a profession in finance.

Navigating Wall Street’s lack of representation

As a woman immigrant operating in the typically male-dominated industry of investing, Chaudhuri was pressured incredibly early on to deal with what she however believes to be the largest challenge on Wall Avenue: a absence of illustration.

“When I was youthful, not observing men and women that comprehended the place I came from or even that appeared like me … that was challenging,” she acknowledged. “It was not that individuals were unkind. I feel absolutely everyone was fantastic, but not possessing a job product, that was undoubtedly something that I wished was different.”

This absence of representation is altering today for the improved, stated Chaudhuri, but she still emphasizes that females ought to not “shy away” from the subject.

“Study after review has proven that ladies are incredibly good income managers when they do commit. When they’re offered chances, they do are inclined to outperform simply because they are great hazard administrators,” described Chaudhuri. “And a major section of being a strong portfolio manager or a good trader is remaining capable to recognize when you happen to be appropriate and when you have to cut your losses.”

Chaudhuri thinks that the asset administration industry’s inherent transparency is also advantageous for selling spend clarity and gender equality among workers.

“Your effectiveness speaks for your do the job, and your performance can be pretty community,” she reported. “If you take care of a mutual fund, anyone appreciates what the effectiveness is.”

To navigate a far more male-dominated industry on a functional level, Chaudhuri advises gals to “not wait around for that fantastic mentor” who “appears particularly like them,” but as an alternative to seek out any one keen to assistance offer advice.

All through her individual profession, other Indian gals had been several and much involving on Wall Avenue, so Chaudhuri sought mentorship from other colleagues, which includes Rick Rieder, BlackRock’s chief investment decision officer of international mounted earnings.

“There’s quite a few different types of persons who will all come with each other and be your board of advisors and enable you cultivate your occupation,” she discussed. “Everyone can be your mentor, and I have found that to be the scenario.”

“Bite-sized” means can improve economic literacy

Chaudhuri thinks that “the most highly effective matter a female can do is spend in the marketplace and observe her prosperity develop.”

Investing in the market place, she elaborated, is the very best way for girls to vote with their values and manage their personal financial future. But however, studies continue to exhibit that women of all ages are not investing at the very same level as gentlemen, which is why 1 of Chaudhuri’s passions is encouraging ladies to take into account their expense behaviors and portfolios.

“You do not have to know every little thing about the marketplaces to spend in the markets, but you have to be investing in a diversified fashion for the extended-expression,” she mentioned.

Even girls who usually are not deeply fascinated in money markets even now want to invest, stated Chaudhrui, and she invites them to increase their economical literacy by next the markets in creative methods.

“Glimpse, not everyone’s fascinated in reading through a major 400-web page ebook about the record of central financial institution coverage,” mentioned Chaudhuri. “But if you can obtain a 20-minute podcast or come across five persons to follow on LinkedIn or Twitter that are speaking about the current market, then that could be your little chunk-sized access to expense know-how which then can help you transform your own expenditure conduct and just take manage of your prosperity creation.”

What’s the average cost of homeowners insurance?

What’s the average cost of homeowners insurance?

Our goal here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” below, is to give you the tools and confidence you need to improve your finances. Although we do promote products from our partner lenders who compensate us for our services, all opinions are our own.

The average cost of homeowners insurance varies by state and the amount of coverage you need. (Shutterstock)

Homeowners insurance typically pays to repair or replace your home in many cases if it’s damaged by a fire, crime, or another unexpected event. 

The price you’ll pay for your policy can vary significantly based on a number of factors, including where you live. This article covers what those factors are, as well as the average cost of homeowners insurance.

You can easily compare homeowners insurance quotes with Credible. 

What’s the average cost of homeowners insurance?

The average cost for homeowners insurance across the U.S. is $1,251 per year, or $104.25 per month, according to National Association of Insurance Commissioners data

This figure has been on the rise in recent years. That’s because of an increase in home repair and rebuilding costs, higher catastrophe losses due to extreme weather, and more people relocating to disaster-prone areas.

Your actual cost of homeowners insurance can vary widely based on the specific type of policy you choose, your location, and a host of other factors. 

Factors that affect the cost of homeowners insurance

Your quote for a homeowners insurance premium takes many factors into account, including: 

  • Age of the home — Newer homes may have lower insurance costs than older homes. If a home is particularly old, you may struggle to find adequate coverage.
  • Type of construction — Your house’s construction style can affect its risk of being damaged in a fire or storm. Frame houses, for example, may be more expensive to insure than brick homes.
  • Location — The setting of your home can affect the price of insurance in either direction. For example, homes in urban areas may face a higher risk of crime, but have better fire protection services — while homes in rural areas may have the opposite dynamic. The quality of your area’s fire department is particularly important to homeowners insurance companies. Your city may have a fire protection class rating that insurers use to set prices.
  • Deductible — A deductible is the amount you pay toward a repair before insurance kicks in. The higher your deductible, the lower your premium tends to be, but the more money you pay out of pocket when you file a claim.
  • Amount of insurance coverage — You’ll want to buy enough insurance to cover the cost of replacing your home in the event of a total loss, making your total coverage highly dependent on real estate and construction costs. The more coverage you need, the higher price you’ll pay.
  • Risk of natural disasters — Certain parts of the country are more prone to disasters like hurricanes, brush fires, and tornadoes. These areas may require you to pay higher premiums.
  • Local laws and regulations — Homeowners insurance is heavily regulated, with rules varying from state to state that can affect insurance costs. Certain states may require specific levels of coverage, which can increase your cost.
  • Your claim history — If you’ve filed numerous homeowners insurance claims in the past, you may face higher costs when you renew or purchase a new policy. This can happen even if the claims you filed weren’t your fault.

Average cost of homeowners insurance by state 

Here’s the average cost of homeowners insurance in the U.S. by state, according to the National Association of Insurance Commissioners:

What are the most expensive states for homeowners insurance?

The most expensive states for homeowners insurance all lie on the Gulf Coast, an area at particular risk for hurricanes. All three states have been hit hard recently, with homeowners incurring billions in damages.

  • Florida — $1,954 average annual premium, or $162.83 per month
  • Louisiana — $1,906 average annual premium, or $158.83 per month
  • Texas — $1,878 average annual premium, or $156.50 per month

What are the least expensive states for homeowners insurance?

The three states with the least expensive homeowners insurance aren’t in areas traditionally prone to hurricanes or tornadoes. Their premiums are less than half the average premiums in the most expensive states.

  • Oregon — $731 average annual premium, or $60.92 per month
  • Utah — $737 average annual premium, or $61.42 per month
  • Idaho — $787 average annual premium, or $65.58 per month

Visit Credible to compare homeowners insurance quotes from various carriers, all in one place.

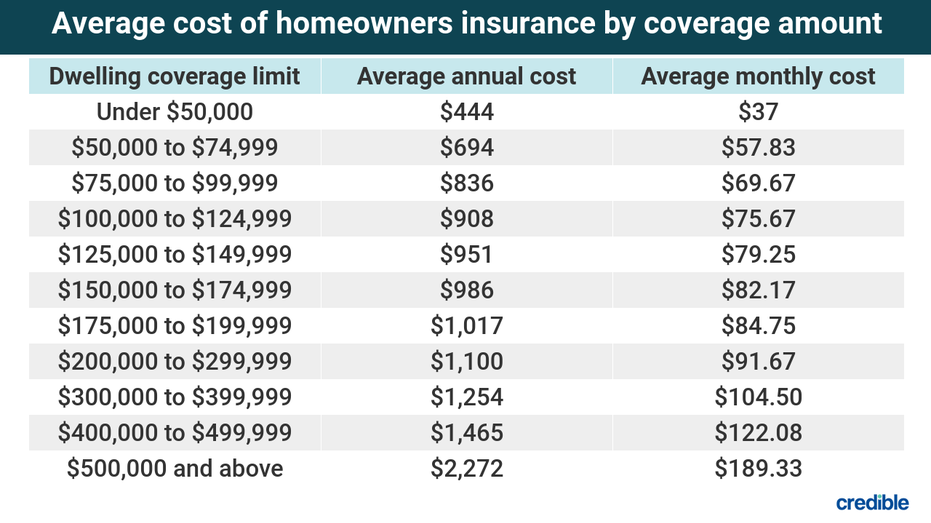
Average cost of homeowners insurance by coverage amount

Homeowners insurance policies generally have a dwelling coverage limit, or the maximum amount an insurance company will pay out to repair or replace a damaged house. More-expensive homes require you to buy a higher dwelling coverage limit, which can have a major effect on your premium.

Here’s the average cost of homeowners insurance by coverage amount, according to the National Association of Insurance Commissioners:

How to lower the cost of homeowners insurance

If any of the average prices give you sticker shock, keep in mind that it’s possible to lower the cost when you buy homeowners insurance. Consider these strategies:

  • Bundle multiple insurance policies. You may have a number of different insurance policies, including auto insurance, life insurance, and business insurance. Some insurance companies may give you discounts if you choose to have multiple policies with the same company, which is called bundling.
  • Take advantage of discounts. Some insurers will give you a discount on your policy if you do things like install a security system or sprinkler system.
  • Increase your deductible. The higher your deductible, the more you’ll pay out of pocket if you file a claim — but the lower your insurance premium will be.
  • Shop around. Once you determine the level of insurance coverage you need, you can get quotes from multiple companies. You may find that the price is significantly cheaper from one insurer to another. Just be sure you’re comparing similar policies.

Homeowners insurance FAQs

Read on for the answers to a few of the most common questions people have about homeowners insurance.

Why does homeowners insurance go up?

The cost of your homeowners insurance may rise over time for a variety of reasons, and some of them are specific to your home. Your homeowners insurance may also get more expensive as your home ages, for example, since older homes tend to be more at risk of damage. You may face a higher premium if you have a history of filing homeowners insurance claims, even if they’re for issues that weren’t your fault.

Plus, factors beyond your home can influence rising prices. One of them is inflation: The price of construction, materials, and other items you’d need to repair or replace your home goes up over time, so your insurance does too. Your policy may automatically increase its coverage (and likely its cost) to keep up with overall inflation. Homeowners insurance rates may also go up in your area if your town has been hit by an unusual number of natural disasters or other catastrophes recently.

Does homeowners insurance affect your mortgage payment?

Yes, in a way. You typically won’t pay your homeowners insurance company directly for your policy. Instead, you’ll pay for your homeowners insurance as part of your monthly mortgage payment, with your lender holding the money in an escrow account and making the premium payments on your behalf. This allows the lender to ensure your homeowners insurance is paid on time, protecting its investment as well as your own. If the cost of your homeowners insurance goes up, so will your mortgage payment. 

What’s not covered by homeowners insurance? 

Homeowners insurance policies generally spell out when damage to your home will be covered and when it won’t. (It usually depends on what caused the damage.) In most cases, your policy will cover damage from fire or storms but won’t cover flood damage or earthquakes. Your policy may or may not cover damage from hailstorms or windstorms.

Wear and tear is generally not covered under a homeowners insurance policy. Your vehicles generally aren’t covered, even if they’re damaged in an event that also damages your house, and your pets aren’t covered either. 

You can usually see what’s not covered under your policy in the “exclusions” section, or you can speak with your insurance agent to find out.

With Credible, you can compare homeowners insurance quotes from different carriers in minutes.

‘Gargantuan Task’: Why India’s Renewable Push Will Be Hard | Business News

‘Gargantuan Task’: Why India’s Renewable Push Will Be Hard | Business News

By ANUPAM NATH and ANIRUDDHA GHOSAL, Associated Press

NAGAON, India (AP) — Designs to create a sprawling photo voltaic park on land cultivated for generations by indigenous farmers in India’s Himalayan foothills erupted in violent clashes with police last 12 months soon after their crops were bulldozed for the improvement.

Most gentlemen from the farming village of a several hundred in Assam state were being out searching for do the job on Dec. 29. A person of the several individuals who remained was Champa Timungpi, who claims she was beaten by law enforcement and kicked in the tummy when she attempted to protest.

Pregnant at the time, the 25-12 months-aged was rushed to a hospital for her accidents. “I came back again household at evening, and I miscarried,” reported Tumungpi, who lodged a grievance with police.

The lush eco-friendly village in Nagaon district — still largely unconnected to the grid and home to family members who earn fewer than $2 a day — is now framed by blue solar panels, barbed wire and armed guards.

Political Cartoons on World Leaders

Political Cartoons

The solar developer Azure Electricity, shown on the New York Inventory Exchange, explained in an e-mail that the organization lawfully acquired 91 acres (38 hectares) in the village from “recorded landowners” and it’s “incorrect and erroneous” to say the land was forcibly taken.

The firm’s situation is strongly disputed by Timungpi and many others in the Mikir Bamuni village who say their legal rights as tenants and proven farmers were being disregarded. Area officers and police did not answer to requests for comment.

However it performs out in a district courtroom, the dispute not only speaks to India’s generally-tangled land ownership guidelines rooted in its colonial era. It also illustrates the complexity and immensity of the troubles experiencing the country of virtually 1.4 billion folks in meeting its renewable power targets for the following decade.

About the future 20 a long time, India’s demand from customers for electric power will develop additional than anywhere else in the world. Compared with most countries, India however has to acquire and elevate tens of millions like Timungpi from poverty, and it will require to construct a electricity method the size of the European Union’s.

How India meets its vitality and financial requirements will have an outsized influence on the world’s weather objectives. The place is a important contributor of greenhouse gases from the burning of coal and other fossil fuels.

Key Minister Narendra Modi explained at very last year’s United Country climate talks that India would enhance its capability of non-fossil fuels electricity to 500 gigawatts by 2030 — from the 104 gigawatts at the get started of this 12 months.

To meet up with its targets, India have to incorporate four situations the volume of energy the ordinary nuclear plant provides — every single month right up until 2030.

These brief-phrase strength targets will not do considerably to restrict worldwide warming to 1.5 Celsius (34.7 Fahrenheit) — the degree over and above which experts warn of catastrophic weather impacts, experts at previous year’s United Nations climate conference experienced warned.

But for India, it’ll continue to be a “gargantuan activity,” demanding investments in between $20 billion and $26.8 billion, when only $10 billion is obtainable, a parliamentary committee said previous thirty day period.

Some road blocks to renewables — these types of as the want to establish electrical power storage for when the sun isn’t shining or wind isn’t blowing — are global worries. Other individuals are additional particular to India — such as the problem of who owns land in poor communities that bear minimum obligation for the local weather disaster and the have to have to realign electrical power devices that have relied on coal for hundreds of years.

Although you will find no apparent roadmap but for India’s renewable electricity thrust, professionals cite a federal report past 12 months that mentioned an optimum combine would be finding more than fifty percent the country’s electrical power from the sunlight and wind by 2030.

But major solar and wind services are sparking conflicts with community communities. This is partly mainly because land ownership is fuzzy at several task web sites. For instance, some communities have utilised land for hundreds of years to farm or graze cattle without having lawful legal rights over it.

As governments and corporations concentrated on transitioning absent from fossil fuels, such conflicts were “collaterals” that had to be managed, Kanchi Kohli, an environmental researcher at the Indian consider tank Centre for Coverage Research.

Required environmental impact assessments had been waived for photo voltaic and wind jobs to make them additional practical. But environmental concerns even now have arisen.

For instance, India’s Supreme Court in April 2021 requested that transmission strains for solar electricity be set underground immediately after environmentalists described the lines had been killing critically endangered terrific Indian bustards. Nine months later, the federal government said burying the traces to safeguard the birds would be far too expensive and would impede environmentally friendly electricity improvement. The court docket is listening to the matter again.

India could decrease its dependence on big photo voltaic parks by developing photo voltaic panels on roofs in metropolitan areas.

The country’s original rooftop plans were being tiny, but in 2015 it set a goal of 40 gigawatts of rooftop solar, ample to ability 28 million residences. Prospects ended up authorized to send electrical power back to the grid — and the sector grew.

In December 2020, the federal govt modified regulations proscribing significant industries and companies from sending energy back again to the grid. These industrial teams are among the greatest spending clients for India’s perennially dollars-strapped ability distribution firms, which missing more than $5 billion in 2020.

With industries sending electrical energy back again to the grid in the evening when demand and ability tariffs are maximum, distribution organizations ended up dropping their finest customers stated Vibhuti Garg, an electrical power economist at the Institute for Electricity Economics and Economical Assessment.

“They were being shedding money,” Garg reported.

The set up value makes rooftop photo voltaic way too high priced for most homeowners. That was the scenario for Siddhant Keshav, 30, a New Delhi entrepreneur, who needed to set solar panels on his house. “It just did not make sense,” he claimed.

Homes comprised much less than 17{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of India’s rooftop solar in June 2021, in accordance to a report by Bridge to India, a renewable energy consulting business. And India has only managed to attain 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of its 2022 rooftop photo voltaic focus on.

Wind could turn out to be a different significant component in India’s clean up electricity portfolio. But the most “attractive, juicy, windy sites” have little turbines applying outdated technological know-how, explained Gagan Sidhu, the director of strength finance at consider tank Council on Energy, Atmosphere and H2o.

By retiring previous wind turbines created right before 2002, India could unlock a capability of 1.5 gigawatts, in accordance to a 2017 study by Indo-Germany Strength Forum, the consulting company Idam Infra and India’s renewable energy ministry. But professionals mentioned it is unclear who would do the retrofitting and pay the invoice.

With a shoreline of about 4,670 miles (about 7,500 kilometers), India could most likely construct enough offshore wind farms to present about a 3rd of the country’s 2021 energy ability by 2050, according to an assessment led by the Global Wind Strength Council.

But these are incredibly high-priced to establish — and the to start with this kind of undertaking, a wind farm proposed for the Arabian Sea in 2018, has still to get underway.

Ghosal described from New Delhi. AP journalist Chonchui Ngashangva in New Delhi contributed to this report.

The Associated Push Health and fitness and Science Division gets support from the Howard Hughes Clinical Institute’s Department of Science Education. The AP is exclusively dependable for all material.

Copyright 2022 The Affiliated Press. All rights reserved. This substance may perhaps not be revealed, broadcast, rewritten or redistributed.
Stargate Finance attracts $1.9B in six days

Stargate Finance attracts .9B in six days

Stargate Finance, a cross-chain protocol developed to help consumers in transferring property among unique blockchains, has accrued around $1.9 billion in total benefit locked (TVL) in less than a 7 days immediately after launching.

Stargate markets by itself as a liquidity transport protocol that permits people to transact native assets cross-chain, featuring decentralized finance (DeFi) users the choice of staking stablecoins in swimming pools the place they are paid out out in the indigenous Stargate token (STG).

The fast developing TVL is likely down to the “up to 26{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} APY” being available farming stablecoin deposits.

By attracting just about $2 billion in TVL at the time of composing, Stargate has cemented alone as one particular of the major 10 DeFi tasks, in accordance to comparative information from DeFi Pulse.

Stargate has a high-profile supporter in quantitative crypto trading business Alameda Exploration CEO Sam Trabucco.

In a Twitter thread to his 150,000 followers, Trabucco announced that Alameda Investigate experienced purchased all readily available Stargate tokens (STG) that had been auctioned off in the course of Stargate’s start on March 17.

In accordance to LayerZero, the protocol that Stargate operates on, 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the full supply of STG or 100 million tokens, have been auctioned off to make liquidity across the seven blockchains that Stargate is launching on.

LayerZero protocol markets alone as an “Interoperability protocol that really works”.

According to a blog publish from LayerZero Labs Co-founder and CTO, Ryan Zarick, the Stargate protocol solves one thing known as the “Bridging Trilemma” by applying unified liquidity swimming pools among chains, instant certain finality of transactions and the use of indigenous property for cross-chain swaps.

Stargate designs to make it doable for any consumer to transfer assets from just one blockchain to an additional a person in a solitary transaction, skipping above the need to have for employing sophisticated and convoluted methods this kind of as locking, minting and burning and redeeming property.

Linked: Vitalik Buterin offers thumbs down to cross-chain apps

The LayerZero team also announced that they had employed Maki, the co-founder of SushiSwap, to guide organization improvement at Stargate.

Stargate is at this time are living on seven principal chains which includes Ethereum, Polygon, Avalanche, BSC, Fantom, Optimism and Arbitrum. The LayerZero workforce plans to insert assistance for other chains like Solana, Terra and Cosmos.