When Alli Williams married her partner in 2019, she realized she would be marrying into about $150,000 of scholar mortgage financial debt.
Now, a few many years later, she and her partner have gotten on the identical money web page with their budgets and lender accounts, and they’ve compensated off not only his pupil loans but also their credit score playing cards and their truck. Williams experienced turn into credit card debt-free independently when she was 25, and now, at 30, the few are credit card debt-totally free alongside one another.
“Paying out off financial debt is not the challenging portion,” Williams says. “Running your cash is the more durable component.”
Williams, a South Carolina-dependent cash coach and operator of FinanciALLI Focused, says that when she and her spouse acquired engaged in 2018, that was the to start with time they established a combined budget. They maintain their spending very low and gain from residing in a lower-value area, and they’ve been strategic about working with percentages of windfalls to fork out off debt and to conserve. But the actual essential, she claims? Recurrent interaction and test-ins about cash.
Income can be a quite personal and — at situations — nerve-racking ingredient of a romantic partnership. Dealing with debts, financial institution accounts, credit cards and expenditures together isn’t really only a logistical problem, it is also a new avenue for potential conflict. If just one fifty percent of a couple likes to help save income though the other particular person is a compulsive spender, that pair will likely have to have to have some complicated conversations to stay away from resentment in the prolonged run. For all those conversations, there are professionals who can give steerage and perception.
Men and women are also reading…
Benefits of a financial advisor for partners
Very similar to a therapist, a financial advisor or funds coach can produce a risk-free room for couples to examine troubles and plan for their futures alongside one another.
Liz and Dan Carroll, an Oregon-primarily based couple and homeowners of Conscious Money Coaches, have been married for 31 yrs. They use their personal success with cash management to deliver actionable advice to their shoppers, these as educating them how to create extended-phrase funds plans collectively.
“Everybody is a very good candidate for at least an once-a-year test-in with a income mentor,” Liz states. “And just like with the compound curiosity you get with investing, the previously you start off the greater.”
If you and your partner choose to perform with a qualified monetary advisor as a substitute of a dollars mentor, make positive to decide on a single that operates as a fiduciary, which indicates they’re obligated to place your interests ahead of financial gain. Nonfiduciary economic advisors make commissions from products they sell to their clientele, so they could force clientele to invest in or make investments in solutions that aren’t essentially helpful.
What choices do couples have for handling their money with each other?
There is no a person-measurement-matches-all remedy to controlling your finances, especially if you are element of a few. Some partners favor to have all of their dollars combined, other people like to retain their funds wholly individual, and some prefer a hybrid of the two. No issue the tactic, couples can use joint accounts to regulate shared bills and conserve for unique aims.
The Carrolls really don’t advocate that married couples separate their finances, nonetheless. Even if one particular husband or wife has debt or a very low credit rating score, they suggest that both of those partners consider on the duty of operating by economic stumbling blocks as a staff.
“Placing it with each other produces in general accountability,” Liz suggests.
“Couples generally convey their individual burdens and strengths into a relationship,” Dan provides. “So if you’re going into a partnership, you have to take that you are going to take the superior with the negative.”
A idea from the professionals: Produce a price range just for ‘fun money’
Joint funds never automatically imply that you have to eliminate your autonomy. Williams and the Carrolls use a procedure in their associations that they say results in a sense of independence while being aligned on their funds: budgeting “pleasurable revenue” into person accounts for every human being.
“It’s like our ‘no questions asked’ cash,” Williams claims. “It is funds the place we don’t have to check in with just about every other prior to we expend it, like my partner paying out $10 at Chick-fil-A, or me paying out dollars at Amazon or Concentrate on. We use Ally Bank’s buckets attribute for our personal accounts, and we technically every single have accessibility to the two, but we really don’t want to test it.”
The Carrolls use a comparable solution for their pleasurable dollars.
“It’s continue to a line merchandise on the spending plan where by all the things comes into one particular bucket, and then some goes out into the enjoyment investing accounts,” Dan suggests. “We extremely suggest that each and every partner receives an equal amount of money, and then they can do whatsoever they want with it. It produces freedom for both of those men and women.”
Funds administration and interaction are foundational competencies for any committed intimate partnership, and, as Dan Carroll can attest, people competencies spill above into other places.
“It really is unanimous from the opinions we get from our clients that conversing through revenue will help the entire partnership.”
The posting For Valentine’s Day, Few Your Finances at first appeared on NerdWallet.
Get the most current neighborhood business information sent Totally free to your inbox weekly.
We planned our excursion to Turks & Caicos quite very last minute, just a few of times in advance of departure. I needed to share my working experience with the entry necessities, given that they’re kind of straightforward, but also variety of challenging. I didn’t see a complete ton about this on the internet in advance of our pay a visit to, so with any luck , my knowledge can support many others, How News Today.
Turks & Caicos entry prerequisites
At the time we planned our vacation, there have been four main entry demands for Turks & Caicos (allow me emphasize that travel limitations are frequently shifting, so examine the Turks & Caicos’ formal website page for recent restrictions):
All readers 16 yrs of age and more mature need to be absolutely vaccinated (nevertheless there’s no requirement to be boosted)
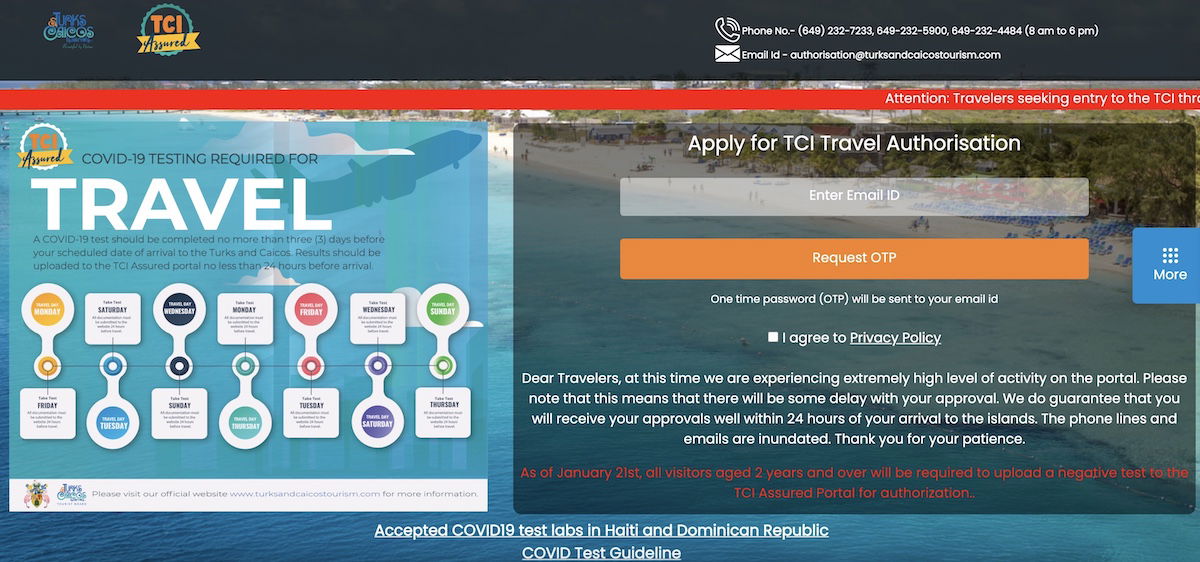
A adverse COVID-19 test end result is expected within just 3 times of vacation possibly a PCR or swift antigen take a look at is sufficient, and kids below two yrs previous are exempt from this necessity
Unique COVID-19 healthcare insurance policies that addresses any expenditures you could incur as a consequence of acquiring coronavirus
A done vacation authorization type, submitted at the very least 24 hrs in advance of your trip
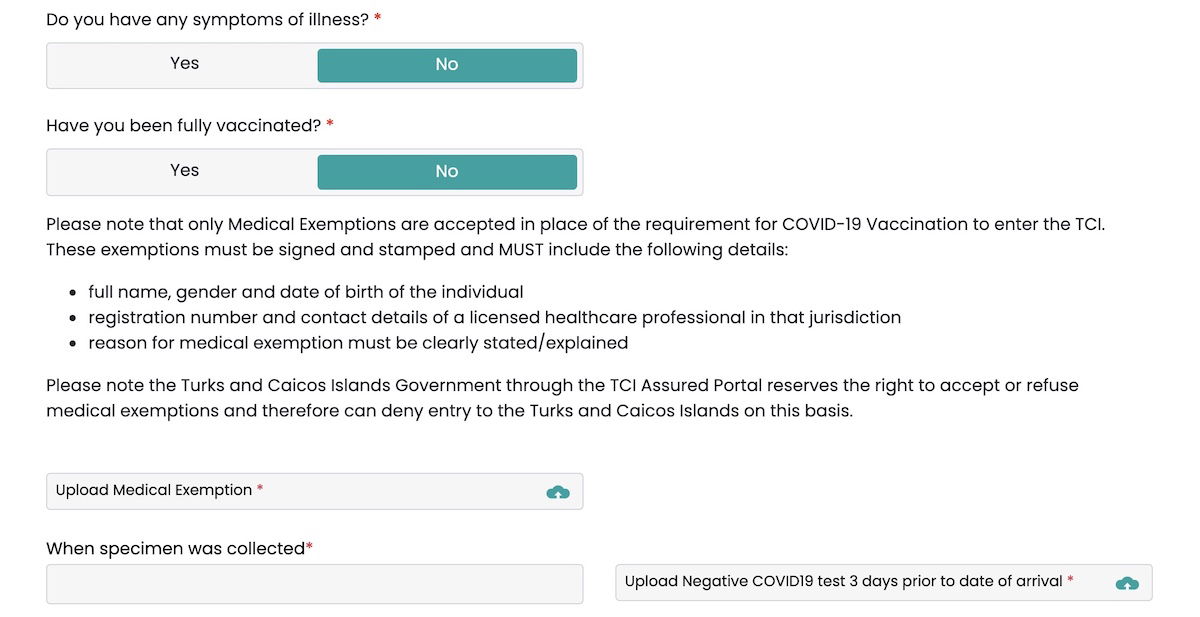
The need to be totally vaccinated is really simple, and needing a take a look at pre-journey was also uncomplicated, presented that a immediate antigen does the trick (and those people are uncomplicated to get with speedy benefits). So let me communicate a bit about the pre-vacation Turks & Caicos journey authorization, the insurance need, and my experience on arrival, How News Today.
Turks & Caicos travel coverage
Turks & Caicos demands journey insurance policy that covers coronavirus clinical fees and complete hospitalization, health professionals visits, prescriptions, and air ambulance. The adhering to are the proposed insurance policy providers:
Travelex
Seven Corners
TripMate
Aura
HTH Planet Extensive
Allianz Worldwide Aid
Generali Insurance policies
World-wide Rescue
HDI World-wide
Travel Guard
Journey Insured International
Trawick
Arch RoamRight
Apex Journey Limited
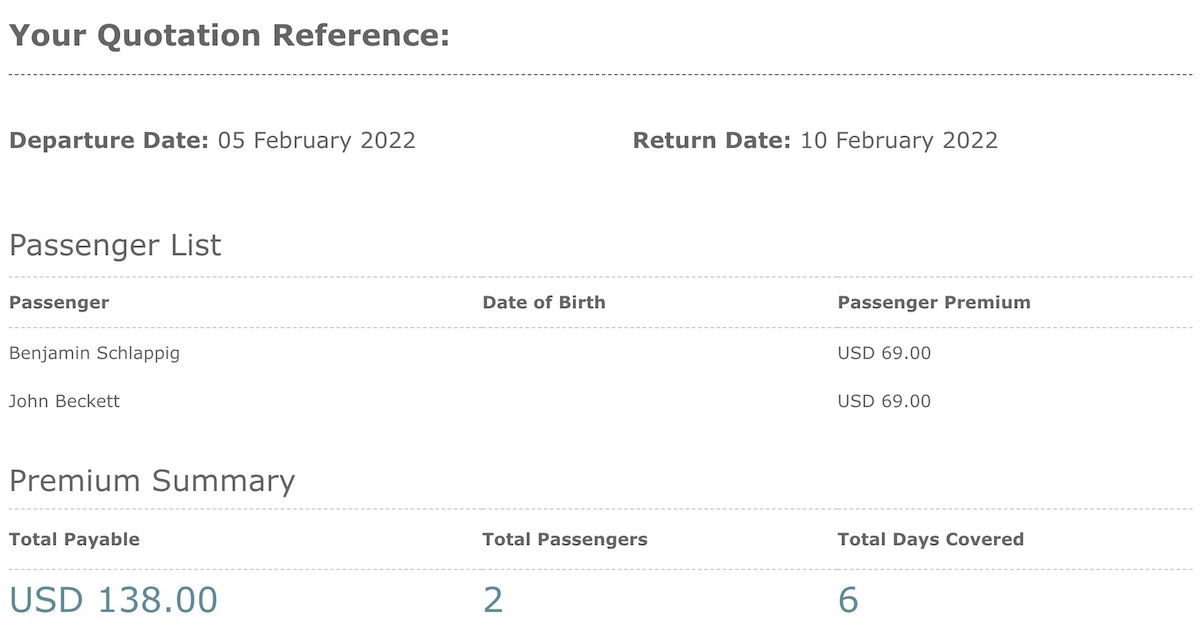
Just after doing some Googling, I made the decision to go with Aura insurance policies, and the course of action of finding insurance coverage was very simple. The business expenses $9.80 for each human being for every day, but the minimum price is $69 for every individual for each excursion.
On the moreover aspect, finding insurance policies was easy — it took only a couple minutes, and I was issued a plan promptly.
Sad to say credit score card insurance coverage won’t qualify for this necessity, so this does incorporate to the price of a journey to Turks & Caicos. Then all over again, other nations around the world charge bigger entry charges.
Turks & Caicos vacation authorization
Turks & Caicos necessitates all website visitors to complete a journey authorization prior to journey. It’s recommended that you submit this at the very least 24 hours prior to journey, however it is observed that “shorter periods can be accommodated, How News Today.”
The genuine facts requested with the vacation authorization was approximately what you’d expect. I initial had to sign up and then get a a person time password.
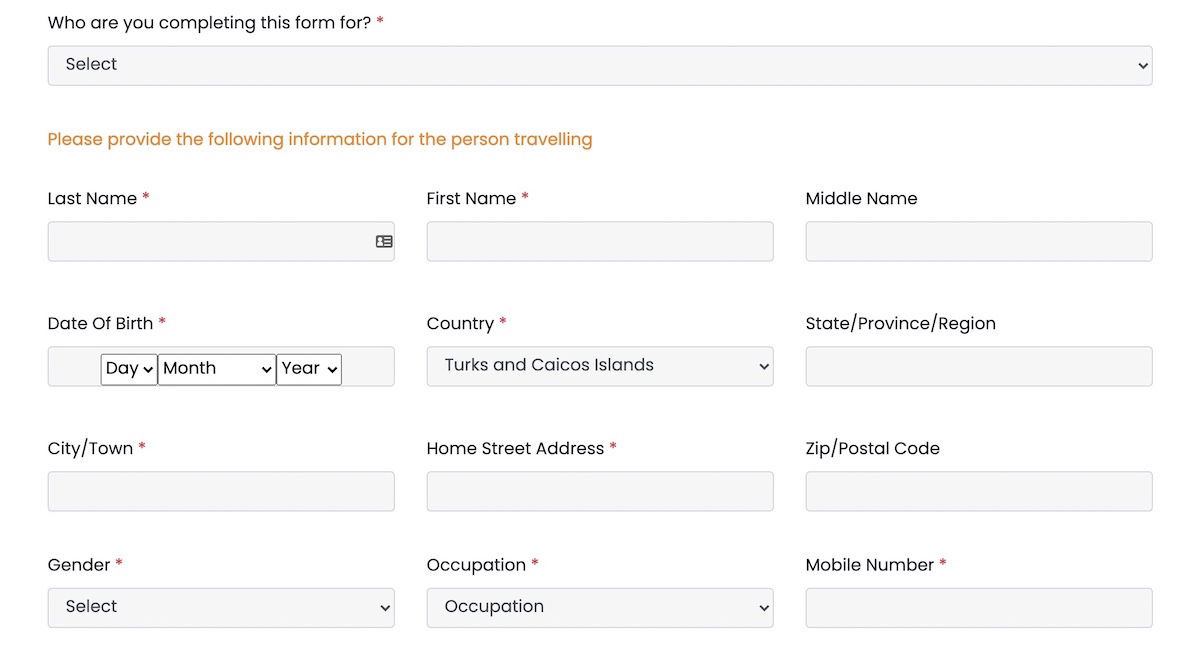
I then had to deliver personalized info, which includes my title, day of birth, deal with, profession, and more.
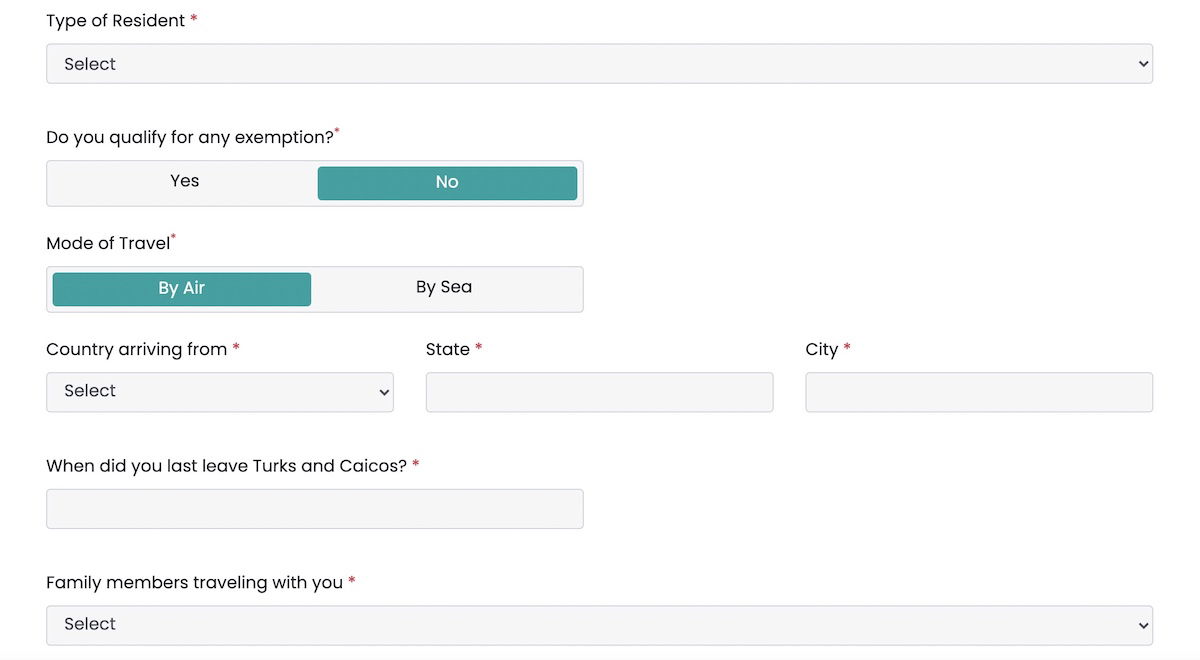
Oddly you are questioned if you have any family members traveling with you, but then you have to have to fill out a independent variety for them anyway, so I just experienced to supply the very same info twice.
Then I had to fill out a well being questionnaire, and was asked to add pictures of my vaccine card, unfavorable coronavirus test, and travel insurance policies.
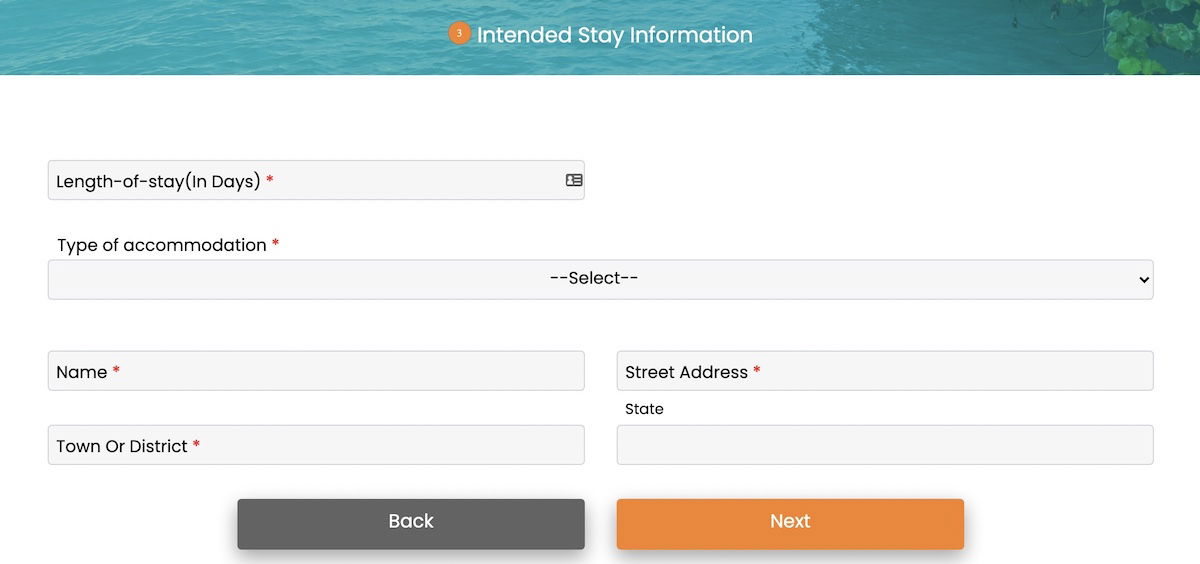
Finally, I was questioned about how lengthy and where by I was preparing on remaining in Turks & Caicos.
I submitted the kinds all over 26 several hours prior to our flight from Fort Lauderdale to Providenciales.
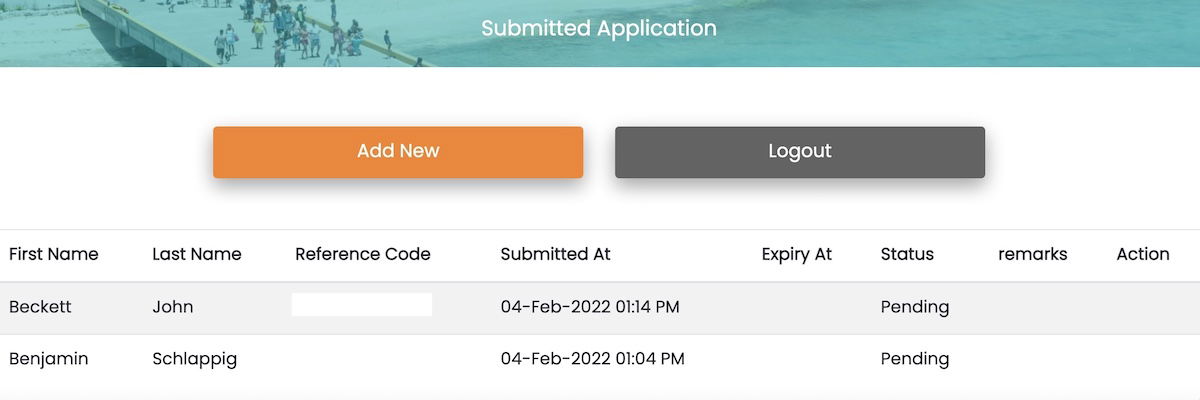
Just about an hour after submitting these documents, I acquired an e mail confirming that all the things experienced been accredited. Despite this authorization, I nevertheless experienced to give all of these paperwork though checking in for my flight.
Turks & Caicos arrivals experience
Fortuitously when we arrive in Turks & Caicos there were no other planes that landed all around the exact same time, so there was pretty much no wait there.
Right before getting to the precise immigration officer, we experienced to after again clearly show our vaccine playing cards, evidence of negative exams, and our travel authorizations. This was all quick adequate.
1 swift factor to be aware — we genuinely lucked out that there was no hold out at immigration, while I have also read of a lot of people today obtaining to hold out an hour or much more right after immigration, relying on how a lot of other flights arrive around the exact same time.
That’s why I believe it is at the very least value currently being knowledgeable that Turks & Caicos has a VIP arrivals services. For $75 for every particular person you can get a rapid keep track of by immigration. That would have been a full waste of money in our situation, but if you arrive at a well known time and would normally have to hold out an hour, I’m confident that’s a price quite a few folks would be keen to shell out.
An additional factor to note, while we’re at it. When you land at Providenciales Airport there are no private taxis available for use. The only options are shared vans that will likely prevent at several resorts. This is not necessarily that inefficient (it possibly additional 15 minutes to our driving time), but if you want a personal transfer you will have to arrange it in progress.
Base line
Turks & Caicos is open to vaccinated site visitors, even though there are some hoops to bounce via. You want to get tested inside of three days of travel (immediate antigen exams are ok), you need to invest in vacation insurance plan (which will charge all-around $10 for each particular person for every working day), and you have to have to fill out a pre-vacation authorization sort (preferably 24 hrs just before departure).
None of this was a big inconvenience, and we also lucked out that we arrived at a time when the airport was empty, so there was no wait at immigration.
If you’ve traveled to Turks & Caicos, what was your expertise with the entry prerequisites?
The investing information presented on this web page is for academic purposes only. NerdWallet does not offer advisory or brokerage companies, nor does it advise or recommend investors to purchase or market unique shares, securities or other investments.
A person of the least complicated approaches to regulate your cash better this yr is to hit the stick to button on some finance influencers. With out obtaining to do a lot operate at all, you are going to get a standard dose of own finance know-how in your social media feed, e-mail inbox or your queue of podcasts.
We talked to some of our beloved Black monetary professionals about the Wonderful Resignation, acquiring a residence in a aggressive housing market and regardless of whether investing in crypto is a fantastic thought.
1. Bola Sokunbi
We asked Bola Sokunbi (founder of Clever Woman Finance) what suggestions she’d give to task hunters:
“While you appear for operate, even even though your income could possibly be restricted ideal now, one particular point you have control in excess of is crafting a economic strategy for financial savings, credit card debt reimbursement, investing, and so on. You can also spend this time while you glance for perform to focus on budgeting and running the income and methods you have obtainable to you now. Don’t be frightened or ashamed to do the job down below your talent set or for much less spend for a momentary period of time, if you will need to have profits coming in ideal absent.”
2. Dasha Kennedy
Dasha Kennedy (The Broke Black Female) stated folks should embrace remote opportunities, irrespective of whether that is freelance operate or networking on the web:
“Don’t underestimate your means to use the competencies you’ve uncovered from your previous employer to gain revenue as a freelancer.
“If you are nonetheless in search of full-time work, proceed to community remotely. I believe that that the foreseeable future of perform is heading to be digital. The latest work local weather has forced quite a few businesses to obtain talent in unconventional ways these types of as social media, digital events and online occupation fairs.
“There’s at present a wave of people utilizing their transferable competencies to change professions and go into perfectly-having to pay, distant-dependent positions that are the full reverse of their earlier [jobs]. Ideal now is the excellent time to know when to pivot.”
Far more: If your work doesn’t give you purposeful perform, you owe it to on your own to sign up for the ‘Great Reshuffle’
3. Mandi Woodruff-Santos
Mandi Woodruff-Santos
mandimoney.com
We asked Mandi Woodruff-Santos (of MandiMoney) on what to take into account prior to shifting jobs:
“Just due to the fact the Excellent Resignation is taking place and a large amount of men and women are quitting, it does not always signify that this is the most effective time to give up for you.
“You’ve obtained to sit down with by yourself and ask by yourself, what is it about this position that is preserving you here? Am I receiving paid my current market charge? Do I feel like I have a great occupation progression in advance of me below?
“If the answers are no, then it could pretty effectively be time for you to go on. Also, proper now, it is hella competitive. So, if you want to stop appropriate now and get started wanting for jobs, get ready for a incredibly, yeah, really crowded market. There is a lot of individuals on the lookout suitable now. It’s not heading to be as quick or as straightforward as it might have been a number of years back for an individual on the lookout to soar ship.”
If you do have a career, Woodruff-Santos is a significant proponent of taking benefit of your retirement accounts:
“It’s not hot. It’s not remarkable. But for most Us residents, primarily most operating People in america, the 401(k) is it. 401(k) is bae, as I like to say, and not more than enough people today are even on the lookout at their 401(k)s. What am I investing in? Am I maxing it out for the calendar year? That’s what people ought to be asking by themselves.”
Also see: ‘Backlash is real’: Certainly, your workplace is probably racist — but how do you even get started to tackle this issue?
4. Michelle Singletary
Michelle Singletary (columnist at The Washington Submit) claimed “feelings are not points,” so if you approach to depart the workforce, leave with a fiscal plan: “Be sure you know how you can control your funds if you are likely to be in amongst jobs.
“If you’re retiring, be sure to do a retirement spending plan. And I imply genuinely crunch the figures. So quite a few people who retire early conclusion up possessing to go again to perform since they underestimated the charge of living, considering that retirement usually means you devote considerably less. You are going to even now have to eat and in all probability will try to eat out. You are going to continue to want to trip. You’ll nevertheless have housing fees, car or truck repairs, and so on.”
Also, she reported, possible homebuyers want to spending plan carefully, also.
“If you are in the sector for a home, really do not lose your perspective on what you can pay for. Don’t just use the qualifications the loan company takes advantage of. Sure, on their paper, you may perhaps seem to be equipped to pay for that home but they are employing your gross earnings. They may well not consider your need to have to go away space in your funds to conserve for an emergency fund, retirement or college or university costs for any youngsters you have.
“When my spouse and I shopped for our first residence, we didn’t purchase as a great deal dwelling as the lenders claimed we capable for. We realized we wished to aggressively help save for our retirements — and we have. We realized we didn’t want to consider on debt to send our kids to higher education — and we did not and neither did they. We realized we preferred to spend off our home finance loan in advance of we retire — and we will. We couldn’t have accomplished all that if we acquired a property finance loan that wouldn’t go away a lot area for these priorities.
Read through: ‘Mortgage charges jumped to the greatest degree considering that the emergence of the pandemic’: People in america are pessimistic about buying a household
“And most importantly, don’t think about yourself a failure if you can’t compete and nevertheless have to lease. Never pay attention to individuals who say you are throwing your cash away. You are not. You are receiving some thing for that lease — a roof above your head.”
5. Kenneth Chavis IV
Kenneth Chavis IV (senior prosperity manager at LourdMurray) mentioned housing prices will just maintain likely up. “If you lease and prepare to do so for a although, make positive you issue in long run rent hikes into your funds and shelling out options. Relying on the metropolis you dwell in, your rent could maximize 10-20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on your subsequent lease, so you will want to be fiscally well prepared for this fact.
Kenneth Chavis IV
LourdMurray
“For people that are hunting to purchase a house, owning a house is often significantly additional pricey than men and women expect, so be guaranteed that the dimensions, locale and facilities of the residences you are looking at match your income and spending budget. If you approach to invest in a house extra than a few months out, it is most effective to program for a 5-10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} boost in your home acquire price for the exact household.”
And Chavis claimed house sellers aren’t the only winners in today’s competitive marketplace.
“The labor marketplace is very related to the housing market place correct now — it’s a historically excellent time to be a vendor! As workers, we are, of class, ‘sellers’ of our skills, time and the like. So, I would recommend any individual who is searching for get the job done or considering leaving their latest position to be selective and come to feel empowered to negotiate for particularly what you want, regardless of whether it be better flexibility, far more payment, more paid time off, etcetera.”
6. Rianka R. Dorsainvil
Rianka R. Dorsainvil
2050WealthPartners.com
Rianka R. Dorsainvil (co-founder of 2050 Prosperity Associates) reminds investors that crypto is just one of quite a few techniques to reach your economic aims:
“Although the cryptocurrency area can provide a community come to feel, know that staying an investor is an particular person sport. 1st, identify what your monetary plans are, and then use expenditure automobiles that will enable you attain people goals.
“Beware of the temptations to ‘get abundant fast.’ Though cryptocurrency is legitimizing, I advise consumers to tactic investing with a prolonged watch. And I’d suggest having a nicely-proven discounts/slush fund right before dipping your toe into the marketplaces.”
7. Lauryn Williams
Lauryn Williams (founder of Well worth Winning) is aware of a factor or two about likely speedy. She is an Olympic medalist in each the women’s 4x100m race and two-woman bobsled. Williams mentioned investing isn’t one of those people issues that people today require to race into:
“I believe there is a great deal of distracting information on in the media right now about investing, and it can be very harmful to people mainly because a large amount of people are operating on some foundational aspects of their finances, these kinds of as having to pay down debt and creating an crisis fund, and all they are hearing all the time is, ‘if you are not investing, you are not serving to on your own, you are not earning your funds operate for you.’ I feel it’s actually vital that men and women have a baseline emergency fund in location ahead of they start out investing, and then, use the instruments that are easy and commonly obtainable, like your 401(k).
“I always inform my customers that investing is the moving walkway that can help you get wherever you want to go. You really don’t want to be fancy. You really do not need to be selecting shares. You really do not want to be undertaking all these different matters that the distractors are indicating you will need to do.”
Read through: ‘Black history is American history’: How to educate yourself and do the job toward racial fairness this month (and further than)
Additional about the influencers
Kenneth Chavis IV is a accredited money planner and a senior prosperity manager at LourdMurray. Chavis has been quoted in countrywide finance media publications and interviewed on the Black Information Channel on retirement arranging, investing, tax organizing and the economy.
Rianka R. Dorsainvil is a certified economic planner, as properly as the co-founder and co-CEO of 2050 Prosperity Companions, a digital, cost-only comprehensive economic arranging agency committed to serving business people, first-generation wealth-builders, and flourishing professionals in their late 20s, 30s, and 40s. She also hosts “2050 TrailBlazers,” a podcast and instructional system aimed at addressing the deficiency of range in the economical scheduling career.
Dasha Kennedy is the creator of the award-profitable fiscal advocacy group, The Broke Black Female. As a digital local community chief, she gives culturally appropriate fiscal literacy assets to around 70,000 Black girls to combat the racial and gender prosperity gap. Kennedy empowers her group to take a private accountability approach towards monetary security even though she advocates for financial justice on their behalf.
Michelle Singletary writes The Colour of Money for The Washington Publish, a twice-a-week particular finance column that appears in dozens of newspapers across the state. She is also the creator of 4 publications on private finance.
Bola Sokunbi is a qualified economical instruction teacher, finance pro, bestselling creator, speaker, and founder of Clever Girl Finance, a economical instruction system and local community for gals empowering them to realize monetary wellness and reside existence on their possess phrases.
Lauryn Williams is a accredited monetary planner and founder of Well worth Profitable, a virtual, price-only financial setting up organization. Williams and her team enable youthful pros get the solutions to the financial inquiries that make any difference most to them. She also hosts Well worth Listening, a podcast encouraging listeners to get started acquiring monetary conversations and choose manage of their cash tales.
Mandi Woodruff-Santos is an inclusive prosperity-developing advocate, vocation mentor and co-host of the well-known podcast Brown Ambition. She’s a frequent contributor to Yahoo Finance Are living. Observe her on Instagram and TikTok @mandimoney.
Much more From NerdWallet
Alana Benson writes for NerdWallet. E-mail: abenson@nerdwallet.com.
Elina Geller writes for NerdWallet. E mail: egeller@nerdwallet.com. Twitter: @themissmiles.
Meghan Coyle writes for NerdWallet. E-mail: mcoyle@nerdwallet.com. Twitter: @inkwaves.
Rosalie Murphy writes for NerdWallet. E-mail: rmurphy@nerdwallet.com.
BANGKOK (AP) — Japanese beverage large Kirin Holdings claimed Monday it has made a decision to withdraw from its joint venture in Myanmar.
Kirin, owner of the San Miguel, Extra fat Tire and Lion brand names, said its board designed the selection to “urgently terminate” the partnership with Myanma Economic Holdings Plc, a military-affiliated enterprise, following locating it would be tough to immediately stop the undertaking in the way Kirin needed to.
The business announced more than a year ago that it was not happy with a Feb. 1, 2021, military services takeover that violated its company benchmarks and human rights plan.
The military services ousted the elected govt of Aung San Suu Kyi triggering mass nonviolent protests nationwide. When the military and law enforcement responded with deadly pressure, armed resistance arose in the towns and the countryside in a intense wrestle for ability.
Political Cartoons
But Kirin had been making an attempt to retain its beer enterprise in the region and get MEHL to promote its stake, expressing it required to guidance its personnel and aid the state. Now, Kirin intends to sell its 51{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} stake, but not to MEHL, Kirin said.
The business stated it hopes to finish its withdrawal by June. No names of opportunity potential buyers of its stake were disclosed.
Human rights activists urged Kirin to “divest responsibly” and stay away from payments to the armed service administration and MEHL. Some opponents of the armed forces experienced urged the Myanmar general public to boycott solutions made by the undertaking, Myanmar Brewery.
Previously, Kirin sought business arbitration in a dispute with MEHL over its system to unwind the joint undertaking. MEHL experienced petitioned for liquidation of the undertaking, which Kirin said violated the joint undertaking agreement and was an “unjustified movement.” A court a short while ago ruled against MEHL’s petition, citing a technicality.
A response from the Myanmar firm was not immediately obtainable.
Myanmar Brewery, founded in 1995, provides beers underneath the Myanmar, Kirin Ichiban, Andaman Gold and Black Shield manufacturer names. It was unclear if the brewery would proceed to make Kirin Ichiban following the enterprise ends.
Kirin claimed it was recording an impairment reduction for 2021 on its business enterprise in Myanmar of 68 billion yen ($580 million).
It is one particular of the handful of Japanese businesses that have signaled they will go away the nation subsequent final year’s coup. Japanese firms are active in manufacturing and genuine estate and aided establish an industrial zone to the south of its premier city, Yangon.
Copyright 2022 The Linked Press. All rights reserved. This materials might not be posted, broadcast, rewritten or redistributed.
Open up finance proceeds to be a important topic in the entire world of fintech as firms tap APIs to obtain customers’ fiscal accounts and provide a gamut of integrated and embedded fiscal products and services. In the most up-to-date advancement, Stitch — a single of the prominent gamers setting up and functioning these APIs in Africa — confirmed to TechCrunch that it has lifted $21 million in Sequence A funding.
This news follows the $4 million Stitch lifted out of stealth in February 2021, a prequel to the $2 million extension round it secured 4 months in the past, bringing its seed spherical to $6 million. In complete, Sew has elevated $27 million to date.
The South African API fintech enables corporations to establish, improve, and scale fiscal solutions. For each a statement launched by the business, it ideas to develop a“financial graph” ecosystem across Africa with the new funding.
The firm describes the monetary graph as an infrastructure for money making blocks that allow firms to publish code as soon as, start in multiple markets and scale a lot quicker centered on interoperability throughout areas, companies, banking companies, and other styles of economic accounts.
“We type of look at the broader monetary ecosystem as a bunch of diverse nodes–bank accounts, retailers these kinds of as fintechs or end-consumers–which are all intrinsically related,” Stitch CEO Kiaan Pillay stated to TechCrunch in an interview. “Often, we believe about the reality that these connections between geographies and institutions really don’t exist however. And a lot of what we check out to do is to bridge those connections and to make these connections ubiquitous.”
Stitch sights this graph in three phases. The initially is what it introduced from stealth: the pure infrastructural engage in of connecting financial and bank accounts with an API. The second seeks to receive retailers and businesses to build use circumstances and apps on leading of that infrastructure. And the final is getting stop customers to website link their accounts by means of these companies.
“On the large degree, individuals moving from money to digital for the quite initial time will cause much more fragmentation. Our check out is that encompassing this all in 1 network or graph assists to open up the place up and break down the silos,” stated Pillay. “And the way we in the end feel about that is that people today can very easily move dollars between many applications concerning several geographies and establishments.”
Stitch’s delivers remedies for e-commerce organizations, marketplaces & platforms and its leading clientele, fintechs. As with other many years, African fintechs outperformed other startups in increasing venture funds, particularly in a record-breaking 2021 where by they raised 50-60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of complete VC funding for every reports. Their relevance can not be overstated and infrastructural gamers these kinds of Stitch, Mono, Okra, Plaid and OnePipe —all who lifted cash within just the earlier calendar year, some in seed and some others, Sequence A — are pivotal to that collective development of driving monetary inclusion and relieve of payments across the continent.
These business customers use Sew for use instances these kinds of as KYC & onboarding, personalized and company money administration, lending, wallet prime-ups and e-commerce checkouts. The platform’s info, and identity goods enable companies to entry client transaction histories and balance info, validate account facts, and complete fraud checks. The payments products allows bank-to-bank transfers for a person-click fork out-ins and payouts.
Some consumers consist of wallet-based organizations these kinds of as Chipper Money and Luno embedded finance providers like ImaliPay subscription platforms like FlexClub and payment aggregators like Yoco.
Sew
Impression Credits: Stitch
In April 2021, Sew introduced its payments solution in South Africa and seen a 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month-on-thirty day period growth in payments volume the pursuing 6 months. In October, Stitch expanded the payment product or service to Nigeria and, at the time, was on keep track of to facilitate $10 million in month-to-month payments by December.
On the contact, Pillay, who co-started Sew with Natalie Cuthbert and Priyen Pillay, did not give any update on this metric but reported Stitch experienced viewed a 104{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} thirty day period-on-thirty day period progress in payments worth considering the fact that launching the product or service previous April. And in Q4 2021, the platform witnessed a 44{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} thirty day period-on-thirty day period client advancement and a 72{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month-on-month increase in joined economic accounts.
“We’re very pleased of the partners and customers we have below as we go on to deepen the payments merchandise and glimpse at regular and recurring payments, which are interesting attribute sets for us,” explained Pillay.
“We lately experienced a couple clients go are living in Nigeria, which has been pretty exciting for us. We just offer you payments there but are keen to deepen the merchandise. We will search at introducing data and identification this yr, as perfectly as deepening the payments established in the same way to how we have it in South Africa.”
New York-dependent extensive-time period financial commitment company The Spruce Dwelling Partnership led this spherical of funding. The spherical also welcomed participation from new and current buyers like PayPal Ventures, TrueLayer, firstminute funds, The Raba Partnership, CRE Enterprise Funds, Village World, as well as fintech founders and corporations this kind of as TrueLayer, founders of Chipper Money, Quovo and Unit, and Guillaume Pousaz’s Zinal Expansion.
“We have been adhering to startups in Africa for many years. Our diligence was pretty clear that this is one of the most talented groups on the continent, and we are enthusiastic to be a component of what they are developing at Stitch,” said Ben Stein, co-founder of The Spruce Residence Partnership.
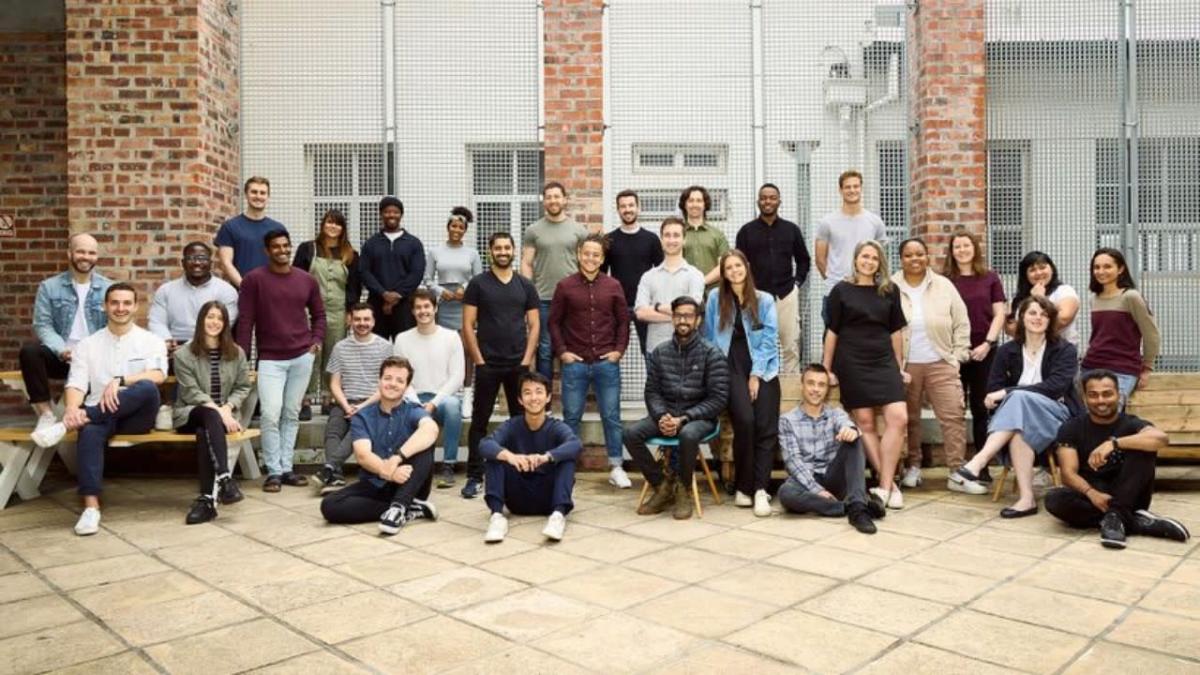
Pillay says increasing dollars from VC corporations and operators that have scaled fintech goods throughout several geographies offers the organization “something very special” as it enters its future progress period. The funding, Stitch claimed, will permit it to expand its workforce throughout places of work in Cape City, Johannesburg and Lagos, start new product or service choices and enter new marketplaces throughout the continent.
Last year, Aimy Steele discovered something she had never seen before in the world of personal finance advice: lessons that felt culturally relevant to her, and inclusive of her experiences.
Steele is no stranger to that world, and she’s extremely familiar with the financial gurus who have become the faces of paying down debt, budgeting and saving. She met Dave Ramsey after completing one of his programs and has avidly followed the teachings of David Bach and Suze Orman. But as a Black woman, Steele found that the advice from the traditional personal finance industry never felt truly relatable.
“We can’t compare our stories and our oppressive experiences with that of our white counterparts, and then still say, ‘But I’m supposed to be doing the exact same thing they’re doing,’” Steele says. “If I don’t see someone who looks like me, then I don’t explicitly link my fate to them.”
So Steele, 42, took matters into her own hands. She signed up for dfree, a faith-based personal finance program specifically designed for the Black community. Created in 2005 by DeForest B. Soaries, Jr. — a retired pastor of First Baptist Church of Lincoln Gardens in New Jersey — dfree walks participants through training courses and connects them with financial professionals. For three months, Steele logged into the program weekly from her dining room table, listening to facilitators discuss homeownership and debt elimination in the face of oppression. She felt much less alone.
And she isn’t alone. Many people of color have long felt left out of the traditional personal finance space. Experts say that much of the industry approaches advice as though all people are on equal footing. But systemic barriers have led the median wealth of white families to rise to about $184,000 while that number remains much lower for families of other or multiple races — at just around $23,000 for Black families and $38,000 for Hispanic families, the communities facing the biggest wealth gaps.
For years, dfree participants have been meeting up weekly in Black churches, sororities and community organizations across the country to learn about paying off debt, insurance and more, all while blending in conversations around racial inequality. Steele recently brought the program to her own church and became certified to facilitate the course. She says her dfree experience wasn’t only transformative because of the financial advice she took away, but also because the program acknowledged the discrimination Black Americans have faced for years.
“Hearing people talk about the fact that there is oppression validates what we have been feeling, thinking and knowing but could not articulate,” Steele says.
So do we throw all traditional personal finance advice out the window? Of course not. Countless people have changed their lives thanks to mainstream money tips. But making room for new faces, new products and new ideas in a world that has been so white-dominated for years is a necessary step — and it’s happening. There’s a movement growing outside mainstream finance narratives that highlights control and empowerment, and it’s being led by people of color, willing to reach an audience in whatever way they can. Getting there is the tricky part.
‘Trauma can last generations’
Money; Courtesy of Rahkim Sabree
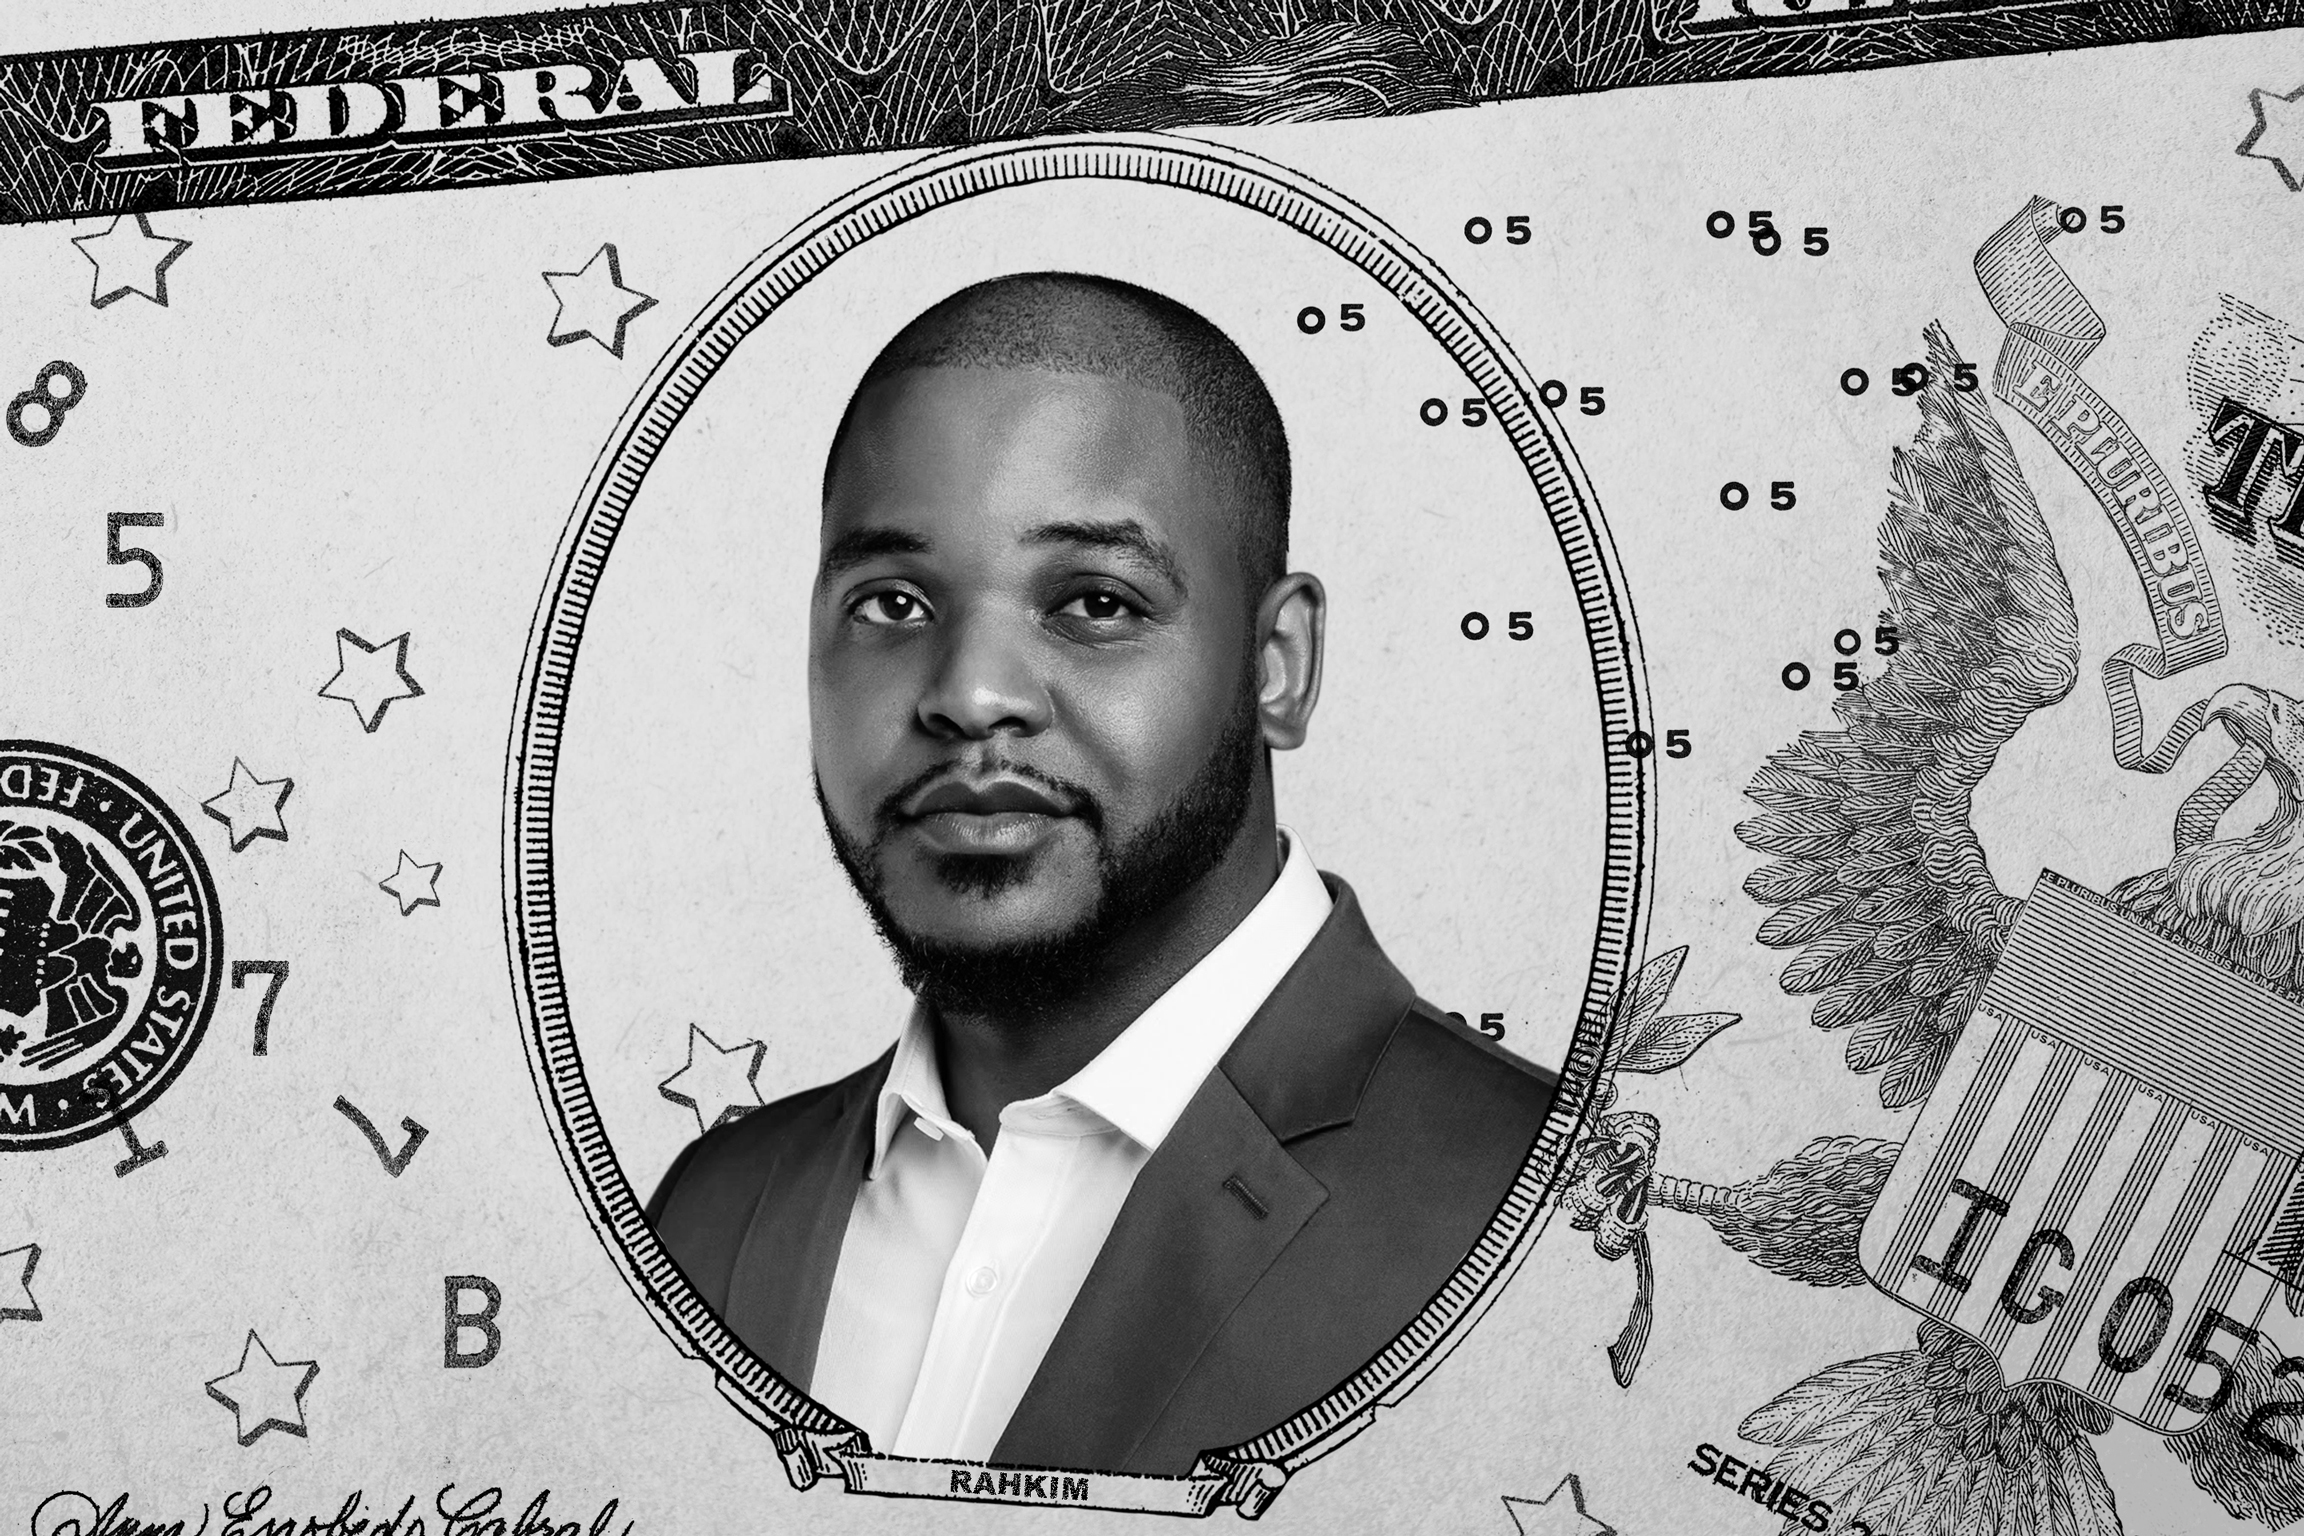
Rahkim Sabree distinctly remembers rushing home ahead of his siblings to tear an eviction notice off the front door before it was seen. There were times he couldn’t afford laundry, and food stamps didn’t always cover the groceries he loaded onto the conveyor belt.
“Situations like that are traumatic,” says the 31-year-old financial coach. “I never wanted to be poor again.”
As he grew up, he sought out as many sources as he could on building wealth, including Robert Kiyosaki’s well-known book “Rich Dad Poor Dad.” But he found that many of the financial texts he read didn’t acknowledge the financial trauma Black people have experienced in this country. That trauma, like the loss of $3 million after a bank created for emancipated slaves collapsed in the 1870s, reverberates throughout the community today, he says.
“When you work so hard to build up capital just to have it taken from you, that creates a trauma and that trauma can last generations,” Sabree says. “Grandma says don’t put your money into banks because they’re crooks, dad says don’t put your money in the banks because they’re crooks — and so you never put your money in the bank.”
Financial education for the Black community has to be unique to the Black community, says Sabree, who helps people work through their own financial trauma, which he says can range from an eviction or bankruptcy to having someone tell you credit cards will ruin your life. Part of the solution, he says, is to point Black people to Black-owned businesses and banks they can trust, like Greenwood, a mobile banking platform designed for Black and Latino customers that was co-founded by rapper Killer Mike. Greenwood provides monthly grants to Black and Latino-owned businesses and produces personal finance educational content targeted at these communities.
Distrust goes beyond banks and touches investing, insurance, credit cards and more, Sabree adds.
Racial inequality has seeped into nearly every aspect of our financial lives. At work, claims of racial discrimination are often the most filed claims but have the lowest percentage of success, and the wage gap shows no signs of shrinking. Meanwhile, Black borrowers are far more likely to be saddled with student loans than their white counterparts. One report found that 20 years after graduation, a typical white borrower has paid off 94{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of their balance on average, while the typical Black borrower had paid off just 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. When it comes to housing, our culture of homeownership was constructed on policies that led to discriminatory practices that still exist today, says Jacob Faber, an associate professor at New York University’s Robert F. Wagner School of Public Service.
“We’re told almost from birth that the best way to build wealth is home ownership,” Faber says. “However, the opportunities to not only buy homes but also accumulate wealth through home ownership is deeply unequal.”
Real estate agents, for example, may steer home seekers to particular areas based on their race, and there’s a major racial gap in home appraisals. Last year, a white man and a Black woman shared that after replacing their photos with pictures of only white family members — and removing books by Black authors — their home appraisal jumped more than 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
“The reality of the lingering effects of discrimination and racism and their economic impacts are irrefutable,” says Soaries, the creator of dfree as well as New Jersey’s first male African-American Secretary of State. “The question now isn’t how this was formed, but what kind of strategies can be effective in helping people close the gap.”
Ads by Money. We may be compensated if you click this ad.Ad
Get the financial advice you need, without leaving your home.
An Online Financial Advisor can help you develop a sound and effective economic plan that works for you. Click below to learn more.
Get Started
New faces, new voices
Money; Courtesy of Giovanna Gonzalez
The world of personal finance advice has always felt “not for me,” says Noemi Ibarra, a 24-year-old Latina woman based in Chicago.
Ibarra is a first-generation American, and her family has struggled with poverty ever since her parents immigrated to the U.S. from Mexico nearly 30 years ago. So when Ibarra graduated college and landed a full-time job, she was scared to invest her money.
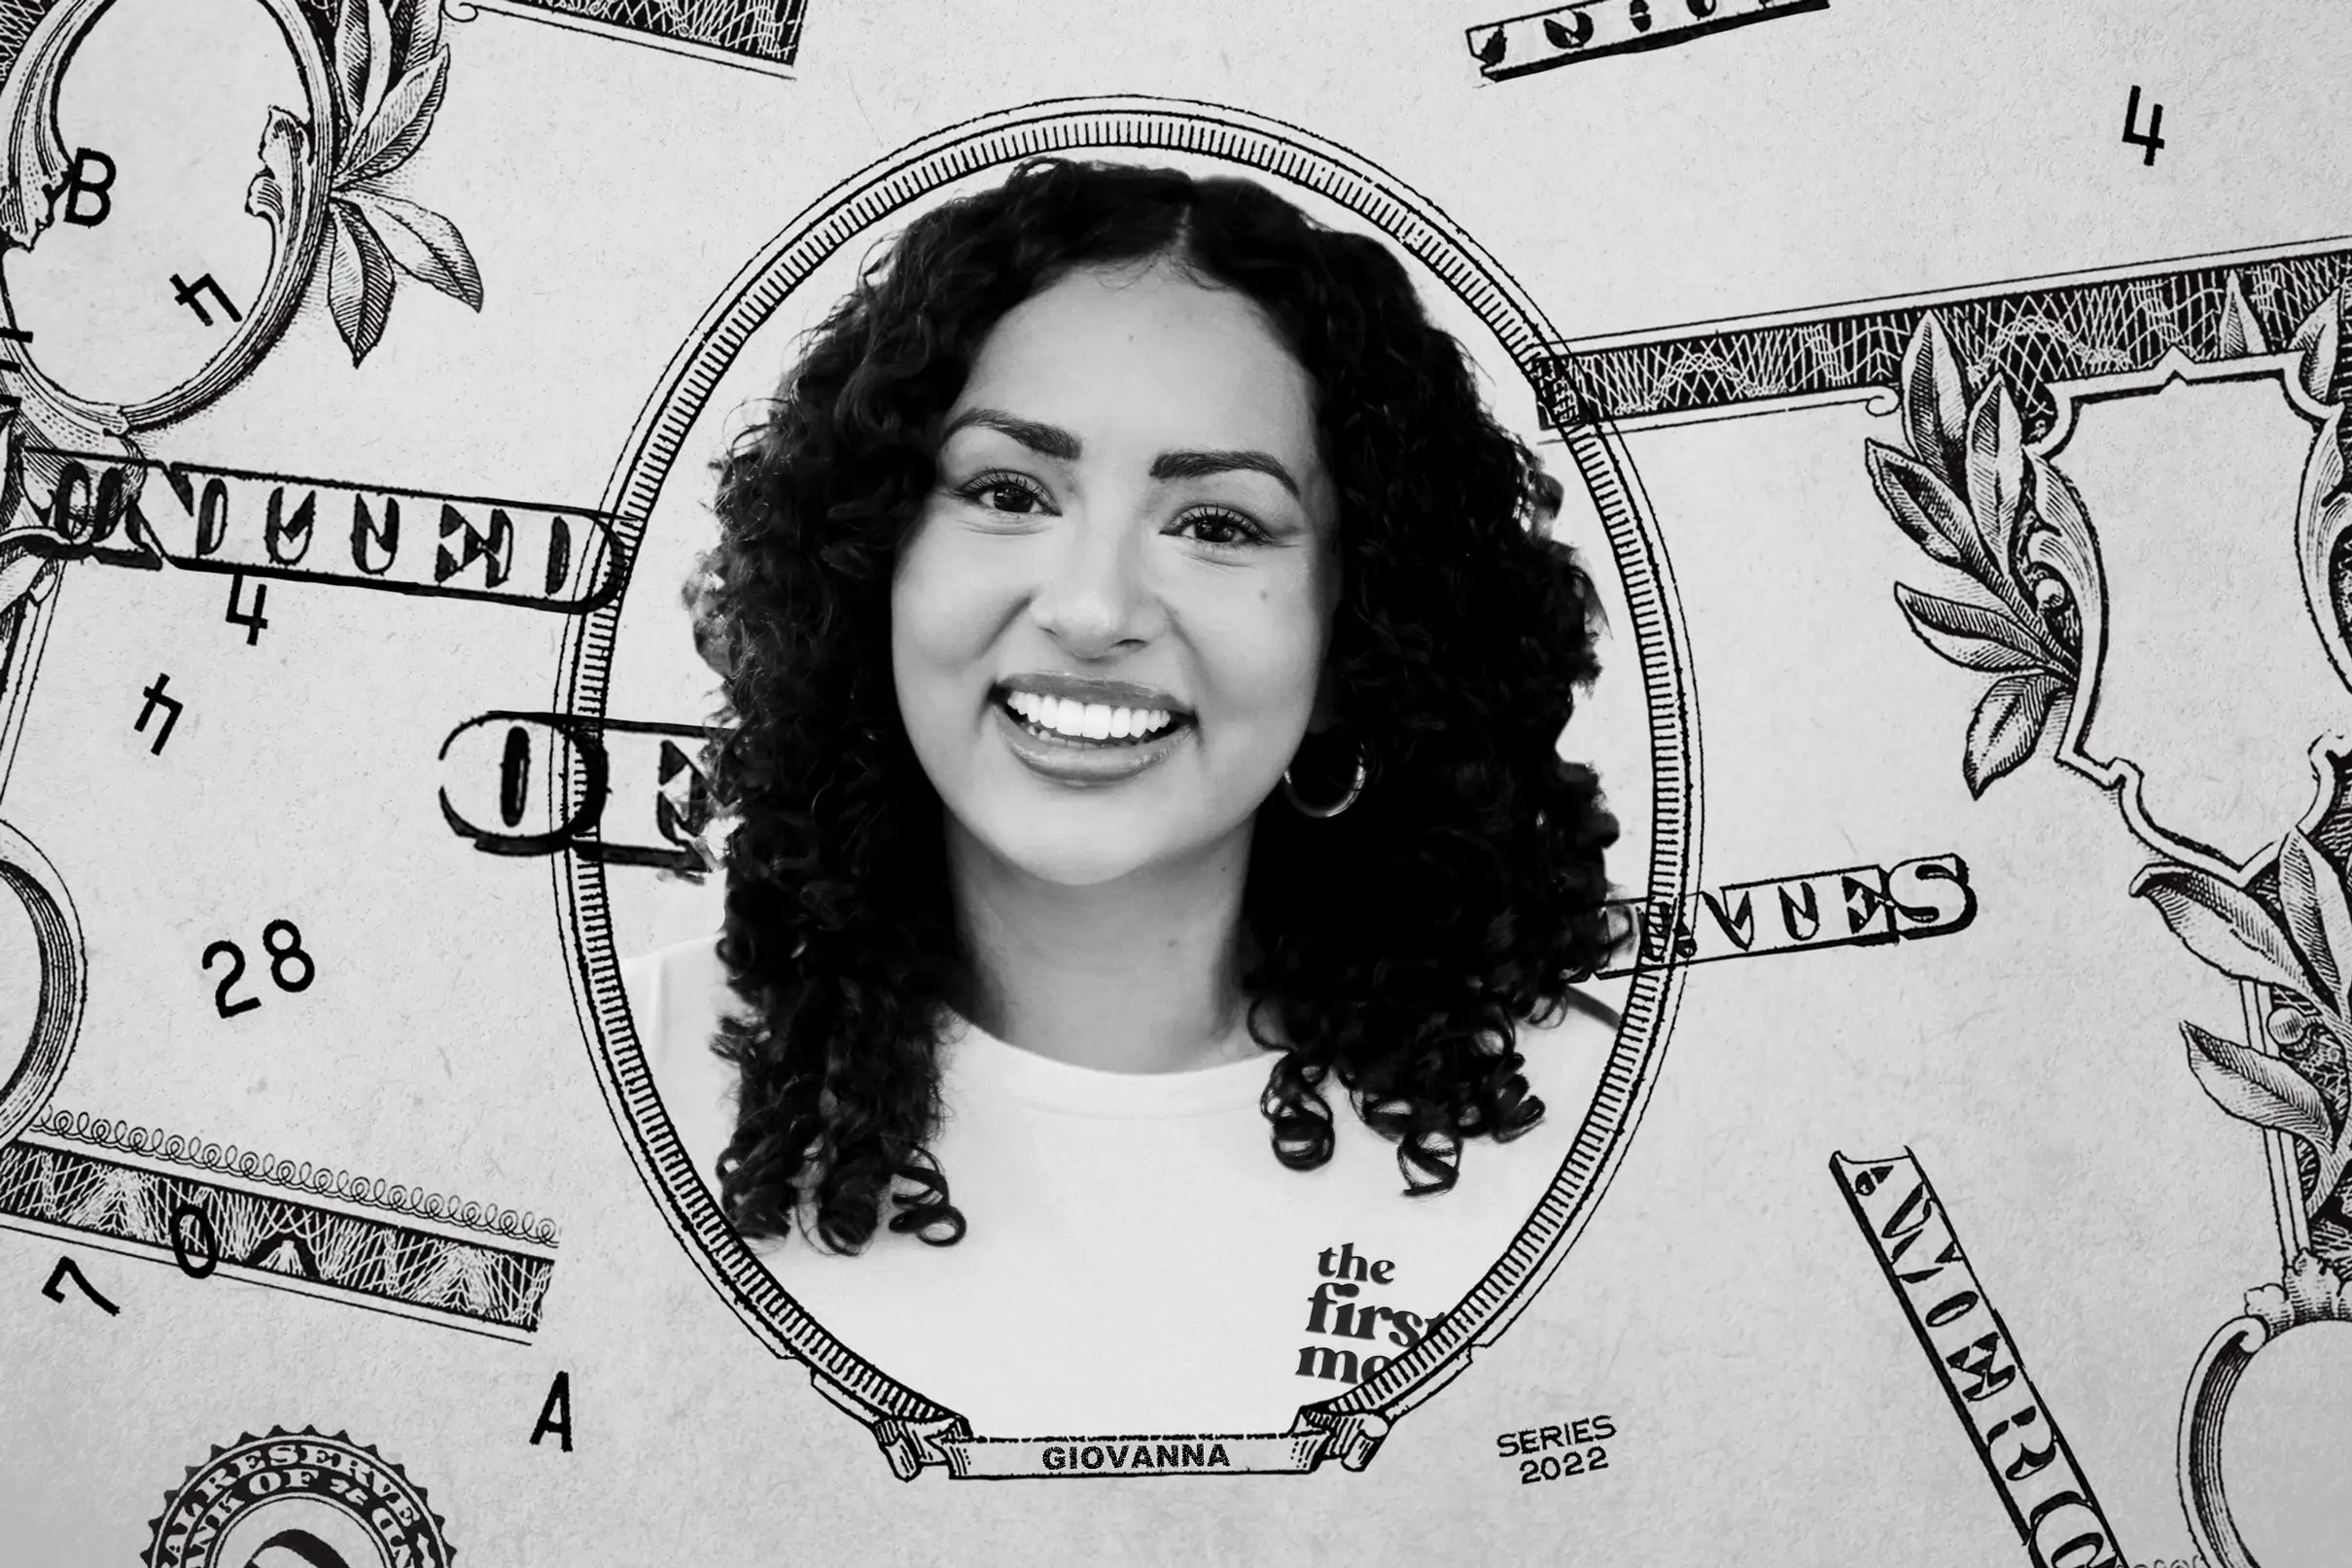
“I didn’t know who to turn to,” Ibarra says. But then she found someone she could relate to: Giovanna Gonzalez, another first-generation Latina woman who has garnered more than 180,000 followers on TikTok with the account name “thefirstgenmentor.” Finding online mentors of color like Gonzalez has made Ibarra say she feels more confident that she, too, can build wealth.
Financial advice on social media has exploded over the last several years, for better or worse. The internet is especially popular for young people to get money advice, with 41{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Z respondents to a 2021 Fidelity survey saying that they turn to social media influencers to educate themselves on investing.
Money experts of color are breaking into the online financial scene. The Budgetnista Tiffany Aliche runs a Facebook group of more than 480,000 members who are mostly Black women, which provides a natural starting place for members to relate to each other. Kiersten and Julien Saunders tackle “the deeply personal side of money through the lens of the Black American experience” via their Rich and Regular blog, podcast and YouTube series.
Delyanne Barros has more than 320,000 followers between Instagram and TikTok. The attorney launched her money coaching business just before the pandemic to share what she had learned about investing with everyone, especially other Latinos, she says.
These newcomers are much needed in the finance world. Gonzalez says she read over 50 personal finance books, but didn’t find that they address issues that hit close to her home, like planning for parents’ retirement and setting financial boundaries with families — concerns she says are specifically pervasive in Latinx communities, but families rarely talk about.
“Money is very taboo in our community,” Gonzalez says.
So she decided to do her part to help others, sharing videos with captions like “Struggling to set financial boundaries with your Latinx family? Try saying this” with advice from a licensed therapist. That particular video is a favorite of Anna Gamez’s, who says she struggles with this exact issue.
“Now I feel really comfortable going into conversations with family and friends,” Gamez, a 31-year-old job recruiter, says.
But not everyone does, or should, get their personal finance advice from social media. The financial advisor landscape needs to change as well, says Vaneesha Boney Dutra, an associate professor of finance at the University of Denver. Eighty-two percent of personal financial advisors are white, according to 2021 data from the Bureau of Labor Statistics. Because advisors looking for clients tend to start looking within their own circles, many of their clients also tend to be white, Dutra says.
“The industry is ignoring a very large piece of the population,” she adds.
The Onyx Advisor Network is trying to change that. Created by two financial advisors, Onyx is a network that focuses on helping “historically underrepresented advisors” start, scale and sustain their businesses by giving them tools, coaching and a network of advisors.
“We want to make sure that the industry looks a lot more like our country,” says Dasarte Yarnway, co-founder of Onyx, which announced its launch plans in December.
Yarnway didn’t even know financial advising was a career he could pursue until he landed his first job at a financial firm. He’s hoping that with platforms like Onyx, more financial advisors of color will see success, and in turn, help those who come after them to do the same.
Ads by Money. We may be compensated if you click this ad.Ad
Online Financial Advisors can guide you toward smart investments and sound economic planning.
We can all benefit from the help of experts, especially when it comes to finances. Reach out to an Online Financial Advisor by clicking below.
Get Started
Changing the financial world for future generations
Money; Courtesy of Jean Smart
Yemi Rose says he has always felt that traditional personal finance content does not speak to him.
“So many things default to white,” Rose says.
With his company OfColor — a financial wellness software platform that partners with employers and focuses specifically on helping employees of color — he hopes to help fill the gap. The platform connects employees with budgeting and savings tools, financial coaches of color and educational content geared towards non-white communities.
“People of color are not a monolith and there’s so much variation and nuance there,” Rose says. “But at the very least we try to attack what has been the traditional invisibility of people of color in personal finance.”
Beyond representation, there’s been a boom in financial tools and products specifically designed to help people of color better their finances. It’s an important change: the one-two punch of diverse racial representation in the personal finance space, as well as tools and products built specifically with these communities in mind.
Jean Smart can’t pinpoint exactly when she knew she had to leave her stable job at financial services giant UBS to start Penelope, which brings 401(k)s to small businesses, a majority of which are minority-owned.
“It was 1,000 cuts,” Smart says. They included seeing the disparities highlighted by the COVID-19 pandemic and the murder of George Floyd. Then, anti-Asian racist events came to light, and Smart says for the first time ever, she asked her mother not to leave her house for fear of her safety.
During that chaos, Smart, a Korean-American woman, found that clients she had helped during her 20-year career in the financial industry didn’t seem to need her help as much as other communities of color who were hurting. She quit her job and turned to those people instead, wanting to help them in the best way she knew how with a new team full of people of color and first- and second-generation immigrants.
So many retirement savings tools are difficult to understand — especially for a small business owner who is juggling tons of tasks at once. Penelope aims to bring them a more streamlined approach to saving for retirement with a 401(k) subscription model that cuts through the jargon, Smart says.
Smart is hopeful about the future. She named her company after someone who embodies why it’s so important to her to help make the financial industry more inclusive: her 10-year-old daughter Penelope.
“I think it’s going to get better,” Smart says. “I have to.”
Newsletter
To celebrate our 50th anniversary, we’ve combed through decades of our print magazines to find hidden gems, fascinating stories and vintage personal finance tips that have withstood the test of time. Dive into the archives with us.
Newsletter
Subscribe successful!
You will now receive Money’s newsletter at
Reply anytime to let us know how we can improve. Enjoy!
Make sure we land in your inbox, not your spam folder. We just sent you a welcome email. Sometimes email clients send our first email to a spam or promotions folder. If you don’t see us in your inbox, check these folders, then drag and drop the welcome email into your inbox.