LONDON–(Small business WIRE)–The pandemic in basic, and the outbreak of Omicron a short while ago, have developed a a lot broader awareness of travel insurance policies. “What occurs if I get Covid during vacation?” is for sure the most commonly questioned query by vacationers throughout the world. The reply is in reality, incredibly basic: “Insurance”.
Several vacation insurance policies companies are now offering travel insurance packages that consist of the clinical coverages of Covid-19. But would it gain travelers in gentle of the new Omicron variant or any variant that might probably surface? And how to come across the most effective on the internet travel insurance among so several choices out there? Adhere to these top strategies advised by Travelner specialists – a leading-course vacation agency – to get travel insurance policies on the web that can totally guard you and your cherished kinds when touring abroad.
Come across a credible provider to get vacation insurance policies online
It is indisputably vital to look at your insurance policies provider’s believability ahead of processing any further transaction considering the fact that it will immediately have an affect on your positive aspects. “The finest way to thoroughly examine your insurance coverage company is by hunting at their point out licensing, promises approach, and problems. And really don’t be afraid to inquire the supplier about how they deal with promises and how they get there at a declare award “, mentioned Tyler Wong of Travelner. These concerns will aid you decide on which coverage business can assistance you to get journey insurance coverage on-line and help you in the event of an crisis.
Really don’t ignore to check your provider’s terms and disorders to make sure that the procedure is transparent and dependable. An insurance coverage company’s money strength is a legitimate evidence of its capability to protected your rewards in case of any incidents. Travelner is proud to be a strategic spouse with Trawick Insurance coverage – proposed by Forbes as 1 of the ideal online travel insurance coverage providers so that we can make certain travelers can thoroughly encounter their holiday seasons when touring with us.
Examine options, rates, and added benefits of inexpensive on line journey insurance coverage offers
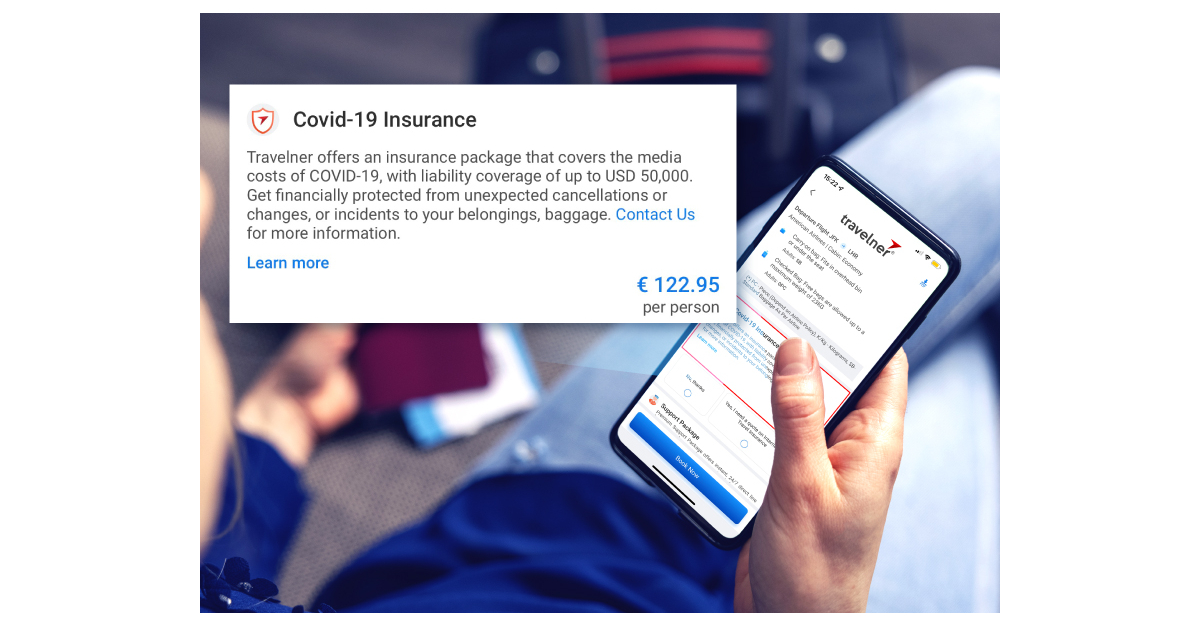
Though most journey insurance plan packages do contain Covid-19 medical expenses, some of them may well not. For that reason, Travelner industry experts advise travelers must read the policies cautiously and seem out for people that exclude pandemics. Travelner is at the moment offering a travel coverage package that covers health care fees for COVID-19, SARS-CoV-2, and any mutation or variation of SARS-CoV-2.
Most journey coverage ideas with health-related added benefits now deal with Covid like any other health issues. So when evaluating selling prices to find the very best on line journey insurance policies, make guaranteed that you are thinking about packages with the very same ideas and positive aspects. Keep in intellect that low-priced on-line journey insurance coverage does not necessarily mean it is the very best alternative for your trip abroad. What’s more, note that to make a claim, you have to have experienced journey insurance plan before starting to be unwell due to the fact coverage is made for unexpected concerns.
Examine on the claims method of the travel insurance coverage company
People frequently forget the great importance of promises method transparency, when in actuality, it is one particular of the determining things to distinguish between an normal and the ideal on-line journey insurance coverage organization. An perfect claims course of action must be transparent and entirely guided so that you really should know who and how to make contact with to make an coverage assert.
With Travelner’s insurance policies, travelers can relaxation certain that the declare treatment is clearly instructed and all assert forms can be located easily on the Travelner internet site. No much more cumbersome method to get your relatives and you fully protected from the pandemic when traveling abroad with our insurance plan deal.
After almost two years, the pandemic has brought major life changes clouding the path to a stable retirement for many individuals. Americans are struggling with key decisions on investments and estate planning strategies, according to a recent Hearts & Wallets report, while the National Institute for Retirement Security says more than half of Millennials and Gen Xers are more worried about their retirement security than before COVID hit.
Add in significant changes in the employment market, with women being disproportionally affected than men and unprecedented numbers of workers taking part in the “great resignation” along with continued market volatility, and it’s no wonder retirement security feels unattainable for many.
But there is hope. Making some smart money moves right now can get you on solid footing for your retirement. Don’t know where to start? Professional advice — whether from a local financial professional or one offered through your workplace, a phone-based or virtual financial professional, or even digital advice tools — can help.
Where to start depends on your personal goals and how the pandemic may have impacted your progress. Here’s what to consider:
If you quit your job as part of the ‘Great Resignation’ …
… You’ll need to make sure the career change doesn’t derail your retirement plan. Think twice before cashing out of your previous workplace retirement plan, which can cost you big in taxes and penalties. Once you’ve landed in your next role, opt into the workplace retirement plan as soon as you’re eligible, contributing at least enough to get an employer match — more if you can. And carefully consider the options for your old 401(k) or similar savings plan.
If your new plan provides access to professional advice, take advantage of it. Or consider speaking to someone outside of the workplace who can provide you advice based on your entire situation.
If you put off milestones, such as buying a house or getting married during the pandemic …
… It’s time to get back on track, but be careful not to overspend to make up for lost time. A financial professional can help look at your current financial picture to create a financial strategy that will help you reach both your short- and long-term goals, or readjust them, as needed.
For newlywed (or soon-to-be-married) couples, a financial professional can serve as a third party to help you set financial goals and navigate the sometimes-tricky waters of combining — or not combining — your finances as you begin building a life together and planning for the future. Financial professionals can also help you make sure you’re adequately protecting yourself from a variety of risks.
If you want advice but aren’t ready for an in-person meeting …
…The virtual environment provides you with a wonderful opportunity to redefine how you would like to interact with your future financial professional. Many workers have come to appreciate the hybrid or completely remote work environment during the pandemic. Consider a professional advice model where you can engage by phone to talk about retirement planning or other financial challenges you’re facing.
If stimulus checks and a less active social life have boosted your savings account …
…You’ll want to make sure you’re reviewing and making progress on your financial goals. If you’ve paid down debt, built adequate emergency savings and are maxing out your retirement savings, you may want to look at your financial wish list — maybe starting a business, buying a second home or retiring early. Either way, you may also want to put your extra cash in savings into investments that match your goals.
Unsure what to do first? If all you need is investing guidance, digital tools can be a good place to start. We have a calculator and be sure to check out the suite of tools on this resource center page. A financial professional can help you prioritize and achieve your goals and, if appropriate, help you allocate your investments.
If COVID forced you into retirement …
… Professional advice can help you stretch your nest egg as far as possible. A financial professional can work with you to determine your best withdrawal strategy, after factoring in the size of your retirement savings, the types of accounts you have (taxable or non-taxable), Social Security and other income sources, and your expenses. They can also talk to you about whether it makes sense to consider working part time or using a guaranteed income product to ensure you never run out of money in retirement.
Remember, regardless of how you arrived at your current situation, taking the right steps now can help you feel confident that a financially secure retirement is in your future. Start today with getting the advice you need.
This article was written by and presents the views of our contributing adviser, not the Kiplinger editorial staff. You can check adviser records with the SEC or with FINRA.
President, Retail Advice and Solutions, Prudential
Brad Hearn is the president of Retail Advice and Solutions, which brings together the extraordinary face-to-face advice expertise of Prudential Advisors with Prudential’s Hybrid Advisory team and digital advice capabilities – creating a single organization with end-to-end accountability for delivering holistic financial advice and solutions across the entire advice continuum.
The corporation and law organization names proven over are produced mechanically based mostly on the textual content of the write-up. We are strengthening this attribute as we continue to exam and acquire in beta. We welcome responses, which you can give working with the opinions tab on the correct of the site.
February 11, 2022 – For the vast majority of modern-day business, a perfectly-created and trustworthy supply chain is the foundation for operational good results. This implies that all parts thereof — from sourcing to manufacturing to distribution — get the job done together reciprocally so that all parts of an close-solution fulfill needed specifications and well timed arrive at their places. In flip, this enables other members in the chain to fulfill their very own specific calls for and fulfill their respective obligations.
But what comes about when a portion of the offer chain encounters an sudden hold off, for case in point, a uncooked material shortage, unscheduled manufacturing unit shutdown, transportation issues, or production troubles? Disruptions at just one component of the supply chain can, and frequently do, build ripple outcomes that improve in magnitude and severity even more up the chain, culminating in hold off or absence of the end-solution in just one or far more necessary marketplaces. This can guide to a vary of unanticipated economical (and reputational) implications for a number of, if not all, associates of that source chain.
Compounding offer chain disruptions across the world
Register now for Free unrestricted accessibility to Reuters.com
Sign-up
According to a current report, U.S. enterprise leaders rated enterprise interruption including source chain disruption as the No. 1 threat for stateside corporations in 2022. This comes as no shock, as recent world-wide activities have prompted, and continue on to trigger, significant — and compounding — disruptions across industries.
COVID-19 pandemic. The pandemic, specially in the to start with 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of 2020, spurred federal government orders across the world that compelled facility closures throughout industries, from time to time for months. Even wherever complete closures ended or ended up not necessary, companies ongoing to impose capacity limits and quarantine needs that curtailed operations and facility occupancy. This unparalleled event led to ubiquitous provide chain difficulties that afflicted practically all industries.
Wintertime Storm Uri. In February 2021, a weeklong winter storm (unofficially referred to by media outlets as Winter season Storm Uri) battered the Point out of Texas and prompted blackouts, highway closures, reduction of water services, and facility closures throughout the state. In addition to currently being a major transportation hub, Texas is the house of numerous significant industries, including oil and gasoline, semiconductor manufacturing, and aerospace and protection, several of which experienced unexpected disruptions as a final result of the storm. The world wide scarcity in semiconductors is envisioned to expense the automotive sector by itself $210 billion in dropped revenues.
Suez Canal blockage. In March 2021, the huge container vessel At any time Presented was grounded for more than six times in the Suez Canal, a important waterway for world transport and transportation. It is estimated that far more than 350 vessels ended up backed up for the duration of that time which includes container ships, bulk carriers, and oil tankers, adding substantial supplemental vacation time to tightly scheduled routes. This 6-working day blockage created provide chain delays that rippled throughout industries globally.
These activities only exacerbated the ubiquitous source chain difficulties created as a end result of the ongoing COVID-19 pandemic.
Provide chain disruptions, and disruptions of this magnitude and scale in particular, can have a devastating influence on a business’ envisioned earnings and other money metrics frequently with minimal-to-no warning. In simple fact, in accordance to the “Allianz 2022 Threat Barometer Report,” 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of firms mentioned they experienced endured a massive influence from the latest offer chain troubles. So, what steps can businesses get to lower these economic impacts? The response may possibly be identified in their insurance policies applications.
Ample insurance coverage can fill the hole
In the wake of a fragmented provide chain, companies should really search to their business interruption insurance plans to determine if they could have protection for resultant monetary losses.
Company interruption insurance coverage usually supplies coverage for money losses seasoned by the insured to the extent physical decline of or problems to the insured’s home pressured it to terminate, suspend, or minimize regular operations. Firms that acquire enterprise interruption insurance policies along with their house insurance policies guard them selves not only from the expenditures tied to fixing the harm or decline at problem, but also the economic losses that arise from related operational impacts.
Company interruption insurance policy assumes that an insured threat straight impacted the insureditself. But what occurs if a crucial member of your supply chain experiences its personal disruption? Due to the fact conventional business enterprise interruption insurance is normally restricted to losses involved with the insured’s possess injury or loss, this line of protection may not be responsive. So, what now?
The good thing is, most business interruption insurance is acquired in conjunction with a comparable but meaningfully unique kind of coverage: contingent business enterprise interruption. Contingent enterprise interruption coverage is created to safeguard a organization from the economical effects of the termination, suspension, and/or reduction of its standard business functions as a outcome of one or a lot more members of the supply chain suffering from bodily reduction of or problems to its house.
Working with Winter Storm Uri as an example, consider a state of affairs wherever a member of a offer chain knowledgeable a pipe burst that destroyed its machinery therefore triggering a hold off in generation of a critical component of the source chain’s conclude-product or service. Other customers of the source chain may possibly be ready to protected payment for their losses beneath their contingent organization interruption coverages, even while the assets destruction did not occur at their respective properties. Contingent business enterprise interruption coverage is a likely priceless ingredient of a business’ insurance policy program in the wake of this sort of supply chain disruptions.
Broader provide chain coverage
As an effectively regular supplying throughout the coverage business, most enterprises obtain contingent business enterprise interruption insurance policies. But in the deal with of an unanticipated supply chain disruption, is this more than enough?
As functions like the COVID-19 pandemic, the Suez Canal blockage, and Winter season Storm Uri have demonstrated, provide chain disruptions can have an endless array of will cause. Whilst contingent company interruption coverage can supply a significant line of defense, it is commonly limited to coverage for disruptions triggered by decline of or problems to residence, for illustration, flooding, hearth, or wind destruction. But what transpires if a source chain disruption is caused by a different variety of possibility? In this sort of circumstances, regular contingent business interruption insurance coverage may well not utilize.
Thankfully, a lot of insurance coverage businesses present broader coverage precisely customized to offer chain challenges. Offer chain insurance policy typically operates the same way as common contingent enterprise interruption coverage, but it encompasses added hazards. For example, offer chain insurance plan may well also go over disruptions as a consequence of labor strikes and shortages, generation difficulties, war or political unrest, and disruptive civil motion.
Depending on a business’ hazard profile, obtaining this broadened protection may perhaps be worthwhile. It is notably significant to take a near glance at all members of the provide chain and discover risks inherent to their corporations.
Is a supplier situated in a country that is not politically secure? Are crucial raw elements issue to adverse impacts from weather difficulties? Is a organization notoriously contentious with labor unions? These kinds of queries are value taking into consideration when identifying if source chain insurance policy is warranted.
Summary
As modern world functions have shown, provide chain disruptions can arise at any time, and can have devastating economic impacts on all associates of the offer chain. Accordingly, it is important to operate with trusted brokers, possibility administration professionals, and protection counsel to critique the impacted business’ coverage method and ensure selection makers realize the scope of coverages accessible. Even though contingent business interruption insurance policy can establish priceless in the wake of a provide chain disaster, most effective techniques dictate that firms meticulously assess their threat profile and look at whether broader source chain protection could be proper.
Ashley B. Jordan is a normal contributing columnist on insurance coverage legislation for Reuters Authorized Information and Westlaw These days.
Register now for Free unlimited entry to Reuters.com
Register
Opinions expressed are those people of the creator. They do not replicate the views of Reuters Information, which, below the Trust Ideas, is committed to integrity, independence, and liberty from bias. Westlaw Today is owned by Thomson Reuters and operates independently of Reuters Information.
“Price discounting is 1 of my pet peeves,” states Sharmila Chatterjee. No, the educational head for the Organization Administration (EM) Track of MIT Sloan School of Management’s MBA plan does not have it out for customers searching for a deal. Somewhat, this is a stitch in a working thread of discussion about larger-photo considering honed from yrs of analysis.
Chatterjee is a business enterprise-to-company (B2B) internet marketing specialist and an award-winning circumstance author who examines problems in the domains of channels of distribution, profits power administration, and partnership marketing. “No one particular really should be engaged in value gouging, of course,” she says, “but get an equitable return on the benefit shipped by means of your choices, this sort of that you can sustain investments for the prolonged-expression results of your manufacturer.”
Citing Millward Brown’s discovering that models account for more than 30 per cent of the inventory marketplace price of providers in the S&P 500 index, The Economist acknowledged that for many corporations, their brand name is their most useful asset. Look at United Airlines’ 2017 branding disaster that resulted in their stock plummeting $1.4 billion in a subject of times soon after movie footage emerged exhibiting the forced removal of a passenger from an overbooked flight.
Brand, in accordance to Chatterjee, is a function of consumer encounter. In a 2019 view piece for United states of america Currently, Chatterjee outlined the relevance of consumer knowledge by inspecting the case of bricks-and-mortar (B&M) stores. When e-commerce emerged in the early 1990s, classic merchants experimented with to contend by slashing price ranges. As a consequence, they have been pressured to cut fees somewhere else: They whittled down sales teams, neglected financial investment in schooling, and dismissed merchandising and solution enhancement — all to the detriment of the in-particular person consumer practical experience.
Their misapprehension of the situation resulted in a self-fulfilling prophecy. Prospects flocked on-line for savings, leaving, among the some others, significant models like RadioShack, Toys R Us, and Sears to file for personal bankruptcy. In an sudden twist, the rise of the electronic age exposed the importance of the human interface. Nowadays, savvy suppliers acknowledge the added benefits of combining e-commerce and B&M, integrating on the web and offline. “Technology is a great facilitator and enabler. Troubles occur when we transform to technological innovation as a panacea,” warns Chatterjee. “Human cash is important for profitable outcomes in most instances — minimizing this arrives at a fantastic cost.”
For additional evidence of the have to have for human-tech complementarity, we need search no even more than the substantial rates of technology implementation failures knowledgeable by corporations today. In 2001, Gartner noted a 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} failure price of purchaser romance administration (CRM) implementation. Quickly-forward to 2021, and those quantities have only increased. How to reconcile this with the truth that CRM paying out displays no signal of slowing down, and for several companies, CRM has become the largest profits region of shelling out in organization application?
In the meantime, a latest review executed by MIT Sloan Management Evaluation with Boston Consulting Group discovered that technologies implementation failure charges of 70 per cent or bigger are the norm, and only 10 percent of businesses report considerable returns on their AI investments. “There is definitely tremendous likely for technological innovation to provide value, but the opportunity is not currently being recognized, and therein lies the position of human funds,” states Chatterjee.
In an exertion to comprehend the high charge of technologies implementation failures, significantly in the B2B context, Chatterjee performed an empirical assessment of acquiring companies that procured and implemented company intelligence application. She uncovered that the most considerable predictors of equally prosperous technological know-how assimilation and all round client gratification had been related to a established of intangibles that the customer assigned to the application seller the “soft” provider side, reflecting a holistic knowing of the customer’s business enterprise context, value generation opportunity, and pathway to value.
She phone calls this the “value attitude.” After a business has a aggressive solution, they will need to be in a position to talk how to greatest extract the prospective worth from the engineering. This indicates, amid other issues, sharing with the customer the transform administration required in the legacy procedures as perfectly as greatest business enterprise procedures and classes figured out from failure. Sellers that communicated “value mindset,” according to Chatterjee, skilled drastically better rates of shopper gratification — to the extent of a a few-to-1 effect. “Again, this demonstrates in spades the outstanding price of the human interface — value not communicated is value not delivered. All over again, technology and individuals as complements,” she explains.
Chatterjee’s study started with a fascination with info silos fostered through her time as a graduate scholar at the Wharton University, in which she to start with became knowledgeable of a statistic that observed a mere 30 per cent of advertising potential customers were pursued by revenue teams. This revelation regarding the hole in the gross sales-promoting interface was a little something Chatterjee channeled into a long time of investigation in the domain of income guide administration and consumer retention. Centered on this disconnect among human actions and the rhythms of capitalism, she would go on to carry out some of the initial reports in the crucial location of the profits-marketing interface, particularly sales guide administration, like a examine she and her colleagues titled “The Revenue Guide Black Hole: On Sales Rep’s Adhere to-up of Advertising and marketing Sales opportunities.”
A self-proclaimed empiricist in her investigate, Chatterjee employs surveys coupled with econometric approaches for evaluation that exams types in the authentic entire world. This target on true-globe small business problems extends to her administrative part main the EM Keep track of at MIT. All MBA systems supply material, regardless of whether it be in finance, advertising and marketing, functions, or management. But at the Institute, Chatterjee emphasizes the relevance of attitude. From the outset, learners in the EM Track are inspired to imagine like CEOs when on a pathway to upcoming management. In practice, this indicates instruction learners to move away from siloed thinking even though adopting a holistic, cross-purposeful technique to difficulty-fixing in order to change companies.
The most effective way to instill this management way of thinking is for students to do the job on actual-everyday living organization assignments and worries with organizations though applying theoretical principles and frameworks learned in the classroom. In their initial calendar year, learners are thrown into the deep conclude. By way of the Organization Administration Lab (EM-Lab), EM Track learners are supplied the opportunity to do the job fingers-on with large enterprises to handle company challenges. “My students’ work on genuine small business challenges embodies the MIT motto “mens et manus,”mind and hand,” she claims.
Businesses like Procter & Gamble/Gillette, Amazon, BMW, and IBM have all participated in EM-Lab assignments. “Multinationals appear back again to us yr right after calendar year simply because we supply valuable results that they can put into practice in their corporations,” says Chatterjee. At the very same time, MIT learners gain from the genuine-globe practical experience, refining their exploration capabilities though creating the attitude of foreseeable future business leaders. “It’s a very symbiotic marriage, a partnership that added benefits all associated,” Chatterjee claims.
If you take care of your finances on your phone or pc, you know how vital it is to do the job with an establishment with person-pleasant electronic equipment. Kiplinger’s Private Finance recently reviewed apps and websites to come across the money businesses with the ideal electronic applications.
The bank’s mobile application and web site are the most person-friendly of the bunch, combining easy navigation, an desirable interface and a handy set of capabilities for bank clients.
Account balances are displayed neatly and prominently on the property web page, and you can drill down into every single account to see a listing of modern transactions and other information.
A single noteworthy application characteristic: Rather than tapping a button to finish sure transactions, this sort of as transferring money or depositing a check, you drag the button across the display.
Most effective card issuer: American Convey
The company’s cellular application and website are basic to navigate yet provide a good deal of characteristics and operation.
Persons are also reading…
It’s quick to come across and use a chat box that provides automatic answers to your queries, as perfectly as stay obtain to client assistance associates. Your assertion stability, whole equilibrium and payment due are featured prominently at the prime of the dwelling webpage, and current transactions are shown under.
Evidently marked buttons consider you to web pages for statements, payments, viewing and redeeming benefits balances, and running these types of tasks as replacing a broken or stolen card and altering account notifications. And consumers in the Membership Rewards application can type by means of card gains on the app and use on-the-go equipment.
Ideal mortgage loan financial institution: U.S. Lender
By way of U.S. Bank’s site and cell app, you can see existing hold out situations to communicate to a client assistance consultant on the cellular phone and ask for to have a rep connect with you if you’d rather not hold out on keep.
Prospects can also “co-browse” with lender representatives, letting shoppers to share their monitor so they can navigate the web page or app with each other. And final summer months, the bank launched a person-way video clip of the agent so that clients can see the individual with whom they are talking.
In response to an influx of property finance loan buyers who necessary economic accommodations as the pandemic induced the economic system to crater, U.S. Lender extra the capacity for clients to make payments by means of its help-program web portal. And all of the essential resources keep their very own.
Geico will get the nod as our electronic winner among the insurers, with a clean up, effectively-made application and website that present great options for the two consumers and noncustomers.
As a Geico consumer, you can use the application to pull up digital insurance ID cards on the go, get roadside aid, post pictures to get an estimate of car problems inside of about 20 minutes, make payments, and chat with a digital assistant about billing, guidelines and other concerns.
Go to Kiplinger.com for extra on this and related cash subjects.
As soon as you’ve achieved your retirement purpose, you face one more challenge: Figuring out how a great deal of your cost savings you can securely withdraw every calendar year without the need of running out of cash.
A guideline that has stood the take a look at of time is the 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rule, which was produced by William Bengen, an MIT graduate in aeronautics and astronautics who later on turned a certified monetary planner.
How it operates: In the initial calendar year of retirement, withdraw 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from your IRAs, 401(k)s and other tax-deferred accounts, which is in which most employees hold their retirement discounts.
For every single year immediately after that, increase the dollar amount of money of your once-a-year withdrawal by the earlier year’s inflation amount. For example, if you have a $1 million nest egg, you would withdraw $40,000 the 1st year of retirement. If inflation that calendar year is 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, in the second 12 months of retirement you would enhance your withdrawal to $40,800.
This presents a useful way to calculate no matter whether you have saved sufficient to deliver the amount of profits you feel you will have to have in retirement.
But a latest report by financial commitment analysis business Morningstar suggests retirees could want to look at a much more conservative withdrawal amount of 3.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Underneath that scenario, a retiree with $1 million in personal savings would only be capable to withdraw $33,000 in the 1st calendar year of retirement.
Morningstar’s summary is primarily based on a combination of high inventory sector valuations, which are unlikely to go on, and small yields on fixed-income investments. Its examination assumes that a retiree has a portfolio consisting of 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} bonds and 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} shares and will consider withdrawals more than 30 years.
Reducing the sum you withdraw each individual calendar year indicates you are going to need to help save extra to create the earnings you want. But there are actions retirees can get that will make it possible for them to just take much larger withdrawals without having raising the risk that they’ll outlive their savings.
Delaying Social Protection is one method. You are going to get an 8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} credit for just about every 12 months you hold off having rewards after whole retirement age, or FRA, till age 70. (FRA is age 66 if you were born involving 1943 and 1954 and little by little rises to 67 for young people today.)
As well as, Social Stability positive aspects get an annual cost-of-dwelling adjustment.
Yet another technique is to modify withdrawals based on industry efficiency, having more compact quantities in the course of down a long time and increased withdrawals when the sector has done very well. Nonetheless another system is to forgo inflation changes, which would routinely decrease the volume you withdraw.