Students face debt and uncertainty despite graduate jobs surge

Students face debt and uncertainty despite graduate jobs surge

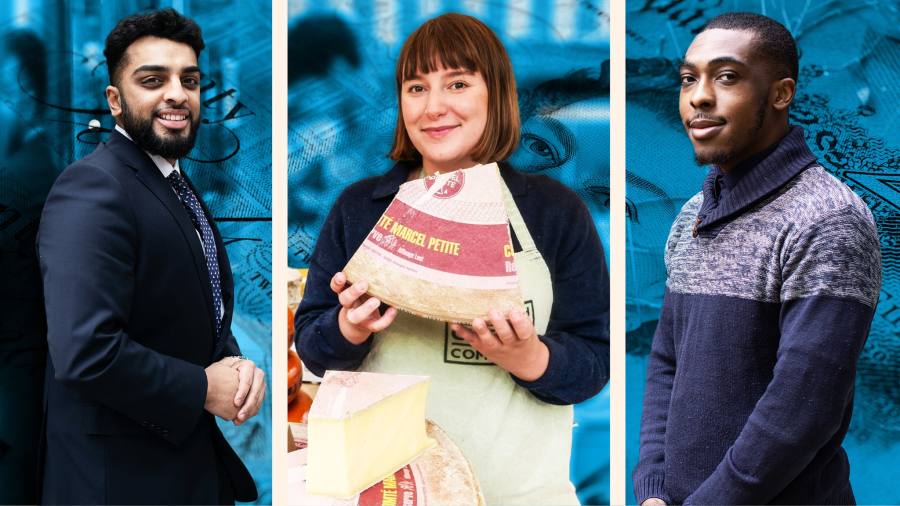
After months of rejection emails, Haider Malik was suddenly in high demand after he found a job in finance by pitching himself outside Canary Wharf tube station.

The plucky first-class banking graduate impressed commuters with his whiteboard and “go-getter” attitude. He had an interview for an accounting role at the property manager Canary Wharf Group within a few hours and landed a role by the end of the week.

His tale caught the imagination of news outlets as far away as Borneo. But even his extraordinary effort last November was only enough to gain a temporary contract.

Graduates such as Malik might have better luck this year. Amid signs that the pandemic may be easing, economic recovery and shortages of recruits have boosted the graduate jobs market.

At the extreme, top London law firms now offer newly-qualified solicitors eye-popping starting salaries of £150,000 a year as City companies try to cope with soaring demand for their services by hiring talented people.

In the wider economy, vacancies for university leavers are also rebounding: graduate opportunities are up by 20 per cent compared with 2019 and up 22 per cent compared to 2021, according to a recent survey by the Institute for Student Employers (ISE), a body that supports graduate recruiters.

With record numbers of young people opting for full-time education and Brexit limiting the inflow of EU talent, employers have even reshaped recruitment plans to hire more school leavers and apprentices to address shortages, says the ISE.

Meanwhile, the government and businesses alike plan to increase the added value in the economy, putting extra effort into recruiting able graduates with the right skills, in areas like maths, engineering and IT, for posts in technology and professional services.

“We fundamentally need educated young people in good careers to drive the economy, that’s not going to change,” says Stephen Isherwood, ISE chief executive. Those graduates who can take advantage of the post-pandemic hunt for talent could find themselves richly rewarded.

Bar chart of {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} showing Proportion of 18-year-olds accepted into UK universities

The workplace transformation

But it’s far from plain sailing. First, the number of students has risen steadily for years, increasing the demand for jobs: there were 2.5mn students in 2019-20, up from 2.3mn in 2015-16, according to the Higher Education Statistics Agency.

The recent increases cap a wholesale transformation of the workplace: of people aged 21 to 64, 42 per cent were graduates in 2017, up from 24 per cent in 2002.

The recruitment market is also still digesting the bulge in job seekers created by the pandemic, which decimated graduate opportunities in 2020-21. There were 91 applications per graduate vacancy in 2021, the highest on record for the ISE.

As Malik found, graduates were left facing rejection email after rejection email. Before landing his temporary role, Malik applied for 50 different graduate schemes and 30 to 40 entry-level roles. “Most of the time I didn’t receive a response or anything,” he says.

While the recovery is now driving a recruitment surge, the effects of this jobs crunch on those involved may be long lasting. Many graduates were forced to take poorer quality roles, according to the Institute for Fiscal Studies. It found there were fewer graduates and school leavers in full-time, skilled new jobs last year compared with 2019, but more in part-time or unskilled work, often in care homes, delivery driving or retail.

This may complicate their efforts to land the jobs they want in the long term, though Charlie Ball, head of higher education intelligence for research organisation Prospects, takes a positive view. He says: “It’s very difficult to say a graduate who decided to go work in a care home in 2020 was wasting their time and investment.”

However, it remains true that the pandemic eliminated “stepping stone” mid-skill jobs, including skilled clerical roles. The Institute of Employment Studies, a think-tank, says more people have been left in insecure and part-time work and less able to acquire the experience needed to pitch for their dream jobs.

Ball says that as the future of the office remains uncertain after the pandemic, the lack of these jobs is still an issue, especially as they are declining anyway because of automation.

Column chart of Average debt on entry to repayment in England (£'000) showing Student loan debt soars

A benefits boom

Still, those who jump through the hoops and secure good jobs will find their degrees pay off. Median salaries have risen to £35,000 for workers of any age with a degree, a premium of £9,500 over non-graduates.

For 21-to-30-year-olds, the finance and banking sector offers the highest median starting salaries of about £30,000, though some investment banking schemes offer many times this in exchange for gruelling hours. Top young lawyers are not alone in securing £150,000 a year.

Ball warns that wage rises may not keep pace with inflation for all graduates but other benefits are also being upgraded. He says: “Businesses will offer flexibility in lieu of wages. They’re likely to be big on flexible working and other perks rather than a big wage uplift.”

Many would-be applicants may not be aware of how quickly the tide is turning in their favour. Some may be working in the temporary jobs they took up to make ends meet; others have signed up in record numbers for full-time education. Sam Windett, deputy director at Learning and Work Institute, says: “We’ve seen a huge rise in full-time education and that’s something that wasn’t predicted at the start of the pandemic.” 

Some 48 per cent of 18-24-year-olds are in full-time education, the highest rate on record, compared with 43 per cent before the pandemic. Windett says: “It could be a consequence of young people sheltering in the education system and not looking for jobs at this point.”

So some employers are struggling to recruit, especially for technical posts. Although ISE’s 177 member organisations, which includes large employers such as the Civil Service, Marks and Spencer and PwC, filled 95 per cent of their positions last year, many found it difficult to recruit in roles such as IT, engineering and skilled trades roles.

Isherwood encourages graduates who think their degree subject may limit them to certain jobs to cast their nets wider. “86 per cent of employers don’t recruit by subject discipline,” he says. “The UK market is different to anywhere else in the world. The majority of the intake often don’t have a degree relevant to the subject.”

With few recruiters focusing on subjects, Isherwood says, people who were resourceful during the pandemic will stand out. “Those who said ‘there was a pandemic, I couldn’t do anything’ will struggle. Those who showed some initiative during the pandemic will be popular.”

Line chart of UK unemployment by age group ('000s) showing Young jobless in the age of Covid

A burden of debt

Students emerging from the pandemic also carry a big burden of debt. This is especially true for those who extended their studies and took on extra loans. The total outstanding student loan debt in England was £160bn at the end of 2020-21, up from £140bn in the previous year.

Undergraduate degrees now cost up to £9,250 per year in the UK. Students starting in 2007 would have paid less for the entirety of a three-year degree. When maintenance loans for living costs are also included, the average debt among those graduating in 2020 was £45,000. For those who restart degrees or take on further loans for postgraduate studies, this figure can be even higher.

Graduates will not necessarily repay everything. They begin repaying back loans once their salary reaches £27,295, paying 9 per cent of anything earned above that figure for at least 30 years. But those who earn less are not required to pay and, for most student loan plans, any outstanding balance 30 years after the first repayment is due is written off.

Last month, the government froze the salary threshold for the 2022-23 tax year, a move described by The Institute for Fiscal Studies, a think-tank, as a “tax rise by stealth”.

The pandemic generation of students, who missed out on face-to-face education, is particularly angry at this prospect. Malik, a graduate of Middlesex University, says: “When the world goes upside down in terms of coronavirus, someone should lend a hand. There was furlough, business grants, what was there for students? Nothing.”

Added to student debt are the rising costs for graduates after they leave university. A study by the think-tank Demos found that those in the 18-to-30-year-old bracket would spend more on housing and bills than other age groups — an average of nearly £1,300 per month more than over-60s.

Limited savings also mean the age group is more vulnerable to financial shocks. For graduates, the monthly debt repayments add to this burden, although graduates generate £10,000 a year in higher earning potential compared with their non-graduate peers.

Should the government increase those student loan repayments by lowering the threshold to £23,000, a graduate earning below the current threshold would have their take-home pay cut by more than £800 annually, says the Institute for Fiscal Studies.

Young people emerging from recessions are more likely to suffer financial scarring, the Resolution Foundation has found, creating barriers on the amount of money they will earn throughout their careers.

It is too early to tell if such effects will persist in today’s lively jobs market as the recovery has been much better than many analysts expected. Malik is trying to help his peers benefit. Using a newly-found social media platform, he is organising careers events for new graduates, showing the same initiative that led him to pitch himself at Canary Wharf. He says: “It’s good to tackle the issue rather than just talk.”


A slice of good fortune

When a job at a London cheese stall became available, one student knew she was in with a chance.

Playing on her surname, Leia Monger, a 22-year-old architecture graduate, told her future employers: “I’m very interested in this job of being a part-time monger, but I’m also a full-time monger.”

The stellar pitch and nominative determinism won Monger her role. Having begun at the stall in the first year of her undergraduate degree in 2017, she now works five days a week at the Borough Cheese Company, between Borough Market and King’s Cross.

What’s in a name? Leia Monger landed a job with the Borough Cheese Company © Tara Rudd

While graduates deal with stiffer competition for top graduate roles, there are opportunities for part-time work to get through their degrees and earn money after graduation. Three-quarters of hospitality businesses are increasing pay to retain staff, according to research agency CGA.

Monger says: “I think I’m lucky that I had that job all through university. I’ve been able to pick up practically full-time hours.”

Hospitality and retail, where young people are disproportionately employed, fell off a cliff during lockdowns, eating into students’ pay packets. From February 2020 to March 2021, 60 per cent of job losses were among under-25s.

However, this trend has since reversed. Jobs are in plentiful supply in these sectors and there is less competition than pre-pandemic from EU workers.

Graduates may be sheltered in the rebounding retail and hospitality sector: the latest statistics from the ONS show that the number of young people not in education, employment or training is no higher than before the pandemic, at 10.1 per cent in late 2021 compared to 11.1 per cent in late 2019.

The problem is the fierce competition for top quality jobs. Monger “loves cheese” but is seeking an architectural placement before commencing a masters degree, the next step towards qualifying as an architect, where she would like to work on public or social housing.

The job hunt is “quite demoralising”, she says. “I do really love my job, but what’s been hard is you have to rewire what you want from your [degree].

“You are taught that you have to design your career as an undergraduate. But those opportunities aren’t there.” 

Internships and short-term roles

Graduate programmes have recovered from the pandemic but “people aren’t taking short-term hires as much as they would have done,” Tristram Hooley, former head of policy at ISE, says.

Data from the organisation shows that internships are recovering, but have shifted dramatically online: 72 per cent were performed virtually in the 2020-21 financial year.

It was also “exceptionally hard” to get work experience, roles or internships or apprenticeships during the [early part of the] pandemic, when more than half of the class of 2020 had their graduate job offers deferred or rescinded or lost internships.
Charlie Ball of Propects said. “This year has not been significantly better.”

Though not as reliable a route into employment as a hiring programme, internships and placements are often a route into quality employment for young people, allowing them to build skills and networks.

Emmanuel Sosanya, a 24-year-old Kent University graduate from Dagenham, east London, has set up as a sole trader after a short-term placement with private equity company Mutares.

He started trading at 16, using demo accounts to explore foreign exchange and commodity markets while still at school. But, he admits: “Getting into finance the non-traditional way is really hard, especially from the background I have.” 

His decision to set up as a sole trader following the role is a sign of the informal way in which placements and internships can help young people. “After the internship, I thought ‘let me see if I can use this skill now properly’,” he says. He manages about $250,000 in investor capital from his family home.

Competition for internship roles is almost as fierce as those for graduate programmes, Dan Hawes of Graduate Recruitment Bureau says. For those from minority backgrounds, like Sosanya, entering white-dominated sectors like finance can also prove challenging.

Sosanya found the Mutares role through the Black Training and Enterprise Group (BTEG), a London charity which supports young people of colour into jobs. In highly competitive environments like finance, he said, “there’s a barrier”. “All the people I was working with there were Cambridge and Oxford grads and I was the only one who was black. For someone from my background, it’s harder to get into these finance roles.” 

Jeremy Crook, chief executive of BTEG, said efforts should be made to address diversity issues.

“I think there’s too much reliance on the market returning to normal,” he says. “It wasn’t particularly fair to start with.”
Business News: DIVINE Home Care Services earns client satisfaction award | News

Business News: DIVINE Home Care Services earns client satisfaction award | News

DIVINE Residence Care Solutions declared currently that it has received the 2022 Best of Residence Treatment – Company of Decision Award from Residence Care Pulse. The Hillsboro-centered agency receives this recognition for the fifth 12 months in a row.

The Company of Selection Award is granted only to top rated-rating home care suppliers, dependent on consumer satisfaction scores collected by Property Care Pulse, an unbiased satisfaction study business for home care. DIVINE Property Treatment Expert services is identified among a decide on few property treatment providers throughout the country who have established their means to offer superb treatment. DIVINE has been given the award consecutively for the last 5 a long time.

“We’re excited to congratulate DIVINE Dwelling Treatment for their well-deserved achievement on earning the Greatest of Dwelling Treatment – Provider of Selection Award,” states Todd Austin, President of Home Care Pulse. “It’s great to see the difficult perform that DIVINE is putting in to give superior-quality treatment and work – and their energy is not going unnoticed. This award enables them to offer evidence of high quality to opportunity new customers and caregivers.”

Very best of Dwelling Treatment – Service provider of Decision award-winning providers have contracted with Residence Care Pulse to obtain comments from their customers by conducting reside phone interviews with their customers just about every thirty day period. Because Household Treatment Pulse is a third-occasion enterprise, it is ready to gather trustworthy and impartial opinions.

“We are really honored to acquire this award, and exceptionally happy of our crew, which inspite of the challenges has managed the focus on the protection and wellbeing of our clientele at all times” said Claudia Berdegué, Administrator and co-owner of DIVINE.

“At Dwelling Treatment Pulse, our mission is to support property care firms make an practical experience that goes beyond client and caregiver anticipations,” said Todd Austin, President of Household Treatment Pulse. “We are pleased to realize DIVINE Property Treatment Services as a Best of Residence Care – Company of Choice and to celebrate their accomplishments as a dependable home care company.”

To come across out more about DIVINE’s motivation to excellence, please pay a visit to the agency’s web page at www.divinehomecareservices.com or call 254-294-3896 24/7.

About DIVINE Household Treatment Products and services.

Founded in 2012, DIVINE is the main unbiased home care company in Central Texas. From hourly visits to 24-hour treatment, and from companionship to Alzheimer’s treatment, we deliver individual aid and domestic companies to our valued customers in the comfort and ease of their individual households.

About Property Care Pulse

Property Treatment Pulse potential customers the home care business in experience administration, on the web instruction, and assessment management. The firm also conducts the annual Property Care Benchmarking Study, the most comprehensive survey of property care vendors in North The united states and administers the once-a-year Greatest of Dwelling Treatment awards to agencies that realize greatest-in-class customer and caregiver satisfaction scores. For extra information, go to www.homecarepulse.com/..

Stocks plunge following red-hot inflation print, Fed policymaker’s remarks

Stocks plunge following red-hot inflation print, Fed policymaker’s remarks

U.S. stocks were deep in the red on Thursday as Wall Street weighed another decades-high inflation print and remarks by St. Louis Federal Reserve President James Bullard that signaled the central bank could intervene more aggressively than anticipated to tighten monetary conditions amid surging prices levels.

The Dow Jones Industrial Average snapped a three-day winning streak closing down 500 points, or 1.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, after comments from Bullard, who said in an interview that he favors an interest rate increase of 100 basis points by July 1. The S&P 500 was down 1.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and the Nasdaq Composite, weighed down by losses in tech, shed 2.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Meanwhile, the closely-watched 10-year Treasury note jumped to 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for the first time since August 2019.

“I typically take the opinions of St. Louis Fed president Jim Bullard with a grain of salt because he has a history of being all over the map with his forecasts and thoughts,” Bleakley Advisory Group CIO Peter Boockvar said in a note. “He does though vote this year and thus is very relevant to pay attention to.”

U.S. inflation accelerated last month in the fastest rise since 1982, with prices across a wide range of goods and services soaring further amid lingering shortages and supply chain disruptions. Consensus economists were looking for a 7.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rise, according to Bloomberg data.

“While inflation continued to overshoot the Fed’s target in January, fundamental drivers of inflation are starting to improve,” Comercia Bank chief economist Bill Adams said in a note. “Remember, a big part of the surge in prices was from shortages, and the economy is making big strides to reduce shortages.”

Quadratic Capital Management founder Nancy Davis echoed a similar point in post-CPI commentary.

“While inflation is weighing heavily on Federal Reserve policy decisions, our current inflationary environment is unconventional and is caused largely by supply chain disruptions, something the Federal Reserve cannot fix with tighter monetary policy,” Davis said.

The 10-year Treasury yield’s jump to 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} pressured technology stocks in Thursday’s trading session. Losses in heavyweights such as Apple (AAPL) (closed down 2.34 to $172.16 per share) and Alphabet (GOOG) (closed down 2.02{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $22,772.05 per share) dragged down markets.

“Even though we see the yield curve start flattening, we are watching the 10-year very closely and the CPI number,” ERShares chief operating officer and chief investment strategist Eva Ados told Yahoo Finance Live on Wednesday, adding the three most significant facors in the data are costs associated with labor, food prices, and energy.

Ados said once the 10-year Treasury hits 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, “that will trigger a psychological level and more anxiety in markets.”

In the previous session, the indexes were lifted by an influx of strong corporate earnings. The Walt Disney Company (DIS), a component of the Dow, unveiled first quarter 2022 results after the bell on Wednesday that sharply beat estimates. Better than expected growth for the entertainment giant’s streaming service Disney+ and a recovery in theme park attendance sent shares up as much as 9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} after the report. Uber (UBER) also posted results after market close, revealing quarterly revenue that topped analyst forecasts and indicated headwinds caused by the Omicron COVID surge have eased.

“Last year, it was all about ‘tell me the story and how great it is,’ while this year, it’s ‘show me the money and show me that you’re growing profitably — that you have cash flow,’” Satori Fund founder and portfolio manager Dan Niles told Yahoo Finance Live.

After a surprise shift by the Federal Reserve on how aggressively it would tighten monetary conditions rocked equities in January, investors have found relief in strong earnings over recent weeks. Bank of America said in its latest update that S&P 500 earnings per share (EPS) are exceeding consensus expectations by 6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} so far for the latest quarter and tracking toward a growth rate of well over 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on a year-over-year basis.

But as earnings season winds down, investors will turn their attention back macroeconomic concerns, with special focus on Thursday’s inflation number — an annual CPI gain of 7.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} — at a 40-year high.

“We do think the focus shifts back to the macro side of the ledger this week,” Stuart Kaiser, UBS head of equity derivatives research, told Yahoo Finance Live on Tuesday, adding the European Central Bank and Bank of England are tightening monetary policy along with the Fed and a series of high inflation prints are expected in coming months. “When we put that all together, we don’t think the bumpy ride is over.”

4:00 p.m. ET: Wall Street’s main indexes cap session in negative territory

Here were the main moves in markets at Thursday’s close:

  • S&P 500 (^GSPC): -83.13 (-1.81{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,504.05

  • Dow (^DJI): -526.37 (-1.47{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,241.69

  • Nasdaq (^IXIC): -304.73 (-2.10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 14,185.64

  • Crude (CL=F): +$0.21 (+0.23{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $89.87 a barrel

  • Gold (GC=F): -$8.90 (-0.48{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,827.70 per ounce

  • 10-year Treasury (^TNX): +10.2 bps to yield 2.0310{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

3:25 p.m. ET: Affirm plunges 33{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} after miss on revenue forecast

Buy now, pay later provider Affirm Holdings Inc. (AFRM) reported a larger loss for its second fiscal quarter due to an increase in stock-based compensation following the company’s initial public offering.

In the three months ended Dec. 31, net loss attributable to common shareholders widened to $159.74 million, or 57 cents per share, from a loss of $26.61 million, or 38 cents per share, a year earlier.

Shares plunged as much as 33{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in afternoon trading. Affirm was down 19.35{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $60.23 per share as of 3:23p.m. ET.

Affirm also confirmed it mistakenly reported a portion of its second-quarter results ahead of schedule after a since-deleted tweet was sent from the company’s official Twitter account Thursday morning.

Affirm logo displayed on a phone screen and Affirm website displayed on a laptop screen are seen in this illustration photo taken in Krakow, Poland on August 16, 2021. (Photo by Jakub Porzycki/NurPhoto via Getty Images)

Affirm logo displayed on a phone screen and Affirm website displayed on a laptop screen are seen in this illustration photo taken in Krakow, Poland on August 16, 2021. (Photo by Jakub Porzycki/NurPhoto via Getty Images)

2:31 p.m. ET: Dow sheds 500 points as rate worries weigh on tech stocks

Here were the main moves in markets as of 2:31 p.m. ET:

  • S&P 500 (^GSPC): -66.45 (-1.45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,520.73

  • Dow (^DJI): -454.94 (-1.27{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,313.12

  • Nasdaq (^IXIC): -215.12 (-1.48{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 14,275.25

  • Crude (CL=F): -$0.11 (-0.12{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $89.55 a barrel

  • Gold (GC=F): -$3.20 (-0.17{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,833.40 per ounce

  • 10-year Treasury (^TNX): +9 bps to yield 2.0190{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

1:05 p.m. ET: Dow tumbles after Fed president says he favors 100bp hike by July

Fed St. Louis President James Bullard said he favors interest rate increase of 100 basis points by July 1, including a 50 basis point hike as soon as March.

“I’d like to see 100 basis points in the bag by July 1,” Bullard, who is voting on monetary policy this year, said in an interview with Bloomberg News on Thursday. “I was already more hawkish but I have pulled up dramatically what I think the committee should do.”

The Dow Jones Industrial Average dropped 200 points following the remarks.

Bullard is said to be the most hawkish member of the Federal Open Markets Committee (FOMC). His take comes following another red-hot read on the Consumer Price Index (CPI), which notched a 7.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} annual gain in January.

12:13 p.m. ET: Stocks edge higher to pare earlier losses

Here were the main moves in markets during midday trading:

  • S&P 500 (^GSPC): -16.16 (-0.35{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,571.02

  • Dow (^DJI): -76.11 (-0.21{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,691.95

  • Nasdaq (^IXIC): -46.31 (-0.32{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 14,444.06

  • Crude (CL=F): +$1.86 (+2.07{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $91.52 a barrel

  • Gold (GC=F): +$5.80 (+0.32{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,842.40 per ounce

  • 10-year Treasury (^TNX): +8.1 bps to yield 2.0100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

9:30 a.m. ET: US stocks falter as Wall Street weighs decades-high CPI print

Here were the main moves in markets at the start of Thursday’s session:

  • S&P 500 (^GSPC): -54.84 (-1.20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,532.34

  • Dow (^DJI): -262.99 (-0.74{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,505.07

  • Nasdaq (^IXIC): -258.68 (-1.79{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 14,231.69

  • Crude (CL=F): -$0.22 (-0.25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $89.44 a barrel

  • Gold (GC=F): -$7.50 (-0.41{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,829.10 per ounce

  • 10-year Treasury (^TNX): +5.3 bps to yield 1.9820{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

8:55 a.m. ET: Stock futures tumble after red-hot inflation data

Here’s how stock futures fared as investors mulled the latest CPI report

  • S&P 500 futures (ES=F): -37.75 points (-0.82{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,540.00

  • Dow futures (YM=F): -139 points (-0.39{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 35,502.00

  • Nasdaq futures (NQ=F): -192.00 points (-0.28{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 14,846.25

8:30 a.m. ET: Inflation reaches fresh 40-year high

U.S. inflation accelerated in January, with prices across a wide range of goods and services soaring further amid lingering shortages and supply chain disruptions.

The Consumer Price Index (CPI) released by the Bureau of Labor Statistics Thursday morning registered a 7.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} annual gain in January. Consensus economists were looking for a 7.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rise, according to Bloomberg data. This represented the fastest rise since 1982, as well as an acceleration from the 7.0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} year-over-year increase seen in December.

Energy prices remained a key contributor to the overall CPI and were up by 27{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on a year-over-year basis in January. Within energy, fuel oil prices jumped 9.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on a monthly basis, tracking the rise in crude oil prices, which rallied to a seven-year high at the beginning of the year. Electricity prices also jumped by a pronounced 4.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on a month-over-month basis.

8:30: a.m. ET: Jobless claims decline as Omicron labor market disruptions ease

First-time unemployment filings came in lower in the latest weekly data, continuing a recent downward trend in jobless claims as Omicron-related pressures on the labor market begin to abate. Another 223,000 Americans filed new claims for the week ended Feb. 5, below expectations of 230,000.

Filings for unemployment insurance have fallen consistently in recent weeks after a temporary surge in mid-January to a print of nearly 300,000, the highest level since October. The rush of U.S. workers applying for benefits was attributed to disruptions from the Omicron variant of COVID-19 and adjusted workforces following the seasonal hiring increase at the end of 2021.

7:00 a.m. ET: Contracts on Wall Street’s main benchmarks flat ahead of CPI print

Here were the main moves in futures trading ahead of Thursday’s open

  • S&P 500 futures (ES=F): -72.50 points (-0.16{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,570.50

  • Dow futures (YM=F): +32.00 points (+0.09{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 35,673.00

  • Nasdaq futures (NQ=F): -43.75 points (-0.29{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 14,994.50

  • Crude (CL=F): +$0.96 (+1.07{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $90.62 a barrel

  • Gold (GC=F): -$3.00 (-0.16{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,833.60 per ounce

  • 10-year Treasury (^TNX): -0.00 bps to yield 1.9290{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

6:00 p.m. ET Wednesday: Stock futures rise slightly ahead of key inflation data

Here’s how the key indexes fared in post-market trading Wednesday:

  • S&P 500 futures (ES=F): +4.00 points (+0.09{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,581.75

  • Dow futures (YM=F): +78.00 points (+0.22{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 35,719.00

  • Nasdaq futures (NQ=F): +15.50 points (+0.10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 15,038.25

  • Crude (CL=F): +$0.31 (+0.35{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $89.97 a barrel

  • Gold (GC=F): +$2.60 (+0.14{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,833.60 per ounce

  • 10-year Treasury (^TNX): -2.5 bps to yield 1.9290{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

A trader works on the floor of the New York Stock Exchange at the closing bell January 14, 2022, in New York, New York. (Photo by TIMOTHY A. CLARY / AFP) (Photo by TIMOTHY A. CLARY/AFP via Getty Images)

A trader works on the floor of the New York Stock Exchange at the closing bell January 14, 2022, in New York, New York. (Photo by TIMOTHY A. CLARY / AFP) (Photo by TIMOTHY A. CLARY/AFP via Getty Images)

Alexandra Semenova is a reporter for Yahoo Finance. Follow her on Twitter @alexandraandnyc

Read the latest financial and business news from Yahoo Finance

Follow Yahoo Finance on Twitter, Instagram, YouTube, Facebook, Flipboard, and LinkedIn

Health Care Cost Basics: What They Are and Ways to Save

Health Care Cost Basics: What They Are and Ways to Save

Putting aside money for emergencies, like replacing a roof or a major car repair, is one of the age-old mantras of personal finance.

But today there’s one major potential expense that, until relatively recently, few working people rarely thought about: Paying for out-of-pocket medical costs.

Why? Because until the past decade or so, most employer health care plans covered the majority of employees’ medical costs.

Not anymore.

The spiraling cost of health care has resulted in many employers shifting more of these expenses to employees. Monthly premiums for traditional health care plans that used to be fairly reasonable now may cost $600 per month or more. And most of these plans have annual deductibles — money you must pay out of pocket for medical expenses before the plan takes over most of the costs.

Since most employees can’t afford these plans, many companies now also offer high-deductible health plans (HDHPs). How pervasive are these plans? In 2019 51{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of all U.S. employees were enrolled in HDHPs.

And for those who aren’t covered at work and have to purchase their own health insurance, HDHPs generally offer the lowest premiums of plans available in state and Affordable Care Act insurance marketplaces.

However, someday — maybe a few years from now, maybe next week — you will need medical treatment for an injury or a major illness. If you’re not financially prepared, you may discover the hard way what “high-deductible” really means.

Three kinds of expenses

Deductibles

Your HDHP may state that it has a $4,000 annual deductible. That means you’ll have to use $4,000 of your own money to pay for medical treatments before the plan starts covering some of the costs. If you don’t believe you’ll have to pay that much, think again. In 2018, the average cost for a knee replacement was $35,000. For spinal fusion, $110,000. Thinking of having a child? It could cost you $4,500 or more once all pre-natal care, delivery and post-partum expenses are tabulated.

As a participant in an HDHP, I’ve personally experienced the painful price of health care. Last year I was healthy for most of the year, but the costs for one visit to an out-of-state emergency room and follow-up appointments ate up my entire $2,800 deductible.

Thankfully, my deductible was relatively reasonable, considering that in 2020 the average deductible for individual subscribers was $4,364 and $8,439 for those with family coverage, according to research conducted by eHealth.

But your expenses may not end when you hit your deductible limit. Many HDHPs require to you to continue to pay partial costs through co-payments and co-insurance.

Co-payments

Co-payments are fixed amounts you pay out of pocket for health care expenses. How much you pay depends on whether you’ve hit the deductible or not. For example, if a procedure costs $500 and your co-payment for such a procedure is $20, you’ll pay $20 only if you’ve paid the maximum deductible. Otherwise, you’ll pay the full $500 out of pocket.

Co-insurance

If deductibles and co-pays weren’t enough, co-insurance can add even more to your medical tab. It’s a percentage of covered health care services you may still have to pay on your own even when you’ve maxed out your deductible.

Let’s say your plan has a 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} co-insurance requirement. If you’ve already hit your deductible and then have another procedure that costs $1,000, you’ll still have to pay $250 out of pocket.

When does it end?

Fortunately, the IRS sets maximum annual limits for total out-of-pocket medical expenses for HDHPs. In 2022, this limit is $7,050 for individuals and $14,100 for families. Any expenses above that level will be fully covered by your HDHP.

But remember — these limits reset every plan year.

Health Savings Accounts to the rescue

If there’s one silver lining in this scenario, it’s that many employers that offer HDHPs also offer Health Savings Accounts (HSAs).

With an HSA, you make pre-tax contributions from your paycheck to an investment account that allows you to withdraw contributions and earnings tax-free to pay for qualified health care expenses.

In addition to medical treatments, you can use your HSA to pay for prescription and over-the-counter drugs, medical equipment, dental expenses, physical therapy and even acupuncture and aromatherapy. You can also use your HSA to help pay for long-term-care insurance premiums.

For 2022, the maximum amount you can contribute is $3,650 per individual ($7,300 per family) with an additional $1,000 in “catch-up” contributions per person for those 55 and older. Some employers also make periodic contributions to their employees’ HSAs to help offset some of these out-of-pocket expenses.

Completely portable

The great thing about HSAs is that you never have to make withdrawals. For example, you may choose to pay your current medical bills from your savings and reserve your HSA money for health care costs during retirement. (Note that once you enroll in Medicare you can no longer contribute to an HSA.)

If you start a new job with an employer that has an HDHP and HSA, you can transfer the assets from your old HSA into the new HSA. If they don’t offer an HSA, you can move assets from your old HSA into one offered by a financial services company. Keep in mind that if you don’t enroll in your new employer’s HDHP (or they don’t have one) you can’t make additional contributions to your HSA.

Having an HSA can help take the sting out of out-of-pocket medical expenses when they occur — but only if you contribute to it.

This may be challenging if you’re also trying to save for retirement, your children’s higher education or a new home. But considering that the pre-tax contributions you make to your HSA have the same taxable-income-lowering benefits as contributing on a 401(k) account, there are advantages to contributing as much as you can to both accounts.

If you’re fortunate enough to receive a tax refund, consider contributing some of it to your HSA. Even though these contributions are after-tax, they may be deductible. If you’re planning on doing this, make sure that your combined pre-tax and after-tax contributions don’t exceed the annual limit.

Other ways to lower health care expenses

This may sound like a tough-love situation, but the fewer family members covered by your plan the lower your premiums and out-of-pocket expenses may be. If your adult children are covered by your HDHP but work for a company that offers its own health care plan, it might be time to encourage them to experience the “joys” of managing their own health care expenses. They’ll have to do it anyway, since at some point they’ll be too old to be covered by your plan (generally age 26, but higher in a few states).

If you and your spouse both have HDHPs at work, compare the monthly premiums, deductibles, co-pays, co-insurance and maximum out-of-pocket expenses for each option. If both options let your use your current primary care physicians and specialists, you may both want to switch to the more potentially affordable option.

And if you’re thinking of having a procedure done, you may also want to estimate total costs in your area. 

It’s unfortunate that people may need to add “future health care costs” to their list of savings goals, but this is a reality that many will have to plan for. If you need help figuring out how to balance these competing priorities, a qualified financial planner can provide guidance to help you make sure that staying healthy doesn’t significantly harm your financial well-being.

Financial Adviser, Partner, Canby Financial Advisors

Joelle Spear, CFP® is a financial adviser and a Partner at Canby Financial Advisors in Framingham, Mass. She has an MBA with a finance concentration from Bentley University.
Securities and advisory services offered through Commonwealth Financial Network®, Member FINRA/SIPC, a Registered Investment Adviser. Financial planning services offered by Canby Financial Advisors are separate and unrelated to Commonwealth.

Should You Get Travel Insurance for Your Spring Break Trip? | Travel

Should You Get Travel Insurance for Your Spring Break Trip? | Travel

Winter is thawing, midterms are on the horizon and beach travel promotions are populating each other publish on your social feeds. This can only imply a person detail — spring break is coming.

Amid the daydreams of sunlight and relaxation, ski hills and hot tubs, or community support outings, college or university and graduate pupils may well be weighing the execs and downsides of spring break travel in the COVID-19 era.

If you pick to vacation, finding a journey insurance coverage policy can be a clever income shift. This coverage can enable shield not only you, but the revenue you prepay for journey expenditures like flights, motels or that will have to-see live performance. In circumstance your designs go awry (which, let us deal with it, feels far more possible now than ever just before), this coverage can be your preserving grace.

What type of journey insurance policies is out there? Do you even require it? Here are a few vital points to preserve in mind when determining regardless of whether to purchase vacation insurance policy for spring break.

Search for journey insurance plan that incorporates COVID coverage

Persons are also reading…

Regardless of if you are traveling overseas or domestically, if you are contemplating purchasing vacation insurance policy, it’s clever to assure it addresses COVID-connected losses. Though it is tempting to purchase low cost basic journey coverage, having much more complete coverage will improved secure you all through the pandemic.

This is significant for a number of explanations:

  1. You’ll be lined for any professional medical expenses incurred if you develop into ill with COVID throughout your excursion.
  2. If you catch COVID a several times ahead of departure and have to have to cancel your nonrefundable excursion programs, COVID-associated excursion cancellation coverage will safeguard your down payments.
  3. If you check optimistic before your return flight household and want to quarantine, journey interruption insurance plan will kick in.

“If you or a touring companion are individually requested to quarantine ahead of or all through your excursion simply because you had been exposed to COVID-19, that can be a covered motive for vacation interruption,” in accordance to Allianz Travel Insurance coverage insurance policies that contain COVID protection.

In a scenario like this, the protected restrictions will change. But normally, you can expect to be covered for more lodge nights, transportation expenses due to the fact of the interruption and the income wanted to possibly terminate your current flight and rebook a new a person.

These last-minute costs can actually add up, so a plan that guards you towards these losses is valuable.

Not all bookings are nonrefundable

As a typical rule, journey insurance is ideal for safeguarding nonrefundable vacation designs. If your transportation or remain is nonrefundable, excursion insurance policy will assistance you get your cash back if you want to terminate for a coated purpose.

Even so, several vacation firms, together with most airways and hotels, have loosened their improve and cancellation policies in current yrs. United, for occasion, has “permanently gotten rid of transform costs for most overall economy and top quality cabin tickets for flights in just the U.S., or concerning the U.S. and Mexico or the Caribbean.” Be aware that this doesn’t include things like its essential financial system fares.

If your spring crack trip can be modified or canceled without a penalty, determine if you continue to need to have the advantages of a in depth journey insurance coverage plan. You may not.

You can buy particular insurance policies a la carte

If you’re even now worried about trip interruptions — such as potentially catching COVID whilst traveling — you can obtain different journey interruption and vacation health care coverage insurance policies a la carte. This can be less expensive than getting a comprehensive system.

Another instance when you could not require a detailed plan is if you booked your spring split trip with a credit history card that presents vacation insurance coverage. Whilst the boundaries may perhaps be lower than on a thorough approach, it may perhaps be more than enough for you. Constructed-in credit history card journey insurance plan usually features journey interruption protection but not professional medical unexpected emergency costs.

So if you decide on not to obtain a journey coverage policy, look at acquiring a separate vacation clinical coverage prepare for peace of brain.

Award vacation cancellations are a a bit distinct ballgame

Some award travel bookings — that is, bookings produced with details and miles — nevertheless incur out-of-pocket taxes or redeposit fees for cancellations. In cases of covered excursion adjustments, journey insurance policies can go over all those prices.

However, various airlines and hotels have also loosened their adjust and cancellation policies for award bookings, and a lot of enable travel benefits to be reinstated without having price.

Some journey credit card issuers, like Chase, present cardholders an on-line vacation reserving portal. If you book journey on the system with the credit card that contains designed-in vacation insurance, your excursion will be included. Having said that, if you transfer factors to an airline or a resort, you no longer get the protection from your credit card.

If you are anxious you’ll improve your thoughts

What if you found a very good spring crack deal that you want to e book, but you’re not guaranteed no matter if you are going to want to travel when the time will come? In this case, weigh your alternatives.

If the flight and resort have a versatile cancellation policy or the strategies are refundable, you do not will need to get vacation insurance coverage right away. If you end up heading, you can normally order a plan a couple days before departure.

Nevertheless, if it can be a nonrefundable scheduling, the only way you can terminate and get some of your dollars back for any motive is if you invest in a journey insurance plan plan and incorporate on the optional Terminate For Any Reason protection. CFAR will make it possible for you to terminate a excursion up to 48-72 hrs before departure and gives again 75{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your nonrefundable deposits.

CFAR must be obtained at the very same time as a in depth travel insurance policies prepare, in 10-21 days of scheduling the excursion, and will have to insure the entire total of the vacation.

Final views on spring crack travel insurance plan

If spring break travel is doodled in your planner, travel insurance policies can be practical for a selection of causes — but it does not make perception for every trip. Look at what coverage you have and comb as a result of cancellation policies before scheduling. If you are nevertheless anxious about the what-ifs, take into consideration providing your self a lot more confidence in your journey programs and guard you with protection.

It could be one significantly less factor to stress about additionally, you’ll get an A in preparedness.

MnDOT gets $45 million bid for Highway 10 job

MnDOT gets  million bid for Highway 10 job

Kraemer North The usa is the obvious lower bidder for a virtually $45 million bridge alternative on Freeway 10 in Anoka, one of 3 jobs for which the Minnesota Office of Transportation opened bids Wednesday.

Basic, Wisconsin-primarily based Kraemer’s price tag of $44.88 million was about 9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} reduce than MnDOT’s $49.1 million estimate for the undertaking, which will swap the Highway 10 bridge in excess of the Rum River, among other scopes of do the job.

“It’s an older bridge, and it does require to be replaced,” MnDOT spokesman Kent Barnard explained Wednesday. “We’re going to be adding some auxiliary lanes on the bridge. And we’re also likely to be raising the profile of that bridge.”

The project captivated five bidders. Also vying for the operate had been C.S. McCrossan ($46.37 million), Ames Design ($46.495 million), Lunda Design ($46.95 million) and Redstone Design ($47.5 million).

The undertaking is aspect of a two-year effort to rebuild a 2.5-mile extend of Freeway 10 from Seventh Avenue to Thurston Avenue. Prepared advancements contain sounds wall set up, an underpass at Fairoak Avenue, roundabouts, new obtain lanes and more.

Barnard said the strategy is to commence building in April.

“Now that we have got the contractor on board, we’ll be ready to pin down the starting up date, with any luck , shortly,” Barnard mentioned. “The significant effect on targeted visitors is going to be this yr and up coming yr. Having said that, the venture will go on into the spring of 2024.”

MnDOT said the makeover will boost site visitors circulation, ease congestion and maximize safety. Other positive aspects include greater bicycle and pedestrian accessibility, a smoother trip, extended freeway daily life, and improved freight obtain.

In the undertaking spot, Freeway 10 carries among 33,500 and 61,000 motor vehicles per working day, MnDOT claimed, introducing that night westbound traffic backups lengthen a lot more than a mile from Fairoak Avenue to the Rum River.

MnDOT’s 2021-2024 Condition Transportation Advancement Method identifies condition bonds and federal dollars as main funding resources.

Whilst level of competition was brisk for the Freeway 10 occupation, two other initiatives allow Wednesday early morning attracted only one bidder just about every.

Hoffman Design Co. submitted a $17.3 million rate for a Freeway 43 enhancement in Winona County, and Northland Constructors of Duluth bid $6.9 million for a Blatnik Bridge resolve in Duluth.

MnDOT’s estimate for the Highway 43 job was $13.5 million, according to the project’s web site.

As part of the Winona County challenge, staff will rebuild Highway 43/Mankato Avenue from Sugar Loaf View to Belleview Street, and construct many roundabouts, the web site notes. The challenge is predicted to make improvements to basic safety, pedestrian infrastructure and street conditions.

The Duluth job will lengthen the life of the Blatnik bridge until eventually the crossing is changed in 2028, according to MnDOT. The venture consists of drainage program enhancements, deck and concrete floor repairs, painting, and additional.

Wednesday’s bidding will come on the heels of a Jan. 28 permitting, all through which MnDOT opened bids for 14 projects with a combined benefit of almost $74 million. Amongst these was a $17 million-plus enhancement on Freeway 36 in the east metro.

Just $73,000 divided the two least expensive bidders for the Highway 36 challenge. Park Development arrived in at $17.409 million, adopted by Valley Paving ($17.482 million), OMG Midwest ($17.997 million) and Bituminous Roadways ($19.9 million).

MnDOT’s estimate was $14.9 million, in accordance to the job web page. As section of the task, personnel will resurface a 12-mile extend of Highway 36 from Edgerton Road to Greeley Road, in accordance to MnDOT.

The task area extends from Tiny Canada to Oak Park Heights.

Michael Kronzer, MnDOT’s Freeway 36 venture supervisor, reported the most latest get the job done on that stretch of highway was a “micro-area crack and seal” in 2011 or 2012, a reasonably limited-term enhancement. The impending job is predicted to build about a 15-yr resolve.

Project positive aspects contain improved pavement and ride top quality, Kronzer said.

“The pavement was getting to a point where by it essential to be appeared at, and so that was the driver for the task,” Kronzer said, incorporating that the job will also consist of drainage and accessibility enhancement, and a signal update.

Relevant: Sole Highway 61 bid is greater than MnDOT envisioned


Like this write-up? Gain entry to all of our good information with a thirty day period-to-thirty day period membership. Commence your subscription here.