Wisconsin updating travel insurance regulations

Wisconsin updating travel insurance regulations
Wisconsin updating travel insurance regulations The legislation also establishes a limited strains travel insurance coverage producer license designed for coverage intermediaries and journey directors. (Credit score: Jareya Nualthong/Adobe Inventory)

Having impact March 1, 2022, Wisconsin’s vacation insurance legislation will classify travel insurance as component of inland marine strains as perfectly as incident and overall health traces if the plan involves illness and incapacity coverage, according to the state’s place of work of insurance coverage.

On top of that, the legislation states intermediaries with authority to promote a home and casualty line are not necessary to be appointed by an insurer to market journey insurance plan. Intermediaries accredited in any important line of authority can promote journey coverage, the Wisconsin Business office of the Commissioner of Insurance plan (OCI) reported.

The regulation also establishes a restricted lines vacation insurance coverage producer license developed for coverage intermediaries and journey directors, which Wisconsin defines as “a human being who immediately or indirectly underwrites, collects charges or premiums from, or adjusts or settles statements of inhabitants of this state in connection with journey insurance policy.”

The regulation also prohibits the use of “negative option” or choose-out processes that demand the purchaser to take an affirmative action to decline coverage when acquiring a trip, OCI documented.

Guidelines for ‘travel retailers’

Organization entities that give vacation products and services can now “offer and disseminate” travel insurance policy in Wisconsin beneath the licenses of a travel coverage producer if they adhere to the adhering to tips:

  • The purchaser of travel insurance policies is offered expected facts these kinds of as a description of the material conditions and the procedure for submitting a assert.
  • The minimal traces journey insurance policy producer keeps a sign-up of every single travel retailer that presents and disseminates vacation insurance on the producer’s behalf.
  • The restricted lines vacation insurance coverage producer designates an staff who is a accredited producer as the human being dependable for compliance with the statutes and guidelines of this condition.
  • The specified liable worker, the officers of the confined traces vacation insurance policy producer, and any other individual who directs or controls the constrained strains travel insurance policies producer’s coverage functions complies with coverage middleman fingerprinting specifications.
  • The constrained strains travel insurance policies producer pays all applicable licensing fees.
  • The limited lines vacation insurance coverage producer requires each staff and approved representative of the journey retailer whose duties contain presenting and disseminating vacation insurance coverage to acquire a software of instruction or instruction.

The law stipulates that journey stores, or their workers and approved reps, which are not accredited confined line travel coverage producers cannot choose the adhering to steps:

  • Evaluate or interpret technical terms, positive aspects, or situations of travel insurance coverage.
  • Assess or deliver advice regarding a future purchaser’s present coverage protection.
  • Maintain himself or herself out as an insurance company, a confined strains travel insurance producer or an insurance policy specialist.​

Connected:

EY to create 200 jobs, set up new finance hub in Calgary

EY to create 200 jobs, set up new finance hub in Calgary

Calgary’s affordable cost of living, well-educated workforce and quality of life were cited as key factors behind the company’s decision

Article content

Calgary’s financial services sector is expanding, with global firm EY poised to set up its first Canadian-based finance centre of excellence in the city.

Article content

Officials with EY Canada will announce Tuesday the establishment of the new hub, bringing 200 jobs to the city over three years, including 50 new hires immediately.

The centre will support internal company operations from across the Americas, with new personnel coming from local hires, as well as roles moving from other locations, said Alison Jackson, EY’s Calgary office managing partner.

Article content

The city’s affordable cost of living, well-educated workforce and quality of life were cited as key factors behind the company’s decision.

“We’ve been really impressed with the talent that we’ve been able to find, both in Calgary and people who are interested to move to Calgary,” Jackson said in an interview.

Article content

“It’s another vote of confidence in our ability to diversify our economy and our ability to attract people to the city.”

Article content

The consulting and accounting giant, which operates in more than 150 countries, has already started hiring staff for the centre.

It will employ financial professionals who perform a number of functions for the company, from data analytics and back-office support to controllership.

“We still like to say it’s cutting-edge internal finances services that will adopt new technologies,” Jackson added.

“There are a lot of people coming in … and they will be leveraging the kinds of technologies that we’re helping our clients get familiar with, whether that is robotic process automation or whether that’s data analytics. They will be applying all those tools.”

The company already has about 600 people working in the community, operating out of the Calgary City Centre building. EY Canada has not contracted out for additional office space, given the uncertainty with the pandemic, she said.

Article content

The announcement follows a string of finance and innovation-related announcements in Calgary in recent years.

In 2019, Morgan Stanley acquired Solium Capital, a Calgary-based stock plan administration services firm, for $1.1 billion. The renamed company, Shareworks by Morgan Stanley, has continued expanding services and adding positions locally.

Last June, the Royal Bank of Canada (RBC) unveiled plans to open a Calgary Innovation Hub in the city’s downtown and expects to create 300 tech jobs by the end of 2023.

Located in Bankers Hall, the centre opened in September. RBC said Monday it’s made a number of hires for the centre in areas involving artificial intelligence, cyber security, data and site reliability engineering.

Article content

“RBC chose Calgary for its newest innovation hub as it already had an established financial services sector, access to an existing talent pool … as well as a developed infrastructure,” Bernice Dunsby, a senior vice-president with RBC, said in a statement.

A study by Alberta Enterprise last year indicated there were 85 financial technology companies operating in the province, up from 28 in 2018.

Pictured is the Bankers Hall building on Stephen Avenue in Calgary on March 12, 2020.
Pictured is the Bankers Hall building on Stephen Avenue in Calgary on March 12, 2020. Photo by Azin Ghaffari/Postmedia

According to Calgary Economic Development (CED), more than 40 fintech firms are based in the city, such as online payments-processing company Helcim or Neo Financial, which doubled its staff last year to more than 400 and recently leased more than 100,000 square feet of downtown office space.

The broader financial services industry in Calgary has grown by more than 30 per cent in the past decade and is projected to expand by seven per cent by 2024, CED said.

Article content

Decisions by large companies like RBC and EY highlight the city’s expertise in financial services, which has grown out of working with the oilpatch, said Patrick Mattern, CED’s vice-president of business development.

“This validates that we’re a great place for finance and financial administration. Every one of these investments is an incremental benefit to us,” Mattern said.

“The prospects for fintech and financial services in this community are terrific.”

Meanwhile, other technology companies have expanded or moved into the city in the past year, including Amazon Web Services, information technology firm Infosys, and IT outsourcing services provider Mphasis.

A study last year by CBRE identified Calgary as one of the top 50 “Tech Talent” cities in North America, climbing six spots to 28 th place, although trailing Toronto, Ottawa and Vancouver.

Invest Alberta CEO Rick Christiaanse said the financial services industry has been identified as one of eight core sectors for the province as it looks to attract more businesses and jobs to Alberta.

“This is significant because we are building an ecosystem for tech and innovation … It’s just another piece in the puzzle,” Christiaanse said of the new EY financial centre.

“At the end of the day, it’s all about momentum.”

cvarcoe@postmedia.com

    Advertisement

    Comments

    Postmedia is committed to maintaining a lively but civil forum for discussion and encourage all readers to share their views on our articles. Comments may take up to an hour for moderation before appearing on the site. We ask you to keep your comments relevant and respectful. We have enabled email notifications—you will now receive an email if you receive a reply to your comment, there is an update to a comment thread you follow or if a user you follow comments. Visit our Community Guidelines for more information and details on how to adjust your email settings.

    Average life insurance rates are steady entering 2022

    Average life insurance rates are steady entering 2022

    Every month lifetime insurance plan premiums were being secure coming into the new 12 months, in accordance to Policygenius information.  (iStock)

    The everyday living insurance plan sector has held price ranges secure coming into 2022, according to Policygenius. Most non-people who smoke noticed smaller amount raises of less than 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} between December 2021 and January 2022, whilst people who smoke failed to see any improvements in their month to month rates.

    Average lifestyle insurance policies rates have stayed continuous regardless of a rise in mortality connected to the coronavirus pandemic. Demise reward payouts rose 15.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2020, in accordance to the American Council of Lifetime Insurers (ACLI). On the other hand, Policygenius facts indicates that individuals really don’t have to worry about mounting daily life insurance policy rates at this time.

    Continue to keep reading to find out a lot more about the normal existence insurance charge for every thirty day period, as nicely as how lifestyle insurance coverage rates are determined. If you’re contemplating taking out a daily life insurance plan plan, stop by Credible to get absolutely free existence coverage rates.

    IS Long term Daily life Coverage A Good Strategy FOR YOU?

    Typical price tag of everyday living insurance by age and gender

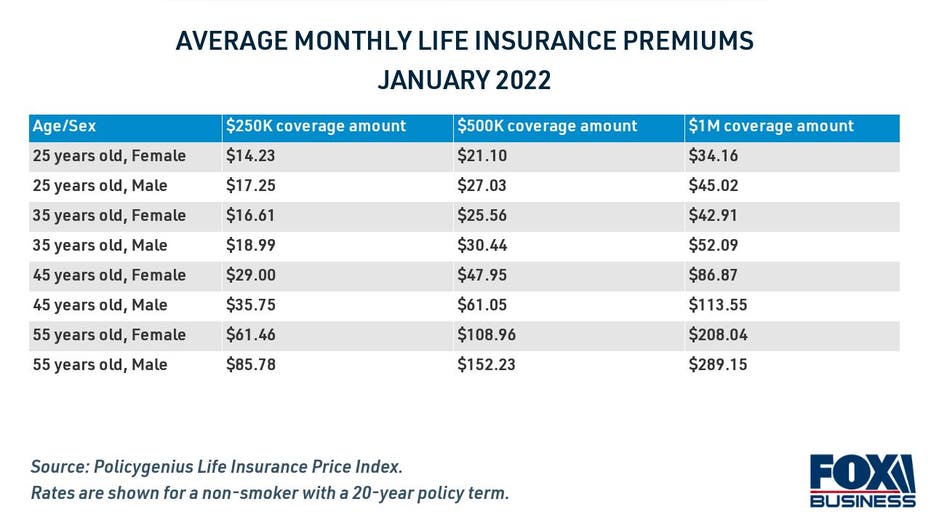
    Monthly life insurance policies rates remained regular entering the new year, according to Policygenius facts, with a negligible raise from December 2021 to January 2022.

    Everyday living insurance plan charges are least expensive for younger policyholders with small well being threats, while costs are inclined to rise with a policyholder’s age. For case in point, it fees $25.56 for each month to insure a balanced 35-12 months-outdated female with a 20-12 months time period existence insurance policies plan truly worth $500,000. That same policy would value $152.23 monthly for a 55-12 months-outdated gentleman in good health and fitness.

    Average monthly life insurance rates by age chart

    Regular lifestyle insurance coverage rates are also noticeably larger for people who smoke than they are for non-people who smoke. The plan used in the example above would expense $224.46 per thirty day period for a 45-year-outdated person who smokes, in contrast to just $61.05 for a non-smoker of the same age.

    No matter a person’s age or overall health score, however, existence insurance coverage premiums have stayed somewhat stable into 2022. If you are shopping for existence insurance, you can look through guidelines and see regular prices personalized to you on Credible. 

    Life Insurance plan Value BREAKDOWN BY AGE, Time period Size AND Plan Size

    How are everyday living coverage premiums calculated?

    The monthly expense of existence insurance policy relies upon on a policyholder’s lifetime expectancy. Lifetime insurance companies take a quantity of factors into account, these as age, sexual intercourse, wellness, health care heritage and even leisure hobbies. Individuals who are riskier to insure ought to anticipate to shell out increased regular monthly rates, whilst very low-chance policyholders will price tag considerably less to insure.

    To figure out your wellness danger, life insurers may involve you to undergo a health care examination. Health and fitness situations like high blood stress or being overweight can component into the general price of a lifestyle insurance policy.

    Rates are also dependent on the form of lifestyle insurance plan you have. Lengthier plan terms will have higher month-to-month prices, even though shorter policy conditions with reduced coverage amounts will be less expensive. 

    It’s commonly encouraged to purchase lifestyle insurance plan with a protection total equal to 10-15 periods your yearly personal cash flow, in accordance to Policygenius. The plan phrase must be lengthy enough to cover you into retirement age. 

    For case in point, a 45-yr-previous mom who earns $65,000 yearly may want to think about a 20-calendar year time period policy with a $1 million protection amount. That is about 15 occasions her once-a-year earnings, which may be necessary to choose treatment of dependents if she dies unexpectedly.

    On the other hand, a 35-calendar year-outdated married gentleman with no youngsters who earns $50,000 per yr could look at a 30-12 months lifetime insurance plan term with a protection sum of $500,000. That policy is lengthy plenty of to get him to retirement age, and the demise reward amount might be enough to protect bills for his spouse.

    When it comes to selecting a life insurance plan, you can find no one particular-measurement-fits-all approach. You’ll will need to contemplate the greatest plan for your lifestyle and money predicament. Get in contact with a monetary professional at Credible to determine your life coverage demands. 

    Getting Everyday living Insurance policy Though You are Youthful AND Healthy CAN Preserve YOU Hundreds

    Have a finance-connected dilemma, but will not know who to ask? E mail The Credible Funds Pro at moneyexpert@credible.com and your issue may possibly be answered by Credible in our Funds Pro column.

    UK Government Holds Breath as It Awaits ‘Partygate’ Report | Business News

    UK Government Holds Breath as It Awaits ‘Partygate’ Report | Business News

    By JILL LAWLESS, Related Push

    LONDON (AP) — Prime Minister Boris Johnson is bracing for the conclusions of an investigation into allegations of lockdown-breaching functions, a document that could help him conclusion months of scandal and discontent, or bring his time in business to an abrupt shut.

    Senior civil servant Sue Gray could flip in her report to the govt as shortly as Wednesday. Johnson’s office has promised to publish its findings, and the primary minister will address Parliament about it before long just after.

    Gray’s office wouldn’t comment on timing, and Overseas Secretary Liz Truss claimed the Conservative governing administration hadn’t still gained the report Wednesday early morning.

    “I be expecting we will not have much extended to wait around,” she told the BBC.

    Political Cartoons on Environment Leaders

    Political Cartoons

    Truss explained she couldn’t warranty the authorities would publish the entire report, stating there could be “security troubles that suggest areas of it are problematic to publish. But we will completely publish the results of the report.”

    Allegations that the primary minister and his staff members flouted constraints imposed on the state to control the unfold of the coronavirus have triggered public anger, led some Conservative lawmakers to simply call for Johnson’s resignation and induced extreme infighting inside the governing get together.

    Wednesday’s headlines offered a lot more terrible information for Johnson, whose recognition in feeling polls has plunged amid the scandal. The Guardian’s front-site headline spoke of “PM’s peril,” when the left-leaning Day by day Mirror reported bluntly: “Number’s up, PM.” The correct-of-center Day-to-day Mail differed, declaring Britain: “A country that has misplaced all feeling of proportion.”

    Johnson has urged his critics to wait for Gray’s conclusions, but his “wait and see” defense weakened Tuesday when police explained they had opened a legal investigation into some of the gatherings.

    London’s Metropolitan Law enforcement drive explained “a variety of events” at Johnson’s Downing Avenue business office and other governing administration buildings met the force’s standards for investigating the “most really serious and flagrant” breaches of coronavirus policies.

    Grey is investigating claims that government staff members held late-evening soirees, boozy parties and “wine time Fridays” although Britain was under coronavirus limitations in 2020 and 2021.

    The “partygate” allegations have infuriated many in Britain, who were being barred from assembly with buddies and family for months in 2020 and 2021 to curb the distribute of COVID-19. Tens of hundreds of persons were fined by police for breaking the principles.

    Johnson and his allies have tried out, without the need of significantly accomplishment, to calm a scandal that is consuming authorities energies that could be greater expended confronting the worldwide disaster above Russia’s military services construct-up in close proximity to Ukraine and a far-from-finished coronavirus pandemic.

    Johnson has apologized for attending 1 party, a “bring your have booze” gathering in the back garden of his Downing Road places of work in May 2020, but claimed he had regarded the bash a perform accumulating that fell within just the principles

    His place of work and supporters have also defended a June 2020 surprise birthday celebration for the prime minister within Downing Road.

    Loyal lawmaker Conor Burns said Johnson failed to know about the gathering in advance.

    “It was not a premeditated, organized party … He was, in a sense, ambushed with a cake,” Burns explained to Channel 4 News.

    Copyright 2022 The Related Press. All rights reserved. This material could not be released, broadcast, rewritten or redistributed.

    Stock futures add to losses ahead of Fed decision

    Stock futures add to losses ahead of Fed decision

    Stock futures opened decreased Tuesday evening immediately after one more volatile session on Wall Street, as investors seemed to the Federal Reserve’s most up-to-date financial plan conference and press conference to clear away some uncertainty on the outlook for financial coverage. 

    Contracts on the S&P 500 sank. The index shut reduce for a fifth time in 6 classes on Tuesday, in a session which observed shares rebound off their lows but fail to break into beneficial territory, as experienced been the circumstance through Monday’s rollercoaster investing day. Technology stocks lagged, and the Nasdaq Composite dropped much more than 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to sink even more into a correction.

    The advertising strain for some major technology names ongoing into the submit-market session, as Microsoft (MSFT) get rid of extra than 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} even after offering better-than-expected fiscal next-quarter income and earnings. Shares of chipmaker Texas Instruments (TXN) rose, having said that, right after supplying a greater-than-expected outlook for latest-quarter gross sales regardless of concerns about ongoing semiconductor shortages. Corporations like Tesla (TSLA) and Intel (INTC) are poised to report results on Wednesday. 

    For marketplaces, the Federal Reserve’s most recent financial plan assertion and press conference from Fed Chair Jerome Powell on Wednesday will be the banner occasion. Traders have been pricing in a additional aggressively hawkish central bank as the Fed functions to rein in inflation presently working at a four-10 years significant. Above the previous few months, the Fed has signaled via its December meeting minutes and in public remarks that it will most likely begin raising fascination prices from latest in close proximity to-zero ranges in March. It is also thinking of starting to roll property off its balance sheet right after amassing some $9 trillion in its bond portfolio. 

    “If you think about what is took place in the markets, it suggests the degree of sensitivity market individuals have to what is going to be the new level atmosphere and the new liquidity atmosphere,” David Bailin, Citi chief financial commitment officer and head of Citi world wide wealth management, instructed Yahoo Finance Stay on Tuesday.

    “The Fed created a key reversal about five months ago when it explained that it was each heading to raise rates and also take into consideration quantitative tightening, which proficiently indicates that you and I are going to have to finance the financial debt that is required issued by the Treasury alternatively of the Fed,” he added. “So with all of that, I think they are going to appear at what happened [in markets] and they are heading to say, our aim in this article is not to shut the economic climate and to make factors slow. The target right here is to sign their willingness to combat inflation to the extent that they can.”

    Other strategists agreed that the Fed’s modern, much more hawkish tilt has remaining traders so considerably with more inquiries than answers. Even though the Fed’s December projections proposed policymakers ended up likely to elevate rates three situations this yr, several industry members have now priced in anticipations for four hikes, although others have prompt as several as five or 6 hikes may be on the table specified the latest inflationary backdrop. And however Powell has recommended the Fed would continue thinking about quantitative tightening, the central financial institution has but to supply a concrete timeline for the get started of this course of action. 

    “We are in a interval of heightened uncertainty,” John Bellows, Western Asset portfolio supervisor, instructed Yahoo Finance on Tuesday. “The market’s hoping to figure out the place that pivot finishes, what sooner or later anchors Fed coverage going. forward and it is still trying to calibrate effectively the scale and magnitude of that Fed pivot.” 

    6:15 p.m. ET Tuesday: Inventory futures add to before losses

    Here is exactly where futures commenced buying and selling Tuesday evening:

    • S&P 500 futures (ES=F): -31 details (-.71{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,318.00

    • Dow futures (YM=F): -164 points (-.48{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 34,021.00

    • Nasdaq futures (NQ=F): -156.50 points (-1.11{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 13,984.25

    Traders work on the floor of the New York Stock Exchange at the opening bell January 25, 2022. - Wall Street stocks fell early January 25 following a deluge of mostly solid corporate earnings but a lower global growth forecast from the IMF. (Photo by TIMOTHY A. CLARY / AFP) (Photo by TIMOTHY A. CLARY/AFP via Getty Images)

    Traders work on the flooring of the New York Stock Exchange at the opening bell January 25, 2022. – Wall Avenue stocks fell early January 25 adhering to a deluge of largely stable corporate earnings but a lower world-wide development forecast from the IMF. (Photograph by TIMOTHY A. CLARY / AFP) (Picture by TIMOTHY A. CLARY/AFP via Getty Images)

    Emily McCormick is a reporter for Yahoo Finance. Observe her on Twitter

    Study the newest economic and company news from Yahoo Finance

    Follow Yahoo Finance on Twitter, Fb, Instagram, Flipboard, LinkedIn, YouTube, and reddit

    insurance: Four myths about personal finance fundamentals that can be dangerous for your money

    insurance: Four myths about personal finance fundamentals that can be dangerous for your money
    Why can not I obtain insurance policy now, argued my 65-yr-previous friend. It is an unfair world for senior citizens, he lamented. They won’t give you household loans, possibly. Well being coverage is expensive when I need to have it most. Luckily my funds is safe in govt deposits. If force will come to shove, I will do a reverse house loan, he declared. Hold out, I just about screamed. Those people are just way too a lot of misconceptions.

    Insurance policies is protection, not for your daily life and your limbs, but for your prosperity. When you start off to build wealth early in lifestyle, you only have the human asset to depend on. You hope to be employed, receive an money and establish some belongings for by yourself. If you have a family members that is dependent on your earnings, their lives also depend on the human asset.

    Insurance policy is your software to make certain that the prosperity you approach to develop is there, for you and your family members, should really anything at all happen to the human asset that could impair its capacity to earn an revenue. Your insurance policy proceeds will kick in and make up for you, if there is a reduction of existence or limb. That is why the calculation of how considerably insurance policy you want considers the income, the devote and the price savings. You pick the goal you want to set for your wealth.

    That is why insurance policies is necessary earlier in everyday living. To act like a shield that guards your prosperity. It is not an expenditure, even if it is marketed as such. It progressively receives high priced to obtain insurance if you want it to also operate as an financial investment. Time period insurance coverage is the least expensive due to the fact it serves the main intent of presenting a lump sum funding to your dependents if you had been to go absent. If you feel you ought to offer for your child’s larger education, you have the possibility of evaluating a time period insurance coverage and an expense product or service independently prior to bundling the two with each other. We digress.

    My good friend will not will need insurance policies when he is 65 simply because he has pretty much arrived at the close of his earning phase. Ideally, he would have plenty of assets saved for his retirement and previous age. It would be the two pricey and superfluous to consider and purchase an additional include of the identical price. My good friend need to know that he needs no insurance coverage if there is ample accrued prosperity. That he is getting older and is a higher threat to the coverage enterprise is the insurer’s aspect of the tale.

    That he finds it high-priced to obtain health insurance policy is an extension of that story. We are living by that transition in India when health and fitness care is overtaken by company passions and insurance coverage companies. Therapy solutions are needlessly elaborate and high priced to feed the profits targets of support suppliers. It is hard to locate an economical health insurance selection for an elder who also suffers pre-present medical conditions. My good friend raises a fair issue, but solutions have to await an additional column for the area that question needs.

    Now to the household mortgage. A financial loan is only a facility to use tomorrow’s income these days. It is always an highly-priced choice to training. The curiosity on the loan is the price to spend for this facility. A mortgage is handy when there is more than enough profits to pay an installment but not adequate wealth to purchase the asset nowadays. Most would not have been capable to personal a home if not for this facility, even if it will come with a price. The lender will care mostly about the worth of the asset getting funded and the skill of the borrower to repay.

    My pal at 65 does not require this highly-priced alternative. He has plenty of funds in his retirement corpus to be in a position to buy whichever he demands. If he have been to use his belongings as collateral, he could still get a loan. But he would have to repay it from his financial investment cash flow, now that he is retired. The math will not operate out. His belongings may earn a return that is reduce than the interest level on the bank loan. It won’t make feeling to get a mortgage his focus should be on optimizing the return on his investments and property and taking on an earnings and spending orientation, fairly than hoping to create new assets.

    That brings us to his investments. There is practically nothing wrong with maintaining one’s revenue with the federal government. Lending to the federal government is the technically proper detail to say. Safe and sound, as my friend appreciates. But that is why the govt will get away with having to pay the lowest fee of fascination. In the lending sector, the charge at which the authorities borrows is the foundation charge. No one particular can borrow less costly than that. There is no questioning the skill of the government to honor its obligation to shell out the desire and return the principal. It can unilaterally increase taxes borrow overseas and in the worst scenario print dollars. But that is the borrower’s aspect of the tale.

    As a loan company, my pal ought to talk to irrespective of whether he is staying as well conservative settling for a lower fee of return. The answer is not to swing wildly to lend to the neighborhood finance enterprise that is presenting an eye popping price. Many reasonable choices exist in the middle. Controlling the retirement corpus needs a strategic method to allocating how substantially will be invested where by. Some quantities for development in fairness property, some in top quality income assets that supply a great interest, some for security and protection, and some for straightforward withdrawal and use. A blend that keeps pitfalls small and returns optimum. Blindly deciding on one particular form of investment is clearly suboptimal for possibility and return.

    Now to the last bombshell about reverse home loan. The product is basic. Rather of getting a personal loan and creating an asset, you sell the asset in progress to get pleasure from an revenue stream. The loan company buys your household for a cost currently, but agrees to pay out you a monthly installment for several several years, at the finish of which they choose around the dwelling. You keep on to live in the dwelling, while earning an earnings. Reverse house loan is a distress alternative not a typical 1. You give up the appreciation in the benefit of your house, in return for an cash flow you desperately need to have. If you have only a household as an asset and no other wealth or cash flow, reverse mortgage is your last choice. Don’t deal with it like a frequent alternative for profits.

    All these are pretty straightforward and much recurring essential ideas. But it is scary to see that a lot of maintain these notions with great conviction.

    (The author is Chairperson, Centre for Financial commitment Instruction and Mastering.)