How MPs’ second jobs fail to gain them experience of the UK economy

How MPs’ second jobs fail to gain them experience of the UK economy

Almost three times more British MPs declared earnings from financial services companies than from manufacturing, FT analysis has revealed — one of many imbalances that may complicate Tory efforts to defend legislators’ right to pursue part-time careers.

MPs’ right to hold second jobs, which spurred a political row this month, has been defended by Jacob Rees-Mogg, leader of the House of Commons. He told Parliament that it was “a historic strength . . . that MPs should have a wider focus than the Westminster bubble”.

The government has now proposed changes to the rules to bar MPs from doing too many hours of outside work or acting as political consultants — but to preserve their right to have other income. A report on how the new rules might operate is set to be published by a cross-party committee next week.

In declarations made since the last election in 2019, some of which relate to the year before the vote, 37 MPs have registered income of various kinds from financial services companies — the largest such bloc of corporate income. The sector accounts for 8.1 per cent of UK GDP.

These include longstanding contractual relationships as well as one-off payments — such as the £160,000 paid to Theresa May, the former prime minister, by JPMorgan Chase in April 2020. The sum was an “advance payment” for two speeches that were postponed by the pandemic; she has yet to give one of them.

By contrast, just 13 MPs have received income from manufacturers, which contribute 9.9 per cent of GDP. Just 8 MPs have financial links to retailers, which contribute 4.9 per cent. Public relations or lobbying companies have employed 30 MPs.

Hannah White, deputy director of the Institute for Government who previously ran the independent Committee on Standards in Public Life, said: “If the point of second jobs is to ensure that MPs can bring real life experience to parliament, then it is deeply problematic that the experience MPs are actually getting is so unrepresentative of the UK economy”.

This has become a partisan issue because of an imbalance in who holds these posts: the positions listed above were held by 68 Tory MPs and just 18 legislators from all the other parties combined.

The issue was also brought to public attention by the actions of Owen Paterson, a Conservative former minister, who was found by a bipartisan committee to have “repeatedly used his position as a member to promote the companies by whom he was paid” in a manner not permitted by the rules. The government whipped its MPs to save him from proposed sanctions — only to be forced to retreat in the face of a public backlash.

Some forms of outside income are more bipartisan: 155 MPs received additional funds from filling in surveys for pollsters — receiving between £30 and £275 for each survey, which typically takes less than an hour.

Meanwhile 105 MPs declared earnings from the media, largely for writing articles (including for the FT Group) or TV appearances. Another 63 have held paid roles in local government. An additional 23 have declared income from book publishing.

Bar chart of number of MPs declaring income from each industry since 2019 v share of the economy showing MPs' corporate experiences do not represent economy

Westminster MPs are allowed to lobby ministers on behalf of companies that have given them money or gifts, and to advocate for them in debates so long as they do not “initiate” conversations or debates. Clients must also not “exclusively” benefit from anything they propose. They also must not use parliamentary facilities for business.

These rules are weaker than in the UK’s devolved parliaments, and markedly weaker than those in the US House of Representatives — where there is a cap on some kinds of earned income and outright bans on others.

Members of the House of Representatives are banned from practising law to prevent them from having conflicting public and private duties.

In the UK, lawyer-MPs are allowed to practise and are not required to disclose their ultimate clients. The 30 MPs declaring income from law — mostly as barristers — include some of Parliament’s biggest earners, such as Sir Geoffrey Cox, the former attorney-general. Cox, whose large volume of outside work helped fuel the outrage over MPs’ second jobs, told the FT that barristers were hired “to advise and represent . . . on a specific issue or in litigation”, not for general representation.

Lawyers are heavily represented in parliament, but together with accountancy, from which 7 MPs declared earnings, the legal sector contributes just 2.7 per cent of GDP.

In the US, members of the House are banned from accepting most gifts — with a particular prohibition on gifts from lobbyists or anyone who also engages a lobbyist. No such bar exists in the UK, where 26 MPs have registered gifts from betting companies and their lobbying body. A total of 111 MPs have taken gifts or hospitality from sports businesses.

The largest gift went to Tracey Crouch, who has just completed a review of the regulation of English football on behalf of the UK government. She declared a £4,560 hospitality package from the Football Association, the sport’s English body, to watch a football match.

“It turns out to be only a small set of businesses that are most interested in paying and entertaining MPs,” said Duncan Hames, a former MP and director of policy at Transparency International UK. “That these companies are often heavily regulated suggests more interest in their parliamentary role than prior experience they might bring.”

MPs are allowed to hold up to £70,000 of shares in a company without registering the holding, so long as the stake constitutes less than 15 per cent of the equity. They are not required to list participation in any funds. In the US, members of the House of Representatives must declare shareholdings over $1,000, as well as any other investments.

One person involved in administering the current UK system told the FT they were “very sceptical” about comparisons to the US — “not least because of [US politicians’] need to raise campaign finance”. This, they said, led to US politicians being “more in hock to big business”.

Campaigners are calling for much more sweeping reforms than are currently being considered. Hames said: “There are still too many blind spots for mischief to hide . . . It could save a lot of trouble if, like in many other workplaces, those wanting to take on second jobs or other contractual relationships first sought authorisation from an independent body, just as former ministers are expected to do.”
Couple launches farm store in Middlefield | Business News

Couple launches farm store in Middlefield | Business News

Shannon Sears is cultivating something new on her family’s Middlefield farm.

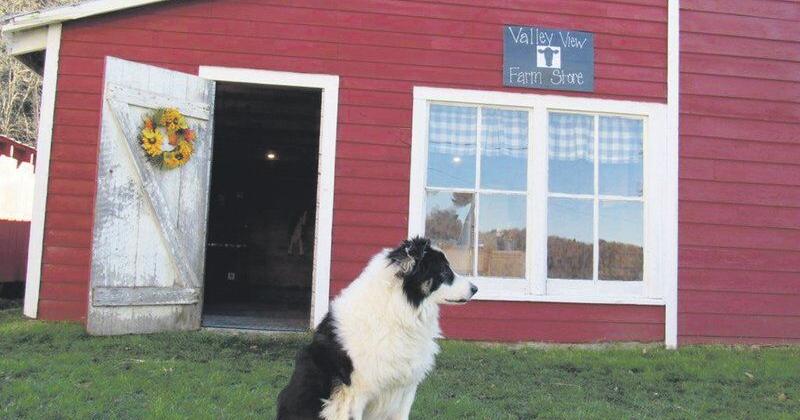
Sears, 23, together with her boyfriend, Robert Dorrough, launched Valley View Farm Store at 3286 County Highway 35 in early November. The store began, Sears said, as a way to expand offerings to locals while supplementing the farm.

“My parents first started farming in Jefferson, and I was 2 when they moved, so I pretty much grew up on the farm,” she said. “It was my parents’, and they bought it in 2000, and now me and my boyfriend are in the process of taking it over.

“(The farm store) is all new,” Sears continued. “The store got started because, in dairy farming, it’s very tough to have a strong revenue stream, especially in Middlefield — there’s no stoplight and there’s no store, the closest one is in Cooperstown — so we wanted to give an opportunity for the local community to be able to have the convenience and be able to get it right up the road at the farm, and we offer only local products.”

The site, Sears said, showcases typical farm store fare along with some surprises.

“Our milk is from Lentsville Farm in Cherry Valley, and they have a Jersey farm there and cheese curds and yogurt that we have,” she said. “And the other (milk carried) is King Brothers, out of Saratoga.

“We have homegrown beef and pork, with different cuts available — hamburger, steaks, sausage, bacon and that’s all grown on the farm — then we have a wide variety of baked goods,” Sears continued, listing products from Brimstone Bakery in Sharon Springs and whoopie pies and assorted muffins from Udderly Sweet. “And we have, from MT Acres in Schenevus, all our health and beauty products, (such as) goat milk soap, aromatherapy, sugar scrubs, lotion, lip balm and grain-free dog treats,” she said.

Sears said, though the store is open for self-service daily from 9 a.m. to 5 p.m., she’s committed to making face-to-face customer connections.

“It’s different, our farm store, because it is manned (during weekend hours),” she said. “We think it’s important to have conversations with our customers and find out what products they like and what products they’re looking for next; it just gives you an opportunity to actually communicate with your consumer and otherwise, you miss out on that.”

Customers, Sears said, are appreciating the venture. Though she said shoppers are primarily “locals,” Sears said that, in summer, “the (Cooperstown) tourist population will probably come over.”

“Our grand opening (in early November) was quite a few customers and people from the community that showed up, so that was good,” she said. “It’s definitely a start. They all really love that the store is right down the road. When I was handing out flyers before the opening, I was talking to one of my neighbors, and she was like, ‘Thank God (you’re opening), because I need a gallon of milk and thought I had to go the store.’ So, the main feedback that we’ve gotten is, it’s very convenient and they love the setup and that we offer products that are some essential household products, and different stuff like the health and beauty.”

And, Sears said, the farm store accepts cash, cards, checks, Venmo, PayPal and other electronic payment forms.

Sears said she’s planning to build on Valley View’s momentum in time for the holidays.

“We’re going to be working on Christmas baskets,” she said. “Those will be deals where the health and beauty can be a basket, with one soap, one sugar scrub, one lip balm at a set price, but it will make an easy gift. And we’ll have a meat special; we’re going to put a steak and some hamburger together.

“(Holiday baskets) are a good seller at a lot of farm stores I’ve been to, but also a thing for when you don’t know what to get that one family member,” Sears continued. “So, it can help check that person off and you’re helping the community and a small business.”

Valley View will host a Dec. 18 Christmas event, Sears said, featuring product specials and photos with Santa and farm animals.

Sears said she plans, too, to expand into farm-fresh to-go options.

“We just opened,” she said, “but we’re currently working with the health department to offer grab ‘n’ go meals — sandwiches, coffee, that kind of stuff.

“I set up our one-year goal and our five-year plan,” Sears continued, “and in five years, we’d like to set up a small cafe in the back part of the store and make it so you can see a viewing window of the cow pasture right there. (People will be able to) sit, have breakfast and watch the cows grazing and really bring that farm-to-table aspect.”

For more information, find “Valley View Farm” on Facebook or follow @valviewfarm on Instagram.

5 Things I’ve Learned in 18 Months of Personal Finance Reporting

5 Things I’ve Learned in 18 Months of Personal Finance Reporting

We want to help you make more informed decisions. Some links on this page — clearly marked — may take you to a partner website and may result in us earning a referral commission. For more information, see How We Make Money.

There’s no shortage of great personal finance advice out there. The problem is figuring out whether or not it applies to you.

“Personal finance is personal before it’s financial,” Talaat McNeely told me during an interview earlier this year. McNeely is the co-founder of the site His and Her Money, which he runs with his wife, Tai. I’ve found this idea to be a helpful way to think about your finances and life in general. 

There is no single tip or money hack that will instantly change your life. But some principles and concepts can put you on the path to achieving your goals. You’ll just need to figure out a way to apply them to your unique situation.

Here are the most impactful lessons I’ve learned during my time as a personal finance reporter, and how I’ve applied them to my life. These tools and concepts helped my wife and me set aside over $20,000 to pay off student loans (once interest resumes next year), build our emergency fund, and feel less stressed about our financial future.

A good budget should manage not only your expenses but also your emotional relationship with money.

5 Things I Learned as a Personal Finance Reporter

Since launching NextAdvisor in the middle of the pandemic, our biggest priority has been sharing actionable advice readers can use right away in their daily lives. In the course of fulfilling this mission, we’ve learned quite a lot about ourselves.

Here are four personal finance concepts my wife and I have incorporated into our everyday approach to finances, plus one strategy we plan to use when we are ready to buy a house. 

1. Budgeting Is About More Than Just Managing Money

For years my budget was a homemade spreadsheet I updated sporadically in hopes of becoming a young Warren Buffet. It rarely worked as well as I wanted. In theory, my budget should have turned me into the ultimate saver. But what frequently happened was: I’d update it once a month only to find out I’d overspent on eating out. And it wasn’t helping me feel any less stressed about money.

One of the first stories I wrote for NextAdvisor was about creating a budget, and that is where I discovered zero-based budgeting (ZBB). Once my wife and I started using the zero-based budgeting method, we didn’t just start saving more but also began to feel less worried about money. In my experience, a good budget should manage not only your expenses but also your emotional relationship with money.

Piper after his surgery. He hated the cone of shame, so we put him in a baby onesie.Jason Stauffer/Getty Images

With ZBB, every dollar that comes in is given a purpose. We assign funds to pay for rent, cellphone, and other expenses. But we also assign money for more than just our current bills. This strategy helped us pay off student loans sooner than we expected. 

ZBB also helped us build an emergency fund for the first time in my life. When the cat needed a $2,000 emergency surgery this past summer, we already had that money set aside. If we hadn’t had an emergency fund, this surprise cost would have been a setback for other goals. Since this money was already set aside, it didn’t negatively affect our other financial obligations. 

We’ve been using the zero-based budgeting app You Need a Budget (YNAB) for almost a year and a half, and we absolutely love it. This app has effectively turned our credit cards into debit cards, which is important because I’m a full-blown travel credit card junkie. When I enter a credit card purchase into the YNAB app, the funds are immediately assigned to pay off that card. So even though I won’t actually pay the credit card bill for up to 30 days, the budget tells me that money is no longer available to spend. 

How to Find a Budgeting Strategy That Works for You

If you want to try zero-based budgeting for yourself, I think YNAB is a great place to start. It’s important to note that it’s not free. But there are plenty of free or cheap ZBB templates available. And ZBB isn’t the only budgeting method that works. As you explore different approaches to budgeting, zero in on why you want a budget in the first place. A budget can help reduce financial stress, and get you closer to your goals without turning you into Ebenezer Scrooge.

2. Prioritize Income Over Expenses

There is a limited number of Starbucks lattes you can cut from your budget—but an unlimited number of ways to make money.

I’ve talked with people who’ve paid off their mortgage in under six years and conquered six-figure sums of debt. One common thread from these success stories is they find ways to make more money. They start side hustles, businesses, or find better paying jobs. Having a budget that works for you is still the first step. But if you don’t net enough income after expenses, then saving for anything else will be a struggle. 

My wife and I are expecting our first child in 2022, and for us, it’s as important as ever to increase our household income. My wife is considering a move from freelance to full-time work, which would provide a more stable income. From there, we might explore other freelance or side hustle opportunities.

How to Increase Your Income

Starting a side hustle might not be as challenging as you think. Chances are you already have interests and talents you could use or develop to boost your income. One great bit of advice Marc Russell shared with me was to repurpose the skills from your current job into a side hustle. Russell is the creator of the personal finance Instagram account Betterwallet. “As long as there’s no conflict of interest with your current job, you can go off and create your own thing on the side and get paid for it,” he said in a previous NextAdvisor story.

3. Negotiating Can Be As Simple As Asking

The thought of negotiating has always terrified me. My idea of a good negotiator has always been a former Navy SEAL or pro athlete, someone who’s in control, confident, and used to winning. In reality, negotiating is often as simple as asking for what you want. Crafting a good offer sometimes includes offering something of value in return.  

I’ve never asked for much of anything, much less a discount on my housing costs. Recently, I was looking to move into a new apartment on a short-term 3-month lease. I emailed my current property managers to ask about two units downstairs I knew were vacant. I asked if either unit would be available for a short-term lease and I gave them valuable information, reminding them the one apartment had been vacant for over a year. Then I offered to pay all three months upfront if they would reduce the rent. 

Now I’m paying over $150 less a month and my landlord has $4,000 more than before I asked for what I wanted.

How to Negotiate More Frequently

Any negotiation is better than no negotiation. Find an approach that could help you ease into it and be more comfortable. Try making an indirect request and see if that’s easier for you. Instead of coming out and saying you want a pay raise, ask your manager something along the lines of, “what have people in my position done in the past to help increase their pay?” At the very least, it gets the conversation started. You’ll never get something if you don’t ask for it in the first place.

4. Be Patient and Consistent. Change Takes Time

Changing the trajectory of your finances takes time. 

That can be disheartening to read. Everywhere you look it’s one headline after another highlighting the youngest millionaire or someone who went from insurmountable debt to financial freedom in less time than it took to read their bestselling book.

Life is a marathon, but we only see the last few hundred yards of other people’s victories. Almost all financial achievements are preceded by a long period of learning and building momentum. Whether it’s learning to code before becoming a tech entrepreneur or saving up for a down payment on a house, meaningful changes take time. 

If you can only take small steps, just keep taking small steps. It can be tough seeing how fast everyone else seems to be moving. What’s not obvious is how much time it took them to develop the speed you’re seeing. Understanding how much time is involved in making meaningful improvements is the foundation for positive financial decisions. 

How to Use Time to Your Advantage

The best way to get time working for you is to start now. Start small, start slow, start without it being perfect. Then your job is to continue what you started, however slowly you’d like, and to learn and make adjustments along the way. 

5. Prospective homeowners: Ask about a zero-cost mortgage 

While reporting on mortgages, the most overlooked strategy I’ve come across for reducing your mortgage cost is to ask for lender credits in exchange for a higher interest rate. In this situation, the credits would be used to cover the loan fee portion of your closing costs. A zero-cost mortgage means you’d be paying a lot less out of pocket every time you buy a home or refinance.

Here’s why I plan to get a zero-cost loan:

  • By reducing the upfront cost I’ll have more liquidity. 
  • What I would have spent on upfront closing costs can be used to pay down the mortgage balance, invest in a retirement fund, or set it aside for unplanned home repairs. 
  • If I move or refinance a combined six times in the next 30 years, I’d pay closing costs (3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}-6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the loan) six times. So for me, taking the higher interest rate with a zero-cost loan is cheaper because our future plans aren’t set in stone. 

When researching lenders, ask if they have a zero-cost loan option. Compare your options and see which one makes the most sense for you. In my experience, the zero-cost mortgage is not as common or widely advertised. Also, the zero-cost mortgage is different from a no-closing-cost mortgage. A no-closing cost mortgage is when the closing costs are rolled into the total loan balance. 

How to Pick the Right Mortgage for You

Any time you take out a home loan, you’ll want to be sure that you understand all your options. Ask a lot of questions and work with a professional who will help you understand your options, rather than just someone who gives you “the answer.” In my experience, most borrowers are overly concerned with the mortgage rate and overlook the closing costs. Interest and closing costs can be easy to miss because they might be added to your loan balance, but you’re still paying even if you’re not paying out of pocket when you close.

Bottom Line

The above practices have given me the patience I needed to establish financial habits that will last a lifetime. They worked for me. But it doesn’t mean you should take the same approach. If nothing else, use these concepts to start thinking about how you can approach your finances differently or to start asking questions you hadn’t considered before.For more information, check out this library of resources on NextAdvisor’s savings page.

S&P 500, Nasdaq rise after weekly jobless claims reach 52-year low, PCE inflation jumps

S&P 500, Nasdaq rise after weekly jobless claims reach 52-year low, PCE inflation jumps

The S&P 500 and Nasdaq gained on Wednesday as technology stocks recovered some recent losses, with investors digesting a deluge of economic data before a holiday market closure. 

Investors considered new Labor Department data showing weekly initial jobless claims fell far more than expected to their lowest level since November 1969, underscoring current tight labor market conditions. However, a separate print showed personal consumption expenditures (PCE) accelerated to rise by 5.0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in October, or the fastest rate since 1990, to add to recent signs of elevated price pressures. 

The 10-year Treasury yield rose to near 1.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} amid these further signs of a firming economic recovery and persistently hot inflation data. 

Rising interest rates have coincided with a selloff in tech and growth stocks this week, with the Nasdaq dropping 0.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on Tuesday after Monday’s more than 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} decline. 

“Initially, the markets were happy with the FOMC decision [for Fed Chair Jerome Powell’s renomination] in the sense that it was sort of a continuity play to some degree. But then rates started to rise, and a lot of folks read rising rates as negative for big-cap tech,” Stuart Kaiser, UBS head of equity derivatives research, told Yahoo Finance Live. “So I think the tradeoff we’re going to have here is that, tech has been market leadership — it’s obviously a strong earnings growth and free cash flow engine for U.S. equities — but if you believe it’s going to come under pressure from higher yields, then you end up with kind of a difficult Catch-22.”

According to other analysts, the market action this week — with a renewed rotation away from technology and growth stocks in the face of rising rates — could presage the investing environment for next year. 

“[Tuesday] might be an example of what we see more of next year as the Fed moves into a mode of withdrawing liquidity from the markets and ending these pandemic-era policies, perhaps with rate hikes at the end of the year,” Jeffrey Kleintop, Charles Schwab chief global investment strategist, told Yahoo Finance Live. “And that means higher-valuation stocks, well, they tend to not do as well in environments of rising interest rates and tighter financial conditions.” 

“So you may want to look to be in those sectors that are maybe trading closer to their average valuations, looking to leadership like financials, energy,” he added. “The only caveat to that is when we see these upticks in COVID cases globally, it tends to favor those lockdown defensives like technology.” 

4:09 p.m. ET: Tech stocks recover, S&P 500 and Nasdaq end higher after jobless claims reach 52-year low, PCE inflation jumps

Here were the main moves in markets as of 4:09 p.m. ET:

  • S&P 500 (^GSPC): +10.76 (+0.23{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,701.46

  • Dow (^DJI): -9.42 (-0.03{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,804.38

  • Nasdaq (^IXIC): +70.09 (+0.44{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 15,845.23

  • Crude (CL=F): -$0.25 (-0.32{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $78.25 a barrel

  • Gold (GC=F): +$4.20 (+0.24{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,788.00 per ounce

  • 10-year Treasury (^TNX): -2.2 bps to yield 1.6450{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

3:50 p.m. ET: FOMC minutes suggest central bank focused on ‘flexibility’ for policy path forward

The Federal Open Market Committee’s November meeting minutes released Wednesday afternoon suggested monetary policymakers were committed to remaining flexible in their policy path forward and would adjust their asset-purchase tapering as needed as new economic data rolled in. The central bank had announced in early November that it was going to begin reducing its asset purchases at a rate of $15 billion per month in each of November and December, and then reassess the size of the reductions going forward. 

“The Committee was prepared to adjust the pace of purchases if warranted by changes in the economic outlook and agreed that the post-meeting statement should say so,” the minutes said. “Members agreed that the addition of this language would acknowledge the importance of maintaining flexibility to adjust the stance of policy as appropriate in response to changes in the Committee’s outlook for the labor market and inflation.”

The November FOMC meeting did not come with an updated “dot plot” of individual members’ projections on interest rates and other economic data. However, the minutes Wednesday noted that the members’ “near-term outlook for inflation was revised up, as consumer food and energy prices had risen faster than expected and production bottlenecks and recent wage gains were seen as putting somewhat greater upward pressure on prices than had been anticipated.” 

12:02 p.m. ET: New home sales unexpectedly rose for a back-to-back month in October 

New home sales rose by 0.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in October to extend gain after a 7.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} increase in September, Commerce Department data showed on Wednesday. Consensus economists were looking for an unchanged reading last month, according to Bloomberg consensus data. 

“The trend is picking up after a steep drop in the first half of the year, and the recent rising trend in mortgage applications points to clear increases over the next few months, with sales hitting 850K or so by January,” Ian Shepherdson, chief economist at Pantheon Macroeconomics, wrote in a note Wednesday. “At the same time, inventory continues to rise rapidly, in contrast to the existing homes market. Supply in the three months October stood at 6.3 months, a bit higher than before COVID. As a result the surge in prices now looks very overcooked, and we expect a clear slowing in the first half of next year.”

10:15 a.m. ET: Personal spending and income each top estimates in October despite 

Personal spending increased in October even amid elevated prices, pointing to continued strength in the consumer despite lingering inflation. 

Personal spending, which comprises about two-thirds of U.S. economic activity, rose by 1.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in October compared to September, the Bureau of Economic Analysis said Wednesday. This was faster than the 0.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rate posted for September and the 1.0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} monthly increase expected, according to Bloomberg data. Real personal spending also accelerated during the month and topped estimates, rising by 0.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from September’s 0.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} increase. 

Personal income, meanwhile, rebounded after dropping last month, rising by 0.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} versus the 0.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} increase anticipated. Income had fallen by 1.0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} month-on-month in September, in part coming after federal enhanced unemployment benefits were phased out at the national level after Labor Day. 

10:10 a.m. ET: Personal consumption expenditures rose at fastest pace since 1990 

A new print on inflation rose at its fastest rate in more than three decades in October, adding to a bevy of data pointing to persistent inflationary pressures. 

Personal consumption expenditures rose by 5.0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in October over last year, accelerating from September’s 4.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rise. The latest monthly print marked the fastest annual growth rate since 1990. 

Excluding volatile food and energy prices, the core PCE deflator was up 4.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in October, also accelerating from September’s revised 3.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} increase. This was the fastest annual rise in the core PCE — the Fed’s preferred inflation gauge — since 1991. 

9:30 a.m. ET: Stocks open lower 

Here’s where markets were trading just before the opening bell: 

  • S&P 500 (^GSPC): -21.59 (-0.46{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,669.11

  • Dow (^DJI): -209.61 (-0.59{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,604.19

  • Nasdaq (^IXIC): -114.56 (-0.73{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 15,658.21

  • Crude (CL=F): -$0.23 (-0.29{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $78.27 a barrel

  • Gold (GC=F): -$1.40 (-0.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,782.40 per ounce

  • 10-year Treasury (^TNX): +1.6 bps to yield 1.681{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

8:45 a.m. ET: New jobless claims reach lowest in 52 years, Q3 GDP revised up

Economic data Wednesday morning came in mostly stronger-than-expected, with a new print on the labor market handily topping estimates while the second estimate of U.S. economic activity in the third quarter was revised higher. 

The Labor Department reported Wednesday that new weekly jobless claims came in at 199,000 for the week ended Nov. 20. This was the lowest level since November 1969, and was much better than the 260,000 new claims expected.

Meanwhile, the Bureau of Economic Analysis released its second estimate on third-quarter U.S. gross domestic product. Quarterly GDP was revised up to a 2.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} annualized rate for the three months ended in September, or above the 2.0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rate previously reported. This still represented a marked slowdown from the prior quarter’s 6.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} annualized rate of growth, however. 

The improvement from the prior estimate came as personal consumption, the biggest component of U.S. economic activity, was revised up to a 1.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} pace, from the 1.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rate previously reported. 

7:16 a.m. ET Wednesday: Stock futures drop ahead of economic data

Here were the main moves in markets ahead of the opening bell

  • S&P 500 futures (ES=F): -13.75 points (-0.29{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,674.75

  • Dow futures (YM=F): -119 points (-0.33{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 35,647.00

  • Nasdaq futures (NQ=F): -59 points (-0.36{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 16,253.00

  • Crude (CL=F): +$0.17 (+0.22{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $78.67 a barrel

  • Gold (GC=F): +$3.40 (+0.19{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,787.20 per ounce

  • 10-year Treasury (^TNX): -0.5 bps to yield 1.66{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

6:16 p.m. ET Tuesday: Stock futures open lower 

Here’s where markets were trading Tuesday evening:

  • S&P 500 futures (ES=F): -4.75 points (-0.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,683.75

  • Dow futures (YM=F): -27 points (-0.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 35,739.00

  • Nasdaq futures (NQ=F): -17.25 points (-0.11{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 16,294.75

NEW YORK, NEW YORK - NOVEMBER 15: A trader works on the floor of the New York Stock Exchange (NYSE) on November 15, 2021 in New York City. Following positive economic news out of China, stocks were up in morning trading on Monday with investors looking at retail sales and earnings results out from major U.S. companies later this week.  (Photo by Spencer Platt/Getty Images)

NEW YORK, NEW YORK – NOVEMBER 15: A trader works on the floor of the New York Stock Exchange (NYSE) on November 15, 2021 in New York City. Following positive economic news out of China, stocks were up in morning trading on Monday with investors looking at retail sales and earnings results out from major U.S. companies later this week. (Photo by Spencer Platt/Getty Images)

Emily McCormick is a reporter for Yahoo Finance. Follow her on Twitter

Weekly jobless claims total 199,000, reaching the lowest since1969

Weekly jobless claims total 199,000, reaching the lowest since1969

New jobless claims fell far more than expected to the lowest level since November 1969 last week, underscoring the present tight labor market conditions as initial unemployment claims near 2019 levels while job openings hold near record highs. 

The Labor Department released its jobless claims report on Wednesday, a day earlier than usual due to the Thanksgiving holiday. Here were the main metrics from the print, compared to consensus estimates compiled by Bloomberg:

  • Initial unemployment claims, week ended November 20: 199,000 vs. 260,000 expected and a revised 270,000 during prior week 

  • Continuing claims, week ended November 13: 2.049 million vs. 2.033 million expected and a revised 2.109 million during prior week

The total number of new weekly filings fell to a fresh virus-era low for a seventh straight week. During the comparable week last year, initial filings came at well over 700,000. Claims also fell below their 2019 weekly average of approximately 220,000. 

“It is fair to say that we didn’t see that coming,” Mark Hamrick, senior economic analyst at Bankrate, wrote in an email Wednesday morning. “Getting new claims below the 200,000 level for the first time since the pandemic began is truly significant, portraying further improvement.” 

“Americans head into the heart of the holiday season with a reasonable expectation that an already tight job market will continue to tighten in the months ahead,” he added. “Retail sales have recently surprised to the upside and that momentum should continue.”

Continuing claims for regular state unemployment benefits have also drawn closer to pre-virus levels. After coming in at the lowest level since March 2020 last week, continuing claims also neared their 2019 average rate of about 1.7 million per week. 

The latest jobless claims data also bodes well for November’s monthly jobs report from the Bureau of Labor Statistics. This week’s report coincides with the survey week for that data, which is due for release next week. Consensus economists expect that report to show non-farm payrolls rose by half a million in November, with the unemployment rate ticking down to 4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from 4.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in October. 

The past couple months’ worth of jobless claims reports have offered just one look at a labor market that has grown increasingly tight as the economic recovery progressed. Though the labor force participation rate has yet to return to pre-pandemic levels, the number of those rendered newly unemployed has fallen precipitously, with many employers incentivized to keep their current workforces as job openings and labor shortages across industries remain elevated. Job openings were last reported at 10.4 million as of the end of September, with this sum dipping only slightly from July’s record high of more than 11 million.

Monetary policymakers have been dealt the delicate task of further stoking employment growth while keeping inflation from running too hot for too long. Federal Reserve Chair Jerome Powell, who just this week was renominated to lead the central bank for another four-year term, has suggested that supply-side constraints contributing present levels of elevated inflation will eventually begin to ease.  

“In our assessment — against a backdrop of moderating growth and slowing inflation in 2022 — policymakers will have to shift focus next year from price pressures to a complete labor market recovery, which will take some time, delaying an eventual rise in interest rates,” wrote Rubeela Farooqi, chief U.S. economist for High Frequency Economics, in a note. 

Emily McCormick is a reporter for Yahoo Finance. Follow her on Twitter: @emily_mcck

Read the latest financial and business news from Yahoo Finance

Follow Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, YouTube, and reddit

Business Insurance Market May See Big Move | Allianz, AXA, State Farm

Business Insurance Market May See Big Move | Allianz, AXA, State Farm

The ” Business Insurance – Market Development Scenario ” Study has been added to HTF MI database. The study covers in-depth overview, description about the Product, Industry Scope and elaborates market outlook and growth status to 2027. At present, the market is developing its presence following current economic slowdown and its Impact. Some of the key players considered in the study are Allianz, AXA, Nippon Life Insurance, American Intl. Group, Aviva, Assicurazioni Generali, Cardinal Health, State Farm Insurance, Dai-ichi Mutual Life Insurance, Munich Re Group, Zurich Financial Services, Prudential, Asahi Mutual Life Insurance, Sumitomo Life Insurance, MetLife. The market size is broken down by relevant regions/countries, segments and application that may see potential uptrend or downtrend.

Get Inside Scoop of the report, request for sample @: https://www.htfmarketreport.com/sample-report/3692724-business-insurance-market-1

“Keep yourself up-to-date with latest market trends and changing dynamics due to Economic Slowdown globally. Maintain a competitive edge by sizing up with available business opportunity in Business Insurance Market various segments and emerging territory.”

Market Overview of Business Insurance:

The Study covers exploration of all necessary data related to the Business Insurance market. All phase of the market is analyzed thoroughly in the Study to provide a review of the current market working. The estimates of the revenue generated of the market includes opportunity analysis using various analytical tools and past data. To better analyze the reasoning behind growth estimates detailed profile of Top and emerging player of the industry along with their plans, product specification and development activity.

With qualitative and quantitative analysis, we help you with detailed and comprehensive study on the market. We have also focused on SWOT, PESTLE, and Porter’s Five Forces analyses of the
Business Insurance market.

Buy Single User License of Business Insurance Market – Global Outlook and Forecast 2021-2027 @ https://www.htfmarketreport.com/buy-now?format=1&report=3692724

Scope of the Report

On the Basis of Product Type of Business Insurance Market: , Commercial Property Insurance, Commercial Health Insurance & Other

The Study Explores the Key Applications/End-Users of Business Insurance Market: Large Corporations, Small and Medium-Sized Companies & Personal

On The basis of region, the Business Insurance is segmented into countries, with production, consumption, revenue (million USD), and market share and growth rate in these regions, from 2014 to 2025 (forecast), see highlights below

** North America (USA & Canada) Market Revenue (USD Billion), Growth Analysis ({1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and Opportunity Analysis
** South Central & Latin America (Brazil, Argentina, Mexico & Rest of Latin America) Market Revenue (USD Billion), Growth Share ({1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and Opportunity Analysis
** Europe (The United Kingdom., Germany, France, Italy, Spain, Poland, Sweden, Denmark & Rest of Europe) Market Revenue (USD Billion), Growth Share ({1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and Opportunity Analysis
** Asia-Pacific (China, India, Japan, ASEAN Countries, South Korea, Australia, New Zealand, Rest of Asia) Market Revenue (USD Billion), Growth Share ({1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and Opportunity Analysis
** Middle East & Africa (GCC, South Africa, Kenya, North Africa, RoMEA) Market Revenue (USD Billion), Growth Share ({1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and Opportunity Analysis
** Rest of World

Know more about of Business Insurance market report , review synopsis and complete toc @: https://www.htfmarketreport.com/reports/3692724-business-insurance-market-1

Business Insurance Competitive Analysis:

The key players are aiming innovation to increase efficiency and product life. The long-term growth opportunities available in the sector is captured by ensuring constant process improvements and economic flexibility to spend in the optimal schemes. Company profile section of players such as Allianz, AXA, Nippon Life Insurance, American Intl. Group, Aviva, Assicurazioni Generali, Cardinal Health, State Farm Insurance, Dai-ichi Mutual Life Insurance, Munich Re Group, Zurich Financial Services, Prudential, Asahi Mutual Life Insurance, Sumitomo Life Insurance, MetLife includes its basic information like company legal name, website, headquarters, subsidiaries, its market position, history and 5 closest competitors by Market capitalization / revenue along with contact information.

There are 15 Chapters to display the Business Insurance market
Chapter 1, to describe Market Definition and Segment by Type, End-Use & Major Regions Market Size;
Chapter 2, to analyze the Manufacturing Cost Structure, Raw Material and Suppliers, Manufacturing Process, Industry Chain Structure;
Chapter 3, to display the Technical Data and Manufacturing Plants Analysis of , Capacity and Commercial Production Date, Manufacturing Plants Distribution, R&D Status and Technology Source, Raw Materials Sources Analysis;
Chapter 4, to show the Overall Market Analysis, Capacity Analysis (Company Segment), Sales Analysis (Company Segment), Sales Price Analysis (Company Segment);
Chapter 5 and 6, to show the Regional Market Analysis that includes United States, Europe, China, Japan, Southeast Asia, India & Central & South America, Business Insurance Segment Market Analysis (by Type);
Chapter 7 and 8, to analyze the Business Insurance Segment Market Analysis (by Application) Major Manufacturers Analysis of Business Insurance;
Chapter 9, Global Production & Consumption Market by Type [, Commercial Property Insurance, Commercial Health Insurance & Other] and End-Use[Large Corporations, Small and Medium-Sized Companies & Personal];
Chapter 10, Production Volume*, Price, Gross Margin, and Revenue ($) of Business Insurance by Regions (2020-2027). [* if applicable]
Chapter 11, Regional Marketing Type Analysis, International Trade Type Analysis, Supply Chain Analysis;
Chapter 12, to analyze the Consumers Analysis of Business Insurance.;
Chapter 13,14, to describe Business Insurance sales channel, distributors, traders, dealers, Research Findings and Conclusion, appendix and data source.

Enquire for customization in Report @ https://www.htfmarketreport.com/enquiry-before-buy/3692724-business-insurance-market-1

Thanks for reading this article; you can also get individual chapter wise section or region wise report version like North America, Oceania, LATAM, South America, NORDIC, West Europe, Europe or Southeast Asia.

See Campaign: http://htfmarketreport.com
Contact Information:
Contact US : Craig Francis (PR & Marketing Manager)
HTF Market Intelligence Consulting Private Limited
Unit No. 429, Parsonage Road Edison, NJ
New Jersey USA
– 08837
Phone: +1 (206) 317 1218
[email protected]