

Mega Millions: How a Billion-Dollar Jackpot Actually Works | Personal Finance

Mega Millions: How a Billion-Dollar Jackpot Actually Works | Personal Finance

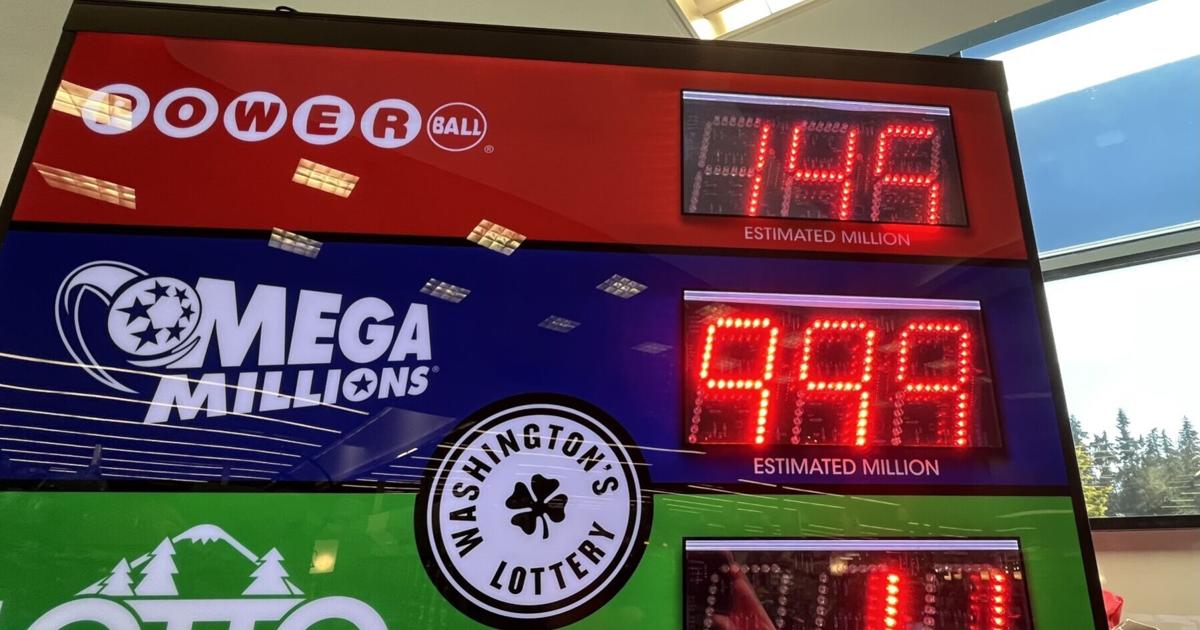
The Mega Millions jackpot has ballooned to an estimated $1.02 billion ahead of the subsequent drawing on Friday, July 29. A billion dollars is not an effortless amount to wrap your head all-around, and it’s took place only two times ahead of in Mega Millions history. If you want a likelihood to get the jackpot, here’s what you have to have to know.

How to acquire a Mega Thousands and thousands lottery ticket

Mega Millions can be performed in 45 U.S. states, as nicely as Washington, D.C., and the U.S. Virgin Islands. Gamers can buy as many $2 tickets as they want. Just about every ticket needs you to pick 5 figures between 1 and 70, and a sixth amount in between 1 and 25 (or, you can let the lottery individuals create the numbers for you). The jackpot goes to the man or woman (or persons) who decide all six numbers accurately.

Your odds of undertaking that are around 1 in 303 million.

Even though it is a national game, just about every collaborating condition has its have rules about how to declare a reward. In point, the size of time you have to file your assert can variety from 90 days to a calendar year from the date the quantities were drawn. Make confident you evaluate the rules in the condition in which you obtained the ticket.

Men and women are also reading…

How much could you get?

Each individual Mega Millions jackpot winner has the choice to just take funds now in a a person-time, lump-sum payment or to get a chunk of the winnings yearly for 30 years.

For the $1.02 billion jackpot, the income solution is $602.5 million.

If you took the annuity selection rather, you could get around $15.3 million for the initially payment. Then just about every just one right after that improves by 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. If you die just before all of the annual payments are made, the rest will be despatched to your heirs.

Just about every possibility has its professionals and downsides, Lisa Kirchenbauer — founder and president of Omega Wealth Management in Arlington, Virginia, and qualified monetary planner — said in an electronic mail.

Kirchenbauer also explained that any one who finds them selves quickly rich ought to put with each other a crew of specialists, which include an attorney, accountant and economical planner.

“Your crew will enable you make a decision which alternative is best for you,” she explained. “It’s not a just one-dimension-matches-all choice.”

How lottery winnings are taxed

If you earn a billion pounds in the lottery, you unquestionably owe federal cash flow tax on it. To begin, according to the IRS web-site, 24{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your winnings are withheld. How a lot that is depends on whether you went for the cash or annuity solution, because you only pay back taxes on what you receive in a presented 12 months.

If you take the hard cash all at the moment — recall, that is about $602.5 million — you’d see $144.6 million taken off the leading, leaving you with $457.9 million.

Arrive April, you’d probably owe added federal cash flow taxes, as perfectly as state income taxes, relying on the place you are living.

What to do if you acquire

Whilst it’s a little something we’ve all probably dreamed about, no a single is ready to get the jackpot. If you do, safeguard your ticket. Whoever possesses a winning lottery ticket can file a assert for the award.

Subsequent, look at your anonymity. Just about every state has its individual regulations about whether lottery winners have to be publicly recognized. Holding your identify out of the news and telling as several individuals as probable guards you from scammers and long-shed “friends” who want to get back in touch.

The critical is to sluggish down, Kirchenbauer said. “Don’t start shelling out the funds just before you have time to program and imagine.”

Worried About Inflation? Don’t Stop Investing | Smart Change: Personal Finance

Worried About Inflation? Don’t Stop Investing | Smart Change: Personal Finance

These days, shoppers are paying out a lot more for just about every little thing, from gas to groceries to apparel. And thanks to larger dwelling expenditures, many people today are extra eager than at any time to conserve hard cash and enhance their price savings.

That line of considering would make sense. But if you might be in a reasonably superior area personal savings-smart (that means you have a entirely loaded emergency fund) and you happen to be capable to cover your monthly expenditures, it pays to maintain investing your revenue at a time like this. This is why.

Graphic resource: Getty Images.

The least complicated way to retain up

Not only is inflation generating the value of items rise, but it is also having into workers’ wages. To set it a different way, the $80,000 wage you make is almost certainly supplying you less getting electrical power now than it did at the commence of the yr because residing prices have risen exponentially above the earlier 7 months alone.

Folks are also reading…

Which is why now’s not a excellent time to give up on investing. Very the opposite — investing your revenue is a single of the very best approaches to outpace inflation and safeguard your long term buying electricity.

Where by should you invest your revenue?

If you might be socking absent cash for retirement, it pays to optimize tax-advantaged personal savings ideas like IRAs and 401(k)s. Classic IRAs and 401(k)s give you a tax split on your contributions, whilst Roth IRAs and 401(k)s permit for tax-free of charge withdrawals.

That mentioned, you could not want to tie all of your financial investment dollars up in an account earmarked for retirement. Even though IRAs and 401(k)s supply their share of tax gains, they’re also restrictive. You are unable to acquire a withdrawal from just one of these accounts before age 59 1/2, for case in point — unless of course you want to spend a high-priced penalty.

That’s why it is essential to make investments some of your funds in a typical outdated brokerage account. That way, you can obtain your cash when you want. And when your investments really should not serve as your unexpected emergency fund, the actuality is that if you will need to faucet your portfolio in a pinch, that alternative will exist penalty-cost-free in a common brokerage account.

What can investing do for you?

Not too long ago, the Consumer Price tag Index, which steps adjustments in the expense of customer goods, rose 9.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on an yearly foundation. If that appears like a huge leap, it is.

But consider this: From 1957 by way of 2021, the S&P 500 index shipped an regular once-a-year return of about 10.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. That’s enough to outpace the rampant charge of inflation we’re grappling with currently.

So if you set your revenue into an S&P 500 index fund, you may improve your savings at a amount that allows you retain or even attain acquiring ability. And if you devote in shares you feel have the likely to defeat the broad current market, you may possibly deliver even better returns in your portfolio.

Do not give up on investing

At a time when anything expenses so a great deal, your natural inclination could be to focus on hoarding hard cash. But the truth is that you have to have to hold investing to continue to keep up with higher fees. And even though an IRA or 401(k) could be a very excellent dwelling for your cash, you may possibly want to branch out into a regular brokerage account as perfectly for added overall flexibility.

10 stocks we like far better than Walmart

When our award-successful analyst workforce has an investing tip, it can pay to listen. Just after all, the publication they have run for above a decade, Motley Fool Inventory Advisor, has tripled the industry.*

They just uncovered what they believe that are the ten very best shares for investors to get correct now… and Walmart wasn’t a single of them! That is right — they believe these 10 shares are even greater buys.

Stock Advisor returns as of 2/14/21

The Motley Fool has a disclosure coverage.

1 No-Brainer ETF to Buy During a Recession | Personal-finance

1 No-Brainer ETF to Buy During a Recession | Personal-finance

As inflation carries on to soar, numerous Individuals are fearful that a economic downturn is on the horizon. Whilst no one — even the experts — can say when or if we will encounter a economic downturn, it would not damage to get started making ready just in case.

If a recession is looming, it can be tempting to push pause on investing. But economic downturns can be 1 of the best prospects to invest more, since inventory selling prices are commonly a lot lower.

It is crucial, even so, that you select the ideal investments. Not all shares will endure a economic downturn, and investing in the erroneous places could be high-priced. You can find a person trade-traded fund (ETF), however, that’s practically confirmed to recuperate from a downturn: The S&P 500 ETF.

Why spend in an S&P 500 ETF?

An S&P 500 ETF is a variety of financial investment that tracks the S&P 500 index by itself, which usually means it consists of the exact shares as the index and aims to mirror its functionality in excess of time.

Men and women are also reading…

The S&P 500 alone has a long historical past of recovering from even the worst recessions and market crashes. Above the last two a long time on your own, the sector has knowledgeable every thing from the dot-com bubble burst to the Great Economic downturn to the crash in the early stages of the COVID-19 pandemic. Despite anything, while, the S&P 500 has recovered.

That indicates if we do confront a further economic downturn, the index is incredibly very likely to recover from this a single, far too. And for the reason that the S&P 500 ETF tracks the index, it will also bounce again.

Continue to keep in head, however, that no expenditure is immune to limited-term volatility. The S&P 500 is by now down about 17{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} so much this calendar year, and it could slide further more if we enter an official recession. Nevertheless, keeping a lengthy-time period outlook is important.

In spite of limited-expression turbulence, the S&P 500 has thrived above time. In fact, considering that 2000, it can be attained returns of nearly 170{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. By investing now and merely holding your investments for the very long expression, you happen to be practically guaranteed to see good normal returns over time — no make any difference what transpires in the in the vicinity of phrase.

Is an S&P 500 ETF right for you?

S&P 500 ETFs are fairly safe, and they are superb for danger-averse buyers as well as all those who like a arms-off kind of expense.

With an S&P 500 ETF, you under no circumstances need to have to choose unique stocks or choose when to get or market. By investing in a single fund, you may immediately individual a modest stake in all 500 corporations that make up the index. All you have to do, then, is invest as a great deal as you can afford to pay for and sit back again and wait.

On the other hand, if you appreciate researching companies and hand-buying specific shares for your portfolio, an S&P 500 ETF may possibly not be the appropriate fit. In the same way, if there are sure companies inside the S&P 500 you’d rather not very own, you can find no way to choose out of investing in particular shares with this style of expenditure.

Also, hold in mind that an S&P 500 ETF can only earn regular returns. In other text, it is not possible for it to conquer the current market. If earning over-common returns is a priority for you, investing in specific shares may well be a improved possibility.

S&P 500 ETFs are one of the most secure investments to invest in in the course of a recession, due to the fact it is really incredibly probably they’re going to get well from any downturn. But they are not the appropriate in good shape for everybody. Right before you get, consider your investing preferences to make your mind up irrespective of whether they’d make a superior addition to your portfolio.

10 stocks we like far better than Walmart

When our award-successful analyst crew has an investing idea, it can spend to listen. Right after all, the publication they have run for above a ten years, Motley Idiot Stock Advisor, has tripled the industry.*

They just disclosed what they imagine are the ten best stocks for buyers to buy appropriate now… and Walmart wasn’t one of them! That’s appropriate — they assume these 10 stocks are even greater buys.

Inventory Advisor returns as of 2/14/21

The Motley Idiot has a disclosure coverage.

Should You Buy I-Bonds Now? | Smart Change: Personal Finance

Should You Buy I-Bonds Now? | Smart Change: Personal Finance

2022 has started out out as a quite rough 12 months for most Americans. The inventory current market is down although inflation is up and wages have revealed indicators of stagnating. That combination has strained people’s paying for electrical power all over the region.

In that atmosphere, I-Bonds, with their assure of inflation-matching returns, seem like a promising island of security and worth security in an normally extremely stormy scenario. In fact, although those people headline figures look promising, the information driving them make I-Bonds a a lot less perfect expense than they feel on the surface. That is not to say they are a poor use of your dollars, just one particular exactly where the real reality may perhaps not reside up to the headline promise in most eventualities.

Individuals are also reading…

Graphic resource: Getty Visuals

Some crucial constraints of I-Bonds

Very first, each human being is minimal to $10,000 of direct I-Bonds purchases for every yr, in addition an more $5,000 if procured by way of a tax refund. That limitation signifies that even though I-Bonds could perform a job in your economical plan, you should not be expecting them to be equipped to use them to secure definitely life-modifying quantities of your funds from inflation.

In addition, once you acquire an I-Bond, your cash is tied up for at minimum a year, except you take place to live in a declared catastrophe location. That tends to make it important to have an option resource of emergency funds for at the very least that first yr right after shopping for an I-Bond. Otherwise, if you have an unpredicted have to have to faucet your hard cash early, you could discover that the interest you’re having to pay to borrow when waiting around for that timer to pop exceeds what you are earning on the I-Bond.

As if that were not more than enough, if you money in your I-Bonds right before you have held them for 5 yrs, you will forfeit the most modern 3 months of desire. In other words and phrases, to genuinely get I-Bonds’ inflation-matching promised returns, you should keep your I-Bonds for at least 5 many years. Any shorter keeping period signifies you will get a lot less than that headline amount. This is vital to notice, due to the fact a 5 yr time horizon is all over the time when it begins to make feeling to make investments in stocks as a signifies to consider to beat inflation.

Then, of program, there are the taxes. Even though exempt from point out taxes, the funds you get paid on I-Bonds is taxed as standard interest profits at a Federal stage. As a result, your headline returns could retain up with inflation, but your getting electrical power on that income probable will not.

Put it all collectively, and I-Bonds come to be instruments that have some use, but are not automatically a terrific option for all other utilizes of hard cash or bonds.

So where by do I-Bonds make feeling?

I-Bonds can be a handy instrument as you’re shifting dollars from shares to hard cash or bonds a several a long time prior to your children begin their school educations. This is mainly because you can normally exempt the interest on I-Bonds from your revenue for tax functions if you are employing the revenue to spend for capable instruction expenditures.

In addition, I-Bonds can be handy in a bond ladder, particularly if you have at the very least a 5-12 months time horizon. This is mainly because you can defer the tax on the interest gained on an I-Bond until you provide it, which sales opportunities to a lot less once-a-year internal drag on your returns than with typical bonds. Be knowledgeable, however, that I-Bonds interest adjusts just about every 6 months, so if inflation receives back below manage, the latest price of return you get on your I-Bonds will shrink.

Eventually, if you are preserving for a aim that is additional than a year out and would in any other case be conserving in a examining or cost savings account, I-Bonds could supply you a much better possibility-modified return on your money. Remember that I-Bonds are securities presented by the United States Treasury. If the U.S. federal government stops shelling out its bondholders, we have in all probability acquired greater issues on our palms than just the lacking cash.

If you’re likely to use I-Bonds, get commenced now

In the end, I-Bonds can serve a affordable intent as section of your total monetary strategy. The 1-calendar year minimal holding time period usually means that the sooner you obtain them, the quicker that clock begins ticking. So if you might be organizing to use I-Bonds, now is a great time to place your prepare in location to make them a aspect of your general portfolio.

10 stocks we like much better than Walmart

When our award-successful analyst staff has an investing suggestion, it can shell out to listen. After all, the newsletter they have operate for in excess of a 10 years, Motley Fool Stock Advisor, has tripled the sector.*

They just uncovered what they think are the 10 best stocks for traders to buy correct now… and Walmart wasn’t a person of them! That’s right — they imagine these 10 stocks are even much better purchases.

Inventory Advisor returns as of 2/14/21

Chuck Saletta has no posture in any of the shares outlined. The Motley Fool has no situation in any of the shares talked about. The Motley Fool has a disclosure policy.

3 Little-Known Ways to Earn Bigger Social Security Checks | Personal-finance

3 Little-Known Ways to Earn Bigger Social Security Checks | Personal-finance

Millions of seniors collect Social Security benefits in retirement, some of them relying on their monthly checks for the majority of their income.

While Social Security was never designed to be your primary source of income, it pays to ensure you’re receiving as much as possible. Your benefits can go a long way in retirement, especially if your savings are falling short.

One of the best ways to increase the size of your checks is to delay claiming Social Security. However, there are a few other, less common options that can also help you earn larger monthly payments.

Image source: Getty Images.

People are also reading…

1. Work at least 35 years

The Social Security Administration calculates your benefit amount by taking an average of your wages over the 35 highest-earning years of your career. That number is then adjusted for inflation, and the result is the amount you’ll receive if you begin claiming at your full retirement age (FRA).

If you’ve worked fewer than 35 years by the time you file, you’ll have zeros included in your average to account for the time you were not working. That will result in a smaller earnings average and less money in benefits.

Even if you have worked a full 35 years already, working a little longer can be beneficial. Chances are you’re earning more now than you were 35 years ago. And because your average is based on your highest-earning years, working an extra year or two when you’re earning more can give you a higher benefit amount.

2. Take advantage of other types of benefits

Retirement benefits aren’t the only type of benefits you might be eligible to receive. In some cases, you could also qualify for spousal benefits, divorce benefits, or survivors benefits.

Spousal and divorce benefits allow you to claim based on your partner or ex-partner’s work record. In both cases, the most you can receive is 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the amount your spouse or ex-spouse is entitled to at his or her FRA.

If you were financially dependent on a loved one who passed away, you could also qualify for survivors benefits. Although usually reserved for widows and widowers, survivors benefits are also sometimes available to parents, children, divorced spouses, and other family members.

3. Contribute to a Roth account

Your Social Security benefits can be subject to both state and federal taxes in retirement. Your state taxes will depend on where you live, while federal taxes will depend on a factor called your provisional income.

Your provisional income is half of your annual benefit amount, any nontaxable interest, plus your adjusted gross income. If your provisional income is higher than $25,000 per year (or $32,000 per year for married couples filing taxes jointly), you’ll owe taxes on up to 85{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your benefit amount.

However, withdrawals from Roth accounts — such as a Roth IRA or Roth 401(k) — don’t count toward your provisional income. If you’re withdrawing a significant amount from this type of account, that can potentially lower your provisional income enough to reduce or even eliminate federal taxes — helping you keep a larger chunk of your benefits.

Your benefits can help you afford a more comfortable retirement, and it’s wise to make the most of them. With a few creative strategies, you can squeeze every penny out of Social Security.

The $18,984 Social Security bonus most retirees completely overlook

If you’re like most Americans, you’re a few years (or more) behind on your retirement savings. But a handful of little-known “Social Security secrets” could help ensure a boost in your retirement income. For example: one easy trick could pay you as much as $18,984 more… each year! Once you learn how to maximize your Social Security benefits, we think you could retire confidently with the peace of mind we’re all after. Simply click here to discover how to learn more about these strategies.

The Motley Fool has a disclosure policy.

How to Make the Most of Rewards Credit Cards | Personal-finance

How to Make the Most of Rewards Credit Cards | Personal-finance

If you happen to be going to use a credit rating card, should not you get compensated to do so? Benefits playing cards assist you profit from your day-to-day expending. This is what you will need to know to get the most important possible returns from benefits cards.

What is a benefits credit history card?

Benefits cards pay back you back again each time you use them. Quite a few this kind of cards give you again a proportion of each and every buy in funds. Other individuals pay back you back again with details or miles for a distinct airline carrier, hotel chain, or basic journey expenditures.

Impression supply: Getty Photographs.

Points and miles benefits are a bit much more complicated as opposed to cash rewards. The worth of a person mile or just one position is not often equivalent to an specific cash equal. Playing cards like Chase Sapphire Most well-liked present Ultimate Benefits points, where by each individual position is worthy of 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} additional in comparison to its money counterpart when redeemed for travel by way of the Chase Greatest Rewards portal.

Men and women are also reading…

Whether in the sort of dollars or factors, these benefits might seem to be small, but they can add up speedily. Benefits accumulate in the account above time till you redeem them.

The 3 sorts of funds back again playing cards

Set-charge playing cards

Set-fee playing cards get paid a established percentage on all transactions, commonly 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, depending on the card. These are best for folks who love a skinny just one-credit score-card wallet with out any fuss. The Wells Fargo Lively Money Card earns an endless 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} cash reward and a hefty $200 funds reward signal-up reward soon after you invest $1,000 on buys within a few months. Underneath this no-frills expending tactic, charge every thing on the card, including considerably less clear goods like car payments on dwelling stability or online and cellphone costs.

Bonus category cards

Bonus classification cards earn elevated money back rewards — generally 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in specific groups like gas, restaurants, or grocery purchases for a individual time frame. These reward classes commonly alter each individual three months. A card may perhaps offer you 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} hard cash back again on Amazon and Goal buys from Oct by means of December. The card member have to enroll to activate the bonus class either on the web, in-application, or by calling shopper support.

All other standard non-bonus buys proceed to earn 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} or 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} dollars again devoid of any activation, depending on the card. The Discover “it” card might be ideal for individuals who really like the exhilaration of unique reward types each and every quarter. To improve rewards, only use this card for the bonus classes.

Tiered cards

Tiered playing cards supply a hybrid concerning fixed-charge and reward category cards. They give a couple pick out elevated rewards classes of up to 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} funds again, and generally 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on all other normal buys. The Blue Hard cash Everyday Card from American Convey delivers advantages like 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at supermarkets, gas stations, and on on the net retail buys, each capped at $6,000 per calendar 12 months. All other purchases gain 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Moreover, it offers you a $200 credit rating on your card balance soon after you shell out $2,000 in purchases on your new card within the 1st six months of membership.

Benefits can be redeemed on-line, in-app, or by calling shopper support. Cardholders can redeem what they’ve acquired to pay out down their equilibrium, donate to charity, reserve travel, obtain present playing cards, or just get a check out for cash.

How to optimize credit rating card rewards

To make the most of your rewards, consider possessing a few credit history cards: 1 from every single classification over.

Ahead of the commence of each quarter:

  1. Plan out your credit history card utilization.
  2. Seem up and enroll in the bonus class for the quarter.
  3. Jot down bonus groups on a sticky be aware and continue to keep it in your wallet.
  4. Increase your funds again by sticking to your spending strategy.

Card Form

A few-Thirty day period Shelling out Plan

Bonus Classification

5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} places to eat

Tiered

3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at supermarkets
3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at fuel stations
3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on on line retail purchases

Mounted-Charge

2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on anything else


Are benefits credit playing cards suitable for you?

Benefits credit history cards are great for buyers scheduling to pay out their credit history card payments in total each month. It is really not worthwhile to pay back upwards of 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in curiosity to receive 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} income back again. Moreover, spending more than you can manage to optimize indication-up bonuses and rewards is tempting but risky. In addition, some of the finest benefits playing cards may possibly demand an once-a-year fee. The concept is to conserve income by racking up credit score card benefits, not drop income by racking up credit card financial debt.

Whatever your shelling out model or economical aims, a good strategy is the top goal in the course of these difficult instances. If your needs match what they offer you, benefits credit score cards could possibly be able to aid you get to that aim.

5 Simple Recommendations to Skyrocket Your Credit score Rating About 800!

Raising your credit score score higher than 800 will place you in scarce business. So rare that only 1 in 9 Us citizens can declare they’re users of this elite club. But opposite to preferred belief, racking up a large credit history rating is a whole lot a lot easier than you could have imagined adhering to 5 basic, disciplined strategies. You will obtain a whole rundown of every inside of our Totally free credit history score manual. It truly is time to put your money foreseeable future 1st and secure a lifetime of savings by raising your credit score rating. Simply just click listed here to declare a duplicate 5 Uncomplicated Guidelines to Skyrocket Your Credit score Score about 800.

Fool contributor Alka Mehta holds no monetary position in any firms outlined. Explore Financial Providers, American Express, and Wells Fargo are promotion companions of The Ascent, a Motley Idiot organization. John Mackey, CEO of Complete Foods Marketplace, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. The Motley Idiot has positions in and suggests Amazon and Focus on. The Motley Idiot endorses Explore Financial Companies. The Motley Idiot has a disclosure plan.