7 Personal Finance Books to Gift Friends Who Want to Get Ahead

7 Personal Finance Books to Gift Friends Who Want to Get Ahead

Looking for the perfect gift for your loved one? Clothes and gadgets may go out of fashion, but knowledge is forever — especially when it’s knowledge that will benefit a bank account. These books will allow you to gift your friends and family personal finance expertise — and although there are an infinite number of websites, influencers and apps to help you manage money, few are equal to the experience of diving into a well-researched book. 

We’ve compiled some of the best personal finance books for all audiences. That includes books for new investors, young adults, sole-income earners and everyone in between. Some are personal favorites and others are from Amazon’s bestseller list, a few are brand-new and others have withstood the test of time. You’ll even find a couple that aren’t entirely about money, but all are good reads filled with worthwhile financial lessons.
Amazon

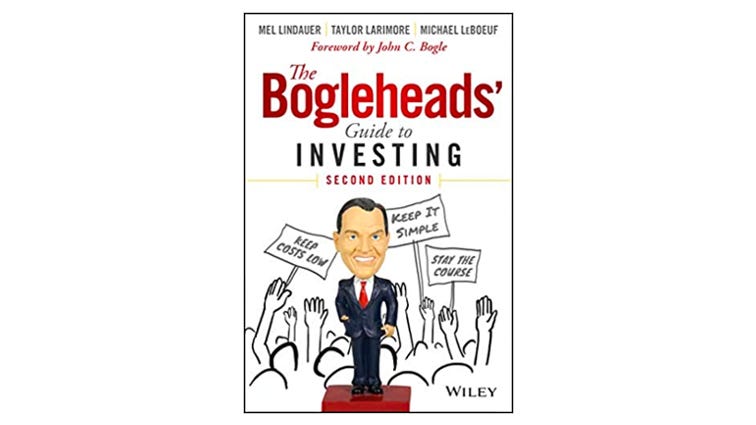
A favorite New Year’s resolution is to start investing, but what does that actually entail? Look no further than The Bogleheads’ Guide to Investing, the perfect manual for investors of any age or experience level. Espousing the investing wisdom of Vanguard founder John C. Bogle, this irreverent guide will teach you how to avoid Wall Street pitfalls and beat the market.
Amazon

Originally published in 1996, this compilation of research on America’s millionaires is ever enduring. It debunks the myth that “wealthy” equals “high-income” and emphasizes the importance of living below your means. Almost two-thirds of America’s wealthy are first-generation rich, and this book can teach financial tips on how to budget and invest your money.
Amazon

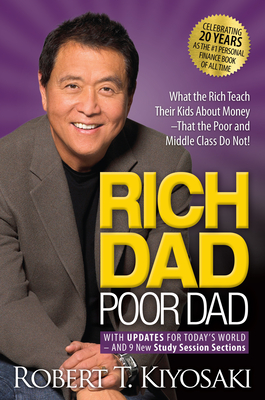
If you’re on personal finance TikTok, you may have seen this entry on your For You page, so you know it’ll make both a timely and relevant gift. Kiyosaki’s premise is that you can become rich regardless of your salary — it’s all about making smart decisions about your money. Geared toward parents, this book will help you better understand your money so you can teach your kids to start managing their finances. Given that most schools don’t teach personal finance, this is a helpful tool designed to walk you through educating your children about money and fiscal responsibility.
Amazon

It may be 2021, but women earning more money than their spouses can still feel taboo. This book is the perfect gift for any woman who brings in the lion’s share of a household’s income. It covers professional and personal topics to create the ultimate guide for any modern woman seeking to successfully navigate money, career, family and relationships. CNET Editor at Large Farnoosh Torabi incorporates personal stories and startling statistics while offering relevant advice for not only sole-income and high-earning women, but every couple merging or maintaining their lives together. 
Amazon

This New York Times bestseller details a simple, effective six-week program to achieve financial competence, dealing with topics from credit cards to automatic bank accounts. I Will Teach You to Be Rich is geared toward readers in their 20s and 30s who are overwhelmed by the world of personal finance and have no idea where to start. Its straightforward approach and useful tips will cut through any confusion and help you get your finances in order with minimal hassle.

Back Bay Books

Outliers has been a perennial favorite since its publication in 2008. Gladwell asks the frequently overlooked questions: What makes successful people stand out? What are the circumstances and opportunities behind the glitz of success?

From the 10,000-hour rule to the importance of “practical intelligence,” Gladwell encourages you to defocus from how success looks and instead think about how success is achieved. An intellectual journey for readers of all ages, Outliers is an analytical insight into the tools, secrets and habits used by successful people. We’d label it a must-read — after all, success in personal finance can be connected to achievements in other areas of life. 
Amazon

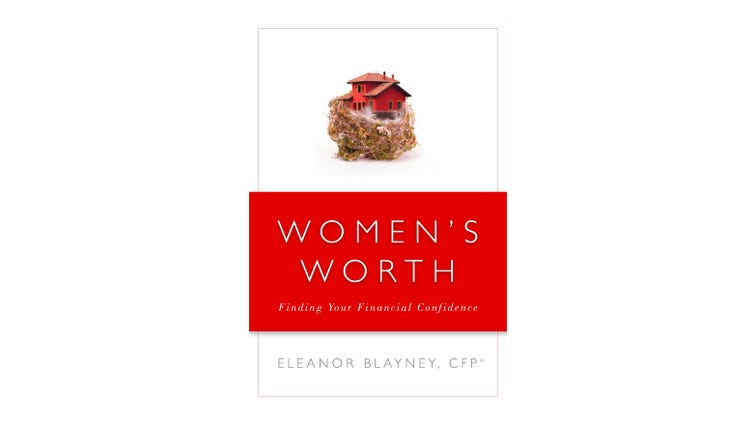
Women live in a world with unique financial needs: They tend to have less saved for retirement, be more conservative investors and see money in terms of impact on family and community. It’s time for their financial advice to reflect that disparity. Certified financial planner Eleanor Blayney offers practical, easy-to-follow advice that centers around two goals: women achieving a high level of financial competence and the creation of forums for women to discuss best financial practices and spread the wealth. This is the perfect gift for any woman in your life who wants to build up their financial literacy. 

Read more

The editorial content on this page is based solely on objective, independent assessments by our writers and is not influenced by advertising or partnerships. It has not been provided or commissioned by any third party. However, we may receive compensation when you click on links to products or services offered by our partners.
The Indie Personal Finance Bestseller List

The Indie Personal Finance Bestseller List

The American Booksellers Association’s specialty bestseller lists provide a present snapshot of what is promoting in indie bookstores nationwide.

Here is the Indie Personalized Finance Bestseller List, dependent on income at unbiased bookstores nationwide for the eight-7 days period ending April 3, 2022. 

1. Abundant Dad Bad Dad
Robert T. Kiyosaki, Plata Publishing, $17.95, 9781612680170

2. The Psychology of Income: Timeless Classes on Prosperity, Greed, and Happiness
Morgan Housel, Harriman Home, $18.99, 9780857197689

3. Finance for the Individuals: Receiving a Grip on Your Funds
Paco de Leon, Penguin Daily life, $16, 9780143136255

4. Feel and Expand Abundant
Napoleon Hill, TarcherPerigee, $10, 9781585424337

5. The Smart Investor
Benjamin Graham, Harper Small business, $25.99, 9780060555665

6. I Will Teach You to Be Rich, 2nd Edition: No Guilt. No Excuses. No BS. Just a 6-7 days Plan That Functions
Ramit Sethi, Workman, $15.95, 9781523505746

7. J.K. Lasser’s Your Income Tax 2022: For Planning Your 2021 Tax Return
J.K. Lasser Institute, Wiley, $24.95, 9781119839217

8. You Are a Badass at Producing Income
Jen Sincero, Penguin, $16, 9780735223134

9. The Richest Gentleman in Babylon
George S. Clason, Berkley, $9.99, 9780451205360

10. Funds Magic: An Economist’s Secrets to A lot more Revenue, Fewer Threat, and a Better Life
Laurence J. Kotlikoff, Tiny, Brown Spark, $29, 9780316541954

11. The 4-Hour Workweek
Timothy Ferriss, Crown, $24.99, 9780307465351

12. Child Ways Millionaires: How Everyday Persons Developed Amazing Wealth—and How You Can Way too
Dave Ramsey, Ramsey Push, $26.99, 9781942121596

13. Good Revenue Revolution: How to Make Far more Dollars to Do Extra Very good
Derrick Kinney, Skyhorse, $26.99, 9781510772915

14. A Random Stroll Down Wall Road: The Time-Tested Tactic for Productive Investing
Burton G. Malkiel, Norton, $19.95, 9780393358384

15. Miss Unbiased: A Very simple 12-Move Program to Start off Investing and Increase Your Personal Wealth
Nicole Lapin, HarperCollins Leadership, $27.99, 9781400226320

16. The Minor Book of Widespread Sense Investing: The Only Way to Ensure Your Truthful Share of Inventory Marketplace Returns
John C. Bogle, Wiley, $24.95, 9781119404507

17. Personal Finance 101: From Preserving and Investing to Taxes and Financial loans, an Critical Primer on Particular Finance
Alfred Mill, Adams Media, $15.99, 9781507214350

18. Get Very good with Funds: 10 Straightforward Actions to Becoming Monetarily Total
Tiffany the Budgetnista Aliche, Rodale Textbooks, $24, 9780593232743

19. The Every thing Guideline to Investing in Your 20s & 30s: Your Step-by-Move Guideline
Joe Duarte, All the things, $19.99, 9781507210307

20. Your Money or Your Daily life: 9 Actions to Reworking Your Relationship with Income and Achieving Financial Independence
Vicki Robin, Joe Dominguez, Penguin, $18, 9780143115762

21. My Cash My Way: Taking Back Command of Your Fiscal Existence
Kumiko Really like, Portfolio, $26, 9780593418840

22. Investing for Dummies
Eric Tyson, For Dummies, $24.99, 9781119716495

23. Money Grasp the Game: 7 Very simple Actions to Financial Independence
Tony Robbins, Simon & Schuster, $22, 9781476757865

24. Richer, Wiser, Happier: How the World’s Biggest Traders Earn in Marketplaces and Lifestyle
William Environmentally friendly, Scribner, $28, 9781501164859

25. How to Retire Content, Wild, and Absolutely free: Retirement Wisdom That You Will not Get from Your Financial Advisor
Ernie J. Zelinski, Visions Intercontinental Publishing, $21.95, 9780969419495

7 Reasons IRAs Are the Best Thing Since Sliced Bread | Personal-finance

7 Reasons IRAs Are the Best Thing Since Sliced Bread | Personal-finance

According to the folks at Gold Medal Bakery, sliced bread was invented on July 7, 1928, when Otto Frederick Rodwedder developed a bread-slicing machine. IRAs, on the other hand, came into being much later, in 1974, via the Employee Retirement Income Security Act (ERISA).

Often underappreciated, IRAs can be surprisingly powerful wealth builders — and given that they can save us from financially precarious futures, they’re pretty great indeed — arguably even better than sliced bread.

Image source: Getty Images.

Here’s a look at IRAs, featuring seven reasons you should consider setting one up — or contributing more to and/or investing more effectively in one you already have.

1. They can make you rich

Let’s start with the most exciting thing about IRAs: They can help you amass a lot of money. There’s a limit to how much you can contribute to an IRA (or several, with the limit applying to the total contributed to all), and it changes every year or few years.

People are also reading…

It’s worth noting that IRA limits are far lower than 401(k) ones, but that doesn’t take away from the potential growth of an IRA. Here are the latest limits:

For 2022

401(k)s

IRAs

Contribution limit for all

$20,500

$6,000

Additional “catch-up” limit for those 50 and older

$6,500

$1,000

Total possible contribution

$27,000

$7,000

The table below shows how much you might amass just investing $6,000 each year — or $12,000, if you’re married:

Growing at 8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for

$6,000 invested annually

$12,000 invested annually

5 years

$38,016

$76,032

10 years

$93,873

$187,746

15 years

$175,946

$351,892

20 years

$296,538

$593,076

25 years

$473,726

$947,452

30 years

$734,075

$1.5 million

Data source: Calculations by author.

Ideally, an IRA will be just part of your overall retirement plan, so while you might be regularly socking $6,000 away in your IRA (or more, especially when contribution limits are raised), you could also be adding thousands of dollars per year to a regular, taxable brokerage account.

2. They can help secure a comfortable retirement

Making good use of your IRA(s) can help you retire with more peace of mind, assured of a nest egg you can draw on to help support yourself.

You’ll likely have Social Security income, of course, but know that the average monthly retirement benefit was recently just $1,665, or about $20,000 annually. You’ll probably want a lot more than that.

3. They can help you avoid taxes now — or later

Another great thing about IRAs is that they’re designed to help you save for retirement in a tax-advantaged way. There are actually two main kinds of IRAs — the traditional IRA and the Roth IRA — and they differ chiefly in the tax breaks they offer.

With a traditional IRA, your contributions are tax-deductible, so they shrink your taxable income for the year of your contribution and, thereby, your tax bill. Roth IRAs, on the other hand, offer no upfront deduction, but if you follow the rules, you can eventually withdraw money from your account tax-free.

4. They offer a wide range of investments

Remember how 401(k)s have much bigger contribution limits, making them seem better than IRAs? Well, here’s a significant upside for IRAs: You can invest in a far broader range of stocks, funds, and other securities in your IRA account than you can in a typical 401(k), which offers only a very limited menu of funds.

So if you want to invest in a bunch of individual stocks — such as growth stocks and/or dividend-paying stocks — you’ll be out of luck with your 401(k), but you can do so in your IRA. (Note: If you invest in stocks that end up soaring and they’re in your Roth IRA, you will likely have a hefty account come retirement that you can tap tax-free.)

5. They’re available to just about everyone

Next, IRAs can be used by most people, with a few income limit restrictions. Anyone can contribute to a traditional IRA, but for the contribution to be deductible, your income will need to be below a certain level. Roth IRAs have income restrictions, too, keeping high earners from contributing fully or at all. Note that Roth IRAs also have to be funded with earned income — so you can’t fund one with lottery winnings, and your kid can’t fund one with allowance money.

Those limits will affect only high earners, not those bringing in typical or even somewhat-above-average wages.

Here’s another IRA distinction: 401(k) accounts are available from many employers, but not all, and self-employed people are out of luck. But self-employed people can contribute to traditional or Roth IRAs — and there are several other special IRAs they might use as well, such as the SIMPLE IRA and the SEP IRA.

6. They’re easy to set up

IRAs are also easy to set up. You can establish an IRA with any good brokerage — and possibly even at your bank. Do a little comparison shopping first, and be sure the IRA you set up will let you invest in the kinds of things you want, such as individual stocks or certain mutual funds — and check out fee schedules, too.

These days, some brokerages are offering no-fee IRAs, while others do charge fees. Always opt for no fees — otherwise, you’ll needlessly be handing over a portion of your earnings regularly.

7. They’re flexible

Finally, IRAs are flexible in some ways. For example, when you leave a job where you have a 401(k) account, you can roll over your 401(k) into an IRA account. You may also be able to turn that account into a 401(k) with your new employer. Try not to just cash it out, as that can shortchange your retirement.

Meanwhile, if you earn too much to contribute fully to a Roth IRA, you may be able to invest in one via a “backdoor Roth.” You would contribute to a traditional IRA and then convert it to a Roth. You can convert a 401(k) account to a Roth IRA, too. Just know that any funds you convert that had originally bypassed taxes will count as taxable income.

Don’t underestimate the wonderfulness of IRAs. Read up on them and their rules and see which kind(s) will serve you best.

The $18,984 Social Security bonus most retirees completely overlook

If you’re like most Americans, you’re a few years (or more) behind on your retirement savings. But a handful of little-known “Social Security secrets” could help ensure a boost in your retirement income. For example: one easy trick could pay you as much as $18,984 more… each year! Once you learn how to maximize your Social Security benefits, we think you could retire confidently with the peace of mind we’re all after. Simply click here to discover how to learn more about these strategies.

The Motley Fool has a disclosure policy.

Web extra: How personal finance columnist Michelle Singletary inspired one family’s debt journey

Web extra: How personal finance columnist Michelle Singletary inspired one family’s debt journey

On modern main software, On Issue talked with the amazing Michelle Singletary, nationally syndicated personal finance columnist at The Washington Write-up. Her column, The Shade of Cash, is celebrating its 25th anniversary.

MEGHNA CHAKRABARTI: We talked a lot about what Michelle has learned about People in america and their revenue around the earlier quarter century. And we also talked about her own finance ministry. The multitalented Singletary isn’t going to just dispense funds guidance in her column. She preaches it from the pulpit at First Baptist Church of Glenarden in Maryland.

MICHELLE SINGLETARY [Archival Tape]: I really don’t want you to believe that I say, will not get a mortgage loan, which is not what I’m expressing, mainly because most of us are not able to pay for to get our house with out a house loan. And I’m not even declaring, will not get a automobile mortgage, though you do know that you can pay out hard cash for your automobile, do you not know that? They will just take hard cash. They will. For the reason that we should not be having loans for automobiles. You can preserve up for your vehicle. I see y’all not having me on this. But you can.

Due to the fact here’s a trick my grandmother told me. When you get a motor vehicle personal loan, you only get one particular. Then soon after you get that one, when you pay that a single off, you just take the payments that you were not paying on it, you fork out it to you. So then when you require a auto, increase one more 10 or 12 decades or 15 a long time, which is how long my husband and I preserve a auto, then you can expect to have the money for a car or truck.

CHAKRABARTI: But you know, a woman can preach. But does the congregation listen? Very well, Jennifer and Tyrone Harris are also users of Michelle’s church. He is an educator. She performs for the federal govt, and they have two sons. They also had $230,000 of debt.

JENNIFER HARRIS: We experienced automobile notes in there as nicely, but the majority of it was college student loans. It was undergraduate degrees for both of us, as nicely as graduate. And so that all merged to $228,000.

TYRONE HARRIS: I did not think that we have been ever going to be capable to climb that mountain of $228,000 worth of credit card debt. I felt like it was just going to be a component of our family members, it was heading to go on household holidays with us. It was going to go into a new dwelling with us. You know, it was going to be at our funeral with us.

CHAKRABARTI: Insurmountable. That’s how Tyrone felt about the debt. But thirty day period just after thirty day period, Jennifer would occur house from Michelle’s lessons and discuss about all the items she acquired, matters they could give up to beat down that debt. But for Tyrone, an educator, there ended up selected things he was deeply reluctant to give up.

TYRONE HARRIS: 1 of the issues that was truly difficult for myself, being an educator, and for my spouse as well, was at the time we experienced our each of our sons in private university. And that was a important region that she felt like if we deleted, we might have a greater possibility of acquiring out of this credit card debt. So it was a actually rough decision. It was anything that we both of those ended up definitely nervous about. It can be a person that we went back and forth with. Because as every single mum or dad, you want the best for your boy or girl. And they are flourishing in their personal college. That’s almost certainly the major conclusion that we designed.

CHAKRABARTI: Now, factors get mentally less difficult to confront when they go from the abstract to the concrete. They requires form. You can see extra plainly how to chip absent at it. Jennifer states all of that came into emphasis for them when they set pen to paper, or really fingers to the keyboard in excel, and documented all of their fees.

JENNIFER HARRIS: We actually listed every thing and actually made a funds and caught to it. There was a line merchandise for every little thing, even enjoyment and foods and gasoline. Each minor cost, every single greenback we brought in, we made absolutely sure it was accounted for. It went someplace significant for us. So that we could type of manage ourselves and make positive we have been on the appropriate track.

TYRONE HARRIS: And she would say, Hey, if we continue at this speed in three months, this is how a lot will owe. You actually noticed the minimize in the amount that we owed. And it really manufactured you want to get the job done even more challenging to be like, Alright, wherever else can we acquire our belts? In its place of five months, can we get this carried out in four months?

CHAKRABARTI: At the start out of their journey, Tyrone had puzzled if radical belt tightening would necessarily mean that they would not get pleasure from existence the way they as soon as did. So how does he really feel now?

TYRONE HARRIS: I imply, lifetime is not miserable. I am definitely in a superior location mentally being aware of we can go to snooze and not get worried about finances so significantly. It has also blessed us to be in a position to assist other household members since we have the resources to assist other folks who might need extra aid. Our little ones are executing wonderful. They are nonetheless understanding and progressing. And so it was just a 4 calendar year of buckling down, tightening your belt and remaining true to the process and just keeping.

CHAKRABARTI: So as you can see, they experienced to do the job tough, continue to be focused and disciplined and never enable up on their objective. But right after 4 several years, Jennifer and Tyrone did it. They paid out down their $230,000 in financial debt totally. Now does that feel like an not possible desire for you? Properly, you can check with Michelle Singletary herself about it. She set up a range in which you can depart her your particular finance concerns. It’s 1-855-Inquire-Post.

Learn About Your Money in Small, Manageable Steps | Smart Change: Personal Finance

Learn About Your Money in Small, Manageable Steps | Smart Change: Personal Finance

So, you want to study additional about your dollars and make moves with it. Go you.

“That’s a minute of self-recognition that requires celebration,” suggests San Francisco-based money mentor Saundra Davis.

And your timing is perfect, as April is Monetary Literacy Thirty day period. This designation would not exist until lots of folks necessary assist comprehending their funds.

“You’re not the one particular individual out there that hasn’t received their finances jointly,” states Orlando-based certified economical planner Angela Moore.

Go simple on on your own, and start off smaller

It is Okay if you really do not conserve significantly or have a clue what IRA stands for. Goal to stay clear of adverse self-communicate and give you grace, suggests Moore, who’s also the founder of Modern Income Training, a platform presenting private finance classes.

Commence with “baby ways,” she provides. Timetable time to check out the measures below, so you’re mentally well prepared. (This is opposed to, say, waiting until you’ve overdrafted and experience frazzled.) For a several of these techniques, you could even established a timer and strategy to invest about 15 minutes on the physical exercise, so you do not get overwhelmed.

People are also reading…

As you consider the pursuing guidance, “think about how you find out very best,” claims Davis, who’s also the founder of Sage Money Remedies, a nonprofit specializing in economic training and setting up for low-wealth and underrepresented communities. For illustration, while group conversations may well be motivating for some persons, other folks would considerably somewhat examine a guide. So try out a few strategies to discover what works for you.

Strategies to understand about money

Discuss with a specialist

A monetary mentor, counselor or other pro can enable you figure out the place to begin and what to prioritize.

The Association for Financial Counseling & Arranging Schooling is presenting no cost virtual periods. The AFCPE web page claims its accredited financial counselors and coaches “can assist you take care of quick bills, make discounts, produce a program to spend off financial debt or navigate financial support positive aspects.”

You have other choices, much too. The Economical Arranging Affiliation gives professional bono money support to low-earnings men and women and these regarded as to be “underserved,” which include veterans, people affected by pure disasters and other individuals.

Or chat with buddies and group users

If you are not up for counseling, just chatting can assistance you assume and study about dollars in a informal way. You can understand how peers regulate money, voice your monetary fears and brainstorm options.

Just bear in mind that you’re participating in an casual conversation — not getting qualified advice. Do your most effective to validate suggestions on your individual. For example, glance for webpages on the subject matter that include things like resources for the info, these as expert professionals or scientific studies.

To discover in-individual income discussions, appear into local church buildings, libraries or universities. Or look at out Meetup, a web-site that aids groups obtain. You could also start income discussions between your very own pals to normalize the topic.

To understand with some others online, Moore implies wanting into Facebook teams that focus on private finance. Checking out Reddit’s r/personalfinance channel and its handy wiki page can also be an quick way to start imagining about income.

Check out quizzes, applications and spreadsheets

Would you choose a solo exploration of your income? Many on the internet applications can assistance you see exactly where you stand and establish your future ways.

Acquire this 8-concern monetary overall health quiz to decide your means to weather fiscal stressors and attain extensive-time period ambitions.

Or see in which your funds is heading with a spending budget app. Mint, for case in point, syncs all your money accounts and reveals how your expenses in good shape into different budgeting classes. Being aware of how considerably you’re paying out on what is a helpful initially move in taking care of your dollars and placing goals.

A cost-free finances spreadsheet, like those people offered by the Economic Trade Fee, NerdWallet and Microsoft Business office, can also support you realize your finances. These spreadsheets are a lot more arms-on than apps that sync your accounts, mainly because you’re liable for filling out fields linked to incoming and outgoing dollars.

Evaluate your funds and established ambitions

Interested in finding out more about your money but do not want to fuss with an app or spreadsheet? Check out Moore’s old-university tactic with her consumers. She has them spend 15 minutes simply jotting down their money inventory on paper.

This would include the quantities in checking, price savings and investment decision accounts ordinary bill payments credit card debt owed believed funds used each individual thirty day period and take-home money. Start with estimates.

“You’re not going to know a ton of this stuff,” Moore claims. Ideally, all these lacking items will make you curious, she states. So search up the authentic figures. You could locate your estimates are way off.

This work out is meant to assistance you realize in which you stand now. Being aware of these essentials aids you make adjustments and set aims.

For case in point, if you invested a lot more than you thought on takeout in March, you could intention to shell out fifty percent as a lot in April. Or probably you are inspired to refinance a mortgage, start an unexpected emergency fund or lead to your place of work retirement prepare.

Regardless of whether you are ready to established objectives on your possess or determine to use a tool or communicate with a professional, you are on the ideal track. As Davis says: “Start just where by you are, with no shame.”

3 Simple Tips to Send Your Retirement Savings Skyrocketing | Personal-finance

3 Simple Tips to Send Your Retirement Savings Skyrocketing | Personal-finance

Like most folks, I have my times when retirement appears to be extremely considerably absent. The real truth, even so, is that it typically sneaks up on us quicker than we notice. That’s why preserving for retirement by starting off as early as feasible is crucial. But it is really also a lot easier mentioned than performed.

If you’re getting a afterwards start on retirement financial savings than you meant, listed here are a number of suggestions you can use to test to develop your retirement savings at leading speed.

Impression source: Getty Photos.

1. Concentrate on keeping expenditures down

It can be impossible to make investments without having shelling out some charges, but you can choose methods to lessen them. 1st, if you happen to be investing by an IRA or a self-employed retirement account, do your study before deciding on an account company. Assess the characteristics and rate schedules for a couple diverse corporations right before you choose which one you want to get the job done with.

People today are also reading…

If you’re investing by way of a 401(k) or other place of work retirement strategy, you probably never get a option about which broker you function with. And you could possibly also be constrained in what you commit in. But you nevertheless have some options.

Most 401(k)s give participants a preference concerning several mutual cash, which cost once-a-year expenses recognized as expense ratios. These are created as a percentage of your belongings. For example, a 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} cost ratio means that every single 12 months, you’ll spend the mutual fund organization 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of all the property you have in the fund. If you have $100 invested, that’s only $1. But if you have $100,000 invested, it can be $1,000.

Check out to retain your expense ratios as small as probable. Index funds are a great, affordable choice for most persons. These money instantly diversify your income between hundreds of shares, and some have expenditure ratios as very low as .03{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

If you don’t have any minimal-price tag possibilities accessible to you, talk to your employer to see if it can be inclined to insert some. Or consider moving your income to an additional retirement account, like an IRA, that provides you higher liberty to commit the way you want.

2. Claim your 401(k) match anytime feasible

A 401(k) match is frequently worth various hundred to a few thousand bucks each individual yr, but its correct benefit is substantially a lot more than that. A $1,500 match claimed this calendar year could be really worth about $11,000 in 30 many years if you earn a 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} common annual fee of return. And if you claimed a $1,500 match every single yr about that 30-yr time period, you’d have above $147,000 just in employer-matched cash by yourself. (In actuality, you can expect to likely conclusion up with a great deal extra.)

401(k) matching packages demand employees to add funds to their possess accounts 1st. Then, the employer will both match the employee’s contribution greenback for greenback or $.50 on the dollar, up to a particular percentage of the employee’s once-a-year salary.

If you received a dollar-for-dollar match worthy of $1,500, you may double the $1,500 of your possess revenue you set apart each individual year. Returning to our example above, your total harmony at the end of 30 a long time would be $294,000 — $147,000 of your possess income and $147,000 from your employer.

With that form of funds at stake, it makes perception to declare your 401(k) match when achievable. If you happen to be not confident how your firm’s matching method functions or if you qualify for a match at all, test with your HR section. Then, do your most effective to declare as substantially of your match as you can every year.

3. Make capture-up contributions if you are suitable

An adult less than 50 years previous is only allowed to lead up to $20,500 to a 401(k) in 2022 and $6,000 to an IRA. But those people who are 50 and more mature can lead up to $27,000 and $7,000, respectively. You never have to do anything at all unique to make these extra contributions. As lengthy as you are going to change at the very least 50 in 2022, you can just set aside the extra revenue without panic of penalties for extreme contributions.

It’s not always straightforward to occur up with this extra income, but if you have it helpful, it is absolutely good to consider advantage of catch-up contributions. If you might be 50 and you never system to retire till your mid-60s or 70s, that funds has near to two a long time to expand prior to you are going to need to have to begin withdrawing it. If you contributed an extra $6,500 to your 401(k) each individual calendar year for 20 many years, you’d wind up with over $276,000 just from your capture-up contributions, assuming you gained a 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} common once-a-year charge of return.

You may well even conclusion up with far more around time. The government periodically raises the contribution boundaries for all retirement accounts, which include catch-up contributions, so you could possibly be equipped to established apart even more in upcoming years.

These recommendations may perhaps not all make feeling for you correct now, but maintain them all in thoughts as you move ahead in your profession. Choose some time to brainstorm other techniques you can improve your price savings, as perfectly. Everyone’s route to retirement appears to be a minimal diverse, so only you can determine which retirement financial savings techniques are appropriate for you.

The $18,984 Social Protection bonus most retirees entirely forget about

If you happen to be like most People in america, you might be a couple of decades (or extra) driving on your retirement personal savings. But a handful of tiny-recognised “Social Stability insider secrets” could assistance be certain a strengthen in your retirement revenue. For example: a person easy trick could pay you as substantially as $18,984 extra… each individual year! As soon as you master how to improve your Social Security benefits, we think you could retire confidently with the peace of intellect we are all soon after. Just click on here to explore how to discover additional about these tactics.

The Motley Fool has a disclosure coverage.