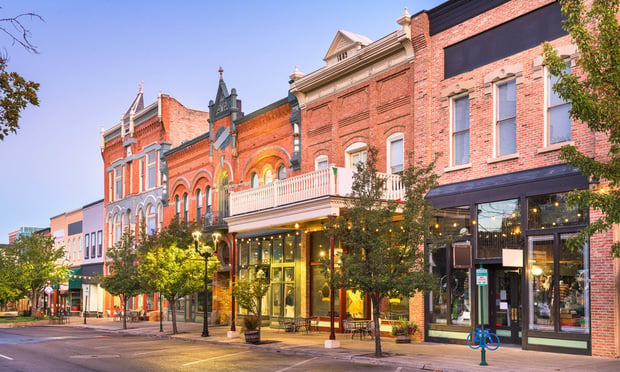
 In addition to financial challenges and the lingering impacts of the pandemic, smaller firms are grappling with shifting purchaser expectations, labor shortages, source chain disruptions and elevated disaster action. (Downtown Provo, Utah/Sean Pavone 2020/Adobe Inventory)
Economic uncertainty is major of intellect for all companies but especially for modest business house owners, several of whom are getting a close seem at all of their expenses, which include insurance plan. Rising from the pandemic, the economic climate continues to be risky, with around double-digit inflation and climbing interest premiums hitting tiny firms especially really hard.
In accordance to Nationwide’s latest Agency Ahead survey of small business owners, most small organization proprietors have a pessimistic outlook on the course of the general U.S. economy. But 72{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} hope situations for their have organization to be favorable in 2023, suggests J.J. Perez, president of Nationwide Corporate Options. Extra than fifty percent of little corporations (58{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) indicated they battle with handling the impacts of inflation on their enterprise, and about two-thirds (68{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) believe inflation will have an even greater impact on their enterprise in 2023.
With a prospective economic downturn looming, organizations have to have to consider how a stock current market crash, prolonged-time period inflation or interruptions to their funds move would affect their skill to meet customer demands, Perez states. Many economists, such as those people at Nationwide, are predicting a shorter or shallow economic downturn, he adds. So it’s significant for small business house owners to consider about how they may place their corporation to be all set to accelerate out of a downturn when it passes and acquire advantage of prospects to acquire marketplace share developed when competition are slower to get better.
“Now, more than at any time, trusted companions like fiscal advisors and insurance agents have a essential function to play in serving to their small business operator clientele navigate today’s risky financial setting, plan for a likely recession and acquire a possibility management approach to prepare for the sudden,” Perez claims.
Modest business enterprise, massive problems
In addition to economic issues and the lingering impacts of the pandemic, tiny businesses are grappling with shifting purchaser expectations, labor shortages, supply chain disruptions and amplified disaster exercise, especially together the coasts, suggests Victor dos Santos, president of commercial insurance coverage at SageSure, which specializes in running catastrophe-exposed property threat. “The future’s uncertainty is each a reminder and an chance to regulate what can be managed,” claims dos Santos. “Small organization proprietors simply cannot change the financial state or the weather, but they can leverage threat administration instruments — from mitigation systems to compact enterprise insurance — to assure they can recover swiftly when catastrophe does strike.”
Cyber hazards also keep on to have an affect on small corporations. The median value of a cyberattack has improved 80{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in the latest years, from $10,000 to $18,000, according to the 2022 Hiscox Cyber Readiness Report. “Hackers are becoming bolder and additional sophisticated, and modest corporations really don’t have the bandwidth to preserve up,” suggests Steven Wilkins, senior vice president and head of Casualty at Hiscox United states.
The improved value of cash offers one of a kind worries for tiny company homeowners as they appear to commit in and scale their organizations, necessitating them to make the complicated conclusion to either commit for expansion at a substantially higher over-all charge or slow expansion and hold out for a more concrete outlook, suggests Jen Tadin, handling director for Gallagher’s International Modest Enterprise apply.
Security troubles from organic activities, which include hurricanes, wildfires and flooding, also influence tiny organizations, and losses from crime are on the increase, claims Richard Clarke, chief insurance plan officer at Colonial Surety Company, which sells and writes surety bonds, fidelity bonds and insurance policies products focused on supporting modest and midsize organizations (SMBs).
Despite this sort of headwinds, 2023 could be a single of the ideal occasions at any time to commence or improve a tiny enterprise, states Joel Katsma, normal manager of sales at Acuity Insurance. “Online internet marketing is evolving absent from the main gamers, and opportunity abounds with customers searching for options as rates rise and company declines in a lot of places thanks to deficiency of staff members,” Katsma says. “If a tiny organization can weather the problems and differentiate on their own by means of this complicated time, they can earn clients and set on their own up for potential expansion. Financial disruption usually makes big options.”
Expertise shortages persist
“Recruiting and retaining talent continues to be just one of the most significant difficulties for modest organizations,” says Jen Tadin, running director for Gallagher’s World wide Modest Organization follow. “Rising wages and a aggressive market for expertise sales opportunities to a true problem for compact company owners in remaining consistently thoroughly staffed. Tiny companies run lean and in many cases have only a smaller quantity of staff members executing on every functionality of the business. Dropping one man or woman places a real pressure on the ecosystem inside of the business enterprise, funnels much more function to the remaining workers and finally a fragile staffing environment.”
The most new NFIB Tiny Business enterprise Optimism Index found that out of the 55{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of homeowners who claimed selecting or making an attempt to retain the services of in December, 93{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} documented number of or no certified candidates for the positions they had been striving to fill. Identical to past year, this usually means smaller organization proprietors are challenged to develop their corporations with much less assets.
“From an coverage perspective, tiny enterprise house owners who are battling with finding and retaining talent, have an opportunity to produce extremely protected workplaces, claims Dax Craig, co-founder and president of Pie Insurance coverage. “It’s crucial their enterprise coverage is up to day and correct, and that staff members are experienced on all place of work security actions. By doing so, they will safeguard their present and future workers whilst making certain no highly-priced and avoidable injuries take place at do the job.”
Coverage industry traits
Little organization insurance policy market place capability remains sturdy, with the the greater part of carriers trying to keep their hunger unchanged, suggests Wilkins.
“There have been some carriers cutting down appetite in greater hazard or specialty classes, but this has generally been more recent insurtech offerings with lesser market share,” he states. “Rates are a diverse tale though, with many carriers reflecting the higher inflation atmosphere and rising social inflation elements into the prices that little companies pay back for their policies.”
Katsma claims little small business has remained to some degree insulated from more substantial business marketplace developments. Carriers keep on to go following small business enterprise and are competing on value, relieve and coverage. However, he notes a looming hardening of the in general professional market place, many thanks to substantial inflation and absence of reinsurance ability, which may possibly transform the landscape heading forward.
“There is bifurcation on home- vs. casualty-driven accounts,” suggests Katsma. “Expect property-pushed accounts to be much additional tricky. The business house market is in unprecedented moments, and a drive for extra rate is not likely to sluggish down in 2023, when casualty traces have taken care of profitability and are still looked at competitively.”
Eric Coleman, senior vice president of Nationwide Tiny Enterprise Coverage, also notes prices are soaring more in catastrophe-prone regions and on property coverages in standard, due to a blend of inflationary pressures, enhanced and much more widely occurring temperature losses, and reinsurance amount will increase.
“There are also further issues on casualty lines in particular legal jurisdictions with verdicts exceeding historic anticipations as courts resume a much more conventional speed subsequent COVID-19 delays in the system,” Coleman suggests. “All of these aspects are putting pressure on insurance carrier results, leading to field-extensive revenue challenges. Capacity is subsequent the route of pricing, with home-pushed accounts, and increased disaster-susceptible geographies, dealing with a tightening of capacity. Carriers are each increasing rates, and decreasing ability to counter the tough problems in the current market. Nonetheless, as is practically usually the circumstance, threats with the very best decline prevention and mitigation strategies, and favorable protecting features, proceed to be desirable to carriers in the marketplace.
J.D. Electrical power a short while ago surveyed small companies about their encounters with their industrial insurance company and uncovered that about one-3rd of little companies explained they had expert a charge improve in 2022, up from 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} the 12 months right before. However, the review also unveiled a good twist buyer gratification also increased.
Stephen Crewdson, senior director of Worldwide Organization Intelligence, Insurance policy at J.D. Electric power, states client satisfaction went up 13 factors 12 months more than yr, a statistically significant improve in satisfaction. He adds that shopper interactions are the major driver of buyer pleasure and notes it is essential for brokers and insurers to notify tiny business enterprise buyers in advance of level boosts alternatively than creating them wait to see it on a renewal statement, assist them comprehend the fundamental motives for the maximize, and proactively appear for approaches to mitigate increases by acceptable modifications to deductibles and protection.
Finding options
Acceptable insurance policies protection is crucial for the longevity of a smaller business enterprise. It can determine irrespective of whether a loss will be a manageable, a non permanent setback or an expensive, enduring hardship, claims dos Santos. “Insurance not only gives economic defense for frequent and expensive challenges, this sort of as intense weather conditions harm, theft, and liability, but it also lends credibility to the business. Quite a few consumers and shoppers may call for proof of coverage before partaking a little small business, which is why company insurance policies goes past indemnity. It can be a instrument that supports continued growth.”
Insurers should really be knowledgeable of the wide assortment of little enterprise prospects and their unique issues and requires, states Charlie Mihaliak, EY Americas Insurance policies Company Transformation Leader and Principal, Tactic and Business enterprise Transformation, and Laura Hollerich, EY Americas Insurance policies Distribution and Product sales Optimization chief. For case in point, gig staff, who symbolize about 15-25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the world wide workforce nowadays, and are expected to symbolize 35-40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the workforce by 2025. These workers are searching for flexible procedures for their business pursuits and private life, according to EY’s 2021 study of tiny businesses. A expanding percentage of organization owners prioritize ESG and are fascinated in advertising and marketing greater societal results. EY’s survey uncovered 63{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of tiny organization entrepreneurs checklist working a sustainable small business as a precedence, and these forms of little organization owners will search for insurers who recognize ESG and related threats and have sector-specific expertise.
Coming out of the pandemic, company interruption protection remains a will have to-have for smaller business enterprise house owners, even if virtually all guidelines proceed to exclude airborne illness/virus,” says Tadin.
“When it will come to cybersecurity, modest business enterprise owners simply cannot be naïve and think attacks won’t take place to them,” says Tadin. “The common charge of cyberattacks would place many tiny corporations out of organization. Solutions contain a cyber-legal responsibility endorsement to a business enterprise owner’s policy or a stand-on your own cyber policy. Glitches and omissions insurance plan, or experienced legal responsibility, makes certain owners they have protection for the perform or assistance they provide in their enterprise. It is necessary to assure the get the job done and predicted outcomes of that work are protected.”
How you can support
Insurance policies carriers and brokers must get the job done to be viewed not as a needed evil but as associates in their customers’ companies, says Katsma. Getting a provider and agent who recognize their business enterprise and have expertise in what they are accomplishing can give compact enterprises an benefit in the market place.
“Carriers and brokers alike are pushing towards worth-additional providers,” Katsma suggests. “As little business has turn into additional competitive, there is a thrust towards differentiation by helping people shoppers with profitability, advertising and overall operations in addition to delivering a sturdy base of insurance policies safety.”
Servicing modest enterprise accounts is one particular way carriers can differentiate on their own from some others, Katsma says. Most carriers now offer you services centers for modest industrial consumers. The critical to undertaking this nicely is furnishing options for all buyers, so you can meet them where by they want to be satisfied.
“You want to have a are living human for consumers who want conversation, chat for people who choose to do it online, an quick cellular knowledge for these who require a swift certification or coverage improve, and complete self-company capabilities for these who want to do it them selves,” Katsma provides. “A a person-dimensions-matches-all approach is no longer acceptable. Carriers and brokers have to have to develop a number of channels and parts of abilities to set them selves apart from competition.”
Insurance coverage specialists who insure small businesses need to be readily available when, the place and how their clients want them to be, together with currently being obtainable during several hours outdoors of the traditional 9-5, investing in technological innovation to provide equipment and provider capabilities that empower clientele to self-serve, utilizing texting abilities to align with the on-the-go life of smaller company house owners and most importantly staying close to the modifying exposures inside of the organization to be certain there are no surprises when the unanticipated transpires, Tadin suggests.
“During the pandemic, 1 point that grew to become very clear is how agile modest enterprises are, quickly altering their merchandise or providers to adjust to a switching surroundings. Now insurance coverage industry experts should be certain they have an understanding of that the company they insured pre-pandemic may possibly look a great deal unique than it does publish-pandemic,” she claims.
Way too generally compact business entrepreneurs see insurance policies as a box they have to have to examine but do not shell out time basically pondering critically about the protection they have and have to have, says Alex Roje, an Insurance Restoration attorney at Lathrop GPM. They tend to concentrate on pricing as the determinative element, normally assuming all insurance policies are the exact.
“With so lots of concerns, expenditures and charges dealing with a compact organization, no a person could fault them for taking that strategy,” Roje suggests. “However, if insurance coverage insurance policies have been automobiles, just one could possibly feel of buying insurance this way: You may perhaps not want a Ferrari but you really do not always want a Pinto possibly.”
Brokers and possibility administration experts ought to do the job carefully with their little enterprise clients so that the target shifts from pricing to threat mitigation, claims Roje. Each compact small business policyholder must sit down with their broker to communicate by way of the dangers that maintain them up at night time, and what it would acquire for each and every to slumber very well understanding that they are acquiring what they compensated for. This should be an interactive procedure where by the policyholder asks issues of the broker as very well, significantly pertaining to the possibility and coverages that other in the same way positioned enterprises are obtaining and why, she says.
Small business owners have not had a great deal of a possibility to come up for air considering that the pandemic, suggests Wilkins. “They’ve been confronted with an onslaught of challenges, like inflation, the economic outlook, cyberattacks and provide chain challenges. Despite these issues, there’s an unshakable optimism and determination amongst modest small business homeowners, with 88{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} getting a optimistic outlook for 2023. From the firms that started out through and survived the pandemic, there’s a well-formulated aptitude for resilience that could electrical power the financial system for years to come.”
Kristen Beckman is a Colorado freelance journalist.
ALM’s Compact Business enterprise Adviser is a LinkedIn group where modest enterprise entrepreneurs can gather to community, have conversations and keep up with the trends and issues affecting their industries.
See also: