Why Budgets Don’t Work For A Lot Of People

Why Budgets Don’t Work For A Lot Of People

Select’s editorial team works independently to review financial products and write articles we think our readers will find useful. We may receive a commission when you click on links for products from our affiliate partners.

If you’re interested in personal finance, you’ve probably heard the tried-and-true advice that budgeting is essential to achieving financial independence. We’re often told that if we don’t diligently track our income, expenses and debt each month we won’t ever get our finances in order.

It’s easy to understand why so many personal finance experts recommend budgeting: It’s a simple solution to a complex issue. By understanding your monthly inflows and outflows of cash, you can identify where you’re spending too much and cut down on those expenses, or you may decide to supplement your income with a side hustle. Budgeting is meant to force us to confront what we might not want to know, whether it’s that we should have opted for a studio apartment instead of a one-bedroom, or that we really just need a new job with higher pay. 

If you’re hesitant to create a budget or if the thought of making one scares you, you’re not alone. A 2020 Intuit Survey of at least 1,500 people found that more than 60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} didn’t know how much money they spent the previous month. If you’ve tried making a budget and you’re unable to adhere to it, it might not be your fault. Select spoke to a policy expert and a personal finance expert about why so many people fail at budgeting and what they can do instead.

Budgeting can encourage a restrictive mindset around money

For many people, budgeting can be similar to dieting. You might eagerly create a new budget or start a diet in the hopes of saving enough to go on vacation or shedding a few pounds, respectively. However, after you’ve slipped up by eating a slice of cake or by spending too much on a new winter coat, you might be tempted to tear up the budget or say ‘screw the diet’. 

The language around budgeting and dieting often have moral connotations: You’re sinful and gluttonous when you indulge by breaking the diet or overspending, and you’re self-disciplined when you can adhere to strict spending limits or calorie counts. If you fail to stick to your budget or diet, it can often feel like a reflection of your character. 

“Budgets don’t work for many people in the same way diets or one-size-fits-all eating approaches don’t work long term. Instead, I believe that finances are personal. In the same way that it’s not about dieting but rather eating well, I don’t believe it’s about budgeting but rather spending and investing well,” says Melissa Browne, author of Budgets Don’t Work (But This Does).

When budgeting doesn’t work for people, it can leave many feeling worse about themselves. And there are a variety of reasons why budgeting might not be compatible with people’s lifestyles. 

Budgeting is difficult when your income or spending is inconsistent

Like many people, my spending and income may vary month to month. Sometimes I’ll have greater expenses due to doctor’s appointments or weekend trips I’m taking. Budgeting requires that people set limits on their spending, so when you have income or spending that varies on a monthly basis, it can be especially hard to stick to a budget. 

Theoretically budgets can be used to smooth consumption and spending over time: Families can save more when they experience income spikes and then use those savings to tide them over when they experience a decrease in their income.

According to a 2019 JP Morgan Chase Study, families needed just six weeks of expenses in order to sustain themselves if their expenses increased (such as an unexpected car repair) and their income decreased (such as unemployment) temporarily. 65{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of families, however, did not have enough money to cover six weeks worth of expenses. So if budgeting works when people plan ahead and save for hard times, why does it still fall short for so many?

Well, the answer is complicated. Sheida Isabel Elmi, a research program manager at the Aspen Institute Financial Security Program, notes that many of the families who experience income volatility, or annual income gains or losses of more than 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, are more likely to have inconsistent hours, lower wages and lack employee benefits like paid parental or sick leave. 

“I worked with this group of nonprofits that works directly with low and moderate income households, called the Consumer Insights Collaborative,” Elmi says. “So one of the things that came out of that research was that really only one type of worker — higher income full-time employees receiving workplace benefits, really stands a reasonable shot at financial security.”

And there are a significant number of families who struggle with income volatility. According to a 2015 Pew Study, 34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of families reported experiencing income volatility. 

Elmi suggests that the many of the financial hardships that low and middle income families are struggling with can’t simply be addressed with a budget. She points to policy and employer-led solutions like the expanded child tax credit, paid family, medical and sick leave, higher wages and consistent hours to help families weather financial hardships. 

There’s also a role that financial technology can play in helping build-up short-term savings. For families and individuals who experience income volatility, automating a set amount of savings each month may not be feasible. Instead, Elmi recommends tailored automation, which sets aside different amounts of money based on your spending habits. For example, a smaller amount is saved the month you have a pricy medical bill to pay off and a larger amount is saved when you receive a bonus at work.

While many experts recommend saving three to six months of living expenses in an emergency fund, the JP Morgan Chase Study found that most families would need around six weeks worth of expenses saved up to deal with an income dip and an increase in expenses.

The money that individuals save in an emergency fund should be liquid so they can easily dip into it if need be. You don’t want to invest your emergency savings in the stock market because you may have to pay short-term capital gains tax and/or you also risk losing money if you have to sell your investments during a market downturn. Consider opening a high-yield savings account for your emergency fund — you’ll earn a higher interest rate with this account than you would with a traditional one.

Some employers, like UPS, are helping workers build-up their emergency fund by providing a short-term savings account where workers can set aside after-tax money.

“Employer facilitated direct deposit is a great way to do this but the key again, is making sure that it fits within a person’s life and their circumstances,” says Elmi.

Apps like Digit or Douugh work by automatically sweeping aside money towards your different savings goals, whether that be an emergency or vacation fund. With these apps, the amount you save fluctuates based on your income and spending, making it a good choice for people who experience constant changes in their finances.

Even if budgeting doesn’t work for you, having an idea of how much you’re spending can be a useful tool to make sure you’re meeting your financial goals, like paying off credit card debt or saving for retirement. Budgeting apps like Mint and YNAB can help you understand how all of your money is being used. And of course, don’t be too hard on yourself if you have periods of higher spending.

Bottom line

If you’ve been wondering why it’s so difficult to follow a budget, you’re not alone, and it’s not your fault. Budgets are often pushed as a one-size-fits all solution to the complicated financial situations that many individuals and families face. They can be especially difficult for those who struggle with income volatility and can be unsustainable for many.

If you’re wondering what you can do instead of budgeting, you can start by prioritizing your emergency fund and putting aside any amount of money you can in order to have enough to cover six weeks worth of expenses. However, as Elmi notes, financial independence is not always in the hands of individuals or families. The financial hardships that many people face may require broader policy or employer-led solutions that can’t be fixed with a budget.

Editorial Note: Opinions, analyses, reviews or recommendations expressed in this article are those of the Select editorial staff’s alone, and have not been reviewed, approved or otherwise endorsed by any third party.
Newburgh Family Members Busted For Burning Down Business For Insurance

Newburgh Family Members Busted For Burning Down Business For Insurance

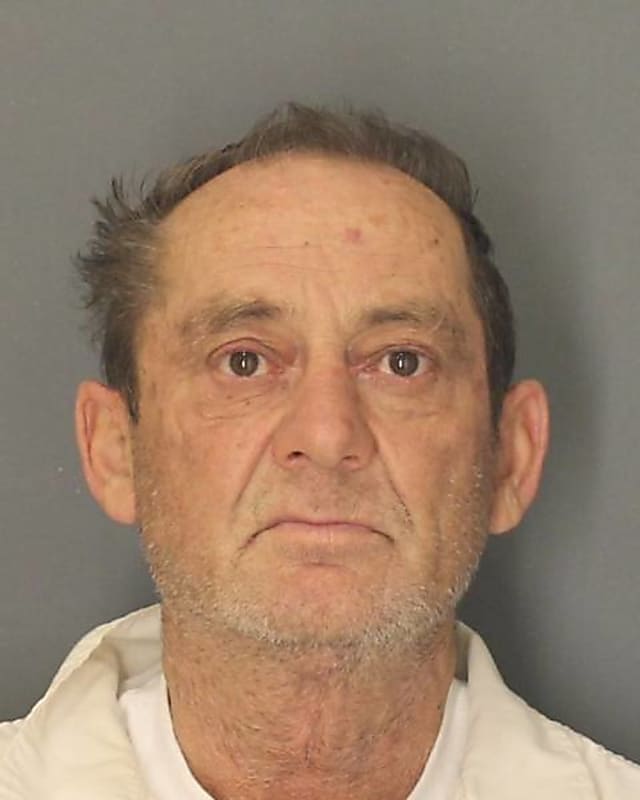
A failing restaurateur who conspired with members of his family to burn down his Hudson Valley business as part of an insurance fraud scheme is facing a host of charges, authorities announced.

Orange County resident Zef Gjurashaj, age 59, of Newburgh, and his nephew’s wife, Yonkers resident Marina Gjurashaj, age 37, were indicted and charged with a series of crimes for allegedly conspiring to burn down his restaurant in 2017.

Specifically, the two were charged by an Orange County grand jury with:

  • First-degree arson;
  • Conspiracy;
  • Insurance fraud;
  • Tax fraud;
  • Various other offenses.

Orange County District Attorney David Hoovler said that the indictment alleges that the two conspired with each other to intentionally burn down Andiamo’s Restaurant on Route 9W in Newburgh in September of 2017.  

It is alleged that Zef Gjurashaj, who was operating the restaurant in the fall of 2017, knew that his business was in a steep financial decline and decided to burn it down for insurance purposes.

Hoovler said that three weeks before the fire, he hired his niece, Marina Gjurashaj to work at the restaurant.

The investigation into the fire found that on Sept. 6, 2017, Marina Gjurashaj intentionally set fire to the building for the financial benefit of her “uncle”.

Thereafter, beginning in December 2017, Zef Gjurashaj, presented fraudulent Proof of Loss papers to his insurance company seeking payment for damage caused by the blaze.

As part of that scam, it is further alleged that Zef Gjurashaj submitted additional fraudulent documents to the insurance company through 2018. On two occasions in 2018, he also testified falsely during an Examination Under Oath (EUO) conducted by the insurance company regarding observations of the scene of the fire.

“Arson in the first degree is one of the more rarely charged crimes in this state due to the complexity of proof and other legal issues and I highly commend all the law enforcement agencies for their tireless work on this case,” Hoovler said in a statement. “The utter disregard for human life and property exhibited in this case is appalling.  

“(Their) selfish actions, in this case, were allegedly motivated by pure greed,” he continued. ”However, the hard work dedicated by the law enforcement professionals during the course of this investigation has brought to light the crimes these defendants hoped would disappear in the flames they set.”

Both Gjurashajs were arrested on Saturday, Nov. 27, and remanded to the Orange County Jail without bail. If convicted of the top arson charge, both face a term of between 25 years to life in prison.

“Insurance fraud involving arson not only burdens consumers with higher insurance premiums but also endangers lives,” acting New York State Department of Financial Services Superintendent Adrienne Harris said.

“Thanks to the excellent and diligent work by DFS investigators in coordination with fellow law enforcement partners, the perpetrators involved in this case have been apprehended.”

to sign up for Daily Voice’s free daily emails and news alerts.

Business News for Dec. 7, 2021

Business News for Dec. 7, 2021

SAN JOSE, Calif. — For the six days that Elizabeth Holmes, the founder of the failed blood-testing start-up Theranos, took the stand in her fraud trial, she blamed others, accused a former boyfriend of abusing and controlling her, and reframed her actions as trying to do good for her company.

On Tuesday, Ms. Holmes capped her defense with flat denials.

“I don’t think I did that,” she said in response to a question about whether she had minimized the findings of a devastating regulatory inspection at Theranos. She then blamed her company’s lawyers for “doing a lot of the talking in that meeting.”

The comments ended Ms. Holmes’s main testimony, which stood out as the rarest of rarities. Few technology executives, let alone a female tech executive, are ever charged with criminal fraud. Even fewer take the stand to defend themselves. Her time on the stand, which is likely to formally finish on Wednesday, was the climax to a trial that has captivated the business world and been held up as a parable of Silicon Valley’s fake-it-till-you-make-it culture on overdrive.

Ms. Holmes, 37, has pleaded not guilty to 11 counts of fraud for claims she made as chief executive of Theranos, which she founded in 2003. If convicted, she faces up to 20 years in jail.

Her trial is now moving into its end stage. Either side may call final witnesses over the coming days, followed by closing arguments and detailed instructions to jurors for their deliberations on a verdict.

“The jury got to know her over six days,” Jeffrey Cohen, an associate professor at Boston College Law School, said of Ms. Holmes. “If the defense is successful, that might be the decision that will make the difference.”

For most of the proceedings, the jury heard witnesses testify about the details of Ms. Holmes’s alleged fraud. Theranos rose to prominence, raising $945 million in funding, by claiming that its revolutionary machines could perform hundreds of tests using only a tiny drop of blood. The hype made Ms. Holmes a fixture on magazine covers that hailed her as the next Steve Jobs.

But a 2015 expose in The Wall Street Journal exposed problems with Theranos’s blood tests, kicking off a downward spiral of regulatory crackdowns and lawsuits. The company dissolved in 2018, and Ms. Holmes was indicted.


Who’s Who in the Elizabeth Holmes Trial

Erin Woo

Erin Woo📍Reporting from San Jose, Calif.

Who’s Who in the Elizabeth Holmes Trial

Erin Woo

Erin Woo📍Reporting from San Jose, Calif.

Carlos Chavarria for The New York Times

Elizabeth Holmes, the disgraced founder of the blood testing start-up Theranos, stands trial for two counts of conspiracy to commit wire fraud and nine counts of wire fraud.

Here are some of the key figures in the case →

Item 1 of 9

Since her trial began in September, prosecutors have called dozens of witnesses, including former board members, lab directors, employees, investors, patients and business partners. They have revealed the details of falsified documents, outlandish financial projections, unrealistic promises and faked demonstrations at Theranos. Witnesses often spent hours on the tedious minutiae of finance, chemistry, technology and phlebotomy.

Much of the case against Ms. Holmes has relied on her emails and text messages to tie her directly to the company’s problems. Prosecutors must convince the jury that Ms. Holmes knew about the problems and failed to disclose them to the people pouring money into Theranos and to the patients relying on its blood tests to make medical decisions.

In her defense, Mr. Holmes’s lawyers tried showing that the witnesses’ stories were more complicated than they had let on. Defense lawyers hit investors for not doing enough research on Theranos before investing. And they tried blaming lab directors for problems with the accuracy of Theranos’s tests.

Through it all, Ms. Holmes sat up stick-straight in her chair and stared straight ahead, her expression obscured by a mask.

After prosecutors rested their case last month, and before calling Ms. Holmes to the stand, her lawyers introduced brief testimony from a biotechnology executive who joined Theranos’s board of directors after it came under fire from the media and regulators.

Ms. Holmes then offered a variety of excuses for Theranos’s shortcomings. She said others had misinterpreted her statements about what Theranos’s technology could do. She said that, until a 2015 regulatory inspection revealed a host of problems and forced Theranos to void its tests, she believed its tests worked. She said she hadn’t been qualified to run a lab and had relied on the statements of others.

She also admitted to adding the logos of pharmaceutical companies to a series of reports, which implied the drug makers had endorsed Theranos’s technology when they hadn’t. For this, she expressed regret.

Her direct testimony ended with a bombshell revelation that Ramesh Balwani, her former boyfriend, business partner and alleged co-conspirator, emotionally and physically abused her. Through tears, she testified that Mr. Balwani had controlled every aspect of her life — including her schedule, diet and presentation — and had even forced her to have sex with him against her will.

On cross-examination, she choked up again when prosecutors had her read text messages with Mr. Balwani that showed a more affectionate side of their relationship. Prosecutors elicited several more mea culpas from Ms. Holmes, including regret over how she handled the Journal exposé and a positive Fortune cover story about the company that was later heavily corrected.

This week, prosecutors homed in on the discrepancies between what Ms. Holmes said in her testimony and what investors said she had told them. Numerous Theranos partners and investors testified that they had believed the company had contracts with the military and deployed its technology in medevacs and on battlefields, for example.

One of the prosecutors, Robert Leach, an assistant U.S. attorney, asked Ms. Holmes different versions of the same question repeatedly to hammer the lack of military contracts. She confirmed that Theranos had not had the contracts.

To show that Theranos was never paid for work with the drug maker GlaxoSmithKline, Mr. Leach also repeatedly asked Ms. Holmes about the lack of revenue, posing the question for each year from 2007 to 2014. Ms. Holmes said no each time.

Ms. Holmes resisted many of Mr. Leach’s lines of questioning by testifying that she didn’t recall or didn’t know. She also tried to dispute details in certain questions.

Ms. Holmes’s lawyers questioned her for a second time Tuesday afternoon with a rapid-fire series of statements meant to undermine Mr. Leach’s points and reiterate her initial testimony. Once again, Ms. Holmes said that Mr. Balwani had created Theranos’s unrealistic financial projections and that Theranos’s scientists had put together reports on its technology.

Until a regulatory inspection revealed deeper problems, she testified, she thought Theranos’s lab was “excellent.” Ms. Holmes also repeatedly stressed her concerns over exposing Theranos’s trade secrets as an excuse for withholding information from investors and partners, testifying again that she worried the company would lose its ability to compete. Discussing Theranos’s use of third-party machines would have violated Theranos’s own trade-secret policy, she said.

Mr. Leach tried knocking down that argument by noting that most of Theranos’s investors and partners had signed nondisclosure agreements that Ms. Holmes expected to be followed.

He further noted that, despite Ms. Holmes’s holding a patent for some technology, a patent did not “necessarily mean the invention described in the patent works.” Mr. Leach asked her if she had created a pill that measures lipids in blood, as described in one Theranos patent.

Ms. Holmes smiled, leaned into the microphone and said, “Not yet.”

Erin Woo contributed reporting.

Stocks close at a record as investors look beyond hot inflation

Stocks close at a record as investors look beyond hot inflation

Stocks ended Friday at a record level as investors shrugged off a key inflation report ahead of the Federal Reserve’s final policy-setting meeting of the year next week. 

The S&P 500 jumped nearly 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to log a record closing high. The Dow gained more than 200 points, or 0.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, while the Nasdaq added 0.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. 

The Labor Department’s Consumer Price Index (CPI) showed yet another multi-decade high rate of inflation for November. The CPI climbed by 6.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in November compared to last year, marking the fastest annual increase since June 1982. This rate matched consensus economists’ estimates, according to Bloomberg data, but accelerated compared to the 6.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} year-over-year rate from the prior month. And even excluding more volatile food and energy prices, the so-called core CPI rose by 4.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} over last year for the fastest increase in about three decades. 

“What we’re looking for is a deceleration as we go forward over the course of 2022,” Luke Tilley, Wilmington Trust chief economist, told Yahoo Finance Live on Thursday, ahead of the CPI print.

“That doesn’t mean prices are going to go down, it’s just a question of, are they going to go up as much in 2022 as in 2021 without the kind of fiscal stimulus we’ve had this year? And we don’t think that that’s going to happen, because it won’t be as much of a push on the demand side,” he added. “And then on the supply side, we’re looking for the labor market to improve, more people returning to work, and of course the delivery and the ports to improve.”  

Other recent data have further underscored the present tightness on the supply side of the economy. Weekly U.S. jobless claims plunged more than expected to reach the lowest level since 1969 last week, coming in even below pre-pandemic levels. And U.S. job openings came in at more than 11 million for only the second time on record in October.  

“Wage increases are probably on the agenda for next year. That’s part of the broadening of inflationary pressures that we’ve already started to see come through in some of that CPI data,” Seema Shah, Principal Global Investors chief strategist, told Yahoo Finance Live on Thursday. “But I have to say that we’re not so worried because we’re starting to see other parts of the inflation picture actually starting to fade. So at the end of next year, 12 months from now, we’re not expecting the kind of 6-7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} CPI numbers … We’re thinking more the 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} level for 12 months time.” 

Given the backdrop of elevated inflation, Federal Reserve officials have adopted more hawkish rhetoric about the monetary policy path forward. Some pundits suggested more rotation could occur in U.S. equity markets beneath the surface as investors price in expectations for tighter Fed policy to rein in inflation. The Federal Open Market Committee is slated to hold its final two-day monetary policy-setting meeting of the year next week. 

“The inflation print from this morning will reinforce the Fed’s resolve to accelerate tapering. With the strength in the economic recovery, it is time to take the crutches away,” Anu Gaggar, global investment strategist for Commonwealth Financial Network, wrote in an email on Friday. “Supply and labor shortages will keep aggregate prices elevated for longer, keeping inflation higher than the Fed target for a while. Omicron might dent the nascent recovery in demand for services such as leisure and hospitality while widening the demand-supply imbalance for goods.”

4:00 p.m. ET: S&P 500 surges 3.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in week

Here were the main moves in markets as of 4:00 p.m. ET:

  • S&P 500 (^GSPC): +44.60 (+0.96{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,712.05

  • Dow (^DJI): +217.29 (+0.61{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,971.98

  • Nasdaq (^IXIC): +113.23 (+0.73{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 15,630.60

  • Crude (CL=F): +$1.04 (+1.47{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $71.98 a barrel

  • Gold (GC=F): +$6.30 (+0.35{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,783.00 per ounce

  • 10-year Treasury (^TNX): +0.2 bps to yield 1.4890{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

—

2:42 p.m. ET: Ford shares jump to the highest in two decades after founder’s grandson spends $20 million in share purchases

Shares of automaker Ford (F) jumped Friday afternoon to reach their highest level since 2001. 

The move came amid news that Ford’s executive chairman Bill Ford, great-grandson of Ford founder Henry Ford, chose to exercise nearly 2 million of stock options at a total cost of $20.5 million as part of his executive compensation. 

—

10:12 a.m. ET: Consumer sentiment improved more than expected in early December: University of Michigan

The University of Michigan’s December Surveys of Consumers saw a bigger-than-expected recovery after reaching a decade-low in November, even as respondents called out rising inflation.

The institution’s headline sentiment index rose to 70.4 in its preliminary December survey compared to the 68.0 consensus economists were expecting, according to Bloomberg consensus data. This came following November’s print of 67.4 — the lowest in about 10 years.

Consumers’ one-year inflation expectations steadied at 4.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, matching November’s rate. For the next five to 10 years, consumers expected inflation to rise at a 3.0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} clip, with this also matching November’s reading.

“Sentiment posted a small overall gain in early December (+4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), although it was still nearly identical to the average reading in the prior four months (70.6),” Richard Curtin, chief economist for the Surveys of Consumers, wrote in a press statement. “The more interesting result was the large disparity between monthly gain among households with incomes in the lowest third (+23.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) of the income distribution compared with the modest losses among households in the middle (-3.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) and top third (-4.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}).”

“The core of the renewed optimism among the bottom third was the expectation of income increases of 2.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} during the year ahead; the last time a higher gain for this group was expected was in 1981,” he added. “This suggests an emerging wage-price spiral that could propel inflation higher in the years ahead.”

He also noted that 76{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of consumers selected “inflation” as “the most serious problem facing the nation,” when asked directly to select between inflation and unemployment. Just 21{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} selected unemployment, Curtin added. 

—

9:30 a.m. ET: Stocks open higher after hot inflation print

Here’s where markets were trading just after the opening bell:

  • S&P 500 (^GSPC): +30.78 (+0.66{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 4,698.23

  • Dow (^DJI): +171.58 (+0.48{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 35,886.82

  • Nasdaq (^IXIC): +113.45 (+0.73{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 15,631.82

  • Crude (CL=F): +$0.85 (+1.20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $71.79 a barrel

  • Gold (GC=F): +$6.40 (+0.36{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,783.10 per ounce

  • 10-year Treasury (^TNX): -1.7 bps to yield 1.47{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

—

8:36 a.m. ET: CPI inflation posts biggest year-over-year increase since 1982

The Labor Department’s Consumer Price Index showed the largest annual increase in inflation since 1982, signaling persistently elevated price pressures in the U.S. economy. 

The broadest measure of CPI grew at a 6.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} year-over-year rate in November, or the fastest rise in nearly four decades. This accelerated from the prior month’s 6.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} annual rise. On a month-over-month basis, the CPI rose 0.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, coming in hotter than the 0.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} monthly rate consensus economists were expecting.

—

7:20 a.m. ET Friday: Stock futures extend gains ahead of CPI report

Here’s where markets were trading ahead of the opening bell:

  • S&P 500 futures (ES=F): +16.75 points (+0.36{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,683.75

  • Dow futures (YM=F): +93 points (+0.26{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 35,846.00

  • Nasdaq futures (NQ=F): +57.25 points (+0.35{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 16,206.00

  • Crude (CL=F): +$0.66 (+0.93{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $71.60 a barrel

  • Gold (GC=F): -$3.50 (-0.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to $1,773.20 per ounce

  • 10-year Treasury (^TNX): +2.9 bps to yield 1.516{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

—

6:25 p.m. ET Thursday: Stock futures open higher 

Here were the main moves in markets in late trading on Thursday:

  • S&P 500 futures (ES=F): +6.5 points (+0.14{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 4,673.50

  • Dow futures (YM=F): +34 points (+0.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}), to 35,787.00

  • Nasdaq futures (NQ=F): +25.25 points (+0.16{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) to 16,174.00

NEW YORK, NEW YORK - DECEMBER 08: Traders work on the floor of the New York Stock Exchange (NYSE) on December 08, 2021 in New York City. Following news from the pharmaceutical company Pfizer on the effectiveness of its vaccine against the Omicron COVID-19 variant, the Dow Jones Industrial Average rallied nearly 100 points in morning trading on Wednesday. (Photo by Spencer Platt/Getty Images)

NEW YORK, NEW YORK – DECEMBER 08: Traders work on the floor of the New York Stock Exchange (NYSE) on December 08, 2021 in New York City. Following news from the pharmaceutical company Pfizer on the effectiveness of its vaccine against the Omicron COVID-19 variant, the Dow Jones Industrial Average rallied nearly 100 points in morning trading on Wednesday. (Photo by Spencer Platt/Getty Images)

—

Emily McCormick is a reporter for Yahoo Finance. Follow her on Twitter

Your 5-Point Year-End Personal Finance Checkup

Your 5-Point Year-End Personal Finance Checkup

Happy woman writes on paperwork at a table with a coffee cup

Image source: Getty Images

Whether 2021 was a good year for you, at this point, it’s almost over. But before you get ready to welcome 2022, it’s important to give your finances a close look. Here are five essential steps to take before the new year arrives.

1. Check your credit report

Your credit report is an overview of your various accounts and loans and how current you are on them. It’s important to get that snapshot of your borrowing picture so you can make sure you’re up to date on your various payments. But also, checking your credit report could be a good way to pinpoint financial fraud early.

Sometimes, criminals will open credit cards or credit lines in consumers’ names and rack up charges against them. You might only discover that you’ve been victimized upon reading your credit report and seeing an account you don’t recognize.

2. Review your budget

If you set up a budget earlier in the year, your expenses may have changed since. Similarly, your income may be rising for 2022, which could mean you’re able to spend a little differently. Now’s a good time to take a look at your budget and make sure it’s accurate. If it’s not, tweak those numbers accordingly, so your budget is ready for the new year.

3. Use up your FSA

If you contributed money to a flexible spending account (FSA) for 2021, now’s a good time to check your balance. Though some FSAs will let you carry over a small amount of money into the next plan year or give you a grace period for using your funds, you may have to spend your balance by Dec. 31 or risk losing it. See what options you have, and if there’s money in your account that you need to spend, think about some of the medications or FSA-eligible supplies you can stock up on, like bandages and certain over-the-counter treatments.

4. See how you’re doing on retirement plan contributions

If you’re saving for retirement in an IRA or 401(k), your goal may be to max out your contributions (meaning, contribute the maximum amount allowed for the year by the IRS) or simply save more than you did last year. Now’s a good time to check on your contributions to date and figure out a way to sneak more money into your account before the end of the year if you haven’t hit your personal target yet.

5. Check on your brokerage account

If you have investments in a brokerage account, it’s a good idea to review them from time to time. If you haven’t done that in a while, take that step in the coming weeks. You may decide to sell a stock that’s been performing poorly and use that loss to lower your 2021 taxes. You can use capital losses in your portfolio to offset gains on stocks sold at a profit or to offset some of your regular income. You may also want to shift some investments around for more diversity.

The moves you make at the end of the year could set you up for a financially strong 2022. Aim to tackle these items before the clock runs out on 2021. You’ll be thankful you did.

Alert: highest cash back card we’ve seen now has 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2023

If you’re using the wrong credit or debit card, it could be costing you serious money. Our expert loves this top pick, which features a 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2023, an insane cash back rate of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all somehow for no annual fee.

In fact, this card is so good that our expert even uses it personally. Click here to read our full review for free and apply in just 2 minutes.

Read our free review

We’re firm believers in the Golden Rule, which is why editorial opinions are ours alone and have not been previously reviewed, approved, or endorsed by included advertisers.
The Ascent does not cover all offers on the market. Editorial content from The Ascent is separate from The Motley Fool editorial content and is created by a different analyst team.Discover Financial Services is an advertising partner of The Ascent, a Motley Fool company. Maurie Backman has no position in any of the stocks mentioned. The Motley Fool recommends Discover Financial Services. The Motley Fool has a disclosure policy.

The views and opinions expressed herein are the views and opinions of the author and do not necessarily reflect those of Nasdaq, Inc.

Travel insurance claims cause frustrations from pandemic cancellations

Travel insurance claims cause frustrations from pandemic cancellations
Covid cancelled Carrol Colbert’s trip to Africa. She’s been struggling to figure out why her trip insurance won’t cover a refund.
Travel insurance issues
Carrol Colbert reads through her travel insurance policy from a trip she booked before the pandemic.

MACON, Georgia (41NBC/WMGT)— Carrol Colbert loves to travel. She’s been to New York, Las Vegas, and even Egypt.

In December of 2019, she booked a trip with her sister for the following June to Morocco and Senegal through Great Value Vacations and CheapOair. Since the trip cost more than $5,000, she purchased travel insurance through Trip Mate.

As the trip approached, the pandemic ruined her plans.

“The company cancelled the trip. I said I’ll just take a refund because I have trip insurance. Well they advised me because of this pandemic we cannot give you a refund,” she said.

Colbert was surprised she wouldn’t get a refund. After contacting Trip Mate, they told her the pandemic wasn’t anticipated and it wouldn’t be a covered reason through her policy. Colbert made sure she documented everything. After reading back through her policy, she believes it should have been covered.

“There was one area that talked about being quarantined and I said we are quarantined to the United States of America. We cannot even get out of this country to go into Africa,” she said.

Kelvin Collins, President and CEO of the Better Business Bureau of Central Georgia, says Colbert took the right steps.

He recommends shopping around for travel insurance, and making sure you read through the fine print. He says it’s important to do your research.

“Make sure you look at customer reviews, check them out with Better Business Bureau. Google their name and make sure this is a company or website that takes care of their customers later,” he said.

Even though Great Value Vacations gave Colbert a trip credit, and CheapOair gave her a partial refund, she still hopes to get the refund she feels the companies owe her.

Colbert says this experience hasn’t hurt her love of traveling though. She hopes to travel to Hawaii next year to celebrate her 40th wedding anniversary.

“I will use other companies and I will continue to travel. I think traveling is great and I look forward to resuming a near normal,” she said.

The Better Business Bureau says if you’re having issues resolving a travel insurance claim from the pandemic, you can file a complaint through them. You can also file a complaint through the Attorney General’s Office.