Worldwide Commercial Insurance Industry to 2028 – Adoption of Advanced Technology in Commercial Insurance Presents Opportunities – ResearchAndMarkets.com

Worldwide Commercial Insurance Industry to 2028 – Adoption of Advanced Technology in Commercial Insurance Presents Opportunities – ResearchAndMarkets.com

DUBLIN–(Business enterprise WIRE)–The “Industrial Insurance coverage Industry By Style, Distribution Channel Company Dimension and Industry Vertical: World wide Opportunity Examination and Market Forecast, 2021-2028” report has been added to ResearchAndMarkets.com’s presenting.

A commercial insurance policy approach provides various varieties of insurance policy insurance policies this sort of as legal responsibility insurance coverage, fireplace insurance policy, theft coverage, plant & machinery insurance plan, company insurance, and other folks. What’s more, these insurance policy insurance policies are specially designed to protect any kind of danger related with enterprise. In addition, business insurance coverage aids lessen the economic losses of corporations and promotes company continuity. It further shields image of the small business by running danger and safeguarding the entrepreneurs, consumers, and shareholders linked to the small business.

With an amplified levels of competition among the the professional insurance policy vendors to supply much better services in terms of protection and polices together with top quality premiums, the demand from customers for industrial insurance policy has enhanced in the industry. In addition, enterprise proprietors have a selection of polices from selection of business insurance coverage vendors to pick out, in accordance to their requirements & choices. In addition, increase in competitors among the small & medium sized organization and raise in want for insurance policies among the the enterprises to guard organization from pandemic cons are some of the components propelling the market advancement. However, high insurance policies premium of business coverage and lack of info amid compact-sized organizations about commercial insurance are some of the key elements restricting the growth of the industrial insurance coverage sector.

On the contrary, maximize in adoption of innovative systems these kinds of as artificial intelligence, machine finding out, predictive evaluation, and others aimed at attaining customer loyalty and to bolster the industrial insurance policy sector presence by providing superior products and services with decreased premium price. For that reason, this is attributed to supply valuable alternatives for the industrial insurance industry in the impending years.

The commercial insurance coverage sector is segmented on the basis of kind, distribution channel, company dimensions, field vertical, and region. On the foundation of style, the current market is segmented into commercial motor insurance coverage, business property insurance coverage, liability insurance plan, marine insurance plan, and others. By distribution channel, it is segmented into agents & brokers, direct response, and some others.

Centered on company dimension, it is segregated into substantial enterprises, medium-sized enterprises, and tiny-sized enterprises. By market verticals, the market is segmented into producing, development, it & telecom, healthcare, electrical power & utilities, transportation & logistics, and some others. By location, it is analyzed across North The usa, Europe, Asia-Pacific, and LAMEA.

The report analyzes the profiles of critical gamers working in the professional insurance plan marketplace this kind of as Allianz, American Global Group, Inc., Aon plc, Aviva, AXA, Chubb, Direct Line Insurance plan Group plc, Marsh, Willis Towers Watson, and Zurich. These players have adopted various procedures to increase their marketplace penetration and strengthen their place in the commercial insurance coverage field.

Key Advantages For Stakeholders

  • The analyze provides in-depth investigation of the world wide professional insurance policy market place together with the current & potential traits to illustrate the imminent expense pockets.
  • Info about important drivers, restrains, & prospects and their affect investigation on the worldwide professional insurance plan marketplace dimensions are provided in the report.
  • Porter’s five forces investigation illustrates the potency of customers and suppliers working in the sector.
  • The quantitative assessment of the world wide business insurance plan current market from 2021 to 2028 is furnished to identify the marketplace possible.

Sector Dynamics

Motorists

  • Improve in require for insurance plan guidelines among the enterprises to protect enterprise from pandemic scams
  • Enhance in level of competition among the little & mediU.S.zed business
  • Availability of massive variety of insurance vendors

Restraints

  • Large insurance quality
  • Absence of recognition amongst tiny dimensions enterprises

Options

  • Surge in use of telematics unit in the retail, development and health care industries
  • Adoption of innovative technologies in commercial insurance

Providers Pointed out

  • Allianz
  • American Worldwide Group Inc.
  • Aon plc
  • Aviva
  • AXA
  • Chubb
  • Direct Line Insurance Team plc
  • Marsh
  • Willis Towers Watson
  • Zurich.

For more details about this report take a look at https://www.researchandmarkets.com/r/xjdlok

Social inflation: Hardly a match for the insurance business

Social inflation: Hardly a match for the insurance business
Social inflation: Hardly a match for the insurance business Insurance plan professionals report that car coverage, umbrella packages, and the excessive and surplus market place are all hardening as a end result of nuclear verdicts. (Photo: Diego M. Radzinschi/ALM Media)

In the Oct 2021 problem of NU Assets & Casualty magazine, we paired a current market update about administrators and officers insurance policies, which just one qualified aptly describes as “sitting on best of” skilled and administration legal responsibility coverages, with a function that explores the impact of social inflation and nuclear verdicts on the insurance industry.

Social inflation continues to be a significant problem for insurers, and for a great reason. Passions can operate superior in courtrooms these times, and the more high-priced a lawsuit verdict, the a lot more that price will ripple through the industry and finally influence premiums.

Tourists says there are 4 variables resulting in social inflation, which is the force to correct societal wrongs as a result of litigation in basic and high-dollar verdicts in distinct.

In a website post on the matter, Travelers states the pattern came to prominence since of expanding public mistrust of companies increasingly advanced plaintiff’s lawyers psychological juries that are swayed by arguments that trigger their drive to secure liked kinds and alterations in the lawful environment that have made “a extra liberal and fewer tenured bench at the state court docket amount.”

That past statement strikes me as primarily loaded simply because it back links political affiliation with small business and economic overall health, which is an “us vs. them” stance that undermines democratic discourse.

Democracy functions ideal when all functions show more than enough regard for just one an additional to interact in difficulty-resolving. The wheels commence to occur unfastened when any one particular aspect retains their possess word as creed and discredits opposing or nuanced views.

A further take I’ve browse on social inflation posits that millennial jurists are pushing the strategy that companies have to spend for current and previous injustices. This looks fishy to me, much too, as not just about every millennial is a card-carrying liberal. What’s much more, if social inflation is currently being pushed by more youthful adults with evolving thoughts about justice, there may possibly basically be no stopping the eventual cultural evolution that will unfold as additional millennials increase to positions of management and electricity.

A person point is distinct: Social inflation’s impression is reaching even further than an individual court docket scenario or insurance coverage firm. Coverage industry experts report that auto coverage, umbrella offers, and the excess and surplus industry are all hardening as a end result of nuclear verdicts.

In accordance to PayneWest Coverage, a Marsh & McLennan Agency, “The insurance policies industry noted an regular 17.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} improve to umbrella rates throughout the initially

section of 2020.” And AmTrust Fiscal documented that the quantity of verdicts ensuing in judgments of $20 million or better rose 300{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} between 2010 and 2019. Enterprise executives there say insurers and producers are now charged with educating insureds about how they can finest mitigate legal charges.

All this remaining claimed, the notion of social inflation isn’t new. Quite a few insurance policies and finance watchers position to comments that Warren Buffett built about the craze about 45 years ago before he was the best doggy at Berkshire Hathaway. Back then, Buffett was chatting about asbestos litigation, which is intriguing. Asbestos product producing largely went the way of the dinosaurs after plaintiffs commenced receiving payouts for the illnesses they formulated thanks to managing the noxious material.

Is it not a good issue that we no for a longer period chance remaining poisoned by typical domestic fixtures?

Change is the only continuous in daily life. While unpleasant, social inflation could be ushering into society inevitable adjustments to which companies and insurers ought to change. Because when society moves, so does insurance policies.

See also:

Why Do You Need Business Insurance? Here Are Some Good Reasons

Why Do You Need Business Insurance? Here Are Some Good Reasons

A business insurance policies policy can be a substantial assist for any business, particularly when you are just commencing up. Company coverage policies are ready to safeguard your belongings towards unforeseen and unlucky activities that could possibly take place to your enterprise. Right here are some motives why it is significant to have insurance no subject what style of organization you operate.


Insurance policy can defend your company from lawsuits

You will help you save oneself a whole lot of trouble if you get insurance plan mainly because it will shield you from lawsuits. If you do organization, you will likely be sued at some stage mainly because some thing or an individual obtained harm as a end result of business enterprise dealings. Your company coverage requirements to defend versus men and women who want money from you, and it can’t just protect own injuries safety. It ought to also include house destruction and bodily accidents for absolutely everyone on-website working for the organization, but not if they are hurt by an outside social gathering like another co-worker (if there was drunkenness).

You could assume this will never ever come about to you, but even if no one particular has ever taken lawful motion right before now does not imply that absolutely nothing could go wrong up coming 7 days or upcoming yr. You need to always have good enterprise insurance policies coverage defending on your own from lawsuits since it is the only way to guard your business enterprise from becoming sued.

The extra that you have heading on in small business, the larger possibility there will be of a lawsuit arising and putting all the things at stake for shedding it all, specially if points go erroneous. To discover how accurately this functions, you can visit onesureinsurance.co.united kingdom the place it will be stated to you. It is often much better to be geared up and informed about these scenarios. 


You might will need to supply proof of coverage if you use for a mortgage

When you’re applying your business enterprise for a bank loan, the lender may well demand evidence of business insurance coverage coverage. Devoid of enterprise insurance policies, your enterprise is placing by itself at hazard in scenario anything happens to it or if you are sued for some explanation. This can be detrimental simply because banks will refuse to give dollars without having any type of business enterprise insurance policy.

Though there are many various varieties of enterprise insurances out there, legal responsibility and home security tend to be two that most corporations will need when implementing for a mortgage or funding their day-to-day operations. The primary plan guiding this variety of organization insurance policy is to make sure that your company’s property are safeguarded versus liabilities incurred by yet another party. These could appear from all varieties of troubles which includes injuries inside the business place, lawsuits brought on by shoppers unhappy with companies, or a thing else.


Your personnel will be more productive and delighted if they know their employer has the security of business insurance 

It is a lot more probably to have a successful enterprise if workforce know business insurance policies will enable deal with their healthcare expenditures, organization property, or business gear. Businesses need to usually have a business enterprise strategy in place just in case one thing takes place with the organization and the employees are not at fault for any of it.

Staff should really not have to get worried about company insurance policies mainly because it could be the variation involving owning a business and closing down for excellent. Personnel want companies who are inclined to take treatment of them, particularly in moments like this, when an employer desires business enterprise insurance just as a great deal as their workers do. 

Here’s a record of matters workers should be insured for:

  • small business residence or devices that is ruined
  • business personnel who are wounded on the job 
  • business assets, like inventory and hard cash registers that are dropped or stolen
  • company owner’s liability
  • professional medical costs for injuries sustained on the occupation


Company insurance policies can be very economical for modest company house owners if they shop about. Companies ought to ask their local businesses how significantly it would value to insure them selves in opposition to damages to small business residence or injuries to personnel. Organization insurance coverage will guard companies from mishaps mainly because any kind of mistake could result in a lawsuit remaining submitted by an not happy consumer or personnel. If you have fantastic coverage, then your enterprise will not go through as terribly when a little something happens in which anyone else is at fault. 


Insurance policy safeguards your company’s property

Enterprise belongings require to be covered in organization insurance plan because if something takes place to them, you will have a huge economic decline. They can be damaged by fire, theft, normal disasters, and other situations beyond your regulate. If they are not safeguarded in small business proprietors coverage (BOP) or professional property plan, then the enterprise operator is accountable for any expenditures that manifest from replacing these items. This suggests that small business entrepreneurs will have to pay back out of pocket for replacements without receiving compensation from their insurer. 

In buy to stop this state of affairs, it is critical to acquire business enterprise coverage as before long as achievable following starting up a company, so all required steps are taken treatment of ahead of some thing undesirable comes about with main effects. Corporations need to also make sure they keep sufficient dollars on hand to go over unexpected situation during the 12 months, these types of as company interruption coverage and business assets insurance policies.

It can include theft and destruction to your enterprise

You need to also address your company for theft and damage to your organization. This style of insurance plan is essential due to the fact it will shield you in situation some thing gets stolen or harmed on your enterprise residence. If this happens, then company insurance plan can reimburse you for what was stolen or harmed during a criminal offense. The protection amount of money differs based mostly on the company’s coverage and how substantially they want their customers to shell out in rates.

Clients will be drawn to you if they see you are careful

If purchasers see that you are insured, they will be drawn to enterprise with you for the reason that it implies that you are very careful and just take all the things significantly. They will recognize that your enterprise is not going to be influenced if a little something comes about to them or their products. 

After they see that every little thing is very well-structured and guarded, it is extra possible for them to get on board. Right after that, they may well advocate you to others and your company will improve promptly.

It is incredibly sensible to get insurance plan presently when it will come to your business enterprise. It is considerably safer for the reason that it will shield you from lawsuits and damages that could arise in situations of theft and incidents. It will also give you a far more effective firm with joyful employees along with clientele who will be happier to soar aboard. There is truly no explanation not to get it!

The Blocking and Tackling of Personal Finance

The Blocking and Tackling of Personal Finance

As the climate cools and the leaves flip, numerous of us seem forward to just one thing: no, not pumpkin spice every thing. Soccer. In the game, the groups with the strongest fundamentals normally put on their own in the finest location to acquire. According to legendary mentor Vince Lombardi, “some people consider to find points in this activity that never exist but soccer is only two things – blocking and tackling.” We can simply pivot to personalized finance to explore what represents the blocking and tackling in that arena.

The most essential basic principle in personalized finance is the strategy of beneficial income stream – paying out a lot less than you make. In point, this is the cornerstone of each individual other location simply because it frees up funds to be applied in the most effective method. If your spending plan is in want of a revamp, focus on the big ticket things initial (motor vehicle payments, house loan/lease, and so on.). This is usually not anything that is promptly actionable as those people payments are possibly set in some style or have the opportunity to even increase. Irrespective of whether it’s refinancing or downsizing, appraise your selections to maintain these dollars hogs under control. On the other facet of the equation, bringing in extra revenue frees up discretionary revenue to be deployed elsewhere. Once again, this is a little something that could not be quickly actionable, but think about an expenditure in you by way of certification or education to improve your foreseeable future cash flow possible.

A corollary to the final paragraph would be to aim on preserving with a reason. Just about every greenback and every single account must have a selected position. Folks get tripped up when they get their priorities blended. For case in point, placing every final dime of your personal savings in your 401(k) leaves your funds vulnerable to an unforeseen incident that forces you to get a loan in what need to be an simply avoidable predicament provided appropriate planning. Diversification of your account styles and financial commitment techniques makes it possible for for flexibility for whatever life throws your way. Tying the previous two paragraphs together, how a great deal is a superior target to preserve? We commonly recommend conserving at minimum 10-20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of cash flow. It’s not simple and it will not come about overnight, but it presents you a concentrate on to shoot for. 

In the very same spirit that the offensive line safeguards the quarterback, you want to make sure your funds are guarded. Everyone in all probability understands the great importance of existence insurance for generating absolutely sure your household is shielded in unfortunate circumstances – what style and how a great deal is a thing that really should be reviewed consistently. An usually neglected protection system is disability coverage. This is at times scoffed at due to the fact there is a notion that we can just “power by means of it.” That might be the case for a broken limb or surgical treatment, but ailments like most cancers are the major lead to of incapacity claims. A disability would have the magnified outcome of decreased earnings or complete loss coupled with a mountain of clinical expenses.

A football coach will meticulously prepare a video game approach for their impending opponent to make certain that every problem is accounted for. In that very same vein, your funds should have the same interest with target on the fundamentals.

For more facts, pay a visit to www.contwealth.com.

David Rath, CFA is the Director of Portfolio Tactics at Continuum Wealth Advisors in Saratoga Springs.

34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Z Is Learning Personal Finance From TikTok and YouTube, Survey Finds

34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Z Is Learning Personal Finance From TikTok and YouTube, Survey Finds

pressureUA / iStock.com

Generation Z has grown up in an age of low commissions and high technology, which has greatly influenced how they invest and learn about money in general. This generation that is between 6-24 years old right now is trying to use what they grew up with — things like social media — to their advantage instead of just for fun. While previous generations might’ve relied on family, financial advisors or other sources to learn about money management, Gen Z appears to be modernizing personal finance education in a way that works for them.  

Read: 51 of the Biggest Money Influencers on TikTok and YouTube
Check Out: The 10 Best Stocks for the Gen Z Investor

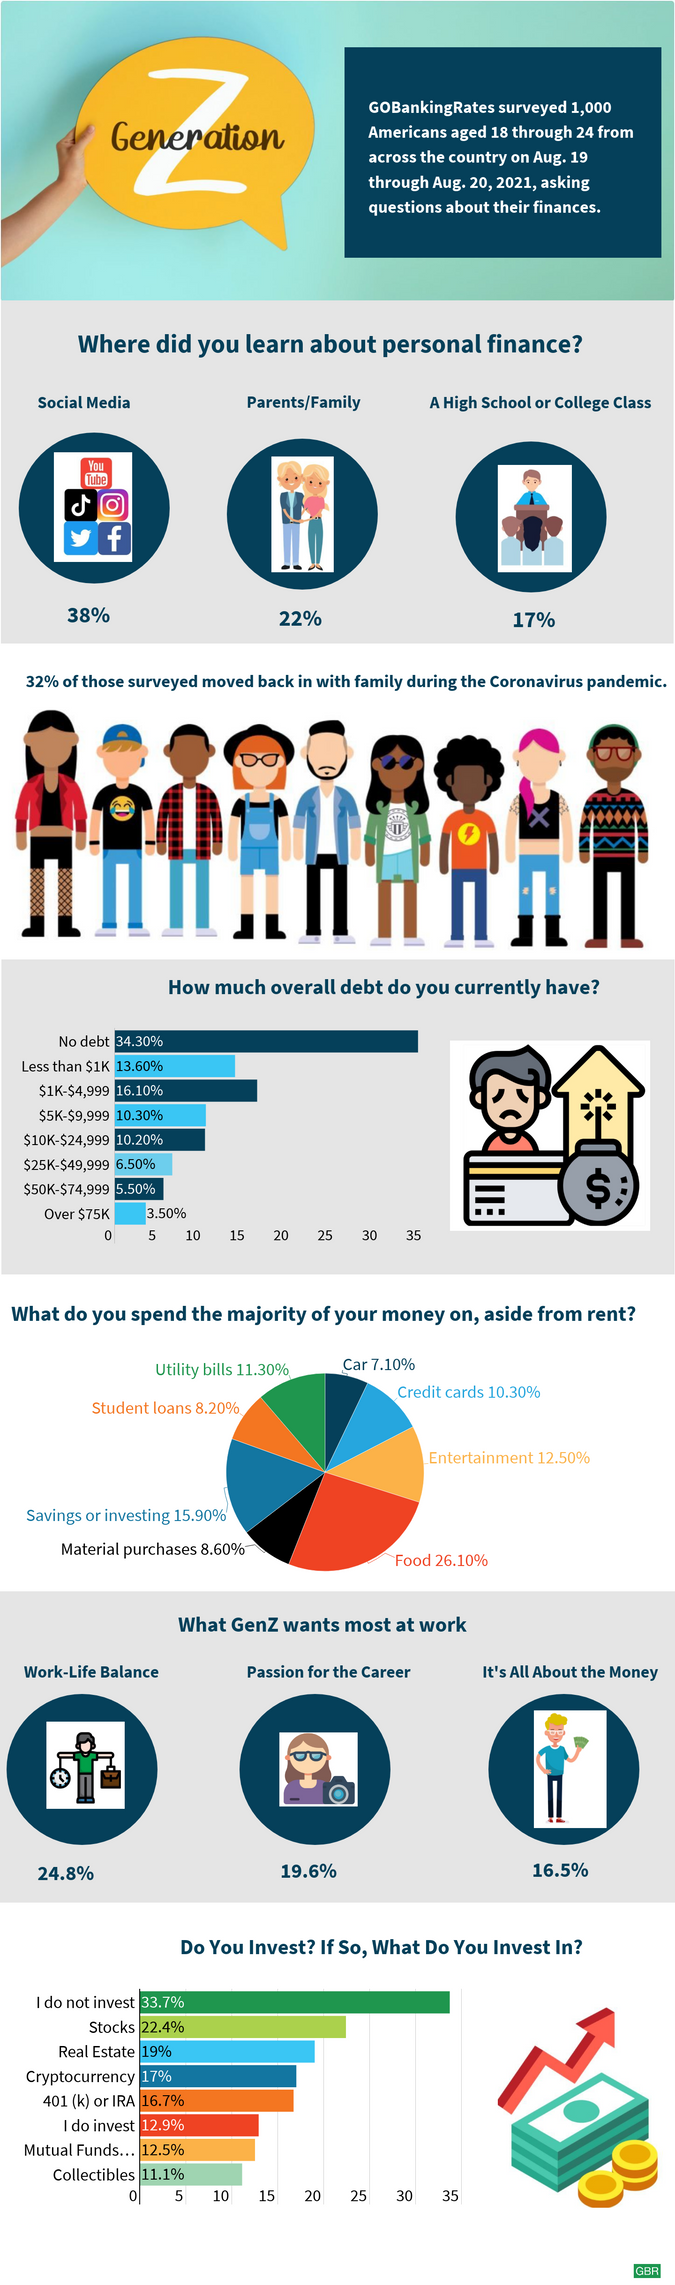
To find out about Gen Z’s approach to personal finance, investing and more money issues, GOBankingRates commissioned a six-question study of 1,000 Americans ages 18 to 24. Here are some of the most interesting results from that survey.

Gen Z Learns Personal Finance From TikTok and YouTube

Perhaps the most notable result from the survey is that the younger generation gets a lot of its financial information from a source that didn’t even exist two decades ago. A whopping 38.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Zers responded that they learned about personal finance from TikTok, YouTube or other social media outlets, like Twitter or Instagram — 34.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} answered TikTok and YouTube specifically. An additional 7.20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} responded that they get their information from personal research and/or online forums like Reddit. Combined, that’s far more than the 22.70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} who reported learning from parents or family. 

A lot can be inferred from this statistic. For starters, it reflects how much social media and online information dominates the lives of Gen Zers. However, it also raises questions about the quality of information that Gen Zers are getting about personal finance. While there is certainly some valuable information to be found online, there aren’t many restrictions as to who can post online and what they can say. If Gen Zers aren’t vetting the information they’re receiving, they could be susceptible to financial misinformation. It also means they might be missing some of the fundamental principles about personal finance along the way, as only 17.60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated they learned their financial information from a high school or college class.

Find Out: 5 Financial Steps Gen Z Should Be Taking Now
See: Surprising Ways Gen Z and Millennials Are Worlds Apart Financially

A Surprisingly High Percentage of Gen Zers Invest in Real Estate

For the purposes of this survey, only those ages 18-24 were included. Typically, people in that age range are either finishing up their education or working their first jobs. In either case, Gen Zers haven’t had a lot of time yet to build up their savings and investment portfolios. Yet, a surprising 19{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of respondents indicated they were invested in real estate, which traditionally requires higher levels of investment and/or a good credit history. This was the second-most popular investment category of survey respondents, just behind the 22.40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicating they were invested in stocks. 

Although a large number of Gen Zers in the survey indicated they were invested, 33.70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated that they were not invested in anything. This represented the single largest individual response to this question. While many Gen Zers may not yet be earning a lot of money to invest, it would benefit them to begin saving and investing as young as possible to take advantage of the power of compound interest.

More: Crypto and 5 Other Groundbreaking Investing Trends for Gen Z
Find: How Will Teens and Gen Z Invest Their Money? Think Low-Risk, ESG and Roboadvisors

Debt Levels Are Generally Under Control for Gen Z

While it might be more encouraging to see a higher level of investment from the survey respondents, the good news is that most of the Generation Z survey respondents indicated they had control over their debt. More than 34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of survey participants didn’t have any debt at all, including student debt, and nearly two-thirds had less than $5,000. However, 9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of respondents had at least $50,000 in debt. 

Find Out More: Life Events That Millennials and Gen Zers Are Choosing To Go Into Debt For

Many Gen Zers Still Rely On Their Parents

From the survey results, it appears that Gen Zers aren’t quite ready to completely stand on their own in times of trouble. During the pandemic, around two-thirds of respondents indicated that they lived with their parents. Although 13.90{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated they have since moved out on their own, a full 49.30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated they either have always lived with their parents or moved back home during the pandemic and are still there.

Read: Gen Z Feels Financially Unprepared for Adulthood — But Has Hope for the Future
More
: 4 Industries Gen Z Might Save — and 4 It Might Destroy

There Are Some Notable Differences Between Male and Female Gen Zers When It Comes to Personal Finance

When it comes to money and finance, there were some relatively significant differences between male and female respondents to the Gen Z survey. For example, 26.13{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of women indicated they learned personal finance from their parents or family vs. just 16.53{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men. Men vastly preferred YouTube as a source of financial information, at 27.17{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. 11.98{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for women. 

Women were also more likely to have zero debt, at 36.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. 31.09{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men, but they were also less likely to be invested: Only 25.77{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men indicated they were not invested vs. 38.10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of women. About 52{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men indicated they were invested in cryptocurrency and/or stocks vs. just 32.50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of women. 

More From GOBankingRates

Last updated: Sept. 15, 2021

Methodology: GOBankingRates surveyed 1,000 Americans aged 18 through 24 from across the country on Aug. 19 through Aug. 20, 2021, asking six different questions: (1) Where did you learn about personal finance?; (2) How much overall debt do you currently have? (Including student loan debt); (3) Do you invest your money? If so, what do you invest in? Select all that apply:; (4) If you had to pick one, what do you prioritize/value the most in a potential job?; (5) Did you move back in with your family during the coronavirus pandemic?; and (6) What do you spend the majority of your money on, aside from rent?. GOBankingRates used PureSpectrum’s survey platform to conduct the poll.

About the Author

After earning a B.A. in English with a Specialization in Business from UCLA, John Csiszar worked in the financial services industry as a registered representative for 18 years. Along the way, Csiszar earned both Certified Financial Planner and Registered Investment Adviser designations, in addition to being licensed as a life agent, while working for both a major Wall Street wirehouse and for his own investment advisory firm. During his time as an advisor, Csiszar managed over $100 million in client assets while providing individualized investment plans for hundreds of clients.

4 Books That Changed My Relationship to Money

4 Books That Changed My Relationship to Money

Welcome to Personal Finance Insider, a biweekly newsletter that connects you with the stories, strategies, and tips you need to be better with money.

Open book with money signs coming out of it on orange background 4x3


Rachel Mendelson/Insider


Here’s what: Books I’m currently obsessed with

I’m a book lover. You can find me reading no less than three books at any given time. Usually one is a novel and the other two are nonfiction.

Picking up a nonfiction book is one of the most cost-effective ways to mentally download a ton of information about a particular topic. And there’s no shortage of books about my favorite topic of all: personal finance.

I’ve read dozens of books about money, and many of them have been helpful in teaching me the basics — how to save, invest, and budget. But today I want to share four books with you that have given me an entirely new understanding of my relationship to money. Here are my current obsessions:

  • Brian Portnoy’s “The Geometry of Wealth” is full of insights that inspire me to think about how I can use money to shape my ideal life. He brings in lessons from other disciplines — history, neuroscience, and philosophy — to illustrate how everything in life is connected to money and how we can use that to our advantage. 
  • Morgan Housel’s “The Psychology of Money” implored me to think about how we behave as investors, savers, and earners. He takes what we assume to be true about money and turns it inside out. I’m always game for new perspective.
  • Rachel Rodgers’ “We Should All Be Millionaires” is a new book, released this past spring, that had me hooked from the introduction. Rodgers’ financial ambition is infectious, plus her ideas are inventive and totally actionable. This book has reminded me to never sell myself short.
  • Ramit Sethi’s “I Will Teach You To Be Rich” has been a favorite for years. It was first published in 2009 and updated a decade later. In addition to really helpful beginner investing and money management advice, Sethi introduces the concept of building a “Rich Life” for yourself and how to identify and get over your money hangups. It’s always relevant. 

Happy reading!

—Tanza Loudenback, Personal Finance Insider correspondent and certified financial planner

P.S. My time at Insider is coming to a close — it’s been a pleasure sharing my money musings with you over the past year. Going forward, senior editor of Personal Finance Insider Stephanie Hallett will be authoring this newsletter.


PFI Newsletter divider


Insider


Ad: This startup wants to help you plan for an easy retirement

After seeing too many people miss opportunities to maximize their retirement income, SmartAsset developed a free tool that helps you find unbiased, expert advice. If you’re ready to make smarter decisions around investing your 401(k), optimizing your savings, and minimizing taxes, SmartAsset’s tool can help you accomplish your financial goals. Learn More »

Disclaimer: SmartAsset is an Insider affiliate partner. We may earn money when you use our links. Learn more.


Join the Master Your Money Bootcamp

In our first two Master Your Money Bootcamps of the year, we got organized — and then we used that mental space to start dreaming big and crunching the numbers. Now we’re taking action.

Our third Master Your Money Bootcamp: Make a plan, presented by Fidelity, is a month-long challenge broken down into simple, one-week exercises. We’ll walk you through tasks that include finding the right accounts for your goals, opening those accounts, setting up an automated system, and figuring out whether you could benefit from professional help.

You don’t even have to sign up. Just check back here for a new exercise every week, or jump in at any time, and follow along on Twitter, Facebook, LinkedIn, and Instagram.


Stories you might have missed

5 strategies an entrepreneur used to go from making $41,000 a year to being a multimillionaire in her 30s

This is a taste of the inspiring advice you’ll find from Rachel Rodgers in “We Should All Be Millionaires,” one of the books I recommend at the top of this newsletter.

Extreme frugality was so stressful it made it hard for me to save, but my new system is helping me save thousands more every year

Insider contributor Katherine McLaughlin set up two separate

checking accounts
for spending after realizing that just because she was “good” with money didn’t mean she had a good relationship with it.

I travel the US full-time on $90,000 a year by following a few smart money rules

Angie Colee, a confidence coach who works with entrepreneurs, has been Airbnb hopping while working for the last nine months. She explains the financial moves she made to take the leap, and how she keeps it going.

5 challenges I did with my husband to save an extra $2,500 in 2021

If you’re looking for ways to bulk up your savings account before year’s end, here are some simple ideas that worked for Insider contributor Jen Glantz.

Enjoying this newsletter and want to recommend it to a friend? Here’s a sign-up link.