Leveraging AI in Camera Monitoring for Improved Technical Support

Leveraging AI in Camera Monitoring for Improved Technical Support

Leveraging AI in Camera Monitoring for Improved Technical Support

The convergence of artificial intelligence with camera monitoring has ushered in a new era of technical support in today’s quickly expanding technological scene. The ability to leverage AI capabilities in analyzing massive volumes of visual data has transformed how industries throughout the world handle technical diagnosis and maintenance.

Let us dig into the critical role that artificial intelligence plays in camera tracking, shedding light on its disruptive potential. As we investigate the incorporation of AI technologies into this sector, we will unearth real-world applications, legal issues, and future trends that are transforming the way technical support is offered, promising increased efficiency, accuracy, and reliability.

How Does AI-powered Camera Monitoring Enhance Technical Support?

AI-powered cameras are critical in technical support because they provide real-time visual insights into complicated systems and equipment. They are a vital tool for remote diagnostics, allowing specialists to diagnose faults, troubleshoot, and guide on-site workers properly. These technology-enabled cameras, when effectively monitored, not only improves efficiency but also decreases downtime, lowers operational costs, and increases safety. It enables technical support teams to proactively handle difficulties, thus promoting smoother operations and maintaining optimal performance across a wide range of enterprises, from manufacturing and medical to retail and beyond.

Key AI Technologies With the Power to Transform CCTV Camera Monitoring

AI has transformed video surveillance by allowing enhanced capabilities that improve security, efficiency, and decision-making. Among the key AI technologies enabling camera monitoring are:

Object Recognition and Tracking

Systems that use advanced AI algorithms can quickly recognize and track objects within live video streams. Modern camera monitoring services rely heavily on object detection and tracking. This technology enables businesses such as manufacturing, healthcare, and security to automate surveillance and improve operational efficiency. Camera monitoring increase safety, decrease response times, and provide crucial insights into real-time activity, providing a vigilant and responsive strategy for security and operations.

Anomaly Detection

A vital aspect of sophisticated data analytics is anomaly detection, which entails identifying odd patterns or anomalies within datasets. This technology, which uses machine learning and statistical algorithms, helps organizations detect abnormalities that may suggest fraud, system failures, or security breaches. Anomaly detection improves decision-making, operational efficiency, and security by automatically detecting irregularities in data streams. It has numerous applications ranging from banking to cybersecurity, ensuring preemptive reactions to possible issues and the integrity of vital systems and processes.

Sentiment Analysis

Sentiment analysis is an NLP technique that evaluates and categorizes the emotional tone, opinions, and attitudes conveyed in text data. It determines whether the attitude behind the text is favorable, negative, or neutral using machine learning techniques. This technology is used in social media monitoring, client feedback analysis, and market research, assisting organizations in understanding customer sentiment, and making data-driven decisions. Organizations may respond to consumer requests, control public opinion, and fine-tune their products and services for increased satisfaction and competitiveness by automating the interpretation of text-based sentiment.

Predictive Maintenance

Predictive maintenance is a data-driven method that forecasts when equipment or machinery is likely to break using advanced analytics, machine learning, and sensor data. Predictive maintenance algorithms can uncover patterns and anomalies that indicate imminent issues by analyzing historical and real-time data. This proactive maintenance method assists organizations in reducing downtime, reducing costly repairs, and optimizing asset performance. It has a wide range of applications in industries such as manufacturing, aviation, and energy, providing effective asset management and cost savings by addressing maintenance needs as they arise rather than on a fixed schedule.

Facial Recognition

Face recognition technology is a cutting-edge use of artificial intelligence (AI) that allows persons to be identified and verified based on face traits acquired by cameras. This game-changing AI tool has numerous uses, ranging from security and access management to customer care in technical support outsourcing services. It improves security standards, speeds up authentication processes, and personalized user experiences by recognizing faces quickly and correctly. Face recognition, while it has potential, creates ethical and privacy concerns, needing careful regulation and responsible application in a variety of sectors.

The Conclusion

In a nutshell, the use of AI in camera monitoring has heralded a new era of technological support and surveillance across a wide range of businesses. These AI technologies, ranging from object recognition to predictive maintenance, have enabled organizations to improve security, operational efficiency, and decision-making. However, it is critical to manage the ethical and privacy implications of these breakthroughs properly. Looking ahead, the continuous advancement of AI in camera monitoring promises even more disruptive possibilities, giving associations the tools, they need to stay competitive, safe, and responsive in an ever-changing world.
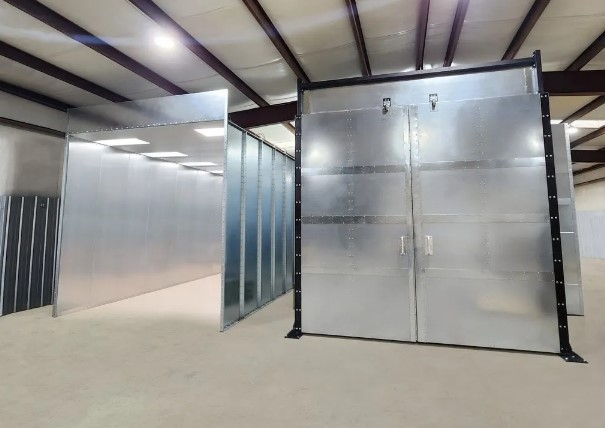
Essential Maintenance Tips for Your Industrial Paint Spray Booth

Essential Maintenance Tips for Your Industrial Paint Spray Booth

Essential Maintenance Tips for Your Industrial Paint Spray Booth

In the realm of manufacturing, an industrial paint spray booth is a pivotal investment that contributes to the quality and efficiency of your operations. To ensure that this essential piece of equipment continues to perform at its best, regular maintenance is crucial. In this guide, we’ll provide you with invaluable maintenance tips to keep your industrial paint spray booth in optimal condition.

1. Cleaning and Inspection

Maintenance begins with the basics – cleaning and inspection. Regularly clean the interior and exterior of your industrial paint spray booth. Use appropriate solvents and cleaning agents to remove paint residue, dust, and debris. Inspect the booth’s walls, filters, and ventilation system for any signs of damage or wear. A clean booth is not only more efficient but also safer for your workers.

2. Filter Replacement

Filters are the workhorses of your industrial paint spray booth. Over time, they become clogged with paint particles and contaminants, reducing airflow and overall performance. To maintain consistent air quality and booth efficiency, replace filters as recommended by the manufacturer. Doing so will also extend the lifespan of your equipment.

3. Monitoring Airflow

Proper airflow is essential for achieving the best paint finish. Regularly check and calibrate the booth’s airflow system to ensure that it meets the required specifications. Adequate airflow helps in the efficient removal of paint overspray, ensuring a clean and even coat on your products.

4. Check for Leaks

Leaks in your industrial paint spray booth can lead to decreased efficiency and compromised safety. Periodically inspect all seams, joints, and seals for leaks. Address any issues promptly to maintain a controlled and safe environment for your employees and equipment.

5. Lighting Maintenance

Good lighting is crucial for quality control during the painting process. Make it a routine to inspect and replace any burnt-out bulbs or damaged lighting fixtures. Proper lighting not only improves visibility but also helps in achieving the desired finish on your products.

6. Electrical and Control Panel Inspection

The electrical components of your industrial paint spray booth play a vital role in its operation. Regularly inspect the control panel, wiring, and electrical connections for signs of wear or damage. Ensure that all safety features and emergency shutdown systems are in good working order to prevent accidents.

7. Training and Documentation

Maintenance is not solely about the physical upkeep of your industrial paint spray booth. It also involves keeping comprehensive records of all maintenance activities, including filter changes, inspections, and repairs. Additionally, invest in training programs for your staff to ensure they understand the equipment’s operation and safety protocols.

In conclusion, proper maintenance of your industrial paint spray booth is essential for the longevity of your equipment, the quality of your products, and the safety of your workforce. By following these essential maintenance tips, you’ll not only extend the life of your booth but also enhance its performance and reliability. Remember, a well-maintained industrial paint spray booth is an investment that pays dividends in the long run, ensuring consistent, high-quality finishes for your manufacturing processes.

Top Qualities to Look for in an Oil and Gas Attorney

Top Qualities to Look for in an Oil and Gas Attorney

Top Qualities to Look for in an Oil and Gas Attorney

When dealing with legal matters related to the oil and gas industry, finding the right attorney is crucial to ensure your interests are protected. An experienced and knowledgeable oil and gas attorney can make a significant difference in the success of your endeavors. If you are in Columbus, Ohio, seeking an oil and gas attorney, this blog post will guide you through the top qualities to look for, helping you make an informed decision.

Expertise in Oil and Gas Law

The first and most fundamental quality to seek in an oil and gas attorney is their expertise in the field. The intricacies of the oil and gas industry demand a specialized understanding of the unique legal issues involved. Look for an attorney who has a strong track record of handling cases in this specific domain. A knowledgeable attorney will be well-versed in local, state, and federal laws that govern the extraction, production, and distribution of oil and gas.

Their Extensive Experience

Experience is a key factor in determining the proficiency of any attorney. An attorney with substantial experience in oil and gas law is better equipped to anticipate challenges, provide effective solutions, and navigate the complexities of your case. Seek out an attorney who has successfully represented clients in a variety of oil and gas-related matters, such as lease negotiations, environmental compliance, and mineral rights disputes.

Local Presence in Columbus, Ohio

Opting for an oil and gas attorney with a local presence in Columbus, Ohio, can be advantageous. Local attorneys are often well-connected with industry professionals and have a deeper understanding of regional regulations and practices. Their familiarity with the local courts and administrative bodies can prove invaluable in expediting legal processes and achieving favorable outcomes.

Strong Negotiation Skills

A top-notch oil and gas attorney must possess exceptional negotiation skills. Whether it’s securing favorable lease terms, resolving conflicts with landowners, or handling contracts with oil companies, the ability to negotiate effectively can significantly impact the success of your ventures. Look for an attorney who can strike a balance between assertiveness and diplomacy to protect your interests while maintaining amicable relationships with other parties involved.

Detail-Oriented Approach

In the oil and gas industry, even the smallest oversight can lead to substantial financial losses and legal complications. Therefore, it is crucial to engage an attorney with a meticulous and detail-oriented approach. They should be capable of reviewing contracts, agreements, and documents with utmost precision, ensuring that your rights and obligations are clearly defined and protected.

Problem-Solving Abilities

Oil and gas projects can encounter various unexpected challenges. An effective oil and gas attorney should possess strong problem-solving abilities to address issues swiftly and efficiently. Look for an attorney with a creative and strategic mindset, who can identify potential roadblocks and devise innovative solutions to mitigate risks.

Client-Focused Approach

A client-focused approach is a hallmark of an exceptional oil and gas attorney. Your attorney should prioritize understanding your specific needs and objectives, tailoring their legal strategies to align with your goals. Effective communication and a willingness to listen to your concerns are essential qualities to look for in an attorney.

Conclusion

Selecting the right oil and gas attorney in Columbus, Ohio, is a critical decision that can significantly impact the success of your ventures. Prioritize qualities such as expertise in oil and gas law, extensive experience, a local presence in Columbus, strong negotiation skills, a detail-oriented approach, problem-solving abilities, and a client-focused approach. By choosing an attorney with these top qualities, you can rest assured that your legal matters will be handled with professionalism and dedication, protecting your interests in the dynamic and challenging oil and gas industry.

Uber Car Accident Claims: Are You Entitled To Financial Support?

Uber Car Accident Claims: Are You Entitled To Financial Support?

Uber Car Accident Claims: Are You Entitled To Financial Support?

If you were an Uber passenger or another accident victim who suffered injuries, you may be entitled to financial support for your treatment costs and other damages. You can submit a claim with the aid of an accomplished lawyer. Your eligibility for a certain amount depends. Other factors also impact liability.

Drivers in Driving Mode

If a driver has a passenger in the car and is logged into the Uber app, Uber’s insurance will begin to pay out. Austin Uber accident lawyer can help victims pursue a full and fair compensation settlement in this case. However, if an Uber driver is on standby or off the clock, they are not insured by Uber. In this scenario, a victim would need to pursue the driver’s auto insurance and their $1 million Uber insurance. Uber accidents are frequently caused by distracted driving. Some drivers use their phones to navigate and communicate with passengers, which can distract them from the road. In addition, some drivers drive recklessly, speeding or weaving in and out of traffic. Injuries in an Uber crash are often serious. It is important to get medical attention right away to document your injuries and ensure you receive the full amount of damages you are entitled to. If contacted by an insurance company, wait to give a recorded statement until you have consulted with an Uber accident lawyer.

Passengers Not in the Vehicle

Some drivers do not have adequate insurance or flee the scene after causing an accident. Uber’s $1 million uninsured motorist policy may cover accident victims’ losses in these cases.

A car accident lawyer can determine the best method of pursuing compensation through this supplemental policy. If non-negligent parties share liability, a lawyer could also seek their payment.

An Uber crash injury can result in costly medical bills, lost wages, and other losses. Batrice Law Firm could pursue maximum compensation for all resulting damages, including pain and suffering.

Many states use shared fault rules that reduce recovery amounts if you are found to be even partially at fault for the accident. An experienced advocate could counter unfair attempts by others involved in the crash to blame you. They can also help you fight to secure maximum compensation from all at-fault parties.

Drivers Not in Driving Mode

Many Uber drivers are distracted while on the job. They use their phones to navigate or communicate with passengers, which takes their attention away from the road and increases their chances of a crash. They may also engage in reckless driving, including speeding or weaving in and out of traffic. Uber’s $1 million coverage will cover any damages up to that amount when an accident victim is hurt due to the negligence of an Uber driver when the driver is logged into the app but not on their way to pick up or carry a customer. This coverage is far greater than the insurance policies of most non-commercial drivers. However, the Uber driver will still need personal insurance to cover their damages, typically including past and future medical care. With the assistance of a knowledgeable Uber accident attorney, victims can pursue financial compensation from the negligent driver and insurance. In some cases, the at-fault driver’s insurance will deny a claim when it becomes necessary to file a lawsuit against Uber for vicarious liability.

Passengers in the Vehicle

As a passenger, you can make an Uber accident claim for injuries you suffer when an Uber driver is at fault. However, the insurance companies of both Uber and the driver will work hard to pay as little as possible in your case. Generally, passengers are only held liable in unusual circumstances. Even so, a crash could cause soft-tissue injuries like whiplash that might not appear until days or weeks after the accident. It is why seeking medical attention immediately following an accident is essential. If you are injured in an accident involving an Uber vehicle, contact your local attorney for advice right away. It’s important to speak with Uber or the at-fault driver’s insurance company only after you’ve consulted your lawyer. Anything you say could be used against you later and affect your chances of recovering the full damages you are entitled to. Always take photographs of the scene and your injuries, and keep all your medical treatment records.

Everything you need to know about insurance for small businesses

Everything you need to know about insurance for small businesses

Many small businesses and startups operate on limited financial resources, so it can be tempting for them to sometimes skip certain coverages, especially if these are not mandated by the law.

But these enterprises also often face many situations that require them to take a leap of faith. While such circumstances present exciting opportunities for growth, they can also expose businesses to unexpected risks – and when these risks do happen, it pays for companies to have some form of financial cushion.

Insurance for small businesses provides financial protection from unfortunate scenarios that could have otherwise cost enterprises thousands, if not millions of dollars, making it difficult for them to recover. Having the right policies in place plays a crucial role in helping companies get back on their feet faster.

Another benefit of carrying proper coverage is that it helps bolster a company’s reputation and credibility as customers often prefer working with businesses that they know are protected financially.

Taking out insurance, however, is just one facet of how small businesses can minimize their losses. Pairing insurance coverage with good risk management practices is among the best ways companies can protect their assets and finances.

Because each small business faces a different set of risks and challenges, there is no one-size-fits-all small business insurance policy that can cater to every need. The type of coverage a company requires is based on an assortment of factors, including the nature of the business, the industry it operates in, and the number of employees.

Small business insurance providers offer a range of policies that can help protect companies against the different risks they face. The selection is diverse, but according to industry experts, these are some of the most essential types of policies that businesses need to maintain their operations when accidents and calamities strike.

1. General liability insurance

General liability insurance is one of the most important coverages that small enterprises need, according to the US Small Business Administration (SBA). Sometimes referred to as business liability or public liability coverage, it protects companies against claims of bodily injury or property damage resulting from their business activities. Policies also provide coverage for claims of reputational damage, including libel, slander, and copyright infringement.

Small businesses do not receive compensation for this type of coverage, instead the payouts are given to the affected third party. Without general liability insurance, companies will need to pay for the claims out of pocket.

2. Professional liability insurance

Professional liability coverage protects small businesses from work-related claims. These include:

    • Inaccurate advice
    • Misrepresentation
    • Negligence
    • Personal injury such as libel or slander

Also called errors and omissions (E&O) or malpractice insurance, it covers legal and settlement costs arising from service-related mistakes and oversights, breach of contract, unfinished work, and budget overruns, among others.

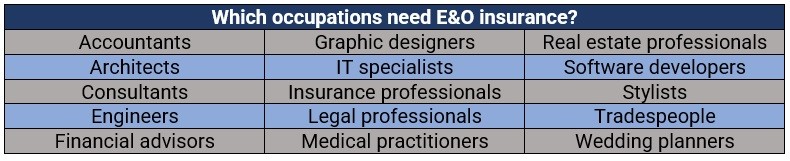
Professional liability insurance covers all of a business’s staff and the company itself. Although not always legally required, having this form of coverage is essential for many small enterprises, especially for those that provide expert or advisory services. The list includes:

  occupations that may need E&O insurance

3. Product liability insurance

Product liability coverage may be worth considering for companies that sell products. This type of insurance for small businesses protects them against lawsuits from customers claiming losses or injury because of the product. It also covers legal defense costs and compensation if the business is found to be at fault.

4. Commercial property insurance

Designed to minimize disruption to a small business’s day-to-day operations, commercial property insurance provides compensation for damages or losses that happen to the following:

    • Property or building the company operates in
    • Equipment and technology the small business uses
    • Inventory of products and materials the company stores and sells

Some policies also pay out a portion of lost income if the damage prevents the business from conducting its usual operations. Also referred to as business property or commercial building insurance, this type of coverage is often a requirement in commercial leasing arrangements.

5. Commercial auto insurance

Commercial auto insurance is a type of car policy designed for vehicles driven for business purposes. In terms of protection, it works similarly to personal auto insurance but covers mainly company cars and commercial trucks and vans. Coverage typically includes:

    • Bodily injury liability: Covers injuries the driver causes another person and legal fees if they are sued over the accident.
    • Property damage liability: Pays out if the business’s vehicle damages another person’s property and legal defense costs incurred in a lawsuit.
    • Combined single limit (CSL) liability: Provides an overall limit for bodily injury and property damage claims against the business rather than having two separate limits.
    • Personal injury protection (PIP): Covers medical expenses for the driver and the passengers resulting from accidents covered by the policy. In the US, PIP is mandatory in no-fault insurance states.
    • Collision insurance: Pays for damage to the commercial vehicle if it collides with another car or object.
    • Comprehensive insurance: Provides coverage for damage to the commercial vehicle, resulting from fire, flood, theft, vandalism, and other covered perils.
    • Uninsured motorist (UM) coverage: Pays out for injuries the driver and their passengers sustain if they are hit by an uninsured driver or get involved in a hit-and-run accident.
    • Underinsured motorist (UIM) coverage: Covers medical expenses incurred when the driver or passengers of a commercial vehicle are hit by someone whose policy is not enough to cover all the costs.

Some states in the US allow commercial vehicle drivers to purchase UM and UIM coverage separately. They can also find business-specific coverage, including those for lost business income.

6. Workers’ compensation insurance

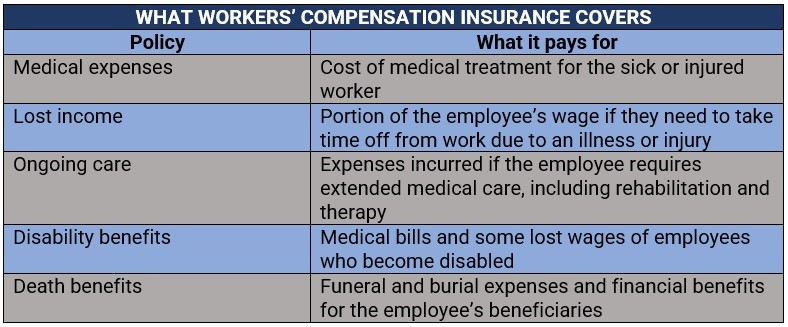
Small businesses with at least one staff member are required to take out workers’ compensation insurance. This pays out the cost of medical care and part of the lost income of employees who get sick or injured while performing their jobs. It also protects small businesses from the financial liability of having to pay for expenses stemming from work-related illnesses and injuries out of pocket.

Workers’ compensation insurance provides different types of protection summarized in the table below.

  what workers’ compensation insurance covers

7. Health insurance

Businesses that employ more than 50 full-time staff in the USA are required to take out health insurance for their workers, according to the Affordable Care Act (ACA), and most countries have a standard number for this. For those with less than 50 employees, the ACA offers a Small Business Health Options Program (SHOP) as coverage.

Health insurance providers offer basic healthcare coverage to small businesses, along with other services that can include Medicaid and Medicare policies, long-term care insurance, dental coverage, and vision benefits. In the US, the top 10 private health insurance companies control almost two-thirds of the market.

8. Business interruption insurance

Business interruption insurance is designed to protect companies against financial losses incurred from the disruption of their operations resulting from an insured peril. Also referred to as BI or business income coverage, it pays out the operating costs while the business temporarily shuts down. These include:

    • Potential revenue
    • Mortgage or rent on commercial space
    • Business loan repayments
    • Employee salaries
    • Taxes

Some BI policies also provide coverage for additional expenses related to the closure such as the cost of setting up a temporary location or the training of staff to use new equipment.

9. Cyber insurance

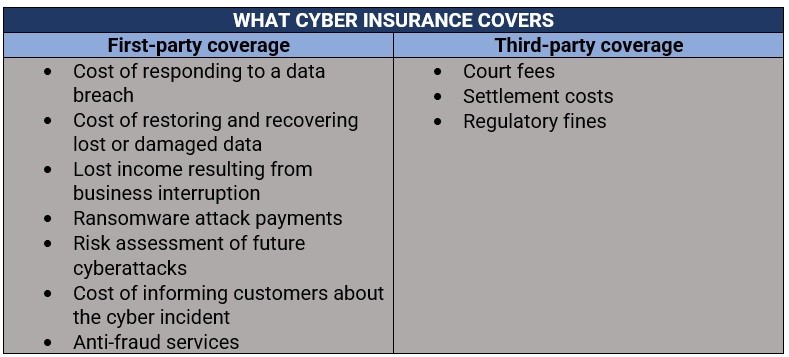
The purpose of cyber insurance is to protect small businesses against financial losses resulting from cyber incidents. Policies typically provide two types of protection:

    1. First-party coverage: Pays out for the financial losses the business incurs due to a cyber incident.
    1. Third-party coverage: Provides financial protection against lawsuits filed by third parties – including customers, employees, and vendors – for damages caused by a cyberattack on the business. Here’s a summary of what these policies cover.

 what cyber insurance covers

Learn simple and practical ways in which you can protect your small business against cyber threats in our cybersecurity guide.

10. Business owners’ policy (BOP)

Designed for small and mid-size businesses, BOP bundles different insurance policies that companies need, including:

    • General liability insurance
    • Commercial property insurance
    • Business interruption insurance
    • Workers’ compensation insurance

Some insurers allow small businesses to add coverage at a corresponding cost depending on their needs. BOP also provides a less expensive alternative to buying different business insurance policies separately.

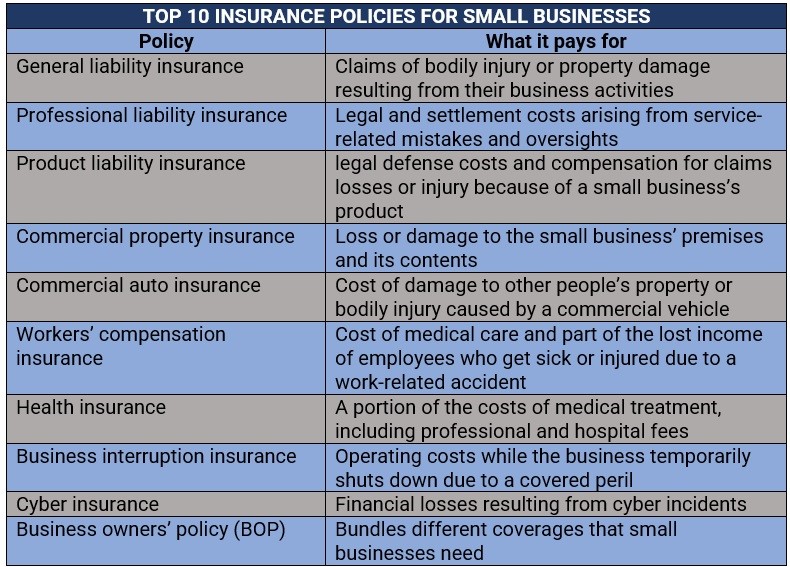
Here’s a summary of the different insurance policies that owners may want to consider to protect their small businesses financially when accidents and disasters occur.

 top 10 insurance policies for small businesses

Because the coverage provided by each policy varies greatly, there is also a huge difference between the factors dictating premium prices for each type of small business insurance.

Rates for professional liability coverage, for example, are calculated using the following parameters:

    • The industry and the risks associated with it
    • Where the business is located
    • Coverage limits and deductibles
    • Years of operation
    • Number of employees
    • Past claims

According to data gathered by Insureon, an independent insurance marketplace for small businesses, the median cost of professional liability premiums is $59 per month or about $713 annually. The firm added that more than half of its small business clients allocate between $500 and $1,000 each year for E&O coverage. About a fifth spend less than $500.

For general liability coverage, customers pay a median premium of $42 per month, or about $500 annually, regardless of policy limits.

Commercial property insurance for small businesses

Commercial property insurance premiums, meanwhile, are influenced by the following factors:

    • Age of the property: Rates for older buildings are higher than those for newer commercial spaces as the latter often incorporate modern safety features.
    • Location: Commercial properties in regions that have had a large number of claims are often expensive to insure.
    • Size of the building: Bigger commercial properties typically have higher premiums as these are more costly to rebuild and repair.
    • Equipment and machinery: Insurance rates for businesses using specialized equipment are more expensive as this may be difficult to replace. For the same reason, companies with older, outdated machinery get higher premiums as well.
    • Safety and security measures: Having closed-circuit television (CCTV), monitored alarms, security patrols, deadlocks, and reinforced entry points can help a business bring down premiums.
    • Total value of contents: Premiums are also dependent on how much equipment, fixtures and fittings, furniture, and stock inside a commercial property are worth.

Workers’ compensation insurance for small businesses

For workers’ compensation, the premium determinants include:

    • The type of industry
    • Job classification codes, which can reflect the riskiness of the work employees do
    • Experience modification rating, which is determined using the company’s payroll and past workers comp claims
    • Safety measures implemented in the workplace

Small businesses pay an average of $47 monthly, or about $560 annually for coverage, according to an estimate by Trusted Choice, a Virginia-based network of insurance agents and brokers.

Cybersecurity insurance premiums, meanwhile, are determined by the size, nature, and location of the business. Data gathered by the small business information resource website AdvisorSmith shows that the average cost of cyber insurance in the US is about $1,589 per year or $132 per month.

Because of the crucial role insurance plays in protecting a small business, industry experts advise companies to shop around and compare options from multiple providers to make sure that they get the protection they need at the best possible price. Here are the key criteria that specialists say small businesses must consider when choosing the right insurance policies:

    • Coverage options: Many policies look similar across insurers in terms of which perils will or will not be covered. Small businesses should ask their insurance providers about adding or extending coverages to suit their business needs.
    • Policy limits: Businesses should make sure that the limit of each insurance policy can cover the full value of the protection they require.
    • Premiums and deductibles: Experts warn small businesses against choosing the cheapest available policy, which could cost them tens to hundreds of thousands – potentially even millions in the long run. Companies should look for policies with premiums and deductibles that offer the best value for the amount of coverage and the relative level of risk facing their businesses.
    • Claims reporting: Businesses should also make sure that they can navigate the claims process easily to minimize financial losses and disruptions to their operations. The process is often laid out in the product disclosure statement of the policy.
    • Company reputation: Businesses should look for insurance providers with a good track record for customer satisfaction and fair business practices.
    • Financial stability: Companies should make sure that their insurer is in good shape financially to cover claims that may arise.

Are you a small business owner searching for the right coverage? What policies do you think are essential for small businesses? Share your thoughts in the comments section below.

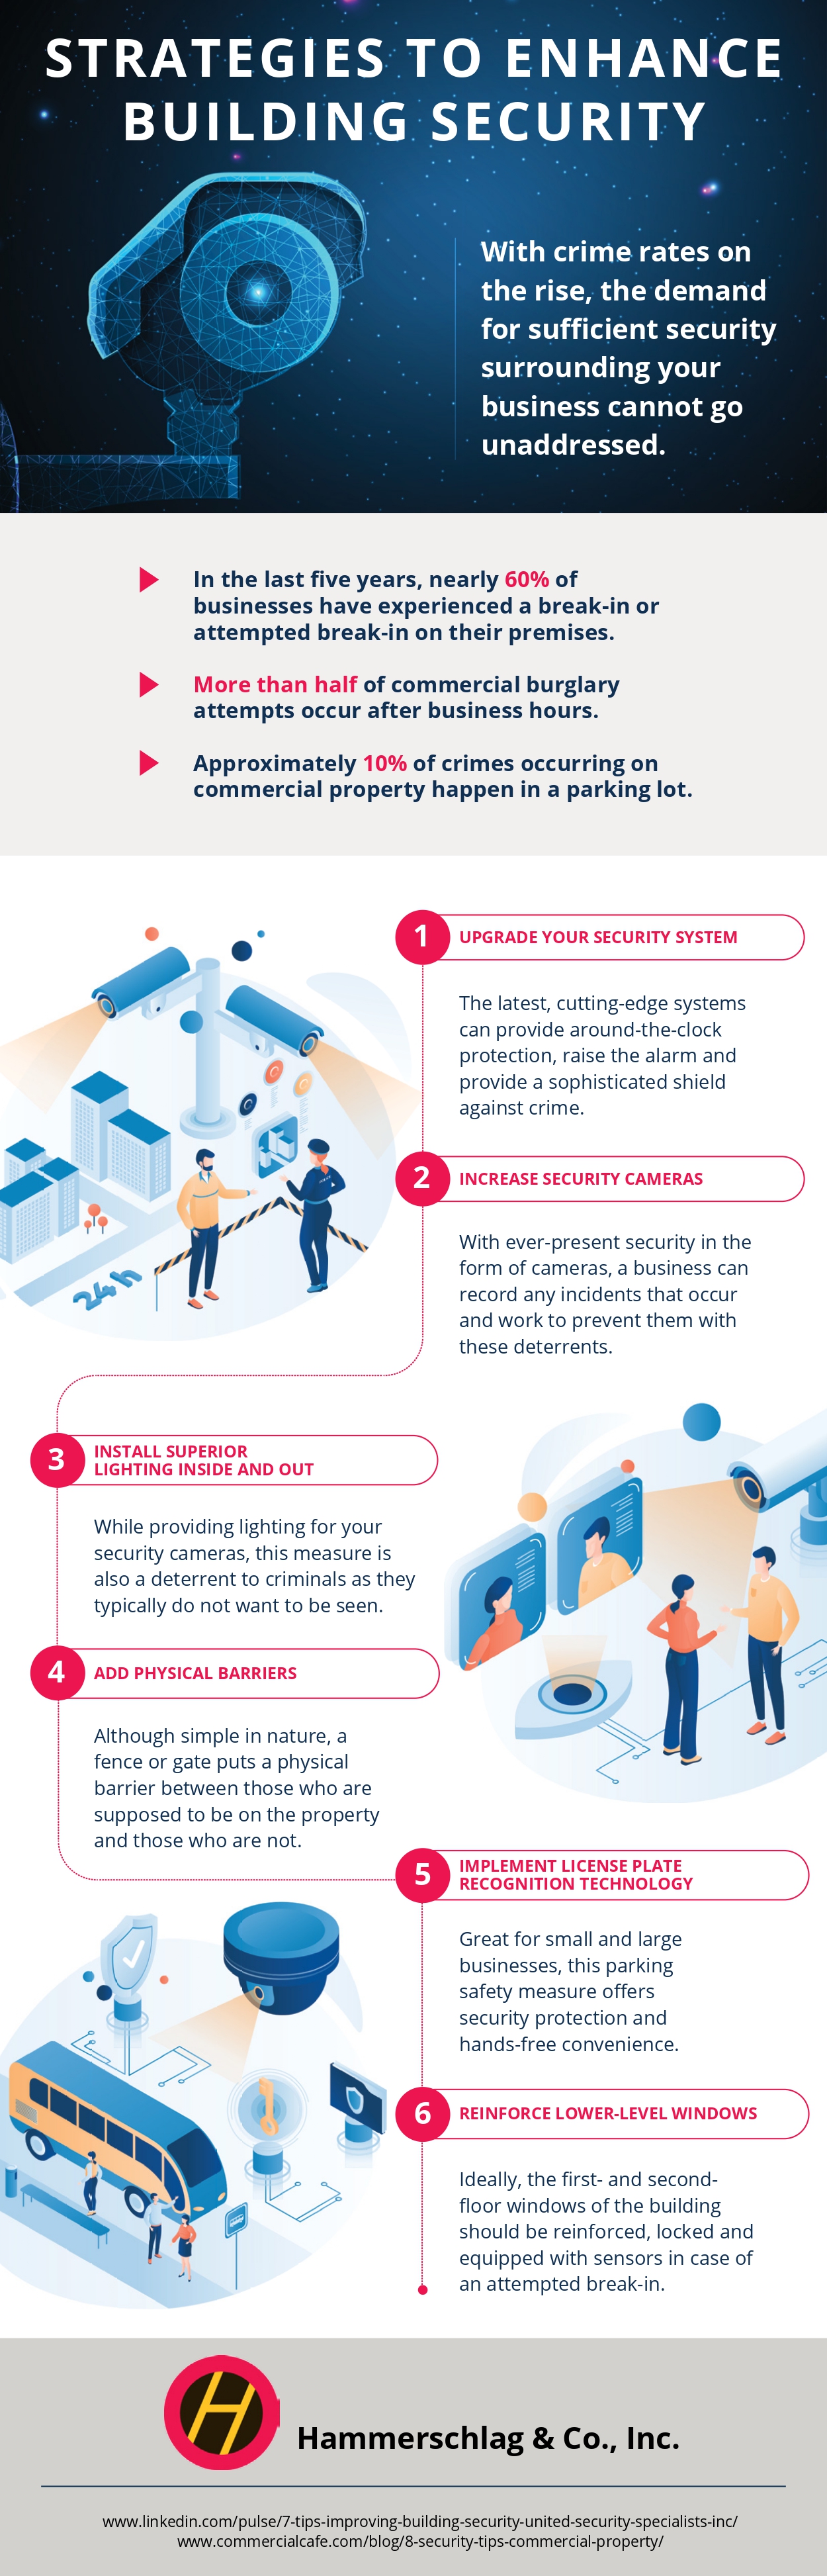
Don’t solely rely on insurance to protect your business. Please see the resource below for proactive measures you can take to secure your business and prevent crime.


parking expert witness

Provided by Hammerschlag & Co., Inc. – a parking expert witness

Pet Care Insurance

Pet Care Insurance

Pet Care Insurance

Pet care insurance is a valuable investment for pet owners who want to ensure the well-being of their furry companions. Just like human health insurance, pet care insurance provides financial protection and peace of mind by covering unexpected veterinary expenses. In this article, we will explore the concept of pet care insurance, its benefits, how it works, tips for choosing the right policy, common misconceptions, and whether it’s worth the investment.

Understanding Pet Care Insurance

What is pet care insurance? Pet care insurance is a type of insurance policy that helps pet owners manage the costs of veterinary care. It typically covers expenses related to accidents, illnesses, and sometimes preventive care, depending on the plan.

Coverage options and plans Pet care insurance policies vary in terms of coverage options and plans. Some policies provide basic coverage for accidents and illnesses, while others offer comprehensive coverage that includes preventive care, prescription medications, and even alternative therapies.

Factors to consider when choosing pet insurance When selecting a pet care insurance policy, there are several factors to consider. These include the age and breed of your pet, any pre-existing conditions, the policy’s coverage limits and exclusions, waiting periods, deductibles, and premiums.

Benefits of Pet Care Insurance

Financial protection for unexpected veterinary expenses One of the key benefits of pet care insurance is the financial protection it offers pet owners. Veterinary treatments can be costly, especially for major procedures or emergency care. With insurance coverage, pet owners can have peace of mind knowing that they have a safety net in case of unexpected expenses.

Peace of mind for pet owners Pet care insurance provides peace of mind to pet owners by alleviating concerns about the financial burden of veterinary care. It allows pet owners to focus on providing the best possible care for their pets without worrying about the cost implications.

Access to quality healthcare for pets With pet care insurance, pet owners can afford to give their pets the necessary medical attention without hesitation. This ensures that pets receive timely and appropriate healthcare, improving their overall quality of life and potentially extending their lifespan.

How Pet Care Insurance Works

Claim process and reimbursement When a pet needs veterinary care, the pet owner pays for the treatment upfront. They then submit a claim to the insurance provider, including the necessary documentation and receipts.

The insurance provider reviews the claim and determines the eligible reimbursement amount based on the policy terms and coverage. Once approved, the pet owner will receive reimbursement for the covered expenses.

Pre-existing conditions and waiting periods It’s important to note that most pet care insurance policies do not cover pre-existing conditions. These are medical conditions that existed before the insurance policy was purchased. Additionally, many policies have waiting periods, which means there is a specific period of time after purchasing the policy during which certain conditions or treatments are not covered.

Deductibles and premiums Pet care insurance policies often have deductibles, which are the amount the pet owner must pay out of pocket before the insurance coverage kicks in. Higher deductibles generally result in lower monthly premiums, while lower deductibles may come with higher premiums. It’s crucial to consider the deductible amount and the corresponding premium when choosing a policy.

Choosing the Right Pet Care Insurance

Researching and comparing insurance providers To find the right pet care insurance, it’s essential to research and compare different insurance providers. Look for reputable companies with a history of good customer service and positive reviews. Compare the coverage options, policy terms, and pricing to find the best fit for your pet’s needs.

Evaluating coverage options and exclusions Carefully review the coverage options and exclusions of each policy you consider. Pay attention to specific conditions, treatments, or procedures that may not be covered. Understand the limits of coverage for different types of treatments, medications, and surgeries.

Reading customer reviews and ratings Reading customer reviews and ratings can provide valuable insights into the experiences of other pet owners with specific insurance providers. Look for feedback on the ease of the claims process, customer service, and overall satisfaction with the coverage.

Common Misconceptions about Pet Care Insurance

Myth 1: Pet insurance is too expensive While pet care insurance does involve a monthly premium, it can actually save pet owners money in the long run. The cost of unexpected veterinary care, especially for serious illnesses or accidents, can be much higher than the accumulated insurance premiums.

Myth 2: All pets are eligible for coverage Not all pets are eligible for coverage, especially those with pre-existing conditions. It’s important to check the eligibility requirements of the insurance policy and understand any restrictions based on age, breed, or existing health conditions.

Myth 3: Pet insurance covers pre-existing conditions As mentioned earlier, pet insurance typically does not cover pre-existing conditions. It’s crucial to be aware of this limitation and consider purchasing insurance when your pet is young and healthy to maximize coverage.

Tips for Maximizing Pet Care Insurance Benefits

Regular veterinary check-ups and preventive care By scheduling regular veterinary check-ups and following preventive care measures, such as vaccinations and parasite control, you can potentially avoid costly treatments for preventable conditions. This can help keep your pet healthy and reduce the need for extensive medical interventions.

Understanding policy limits and exclusions Read the fine print of your pet care insurance policy to fully understand the coverage limits and exclusions. Be aware of any waiting periods, specific conditions not covered, and the maximum payout for different types of treatments.

Maintaining accurate medical records for your pet Keeping detailed medical records for your pet is essential when filing insurance claims. Maintain a record of vaccinations, treatments, surgeries, and any other relevant medical information. This documentation will help expedite the claims process and ensure accurate reimbursement.

Is Pet Care Insurance Worth It?

Deciding whether pet care insurance is worth the investment depends on several factors. Consider the breed and age of your pet, their predisposition to certain health conditions, and your financial situation. While insurance does involve monthly premiums, it can provide financial security and peace of mind, especially in the case of unexpected emergencies or

costly medical treatments. It’s important to weigh the potential savings and benefits of having insurance against the monthly premiums.

When calculating the cost-benefit analysis, consider the average veterinary expenses for your pet’s breed, the likelihood of accidents or illnesses, and the potential need for specialized care or surgeries. By assessing these factors, you can make an informed decision about whether pet care insurance is worth it for your specific situation.

Ultimately, pet care insurance can provide a safety net and alleviate financial stress when it comes to your pet’s healthcare needs. It allows you to focus on providing the best care for your furry friend without worrying about the cost implications.

Conclusion

Pet care insurance offers valuable financial protection and peace of mind for pet owners. By understanding the concept of pet insurance, its benefits, how it works, and factors to consider when choosing a policy, you can make an informed decision. Despite common misconceptions, pet insurance can be a worthwhile investment, providing access to quality healthcare for your pet and potential long-term savings. Remember to research and compare different insurance providers, evaluate coverage options and exclusions, and maintain accurate medical records for your pet’s benefit.

FAQs (Frequently Asked Questions)

Q1: Is pet care insurance expensive? A1: The cost of pet care insurance varies depending on factors such as the pet’s age, breed, and the coverage options selected. While there is a monthly premium, it can be offset by potential savings on unexpected veterinary expenses.

Q2: Can pet insurance cover pre-existing conditions? A2: Pet insurance typically does not cover pre-existing conditions, which are medical conditions that existed before the insurance policy was purchased. It’s important to review the policy terms and understand the limitations.

Q3: How does the claim process work with pet care insurance? A3: The claim process usually involves paying for veterinary care upfront and then submitting a claim to the insurance provider. After review and approval, eligible expenses are reimbursed according to the policy terms.

Q4: Are all pets eligible for pet care insurance? A4: Not all pets are eligible for coverage, especially those with pre-existing conditions. Eligibility requirements may vary depending on factors such as age, breed, and existing health conditions.

Q5: Can pet care insurance help with preventive care? A5: Some pet care insurance policies offer coverage for preventive care, including vaccinations and regular check-ups. However, the extent of coverage varies, so it’s important to review the policy details to understand what is included.

Partner Site : SEO Services, Movie News, Real Estate News, Business News Today, Hot News Today, Get Auto Repair, Business Franchise, News Technology, Fashion Sports Shoes, Health News