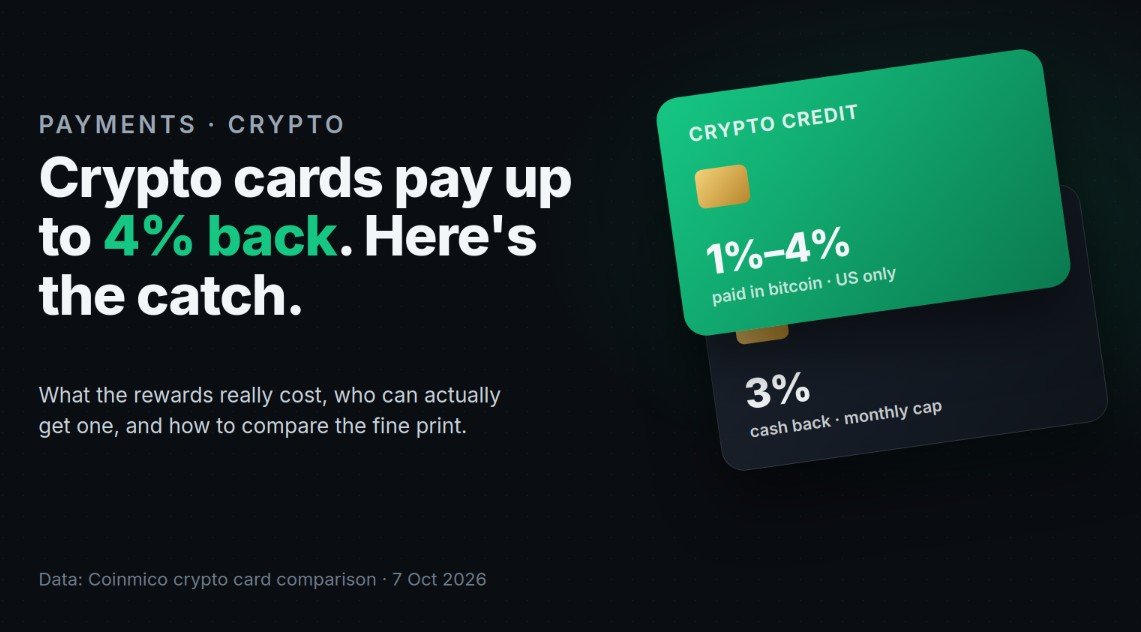
The adverts are hard to miss: a sleek metal card,”up to 4% back in bitcoin”, and a promise that your morning coffee is quietly building a crypto portfolio. As someone who pays for most things by card and is naturally suspicious of anything with “up to” in it, I spent an afternoon comparing a dozen of these cards. The rewards are real. So are the conditions.
How a crypto card actually works
Despite the name, a crypto card does not usually spend crypto at the till. Most are ordinary Visa or Mastercard debit cards linked to a balance at a crypto exchange or wallet; when you pay, the issuer converts your crypto or stablecoins to the local currency behind the scenes, and the shop receives money as normal. A few are genuine credit cards with a monthly bill. The “crypto” part is mainly the reward: instead of air miles or cash back, you get a slice of bitcoin or another token.
The headline rates
Looking across the market, the strongest rewards cluster between 1 and 4 per cent. Gemini’s credit card pays 1 to 4 per cent by spending category, in bitcoin or a choice of 50-plus assets, with no annual fee. Coinbase’s card pays 2 to 4 per cent in bitcoin. ether.fi’s debit card pays a flat 3 per cent cash back, capped monthly. MetaMask’s card pays 1 per cent on the free virtual version and 3 per cent on a metal card. For comparison, a good conventional cashback card pays 1 to 2 per cent, so on paper the crypto cards win comfortably.
The catches
This is where the afternoon went.First, geography: the two highest-paying cards are available in the United States only, several others are restricted to the European Economic Area or the UK, and MetaMask has closed sign-ups in the US and UK entirely. Second, the hidden price of entry: Coinbase’s card requires a paid membership from $49.99 a year, and Nexo’s cashback programme only applies once you hold more than $5,000 of its token. Third, the metal: MetaMask’s 3 per cent tier costs $199 a year, which you need to spend around $10,000 annually just to earn back. Fourth, and most overlooked, the reward is paid in a volatile asset. Four per cent in a token that falls 30 per cent is less than 3 per cent; four per cent in bitcoin during a good year is a great deal more. You are being paid in a lottery ticket, which is either the point or the problem depending on your temperament.
How I ended up comparing them
The thing that saved me from a dozen browser tabs was a comparison table on Coinmico, an independent crypto market data site, which scores each card on reward, cost, regional availability and whether you hold the money yourself or the issuer does. Usefully, it reads the numbers from each issuer’s own terms page and prices the reward tokens on the site’s own market index, so the “4%” is shown as what it is actually worth today. Its current top three are Gemini (8.3 out of 10), Coinbase One (8.1) and ether.fi (7.7).
The verdict for a business or a busy person
If you live in the right country, already hold crypto, and would rather be paid in bitcoin than in pennies, a crypto card is a genuinely better deal than a standard cashback card. If you do not, the fine print eats most of the difference. Either way,the comparison takes ten minutes on the best crypto cards page,and it is ten minutes better spent than on the adverts.
Credit rating playing cards vs. debit cards — what is actually the variation? Which kind of plastic is ideal for you? Personal finance professionals perennially disagree on which type of plastic delivers additional gain but the final decision should be dependent on a cardholder’s method to hazard and capability to manage credit card debt, as effectively as the sort of acquire being produced. Being aware of how every single card operates can assist you use the most effective card for your circumstance.
Credit rating cards vs. debit cards: What’s the variation?
The key variation among debit cards and credit rating playing cards lies in how the merchant is paid.
Debit playing cards Debit playing cards attract cash from your checking account, when credit score cards rely on cash that the credit rating card corporation has loaned you.
Subscribe to Kiplinger’s Private Finance
Be a smarter, improved educated trader.
Conserve up to 74{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}
Indication up for Kiplinger’s Totally free E-Newsletters
Income and prosper with the best of specialist guidance on investing, taxes, retirement, individual finance and additional – straight to your e-mail.
Profit and prosper with the best of expert advice – straight to your e-mail.
Debit playing cards are linked to checking accounts. When you make a order income you previously have is deducted, typically in just 24 hours. How much you are ready to spend utilizing a debit card depends on how much funds you have in your account. If you invest over that quantity, your card could be declined or you could be charged an overdraft fee.
Credit history playing cards On the other hand, credit cards allow for you to make purchases by drawing on a line of credit history. How a great deal you’re able to devote with a credit score card depends on what your credit limit is. You will not be capable to exceed this quantity. Any buys you make utilizing a credit card are additional to your monthly bill, with a bare minimum payment (commonly a percentage of that complete bill) thanks each individual billing cycle. However, if you shell out as well significantly and fail to fork out off your credit score card every thirty day period, you could land in credit card debt and accrue interest.
An additional major big difference in between credit score and debit playing cards is the chance to generate rewards. For numerous, the enchantment of a credit rating card is linked to the truth that by purchasing with them you can generate dollars again, details and/or airline miles. In addition, credit card perks often include prolonged warranties and purchase protections, relying on the sort of credit card.
Hold in thoughts that some merchants will involve you to use a credit history card. For illustration, if you happen to be picking up a rental vehicle you can possible have to have a credit card, and Airbnb only allows you shell out with debit cards that can be processed as credit score playing cards.
Furthermore, credit playing cards influence your credit rating, although debit playing cards do not.
Which card provides most protection?
Debit card protections
In the scenario of fraudulent activity on your debit card, you’ll be protected by the Digital Money Transfer Act (opens in new tab)(EFTA).
In accordance to this law, if your debit card will get shed or stolen, you are going to only have two enterprise times to report it to the financial institution for your fraud liability to be $50. If you report right after two days — but prior to 60 times — your liability will be $500. Notifying the bank after 60 days indicates you could be liable for all transactions.
Credit rating card protections
Credit score cards supply a little bit more defense, thanks to the Fair Credit Billing Act (opens in new tab). If you observe any fraudulent transactions on your credit card, you’ll only be liable for up to $50. In addition, lots of credit history playing cards present more purchase and rental protections as well as prolonged warranties on transactions designed with the card.
Though both of those debit cards and credit rating playing cards present fraud security on your account, credit rating cards typically give greater protection. Both equally credit and debit accounts are monitored for any suspicious transactions, and your card issuer will notify you if any transactions seem off.
On the other hand, opting for your credit history card is normally the safer alternative. If there’s fraudulent shelling out on your credit score card, your money will continue to be safe and sound in your checking or discounts account. On the other hand, if a fraudster spends cash on your debit card, you’ll be out of income until eventually you can get the expenses reviewed.
When to use a credit card
Here’s when you’d be far better off applying a credit rating card to make buys.
When you are on line browsing: Get advantage of fraud legal responsibility protections supplied with credit rating cards when earning online buys. If there is any fraudulent action on your credit score card account, it’s not “your” funds to get again, but fairly the card issuer’s. Your personal funds will however be protected in your examining or price savings accounts.
If you’re wanting to build credit score: If you’re on the lookout to raise your credit score score or build your credit history record, applying a credit card is typically a superior option. By displaying a heritage of steady, on-time payments, you will be capable to do just that. Plus, there are many playing cards geared toward people today with undesirable credit or no credit history background that efficiently functionality as a debit card, contemplating you are going to have to put down a money advance that functions as your credit score restrict. Right here are the finest credit history cards for undesirable credit history.
When you want to gain benefits: Applying a benefits credit score card can be an straightforward way to make cash back again or rewards points on the purchases you happen to be by now generating. Some cards have a flat-price funds back benefits price, when other folks provide better factors on purchases built in precise paying types. In addition, lots of credit score playing cards appear with other further gains, like buy protections, extended warranties and no cost checked baggage.
When to use a debit card
When you’re at the ATM: If you require to withdraw income, you ought to use your debit card. If you use an ATM that is in-network, withdrawing money is absolutely free. On the other hand, if you use a credit history card to get out income at the ATM, you will be charged desire on the transaction as it’s regarded as a dollars progress. And though using an out-of-community ATM with your debit card will commonly charge a charge, it’s very likely even now cheaper than making use of a credit card. You can also stay clear of the ATM altogether by procuring with a debit card someplace that can give dollars back again.
If you need to prevent financial debt and interest: If you’re wanting to steer clear of overspending and in convert using on personal debt, you should adhere to applying your debit card. This way, you won’t be tempted to run up a harmony that you can not spend off in full each month. If you never carry a equilibrium, you also won’t incur any desire prices which can be pricey.
The credit rating card types on creditcardGenius have expanded to greater signify Canadian company homeowners. The 3 new categories are:
moneyGenius ranks more than 36 groups, doing the job relentlessly to come across the most trusted and worthwhile fiscal merchandise that could help you save (and gain) Canadians the best amount of dollars probable.
Painstakingly analyzed using a refined math-based algorithm or element-primarily based ranking process, the reliable rankings are bolstered by an at any time-escalating hard cash again system named GeniusCash. The initiative was released with an unparalleled Tesla giveaway, formally handed off to Tony Yip in November.
Continuing the spirit of providing again, moneyGenius has a short while ago launched the Mountain Of Prizes giveaway, with multiple tiers of prizes well worth about $20,000.
“Private finance education is only acquiring much more significant as Canadians wrestle in the facial area of a tricky economy,” claimed Stephen Weyman, Co-Founder of moneyGenius and creditcardGenius. “Our objective is to supply readers with unbiased, dependable data and reward them for taking control of their finances. We hope to give back even far more in 2023.”
Sneak peek of the very best credit card and personalized finance winners:
Category
Winner
Best Cash Back again Credit rating Card
Amex SimplyCash Most well-liked
Most effective Equilibrium Transfer Credit rating Card
Reliable by above 320,000 viewers and subscribers just about every month, WeyMedia is a main Canadian individual finance firm that delivers nicely-investigated written content and economic resources to the every day customer. moneyGenius was introduced in 2010 to provide Canadians with the instruments to make each dollar count, and creditcardGenius was released in 2017 to generate the only credit card matchmaker that right away compares 126+ attributes of almost 200 Canadian credit cards. Their hard cash back rewards system, named GeniusCash, gives money back for everyone applying and accredited for featured products.
Media contact: Nikita Garner 1-506-305-6866 nikita@moneygenius.ca
Insider’s experts choose the best products and services to help make smart decisions with your money (here’s how). In some cases, we receive a commission from our our partners, however, our opinions are our own. Terms apply to offers listed on this page.
Travel insurance and some credit cards can protect you from financial loss while traveling.
Travel insurance offers more comprehensive coverage that protects you on one or multiple trips.
Credit cards may cover trip cancellations, lost bags, and other events during trips booked with your card.
Anything can happen while traveling. Flight delays, lost luggage, or even unexpected injury or illness. When these things occur, travel insurance or the travel protections included with your premium credit card may be able to help, providing medical coverage, offsetting your financial losses, or even reimbursing you fully.
But do you need both travel insurance and credit card travel protections? Here are details on both and tips for deciding which one is right for your trip.
Travel insurance vs. credit card travel protections: At a glance
Many credit cards offer travel protections that can help you in certain unexpected travel situations. But they aren’t exactly the same as a separate travel insurance policy.
Here’s how the two differ at a high level:
Travel insurance: Travel insurance is coverage that you purchase either for a single trip or for multiple trips in a year. It typically covers the costs associated with a trip cancellation, trip delay, medical emergency, and certain other unforeseen events that may occur while traveling.
Credit card travel protections: These are benefits automatically included with certain consumer credit cards. They often provide coverage for delays, lost baggage, rental car collisions, and other events during travel. Sometimes credit cards advertise these protections as a type of travel insurance, though they’re not actually a separate insurance policy.
Generally speaking, designated travel insurance is more exhaustive than the protections offered by a credit card. Still, it’s worth it to compare both options, particularly if you’re taking an expensive trip.
“It is always wise to check your credit card protection against a travel insurance plan,” says Carol Mueller, a vice president at Berkshire Hathaway Travel Protection. “Credit card protection may not include the full, bundled, comprehensive coverage a travel insurance plan would.”
What is travel insurance?
Travel insurance protects you from financial losses related to travel. “There are three main areas of coverage: Protecting yourself, protecting your personal items, and protecting your investment,” says Christina Tunnah, general manager of Americas and global marketing at World Nomads, a travel insurance and safety services provider.
Travel insurance works much like any other insurance policy. When a covered event occurs, like your trip is canceled or you’re hurt while traveling, you file a claim with your insurer. If it’s accepted, the company reimburses you for the costs up to your coverage limits.
“Most people have no idea that their health insurance does not cover them abroad,” says Shane Mahoney, founder of Lugos Travel, a travel advisory. “So, a broken arm from a slip and fall or a heart attack can be financially devastating.”
There are single-trip travel insurance policies and annual travel insurance plans, which cover all of your trips within a 12-month period. According to Meghan Walch, director of product for insurance comparison site InsureMyTrip, single-trip policies tend to cost between 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your total prepaid, nonrefundable trip costs. So, on a trip that costs you $10,000 to book, you’d pay around $400 to $1,000 for insurance, depending on which coverages you want.
Aside from the extra cost that comes with travel insurance, the main difference between these policies and credit card protections is that an insurance policy will typically cover emergency medical expenses and the costs of evacuating the traveler for necessary medical care.
“Some travel insurance policies also provide epidemic coverage endorsements, which provide coverage to customers who become ill with COVID-19 or a future epidemic, are individually ordered to quarantine, or are denied boarding due to a suspected illness,” says Daniel Durazo, director of external communications at Allianz Partners, a travel insurance provider.
Separate travel insurance policies also tend to offer more robust cancellation coverage. In many cases, credit card protections cap reimbursement at just $10,000 a trip, while travel insurance often goes up to $100,000. Most credit cards will also only cover trips purchased with the card or its reward points.
Example of travel insurance
According to Tunnah, the medical protections that come with travel insurance “cover accidental injury and illness — such as tripping on a cobblestone street in Croatia or getting food poisoning in Thailand.”
If one of the above were to happen to you while traveling, you’d file a claim with your insurance company — either by calling an agent, submitting a claim via mail or fax, or using the insurer’s website or mobile app. You usually need to do this within 90 days of the event, though the sooner you can file, the better.
When submitting a claim, you also need to provide proof of your financial loss — a receipt from the medical clinic you used or a medical statement from the doctor. Once the claim has been reviewed and approved, you’ll receive a reimbursement payment, usually via a check mailed to your home address.
Insider’s Featured Travel Insurance Companies
Editor’s Rating
4.5/5
Editor’s Rating
4.7/5
Editor’s Rating
4.45/5
What are credit card travel protections?
Many premium credit cards offer travel protections to cardholders, but the exact coverages depend on the credit card. Typically, only trips booked with that card qualify for coverage.
“Credit card travel insurance has one big advantage that interests travelers: it’s usually free or included in the card’s annual fee,” Durazo says. “Credit cards’ travel benefits can be useful for smaller things, like travel delays or lost bags, but only travel insurance provides reliable protection in real emergencies, like expensive medical emergencies such as hospital visits and evacuations.”
In some cases, however, a credit card may cover catastrophic accidents. The Chase Sapphire Reserve, for example, offers up to $1,000,000 worth of coverage for an accident that causes loss of life, speech, hearing, or use of a hand, among other life-altering injuries.
Additionally, credit card coverage limits tend to be much lower. The Sapphire Reserve card offers up to $20,000 per trip in cancellation coverage, while a basic travel insurance plan from Travel Guard offers five times as much coverage.
Example of credit card travel protections
Your credit card travel protections could come in handy if an airline loses your luggage. In this scenario, you would file a claim with the carrier and then your credit card issuer. Once approved, they’d reimburse you for the total value of the items lost, minus any reimbursement you received from the carrier.
For these types of claims, you will typically need to submit your claim form along with a travel itinerary, proof of your claim with the carrier, copies of any associated receipts (for your checked baggage fee, for example), and copies of receipts for any replacement items like a new suitcase, wallet, or anything else lost by the carrier.
The bottom line
Both travel insurance and credit card protections can prove helpful if your trip is canceled or you experience some other loss while traveling, but the right choice will depend on the specifics of your exact trip and budget.
“Every trip is different, and every traveler has different needs and concerns,” Walch says. “For a short trip to a family member’s house in the US, the travel insurance offered through the credit card may suffice. However, if you’re traveling abroad or going on a longer vacation and you’re worried about unknown emergency medical expenses or loss of money because of a cancellation, then you may want to consider a traditional travel insurance policy.”
Aly J. Yale is a freelance writer, specializing in real estate, mortgage, and the housing market. Her work has been published in Forbes, Money Magazine, Bankrate, The Motley Fool, The Balance, Money Under 30, and more. Prior to freelancing, she served as an editor and reporter for The Dallas Morning News. She graduated from TCU’s Bob Schieffer College of Communication with a focus on radio-TV-film and news-editorial journalism. Connect with her on Twitter or LinkedIn.
If you happen to be going to use a credit rating card, should not you get compensated to do so? Benefits playing cards assist you profit from your day-to-day expending. This is what you will need to know to get the most important possible returns from benefits cards.
What is a benefits credit history card?
Benefits cards pay back you back again each time you use them. Quite a few this kind of cards give you again a proportion of each and every buy in funds. Other individuals pay back you back again with details or miles for a distinct airline carrier, hotel chain, or basic journey expenditures.
Impression supply: Getty Photographs.
Points and miles benefits are a bit much more complicated as opposed to cash rewards. The worth of a person mile or just one position is not often equivalent to an specific cash equal. Playing cards like Chase Sapphire Most well-liked present Ultimate Benefits points, where by each individual position is worthy of 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} additional in comparison to its money counterpart when redeemed for travel by way of the Chase Greatest Rewards portal.
Men and women are also reading…
Whether in the sort of dollars or factors, these benefits might seem to be small, but they can add up speedily. Benefits accumulate in the account above time till you redeem them.
The 3 sorts of funds back again playing cards
Set-charge playing cards
Set-fee playing cards get paid a established percentage on all transactions, commonly 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, depending on the card. These are best for folks who love a skinny just one-credit score-card wallet with out any fuss. The Wells Fargo Lively Money Card earns an endless 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} cash reward and a hefty $200 funds reward signal-up reward soon after you invest $1,000 on buys within a few months. Underneath this no-frills expending tactic, charge every thing on the card, including considerably less clear goods like car payments on dwelling stability or online and cellphone costs.
Bonus category cards
Bonus classification cards earn elevated money back rewards — generally 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in specific groups like gas, restaurants, or grocery purchases for a individual time frame. These reward classes commonly alter each individual three months. A card may perhaps offer you 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} hard cash back again on Amazon and Goal buys from Oct by means of December. The card member have to enroll to activate the bonus class either on the web, in-application, or by calling shopper support.
All other standard non-bonus buys proceed to earn 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} or 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} dollars again devoid of any activation, depending on the card. The Discover “it” card might be ideal for individuals who really like the exhilaration of unique reward types each and every quarter. To improve rewards, only use this card for the bonus classes.
Tiered cards
Tiered playing cards supply a hybrid concerning fixed-charge and reward category cards. They give a couple pick out elevated rewards classes of up to 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} funds again, and generally 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on all other normal buys. The Blue Hard cash Everyday Card from American Convey delivers advantages like 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at supermarkets, gas stations, and on on the net retail buys, each capped at $6,000 per calendar 12 months. All other purchases gain 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Moreover, it offers you a $200 credit rating on your card balance soon after you shell out $2,000 in purchases on your new card within the 1st six months of membership.
Benefits can be redeemed on-line, in-app, or by calling shopper support. Cardholders can redeem what they’ve acquired to pay out down their equilibrium, donate to charity, reserve travel, obtain present playing cards, or just get a check out for cash.
How to optimize credit rating card rewards
To make the most of your rewards, consider possessing a few credit history cards: 1 from every single classification over.
Ahead of the commence of each quarter:
Plan out your credit history card utilization.
Seem up and enroll in the bonus class for the quarter.
Jot down bonus groups on a sticky be aware and continue to keep it in your wallet.
Increase your funds again by sticking to your spending strategy.
Card Form
A few-Thirty day period Shelling out Plan
Bonus Classification
5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} places to eat
Tiered
3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at supermarkets 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at fuel stations 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on on line retail purchases
Mounted-Charge
2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on anything else
Are benefits credit playing cards suitable for you?
Benefits credit history cards are great for buyers scheduling to pay out their credit history card payments in total each month. It is really not worthwhile to pay back upwards of 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in curiosity to receive 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} income back again. Moreover, spending more than you can manage to optimize indication-up bonuses and rewards is tempting but risky. In addition, some of the finest benefits playing cards may possibly demand an once-a-year fee. The concept is to conserve income by racking up credit score card benefits, not drop income by racking up credit card financial debt.
Whatever your shelling out model or economical aims, a good strategy is the top goal in the course of these difficult instances. If your needs match what they offer you, benefits credit score cards could possibly be able to aid you get to that aim.
5 Simple Recommendations to Skyrocket Your Credit score Rating About 800!
Raising your credit score score higher than 800 will place you in scarce business. So rare that only 1 in 9 Us citizens can declare they’re users of this elite club. But opposite to preferred belief, racking up a large credit history rating is a whole lot a lot easier than you could have imagined adhering to 5 basic, disciplined strategies. You will obtain a whole rundown of every inside of our Totally free credit history score manual. It truly is time to put your money foreseeable future 1st and secure a lifetime of savings by raising your credit score rating. Simply just click listed here to declare a duplicate 5 Uncomplicated Guidelines to Skyrocket Your Credit score Score about 800.
Fool contributor Alka Mehta holds no monetary position in any firms outlined. Explore Financial Providers, American Express, and Wells Fargo are promotion companions of The Ascent, a Motley Idiot organization. John Mackey, CEO of Complete Foods Marketplace, an Amazon subsidiary, is a member of The Motley Fool’s board of directors. The Motley Idiot has positions in and suggests Amazon and Focus on. The Motley Idiot endorses Explore Financial Companies. The Motley Idiot has a disclosure plan.
Get the newest neighborhood enterprise information shipped No cost to your inbox weekly.
Most effective for travel accident insurance coverage (organization)
Ink Organization Endless Credit score Card
Coverage aspects: $500,000 in protection
(Credit: Seventyfour/Adobe Inventory)
Finest for luggage insurance plan
Chase Sapphire Favored Card
Coverage information: $3,000 in dropped baggage protection
(Credit rating: jumlongch/stock.adobe.com)
Ideal for luggage insurance (company)
Ink Enterprise Limitless Credit Card
Coverage aspects: $3,000 in missing luggage coverage $500 in delayed baggage coverage for each trip.
(Credit: byeolsan – stock.adobe.com)
Very best for journey hold off/cancellation coverage
Chase Sapphire Desired Card
Coverage particulars: $20,000 for every excursion in cancellation coverage $500 per ticket in vacation delay protection
(Credit: Ekaterina Pokrovsky/inventory.adobe.com)
Finest for trip hold off/cancellation insurance coverage (organization)
Ink Small business Endless Credit score Card
Protection aspects: $10,000 for every excursion in cancellation coverage $500 for each ticket in journey hold off coverage
(Credit: Nikolay N. Antonov/Adobe Stock)
Greatest for overall journey insurance plan coverage
Chase Sapphire Most popular Card
Protection facts: $500,000 in journey accident protection $3,000 in missing luggage protection $500 per excursion in delated baggage coverage $20,000 for every journey in cancellation protection $500 for every ticket in trip hold off protection
(Credit score: Seventyfour/Adobe Inventory)
Ideal for general vacation insurance policies coverage (organization)
Ink Company Unlimited Credit Card
Coverage information: $500,000 in journey accident coverage $3,000 in lost baggage protection $500 per journey in delayed baggage protection $10,000 for every journey in cancellation coverage $500 for each ticket in journey hold off protection
(Credit history: prostooleh/Adobe Stock)
There are a great deal of factors to take into account when picking out a credit history card, but even though you’re sizing up interest costs and rewards, it is also crucial to think about the protections your card can offer you, specifically if you use your card to travel.
Recently, WalletHub launched a report for which they examined 92 credit score playing cards from the 10 major issuers to determine out which playing cards offer you the best protection when traveling for the two own and small business functions. They looked at several places of protection as they as opposed the cards’ travel insurance policies offerings.
Travel incident coverage
The average policy consists of $250,000 of death and dismemberment protection for the major cardholder and authorized buyers and their spouse or domestic spouse. The best playing cards, WalletHub states, offer up to $500,000 of demise and dismemberment coverage, which extends further than the primary cardholder to not only their spouse/husband or wife, but also any dependent youngsters and in some cases even much more distant loved ones members, this kind of as mother and father-in-regulation.
Baggage insurance coverage
WalletHub located the average credit history card with vacation insurance coverage provided $3,000 of dropped luggage coverage, but no coverage for delayed luggage. Meanwhile, the very best policies provide not only $3,000 of coverage for shed baggage, but $500 for delayed luggage, which aids reimburse the cardholder for required private and business products they ought to substitute in advance of their bag comes.
Journey hold off/ cancellation coverage
The ordinary credit card doesn’t present any form of hold off or cancellation coverage, the report observed. Nevertheless, some insurance policies offer as a lot as $20,000 for every journey if it is cancelled or slash brief and up to $500 if a journey is delayed much more than 12 hrs.
In the slideshow higher than, we’ll appear at WalletHub’s options for the credit history cards with the strongest coverage choices for both personalized and enterprise vacationers.