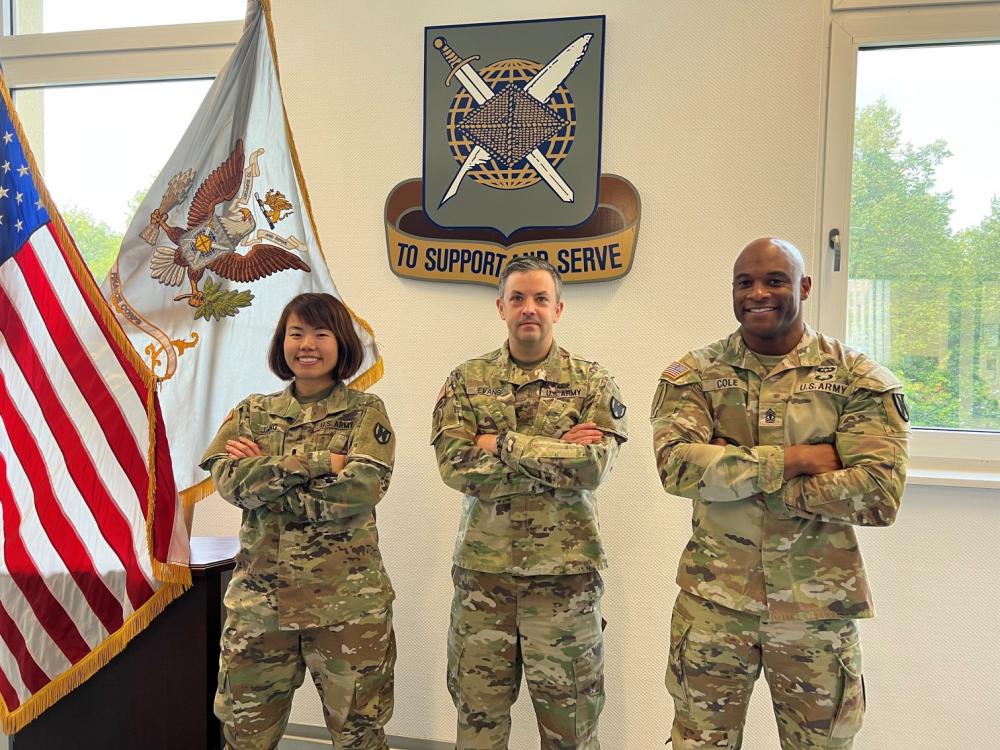
The 21st Theater Sustainment Command transports troops, equipment and materials all over the European Theater, demonstrating U.S. versatility, agility and skill. When it arrives to in-transit visibility of chilly, tough money, 266th Finance Help Center adds ingenuity to that listing.
While deployed to Camp Arifjan, Kuwait from June 2021 to February 2022, Maj. Jonathan Evans and Sgt. To start with Class Willie Cole were section of a Counter Menace Finance Fusion Cell charged with operationalizing the CTF thought. The U.S. Department of Defense defines CTF as “activities and abilities made to deny, disrupt, wipe out, or defeat finance devices and networks that negatively have an impact on U.S. interests.”
“We had the suitable team in the proper site,” explained Cole, who is now 21st Distinctive Troops Battalion’s Headquarters and Headquarters Company Very first Sergeant. Alongside with Evans, the Fusion Mobile also bundled Cpt. Devin Cook dinner, now a student at the Captain’s Occupation Program.
According to Cole, the crew had the profitable system of expertise in various economic programs, sensitive action experience, fiscal know-how, recognized interactions and vital clearances desired to discover, collect and evaluate facts essential to stop and disrupt adversaries’ means to increase, use, go and retailer assets.
Evans mentioned the staff appeared at how they could operationalize their data. “There was a great deal of experimentation with financial analysis, and from that, the phrase ‘fiscal preparing of the environment’ progressed,” explained Evans.
According to Evans, fiscal planning of the surroundings examines the economic and fiscal aspects of the running setting that are probably to impact military functions. This info can assistance commanders and staffs make far better-educated conclusions and get ready for vital meetings. 
“The CG [in Kuwait] had a amount of mil to mil engagements and we did a just one slider of just economic info for the nations around the world he was traveling to,” stated Evans. “And we can add that in this article [at 21st TSC] for different projects.”
1st Lt. Ying Jiang works with Evans at 266th FISC as they keep on to refine the perform started off in Kuwait. She describes an additional CTF line of hard work that helps prevent assets from flowing to adversaries—vendor vetting.
“Counter threat finance is related, for the reason that with hard cash, how do you actually trace exactly where the funds is heading?” Jiang claimed. “When we do vendor vetting mitigation the point is truly to stop cash likely into our enemy’s hand.”
“That contains determining if critical management personnel are aligned with bad actors, and if corporations are certainly owned by who they claim they are owned by. If we pump a large amount of U.S. pounds into the country…..and if we are having to pay nearby suppliers, that may have all kinds of consequences,” mentioned Jiang.
Cole explained one particular of their initial consumers was “blown away” by the data they supplied. “We gave them details that they could use as proof to assistance the intel aspect of the residence. From an intel perspective, our financial facts strengthened their scenario.”
The CTF crew has partnered with U.S. Army fraud investigative models and consistently performs with different entities these as Military Counter-Intelligence, Felony Investigative Division, Army Intelligence and Non-Lethal Effects operate groups. They customize the information they package deal dependent on their customers’ requirements.
“From a counter intelligence standpoint, they need particular facts,” explained Cole. “From a straight up combatant commander info [perspective] seeking at the intel side of the property, they require sure data. The fraud men and women want a distinct package. So demo and error, we had been ready to establish distinctive offers based on client demands.”
Evans cited the method of port-collection as an example of how CTF can inform determination-earning as 21st TSC conducts enterprise through Europe and Africa, efficiently acquiring, staging and transporting tools and staff during the two continents.
“As [21st TSC planners] look at various ports and what we are performing to assist rotational models, becoming equipped to inform them on the economic position of that location and seeking at beneficial possession of firms we are undertaking business enterprise with now, gives them a far better photo of the over-all running ecosystem.”
Cole additional that it is also critical to stick to up right after the truth. “We pump tens of millions and hundreds of thousands of dollars into that economy,” mentioned Cole. “We want to be capable to stick to that revenue, in essence by seeking at the contract details. Income generally moves with a objective. It is our task to inform and suggest on the objective.”
For 266th’FISC, accountability on the battlefield usually means figuring out exactly where the cash is transferring.
“Defense wins the championship,” explained Jiang. “We are stewards of governing administration funds and we want to make absolutely sure we are paying out taxpayers’ income thoroughly and lawfully and not having to pay the enemy.”
The team acknowledges 266th FISC Director Col. Lance Sneed for supporting their continuing attempts to show the price of finance and comptroller forces and make CTF available and very easily built-in into command organizing.
“Col. Sneed provides us all the freedom we have to have and the latitude to experiment and explore and see what performs,” stated Evans. 
Jiang agreed, saying functioning on CTF is like doing the job for a start out-up company.
“There’s no guaranteed upcoming,” said Jiang. “You do not know what tomorrow’s likely to appear like. It requires a ton of personalized desire. To me the problem is the pleasure of the career. That is why I wanted to sign up for the crew.”


Day Taken:

12.02.2022


Date Posted:

12.05.2022 05:05


Tale ID:

434352


Place:

KAISERSLAUTERN, RP, DE


Net Views:

10


Downloads:


General public Area 
 
This get the job done, 266th FISC Plays Potent Defense with Counter Menace Finance, by Eleanor Prohaska, discovered by DVIDS, need to comply with the limitations revealed on https://www.dvidshub.web/about/copyright.
GUANGZHOU, China, Dec. 4, 2022 /PRNewswire/ — The Global Finance Discussion board (IFF) offered the IFF World Inexperienced Finance Award for the duration of its world annual assembly on Dec. 3, as the business continues to advertise green finance and realize institutions that have made important attempts in sustainable development worldwide.
The once-a-year award is granted to establishments that have contributed considerably to worldwide, regional or countrywide sustainable improvement by green finance techniques, and carried out projects that help achieving carbon peak and carbon neutrality, addressing climate transform and biodiversity conservation.
This 12 months, the IFF granted the award to 20 world-renowned institutions that have shown remarkable initiatives in practising eco-friendly finance. The recipients contain London Inventory Trade Group (LSEG), China Design Financial institution Corporation, Société Générale S.A., UBS Group AG, PricewaterhouseCoopers, China Asset Management Co. Ltd., Ping An Financial institution Co. Ltd., China Energy Conservation & Environmental Protection Team, Lender of Beijing Co. Ltd. and Shenwan Hongyuan Group Co. Ltd., among other individuals.
David Schwimmer, main executive of LSEG, claimed LSEG is proud to be acknowledged by the IFF for its initiatives to deliver sustainability merchandise and solutions to shoppers all-around the planet.
He additional that LSEG commends the IFF for its extensive-standing commitment to discussing sustainable finance.
In a speech in the course of the 2022 IFF Once-a-year Conference, United Nations Secretary-Normal António Guterres explained that the window to avert climate disaster is closing quickly.
“Everyone must perform their component and completely align their organization designs with the 2030 Agenda and weather plans. Intercontinental economic establishments and growth banking companies need to alter their tactic to possibility and systematically leverage non-public finance for creating nations around the world at acceptable expenditures,” stated Guterres.
Dame Jenny Shipley, co-chair of the board of judges of the IFF Worldwide Environmentally friendly Finance Awards and previous key minister of New Zealand, said it’s interesting to see that people are turning their head to how to deliver multi-disciplinary aspects jointly utilizing finance and also wanted environmental and sustainability results, to in fact realize significant aims.
Established in 2020, the IFF World wide Eco-friendly Finance Award strives to market sustainable finance practice in the finance sector so as to battle the weather disaster and reach sustainable advancement.
About Global Finance Discussion board (IFF)
The International Finance Forum (IFF) is a non-gain, non-formal impartial worldwide corporation founded in Oct 2003 by leaders from China, the US, the EU and the other G20 nations around the world, in live performance with rising economies and the leaders of many global organizations, such as the UN, the World Financial institution and the IMF. Also identified as the Finance 20 (F20), the IFF is also a significant-stage long-lasting dialogue system and multilateral cooperation corporation in the earth of finance.
Resource International Finance Discussion board (IFF)
Fifth and Remaining Discussion Draft Bolsters Laws and Regulations Aimed at Placing Accessibility to Psychological Wellness Care on Par with Actual physical Wellbeing Care in Medicare and Medicaid
Washington, D.C. – Senate Finance Committee Chair Ron Wyden, D-Ore., Position Member Mike Crapo, R-Idaho, and Senate Finance Committee customers Sens. Michael Bennet, D-Colo., and Richard Burr, R-N.C., these days introduced a discussion draft which includes policies aimed at improving upon mental health parity in Medicare and Medicaid and serving to to set entry to mental health and fitness and substance use problem (SUD) products and services on par with bodily wellbeing treatment. Mental wellbeing parity consists of a set of laws aimed at ensuring psychological and physical health and fitness care are coated equally by overall health coverage.
“Too frequently the idea of psychological wellness parity falls limited of truth,” Wyden reported. “These procedures stand for the to start with step in the direction of addressing the psychological health and fitness parity and ghost network issues that I intend to establish on in the coming months — specially the difficulties I listen to about consistently from family members at household who are not ready to find available mental health professionals lined in their insurance coverage networks. I’m proud that the committee has been able to come with each other all through the calendar year to release a entire host of guidelines aimed at enhancing mental health treatment for Us residents, some of which have by now grow to be regulation. I will keep doing work to enact these guidelines and assure all People can get mental wellbeing care when they have to have it.”
“These proposals will assist us acquire supplemental data and improve transparency to be certain Medicare beneficiaries have accessibility to cost-effective mental health expert services, on par with their accessibility to bodily wellness companies,” claimed Crapo. “I thank Senators Bennet and Burr for their perform on this discussion draft, and glimpse forward to obtaining responses on every single mental health dialogue draft from our colleagues and stakeholders.”
“As I journey across Colorado, I constantly listen to about the mental and behavioral overall health challenges Coloradans and their kids experience and the difficulties they experience getting inexpensive, significant-excellent care. We want to change our technique to be certain our wellness care program equitably addresses the two mental and bodily wellbeing,” Bennet stated. “These policies are a phase ahead to enable realize parity, and I’ll continue working to reimagine our mental and behavioral health and fitness method to greater care for Coloradans and families throughout the place.”
“Mental health and fitness providers are a significant overall health care have to have as our country recovers from the pandemic,” explained Burr. “This dialogue draft lays a basis for advancing practical procedures that bring to the forefront the significance of making sure sufferers have the info needed to make the greatest health care selections for on their own and their households, and I look forward to getting comment.”
Procedures in the discussion draft incorporate:

Strengthening the accuracy of provider directories in Medicare Advantage programs.


Strengthening needs in Medicaid for managed care businesses and states to preserve routinely current service provider directories that contain, in aspect, data on accessing care from behavioral health specialists.

Immediate GAO to conduct a examine of the variances in enrollee value-sharing and utilization management concerning behavioral and non-behavioral well being expert services in Medicare Edge and as opposed to classic Medicare.

Call for Medicare to give guidance to overall health treatment suppliers detailing the extent to which Medicare beneficiaries with compound use problems can obtain partial hospitalization application services.

Direct GAO to report on Medicaid payment charges for behavioral health and fitness expert services in contrast to health-related and surgical services across a sample of states.

This discussion draft on mental health and fitness parity is the fifth and last legislative draft the Finance Committee has unveiled considering that kicking off its bipartisan psychological well being initiative. The 1st, introduced in May perhaps, centered on telehealth procedures. The second, launched in June, concentrated on youth psychological health and fitness. The third, released in September, focused on expanding the psychological overall health care workforce. The fourth, launched in November, concentrated on integrating bodily health and mental wellness treatment vendors.
The whole textual content of the discussion draft is obtainable here. A summary of all provisions launched by the committee as a section of the bipartisan mental wellness effort, which includes psychological health parity, is accessible right here.
Bob Powell (00:03): All right. Welcome everyone to our Women, Divorce and Retirement webinar. I’d like to remind everyone that all attendees are muted and off video, but the event is being recorded. And if you have a question, please type it into the chat box at the bottom right of your screen. Panelists will, we’ll have panelists speak to their top items and cover questions as we go through the webinar today. And as a reminder, everyone will receive a link to the recording when it’s posted on retirement daily.
I’d like to take a moment to introduce our subject matter experts for today’s webinar. We have Rick Fingerman, who is the co-founder and managing partner of Financial Planning Solutions. We have Katie Marsden, who is a wealth advisor for Buckingham Strategic Wealth. And Amy Shepard who is a financial planner at Sensible Money. Welcome.
So, the order of business today is in essence to look at what happens now that your divorce is final. Where do you begin as you contemplate your new life as a divorced woman? And Katie, we’re going to start with you. You’ve developed a checklist that outlines the topics that divorcees need to address, including how assets in a house get divided. Where do you suggest that they begin?
Understand Your Goals
Katie Marsden (01:25): So, one of the best places to start is to really take a step back and what I like to call it is redesigning your future. What I mean by that is starting from scratch with really all of your financial plans to reassess what’s important with you and how maybe your goals have changed for the future. There’s likely been changes in your life, some big, some small changes around income sources, cash expenses, maybe where you live, how much assets you have towards retirement. There’s been quite a bit of changes. I recommend people really just take a step back and start with the basics of putting together a new plan and focusing on what their goals are.
Katie Marsden
So, kind of thinking through what do you want your financial future to look like? Have your goals changed; your aspirations changed? Has your timeline, maybe, for retirement or other things changed? And then taking a look and figuring out, okay, what do we need to change as far as your finances go to support those goals? And not everybody’s ready to do this on day one, but the idea is to get you start starting to think about how some of these changes in your life should change your overall plans.
Bob: You mentioned goals-based planning. Why is that important?
Katie: It’s important because it is really focused on you as an individual and what you’re trying to accomplish, rather than just focusing on a return figure. Other things, it’s to make sure that your needs are met as an individual and that you get where you’re trying to go at the end of the day.
Bob: In terms of cash flow, two things that probably might be different than they were before you were divorced is the notion of having child support and alimony. Is that something that people need to weigh into their plans as they think about their basics?
Katie: And it varies so widely from every individual. So, cash flow in general has likely changed a lot going from possibly one income to two or two incomes to one or one to having just support payments. So, starting a really close look at your cash flow, where is the money going, what expenses do you have? That is a great place to start just to reassess everything and see how it fits in with your plans.
Bob: Amy, Rick, anything to add to that?
Amy Shepard: I would just always echo what Katie says. I think just having your goals figured out, knowing what’s important to you, if you know that it makes it a lot easier to start tackling all the financial pieces and working through a checklist that probably does seem overwhelming.
Amy Shepard
So, I think it does help give some clarity when you can take a step back and just think about what’s really important and what do you want to accomplish with your own life.
Rick Fingerman: Yes, exactly. I think those points are right on, because when you’re in a relationship, your goals might be very different than your partner’s goals.
Rick Fingerman
So now it’s your opportunity to really put a plan in place that gets you where you want to be. Having that checklist and having someone to work with, especially to work you through the process is really key.
Manage Your Risk – Insurance
Bob (04:47): So, one of my favorite topics is risk management. And Amy, obviously when someone is newly divorced, they have to revisit all the possible insurance needs that they might have, whether it’s health insurance, property and casualty, disability insurance, life insurance, et cetera. Walk us through what folks need to know.
Amy: There’s a lot here, so there’s a lot to look through, but some of the big ones that I’ve seen frequently, health insurance could be a big factor for a lot of people. If you are on a spouse’s group plan and maybe now, you’re not able to be.
Or I have seen instances where folks are already retired and there’s some setup where even though now, you’re divorced, you can stay on an ex-spouse’s insurance for a period of time if it’s to get you to Medicare age or something like that. So, health insurance is important whether or not you figured it out before the divorce was final or after the fact.
There’re so many options out there and we all know health insurance does not get cheaper, it’s only more expensive as time goes on. And so just taking the time to figure out what’s the best coverage, whether it is an option that somebody might have to go through their own employer, or if you’re not working, what are your options? That can be overwhelming. So just taking the time to figure out and making sure that basic need is covered, that you have health insurance in place. That’s a really big one.
Another one is life insurance. And so going back to what Katie said about the goals, depending on what your goals are, your insurance needs may have changed if your goals have changed. A lot of times we get life insurance to help cover our financial contribution to our marriage, but if we’re no longer married, we may not have the same need for life insurance. Or maybe the numbers still support needing the life insurance, but we have to make sure we go through the steps of updating beneficiaries. Maybe we don’t want an ex-spouse listed as the beneficiary anymore. So that’s an important thing to go through.
And I think it’s a two-part consideration: One, do you still need life insurance and two, if you do, how do you structure it so it matches your goals? Make sure that any proceeds go where you want them to.
I think for a lot of people, especially with children, maybe they change it from an ex-spouse to their kids or if they have a trust set up or something like that, you just, again, want to tie it back to what your goals are.
Another really important thing, I think, that divorced or otherwise, [another] insurance consideration is long-term disability. It’s something that doesn’t get enough attention, but it is important at any stage in your life. But it’s another really important thing to look at when your whole financial and emotional life changes after a divorce.
So, long-term disability insurance is really important if you are still working and maybe your timeline has changed for when you expected to retire. If there’s still a lot of working years ahead of you that are needed to make your goals a reality, having long-term disability insurance is really important because it essentially protects your income. And so, if you have an unfortunate event, like something as, I’m going to say minor, as maybe a car accident that you can recover from, but it takes you out of work for a period of time, to something more serious like cancer or some other illness, that it does affect people well before we want to think that it does.
We tend to think that all that stuff really happens when we’re really old, but that’s not the case. And I think just again, having the risk management in place to make sure that whatever the goals are that you first identified, that you are supporting them even as life continues to throw curve balls, because I’m sure divorce is one big one, but they’re, they’re always around every corner. I think those are some of the really important insurance considerations to look at.
Bob (08:44): Insurance is never quite frankly, the most exciting of topics to talk about, but it’s certainly one of the most elemental blocking and tackling aspects of a financial plan. Katie, Rick, any additional thoughts?
Katie: Two things that came to mind for me. One was just know when your COBRA, if you have COBRA insurance, know when it expires so you could start planning for it well before the coverage ends.
And just one other thing that came to mind was for some of the clients that I work with who have been out of the workforce, [they] have found since their health insurance is such a large expense that if they are able to find work that they enjoy doing and can have that cover for a period of time, if they’re below Medicare age, that it can be a big sigh of relief from an expense perspective. So that’s just something to think about how it can help the bottom line by getting that coverage through an employer.
Bob: And in cases where someone may have to use ACA, there’s also the possibility depending on their income of receiving advanced premium credits as well.
Katie: Correct. Correct.
Bob: Right. Rick, at any additional thoughts?
Rick: Yes, I mean, just a few things I’ve seen in the years I’ve been doing this, sometimes on homeowner policies, you might have a rider for boats or other types of things that might not be in your picture anymore. Maybe the ex-spouse has that, or maybe that car is still on your auto policy, things like that. But it’s a good chance to sit down with your agent and really look at things like deductibles, see if there’s any gaps in coverage, make sure you have an umbrella policy, which is just a liability policy over and above any kind of liability that you have on your car, because we live in a litigious society and if you happen to hit someone with your car or they fall down your stairs, you want to be protected that way.
Rick Fingerman
And then lastly, one thing I’ve seen is where the divorce decree might have said that life insurance was supposed to be kept for a spouse for a number of years. So, you want to be careful of changing beneficiaries, which I totally agree with because I’ve seen more mess up with people that just never change a beneficiary, whether it’s life insurance, whether it’s a 401(k) plan, and that exposure is still on there and it can cause real problems later on. So just want to be mindful of all those things. As you pointed out, insurance isn’t always the most riveting topic, but it is a really important one to look at.
Saving & Investing Now That Your Single
Bob (11:07): So, Rick, divorced women still need to save and invest for many goals, retirement included. What do divorced women need to know about this topic?
Rick: Well, when you are a married couple, generally speaking, one person hopefully at least is saving towards retirement. If they’re both in the workforce, hopefully you’re both saving. And then when you split up, in theory, some expenses go away, but two people can live cheaper than one usually. And so, it’s important to have, again, that comprehensive financial plan to figure out what your expenses are going to look like in retirement and then back into how much money do I need to fund my life once those paychecks stop, whether it’s support of some kind or money from a job. Once those paycheck stops, you have to rely on other forms like Social Security or maybe a pension or investments and earnings and things like that.
I think it’s really important to get a handle on that first, and then you can back in and say, I need to save X for a number of years, and then just stick to that plan and adjust as time goes on. And if you’re working with a financial, certified financial planner, for an example, hopefully they will keep you on track and make any adjustments that are needed over the years.
Bob (12:22): There’s also, I think, Rick, this notion of one’s risk tolerance may be different going forward as a divorced spouse versus when they were a couple.
Rick: Absolutely. I don’t like to stereotype or generalize, but I will. Because in my experience, women tend to be more logical thinking when it comes to risk tolerance and investing where some spouses might be much more aggressive and that might not be a good feeling for that, that divorce spouse. So, you really want to look at your risk tolerance, see what you’re comfortable with, and it might be a good opportunity to look at certain value-type investing, too. We have clients that want to invest in a certain way, whether that’s excluding certain things like tobacco and alcohol or fossil fuels and things like that. Or also be inclusive to try to invest in companies that might have more equal pay for everyone, those types of things. So, it’s a good time to really look at it as a new journey going forward for yourself versus how it might not have really fit you well as a couple.
Bob (13:30): You mentioned timelines and the need to reevaluate them. One thing that comes to mind is oftentimes women may leave the workforce during their childbearing years or may leave the workforce for one reason or another, and that impacts both their ability to save for retirement and impacts their Social Security benefits, et cetera. Amy or Katie, any thoughts about how timelines need to be adjusted given the possibility that women enter and exit and reenter the workforce?
Katie: In general, women tend to have less saved than men. They do studies showing the amount that women have saved and invested versus men. And in general, women have less saved, but for some of the reasons that you mentioned of not necessarily being in the workforce as long, but then on the flip side, women also are more likely to live longer than men. So, we have a little bit of a financial planning conundrum there, we have a little bit less to work with and a longer time horizon, in some cases. Of course, there’s always exceptions to every situation, but it’s something that is important to be mindful of and making sure that we’re including that as part of our plan and that we’re making the dollar stretch as long as they’ll, they’ll likely need to go,
Bob: Amy?
Amy: Yes, I always share when it comes to longevity, I have a great aunt who just recently passed away at 107 years old. And so yes, she is definitely one of the exceptions, but women do tend to live longer than men. And so yeah, Katie, you hit that the nail on the head there. It is really important. I think the only thing I would add is just that you don’t need to have a lot to make a solid financial plan. I think it can be really overwhelming when you go through a major life change like a divorce, and then you start thinking about your future and people naturally think about the dollars in the sense. But I have seen plenty of situations where I work with folks that never made a substantial amount of money, but they’ve been able to do just fine in retirement.
On the other hand, I’ve seen situations where people make more money than you could ever imagine, and they’re struggling to plan for their retirement. And I think the piece of advice I would give is just try not to worry too much. If you feel like you don’t have enough and sit down with somebody and really look over the numbers, go back to your goals and figure out if what you have is sufficient for you. If sometimes people are surprised to find out that by doing things like delaying Social Security can give them enough monthly income to cover the vast majority of their expenses. And that can be a relief even if there isn’t a ton of investment that have been accumulated. I think the takeaway is just there’s always options and it’s really important to explore them all.
Tax Planning
Bob (16:31): So, let’s turn our attention to income taxes. Divorced women are sometimes in for a surprise when they file as a single taxpayer when it comes to RMDs or collecting Social Security. Amy, what do our divorced audience need to know about income taxes?
Amy: Bob, the big thing like you mentioned, is not only has your life changed in so many ways, but your tax situation has also changed quite a bit because now you file taxes most likely as a single taxpayer instead of a married taxpayer, which has its own set of considerations. And so, when you add a lot of the things we’ve talked about, one being women live longer than men, statistically; women don’t have much saved, all of that. For a lot of divorced folks, there’s a kind of this surprise tax bomb waiting later in life. So, as you progress through your life, as you progress through retirement, if you do have pre-tax retirement accounts, at age 72, you have to start withdrawing from them. Well by 70, you’ve also started Social Security. And what I often see is that later in life, especially single taxpayers, they start to creep up into higher tax brackets later on where in the early years, whether it was when they were still working or after they’ve retired but before gotten into their seventies, sometimes there’s what we call the opportunity zone, where they have some lower tax years, they can do some long term tax planning to help reduce those future required distributions and reduce the amount of taxes they spend over their lifetime.
And so, it all comes back to the importance of having a financial plan. Looking long term and not getting so caught up in just the short term. There’s of course going to be really important short-term things that you have to tackle, but it’s really important to look at the big picture, look at what your goals are, and then map out what you expect your tax situation to look like over the next several decades. And then see what decisions you can make early on to help limit the amount that goes to taxes. And for a lot of people, not only do they like the idea of saving money on taxes, but it’s also really comforting to know that if you have a strong tax plan in place, it has the potential to give you more money to enjoy doing the things you want to do. And I think it’s just the long-term view is really important to just spend the time and look at it and make decisions based on the numbers, based on the numbers and your goals instead of just guessing on what might be the right choice.
Employer Benefits
Bob (19:07): So far, all that we’ve talked about does seem like quite a bit of work. Katie, any thoughts about income taxes and maybe making that topic less painful?
Katie: Two things that came to mind with that topic. One, Amy mentioned that most people have to, after a divorce is finalized, file as a single taxpayer. And just taking a look at if it was included in your documents, if you have children, if you can file as head of household, every little bit helps. And then the other piece of just who can use the children on their tax return for the child tax credits.
Another important thing, which I think we all kind of forget because you set it and forget it, but if you are working to take a look at your withholding and see how taxes have been withheld from your employer. And if going forward there is changes that you can make, so to touch base with the HR department of your company or your CPA to make sure that you’re not doing too much or too little because that can make a difference in our cash.
Bob: Rick, any additional thoughts?
Rick: Katie just brought up a good point about benefits at work made me think about could be opportunities there. Again, looking at that overall comprehensive financial plan, seeing if you’re on track for retirement, it might be a good opportunity to max out your 401(k) plan if that’s available at work. Maybe incorporate a flexible spending account that uses pre-tax dollars to pay for medical stuff like your kids might need braces or things like that. Or even a health savings account, an HSA, which is really a great vehicle, if you have a high deductible health plan, it might be a good fit for you.
I think, again, it sounds like this whole thing comes down to having a really good financial plan and someone to help you with all that. But yeah, the tax component can be huge. You know, filing single, Katie pointed out head of household would be a great thing to do if you’re eligible. And some people just don’t do that if they’re doing their taxes on their own especially. So yeah, I think again, look at everything that’s available.
Retirement and Social Security Planning
Bob (21:23): I’d like to remind everyone who’s attending the webinar that you can ask a question using the Q and A button at the bottom of your screen. We will be leaving more than sufficient amount of time to take questions from everyone here with our esteemed panelists.
So, I want to turn my attention to one of my favorite topics, retirement planning. Rick, from your perspective, what do folks need to know about Social Security, RMDs, QDROs divorce, spousal benefits, et cetera, joint and survivor pensions, et cetera?
Rick: Yes, all that good stuff. Well, we’ll start with Social Security. If you’re married for at least 10 years and you’re divorced, you’re entitled to a divorced benefit on your spouse. And generally, 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of their full retirement-age benefit. There are some caveats of when you actually start collecting. If you collect at 62 versus your full retirement age, your benefit is reduced. If you’re married, your spouse that you’re collecting on doesn’t, if you’re married, can be married. But if you are married, remarried, you can’t do that. But if they pass away and you remarried after age 60, there’s an opportunity to collect a hundred percent of what they were getting. So Social Security plan can be a big piece of that to see where it makes sense to collect, whether it’s your own work record or an ex-spouse’s record. When it comes to RMDs, I think Katie mentioned at 72, maybe it was Amy, I’m sorry, at 72 you have to start taking these required distributions and it’s a good opportunity.
Someone pointed out that there might be a window where your income is lower and maybe there’s some opportunity to during those low tax bracket years to do things like Roth conversions where you could limit the amount of those required distributions that you might need later on if it seems like you’re going to be in a higher tax bracket later. So, looking at all that I think really makes sense, too.
As far as QDROs, I’ve seen situations that QDROs, basically a qualified domestic relations order, and it’s generally around someone’s 401(k) or workplace plan to split that up between spouses, so it’s not a taxable event. So, you want to make sure that once the divorce is settled that the QDRO has not been, those assets haven’t been transferred, you want to make sure that that gets done properly. Because that I’ve seen cases where that sits around for five, six years and just never gets done and that’s not ideal.
The Value of the Checklist
Bob (23:51): What advice do you have around making sure that it does get done? Working with a planner, having a checklist in place?
Rick: Yes, absolutely. Working with a planner, having that post-divorce checklist to some, make sure nothing’s forgotten. The checklist I think is a great idea because it could be as simple as saying check beneficiaries, is the QDRO completed? There was one, was the house retitled, if you’re keeping the house, all those things are really important because it’s easy to forget this stuff even for us that do it every day. So, we really want to have some kind of checklist, check it off. I always feel good checking things off personally, I’ve even written things down just so I can check them off. But it’s a good feeling and I think the client feels good too, knowing that they’re making some progress.
Bob: Katie, I know you’re fond of checklists. Any additional thoughts on QDROs and Social Security and RMDs and retirement planning in general?
Katie: Yes, I make a checklist for everything. I would just echo a basic, what Amy was saying earlier, about not getting overwhelmed or feeling that you, maybe, aren’t exactly where you want to be at a certain point. Because the reality of a lot of divorces is that you had a pot of money that’s now split in two. And that regardless of how big or small that amount is, it can make people feel uneasy because you’re planning with a different amount than what you had been previously.
So, what I like to remind people is that in any retirement planning there’s always levers to pull. You can save more, spend less, work longer, it just depends on your priorities. So, before you get overwhelmed by looking at how the dollars have changed, also taking a look at how maybe some of your habits could be adjusted to where you can still end up in the same place. But just what levers can you pull? And for different people that’s a different answer. So just exploring those options and seeing how to get to a comfortable place with getting to retirement.
Bob: Amy?
More on Social Security
Amy: I think I just will emphasize the importance of the Social Security planning. Social Security is, like many of the topics we’re discussing a lot, a lot of rules, there’s a lot of nuances but there’s also a lot of benefit. And I think some people are often surprised when we put the numbers on paper to show how much value Social Security could provide over a lifetime. And then how that value can change, depending on if you start benefits earlier or later.
And, I think, just emphasize the importance again of just taking the time to work through these things carefully. A lot of the decisions that you make when it comes to retirement planning are one and done. You make the choice and you want to make the right one. And so, to make the right one and not regret a decision or make it hastily, I think it’s just really important to spend the time working through all the details.
Bob (26:52): I know when I talk to readers, they’re often surprised that they’re entitled to divorced spousal benefits or even a deceased beneficiary’s benefits. Do you find that to be the case in your practice that divorce women are sort taken aback that they can receive those benefits?
Amy: Sometimes people are, they just didn’t know what the rules were or there’s just such so much conflicting information out there they didn’t understand them the right way. There’s also a lot of confusion about the amount that you can receive. I’ve had a lot of people come to me and say, oh well I thought I could just get 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of my ex-spouse’s benefit because we were married for 10 years. And that is partially true, but sometimes you know, 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of their benefit may not be as much as if you took your own benefit.
And so Social Security, the way that it has tended to work is when you do file for benefits, they look at an ex-spouse’s record and they give you the biggest benefit you’re entitled to. But sometimes Social Security doesn’t always know all the rules depending on who you talk to when you call. And so, I think it’s just important again, to just not only spend the time to do your own homework, and some people don’t love doing their own homework and that’s okay, that’s why it just makes it even more valuable to work with a planner that can help you go through all of those pieces and make sure that what you heard or what you think you’re entitled to is the right thing for you.
Defined Benefit Plans
Bob (28:19): So, they don’t as prevalent as they once were, but some folks still have defined benefit plans and typically the beneficiary can choose a single life or maybe a joint and survivor option as well. Katie, any thoughts about what folks, divorced women need to know about defined benefit plans
Katie: As far as receiving them?
Bob: After the, post-divorce?
Katie: That can be a little complex. Most of the time it’s determined, kind of what’s going to happen, with those plans during the divorce. So oftentimes I’ll see that a client will, or maybe you didn’t necessarily work at an employer, but you’re entitled to a portion of your ex-spouse’s pension and some places it’s easier and harder to get information. Some of them you have an option to get a lump sum. Others you can take it at your retirement age.
There’s a lot of different rules so it can get a little complex. But what I would say is to make sure you call, get all of the information that you can from the plan administrator, and understand timing, what those payout amounts might be, what happens to your benefits if something were to happen to you, if you could name a beneficiary, there’s just a lot to make sure that you get the information and then when you can start taking those benefits and how best to receive them. So that’s where just getting the information is the first step because every plan is different
Estate Planning
Bob (30:01): So, we’ve covered a lot of ground. The last big topic is estate planning and divorce. Women, obviously they need to update their wills. Durable powers of attorney, we mentioned beneficiary designations, and the like. Katie, talk more about estate planning for divorced women.
Katie: Estate planning tends to fall, I think, at the bottom of everybody’s list. It’s thinking about our own death, is not really something most of us want to do, but it’s really important and particularly after a divorce.
I use this example because I think it really hits the point that I’m trying to make. Assume that you were to go out tomorrow and were hit by a bus and you haven’t updated any of your documents. Do you really want your ex-spouse to be the one making decisions about your healthcare if you haven’t updated it? And if it were me, I would say absolutely not. That’s not really who I’d want in charge. Not necessarily a bad thing. Sometimes that might be still the person you want, but having the option to take a look at your entire estate plan and decide who are the people that you trust, and that you want in those roles, that may different.
I mean oftentimes when you’re married it’s by default you pick your spouse to make those decisions, both from a financial perspective and health perspective, and named in your will. That likely has changed for most people. You might want to name if you have adult children, to name them or maybe a sibling or somebody else that you will carry out your wishes. And I’d say a lot of our planning from an estate planning perspective changes after a divorce of what we want to happen with the dollars that we have, where we want them to go, are they different people? Do you have charities in mind?
We always recommend to meet with an estate planning attorney. Most of the time you’re going to want to start from scratch because if you did have documents in place previously, they might not be as relevant anymore. But you just want to make sure that you have the right people in place to ensure that your wishes are carried out if something were to happen to you. Also, important if you have children and there’s decisions that you want to make sure are known and in writing. And if there’s funds being left to them who you want to be the guardian of that. There’s quite a bit from a planning perspective of just making sure your wishes are known and updated and you continue to keep them relevant.
Bob: Rick, Amy thoughts on that?
Amy: A couple thoughts came up for me. One of the big ones is yes, super important to update all your estate planning documents, but also really important to know that just because you update say your last will, if you don’t also update all of the beneficiaries on your other accounts to match, the will to a certain extent can be irrelevant.
What I mean by that is if your will says one thing, but the beneficiary on, say your retirement account, says something else, the beneficiary listed on the actual account is what is going to hold true. And so, I think it’s just important to know it’s not as simple like most things, it’s not as simple as just update your estate plan. You still have to go through each account to make sure all the beneficiaries match. So, everything says the same thing. The other thing is that if you are working and you work for a large enough company, a lot of big companies offer the option to enroll in a legal plan benefit during open enrollment.
I know when people hear the term estate planning or an estate planning attorney, they see dollar signs and they say, oh that sounds really expensive. And it can be. I mean basic estate plans usually run a couple thousand dollars.
One way to still tackle it but more maybe cost effectively is, if you have a legal plan benefit through work. It’s something that you don’t want to postpone, you know, ought to tackle it. And with legal benefits through work, usually you can only enroll in them during open enrollment or if there’s a qualifying event. You may have the option to sign up for one even if it’s not open enrollment. But I think the short version of the story is make sure your new estate plan matches all the account beneficiaries and also just look at options on how you can try to get your estate planning done for as an affordable cost as possible.
Q&A
Bob (34:48): We have some questions that have come in from our attendees, I’ll just go through them one by one and they can be jump all.
“I did not get the house in my divorce and have been told by friends that I’ll be renting from here on out. Is it feasible for a mid-sixties age person to consider purchasing a small house once the housing market cools or is it better to hold onto the small amount I’ll have towards living expenses, medical, as I age?”
Rick: Good question. I find the house is one of those areas that’s probably one of the biggest topics in a divorce. Who gets the house? Someone wants to hold onto the house and many times it’s not a financial reason, it’s an emotional reason.
I was raised that renting was throwing money away, so, you want to always buy a house. But I have found, especially as I’ve gotten older and don’t want to get up on a ladder and clean gutters, that renting is not really the worst thing in the world.
And I think, again, it comes down to having that comprehensive financial plan to see when you own a house, people sometimes think, well I’ve got the mortgage payment, I’ve got taxes, I’ve got insurance, and a water bill maybe, and then that’s it. But stuff happens in a house. The roof needs to be replaced, the boiler breaks down, the water heater lets go at 3:00 AM. So, there could be ongoing cost that you might not incur while you’re renting.
I think, you know, really, want to look at that and make your life as easy as possible. Sometimes renting is the right answer, sometimes buying just like, it depends, is kind of that catchphrase for a lot of financial pieces.
Bob: Amy? Katie?
Amy: I agree a hundred percent. I have run scenarios; I’ve been asked that exact question. And what we do is we run a side-by-side comparison. If all else is the same, here’s one version where you do buy a house, here’s one version where you rent. We typically assume rent does increase with inflation, as the years go on, because that’s what happens in real life.
In the house version, we do try to account for some annual cost to maintain and repair a home and we just look at the numbers, what looks better, what looks better it. You’re making guesses, you have to have some assumptions in there. But it is a really helpful way to, instead of just guess how does it feel, what numbers actually look like, your retirement plan will be more sustainable.
I think that’s one way to approach it is first you look at the numbers and if the numbers very clearly show one is better than the other, sometimes that’s all you need. What I do find is a lot of the times the numbers don’t really necessarily show one is that much different.
And so, then it comes back to the values conversation of, if you rent or you buy, maybe the plan still looks great, but which one feels better? Do you feel better having your own place that you can call yours or do you feel better knowing that if, you know, get termites, you can call a landlord and they can come take care of it. It’s kind of all those pieces together.
Bob: Katie, I’m sure you have some thoughts too.
Katie: Well, and the only thing I was thinking, because this is a question we get a lot of, is what makes the most sense? And, I hate the answer, is oftentimes it depends. It depends on how they spend and what that might look like. But really there’s the question of does it need to come out of my portfolio or should I save it?
I mean there’s also the option of does it make sense to take an amount out for a down payment and then do you qualify for a mortgage and can you get a mortgage to where you’re in a comfortable house that’s maybe spending less than what you were on rent? Another one of those examples of there’s always variables but that you can adjust in different scenarios.
So that would be one where you just, you have to crunch the numbers, but at the end of the day, where are you most comfortable and what’s going to provide you the greatest chances of success? Having it in your portfolio that you can access it or helping with cash flow by owning a home.
Bob (38:54): Another question is:
“How do you plan for retirement and your kids’ futures when you only have one income? Some of us don’t have child support or alimony. If there is any money left over, how best to invest for the kids’ 529 versus custodial account versus other options?”
Katie: Another great, great question. The first thing that I often think of is you can always borrow money for college and you cannot do the same for your retirement. So, make sure, I know it’s hard, I’m a mom myself, so I want to set my kids up with, to be successful, to do everything in my power to make sure that they have the money that they need to do X, Y, and Z. But a good way to think of it is doing, you’re doing them a service by taking care of you first.
Make sure you have what you need in retirement and then what makes sense if, how much do you want to contribute to the future? What is the goal for the money? If it is for college, then 529s are an excellent tool. And if you want to just have some money set aside for them to have complete flexibility of what they use the money on, then custodial account is a good option. If you want to set it aside in a brokerage account in your name and you don’t necessarily know where you want it to go or what that will look like, but the ability to use it on yourself if you need to, that’s when I go the third option for a brokerage account.
But pay yourself first and then really be clear about what you want to save for, for your kids, and then see if you can come up with some compromise to make sure you’re taking care of both goals but not sacrificing your retirement first.
Bob: Great advice. Amy or Rick?
Amy: I agree with all of that. I went through a brief moment of thinking I was going to start being really generous and saving for my kid’s future and then all of a sudden, we had three of them and I was like, you know what, let’s go back and look at my goals. And what I try to think of too, everything Katie said is totally true.
But I also just think of, if you save for your retirement first, one of the kind of lights at the end of the tunnel you can look forward to is if you put yourself in a really good place for your retirement, maybe what will happen is by the time your child gets to college age, you are in a better position to maybe help them.
You’ve saved for yourself, and maybe you don’t have a ton saved towards their college or saved towards their first home or whatever it may be, but now you’re more financially secure enough to be able to maybe help them with covering some of the costs of books or taking money from your own savings to just help make their life a little bit easier, so it doesn’t have to be all or nothing.
Rick: And I think college planning could be a whole other webinar, actually a 10 hour one. But as a single parent that’s not earning a huge amount of income, there are opportunities for more financial aid. and we don’t know if the child is two years old now, we don’t know 16 years from now what that’s going to look like.
But again, I think Amy and Katie are right on board. It’s kind of [like] putting the oxygen mask on yourself first on the plane before you put on someone else because if you don’t take care of yourself then your kids are going to end up taking care of you and that’s probably not a good thing either.
Retirement first, there’s always a way to pay for college. But as Katie pointed out, as far as I know, I haven’t seen any loans for retirement unless it’s like a home equity line of credit and that’s not a good strategy so don’t do that. So yeah, there’s always a way to pay for college. It might be a different school or it might be something else.
Bob (42:47): Another question is:
“How do you find a retirement planner who’s also an expert on taxes? I can’t seem to find them wrapped into one person and then when they are separate, the perspectives and advice don’t mesh.”
Rick: That’s interesting. I’m thinking they mean saving for retire, like having a retirement plan, but also looking at the tax implications. There are certified financial planners that are also CPAs out there and there are also certified financial planners that are very well versed in taxes. I would just recommend probably interviewing more people and finding the right fit.
Katie: It’s also becoming increasingly common for firms to have CPAs on staff. I know at Buckingham we have CPAs that will actually do your tax return and then you have an adviser and then they work together to make sure that your retirement plan and your tax plan are cohesive. I think that is becoming more and more common at firms. So that might be a good option, looking for a firm in your area that has an offering similar to that
Bob: Amy?
Amy: Yes, we do the same as Katie described. And I would say, also, one of the things that I find is that if you look for a financial planner who leads with a financial plan, usually you can find more of that comprehensive advice.
What I mean by that is, a lot of times, it’s unfortunate but people call themselves financial planners or financial advisers, and they don’t ask you anything about a financial plan, they just want to manage your investments. Which is an important piece of the puzzle. But generally, we always say at Sensible Money is, if you ask us how to invest your money, we’re going to say, well, we have no idea, what’s your plan? We need to know the plan so we know how to invest your money.
And think if you go out looking for a financial planner or an adviser that does the plan first, usually you find that that approach also translates really well into also looking at the tax piece, too, because they are connected.
Bob (44:59): Another question we got revolves around, we mentioned risk tolerance earlier about investment planning and saving investing. The comment is:
“I can say that risk capacity will also change and it should be reassessed along with risk tolerance as a result, as the asset allocation strategy will most likely change and the new financial plan will be the blueprint for this. Any thoughts about that?”
Katie: I mean as your risk capacity changes depending on, most of the time after a divorce, not only will the tolerance for risk, but also it becomes, for a lot of people, they can need and want a sense of security. So as far as risk is concerned, it becomes just as important if not more important to retain what they’ve saved and what they’ve walked away with. And that outweighs sometimes doubling or tripling it in, if you’re following me there, just the financial situations change. So certainly, I would agree with that.
Bob: Rick or Amy, any additional thoughts?
Rick: I think risk tolerance is one of those things, depending on when you measure someone’s risk tolerance, if you measured it this year, I think you would get a very different score than if you measured it two years ago. It’s usually changing as someone ages; it probably changes because they’re getting closer to maybe not working. It’s something that is an important conversation to have and ongoing as well.
Amy: I would just add, too, that if you’re talking to a financial planner and you don’t feel comfortable with their approach, keep looking as it’s not a one-size-fits-all. There are lots of approaches out there to investing and retirement planning and you have to find one that you’re comfortable with.
I think it’s important to interview a lot of different people and find one that just does feel like the right fit for you. Some approaches are more risk averse and some are more comfortable with risk and you have to find the one that you can sleep at night using because if it’s something that you don’t feel good about, you’re not going to enjoy it, you’re not going to feel comfortable with it and you’re probably going to change course at not a good time. You need something that fits with you.
Bob (47:24): We have about 10 minutes left. We have a boatload of questions here. I’ll try to go through them as quickly as possible. The next one reads, I’ll try to paraphrase:
If someone has sufficient equity in their house, could they look at a reverse mortgage for purchase with no mortgage having to be made?
Katie: So, if they have sufficient equity, that would assume they already own the house. Yes, it’s an option. That’s certainly an option. I have clients with reverse mortgages that it made sense at the time. So really that’s one of those things that you’d have to evaluate.
Bob (48:01): All right. I’ll move on to the next one. We’ll do this rapid fire.
“What do you do first? Find a financial planner or an estate planning attorney. Can one person set you up with everything? How do you leave money for someone who has a mental illness?”
Rick: Great questions. I think they both dovetailed together because definitely someone with mental illness, you know would probably use a special needs trust. You need an estate planning attorney to do that piece. I personally would, I’m guessing biased, but I would start with a financial planner because they have other relationships generally with CPAs and estate planning attorneys and they might be able to find a really good fit for you based on their needs. So that’s where I would start.
Amy: I would just say to start with, if you find a really good estate planning attorney and you trust them, you start there and they probably have recommendations for a financial planner just like the other way around. I do think it goes back to finding someone you’re comfortable with first and foremost.
Bob (49:05): All right, so let’s see. The next one I have is:
“I plan on selling my house when I have two of my three out of the house. Should I invest the profit from selling my house, approximately six years away, or put profit towards a smaller mortgage when you would be about 10 years from retirement?”
Amy: That dreaded answer, it depends.
It depends on the math. I would say if it was two years ago, most of the time the math would support taking the cash and investing it because mortgage rates were so low. With mortgage rates continuing to creep up now, running the numbers and really look, doing a comparison, is so much more important because it does really depend.
I think when you’re looking at retirement planning, generally we want to assume a pretty conservative rate of return on your retirement investments. The concept of you want to under promise and overdeliver. You’d rather plan for the worst, hope for the best.
So, if you were conservatively saying, oh my retirement investments maybe will average 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} a year over my lifetime, but now you have to get a mortgage with a 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} interest rate, quick math just says, oh, I’m paying 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on the debt and I’m only going to earn 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} on the investments, I would rather pay off that mortgage as quick as possible. Those are some of the rules of thumb, but it really does come down to, again, comprehensive plan and just looking at how all the pieces fit together.
Bob: No getting around that plan, I think.
Amy: We all need bumper stickers. “It depends,” the financial planner’s favorite answer.
Bob (50:43): All right, we got the one last question here.
“What if you had everything in place, including long term disability, and became disabled and employer long term disability denied your benefits, typical, can never work and you’re only 57 years old. SSDI doesn’t cover much even though I’m maxed from it. Is the only option alimony modification? What happens when I turn 65 and alimony, a very low amount, ends?”
That’s a lot of questions.
Amy: I don’t know if I have an answer for that one.
Rick: Not a simple answer, for sure.
Katie: And that would be a good example of a time where working with someone who can take a look at your current disability policy, make sure that, I mean ,of course you wanted to look at it before you’re disabled to make sure that it is the type of coverage that you’re hoping and needing. It sounds like you’re already disabled, so having someone look and make sure that the insurance company is correct in their denying of benefits, that there, there’s not any other options there.
And, I would just see if I could find somebody who knows disability insurance well and the options with Social Security to help you evaluate those options. I actually might start with going back to the attorney that you worked with and seeing if there is, how much it’ll cost to modify your alimony, and if there are any options to having it go beyond 65. But that really depends on your case and what state you live in and what the options are there. So, in your case, I might start back with the divorce attorney and then work with someone who specializes in disability.
Rick: And I imagine that some disability insurance companies just deny a claim the first time around, and Social Security might. So, it’s definitely worth, again, like Katie mentioned, get an expert in and look at reapplying and challenge them, and maybe they’ll change their answer.
Final Thoughts from the Panelists
Bob (52:56): We have about four minutes left. I want to leave time for each of you to provide a summation of “what now?” questions, now that someone might be divorced and embarking on their new life. Rick, why don’t we start with you?
Rick: So, I guess we start with, it depends, and also, it’s really important to have a good comprehensive, holistic plan to really look at every detail. And again, as Katie pointed out, we don’t want to overwhelm people, so we just bite off as much as we can chew and start with the more important things first and then work our way down the list.
And it might take a few months, it might take a year, but it’ll get done. And especially if you’re working with someone that can kind of keep you on track. And I think that’s really, really key.
Bob: Amy?
Amy: Yes, I a hundred percent agree with the comprehensive financial plan, identifying what your goals are and then sitting down and taking the time to map it all out is important.
I think the other thing I would just say is I always try to be a glass half full person and I think we all go through really challenging times in our life, some more so than others. But as hard as it is to go through it, I always just try to remind people that you will get through it. It’s going to stink right now while you’re in the thick of it. It usually is really overwhelming and it’s hard to think about what life might be like on the other side. But I think that also just adds to the importance of sitting down, thinking about your goals and trying as much as you can to think of it as a fresh start and a new opportunity.
And hopefully it, it’s the bad stuff’s behind you and the good stuff is what you have to look forward to.
Bob: Katie, you get the last word here.
Katie: Okay, so I’m going to go with very simple advice. Just staying organized.
You have a laundry list of things that we’ve told you, we’ve shared with you a lot on your to-do list. One of the best things you can do for yourself is just stay organized and if you need a little bit, help finding someone to be an accountability partner.
If you don’t have access to a financial adviser, aren’t already working with someone, find someone else in your life that can check in with you to make sure that you’re getting all of these things crossed off your list because they’re so, so important. So just find anyone that is willing to help nudge you along and provide friendly reminders.
Bob: Well Rick, Katie, and Amy I want to thank you for sharing your knowledge and wisdom with our attendees today. It is greatly appreciated and I want to thank all the attendees for today’s session. It has been recorded. We will post it on Retirement Daily so you can view it again if you miss something or want to re-listen to it at a future date. And again, we’ll thank you.
We plan to do these webinars every quarter. We plan to focus on a different topic. I guess I should ask Amy, Rick, Katie, is there a topic that we should drill down on the next webinar?
Amy: Trying to think what’s the most important.
Katie: I mean, investing in retirement planning, we could probably all three talk for hours about each of those topics. So, getting a little bit more specific on strategies and ideas and things like that would probably serve people well.
Amy: Right.
Bob: Perfect. That’ll be the topic for the next one. Thank you again for attending and thank you for being our special guest today to help folks. Thank you again
You May Also Like…
Other relevant articles from Retirement Daily
Think You Can’t Retire Now? Think Again.
Our expert shares the four key factors to a financial plan and what determines if you can retire now versus later on.
Ask the Hammer: Are Medicaid Compliant Annuities a Good Idea?
Jeffrey Levine covers the topic of acquiring Medicaid compliant annuities.
Talkin’ Turkey: Medigap or Medicare Advantage Plans?
TheStreet
Ten questions to liven up your Thanksgiving conversations.
Private finance is a intricate element of lifestyle. For example, you can not just get your money, subtract bills, and see what is still left. Confident, which is where by it commences. But plenty of further, nuanced things also component into a balanced budget and productive prosperity generation method. Therefore, it can help immeasurably to insert at the very least a number of personalized finance tech applications to your toolbox.
With that in mind, below are some tips for the finest personal finance tech equipment that deliver person-pleasant and efficient guidance for performance-minded people.
1. Veteran.com keeps you up to date.
Usually the best individual finance solutions modify to your particular wants. If you commit far too significantly, a expending tracker is useful. If you are a saver, a retirement app is a fantastic in shape.
In some cases the applicability of a particular finance instrument can be even extra precise — as is the scenario with Veteran.com. The armed forces-focused web-site offers a broad array of methods for both latest navy members and veterans.
Alongside with blogs and assets on education, work opportunities, and housing, the well-liked web page has an overall portion dedicated to cash and finance. This features navy pay charts, an up to date army shell out calculator, and even a VA Disability calculator.
As veterans and lively users of the armed forces navigate their particular funds, the website can deliver a regular stream of handy data.
2. Acorns aids with personal savings.
Running to help save income is one of the most popular personalized struggles at any time. Trying to do so when inflation costs are high can really feel unattainable. The temptation to shell out dollars on requirements and desires alike can be difficult to get over. Empty financial institution accounts and crowded credit card statements can leave you feeling pressured.
Enter Acorns. The monetary technological know-how company enables buyers to invest seamlessly in their future. Its on the internet application and banking tools are user-friendly, holding things uncomplicated and uncomplicated at every single move. At the very same time, they are backed by authorities from significant investment firms like BlackRock and Vanguard.
The revolutionary financial institution delivers various equipment to enable folks dominate their funds and build towards a improved long run. One particular of these applications is the company’s computerized price savings and investment decision option. This rounds up every single transaction that usually takes spot, placing the further dollars into effectively-balanced, professional-developed portfolios. As a outcome, the final result is superior monetary awareness and a sluggish-but-steady trickle into your personal savings.
3. Mint provides you a economical snapshot.
Some persons require targeted particular finance tech applications. Other folks will need extensive alternatives. If you find that you’re in the latter category and an eclectic fintech stack isn’t supporting, you could want to test the Mint app.
Mint is an software with a higher popularity. It can backlink to multiple checking accounts, integrating your assets into a solitary dashboard. This offers you a unified economic snapshot that can help you see constructive and unfavorable tendencies before they get out of hand.
The strong software program alternative can also categorize transactions, forecast investing patterns, and create price range suggestions. This offers a continual stream of insights that can foster beneficial money practices.
4. Particular Capital is thorough finance defined.
Another software identical to Mint is Own Cash. The prosperity management application presents a in depth and insightful money overview.
At the time again, this piece of fiscally-minded computer software has the electric power to carry with each other a number of money information sets. You can url up distinct own examining and cost savings accounts to create an amalgamated snapshot of your current finances.
Alongside with aiding with budgeting and hard cash stream, Personalized Funds also presents a price savings planner and net really worth choices. The former helps develop and observe price savings targets. The latter gives you an correct watch of your net truly worth at any minute.
The application also has in depth retirement personal savings alternatives, this sort of as a retirement planner and a price analyzer. These assets can aid keep track of any peaceful or hidden charges to your very long-expression financial savings. You can even evaluate if you are preserving more than enough for foreseeable future academic fees and can periodically carry out an investment checkup.
5. Position Revenue provides you comparables.
Evaluating your own accomplishment to some others is a unsafe exercise. You really don’t want to stoke avoidable levels of discontentment or jealousy. And but, there are instances when observing how you stack up in opposition to others can present valuable information and facts.
Status Cash is the great resolution for people moments. You can input your different money owed and property into the app. From there, it analyzes them and then supplies comparables to other people in equivalent instances.
Wholesome doses of peer-to-peer comparisons can be a wonderful way to remain motivated. Consequently, it can also offer point of view and support workaholics and the hyper-bold let on their own some perfectly-acquired relaxation.
6. GoodBudget goes back again to budgeting roots.
Funds can come to feel frustrating. When which is the circumstance, occasionally the best alternative is a simple one. Which is where GoodBudget comes into the photograph.
The personalized finance instrument focuses on the strategy of relatable and consumer-helpful funds. In simple fact, it embodies the digital variation of one of the oldest and most grounded varieties of personal finance: the envelope program. That is a form of monetary organization that utilizes envelopes to divide and track cash, generating a organic barrier to overspending in the procedure.
GoodBudget gives you an app-driven envelope system alternative. Customers can divide their revenue into various “envelopes” that assist keep track of how significantly money they have still left in every single group. To be good, the consequence is very similar to most budgeting apps. For individuals who battle with partitions of figures and charts, even though, an obtainable visual like envelopes can make all the variance.
7. Prism will help you keep track of your expenses.
Own budgets are likely to aim on cash flow, bills, and financial savings. It will help calculate what you owe other people and how substantially you want to set apart for a wet day. But it does not actually pay out off your costs. Which is an additional stage that is effortless to forget — in particular if you have a ton of unique expenses to attend to on a regular foundation.
Prism is an application that assists eliminate the worry of the bill-pay cycle. Compared with more detailed options on this checklist, like Mint and Own Money, this is a fintech device devoted to a single exercise, and a person exercise only: spending your charges.
The app connects you with your several creditors. It syncs up accounts and tracks what you owe. These are then introduced in the Prism app, wherever you can see what you owe, when, you owe it, and to whom it must go.
8. Etrade helps manage investments.
If you already have a firm grasp of simple individual finance and you are searching to acquire the upcoming stage, you may want to contemplate Etrade. The financial prosperity management software package facilitates fingers-on buying and selling and expense. This turns an if not challenging activity into a really obtainable type of particular finance.
Etrade doesn’t acquire commissions and has a extensive selection of diverse financial commitment product possibilities. These incorporate the two energetic brokerage accounts as nicely as retirement alternatives. In possibly situation, if you want to remain concerned in your retirement organizing, Etrade presents you fast and quick accessibility at all situations.
9. Vanguard attributes automatic investing tools.
Vanguard is yet another retirement and financial investment-focused private finance alternative. The dependable brand name presents automatic investing instruments and reliable assist.
A vital factor that draws in several buyers to the prosperity management instrument is the truth that it is trader-centered — and that is not just referring to a purchaser support initiative. Vanguard is actively owned by those people who commit in Vanguard cash. As a consequence, this offers them a collective focus on mutual prosperity generation and effective asset management. Add its suite of complete fintech instruments, and it’s an uncomplicated choice for numerous in research of simple-to-use individual finance solutions.
10. Due will get top marks for producing prosperity.
It would be a gross oversight to neglect Because of on this listing. Lots of peg the common economical device as the internet’s amount one particular retirement useful resource. Forbes rated it as a top rated finance weblog with outstanding assets for these hunting to crank out wealth. Entrepreneur Magazine referred to as it one particular of the finest sites on the interweb to glean retirement info.
Due is the fantastic combination of methods and applications for private finance management and prosperity technology functions. The internet site has many finance-focused merchandise, from annuities to lifestyle coverage and past. It also has a wealth of information and facts in the variety of an ever-increasing website and a lengthy record of detailed guides that revolve around dollars and its administration.
Whether it is the need to have for quality fintech applications or a resource to advise your use of people applications, Due is the a person-prevent store for thriving particular finance.
Particular finance is constantly significant. In the course of economic and fiscal crises, it’s notably intelligent to acquire handle about your earnings, fees, and investments.
To sum up, use the checklist above to identify the greatest personalized finance tech tools to fill in your individual money shortcomings. Do you have to have a specific solution for some thing like shelling out bills? Or is a extra detailed application in buy? Think about your problem, make your collection, and then devote in taking your private finances to the following stage.
On December 12 Broadway star Jessica Vosk will return to Carnegie Corridor to accomplish Get Happy: A Judy Garland Centennial Celebration.
Garland, who would have been 100 this year created her Carnegie Hall debut just after almost 4 decades into her job. The exhibit was so famous, it is deemed to be a person of the most memorable nights in the Carnegie Hall’s record.
Jessica Vosk
Jenny Anderson
When a are living recording was launched a handful of months after it won five Grammys and was on the Billboard charts for 73 weeks. Garland turned the to start with solo lady to gain the coveted Album of the Calendar year.
In this tribute to the existence and artistry of Garland, Vosk will carry out her classic songbook amid rare performance footage of Garland herself. Vosk will sing alongside another theater excellent, Andy Karl, who has starred on Broadway in Groundhog Day, Rocky, Rather Girl, Legally Blonde and On The Twentieth Century. Get Happy also has a staff of creative large hitters. Penned by Robert Cary and Jonathan Tolins, the demonstrate is directed by Michael Arden with Mary-Mitchell Campbell as new music director.
Vosk, whose credits contain Elphaba in Wicked on Broadway, Joseph and the Amazing Technicolor Dreamcoat, Fiddler on the Roof, Finding Neverland and The Bridges of Madison County, was approached with this strategy all through the pandemic.
“It was coming up on Judy’s 100th birthday and produced me imagine, Wow. We shed this female so early in her existence, and nevertheless she’s been at any time current because then. Like she in no way left us,” states Vosk of Garland who passed absent eight years soon after her Carnegie Hall live performance when she was 47. “How do I honor the memory of this icon, who famously played Carnegie hall just before her demise, nonetheless ideally breathe new life into her cannon of new music? I like a tough process like that.”
As the previous joke goes, when the pedestrian approached a musician for instructions inquiring, “How you get to Carnegie Hall?” The musician replied “Practice. Practice. Practice.” In Vosk’s circumstance, not only was it apply that led her to Carnegie Corridor. She also received there by way of Wall Road.
Jessica Vosk
Matthew Murphy
Just before she even graduated from higher education Vosk took a position at a money organization in midtown Manhattan. “I begun entry stage, experienced no clue what I was executing, but was offered a dictionary of investment phrases, which I however have and a cubicle and informed what to do,” says Vosk. When she had clients in all locations of finance and was climbing the ladder of success in that entire world she left at the rear of her the piece of her that put in her childhood carrying out theater and singing.
“I fundamentally killed the inventive elements of me. I remaining it all driving. The theatre I did as a child, the singing lessons, the a great number of several hours of observe,” says Vosk who equates her singing to breathing. “All absent.”
But reducing off that vital component of her manifested in nervousness and in the long run whole-blown worry attacks. “I understood I experienced to repair it, and I resolved to leave the occupation,” she claims. “No safety net. Just hope. I belief My gut always, even to this working day. And my gut mentioned that if I failed to go soon after my passion, I’d regret if for the relaxation of my life.” Vosk was confident that even if she fell flat on her encounter which she however in some cases does she could say, ‘I took the chance on myself. I’m so happy I did.”
That hazard on herself compensated off. Seven a long time just after leaving her finance occupation Vosk made her Broadway debut in The Bridges of Madison County in 2009. In 2018, after enjoying her on tour, she landed the role of Elphaba in Wicked on Broadway.
Vosk says that her dive and persistence retained her heading. “I woke up for the cattle calls, I hardly at any time obtained observed since I didn’t have an equity card,” she suggests. “I stayed up for the open up mic nights exactly where I hoped a person “important” would hear me. I imagined that if I went By way of the sacrifice to give up a secure job for this new one I’d far better exhibit up . But it wasn’t really.”
Despite the exhaustion, sacrifice, melancholy and thickened skin, she credits the expertise as crucial to her progress. “It’s all a section of who I am today and why I’m below,” says Vosk. “But it has taken a great deal.”
Devoting a live performance to Judy Garland in the great hall where by she famous performer produced this kind of a profound effects is specifically significant. “To me, Judy was a creature of utter complexity. To loosely quotation her, she sang about rainbows and she’d been searching for rainbows for her entire lifetime. It is no solution that Judy had demons, but never we all,” states Vosk who is encouraged by Garland’s unwavering spirit. “The resilience and tenacity of this girl to endure in a enterprise considering the fact that age 3 is unbelievable. A business that was not kind to gals, in particular. Exotically all those two wanted to run their own demonstrate and be their possess manager.”
As Vosk sees it women like Garland developed the mildew and opened the doorways for other women like herself to run by. “She and numerous other gals are who I look up to as I go on to navigate my personal route,” claims Vosk. “These items are terrifying to do. They are lonely.”
So what can men and women be expecting to knowledge at Get Pleased? “They will see historic times Judy created, but also with a serious glimpse at the lifestyle Judy led—good, poor, magical and everything in between,” says Vosk. “And then you’ll also hear me belt my a** off.”