Cyber Monday personal finance gifts to buy now

Cyber Monday personal finance gifts to buy now
Blue sofa with gifts and table with laptop and credit card for online Christmas shopping.
From college financial savings strategies to retirement setting up and insurance coverage protections, offers tied to private finance are useful very long past the holidays.

Getty Photos


As the holiday browsing season heads into superior equipment with Cyber Monday, you may well want to glimpse for options to high priced toys or actual physical items. Think about a different kind of present – a money a single. There are lots of strategies to give generously moreover a wad of money or a verify inside a holiday break card. 

Begin with a discussion, suggests Angela Furubotten-LaRosee, direct economical planner at Avea Financial Organizing in Richland, Washington. Subjects can include running credit rating playing cards and personal savings, early vocation workplace added benefits and handling the economical photo for aging parents or retirement. Convey up what you have acquired from faults, much too, she indicates.

“Households just will not speak ample about the superior, the poor, and the reality bordering their have fiscal condition,” Furubotten-LaRosee mentioned.

Cyber Monday individual finance presents to obtain now  

Once you’ve talked with your family, you may have a far better idea of what would make a excellent reward. Right here are a handful of strategies from industry experts:

Money arranging

You can aid a beloved 1 straighten out their finances, program for the long run and even get their estate in order by selecting an online economic adviser or planner.

“For any person that does not previously function with a CFP,  gifting time with a single is great, specially this time of 12 months and can assist to start off the New 12 months on more powerful monetary footing,” reported Melissa Sotudeh, a CFP and director of advisory solutions at Halpern Economical, a Washington D.C.-location organization.

Get began on line now.

Estate planning 

Estate arranging, ncluding wills, wellbeing directive preparation and lifestyle insurance can be a specially helpful reward. 

“It is some thing that most people place off and won’t get for on their own,” reported Mark Struthers, a accredited monetary planner with Minneapolis-based Sona Prosperity Advisors.

Lifetime insurance 

Daily life insurance policies payments can also make a good gift as part of economical preparing at any age, like estate arranging, professionals note. Supporting somebody make payments to retain this protection may well be appreciated.

Get started off on-line now.

Contribution toward a Roth IRA

In 2022, the annual contribution restrict is $6,000 a 12 months or $7,000 a yr for individuals 50 or older, so be acutely aware of how significantly you’re contributing as opposed to a person’s restrict and past contributions.

Get started on the internet now.

Pet coverage

Pet insurance plan can be most welcome for the proper receiver

“I have experienced individuals give a certification to exhibit they purchased it and the folks that gained it cherished it,” Struthers states.

Get started on-line now.

Gold 

Gold is traditionally imagined to be a hedge towards inflation as its value can rise in an uneven financial system.  For youthful folks searching to diversify their portfolio, it could make sense to pursue gold as an asset. 

Get began on the net now with a absolutely free wealth defense package.

Money presents for kids 

There are various varieties of accounts that you can open for young children that will help them stay a financially safe lifestyle perfectly into adulthood. 

Custodial Roth IRA (or kid’s Roth IRA)

A custodial Roth IRA follows Roth IRA principles with some significant caveats. A custodian manages soon after-tax contributions – commonly, a parent, guardian or grandparent – till the child reaches legal adulthood (age 18 to 21 depending on the state).

“In purchase for the little one (or anyone) to be in a position to make a contribution to a Standard IRA and/or a Roth IRA, the little one must have their own acquired cash flow for the contribution yr,” stated Alicia Reiss, a qualified monetary planner (CFP) and owner of the digital business The Organization of your Everyday living.

Small children never have to have to use their very own dollars to make the contribution but contributions can not exceed additional than the kid gained that calendar year, Reiss provides. 

Get began on the net now.

529 prepare for college or university

A 529 account will work like an financial investment account for educational uses only. Details fluctuate by state and contributions to 529 ideas can be useful when it will come to taxes. Funds may well only be withdrawn for particular instructional applications or you will facial area a penalty.

A 529 approach “can be improved than the [children’s] Roth given that the owner, the mother or father, or the grownup, does not give up manage,” mentioned Struthers. “And simply because it is schooling distinct, it tells the baby that you imagine that they CAN get the grades and CAN get into faculty.”

Uniform Transfer/Gift to Minors Act accounts (UTMA/UGMA)

These are investment accounts designated for little ones that transfer to them at the age of the vast majority – 18 in most states but up to 21 in others.

Don’t forget to check tax boundaries and rules

It truly is essential to be aware of gift and estate tax restrictions, notes Brett Spencer, a CFP and founder of Boston-based mostly Affect Economical.  For 2022, gifts in excess of $16,000 (the once-a-year exclusion amount of money set by the IRS) can be taxable.

It also assists to be mindful of financial aid qualification restrictions, especially if a young grownup is receiving completely ready to fill out a Federal Software for Financial Student Assist or FAFSA, authorities be aware.

“If a present is intended for a grandchild’s training, grandparents may possibly want to own the account with the kid listed as the beneficiary,” Spencer notes. That’s simply because the belongings of both of those mom and dad and child may well be counted when calculating higher education economical assist eligibility. Grandparents usually are not generally regarded in the equation, he notes. 

What 5 key personal finance issues mean for you

What 5 key personal finance issues mean for you

As Individuals head to the polls, quite a few essential personal finance concerns are weighing on voters’ minds and wallets.

This week, the Federal Reserve enacted its fourth consecutive .75 share position interest level raise to struggle inflation, triggering further stock marketplace losses.

In the meantime, recession fears are growing, with 84{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Individuals worrying how a extended economic downturn may affect their funds, in accordance to a MassMutual report released Thursday.  

Much more from Individual Finance:
What the Fed’s .75 share position curiosity amount hike usually means for you
Democrats warn that Social Safety, Medicare are at stake
What ‘millionaire tax’ plans on the ballot in California and Massachusetts indicate for best earners

“The over-all financial system has been so important, and I feel it truly is influencing the elections,” stated lawyer Marc Gerson, member chair of the tax division at law firm Miller & Chevalier in Washington D.C.

Some difficulties appear on condition ballots, but federal plan depends on which occasion controls Congress. Although Republicans are favored to earn the Household, the Senate hinges on a handful of aggressive races.

Below are five of the most pressing problems this election period — and how Tuesday’s final results may possibly have an effect on your wallet.

1. Democrats cite threats to Social Protection, Medicare

As Election Day strategies, Democrats are telling voters that Social Safety and Medicare could be at hazard if Republicans take manage of Congress.  

“They are coming immediately after your Social Security and Medicare in a big way,” President Joe Biden reported in a speech Tuesday in Hallandale Beach, Florida.

The Inflation Reduction Act enacted Medicare reforms to decrease prescription fees for retirees. Having said that, Republicans could try to halt these changes, Biden reported.

He also pointed to probable pitfalls to Social Security, based mostly on plans from sure Republicans, including Sens. Rick Scott of Florida and Ron Johnson of Wisconsin. But each lawmakers have denied intentions to damage the program.

Scott has named for reauthorizing Social Safety and Medicare every single 5 several years in Congress, when Johnson implies revisiting the systems annually.   

2. Republicans force for even more tax cuts

3. Least wage hikes on the horizon

4. A achievable huge gain for unions

Coming out of the pandemic, union support is at a document substantial. Additional than 70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Us citizens approve of labor unions, a Gallup poll recently found.

The final result of a ballot evaluate throughout the midterm election could speed up that expansion: Voters in Illinois will make a decision whether or not to supply personnel with the elementary right to organize and deal collectively.

If the provision will become regulation, “it will reveal solid well known guidance for labor legal rights in a big, essential condition,” said Daniel Galvin, an associate professor at Northwestern University whose analysis spots involve workers’ rights and labor politics. “It would also sign to the rest of the country that the appropriate to cut price collectively ought to be observed as a essential correct worthy of constitutional defense.”

5. ‘Millionaire tax’ in California and Massachusetts

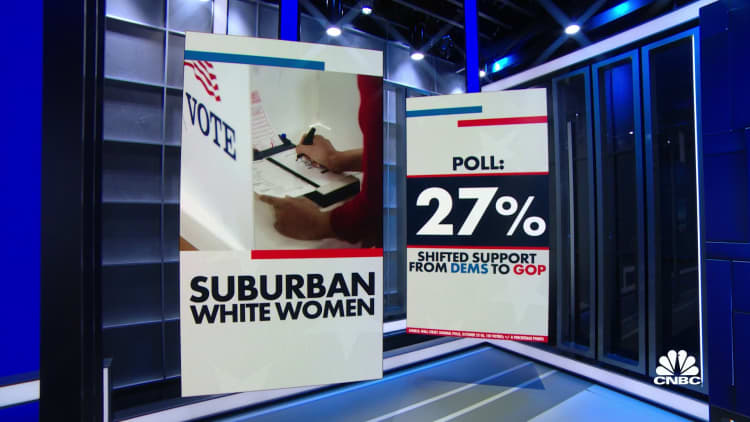
Polls show Republicans poised to win in midterms

What Is a Fintech Degree? How Finance & Tech Meet

What Is a Fintech Degree? How Finance & Tech Meet

If you’re interested in pursuing a career in finance, you may be wanting to know what diploma you must generate. A rising area that combines finance and technologies is fintech. But what is a fintech degree, and what can you assume to understand? We fulfilled with Dr. Theo Owusu and Dr. Donald DeSormoux, two gurus in the discipline, to examine the fundamental principles of fintech and why a degree in fintech is well worth your though. So if you are ready to study more about this enjoyable field, preserve looking at!

What Is Fintech?

Fintech, short for monetary engineering, is a promptly increasing field that refers to the use of technologies to streamline and improve traditional economical providers. Fintech organizations normally use impressive technological know-how to present far more practical, protected, and economical solutions to customers and organizations than standard economic establishments. In recent several years, fintech has been one of the swiftest-expanding industries in the globe, with new startups popping up throughout the world.

Many experts believe that the world-wide fintech marketplace will grow exponentially in the coming a long time and that fintech will revolutionize the financial sector as we know it. Presently, fintech is disrupting classic monetary establishments and giving new opportunities for people and firms alike. If you’re fascinated in the foreseeable future of finance, fintech is surely a thing you really should hold an eye on. And as much more and additional folks undertake electronic gadgets and mobile applications for their daily banking requires, it is probably fintech will only continue to expand in level of popularity.

Illustrations of Fintech

Some of the most popular illustrations of fintech consist of:

  • Mobile banking
  • Peer-to-peer payments
  • Expense administration apps
  • Electronic currencies
  • Cryptocurrency exchanges
  • Budgeting and personal finance applications

Fintech startups are continuously producing new and progressive approaches to enhance money expert services. As the marketplace carries on to increase, we can assume to see even additional amazing illustrations of fintech in the decades to occur.

How Fintech May well Previously Have an impact on You

You may well not know it, but fintech is by now impacting your existence. From mobile banking apps to cryptocurrency, fintech is transforming how we regulate our income. Here are some approaches that fintech may well now be impacting you:

  • If you have at any time produced an on-line buy, you have applied fintech. On the web payments are processed making use of electronic signifies, these as credit cards or PayPal. This is a handy way to pay out for goods and providers without having having to have hard cash.
  • Cellular banking applications are 1 of the most popular purposes of fintech. These apps allow for you to examine your equilibrium, transfer resources, and pay charges from your smartphone. If you use a cellular banking application, you’re using fintech.
  • If you have at any time made use of a rideshare application like Uber or Lyft, you have employed fintech. Rideshare applications use GPS technologies to join motorists with travellers. The fare is then calculated and paid out for electronically devoid of needing dollars.
  • Fintech is also currently being employed to create new types of forex, such as Bitcoin. Bitcoin is a digital currency that allows end users to make peer-to-peer transactions without needing a central financial institution or middleman.

And whilst some areas of fintech are continue to in the early levels of development, this engineering will most likely continue on to influence our life significantly. As fintech continues to evolve, we will probably see even additional variations in how we deal with our finances.

Fintech Businesses

Fintech companies are swiftly altering the money landscape. From cellular apps that assist you finances your investing to on the internet platforms that make it easy to make investments, fintech corporations give new and hassle-free means to regulate your finances. By offering intelligent options to prevalent troubles, fintech corporations are creating it less difficult than at any time for individuals to control their cash. Some fintech companies you could by now do small business with contain:

  • PayPal is a common on the net payment program that will allow users to make payments and send out revenue securely around the internet.
  • Sq. is a cellular payment method that lets organizations to course of action credit rating card payments making use of their smartphones or tablets.
  • Mint is a common budgeting and particular finance application that can help users track their paying out and conserve income.
  • Robinhood is a fee-no cost inventory trading application that enables users to get and sell shares with no paying costs.
  • Wealthfront is an automatic expense management company that helps consumers help you save money on financial commitment service fees.
  • Acorns is a cellular app that helps users conserve and devote their spare alter.
  • Betterment is an on the net financial investment system that features customers a very simple and effortless way to make investments their funds.

In quite a few circumstances, fintech providers can supply these products and services at a portion of the value of traditional economic establishments. As a final result, fintech companies are escalating in reputation and will continue to considerably effect the financial market in the coming a long time.

Sorts of Fintech Levels

If you are searching to get into the remarkable subject of fintech, you are going to will need the right schooling. No make any difference what form of fintech diploma you decide on, make positive a trustworthy firm accredits it. This will ensure that employers in the sector realize your diploma and that you are acquiring the good quality education you need to have to succeed in this competitive field. Here are some of the diverse sorts of fintech levels that can help you land a task in this rising field:

Undergrad

Learners fascinated in pursuing a profession in the fintech business may perhaps question no matter if they will need to get an undergraduate degree in fintech. The remedy is that it relies upon. Though getting an undergrad degree in fintech can definitely give you a leg up in the task market, quite a few schools have still to acquire this kind of a system, and there are quite a few methods to crack into the field with out a single. Lots of fintech companies want choosing personnel with a finance, computer system science, or engineering history. The crucial thing is to make certain you have the foundational expertise and know-how in the finance and engineering sectors that employers are seeking for.

Learn

A fintech master’s diploma can give students with the understanding and abilities they need to have to realize success in this promptly shifting sector. It will typically cover subject areas these as economical regulation, financial commitment banking, possibility administration, and details analytics. In addition, college students will have the option to achieve fingers-on practical experience, no matter whether via internships or in-course lab assignments.

According to Dr. Owusu, this palms-on experience is critical to creating the practical information college students will need to thrive in a fintech profession. For case in point, in the details analytics class at Keiser University’s Master of Science in Financial Technology program, learners have the option to conduct data analyses employing the types of instruments they will use in their upcoming occupations. There is a extensive gulf in between looking at about how knowledge assessment and visualization work in theory and really carrying out it. A good quality master’s system in fintech need to thus include things like these immediate, energetic discovering experiences.

Certificate

If you are fascinated in pursuing a occupation in fintech, but don’t want the time motivation of a degree plan, then you may want to contemplate receiving a certificate in fintech. There are a several different means to get a certification in fintech, but a single of the most common is on line courses. These courses can be taken at your possess tempo and ordinarily include subjects like money technological know-how, digital banking, and blockchain. With a certification in fintech, you’ll be equipped to exhibit your information of this fast developing industry and demonstrate businesses that you’re ready to do the job in this remarkable subject.

Just one disadvantage to certification in fintech is that they swiftly turn out to be outdated. As Dr. Owusu pointed out, certificates can expire every single 5 years, meaning you would then have to reapply for certification. A degree, on the other hand, by no means expires. So whilst the upfront commitment of a certificate application might be beautiful, keep in mind to look at the prolonged-term implications of this instructional route.

Online Vs. In Particular person

There are a several key criteria to hold in mind when selecting regardless of whether to get paid a fintech degree on-line or in person. A single of the most important variables to contemplate is your learning model. An in-particular person application might be a greater healthy if you want a much more palms-on method. On the other hand, if you are the sort of learner who prefers to do the job at your individual speed, an online method could be a far better selection.

Yet another vital thing to consider is your schedule. An on the net software could possibly be much more easy if you have a complete-time occupation or other commitments that make it tricky to show up at classes in particular person. On the other hand, if you can devote the time to attending courses on campus, an in-human being method can give a much more immersive working experience.

At last, it is important to look at your price range when generating your choice. In standard, on the internet programs are a lot more economical than in-particular person packages. On the other hand, there may well be some supplemental fees linked with an on the web method, these kinds of as personal computer products and software. Eventually, irrespective of whether to go after an on the internet or in-particular person fintech program depends on your person requirements and preferences.

Programs You Could possibly Consider in Fintech

A good quality fintech program will provide classes masking the gamut of recent and emerging technologies for economical services, so graduates are perfectly-positioned for leadership roles in modern-day finance and electronic forex environments. Conventional programs you can assume to take in a fintech plan incorporate:

  • Knowledge Analytics
  • Artificial Intelligence & Equipment Studying
  • Digital Payments and Market Lending
  • Cryptocurrency and Blockchain
  • Facts Visualization
  • Fintech Law & Coverage
  • Technological know-how Innovation
  • Money Security

Opportunity Jobs for Your Fintech Degree

The fintech industry is escalating swiftly, ensuing in a developing need for workers with competencies in this region. Competitiveness for jobs can be intense, so planning oneself with a complete knowing of know-how and how it can be used to finance is essential. Fintech is an at any time-evolving discipline, so you need to be at ease with change and adaptable to new systems and developments. And quite a few fintech firms are startups, so you really should be prepared for a quick-paced work atmosphere. With these points in thoughts, if you consider a career in fintech would be a superior match for you, below are some typical positions in fintech you could utilize for:

  • Economic technologies analyst
  • Blockchain developer
  • Quantitative analyst
  • AI developer
  • Possibility and compliance technological innovation officer
  • Main engineering officer
  • And extra!

Is a Fintech Degree Value It?

As businesses turn out to be extra reliant on technological innovation, the will need for staff members with both equally money and technical competencies will only expand. A fintech degree offers the best mix of coaching in the two spots, generating you a really sought-soon after staff. As the finance and technology industries carry on to merge, a fintech diploma can be beneficial and valuable.

There are several positive aspects to pursuing a fintech diploma. Probably the most clear is the earning possible. Fintech employment are among the the highest-shelling out in equally the finance and tech industries, and as the demand from customers for fintech personnel grows, so also will salaries.

In addition to the earning possible, a fintech degree also gives exceptional work safety. As prolonged as finance and tech continue to converge, there will be a need for workers with fintech competencies. Even if you reduce your career, finding a different 1 in the identical area will be easier than a lot of other fields.

Eventually, a fintech diploma can be immensely gratifying. If you are intrigued in the two finance and technological innovation, pursuing a fintech degree permits you to combine your two passions into just one occupation. What could be better than having paid to do what you like?

Keiser College provides an excellent graduate-degree money technological know-how diploma if you are completely ready to start your career in fintech. Graduates of our 100 percent on the internet, palms-on graduate plan are geared up to deliver improved money solutions to clients and organizations by leveraging new systems, aiding economic companies with handling different fiscal features of their small business, and giving strategic direction relating to new technologies for corporations in an array of industries. Speak to us these days to master additional about our master’s in fintech!


Impact Experience’s Business Climate Finance Initiative Applauds and Welcomes U.S. Department of Labor Final “ESG Rule” Release

Impact Experience’s Business Climate Finance Initiative Applauds and Welcomes U.S. Department of Labor Final “ESG Rule” Release

OAKLAND, Calif.–(Business enterprise WIRE)–The Company Local weather Finance Initiative (BCF), incubated by Impact Practical experience, applauds and welcomes the launch of the Office of Labor’s Ultimate Rule on Prudence and Loyalty in Picking Approach Investments and Working out Shareholder Legal rights, on November 22, 2022. The Ultimate Rule is a considerable clarification of the Employee Retirement Money Stability Act (ERISA) specifying that fiduciaries, in this scenario 401(k) or described profit plan sponsors, “may think about local climate change and other environmental, social, and governance (ESG) variables when they make investment selections and when they exercise shareholder legal rights, including voting on shareholder resolutions and board nominations.”1

As an firm that supports companies to assess and disclose the weather impacts of company funds deposits and retirement ideas, as very well as to decarbonize people assets, BCF thinks that the Final Rule will allow for retirement program sponsors to a lot more proactively account for ESG elements, which includes climate and carbon-connected dangers, in the financial investment menus they offer you to 401(k) system contributors.

There are a lot of important provisions in the Remaining Rule, including people associated to how the thought of ESG aspects may align with fiduciary responsibilities of prudence and loyalty, and how ESG factors might be considered in the application of shareholder legal rights, together with proxy voting.

In addition, the Closing Rule gets rid of exclusive, more restrictive procedures for a 401(k) plan’s Certified Default Financial commitment Choice (QDIA) that ended up used in the 2020 procedures promulgated by the prior Administration. Although the prior rules prohibited the consideration of ESG things in any investment fund specified the QDIA for a retirement plan, the Closing Rule gets rid of individuals restrictions, meaning that program sponsors can now possibly give ESG-oriented target day and other diversified fund alternatives as the default choice for new strategy contributors. Focus on day money and other “hybrid” automobiles built up about 27{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of all defined contribution strategy property in the first fifty percent of 2022,2 so this is a most likely major option for system sponsors to prudently deal with weather change and other ESG concerns.

Eventually, the Last Rule explicitly notes that retirement plan participants’ views on investing in ESG and related factors can be thought of by approach fiduciaries in deciding approach menu choices, perhaps paving the way for personnel to participate in an significant function in shaping the ESG techniques of the retirement plans they are saving for the future in.

Jenna Nicholas, CEO of Influence Practical experience, claimed, “With this extensive-ranging and ahead-looking Remaining Rule, the Division of Labor has obviously acknowledged that considering local climate, carbon, justice, equity, range, and inclusion (JEDI) and other ESG-similar lenses can be nicely-aligned with prevailing standards of fiduciary responsibility. In the week pursuing the summary of COP27, and the enhanced target on mitigating future local climate impacts and addressing historic injustices that it brought, this Ultimate Rule will provide to unlock billions of dollars of retirement money in direction of achieving increased alignment with international weather aims.”

ABOUT Small business Local climate FINANCE

Effects Practical experience builds bridges and deep relationships in between associates and communities to shift funds marketplaces towards more equitable practices. Influence Working experience is incubating the Organization Weather Finance Initiative. The Company Climate Finance Initiative was launched with two plans in brain: 1) evaluate and disclose the climate affect of company dollars deposits and retirement funds and 2) decarbonize bank accounts and personnel retirement ideas, beginning with a team of major US companies. Via study and convenings, the Initiative will assistance assist communities of apply between companies who will be functioning toward these targets implementing a distinctive Justice, Fairness, Variety and Inclusion lens. For more facts on this initiative, see www.businessclimatefinance.org or comply with Affect Working experience on LinkedIn, Twitter and Instagram.

1 Ultimate Rule on Prudence and Loyalty in Deciding on Plan Investments and Exercising Shareholder Legal rights (dol.gov)

2 Quarterly Retirement Marketplace Info | Investment decision Business Institute (ici.org)

3 Things Personal Finance ‘Experts’ Get Wrong

3 Things Personal Finance ‘Experts’ Get Wrong
Young woman listening to podcast on her headphones while drinking coffee.

Graphic supply: Getty Visuals

We protect a lot of guidance from personal finance gurus right here at The Ascent. In numerous conditions, these people are plugged into the shelling out and personal savings practices of Us citizens, and often, they themselves have been way down in the depths of personal debt and dire money instances, so they have wisdom to impart. In addition, assistance from finest-offering authors and radio exhibit hosts tends to be a great deal additional accessible than facts from teachers, like economists. That said… are personalized finance gurus generally supplying you the appropriate facts?

Recently, the podcast Freakonomics Radio (a individual most loved of yours actually) questioned the problem, “Are Particular Finance Gurus Providing You Negative Suggestions?” In this episode, the Freakonomics crew spoke to Yale College economist James Choi, who performed a study of suggestions presented in 50 guides by particular finance authorities vs . knowledge espoused by economists, and mentioned the variations when it arrived to saving income, taking care of personal debt, receiving a house loan, and additional. Let’s get a glance at some of the loudest opinions in the world of own finance and see how they stack up to tips from economists.

Explore: This credit card has a rare $300 welcome bonus

Far more: These {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR credit score cards manufactured our very best-of record

Warn: optimum funds back again card we’ve viewed now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR for 15 months

1. Your cost savings fee should really be continual!

It really is a widespread refrain between individual finance professionals: aim to conserve a selected proportion of your profits, no make any difference what age you are, what work you have, or what phase of lifetime you are in. According to Choi’s conclusions from studying economic theory, it really is off base when you look at issues like cash flow vs . paying above one’s life time. When you are youthful, you very likely will not likely make as substantially cash as you will in middle age, and so it could be challenging, or downright extremely hard to regulate your costs and fees even though also conserving that specified share of your cash flow. In the meantime, you could possibly also have some rather massive costs as a more youthful human being. Perhaps you want to get married and have a large wedding ceremony in your 20s or 30s. It’s possible you want to get a dwelling, which arrives with a higher upfront value.

As you get more mature, you will now have done these massive highly-priced things, and you may also possible be building a lot more money at operate. This frees up much more of your earnings to preserve. That explained, if you get in the routine of conserving funds at an early age, it will undoubtedly be much easier to preserve at it as you get older (and make extra dollars). Furthermore, you can choose advantage of the wonder that is compound desire.

2. Do not get an adjustable-rate home finance loan!

Quite a few own finance gurus recommend towards adjustable-price home loans (ARMs). From an psychological standpoint, this will make feeling. Right after all, when you get a fixed-level property finance loan, you will never have to worry about your mortgage loan payment transforming over the lifetime of the mortgage. And if inflation is up and soaring, like it is correct now, this can be a very good matter. But ARMs normally appear with a lower desire level to start out with, and you are going to keep that for a period of time. For example, if you get a 5/1 ARM, you are going to have that minimal beginning desire charge for the very first five a long time right before it starts switching each yr. And what if inflation is reasonable above the system of your loan? You could be getting rid of revenue with a preset-charge home loan, except if you happen to be currently maxing out your spending budget to purchase a property (which isn’t the best notion).

So think about finding an ARM, and if you don’t want to choose the probability of your payment rising following that first interval of set desire, refinance to a fixed-rate loan in advance of it really is above. Right now, finding into a house by working with an ARM should really preserve you money, as the normal amount for a mounted-level property finance loan is 7.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} as of this composing, although the regular amount for a 5/1 ARM is 5.96{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

3. Snowball your financial debt payoff!

For every Choi’s analysis, about fifty percent of the particular finance writers whose guides he read espoused the snowball strategy for having to pay off credit history playing cards and other significant-fascination debt, when half advocated the additional mathematically effective approach, the personal debt avalanche. Economists like the debt avalanche system way too, because you will expend a lot less cash shelling out off your financial debt by focusing on the money owed that have a better curiosity fee first.

However, having to pay off the smallest total initial and performing your way up presents you some early wins, which can compel you to continue to keep heading, and preserve paying out matters off. I a short while ago received out of credit card debt using the snowball technique, and it was in truth incredibly mentally and emotionally enjoyable, inspite of probable costing me a lot more revenue over-all due to me not prioritizing increased-desire financial debt payoff first.

Does any of this matter?

So, figuring out that some of the most cherished views of individual finance experts are off-foundation from an economic standpoint, does any of it genuinely matter? Most likely not. And Choi acknowledges this, based on the availability of assistance from particular finance gurus vs . from tutorial economists and the simple fact that a lot of folks locate it easier to abide by a straightforward directive like, “help save 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your money no issue what,” or “keep away from adjustable-price mortgages.”

In the long run, we have all received to handle our personal cash, and test to do our ideal to lower through the sounds and come across the ways that work for us and that we will stick with. The odds are very good that you are going to come across good results with some technique promoted by a preferred individual finance expert, by way of their web page, guide, or podcast. And that is completely ok.

Notify: greatest money again card we have noticed now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2024

If you might be employing the incorrect credit or debit card, it could be costing you severe income. Our pro enjoys this best choose, which functions a {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until finally 2024, an crazy cash back again charge of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all somehow for no yearly charge.

In actuality, this card is so great that our pro even utilizes it personally. Click on below to study our total evaluate for free and implement in just 2 minutes.

Browse our no cost evaluation

We’re firm believers in the Golden Rule, which is why editorial viewpoints are ours on your own and have not been formerly reviewed, authorised, or endorsed by included advertisers.
The Ascent does not go over all delivers on the industry. Editorial content material from The Ascent is independent from The Motley Idiot editorial information and is established by a distinctive analyst team.The Motley Fool has positions in and suggests Avalanche. The Motley Fool has a disclosure coverage.

The sights and opinions expressed herein are the sights and views of the writer and do not necessarily mirror these of Nasdaq, Inc.

A longstanding pillar of Boston’s economy, finance is fading even faster since COVID

A longstanding pillar of Boston’s economy, finance is fading even faster since COVID

It is a trend that can be connected to the pandemic and the rise of remote function. But it also underscores deeper concerns that Boston-region business leaders have lengthy held, especially considering that the Terrific Recession hit in 2008.

The city has very long been a money services hub. It is the birthplace of the mutual fund and the center of banking in New England. But marketplace consolidation, automation, and the superior cost of dwelling have progressively chipped away at that position. The ranks of people functioning in fiscal expert services in Massachusetts have stagnated, under no circumstances receiving again to the peak of 192,000 work opportunities viewed in early 2002, and usually hovering in the 170,000-vary for considerably of the very last decade. In September, the variety dipped below that threshold for the first time considering the fact that 1996.

The change has been seismic, even right before the pandemic when tech companies took around considerably of the Economical District. Now, with half-empty workplace towers all over the district, there is even been chat of changing some of those people business office properties to lab room, to accommodate the region’s rapidly-developing life science sector. (Just one these kinds of conversion, of a making near South Station that after held the country’s greatest WeWork site, is underway).

Japanese Financial institution main government Bob Rivers reported he thinks the money products and services sector’s heyday in the metropolis has come and long gone.

“I assume the ‘Financial District’ is heading to change into something else,” Rivers claimed, “[although] it might go on to be known as that for legacy factors.”

Rivers runs the most significant regular financial institution based in Boston, but Eastern’s headquarters on Franklin Street only occupies about 45,000 square toes, and he is arranging to minimize again even that modest amount, as quite a few office staffers function remotely. As with a lot of Boston CEOs, Rivers anxieties that the substantial cost of housing drives folks absent he claims he sees new hires “Zooming in” from Florida, a little something he would never have envisioned in advance of the COVID-19 pandemic.

The fact that Japanese is the major Boston-based retail financial institution states anything in and of itself. Gone are the times when Fleet bankrolled IPOs, or BankBoston managed branches in South America. Jap is proudly local, with a footprint principally minimal to Japanese Massachusetts. Now, the only main impartial retail bank based mostly any where in New England is Providence-dependent Citizens Money Group, which has kept its workforce steady at about 18,000 for at minimum a decade and has a main existence in Bigger Boston.

“I’d be stunned if you see internet work rising in the monetary providers [over the next five years],” CEO Bruce Van Saun stated. “I don’t believe any one has a approach that states which is heading to materialize.”

Banking is just just one of a few critical factors of Higher Boston’s money providers sector, together with coverage and financial commitment administration. Even though Point out Road and Fidelity Investments continue being, they’re the only two key impartial fund companies based mostly in the city. Massachusetts is even now dwelling to two massive unbiased insurers: Springfield-based mostly MassMutual, which specializes in everyday living insurance, and house-and-casualty large Liberty Mutual, which have equally expanded their office environment footprints in this article. (Boston also remains a big participant in enterprise capital and personal equity, but most of all those companies, with a number of noteworthy exceptions, are inclined to operate with relatively reduced staffing concentrations.)

The developing sense that Boston has become a department-office town has weighed on the Greater Boston Chamber of Commerce for years. Unlike some other significant neighborhood industries, finance and insurance policy doesn’t have a powerful lobbying group to champion it on Beacon Hill or its personal quasi-public agency to cultivate corporate expansions.

A check out of home windows along Congress Street in downtown economical district Boston on Sept. 24, 2020.David L. Ryan/World Personnel

For this reason, the Chamber persuaded lawmakers eight a long time ago to build an advisory council for the market, a group that consists of reps from Point out Road, MassMutual, and Fidelity, as properly as a handful of lesser corporations, between other individuals. The council fulfills 3 times a year to advise the governor on policies for strengthening the sector, even though it’s not obvious how a lot the lower-profile council has served form public plan.

When he was at the Chamber, Jim Klocke led the thrust for this council, to glow extra of a highlight on economical services. A lot more just lately, prime money executives began trying to make Boston a hub for fiscal-engineering startups, hoping to capitalize on the region’s tech and innovation economic system.

But technology has its downsides. Klocke, who now leads the Massachusetts Nonprofit Community, concerns the prevalence of remote operate is getting its toll on the economical sector’s presence in Massachusetts.

“I would imagine that money services would be more susceptible to that syndrome than some of the other major industries,” Klocke explained.

Current chamber CEO Jim Rooney agrees. It is much easier nowadays, Rooney mentioned, to employ the service of personnel in decreased-charge spots.

“That speaks to this problem of competitiveness,” Rooney explained. “The additional we are complacent about it, the increased probability that these varieties of trends will continue.”

Several, if any, monetary company businesses have grown at a speedier rate in recent several years than Fidelity.

In this Oct. 14, 2019 file photo a Fidelity Investments emblem is hooked up to a developing in Boston. Steven Senne/Related Press

The firm has additional about 900 careers in Boston considering that right before the pandemic, developing its head count right here to additional than 5,500. Nonetheless, that amount is significantly from the 13,000 that Fidelity used in Massachusetts approximately 15 many years in the past. And Fidelity has developed employment noticeably in other locations, together with Smithfield, R.I., and Merrimack, N.H., considering the fact that launching this using the services of surge far more than two yrs back.

Kirsten Kuykendoll, Fidelity’s head of talent acquisition, explained most new hires however need to have to be tied to a physical area, even though the corporation is flexible about the days when employees can function from home. Although most of Fidelity’s job expansion is happening in other places, she pointed to the internet maximize in Boston around the last two many years as proof that “we surely see the place as a actually wonderful location to locate expertise.”

Other firms strike a comparable tone.

Even as the sector little by little sheds careers to considerably less highly-priced locales and the amplified use of automation and synthetic intelligence, quite a few fiscal marketplace leaders say Boston is a position they want to be, and keep on being bullish on the town and the state. The marketplace may possibly not be as prominent as it after was. But it’s even now important to the city’s financial achievement.

“People nonetheless see Boston as a economic services hub, whilst not in the very same way individuals did 10 yrs in the past,” said Lexie Bishop, a local branch supervisor for Swiss investment decision lender UBS. “Health treatment, biotech, and training obviously arrive to thoughts in conditions of the industries that Boston is acknowledged for. Just one of the matters that helps make Boston so particular is that we have a large amount of diversity in conditions of the industries that have a existence below.”


Jon Chesto can be attained at jon.chesto@globe.com. Stick to him on Twitter @jonchesto.