Boeing to cut around 150 finance jobs in US

Boeing to cut around 150 finance jobs in US

Boeing will slash around 150 finance work opportunities across its internet sites in the United States this yr as component of an hard work to simplify its company framework and improve efficiency. 

“For the final several a long time, we have been simplifying our company framework to reduce complexity and concentrate much more resources in engineering, manufacturing and merchandise progress,” a Boeing spokesperson advised FOX Business enterprise. “Quite a few of our corporate capabilities, which include Data Technological innovation and Finance, have implemented changes to streamline their operations, resulting in decrease staffing levels in some company capabilities.” 

Ticker Stability Past Transform Change {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}
BA THE BOEING CO. 143.27 -2.68 -1.84{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}

The spokesperson added that the aerospace big will begin sharing “pick operate” with Tata Consultancy Companies of India and “assess future impacts as the procedure carries on in the coming yrs.” 

UNITED Airways GROUNDS PLANES AS IT COMPLETES INSPECTIONS

According to its latest once-a-year report, Boeing had a total workforce of around 142,000 workforce as of the close of 2021, with 12{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} situated outdoors the U.S. The complete bundled roughly 47,000 union customers. 

Boeing has due to the fact expanded its workforce by about 10,000 workers this 12 months to “generate balance in output and commit in engineering and innovation.”

Boeing Chicago HQ

The Boeing symbol hangs on the company environment headquarters setting up of Boeing November 28, 2006 in Chicago, Illinois. (Picture by Scott Olson/Getty Pictures) ((Photograph by Scott Olson/Getty Images) / Getty Images)

The reductions are unrelated to Boeing’s plans to go its corporate headquarters from Chicago to Arlington, Virginia, in accordance to the spokesperson.

Click on Listed here TO Read More ON FOX Enterprise

The prepared layoffs appear as Boeing delivered its very first 787 Dreamliner to American Airways in August next approval from the Federal Aviation Administration. Boeing halted deliveries in May perhaps 2021 immediately after the FAA elevated fears about its proposed inspection technique. In September 2020, the FAA mentioned it was investigating production flaws in some 787 jetliners. 

The agency’s elevated scrutiny on the certification of Boeing’s planes comes just after two deadly crashes in 2018 and 2019 grounded its 737 Max jet. The 737 Max has considering the fact that returned to the skies right after remaining cleared to fly in November 2020.

In July, Boeing described that its quarterly profit fell to $160 million, or 32 cents a share. Gross sales during its 2nd quarter fell 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $16.7 billion. The enterprise created good working cash circulation during the quarter and mentioned it remains on track for positive income movement for the whole calendar year.

Shares of Boeing are down around 29{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} calendar year to date.

Reuters contributed to this report

Top 5 Personal Finance Reddit Communities Checking Out

Top 5 Personal Finance Reddit Communities Checking Out

Battling with economic management? Reddit is in this article to the rescue!

Nearly anything you’re intrigued in, no make a difference how specialized niche, most likely previously has a community on Reddit. Reddit is a dialogue website wherever people make up communities, or “subreddits”, for just about almost everything, from health tips, funny movies and terrifying fictional stories to individuals dedicated to basically venting about bothersome matters.

Just one these types of group of subreddits is particular finance. I mean, let’s encounter it: most of us don’t have the very best financial know-how. We master by ourselves—be it by way of textbooks, YouTube videos, content or guides on the online. Nevertheless, all of this falls quick of serving to us with the actual monetary predicament we might be working with. Which is exactly where Reddit comes to the rescue. If you are hunting for some 1-on-just one assistance from people today who could have dealt with the very same cases as you, below is a record of subreddits you should really verify out: 

r/PersonalFinance

r/PersonalFinance is a community produced up of 16.4 million users that describes by itself as a community where by you can find out about budgeting, saving, investing and retirement planning. If you seem at the subreddit’s Wiki web page, you are going to see advice categorized according to distinct age teams as well as distinct sorts of credit score and investments. 

The subreddit also has 30-working day problems that are intended to encourage community members to get their finances in order. As of writing this posting, the obstacle for the thirty day period is to observe all your investing behavior. The neighborhood has offered actionable techniques to observe costs by making a price range finish with groups, like personal savings and retirement cash.

r/FinancialPlanning

r/FinancialPlanning is your basic tutorial to a a lot more frugal way of life. The group has 400,000 associates who go over inquiries about windfall gains, negotiating income and exactly where to commit subsequent. The neighborhood also tells you the varieties of files you need to get when you purchase shares. 

Contrary to the preceding entry on this checklist, investing or inventory analysis is not within just the scope of this subreddit. The guidelines of the neighborhood discourage customers from composing posts relevant to speculative investments, this sort of as cryptocurrency. 

r/Budget 

r/Price range should really be your go-to spot for enable with developing your personalized price range. The group has 24,000 users who talk to every single other about the lowest priced areas to purchase groceries, how to track credit history card payments and the budgeting applications they should really use. 

The Redditors in this local community also share their spending budget sheets with every single other. Associates can seem at the sheets and help them see wherever they could be reducing costs and suggest them on how to are living on a spending budget. Some very good Samaritans on the subreddit also create personalized budgets for other folks to use. 

r/povertyfinance

r/povertyfinance is a group produced up of 1.4 million individuals featuring strategies and suggestions for those struggling fiscally. The community’s Wiki web page incorporates in-depth info about foods financial institutions, low-cost health care and no cost financial literacy programs. Redditors can use this subreddit to vent about their troubles, get encouragement from other local community associates and also share guidance on how to be thrifty about their bills. Some local community users even attain out to share position options with other individuals who may possibly be fascinated. 

If you are familiar with the basics of fiscal management and need to have guidance associated to investing, this may be the right place for you. Manufactured up of 2.1 million customers, r/investing is replete with guidance on how to commit in capital markets. The local community was established in 2008, shut to when the stock market place crashed. 

This subreddit follows all investment-linked news intently, offering in-depth posts asking inquiries about why the industry appears to be the way it does. Users share suggestions on exactly where to spend and also demonstrate financial commitment-related conditions to those who may well be unfamiliar with them. Customers can also accessibility a reading through listing about investing, economic stories and comprehending stock marketplaces. 

According to the 2020 S&P Financial Study, only a single in 3 grownups can appropriately reply three out of 4 thoughts about numeracy (potential to apply straightforward numerical principles), inflation, threat diversification and interest compounding. This ought to convey to us that money awareness is minimal to only a couple folks in the earth. The most effective way to unfold financial literacy is for those people who have the monetary know-how to share data with others, and that is exactly why these communities are so vital. If you are commencing your journey toward turning into economically independent, make certain you check out these subreddits out!

Also go through:

Header impression courtesy of Unsplash

Is Finance a Good Career Path for You? | Careers

Is Finance a Good Career Path for You? | Careers

For a work with remaining electric power, consider a finance profession. Although technological innovation is helping persons manage their revenue in new methods – such as by on the web banking companies and digital wallets – no app can replace the know-how of a prosperity advisor, accountant or monetary analyst.

“Banking could possibly glance really different in the long run, but finance is not heading away at any time before long,” claims Arjun Kapur, taking care of director of Forecast Labs, a enterprise team within Comcast NBCUniversal.

That can make finance an desirable sector for all those who want an in-need profession that has good money prospective. And neglect the stereotype of it getting a man’s environment. Quite a few women of all ages discover achievement in the area as well.

“It’s not all analytics,” says Judi Leahy, senior wealth advisor with Citi World wide Wealth. Finance industry experts need to have to be able to listen and share details in an available way. “I believe ladies have a a great deal bigger edge (when it arrives to) communication with clientele.”

If you are contemplating a job in finance, here’s what you require to know about the pros and downsides, ordinary salaries for finance careers and no matter if you have to have an MBA or put up-grad diploma to continue to be competitive.

Execs and Disadvantages of Finance Professions

Good payment is 1 explanation finance professions can be so interesting. The median yearly wage for all business enterprise and economical occupations was $76,570 in May perhaps 2021, in accordance to the Bureau of Labor Figures. Which is noticeably increased than the median annual wage of $45,760 for all occupations. And lots of finance careers can get paid considerably additional.

“You have the capacity to make a respectable earnings relatively early on,” states Logan Allec, a CPA and proprietor of tax aid enterprise Option Tax Relief. For individuals who perform in general public accounting firms, he claims it’s not unreasonable to be making a six-figure wage in just 4 or 5 several years.

Nevertheless, that profits will come at a selling price: general public accounting employment can be stress filled. Non-public accounting roles – this kind of as serving as an in-dwelling accountant for a enterprise – can be much less nerve-racking but could not appear with the similar upward mobility and salary.

For Leahy, one particular of the professionals of performing in finance is the chance to perform in a dynamic field, in which no two days are the similar. She adds that her work has also provided the opportunity to make connections with many others, indicating she has manufactured numerous superior mates more than the decades thanks to her position.

The draw back may well be that this is not a occupation route that lets you shut down your personal computer and go away your function guiding at the place of work – at the very least not if you’re employed as a money advisor, according to Leahy. “This is not 9-to-5. It is 24/7,” she says.

Expertise Necessary to Operate in Finance

Finance isn’t for all people, and you’ll want the proper combination of tricky and delicate abilities to be prosperous.

“You’ve bought to be a quantities man or woman for anything in accounting and finance,” Kapur claims.

Based on their purpose, finance and accounting pros may well use math and statistics on a day by day foundation. Their work may possibly contain generating spreadsheets, producing budgets, forecasting profits and reconciling accounts.

A lot of careers also consist of functioning instantly with consumers, and getting ready to communicate correctly is crucial for these roles.

“My major asset with consumers is listening,” Leahy claims. “You have to listen.”

Attention to depth, difficulty fixing and critical imagining are also vital to results in quite a few of the best work opportunities in finance.

Is Finance a Tough Profession?

Irrespective of whether finance is a tricky profession relies upon on your particular skills and tastes. Though there is place for innovation in some monetary work, other individuals do not go away much room for creativity. After all, as Kapur claims, accounting is accounting.

Some individuals take pleasure in the difficult and dynamic function of several finance occupations while other folks may find it to be tense.

“You have to be ready to multitask. You have to have a willingness to discover,” Leahy says. Stagnation isn’t really an alternative, specifically for monetary advisors. The stakes are much too significant, according to Leahy: “As a prosperity advisor, you’re taking care of not only their income. You are managing their lives.”

Before committing to a job in finance, it can be clever to discuss work responsibilities with experts in the discipline. They can provide a extra total image of what an profession involves and how you may shell out your times when working in that placement.

How to Get a Finance Task

Most finance work involve at the very least a bachelor’s degree, typically in a business enterprise or finance-similar field. Even so, not every single prosperous experienced took that route.

“I arrived in as a result of the backdoor,” Leahy states. “My degree was in geology.” In 1984, when careers in that field dried up, she observed perform as a income assistant with a financial business and turned absolutely certified in 1985.

Right now, there may possibly be more competitiveness for employment. “It’s gotten a lot more difficult if you are not the product of the crop,” Leahy claims. Nevertheless, she adds that it continues to be attainable for individuals with a degree in a distinctive area to crack into finance. “From an advisor point of view, it helps to get the job done with an advisor to coach,” she implies.

Entry-level positions might not automatically be in which you imagine your vocation in the extensive operate, but they can be stepping stones to far better possibilities in the future. “I started my vocation in the start-up earth as an analyst,” Kapur says. “You have to be at ease commencing from the base and operating your way up.”

Getting an innovative degree these types of as a Master of Small business Administration may be essential for specified positions, especially people at the managerial or executive stage. However, it may perhaps be greater to obtain some function working experience to ascertain how properly you like the industry just before committing the time and electrical power required to gain an MBA.

For accountants, Allec suggests possessing a Licensed Community Accountant license can open doorways to new careers, but getting to be a CPA is not required to operate in the area.

What Is the Optimum Paying out Finance Position?

Company and finance work, as a full, pay far more than other occupations, and here’s a glimpse at median salaries from some of the finance occupations that built the 100 Finest Work rankings from U.S. Information:

“Within finance and accounting, the demand for capable pros is so superior,” Allec says.
That might enable drive up salaries for some specialists. Private money advisors, economic examiners and money analysts are amongst the occupations anticipated to have quicker than normal progress in between 2021 to 2031, according to the BLS.

Is a Vocation in Finance Worthy of It?

If you are searching for a job with significant-earnings probable and a great deal of career prospects, finance can be a rewarding subject. Several individuals who excel in this sector locate that it fits perfectly with their pursuits and capabilities.

“I always loved quantities,” Allec states. “I cherished placing factors in spreadsheets as a kid so it seemed like a pure course to go.”

Finance possibly isn’t well worth it if quantities set you to rest, but if you delight in making budgets, calculating financial commitment returns or preparing for your retirement income, a profession in finance may possibly be a wonderful way to gain some income doing what you enjoy.

Greg Bolan Discusses Reasons Military Veterans Should Focus Civilian Careers in Finance

Greg Bolan Discusses Reasons Military Veterans Should Focus Civilian Careers in Finance

Greg Bolan is a army veteran who served in the United States Military. Now operating in corporate finance, Greg Bolan understands how serving in the army can put together service users for the following chapter of lifetime, with management skills, self-self-discipline, and strategic imagining skills. In the subsequent short article, Mr. Bolan discusses under the numerous causes why armed service veterans really should consider a vocation in finance in their publish military life.

Just after retiring from the navy, a lot of veterans question irrespective of whether their expertise can be tailored and used to the civilian earth. But, what they from time to time ignore is that they have a wealth of information in logistics and analysis. Even though it may not be for everybody, Greg Bolan says that a vocation in finance might be a excellent choice for veterans who want to use their analytic and strategic pondering expertise in a new marketplace.

The transition out of the armed forces can from time to time be complicated and perplexing but by concentrating on a career in finance, veterans can very easily assimilate into the civilian globe. Their track record in the military services generally offers a powerful basis of expertise that they can then apply to a successful and profitable new life path.

Previous Armed forces Users are Trained in Self-Self-control and Leadership Competencies

When new recruits 1st enlist in the military, they commit the initially couple months in basic instruction studying necessary expertise desired to do well within the army. These techniques involve self-discipline, bodily conditioning, management abilities, and specialized navy instruction. Right after finishing primary coaching, they’re predicted to sustain these techniques on their possess, strengthening a society of self-handle explains Greg Bolan.

Lots of veterans worry that these abilities may perhaps make them much too rigid for the civilian entire world nevertheless, in the finance sector, self-discipline and leadership expertise are remarkably valued states Greg Bolan. Right after all, finance can speedily turn out to be a higher-tension atmosphere, requiring a cool head and mindful steering to bring a workforce towards accomplishment.

Furthermore, the military services also instills a feeling of teamwork in its members. In the finance sector, this teamwork is necessary for results. Mainly because the market is so quick-paced and ever-changing, these who can operate with each other quickly and competently are really sought-just after.

Greg Bolan
Both Finance and the Military services Call for Strategic and Analytic Thinkers

The army is all about organizing and strategy. Greg Bolan describes that armed forces users are generally tasked with creating brief decisions that could imply life or demise for on their own and their fellow soldiers. This variety of stress often involves break up-2nd strategic imagining and an potential to assess a scenario from all angles.

Despite the fact that the stakes are undeniably lessen, the finance field also necessitates its employees to be strategic thinkers. From investing to budgeting, individuals who perform in finance will have to be in a position to make audio conclusions based on details evaluation and an knowledge of the market. For veterans, this kind of pondering will likely appear in a natural way claims Greg Bolan.

Finance is a Dynamic and Worthwhile Career Selection

The finance sector is always modifying and evolving, offering those people who get the job done inside it a regular obstacle. For veterans who are utilized to the structure of the army, this dynamic natural environment may well be desirable. Furthermore, Greg Bolan claims that these who succeed in finance often come across them selves rewarded with high salaries and task security.

In contrast to other industries, finance is fairly steady, fulfilling veterans with a feeling of protection as they transition into the civilian world. This feeling of protection can make the transition a lot easier and deliver a sense of group that they might pass up soon after leaving the provider.

Attainable Problems Veterans May Face While Doing the job in the Finance Industry

Whilst working in finance might be a excellent fit for many veterans, they may face a couple of worries according to Greg Bolan. For instance, the field can be very aggressive, earning it difficult to get a foot in the doorway. Whilst most veterans experienced a designed-in local community of like-minded soldiers close to them 24/7, soon after leaving the provider, they’ll have to quickly construct a community to come across their spot within the industry.

Also, the finance sector is recognised for its extensive hours and significant anxiety amounts. Veterans who are used to a much more regimented life style may possibly discover the lengthy and variable several hours tricky to alter to. They’ll have to wake on their own up, get to get the job done, communicate, socialize, and adapt to ever-shifting requirements points out Greg Bolan.

Ultimately, veterans ought to master to assimilate to non-hierarchical job advancement. In the navy, it is quick to go up the ranks, but in finance, promotions are usually dependent on task general performance, not many years of service. This could be a tricky adjustment for veterans who are utilised to a a lot more rigid framework.

Ultimate Views

For a lot of veterans, a vocation in finance might be a good selection. Their military education normally supplies them with critical capabilities that are really valued in the industry, these kinds of as self-control, strategic considering, and leadership. Additionally, the finance business is constantly modifying, furnishing veterans with a continual challenge. Though there may be a handful of troubles, these as the extensive several hours and higher anxiety levels, the benefits frequently outweigh the problems.

Citibank Partners Yahoo to Enhance Public Literacy on Personal Finance

Citibank Partners Yahoo to Enhance Public Literacy on Personal Finance
yahoo

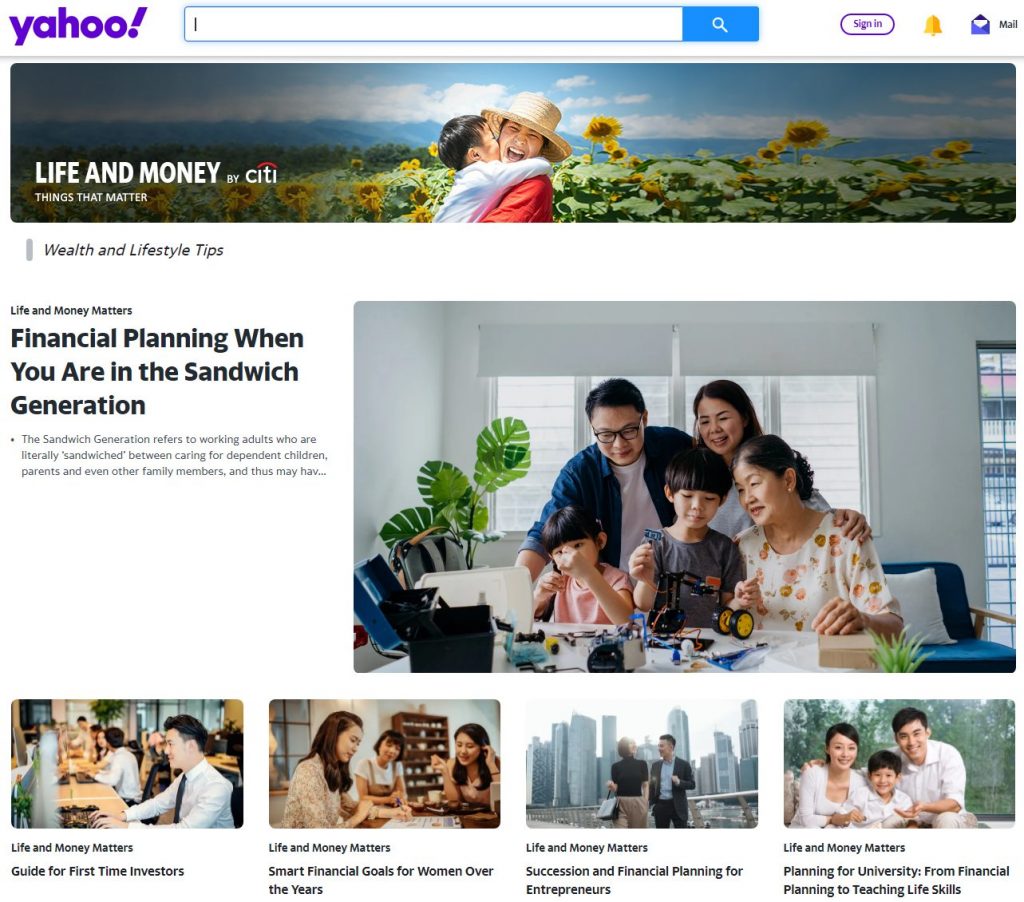
Yahoo and Citibank have teamed up to start Everyday living and Income, a devoted private finance hub geared in the direction of various audiences, providing refreshing perspectives on money, and equipping them for their economical journey across different everyday living phases. Hosted on Yahoo Finance in Singapore – the #1 source for enterprise and finance news in the state – Life and Income will see Citibank share specialist insights and suggestions on private finance with readers.

While financial literacy in Singapore is the greatest in Southeast Asia, swift modifications in the fiscal landscape, technological advances, as perfectly as switching life-style behaviors and lifetime expectancy keep on to gasoline developing fascination in particular finance as they develop their aspirations. While there is no lack of information and facts accessible online, Singaporeans are significantly discerning with their finances and on the lookout for sources and information they can have confidence in.    

Seeking to empower audience as they regulate their funds and assume about their potential, Daily life and Dollars will function a specially curated variety of original information contributed by and jointly with Citibank, as very well as pertinent aggregated material from Yahoo Finance. With insightful explainers accessible in several multimedia formats this kind of as content, films, and podcasts, the hub will include a extensive array of topics all over own finance and way of life. These involve conserving, investing, advancing careers, attaining operate-daily life harmony, sustainable residing, parenting, and other individual finance and life style pursuits. 

With a aim on enabling readers to live richly – economically, bodily, and emotionally – the written content will deal with misconceptions, encourage new lifestyle habits, and deliver actionable tips for viewers of different lifetime stages. Between them are first jobbers searching for economical independence, starter family members purchasing their aspiration residences, mid-vocation professionals progressing by means of milestones, and seasoned achievers organizing their suitable retirement.  

“As a foremost source for finance news, Yahoo is concentrated on giving information and info that will assistance give our visitors the self confidence to make intelligent economic conclusions. We are thrilled to associate with Citibank and establish empowering content on private finance, and enable drive meaningful connections with audiences trying to get rich insights that will help them reach monetary empowerment and lead their wanted lifestyles,” explained Carol Tay, senior director sales Southeast Asia, Yahoo.

“Our partnership will give viewers the chance to obtain Citibank’s hottest particular finance insights and tips, as very well as better provide our purchasers with an additional supply of trustworthy finance-related content material. We hope to offer a fresh and trustworthy economic point of view to those navigating life’s milestones, leveraging Yahoo’s strong editorial experience and sizeable organic and natural database,” mentioned Mylene Ong, head of digital product sales and marketing and advertising, Citibank Singapore.

An economist studied popular finance tips. Some might be leading you astray : Planet Money : NPR

An economist studied popular finance tips. Some might be leading you astray : Planet Money : NPR

Individual finance smackdown

Pixabay


hide caption

toggle caption

Pixabay


Personal finance smackdown

Pixabay

Controlling your cash is clearly an significant part of remaining a liable adult. But how should really you do that? It turns out that there is a significant gulf amongst the information given by the authors of well-liked finance textbooks and academic economists.

In a new research titled “Well-known Private Fiscal Tips versus the Professors,” the Yale financial economist James Choi rummages by way of 50 of the most well-known textbooks on particular finance to see how their tips sq. with regular economic thinking. It is like a cage match: Finance thinkfluencers vs economists dueling in excess of what you ought to do with your income.

And, sure, Choi is an economist, but he may well be a more neutral referee of this smackdown than you’d think. That is since he’s a behavioral economist who will not swallow the canon of aged-university economics hook, line, and sinker. Classic financial designs portray individuals as hyper-rational, disciplined creatures, who constantly make optimum fiscal decisions for them selves. Behavioral economics, which has fairly much taken over the discipline, emphasizes that men and women are quirky, typically irrational, and susceptible to faults.

In a way, Choi says, behavioral economists like him try out to assistance people defeat their shortcomings and reach their money targets as if they have been the savvy creatures of outdated-school concept. And so, he says, classic economic idea could nonetheless offer a excellent over-all guidebook for how to improve your economical properly-currently being. But, Choi states, the information of well-known finance thinkfluencers, who are likely to concentrate on helping us get over our flaws and foibles, might basically be more successful in some scenarios.

So, who’s right in this monetary royal rumble? The authors of self-aid finance textbooks or the stalwarts of common economic principle? When Choi won’t generally offer definitive answers, this debate may possibly spark some suggestions on how you can much more correctly deal with your finances.

How Need to You Conserve Cash?

When it comes to saving money, quite a few economists supply relatively counterintuitive — and, dare I say, possibly irresponsible — information: if you happen to be younger and on a strong job track, you may possibly contemplate investing far more and saving less suitable now.

Which is mainly because you’re most likely going to receive a bigger paycheck when you are older, and to definitely squeeze the enjoyment out of lifestyle, it may well make feeling to live a little bit past your usually means at the moment and borrow from your long term, richer self. Economists connect with this “usage smoothing,” and it is really a attribute of standard financial styles of how rational men and women preserve and commit more than their life span. The strategy, Choi claims, is “you don’t want to be starving in just one period and overindulged in the upcoming. You want to easy that about time.” The sort of perfect state of affairs: you begin off adulthood saving very little or almost nothing or even using on financial debt, then you conserve a whole lot through your primary-age earning decades, and then you devote all those discounts when you retire.

“I convey to my MBA learners, ‘You of all folks should really feel the minimum sum of guilt of having credit rating card debt, since your earnings is rather low suitable now but it will be, predictably, quite superior in the really around long run,'” Choi suggests. As soon as they commence generating funds, he states, they should probably pay down that credit card debt rapidly due to the fact credit history card companies charge large fascination charges.

Looking through by well-known finance guides, on the other hand, Choi finds that the large the vast majority of well-liked authors provide guidance that contradicts this technique: in the course of your existence, the thinkfluencers say, your intention need to be to are living in just your means and help save a constant share of your income. It would not matter if you happen to be 20 or 30 or 50 they implore you to stash cash away immediately and spend it for your future.

In arguing this, the thinkfluencers frequently cite the energy of compound interest. The more time you preserve money, the more curiosity it accrues. As a end result, wealth snowballs in excess of time, so conserving a huge share earlier could make a ton of feeling.

Of training course, economists also figure out the energy of compound fascination. Exactly where thinkfluencers and aged-school economics actually depart from just about every other, Choi states, is “the usefulness of setting up preserving consistently as a willpower,” Choi says. This commitment, he states, “is nearly normally missing from economic types of ideal preserving — [and is] a likely vital oversight.” In other terms, some of us could possibly have to have to adopt challenging-and-quickly preserving rules at a younger age to create the self-control desired to guide more affluent life, even if which is much less than optimum from a regular financial viewpoint.

So who wins on this point? “I am in fact agnostic about it,” Choi states. “On the one particular hand, I do have a ton of sympathy for the perspective that you might be unnecessarily depriving you in your twenties and even thirties when, really predictably, your revenue will likely be substantially increased in later decades. That being reported, I do assume that there is one thing to this notion of currently being disciplined and understanding to reside in your indicates at a younger age.”

How Should You Consider About Your Price range?

In aged-university economics, funds is dollars. It really is fungible. There is no motive to put labels on it. Absent some economically advantageous purpose to do so (like the potential to get subsidies or a reduced tax fee), it will not make perception to established apart price savings for precise purposes, like a new car or truck or a future holiday vacation or a down payment on a property. A greenback is a dollar.

Of study course, several people today you should not believe this way. They often do what behavioral economists get in touch with “mental accounting,” earmarking particular revenue for this and that. “In much more severe versions of mental accounting, you can’t use the cash that you’re conserving for your Hawaii holiday for the down payment on your potential household,” Choi suggests.

Choi finds that 17 of the 50 textbooks he study by advocate for some type of psychological accounting training. And, he suggests, this information could possibly really make sense. It helps make financial calculations easier for people and may well encourage them to execute their targets.

Need to You Be “Dwelling Abundant, Dollars Bad”?

Quite a few Us residents are living in huge properties and are stretched skinny paying for them. When their home is a beneficial asset, and they are technically rather abundant, they are just squeaking by, living paycheck to paycheck. People today commonly refer to this as “property loaded, hard cash weak.”

Choi claims both equally popular fiscal advisers and most economists are very crystal clear: don’t do this! Do not acquire a property you are not able to truly find the money for. That can be super nerve-racking and perhaps ruinous.

How Considerably Of Your Revenue Should Be In Shares?

Choi says that common advisors and economists also typically concur that when you are younger, you need to commit most of your money in shares and only a little little bit in bonds. In addition, Choi says, each camps concur that as you get more mature, you should really get far more conservative, rebalancing your portfolio away from shares and extra toward bonds simply because shares are riskier than bonds. But, Choi states, even though both of those of these teams recommend people today to do the same factor with their investments around time, their reasoning for accomplishing so is quite diverse.

Usually speaking, well-known financial advisers say that, while stocks are dangerous in the limited run, you should really devote primarily in them when you are youthful for the reason that they gain larger returns than bonds around the long operate. “The well-liked belief is that the inventory industry is form of certain to go up if you just maintain on to it for long adequate,” Choi says. “Now, this is just not correct. And you can see this in Italy and Japan. In Japan, the inventory market place still has not recovered to the level it was again in 1989. So it truly is not accurate that stocks will usually gain about the extended run. Negative points can take place.”

But while well-liked authors may well discount this danger in excess of the long expression, their advice recognizes that keeping shares is risky in the brief phrase. Which is why they argue that, as you get closer to retirement, you should get out of shares and go into bonds, which are normally fewer risky. A preferred rule of thumb: 100 minus your age is the share of your portfolio that ought to be in shares. The remainder should be in bonds. So if you are 30, you need to be 70 per cent in stocks and 30 p.c in bonds.

Though economists concur that you must get a lot more conservative above time with your financial portfolio, Choi claims, their reasoning is extra nuanced.

“For nearly all doing the job people, the key financial asset they have is their future wage income,” Choi claims. In other words and phrases, think of your work competencies (your “human funds”) as element of your economical portfolio. It’s like the largest sort of prosperity you personal, and it can be usually safer than stocks or even bonds. When you happen to be young, this safer sort of wealth is a big portion of your portfolio, so you can balance it with risky stocks. Guaranteed the inventory marketplace could possibly crash, but you still have the security of getting capable to receive income at your career for a lot of extra a long time. As you get closer to retirement, this safer asset, your labor, represents a a great deal more compact portion of your portfolio — and that tends to make it a lot extra frightening to be all-in on dangerous stocks. “Which is why you should come to be much more conservative in your economical portfolio allocation around time,” Choi claims.

Ought to You Treatment No matter whether Stocks Fork out Dividends?

Choi claims there are some well known money publications that suggest people today to acquire shares that pay out dividends. For the uninitiated, dividends are checks that businesses mail to their shareholders generally each quarter. “There seems to be this fascination with making ‘income’ from your investments,” Choi states.

Economists, frequently talking, believe this is dumb. “If I want to devote some money from my prosperity, I do not need to have to wait for the firm to mail me a check out,” Choi says. “I can just provide some shares and use the proceeds from that sale to finance my expenditure wants. And so there ought to be no rationale why I desire shares that pay out dividends versus shares that will not fork out dividends. And in truth, dividends are tax-deprived. So, a inventory that pays dividends is heading to put a larger tax load on you, all else equivalent, than a inventory that doesn’t fork out dividends.”

Choi is with Workforce Economist on this 1.

Really should You Invest In International Inventory Markets?

Economic concept stresses the significance of diversifying your investments. This, Choi states, is true of diversifying the international locations you commit in, too. Theoretically, the more international locations you make investments in, the a lot less risky your financial commitment portfolio will be. Some international locations will do very well. Other folks will do improperly. “So economic theory would say you want a diversified portfolio that retains a bit of every single country’s stock sector in the earth,” Choi says.

But folks will not do this. They show what economists connect with “house bias.” The French are extra most likely to make investments in French firms. The Japanese are far more likely to invest in Japanese providers, and so on. This has extensive been a puzzle to economists. The answer may possibly lie in the pretty much common help for ‘investing at home’ among the thinkfluencers. “The placing thing about the preferred authors is that they all recommend home-biased portfolios,” Choi states. Choi just isn’t definitely positive whether or not this will make a lot feeling. “It just would seem to be a little bit of jingoism, the place folks just like the stocks that they are acquainted with.”

Should really You Make investments In Actively Managed Cash or Passive Index Resources?

Actively managed resources are those in which you shell out an expert to decide and choose shares for you. These fund managers demand big service fees with the promise of increased returns. Index funds have nobody actively finding and deciding upon investments for you. These resources simply just passively keep a little piece of every single big corporation in the inventory market, thereby earning the general typical current market return.

Economists and thinkfluencers concur on this a person, too. “Most people generally claims you should really go with index money,” Choi states. “The information are quite compelling. On average, passive funds outperform actively managed money.”

Choi’s Significant Takeaway

So who wins? The thinkfluencers or the economists? Economists, Choi implies, could know a ton about how people ought to act. But, as an empirically minded behavioral economist, Choi recognizes that men and women normally never act this way. And that is exactly where he has a degree of sympathy for the common authors. “Provided that we have all these quirks and frailties, we could have to vacation resort to approaches that are fewer than fantastic.”

“I assume of it in terms of diet regime,” Choi says. “The best diet regime is the one that you can adhere to. Financial concept might be saying you will need to be taking in skinless hen breasts and steamed vegetables for the relaxation of your daily life and nothing at all else. Which is likely to be the finest for your well being. And, truly, really couple folks will truly do that.”

He certainly has that right.