Milwaukee students learn importance of personal finance

Milwaukee students learn importance of personal finance

MILWAUKEE — During the week, Heaven Renee Williamson can be located at a computer system at Milwaukee Hamilton Superior School, discovering the relevance of personal finance.


What You Have to have To Know

  • Milwaukee Community Faculties is piloting a Personalized Finance curriculum 
  • More than 470 pupils across a few colleges are enrolled in the program
  • MPS received a grant from Next Gen Personal Finance to build their curriculum
  • It will come to be a graduation requirement beginning in 2028

In just one of her lessons, Williamson is studying how to funds the cash she’ll make in her job. 

“I’m likely to college for psychology to turn out to be a therapist, and company and finance to turn into a actual estate investor,” Williamson explained. 

To start out, she has to obtain out the average income she could make. 

“As a therapist, I will make $31 an hour, so about $64,000 a yr,” Williamson mentioned.

From there, she has an excel spreadsheet where by she enters her web pay back, gross pay back, will take out dollars for taxes and expenditures, and finds out how considerably she’ll have leftover every thirty day period. 

She stated it’s a thing she and her classmates do not definitely consider about much too generally. 

“At the moment, no, but we’ve got to think forward,” Williamson mentioned. 

That’s why the Milwaukee General public Faculty Board of Administrators voted to make own finance programs a requirement to graduate starting up in 2028. 

Ideal now, it’s an elective training course to check out the potential program.

“It’s essential to give universities an chance to actually perform with learners to establish the study course, and let students to give us responses on how we can improve the study course and make it far more significant for them,” stated Marti Diaz, the Monetary Literacy Trainer Mentor with Milwaukee General public Colleges.

Diaz mentioned there are additional than 470 college students across 3 colleges at Greentree Prep, Riverside, and Hamilton Large Colleges enrolled in the plan. 

“In the spring, we’d like to include on six a lot more educational institutions,” Diaz reported. 

To enable, MPS was awarded a grant from Future Gen Private Finance, a company that supplies particular finance curriculums for educational facilities all across the nation. 

This year, MPS was the biggest urban faculty district to get a grant to acquire the plan, in accordance to MPS. 

“For our city and for our district, that we’re capable to have this chance for our learners to find out about private finance is definitely outstanding,” Diaz mentioned. 

Pupils stated even nevertheless it is not a necessity but, more learners should really get these courses. 

“It’s essential because it basically teaches you about the genuine world, and not just e book things,” Williamson stated.

New Program Aims To Expand Teen Financial Literacy Across The U.S. With Backing From Charles Schwab Foundation

New Program Aims To Expand Teen Financial Literacy Across The U.S. With Backing From Charles Schwab Foundation

Classes like geometry, biology and—increasingly—personal finance fill the average teenager’s superior school timetable. Nonetheless, obtain to high-quality economic literacy courses remains uneven in the U.S., and much less than fifty percent of states need them for graduation.

The Charles Schwab Foundation hopes to bridge the gap with an ambitious software declared currently that designs to make private finance programs accessible to every middle and high faculty in the U.S. by 2025—for no cost. The charitable arm of the Texas-based mostly brokerage behemoth (it has $7.6 trillion in property underneath management) will operate the plan, dubbed Moneywise The usa, aiming to teach up to a quarter of Schwab’s 32,500 U.S. staff members as volunteer instructors. 

Built in live performance with a selection of businesses that set educating benchmarks and advocate for accessibility to personalized finance programs, which include the Council for Financial Schooling (CEE) and Soar$tart Coalition, Moneywise America’s 22 hrs of curriculum runs the gamut from budgeting and preserving to accountable long-phrase investing, claims Carrie Schwab-Pomerantz, president of the Charles Schwab Foundation and daughter of the firm’s eponymous billionaire founder. 

“We’re in a time in which you will find not financial parity, and there are a good deal of social issues that we are confronting these days as a nation,” observes Schwab-Pomerantz. “We want to be element of that remedy, and we feel economic literacy is a great equalizer.”

This is not the foundation’s to start with foray into monetary literacy: it partnered with the Boys & Ladies Golf equipment in 2003 to create a individual finance study course that has given that reached additional than a single million teenagers. So far this 12 months, Moneywise America has accounted for about 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the Charles Schwab Foundation’s total giving towards economical literacy, and as the plan grows, the business expects it to come to be its largest economic literacy expense. As early as 2022, faculties will be capable to start requesting resources (which include Schwab volunteers to teach the curriculum) through a devoted internet site. The method will also be obtainable to nonprofits—for example, Moneywise The united states is partnering with the Lady Scouts to increase economical literacy applications beginning in late 2022 for members in grades K-12. 

When teenagers discover about individual finance, it can have a beneficial impression on their foreseeable future economic wellbeing, self-confidence and ability to deal with college student loans and income emergencies, says Annamaria Lusardi, a professor of economics and accountancy at the George Washington University College of Business enterprise in Washington D.C. and founder of the school’s money literacy centre.

“The results are extremely apparent, that we know money schooling does work for a selection of behaviors in young folks,” Lusardi emphasizes.  

Now, only 21 states need that high faculty learners get a personal finance study course to graduate, in accordance to CEE’s hottest nationwide study, printed in 2020. Lusardi supports a lot more expansive own finance instruction specifications, adding that exposure to this style of discovering has ordinarily been reserved for youthful people today with rich, nicely-educated mom and dad who instilled monetary concepts early on.

“I believe the school has a critically important position to participate in, due to the fact they offer entry to every person, they supply entry early on and they supply a demanding background,” claims Lusardi, who has researched economic literacy for almost two a long time. 

The general public looks to concur. Far more than 80{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of People feel superior schoolers need to acquire private finance classes, for every a survey released last month by the Nationwide Financial Educators Council. Still most states are unsuccessful to train the subject effectively. A modern investigation by the American Public Schooling Basis asserted that two-thirds of states (35 states such as Puerto Rico and Washington D.C.) acquired grades of “C” or less for money literacy instruction, with just 17 states earning grades of “A” or “B.” Moneywise America’s curriculum and volunteer instructors will be obtainable cost-free of charge to universities and nonprofits, which could assist fill that persistent hole involving intent and execution. 

Teenager investing has viewed a increase yr: child-targeted budgeting and investing apps like Greenlight have taken off, even though Fidelity introduced youth brokerage accounts in May that permit 13-17 calendar year olds to purchase and market shares, ETFs and mutual funds with no parental acceptance just after the account is proven. Although pupils have extensive expressed fascination in investing lessons, thoughts about Robinhood and other fresh investing trends have begun popping up in latest months, in accordance to Shahar Ziv, founder of Acing Your Funds, a economic wellness company that partnered with the Harvard University Staff Credit history Union in 2011 to present an annual private finance administration course. 

“The subject matter that college students are most intrigued in is investing, as gauged by attendance and need for workshops on that subject,” claims Ziv, a Forbes contributor.  “But in order to have funds to spend and to do so neatly, they will need to 1st find out the fundamental principles, these kinds of as budgeting, preserving and economical planning. 

Although the Charles Schwab Basis operates independently from the brokerage from which it derives its identify (and funding), Moneywise The us could possibly have the extra benefit of attracting the subsequent generation of wise, effectively-well prepared buyers.

“The best achievement is if they come to be economically qualified and self-assured, mainly because that will direct to fiscal safety,” claims Schwab-Pomerantz. “Whether they arrive to Schwab or Fidelity, which is their preference. We are just striving to give them the foundational data, so that they can make intelligent alternatives for their long run.”

The Recorder – Area schools discuss benefits of financial literacy programs

The Recorder – Area schools discuss benefits of financial literacy programs

Region faculty districts are expanding their aim on monetary literacy for middle and significant college pupils, in part thanks to a Greylock Federal Credit score Union sponsored plan termed Banzai.

Considering that 2010, Greylock Federal Credit Union has labored with Banzai to encourage the no cost on the net source and convey financial literacy schooling to much more than 14,440 pupils in Western Massachusetts and Columbia County, N.Y. The articles library can be found at greylock.teachbanzai.com, enabling customers to observe actual-globe financial education from their household or classroom, applying any internet-enabled machine.

In accordance to Banzai Public Relations Professional Elizabeth Fitts, the on the web assets can be utilised as supplemental materials to current college curriculum. In addition to being available to pupils, Greylock Federal Credit history Union customers may well also accessibility Banzai assets — which includes posts, calculators and customizable coaching periods that explain anything from the fundamental principles of filing taxes to how health and fitness insurance policy works.

Franklin County Technical University College or university and Profession Consciousness Educator Justin Lawrence stated the Turners Falls school will be applying the Banzai program as a unit for juniors and seniors in its School and Vocation Recognition course.

“Our complete reason is building futures, and we consider that a major component of that is economical literacy,” Lawrence said. “No subject their school or career intention, financial literacy is likely to be significant.”

He spelled out the software has an on the internet part in which pupils can obtain components and lesson plans, and an involved workbook will allow students to apply physical exercises on paper. Students check out out controlling a spending budget, preserving for a purpose and working with unforeseen money pitfalls.

In accordance to Fitts, Banzai methods are applied by more than 80,000 instructors throughout the U.S. and the instructional applications align with Massachusetts’ state curriculum prerequisites. Right after ending the Banzai courses, she explained customers will know how to observe in which their money is and what it’s for, realize money trade-offs and prepare for a monetarily seem long run.

Lawrence co-teaches junior students in a shared classroom together with Raye Youthful, who teaches seniors. He is an 2008 Franklin County Technological Faculty alumnus who returned as a new use this 12 months right after the “Career Awareness” class was expanded into the “College and Job Awareness” class, and to contain juniors alongside seniors for the very first time.

“We’re heading to be concentrating on university and career since our college students definitely have the alternative for each,” Lawrence said. ‘“All roadways direct to work’ is a thing that we’re declaring.”

In addition to economic literacy, the College or university and Career Awareness class teaches students other useful daily life expertise, such as higher education and career software competencies, interview skills, enterprise methods and other employability techniques that “are significant for absolutely everyone, regardless of whether their upcoming action soon after large faculty is a higher education classroom or business,” Lawrence reported.

Though educational institutions and inhabitants in several Franklin and Hampshire county cities are stated as possessing access to Banzai, some educational institutions have picked to use other fiscal literacy means for their curriculums. Mohawk Trail Regional College College or university and Occupation Counselor Sara Neuenschwander reported her district does not use Banzai. As a substitute, it employs Subsequent Gen Personal Finance (ngpf.org) to educate students in seventh as a result of 12th grades in the course of advisory intervals in the very first half-hour of each and every college working day.

“We decided their curriculum was what our pupils form of had been asking for,” Neuenschwander explained of the Following Gen Own Finance method.

The program delivers semester, 9-7 days and 12 months-prolonged selections. It also provide professional growth assets, films, podcasts and other instructional instruments in a “very perfectly laid out platform,” she claimed.

The use of the Upcoming Gen Private Finance plan will tie into the Mohawk Trail Regional College District’s “Trailblazer Design,” which focuses on scholar-centered understanding and aims to put together students for the world immediately after high college — no matter whether that is university or occupations.

Neueschwander reported students ended up surveyed on subjects they would like to learn about.

“Personal finance relevance — information they can use now — came up as a major thing they seriously were being interested in,” she said. “We have a particular finance class, and a good deal of feed-back we obtained from learners was that that was these a valuable class. So we listened to what our college students had to say and found the (Subsequent Gen Personal Finance) curriculum.”

Zack DeLuca can be reached at zdeluca@recorder.com or 413-930-4579.

The 5 Best Podcasts for Personal Finance

The 5 Best Podcasts for Personal Finance
Spiderstock / Getty Images/iStockphoto

Spiderstock / Getty Images/iStockphoto

If you are seeking to learn personalized finance, or obtain a way to submerse you further more and hold money on your head, podcasts are a great way to commence. You can listen during day-to-day commute situations or even when you’re carrying out other points, if you’re a very good multitasker.

Did You Know?: Outdated-School Funds Suggestions You Should not Observe Anymore
Come across Out: 12 Important Money Guidelines for Each Stage of Your Fiscal Existence

GOBankingRates identified five private finance podcasts that go over every thing from student bank loan credit card debt to authentic estate investing to retirement organizing (and much more). Hosted by specialists, if you’re into all things personalized finance you should absolutely give a hear.

Brown Ambition

Brown Ambition is headed up by bestselling finance author Tiffany Aliche, and past director of articles at Lending Tree, Mandi Woofruff-Santos. The women deal with true, day-to-day complications with everything from how significantly income is correct to give at weddings to how to conserve for retirement when you are however drowning in college student financial loans and credit score card credit card debt. The ladies also have an “Ask Me Anything” portion on their web-site in which you can submit any question you have anonymously to be highlighted on their five-star rated weekly clearly show. They hold it mild, but straightforward — and what much more could you truly want?

Read: Funds Information Industry experts Would Give Their More youthful Selves

Coach Carson

Actual estate investing is acquiring its moment this 12 months, and Coach Carson‘s podcast focuses on how to make revenue investing in real estate properties. Regardless of whether you are on Instagram and your beloved meme site pops up sponsoring another person with a write-up describing how they bought wealthy with “seven rental properties,” or a speedy TikTok beat that statements genuine estate built them massive bucks, likelihood are superior that your eyes have landed on this technique in 2021. Coach Carson interviews massive wigs in the authentic estate house, so you get to listen to straight from the execs on how to do what it looks like absolutely everyone else is. This edge, plus his concentrate on this approach as a route to economical independence, is what helps make his display a stage above the others.

Acquire a Search: Finest Investing Information From These Top rated 10 Gurus

Freakonomics

Certainly each money qualified and economics university student on the earth is aware the ebook by identify, but now Steven Levitt and Stephen Dubner have graced us once yet again with their personal podcast. The standard gist of the reserve is that there is an underside to anything — specially the way the entire world, and the economic climate, works. Levitt is a distinguished economics professor at the College of Chicago, and describes properly the hidden aspect of every thing in the smash-strike debut reserve. Dubner famously said, “Morality, it could be argued, represents the way that persons would like the earth to function, while economics signifies how it truly does operate.”

Professional Earful: 10 Ought to-Hear Personal Finance Audiobooks

Fifteen Minute Fiscal Advisor

Michael Policar is a licensed fiduciary money planner who also runs his possess financial organizing podcast. He’s a pro, and you can convey to by the way he speaks. If you have ever viewed Khan Academy on YouTube all through university or making ready for a grueling licensing exam, Policar’s fashion and very clear explanations will audio familiar to you. He describes items like your personnel gains in a concise, tutorial way — but with out dragging on for half an hour. His know-how comes when detailing something like a 401(k) during its distributions phase, and how to established your retirement accounts up to guarantee you pay as minimal tax as doable — a little something you’d ordinarily have to pay out a monetary advisor to do. He also discusses how to get started investing, tax techniques in general and estate organizing amongst other items — and all in 15 minutes.

See: 10 Economic Guides That Will Improve Your Lifetime (and Funds)

We Analyze Billionaires

Billionaires are not well known with anyone. That stated, we can all borrow from some of their demonstrated strategies to strengthen our very own financial life, and that’s accurately what Stig Brodersen and Trey Lockerbie do with their podcast. Aspect of the Investor’s Community, the duo provide interviews like inflation masterclass with heads of financial commitment companies. Yet another favorite — “How to determine a terrific company” — teaches listeners how to pick stocks for elementary value rather than what is trending on Reddit.

Additional From GOBankingRates

Final updated: Sept. 21, 2021

This article initially appeared on GOBankingRates.com: The 5 Finest Podcasts for Personalized Finance

Why 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} Finance Offers Don’t Always Make Sense

Why 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} Finance Offers Don’t Always Make Sense

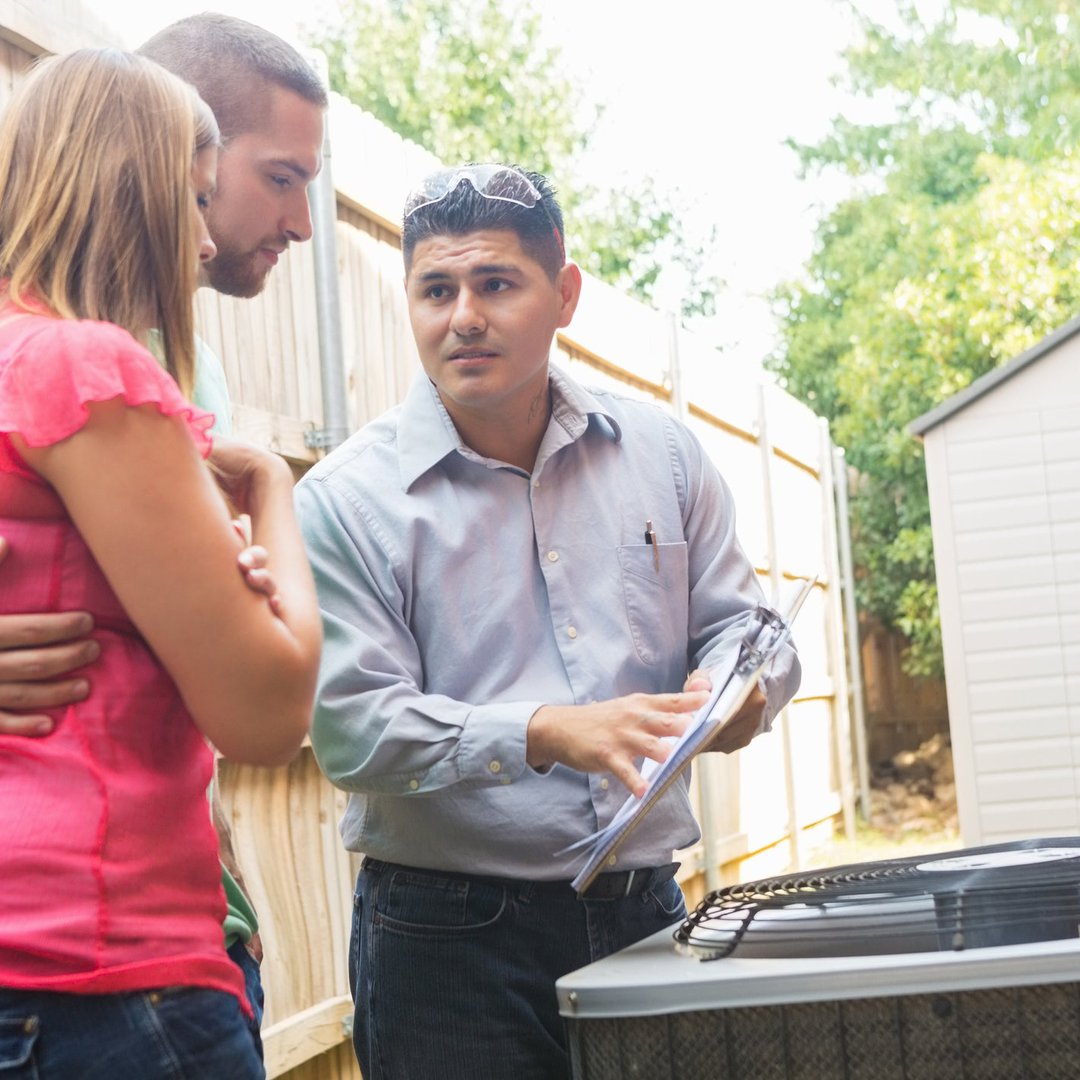
Just lately, my home’s air conditioning technique made the decision to crack, without having warning, on rather much the most popular day of the calendar year. Considering the fact that the procedure was more mature, repairing it didn’t make perception for my individual funds. I was pretty considerably compelled to change it with a new model — at a rate tag of about $7,000. I was actually, truly sad.

Fortunately, I took place to have the $7,000 offered in my personal savings account to go over that price. I make a level to set revenue aside for emergencies, because as a house owner, I know that highly-priced repairs can pop up at any time.

I practically did not withdraw from my discounts, for the reason that the air conditioning business available me a offer that seemed good — finance my new air conditioner at {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} about 24 months. With that supply, I could’ve taken on a monthly payment of about $300, which my incoming paychecks could protect without tapping into my cost savings. And considering that it was a {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} financing provide, I figured I had nothing at all to shed.

In the conclusion, I compensated for my substitute air conditioning program outright, utilizing income from my price savings. Here is why.

One email a working day could support you preserve thousands

Ideas and tricks from the professionals sent straight to your inbox that could enable you help you save 1000’s of pounds. Signal up now for no cost access to our Personalized Finance Boot Camp.

By publishing your electronic mail deal with, you consent to us sending you funds guidelines along with items and services that we consider might interest you. You can unsubscribe at any time.
Remember to study our Privacy Assertion and Phrases & Ailments.

The catch with {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} financing

You could possibly believe that {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} finance provides are way too great to be correct. But for the most aspect, they are absolutely authentic. It truly is not uncommon to get these presents to finance a invest in, regardless of whether it’s home furniture, a new auto, or a household maintenance.

But prior to you indication up for a {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} finance offer, it pays to inquire just one critical issue — is there a discounted for having to pay outright?

Typically, when providers provide {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} funding on an item or assistance, they develop the charge of funding into the estimate for the job. I was quoted around $7,200 to substitute my air conditioner at initial — but that $7,200 assumed I’d finance the substitute unit.

When I questioned about a lower price for not financing my air conditioner, the estimate dropped to about $6,900. That’s nevertheless a large amount of revenue. But considering that I had the hard cash in my discounts account, and withdrawing that income would not deplete my crisis fund, I figured it created far more sense to spend for my air conditioner outright and save myself the $300.

This isn’t to say that you generally qualify for a price reduction if you forgo {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} funding and spend in just one lump sum up front. But in some scenarios, you will enjoy some financial savings for paying outright. And that’s why {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} financing provides really don’t often make feeling.

If you you should not have money in price savings to go over a presented price, or you want to keep additional liquidity (meaning, you want to make certain you have a great deal of access to hard cash), then {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} financing presents are generally a very good way to go. Say you might be wanting to buy furnishings really worth $5,000, and can finance it at {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} more than two yrs. If you only have $7,000 in your price savings account, you should really in all probability indication up for the financing offer. If you don’t, you are going to depart by yourself with a mere $2,000 in the bank to cover unplanned expenditures.

But if, in that illustration, you have $25,000 in personal savings, you may perhaps want to spend for your furnishings outright if you can get a low cost. In that situation, you can expect to continue to have $20,000 money, and if that is enough to deal with at least a few comprehensive months of residing expenses, you will not have to fret about using a $5,000 withdrawal.

In my circumstance, I am happy I questioned about paying out up entrance for my air conditioner in trade for a modest price cut. Though I’m unsatisfied that expenditure arrived my way, saving a tiny money on it built me experience much better about the full circumstance.

Personal Finance: Mid-year review of your portfolio | Mumbai news

Personal Finance: Mid-year review of your portfolio | Mumbai news

With so lots of investment decision choices accessible, creating a portfolio is not difficult. But, for your dollars to expand, you have to have to be aware of expense developments and variables that have an effect on dollars development. It is important to frequently assess and appraise if the dollars invested is rising at the tempo initially envisaged. On the other hand, this entails a continued analysis together with a mid-year review of the portfolio. You can perform a mid-yr portfolio assessment in 5 simple and straightforward steps. These consist of:

Adopt a long-expression method

Overlook quacks that guarantee you double returns within just a thirty day period. Constructing a portfolio with a lengthy-phrase tactic and adopting the exact same strategy although examining it is vital. When the latest moments may possibly have turned your interest to acquiring an unexpected emergency fund or more than enough dollars in your personal savings accounts to meet up with procedure costs, investing with the intent to protected your prolonged-phrase economical potential should be the purpose. Current market movements may perhaps acquire a toll on specific investment possibilities that experienced seemed rewarding otherwise. Extended-expression financial commitment choices incorporate equity-type investments like stocks and serious estate. Fully grasp the market dynamics included in the performing of any and every single fiscal instrument. For illustration, debt devices offer stability but do not defeat inflation. Deciding upon to devote in equities as a result of Systematic Expenditure Designs (SIPs) makes certain normal financial commitment in the sector. This will also help save you from the inconvenience of timing the market place ahead of moving into and exiting it.

Hedge threats

The extent to which your decision of investments will behave in the very long run depends on the quantum of risk related with them and regardless of whether they have been shielded towards sudden market movements or unforeseen situations like the recent epidemic. A one of a kind way of hedging threats can be as a result of insurance plan. Likewise, investments need to also be insured by securing an unexpected emergency fund to meet contingencies. To guarantee complete money security, you need to consider care to diversify your investments. A nicely-diversified portfolio includes stocks, mutual fund investments, fastened-revenue devices, sovereign gold bonds and a bit of serious estate.

Money aims

Investments are manufactured maintaining economic ambitions in mind. Based on your chance appetite and ideal earnings in the lengthy operate, you can put your funds into equities and debt instruments. Apart from, you have to take into consideration components like current market volatility, modifying curiosity fees and sporadic monetary tips by the governing administration even though investing your cash. For case in point, a few many years back, Device Joined Insurance policies Plans (ULIPs) have been most popular irrespective of a part of the premium remaining dedicated to lifestyle deal with owing to its tax exemption alternative. However, modify of principles authorized exemptions from tax only for ULIPs with yearly quality up to ₹2.5 lakh per annum. This prompted lots of to change their investments to mutual funds topic to the very same tax slabs. Nevertheless, in the latter, the complete funds was invested in fairness or debt devoid of the burden of the included insurance policies include.

Tax implications

Investments, insurance policies and tax-conserving steps are distinctive from each and every other. Though examining your financial commitment portfolio, examine if you have availed of the tax-saving possibilities too this sort of as paying out for tax-saving fastened deposit receipts, general public provident resources, fairness-joined price savings techniques, and so forth. Start checking at the portfolio stage and then move on to specific investments to check which receive superior returns. When saving on taxes is crucial, the emphasis ought to normally be on investments that get paid substantial returns and not deciding on those that promise tax benefits but give very low returns. While reviewing attainable returns, compute the likely tax load too to work out the write-up-tax returns.

Change asset course

There is nothing mounted about belongings. If situations suggest the doable want for sufficient money in the future, opt for investments that can be conveniently liquidated. Opt for basic income market devices like accumulating income in savings accounts or parking some amount of money in set or recurring deposits. You can put some money in particularly brief-expression expense options as well.

Individual Finance is a weekly attribute that aims to deliver our readers pertinent and practical economic facts.