34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Z Is Learning Personal Finance From TikTok and YouTube, Survey Finds

34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Z Is Learning Personal Finance From TikTok and YouTube, Survey Finds

pressureUA / iStock.com

Generation Z has grown up in an age of low commissions and high technology, which has greatly influenced how they invest and learn about money in general. This generation that is between 6-24 years old right now is trying to use what they grew up with — things like social media — to their advantage instead of just for fun. While previous generations might’ve relied on family, financial advisors or other sources to learn about money management, Gen Z appears to be modernizing personal finance education in a way that works for them.  

Read: 51 of the Biggest Money Influencers on TikTok and YouTube
Check Out: The 10 Best Stocks for the Gen Z Investor

To find out about Gen Z’s approach to personal finance, investing and more money issues, GOBankingRates commissioned a six-question study of 1,000 Americans ages 18 to 24. Here are some of the most interesting results from that survey.

Gen Z Learns Personal Finance From TikTok and YouTube

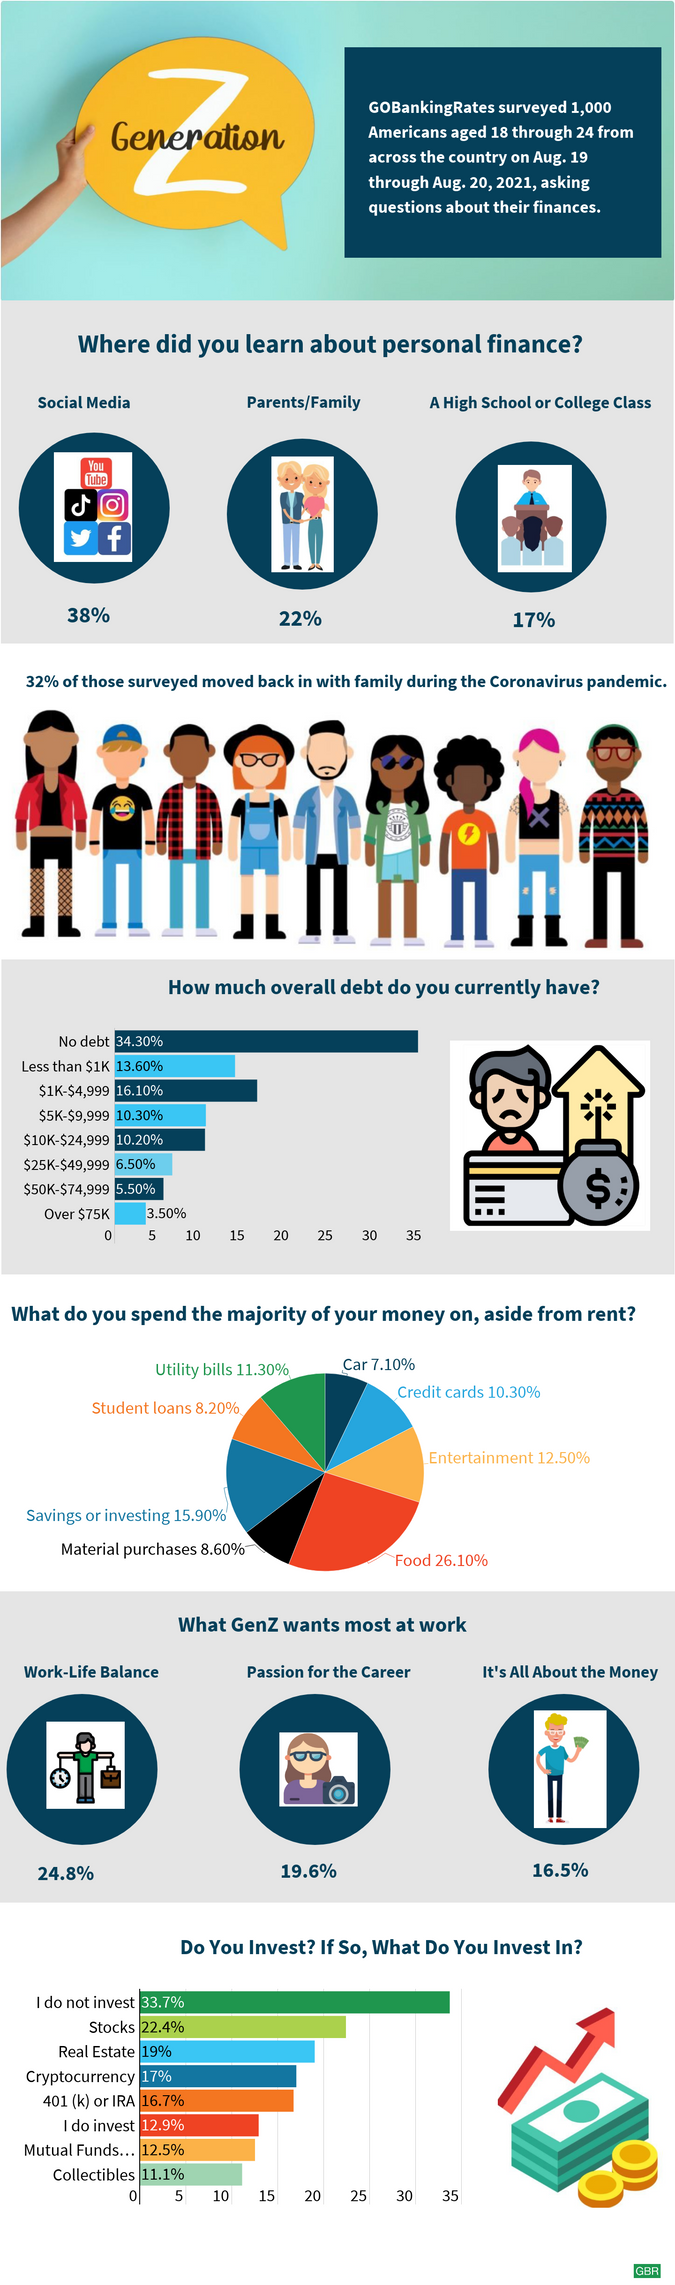
Perhaps the most notable result from the survey is that the younger generation gets a lot of its financial information from a source that didn’t even exist two decades ago. A whopping 38.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of Gen Zers responded that they learned about personal finance from TikTok, YouTube or other social media outlets, like Twitter or Instagram — 34.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} answered TikTok and YouTube specifically. An additional 7.20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} responded that they get their information from personal research and/or online forums like Reddit. Combined, that’s far more than the 22.70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} who reported learning from parents or family. 

A lot can be inferred from this statistic. For starters, it reflects how much social media and online information dominates the lives of Gen Zers. However, it also raises questions about the quality of information that Gen Zers are getting about personal finance. While there is certainly some valuable information to be found online, there aren’t many restrictions as to who can post online and what they can say. If Gen Zers aren’t vetting the information they’re receiving, they could be susceptible to financial misinformation. It also means they might be missing some of the fundamental principles about personal finance along the way, as only 17.60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated they learned their financial information from a high school or college class.

Find Out: 5 Financial Steps Gen Z Should Be Taking Now
See: Surprising Ways Gen Z and Millennials Are Worlds Apart Financially
A Surprisingly High Percentage of Gen Zers Invest in Real Estate

For the purposes of this survey, only those ages 18-24 were included. Typically, people in that age range are either finishing up their education or working their first jobs. In either case, Gen Zers haven’t had a lot of time yet to build up their savings and investment portfolios. Yet, a surprising 19{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of respondents indicated they were invested in real estate, which traditionally requires higher levels of investment and/or a good credit history. This was the second-most popular investment category of survey respondents, just behind the 22.40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicating they were invested in stocks. 

Although a large number of Gen Zers in the survey indicated they were invested, 33.70{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated that they were not invested in anything. This represented the single largest individual response to this question. While many Gen Zers may not yet be earning a lot of money to invest, it would benefit them to begin saving and investing as young as possible to take advantage of the power of compound interest.

More: Crypto and 5 Other Groundbreaking Investing Trends for Gen Z
Find: How Will Teens and Gen Z Invest Their Money? Think Low-Risk, ESG and Roboadvisors

Debt Levels Are Generally Under Control for Gen Z

While it might be more encouraging to see a higher level of investment from the survey respondents, the good news is that most of the Generation Z survey respondents indicated they had control over their debt. More than 34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of survey participants didn’t have any debt at all, including student debt, and nearly two-thirds had less than $5,000. However, 9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of respondents had at least $50,000 in debt. 

Find Out More: Life Events That Millennials and Gen Zers Are Choosing To Go Into Debt For

Many Gen Zers Still Rely On Their Parents

From the survey results, it appears that Gen Zers aren’t quite ready to completely stand on their own in times of trouble. During the pandemic, around two-thirds of respondents indicated that they lived with their parents. Although 13.90{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated they have since moved out on their own, a full 49.30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} indicated they either have always lived with their parents or moved back home during the pandemic and are still there.

Read: Gen Z Feels Financially Unprepared for Adulthood — But Has Hope for the Future
More
: 4 Industries Gen Z Might Save — and 4 It Might Destroy

There Are Some Notable Differences Between Male and Female Gen Zers When It Comes to Personal Finance

When it comes to money and finance, there were some relatively significant differences between male and female respondents to the Gen Z survey. For example, 26.13{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of women indicated they learned personal finance from their parents or family vs. just 16.53{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men. Men vastly preferred YouTube as a source of financial information, at 27.17{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. 11.98{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for women. 

Women were also more likely to have zero debt, at 36.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} vs. 31.09{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men, but they were also less likely to be invested: Only 25.77{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men indicated they were not invested vs. 38.10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of women. About 52{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men indicated they were invested in cryptocurrency and/or stocks vs. just 32.50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of women. 

More From GOBankingRates

Last updated: Sept. 15, 2021

Methodology: GOBankingRates surveyed 1,000 Americans aged 18 through 24 from across the country on Aug. 19 through Aug. 20, 2021, asking six different questions: (1) Where did you learn about personal finance?; (2) How much overall debt do you currently have? (Including student loan debt); (3) Do you invest your money? If so, what do you invest in? Select all that apply:; (4) If you had to pick one, what do you prioritize/value the most in a potential job?; (5) Did you move back in with your family during the coronavirus pandemic?; and (6) What do you spend the majority of your money on, aside from rent?. GOBankingRates used PureSpectrum’s survey platform to conduct the poll.
About the Author

After earning a B.A. in English with a Specialization in Business from UCLA, John Csiszar worked in the financial services industry as a registered representative for 18 years. Along the way, Csiszar earned both Certified Financial Planner and Registered Investment Adviser designations, in addition to being licensed as a life agent, while working for both a major Wall Street wirehouse and for his own investment advisory firm. During his time as an advisor, Csiszar managed over $100 million in client assets while providing individualized investment plans for hundreds of clients.

4 Books That Changed My Relationship to Money

4 Books That Changed My Relationship to Money

Welcome to Personal Finance Insider, a biweekly newsletter that connects you with the stories, strategies, and tips you need to be better with money.

Open book with money signs coming out of it on orange background 4x3


Rachel Mendelson/Insider


Here’s what: Books I’m currently obsessed with

I’m a book lover. You can find me reading no less than three books at any given time. Usually one is a novel and the other two are nonfiction.

Picking up a nonfiction book is one of the most cost-effective ways to mentally download a ton of information about a particular topic. And there’s no shortage of books about my favorite topic of all: personal finance.

I’ve read dozens of books about money, and many of them have been helpful in teaching me the basics — how to save, invest, and budget. But today I want to share four books with you that have given me an entirely new understanding of my relationship to money. Here are my current obsessions:

  • Brian Portnoy’s “The Geometry of Wealth” is full of insights that inspire me to think about how I can use money to shape my ideal life. He brings in lessons from other disciplines — history, neuroscience, and philosophy — to illustrate how everything in life is connected to money and how we can use that to our advantage. 
  • Morgan Housel’s “The Psychology of Money” implored me to think about how we behave as investors, savers, and earners. He takes what we assume to be true about money and turns it inside out. I’m always game for new perspective.
  • Rachel Rodgers’ “We Should All Be Millionaires” is a new book, released this past spring, that had me hooked from the introduction. Rodgers’ financial ambition is infectious, plus her ideas are inventive and totally actionable. This book has reminded me to never sell myself short.
  • Ramit Sethi’s “I Will Teach You To Be Rich” has been a favorite for years. It was first published in 2009 and updated a decade later. In addition to really helpful beginner investing and money management advice, Sethi introduces the concept of building a “Rich Life” for yourself and how to identify and get over your money hangups. It’s always relevant. 

Happy reading!

—Tanza Loudenback, Personal Finance Insider correspondent and certified financial planner

P.S. My time at Insider is coming to a close — it’s been a pleasure sharing my money musings with you over the past year. Going forward, senior editor of Personal Finance Insider Stephanie Hallett will be authoring this newsletter.


PFI Newsletter divider


Insider


Ad: This startup wants to help you plan for an easy retirement

After seeing too many people miss opportunities to maximize their retirement income, SmartAsset developed a free tool that helps you find unbiased, expert advice. If you’re ready to make smarter decisions around investing your 401(k), optimizing your savings, and minimizing taxes, SmartAsset’s tool can help you accomplish your financial goals. Learn More »

Disclaimer: SmartAsset is an Insider affiliate partner. We may earn money when you use our links. Learn more.


Join the Master Your Money Bootcamp

In our first two Master Your Money Bootcamps of the year, we got organized — and then we used that mental space to start dreaming big and crunching the numbers. Now we’re taking action.

Our third Master Your Money Bootcamp: Make a plan, presented by Fidelity, is a month-long challenge broken down into simple, one-week exercises. We’ll walk you through tasks that include finding the right accounts for your goals, opening those accounts, setting up an automated system, and figuring out whether you could benefit from professional help.

You don’t even have to sign up. Just check back here for a new exercise every week, or jump in at any time, and follow along on Twitter, Facebook, LinkedIn, and Instagram.


Stories you might have missed

5 strategies an entrepreneur used to go from making $41,000 a year to being a multimillionaire in her 30s

This is a taste of the inspiring advice you’ll find from Rachel Rodgers in “We Should All Be Millionaires,” one of the books I recommend at the top of this newsletter.

Extreme frugality was so stressful it made it hard for me to save, but my new system is helping me save thousands more every year

Insider contributor Katherine McLaughlin set up two separate

checking accounts
for spending after realizing that just because she was “good” with money didn’t mean she had a good relationship with it.

I travel the US full-time on $90,000 a year by following a few smart money rules

Angie Colee, a confidence coach who works with entrepreneurs, has been Airbnb hopping while working for the last nine months. She explains the financial moves she made to take the leap, and how she keeps it going.

5 challenges I did with my husband to save an extra $2,500 in 2021

If you’re looking for ways to bulk up your savings account before year’s end, here are some simple ideas that worked for Insider contributor Jen Glantz.

Enjoying this newsletter and want to recommend it to a friend? Here’s a sign-up link. 

More reasons to learn about finances

More reasons to learn about finances

In the final column we shown the to start with a few of my ten good reasons to find out about private finances, and to teach them to your little ones. There are many other reasons. These 10 ended up just the 1st kinds to arrive to brain. Below are the previous seven.

1. You really do not want the bad management of your funds to reduce you from acquiring not only your economical ambitions, but your profession and existence aims.

2. It is not about your Educational IQ, it is about your Monetary IQ, and the two are not the exact same. Also it is not about how substantially money you have in lifestyle, it is about how you regulate your funds, and those people two matters are not the very same either. You need to see the experts in personal bankruptcy court (lecturers, engineers, nurses, and so forth.), who have so mismanaged their money, and they experienced a good deal of it.

Personal Finance for Young People

Personal Finance for Young People

Youthful people today these days have a broader scope of earning from an early age, as opposed to individuals from a former generation. Even though crafting this post, I found out that even right before ending their undergraduate degree, lots of pupils get associated in some kind of employment, Real Estate.

For that reason, soon after finishing their diploma and becoming a member of the workforce, the very first paycheck does not catch them very as off guard as 1 would assume it to, and with prior knowledge in earning, they are able to make better use of the revenue as well.

For all most recent news, stick to The Every day Star’s Google News channel.
Nevertheless, even when 1 earns all over their scholar a long time, earning immediately after graduation holds a distinctive form of that means due to the fact one is envisioned to out of the blue be additional dependable at that stage. In a single kind or a further, yours certainly has also generally experienced some sort of an income. The serious dilemma of really handling my funds in a correct way began when I was set on a month to month payroll even though doing the job entire time for an organisation.

At the root of controlling one’s finances lies obtaining a surefire resolution of correctly preserving up that dough and this looks to be wherever youthful persons battle the most.

“I initially commenced earning when I was 19 decades aged but it is really only been a few of months considering the fact that I actually begun to conserve up portions of my wage. Ahead of that, I would skip the personal savings component fully which I now realise was a foolish thing to do,” relays English literature graduate Tarin Ahmed*, 24, now working as a content material author for a website advancement enterprise.

With an growing scholar financial debt culture circling today’s youth, the biggest assistance any one can give you about handling your funds is to generally preserve up a great chunk of your monthly profits when it is attainable. This, of training course, may well not be feasible relying on one’s situations. But, even if you can save 10 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your earnings, it is really a great start out. A excellent suggestion to get you heading on your personal savings journey is to start off considering it as a non-negotiable month-to-month expense.

Saving does not occur without having its possess hurdles both. With the social media algorithms and specific ads displaying you items that you only believed about possessing in your desires, mastering self-command has to develop into one’s next-character.

Card payments and cellular money companies (MFS) have also taken centre stage amongst the youth now and although we cannot deny the pros these providers have brought along with them, the relieve of payments by means of these procedures often make it all also hassle-free to purchase merchandise.

Not to point out, when we buy by way of cash, we are giving absent one thing tangible which in some cases tends to make it a lot easier to restrain oneself when we glance at the ever-decreasing volume of our wallet. In distinction, obtaining something as a result of the simply click of a button could not have the exact effect. As a result, self-manage turns into all the additional essential and complicated at the similar time.

This is when budgeting will become your most effective mate. Budgeting can be as complicated as you want it with various excel sheets and budgeting applications, or it can be as basic as mentally categorising the checklist of expenditures and personal savings. A superior middle floor in this article for starters would be to just use excellent outdated pen and paper to categorise all the demanded fees for the thirty day period and then assign a particular proportion of the every month income to every single group.

Owning an notion of the required expenses at the start of the thirty day period will assistance you mentally put together on how to go about shelling out throughout the month as perfectly as stop you on your tracks when you are on the verge of overindulging. Listing down all the actual expenditures at the stop of the thirty day period and retaining track of them would also assistance you make greater paying out decisions in the long term since you will be capable to see the larger photo. You can monitor down in which you are paying the most of your funds and if there are strategies to slash down specified unwanted costs.

If you are fascinated in superior managing your income move, seeking into budgeting applications can be an possibility. In addition to providing budgeting methods, these apps also deliver other solutions that let you to lessen your payments, help save income, or even give you expenditure suggestions in some scenarios. Here, you may have to go as a result of a trial and error system to discover the app that greatest suits your needs. An critical phrase of tips,adhere to the membership cost-free apps and you should not insert onto your checklist of bills.

Besides strict budgeting, another way to create far more wiggle home inside your income is to just shell out smartly. What it in essence indicates is to acquire edge of the actuality that we can get any facts we have to have at the tip of a button. Research extensively for much better specials specially for goods you want to invest on each individual thirty day period this sort of as your everyday groceries or an highly-priced piece of tech that you may be utilizing for a long time. Make certain to constantly get the finest deal for your buck. If you are ready to even conserve 20 percent on your everyday espresso, in the prolonged run, this will add up to a big quantity.

A common topic that seems to extend among refreshing graduates is their lack of any suitable extended-time period money strategy or goal.

“In terms of controlling my finances, I just preserve my earnings in my MFS account and commit from there as necessary albeit preserving up 60 p.c of my income each individual thirty day period,” states Famia Farhin, a 22-year-aged who runs a little business enterprise offering hand-created add-ons and paintings online.

A comparable mentality is again echoed by 25-yr-outdated Farhan Rahman who is effective for a pharmaceutical corporation. Just after encountering the company sector for about a calendar year, he points out, “I usually conserve at minimum 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of my regular monthly earnings. I would not phone it a fiscal prepare essentially, but my plan is to have a sustainable backup considering the fact that you hardly ever know what can go completely wrong.”

Only conserving sure amounts of revenue does not serve very well in the very long operate as inflation may end up eroding the value of your really hard-gained funds. In this circumstance, 1 has the possibility to conserve revenue in price savings accounts that deliver curiosity, funds marketplace accounts, or opening a certificate of deposit.

As liberating as it may be to be capable to pay out for oneself, personalized finance can be a tough concept to wrap your head close to at first.

“The self confidence and independence that comes from earning your individual funds can’t be in contrast to any other. It makes you experience that your belief counts. I experienced large options with my tough-earned dollars which provided travelling, buying items, and preserving up for my long run. I was psyched to be in a position to plan for myself,” displays Sudeshna, who is effective as a documentation officer for the development sector, after finishing her undergraduate diploma.

For the types who have just started out earning, you may well not have even thought this thoroughly about your funds but. In that situation, just start out off by simply just creating a finances and then sticking to it.

*Names have been improved for privateness

Tasnim Odrika has only one identity trait and that is cats. Share concepts for new personality characteristics with her at odrika02@gmail.com

Visit : https://marylandheightsresidents.com/

Personal Finance: What must you read in a mutual fund before investing in it? | Mumbai news

Personal Finance: What must you read in a mutual fund before investing in it? | Mumbai news

Given that the start off of this year, asset administration organizations have declared roughly 100 new mutual resources with just about every fund catering to distinct traders with distinctive threat profiles. Several of the new fund choices (NFO) ended up much less expensive with lower internet asset values (NAVs). Provides of reduced NAV have enticed lots of laymen investors blissfully unaware of the aspects that ought to be looked into before investing in mutual funds. Even though a very low NAV justifies the rupee value averaging approach and allows accumulate much more models in the beginning, there are challenging info that a single must not disregard though studying a fund to consider its prospective clients. Mutual resources differ due to the fact of portfolios and risk-return valuations, so before you acquire a single, you will need to assess and evaluate these factors:

Check for various danger amounts

The danger component is distinct for all mutual fund groups. You need to verify if the mutual fund is incredibly dangerous, reasonably threat or involves very low to reasonable possibility. For case in point, many persons unable to trace and monitor inventory market place movements desire investing in equity mutual cash. Though these are significantly less dangerous than direct investments in shares and inventory, they occur with a particular quantum of chance. In advance of investing in any mutual fund, check out for the inherent possibility in the pictorial representation of the danger identified as riskometer. Every mutual fund scheme has a amount of threat assigned to it in the riskometer – watch that very carefully ahead of investing.

Portfolio issues

Commonly, we chat about portfolios whilst planning an expenditure basket or investing in our preference of stocks as for each our threat appetite. But did you know that you will have to also look at the portfolio of a mutual fund to look at the sector it is invested in the most? Choose for instance two midcap resources. Axis Midcap Fund focuses far more on fiscal services sector with up to 17.49{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} invested in all those shares, when IT shares constitute 13.97 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the full allocation. In comparison to this, Kotak Rising Fairness Fund has no IT stock and its expenditure in economical solutions sector is 12.47 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of its full portfolio allocation. Realizing the sectors that a mutual fund invests in makes it possible for you to make informed decisions: what’s going on presently in the IT and financial sectors? How would stocks in companies from these sectors conduct otherwise from that of the hospitality sector or any other that has been marred below the pandemic outcome.

Good quality of stocks

Examine for the top quality of stocks in the portfolio. Comply with the list of names of the businesses and the percentage of investments manufactured in them. For instance, stocks of TCS, L&T Technology Solutions, IRCTC, SRF Minimal, Godrej Genuine Estate, and so forth. are anticipated to produce increased returns in the very long operate owing to the nature of their enterprises or enjoy monopoly status in today’s periods. Verify if the best high-quality of stocks prime the list as their existence in the portfolio reflects the ability of the fund to provide outstanding returns on the amount invested. The excellent of shares in the portfolio would be mirrored in the returns that underscore your portfolio overall performance.

Immediate options as opposed to normal plans

Even though acquiring a mutual fund scheme, you will be specified the selection to choose among direct and common mutual resources. Essentially, these differ only in conditions of their price ratios. As is apparent from their greater NAVs, direct options make increased returns in comparison to standard plans. The expense ratio of the former is lesser than the latter. This is simply because direct programs can be invested in sans any intermediaries while the standard strategies contain getting by way of an agent or broker and that’s why contain commissions and brokerage charges.

Regularity of returns

Earlier overall performance is not the hallmark of guaranteed returns in long run. A mutual fund earning 17{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} returns in a person calendar year that goes down to 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in the subsequent year is a bring about of issue. Review this with a mutual fund that has been offering 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} returns 12 months on yr. Consistency in performance is important as it underscores the fund manager’s potential to hedge challenges while earning good returns that beat inflation. A steady fund has greater probabilities of providing improved returns each and every year for a extended period.

Fund Supervisor Overall performance

General performance evaluation of a fund is the crucial to evaluating a fund manager’s expertise. Exceptional returns of a fund mirror the qualified fund manager’s skill to manoeuvre by means of the oscillating stock industry movement, particularly, in the course of predicaments like the stock market place crash in March 2020. Do a track record check of the fund supervisors connected to the mutual fund to ascertain their potential to receive substantial returns in sync with your money intention.

NAV efficiency

A lot of people shy absent from investing in mutual resources with better NAVs. Comparing NAVs is futile as mutual money with the identical portfolio will yield similar returns. However, some cash perform greater than other individuals or have much more assets less than administration, as a result, explaining their larger NAVs. There is a widespread misconception that mutual funds with lessen NAV are more cost-effective, and that’s why, far better. Also, just since some mutual cash have substantial NAVs, they should not be overlooked.

Periodic rebalancing

In no way spend in a single mutual fund by itself just for the reason that its portfolio and scheme details match your economical targets. Verify diverse mutual cash, their portfolios and come to a decision how they can increase value to your financial commitment goals. Just before you start off investing, check out for the asset allocation in these mutual money. Moreover, you have to regularly check out to examine how your mutual resources are doing. Also, do periodic rebalancing of your money based on your new aims, which suggests redeem a non-executing fund to devote in a fund that promises increased valuations.

Personal Finance is a weekly element that aims to provide our viewers pertinent and handy financial details

How the pandemic changed personal finance and how you can save, invest and spend better

How the pandemic changed personal finance and how you can save, invest and spend better

How need to just one develop their difficult-acquired cash?

This dilemma has been prepared, spoken, and debated at size and in depth. And, proceeds to.

However, most people today however find it tough to control, preserve and invest their earnings. If just about anything, the pandemic has as soon as again place the spotlight on why a person ought to plan their monetary foreseeable future early on. And, the encounter was no unique for Monika Halan, ideal-marketing writer and consulting editor and section of the management group at Indian every day Mint. She claims, like lots of, the pandemic compelled her to relook at her portfolio allocation. This is in spite of the truth that they are in their 50s and self-confident of earning even publish retirement. She reveals that it is not the current market crack of 30 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} that activated the rethink but the actuality that there are a lot less many years forward than a more youthful individual – each in phrases of well being and revenue.

Dollars administration: Classes from the pandemic

Monika could up her saving concentrate on sharply the working day she decides to go on a lockdown manner pandemic. Whilst she formerly regarded herself a frugal spender, the lockdown had prevented her from investing everything outside of the basic principles. Other than EMIs, hire, helper salaries and principles, the fees had crashed. This encounter of residing on so minimal was a impressive encounter, she shares.

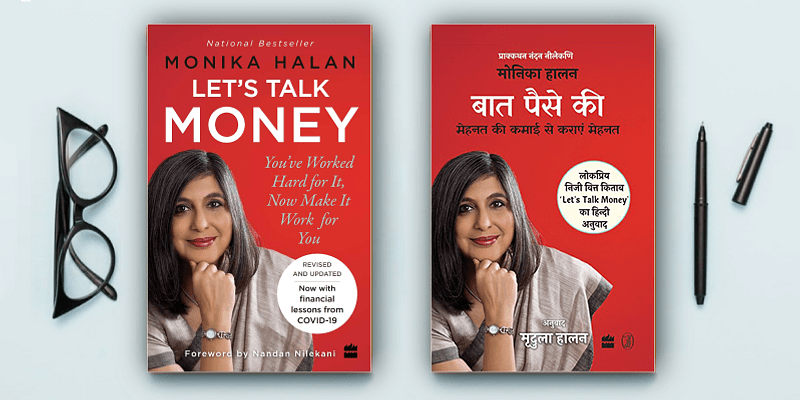
In the updated edition of her best-providing e book Let’s Speak Cash – to start with posted in 2018 by HarperCollins – Monika shares intriguing insights on what the pandemic taught all of us about our money. Pointing to a different economical lesson was the will need to have an crisis fund. Holding a higher-hazard personal sector deal occupation, she experienced managed a 6-month unexpected emergency fund irrespective of figuring out that their employment are fairly safe. But, she resolved to ramp up the fund to two years’ costs in a fastened deposit (FD). In the e-book she claims, “The want for zero-chance cash desired for survival in a safe and sound lender (PSU or 1 of the premier non-public sector banking companies) all of a sudden results in being manifest. My advice of crisis money has now transformed. For these forty years and under in a protected position, you are fantastic with six months of dwelling expenses in an FD. But as age raises, as the riskiness of the task goes up, ramp up the fund to reach two many years for older cohorts in jobs that are not that safe.”

The 3rd lesson was that of rethinking chance. From freezing of deposits by a personal lender to fund properties shutting down to market place crashing, practically nothing felt safe and sound, which highlighted that no economical merchandise was without possibility, just different forms of threats. She writes, “The fact is that there is no safe haven for your cash. Each and every investment decision arrives with some challenges and you have to make a decision which a single you are capable to just take.” And, listed here she can make an fascinating observation. She details out that danger capability and risk urge for food are absolutely two unique items. Though danger appetite refers to one’s willingness to get challenges, risk potential is dependent on aspects this sort of as age, quantity of dependents and stage of dependents, self-confidence in making earnings for a extended time. Which is why threat hunger and chance potential have to have to be aligned though setting up the funds and allocating assets. In the reserve she also clarifies why just one fastened obligation-to-profits ratio should be 30 per cent or much less. In other text, all EMIs put alongside one another ought to not be much more than 30 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} or fewer.

She writes, “Uncertainty obtained a new identify with COVID-19 for our wellbeing, daily life, earnings, and prosperity. Whilst the standard ideas keep on being the identical, there are some classes learnt from this crisis for our wellness and prosperity.”

Finance is for anyone

Apart from how the pandemic introduced in a shift in viewpoint on certain factors of money administration and investments – which Monika points out in detail and quotes her own investments as illustrations – the e-book holds elevated relevance for persons who are on the lookout for simple guidelines and straightforward-to-fully grasp explanations on how to deal with their cash. And, right here, Monika’s previous working experience as a certified economic planner and a leader who labored in India’s major media organizations creating and operating productive columns and Television set exhibits close to particular finance advice, will come to the fore. For her, tips are not only insightful and complete but also functional. The a lot of authentic-existence anecdotes perform an equal purpose in making it quick to realize. The guide cuts by the cutters due to the fact the explanations address each problem you experienced in mind and evidently outlines the measures you could take to regulate your funds improved amidst the Indian realities.

For instance, the e book reiterated the require to notice your investing patterns and how you can evaluate the sample to conserve income that you can later on commit. She describes how as soon as you problem your paying, you will comprehend how significantly income you really want for handling regular charges. and by parking income for investing you will be able to gauge your discounts capability. She advises that a single need to be equipped to shift at the very least 10 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your in-hand salary for investments, irrespective of what your economic commitments are – be it EMIs, hire, etcetera. She writes, “Eating out, heading to the motion pictures, travelling and getting devices are the huge finances breakers. Go for a balanced instead than a hard-shelling out eating plan. Tough meal plans fall short.”

The ebook also demystifies lots of facets about dollars management and investments. For occasion, it not only describes what a healthcare insurance policy deal with is, but also if one particular need to invest

in health care include even if they are protected by their companies and how much protect a single would. It explains the distinctive policies that are available in the sector, the prices, the positive aspects and the questions one should talk to in advance of producing a selection. A different economical merchandise that the e book points out fantastically is lifestyle insurance coverage and her choose on it. She writes, “We invest in daily life insurance policy for all the incorrect motives – dread, greed, pity, irritation, taxes. The genuine purpose for a existence deal with, to shield your loved ones if you die, is hardly ever discussed.” She adds, “The working day you recognize that it is in your greatest interest to independent investments and coverage products and solutions, is the working day you go solidly to creating your fiscal stability. Else you are constructing prosperity for vendor and the insurance policy companies.”

Really do not miss out on the chapters on ‘Let’s de-jargon investing’ – character of distinctive forms of investments and the reason they serve. and what kills a cash box that talks about the a single solitary element that is liable for the investment selections.

TITLE: Let us Communicate Dollars

Writer: Monika Halan

PUBLISHER: HarperCollins India

Invest in NOW (English): https://harpercollins.co.in/product or service/allows-chat-cash/

Acquire NOW (Hindi): https://harpercollins.co.in/item/baat-paise-ki/