Facing Your Personal Finance Monsters

Facing Your Personal Finance Monsters

Few factors are scarier for me than Stephen King, significantly his reserve and pursuant film It. Thanks to them, I can in no way go near a clown all over again. There are also some scarier matters that can haunt us day soon after working day and night after night time: our individual funds. Right here are a couple of tactics to assist you conquer your best cash fears so that you can start out crushing your economical ambitions:

Anxiety #1: Shedding management of your money

Budgeting can be scary. We really don’t like owning to monitor just about every penny or sensation terrible about our paying out, nevertheless we feel awful when we’re broke or are residing paycheck to paycheck. It’s like staring at the encounter of failure and then wanting up at an insurmountable mountain to defeat. Yikes!

Deal with that monster in 3 measures:

1) Get started with “why?” Compose down why staying in handle of your revenue is essential to you. What will that make it possible for you to execute and how would your life modify? How would that sense? Setting up a potent ample “why” can give you the courage and commitment to get started the budgeting journey.

2) List out your expenses. I want the pen and paper method as a setting up stage. If you want a spreadsheet, here’s a template, you can use. If you want one thing larger tech, then an app like Simplfi, Mint, or Pocketguard may do the trick . The most essential issue is to decide on the technique that is least complicated for you.

3) Discover opportunities to preserve. Comparison store for charges like cable, wi-fi cellphone, and insurance. Get rid of charges for matters you really do not use or that don’t align with your why. You can check out added tips below.

Concern #2: Managing out of money

Owning your checking account go to zero is stressful. Then the unpredicted happens and you are still left with a horrible determination to make in between selecting which monthly bill will go unpaid or pulling out your credit history card. As we all know, the unanticipated tends to come about fairly often.

Deal with this monster in 3 measures:

1) Create an unexpected emergency fund: Open up a individual account for your crisis discounts. A superior produce financial savings or cash marketplace account is a excellent place to begin. The purpose of this account is for accurate emergencies, not for the occasional travel price or gift.

Make obtaining that account to $2,000 your #1 priority. Once you are there, proceed to increase all those personal savings in the direction of 3-6 months of costs though balancing your other economic priorities. You can study far more about making an crisis fund listed here.

2) Price range for occasional costs: If you want to be thriving with your budgeting, you are going to require to set aside funds for occasional expenses. For instance, if you commit $2,000 a 12 months on journey and $1,000 a yr on presents or birthdays, you can established apart revenue for these expenses in advance. I’ve uncovered setting up and funding a different account for each and every occasional annual price (ex. travel and holiday seasons) to be tremendous practical.

3) Set your price savings on automated: Set up a immediate deposit or computerized month to month transfer to your separate personal savings account. Your employer may be able to take funds immediately out of your look at and deposit it for you. If not, set up an automatic transfer from your checking to a financial savings account on payday.

Panic #3: Going through a mountain of high-curiosity amount personal debt

Carrying higher fascination charge financial debt (everything higher than 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}) can give you a horrible scenario of the heebie-jeebies. The extended you wait to address it, the even worse the catastrophe that awaits you will become. Creating your transfer now will preserve you time, money, and debilitating strain that can negatively affect your lifetime.

Slay the financial debt monster with these 3 moves:

1) Get inventory: List your debts, such as the total equilibrium, curiosity rate, and least payment because of.

2) Pick a credit card debt spend-off technique and put into practice it. The two most well-known approaches are the credit card debt snowball and the credit card debt avalanche. The credit card debt snowball is effective wonderful if you have lots of money owed and need to have some fast wins to raise your self esteem. With this tactic, you focus on paying out more on the least expensive balance debts very first and make bare minimum payments on everything else. As you pay every single equilibrium off, you roll the complete payment and insert it to the subsequent least expensive balance and repeat until you are financial debt-totally free.

The financial debt avalanche focuses on producing the more payments on the maximum interest charge equilibrium and minimum amount payments on every little thing else. You then roll the full payment to the following best desire level credit card debt at the time the prior debt is paid off. This strategy saves you the most time and revenue and can perform very well if you have a lower selection of debts and/or treatment most about the base line.

3) Leverage superior credit rating to refinance: If you have a sturdy credit history rating, leverage it to pace up your financial debt independence. (If not, comply with these recommendations to increase yours.) You may perhaps be able to sign up for a {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} equilibrium transfer, which can lower your fascination prices for a interval of 12, 18 or even 24 months.

You can also refinance your money owed through a lessen amount individual personal loan. Use a web site like this to take a look at what you may qualify for. Just be absolutely sure not to use these as an justification to even further insert on to your personal debt!

Fear #4: Getting to work Without end

Sufficient reported.

Just take these measures to protect against that nightmare from coming real:

1) Run a retirement estimate. This will let you see if you’re on monitor. You can use a calculator like this or a single of these.

2) Conserve sufficient to choose gain of your employer’s retirement system match. That is totally free money!

3) Routinely raise financial savings. If you can not preserve more than enough now to close the hole, test making use of an automated contribution charge escalator that could be made available in your employer retirement strategy or established a reminder in your calendar to manually enhance your discounts by 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} or far more every single yr (preferably about the time you get a increase) until finally you strike your goal!

Dread #5: Your investments getting long gone Eternally

The marketplaces have been ridiculous unstable and the media in all places is screaming recession, catastrophe or worse. In the course of these moments, we are inclined to really feel the most unsafe and apprehensive about our investments. In brief, the investment decision panic component is superior. Just take these techniques to calm those financial commitment jitters:

1) Really do not worry and make an psychological conclusion. In its place, evaluate your chance tolerance by using an evaluation like this. It will give you with an concept of what an correct expenditure mix need to search like provided your time body and convenience with taking possibility.

2) Stay targeted. The ideal matter you can do is to keep the training course and concentrate on your ambitions. If you have a money will need in the up coming 3-5 years then establish up your conservative bucket (in money, cost savings, or funds markets). If your demands are a lot extended time period, concentration on having an expense solution that is adequately diversified and is aligned with your time body and ease and comfort with threat.

3) Keep investing uncomplicated. If you really do not have the time, interest, and practical experience to control investments on your individual, think about a palms-off solution like a focus on date fund, asset allocation fund or a robo-advisor. If you want to be much more palms-on, target on very simple and small-charge investments like index resources and have a course of action to rebalance and test in on your investments. You can leverage these ideas to get you started.

As you can see, vampires, ghouls and goblins aren’t the only matters that fill a Halloween horror story. End respiration existence into these own finance monsters by starting to act currently. If you would like more assistance receiving commenced, consider consulting a competent and unbiased economical professional. You may well even have accessibility to just one for no cost via an employer-supplied financial wellness gain.
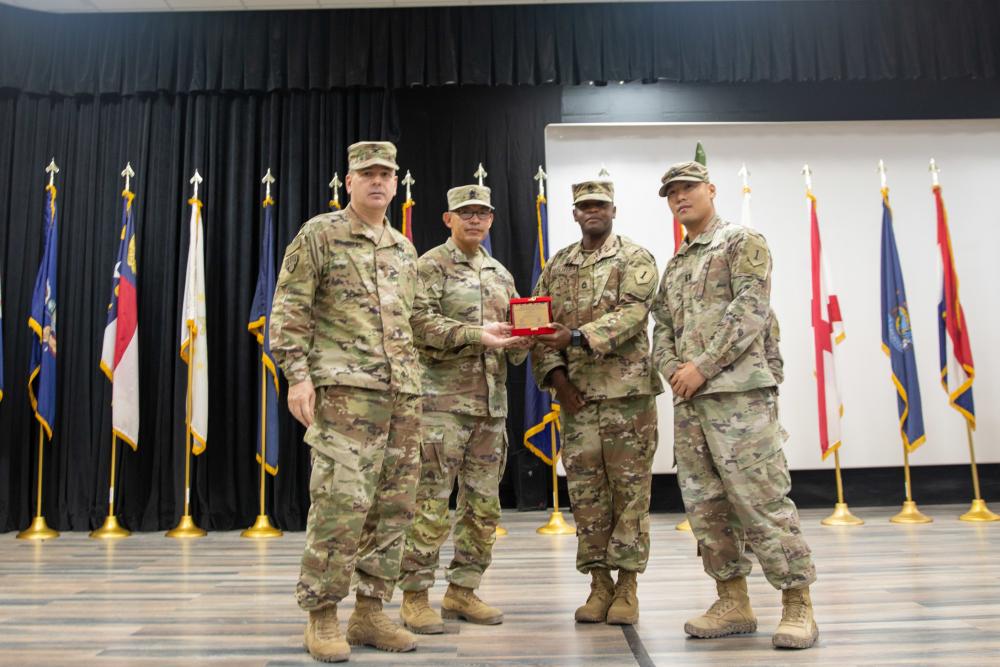
DVIDS – News – First Infantry Division’s Finance Unit transfers authority to 82nd Airborne’s Finance Battalion in Kuwait

DVIDS – News – First Infantry Division’s Finance Unit transfers authority to 82nd Airborne’s Finance Battalion in Kuwait

&#13
CAMP ARIFJAN, Kuwait, — A Transfer of Authority ceremony took position involving the 9th Money Management Assistance Unit, Undertaking Force Wildcards, and the 82nd Finance Battalion, Job Drive Diamond, on Nov. 19, 2022, at 10:00 a.m. at Camp Arifjan in Kuwait.

The ceremony that took position in the Morale, Welfare and Recreation Theatre here signified the finish of the obligations and duties of Task Force Wildcards, commanded by U.S. Army Maj. James Lemley, and the assumption of those responsibilities and obligations by Job Pressure Diamond, commanded by Lt. Col. Adrian Plater.

Col. Seth Morgulas, commander of the 369th Sustainment Brigade carried out the transfer of authority ceremony.

Morgulas took the time to emphasize that finance is one particular of all those matters we usually get for granted until eventually we want funds or until finally we really do not get paid. He also reminded anyone of the achievements and obligations of the 9th Economic Management Aid Device, or FMSU.

“In the very last 9 months the 9th FMSU collected more than $114 million and disbursed approximately $1 billion together with electronic resources transfers and accredited about $700 million in professional vendor fork out,” he explained.

The 9th FMSU also executed the EagleCash Smart Card which can give for all a services member’s economical wants, as an alternative to money, Debit cards, credit cards, and checks, when in a deployed locale.

Morgulas said that the Troopers of the 9th FMSU accomplished substantially and maintained the position quo of fiscal administration excellence throughout the CENTCOM place of accountability and expressed that he was very pleased of them and all they have accomplished and explained to them they must be very pleased of by themselves.

He wished them the greatest of luck in their following mission and long term assignments, and safe travels back again to their residence station.

The 9th FMSU signaled their transfer of authority by neatly and securely rolling their guidon, identified as the hues, and placed it in its scenario.

Capt. Danny Bungcayao, the command representative of the 9th FMSU, spoke about the dedication of his crew and their capacity to react to operations in several spots regardless of the tiny sizing of the unit.

He explained that the team went higher than and beyond to ensure operations had been finished with the utmost precision, professionalism and performance.

Bungcayao named just about every section and leader by identify, irrespective of rank, and manufactured specific mention of his junior enlisted Soldiers who stepped up and volunteered to choose on responsibilities previously mentioned their station.

Morgulas and Command Sgt. Maj. Curtis Moss with Activity Power Hellfighter introduced gifts to Bungcayao and Sgt. Very first Class Ivan Deoliveria, who gained them on behalf of the outgoing 9th FMSU.

Maj. Lemley could not attend but Morgulas wished him the most effective also. He thanked Lemley for his extraordinary leadership the past nine months, as effectively as Lemley’s devotion and stewardship of government resources, and his treatment for the soldiers assigned to the 9th.

The 82nd Finance Battalion, or FI BN, uncased their shades soon after the 9th FMSU cased theirs.

Morgulas welcomed the 82nd FI BN to the group. He stated that he appeared ahead to performing with them about the next 9 months.

“The up coming thirty day period will be tough but fulfilling for all of the Soldiers of the 82nd,” he stated.

Lt. Col. Adrian Plater, the commanding officer of the 82nd FI BN, thanked the leaders of the greater echelons for the prospect and explained that he, Command Sgt. Maj. Jennifer Boynton, his senior enlisted advisor, and all the Soldiers of Endeavor Drive Diamond are ready to deliver the aid important and take care of the obligations placed on them.

The ceremony closed with a benediction sent by Chaplain Maj. Robert Volk with the 369th Sustainment Brigade’s device ministry workforce, followed by the Military Music.

For additional data on EagleCash please visit https://www.fiscal.treasury.gov/eaglecash/

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

Day Taken: 11.19.2022
Date Posted: 11.20.2022 15:16
Tale ID: 433603
Spot: CAMP ARIFJAN, KW 

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13

&#13
&#13

&#13

World-wide-web Views: 46
Downloads:

&#13
Public Domain  &#13
&#13

Budget may steer clear of major reforms, PSB sale

Budget may steer clear of major reforms, PSB sale

Finances 2023-24 will very likely sidestep major reform initiatives, be it the targeting of fertiliser subsidy by using direct gain transfer (DBT) or the privatisation of community sector banks (PSBs) and state-run insurance policy corporations, men and women acquainted with discussions in govt mentioned.

This is due to the fact the Centre has resolved to go slow on stalled money-sector and expenditure reforms that could probably guide to any political backlash and expense it electorally. 9 condition Assembly elections are to choose place just before the normal elections, which will be held latest by May perhaps 2024. “The governing administration doesn’t want to antagonise persons just when so lots of states are likely to the polls ahead of the standard elections in early 2024. Political opponents could instil anxiety amid folks about reforms even nevertheless they are well-intentioned,” a senior official mentioned. “There is no hunger for any important disinvestment now in the banking or insurance plan sector. Even several BJP leaders are against privatisation,” one more formal reported.

Finance minister Nirmala Sitharaman, in her Funds speech of 2021-22, experienced declared that two PSBs and 1 point out-operate typical insurance provider would be privatised, incorporating that Charges would be released in Parliament for this purpose. The voting legal rights cap of 10 for every cent for a non-govt shareholder irrespective of her shareholding is among the the critical constraints determined for the privatisation of PSBs. The govt will have to have to possibly amend or repeal the Banking Providers (Acquisition and Transfer of Undertakings) Functions of 1970 and 1980, normally referred to as nationalisation Acts, to eliminate the hurdle. Although the Banking Rules (Modification) Invoice, 2021, was outlined as element of the legislative enterprise for the wintertime session of Parliament that concluded on December 23, 2021, it is nonetheless to be tabled in the House. The Cabinet, far too, has to ratify the draft Invoice before it is introduced in Parliament. Sections within just the federal government come to feel that the system could be initiated only immediately after extra consultations amid stakeholders, significantly likely traders.

On its element, the Niti Aayog has currently recommended the privatisation of Indian Abroad Lender and Central Lender of India, but the governing administration is nevertheless to just take a last contact on the names of the offer-off candidates. The stalemate is even as the governing administration is open to the idea of offloading its complete fairness in the two banks that are proposed to be privatised, as an alternative of the first system to retain a 26{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} stake, to garner increased curiosity from probable buyers. With it, there would be procedural changes, like the quantum of individual shareholding in these banks, to aid the offer-off. Now, Parliament has cleared a Invoice to aid the privatisation of state-run normal insurance policy organizations by eradicating the necessity of the central govt to hold at least 51{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} stake in an insurance provider. But the sale of a condition-run insurance provider is yet to just take area. Even however the government has efficiently managed to privatise ailing countrywide provider Air India this 12 months, it abandoned the privatisation of gas retailer-cum-refiner BPCL because of to adverse marketplace circumstances as properly as the lack of authentic pricing flexibility for oil advertising and marketing organizations.

The Centre’s fertiliser subsidy bill, which has nearly tripled to about Rs 2.3 trillion in FY23 from Rs 70,000-80,000 crore per annum right before FY21, may well stay elevated in FY24, too, if international hydrocarbon charges really don’t moderate. To curb the rise in subsidy, the authorities was toying with the strategy of providing subsidised fertilisers or equal dollars on a for every-acreage foundation. “No one is conversing about the fertiliser subsidy reforms now,” yet another formal mentioned. FE

The trauma of the 20-year-old applying for the $200k finance job. Jane Street’s FTX sorrows

The trauma of the 20-year-old applying for the 0k finance job. Jane Street’s FTX sorrows

It might sound like a wealthy person’s difficulty and to be fair there almost certainly is a honest overlap with complications in that group, but it is also the trouble of the particular person making an attempt to be (comparatively) prosperous. – Implementing for a banking career when you happen to be a newly elite university college student is really hard. When your aspirations are contingent on a faceless Hirevue interview, you can experience disempowered. 

The Money Periods‘ Lex column has identified students enduring these sensations. They are at the Wharton Faculty in Pennsylvania and quite possibly hence fall into the Outstanding Sheep category of outstanding young people today who jump beautifully through hoops with no contemplating why, as outlined by former Yale professor William Deresiewicz. The Wharton learners are not possessing an easy time. They are “anguished”, states the FT. Their time is expended refreshing LinkedIn to see irrespective of whether classmates have introduced how “excited” they are about their expenditure banking internship at JPMorgan following summertime but. 

Aside from LinkedIn features, a lot of this has been going on for many years. But this year, it really is even worse than it is been for a when because internship programs have opened so early. As we described in Oct, banks haven’t just been selecting for summer season 2023 internships, but for summer time 2024. This means initial 12 months (sophomore) students who could possibly in any other case be signing up for cheese societies or consuming beer are obtaining a harsh indoctrination to the expense banking recruitment procedure, and an early introduction to the unfamiliar horrors of failure. 

To have any chance of internship software achievements, time that ought to be used finding out ought to be invested ingratiating oneself with senior bankers at recruitment activities and making ready for interviews that incorporate technical issues on accounting, valuation and modelling even while you haven’t actually examined any of that stuff nevertheless. Basically accomplishing the interview is a around impossibility. Having an job interview for a graduate job at non-public fairness firms marks you out as the sort of amazing individual everyone needs at their occasion (except there are no parties since everyone’s so busy refreshing LinkedIn).

Certainly, it’s determined by money: entry level banking positions now pay out $200k, points out the FT in a few decades that can double. But it truly is peer pressure and anxiety of failure also. It is really “insanity” states a person student. It is all above by the time you happen to be 21: you’ve both got the internship, or you have not. 

Individually, the other traumatized men and women on the fringes of finance right now are allegedly to be found at Jane Avenue, the algorithmic proprietary trading business. Two of Jane Street’s alumni – Sam Bankman Fried himself and Caroline Ellison were jogging FTX and Alameda Investigation respectively, that means the business is becoming described in the same breath as the blow-up of the crypto exchange and its trading arm. There have been statements, for example, that SBF made his behavior of going barefoot for the duration of his time there. 

Jane Road hasn’t said something directly, and neither SBF nor Ellison have worked at the company for at minimum 4 decades, but Autism Capital the Twitter account linked with “based” information on FTX, purports to have unearthed an individual acquainted with the means of Jane Street insiders. They are, allegedly, not content.

Meanwhile… 

Genesis was seeking for a $1bn loan before it suspended redemptions. (WSJ) 

From the new CEO of FTX: “Never in my career have I found these types of a entire failure of company controls and this sort of a complete absence of reliable monetary information and facts as occurred in this article.  From compromised devices integrity and defective regulatory oversight abroad, to the focus of management in the fingers of a very small group of inexperienced, unsophisticated and perhaps compromised men and women, this condition is unprecedented.” (WSJ) 

There was no everyday reconciliation of crypto positions. A software package backdoor “conceal[ed] the misuse of purchaser funds”. Person keys and critically sensitive data were being sent all-around the team by an “unsecured group electronic mail account”. (Fiscal Situations)

Homes for staff had been purchased with firm resources, expenses had been approved with emojis, there wasn’t even a list of workforce and no just one genuinely realized who worked there. (Bloomberg) 

‘Essentially, in his individual terms, SBF’s internal compass right here put his tolerance for hazard on a provided guess at about 5 instances that which Kelly wager sizing would say so — an immense appetite for threat, and an immense urge for food for coinflips.‘ (JoeJedwards)

Sam Bankman Fried switched up his lawyer and now has a Stanford law professor fairly than your normal lawful kind. (Semafor) 

It’s not effortless losing your occupation in technologies now. “In excellent occasions, they probable thought they could depart a career, take a few months off, care for them selves, and nevertheless be snapped up in a day.” (Business enterprise Insider)

Elon Musk gave Twitter staff members right until 5pm yesterday to indicator a sort accepting that they would need to have to be “hardcore” and get the job done at “high intensity” about the subsequent couple of months, or take three months severance spend. Staff say it is unfair: “I shouldn’t have to selected in between my position and seeing my youngsters at evening and on weekends.”  (Bloomberg) 

Twitter staff have been stressing that Musk is monitoring how extended it can take them to simply click. (Platformer)

Evercore hired Richard Hoyle from Lazard to deal with TMT in London. (Bloomberg) 

British isles fiscal solutions employment are reduced than they must be. There would be about 91,000 much more work experienced growth in monetary expert services work retained tempo with the relaxation of the British isles economy considering that the Brexit referendum. (Monetary Moments) 

Angelo Scasserra, Credit rating Suisse’s co-head of banking in Australia resigned. (Bloomberg) 

Robots with Liquid crystal display eyes are becoming used to produce espresso, meals and offers to overwrought personnel in busy places of work in Korea. (New York Periods) 

Anyone purchased Steve Jobs’ outdated Birkenstocks for $220k. “He was basically confident of the intelligence and practicality of the design and the convenience of wearing it. And in Birkenstocks he did not feel like a businessman, so he had the freedom to think creatively.” (Bloomberg) 

Image credit history: eFinancialCareers/Dall-e


Click on here to make a profile on eFinancialCareers. Make yourself obvious to recruiters choosing for best jobs in technology and finance. 

Have a private tale, idea, or comment you’d like to share? Get in touch with: sbutcher@efinancialcareers.com in the to start with occasion. Whatsapp/Sign/Telegram also available (Telegram: @SarahButcher)

Bear with us if you depart a comment at the bottom of this posting: all our remarks are moderated by human beings. From time to time these people may be asleep, or away from their desks, so it may well get a though for your comment to appear. Finally it will – unless of course it’s offensive or libelous (in which case it won’t.)

4 Concerning Personal Finance Charts

4 Concerning Personal Finance Charts

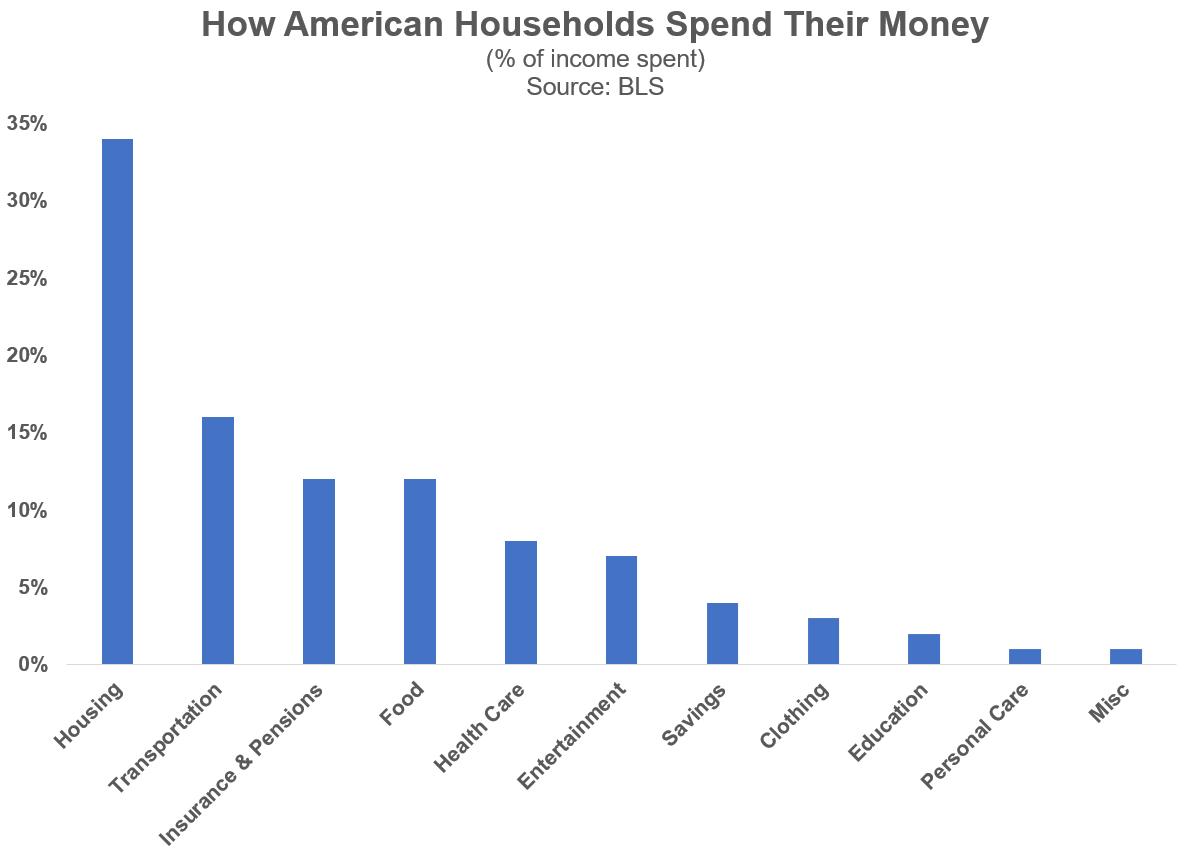
This is how Us residents shell out their funds1 (in accordance to a review by the Bureau of Labor Figures):

4 Concerning Personal Finance Charts

Like most aggregates when you are working with hundreds of millions of folks, everyone’s expending is in all probability relatively various than these averages.

But directionally these figures seem ideal to me from a big-picture standpoint. The two greatest line objects for the bulk of homes are housing and transportation.

These two categories make up fifty percent of the spending budget in the normal American family.

If you want to get in advance monetarily you have to rightsize housing and transportation. If you shell out way too much revenue on your dwelling situation or your car or both equally you’re heading to have a hard time creating wealth.

I never like to devote shame people today but I have been anxious for a range of many years now about how significantly folks are investing on trucks and SUVs.

It’s obtaining out of hand.

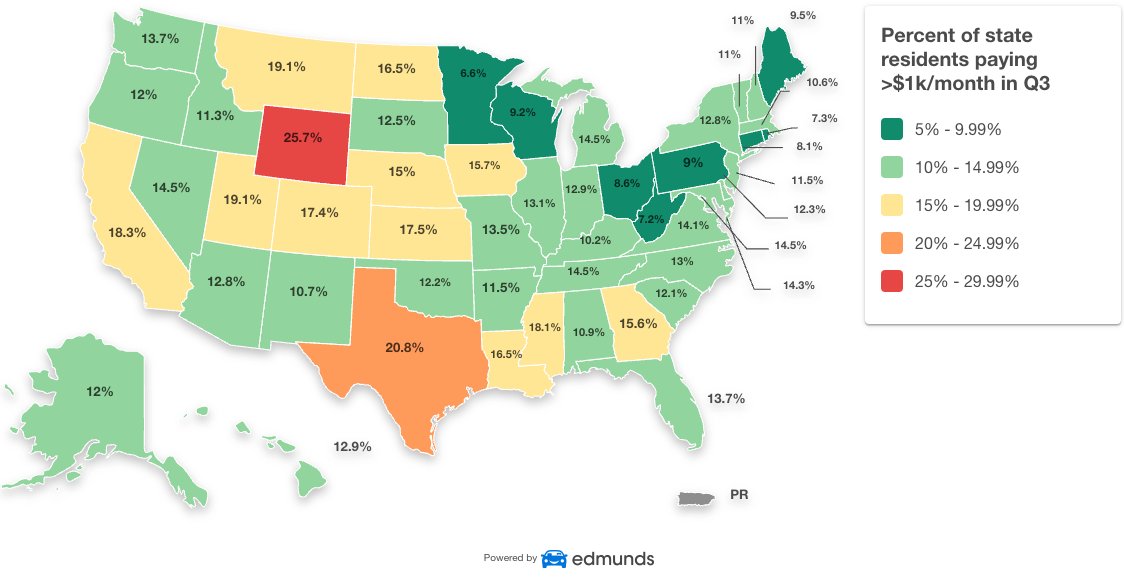
Glance at this chart that displays the percentage of residents by condition having to pay $1,000 a month or much more for their vehicle payment:

1-quarter of folks in Wyoming are paying more than $1,000/thirty day period! Much more than just one-fifth of people in Texas are doing the exact. It’s virtually 1 in 5 in California.

This is personalized finance insanity.

There are a variety of financial explanations these payments have been soaring in new many years. The source chain shortages have driven up the expense of cars and that’s nonetheless not back to usual.

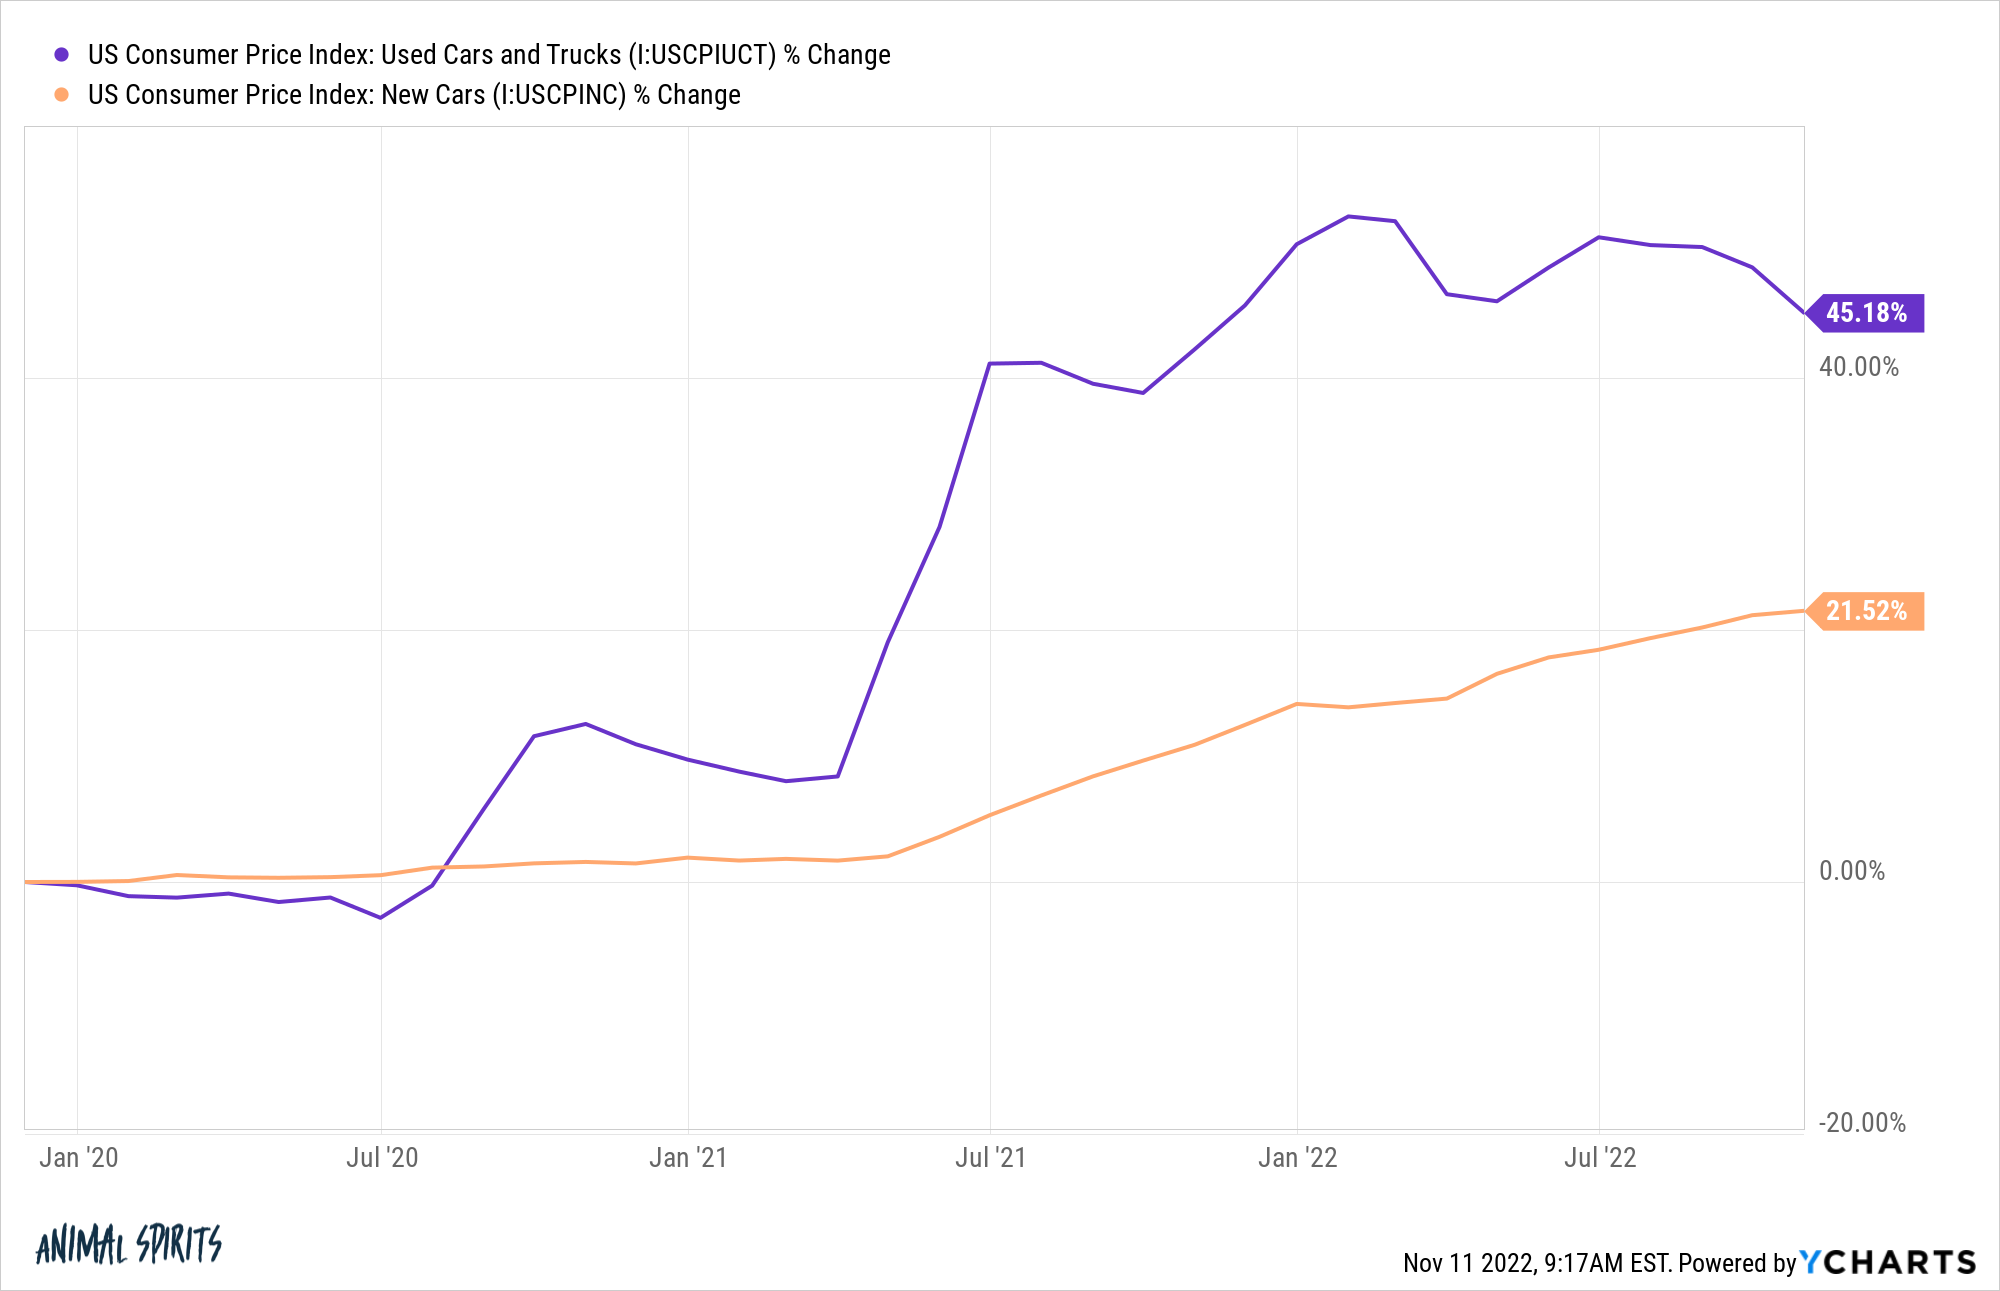
In the previous 3 yrs on your own the rate of new vehicles is up far more than 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Applied vehicle price ranges are up a lot more than 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}:

Anyone who has had the misfortune of needing to buy a automobile has been in a tricky location in the latest several years.

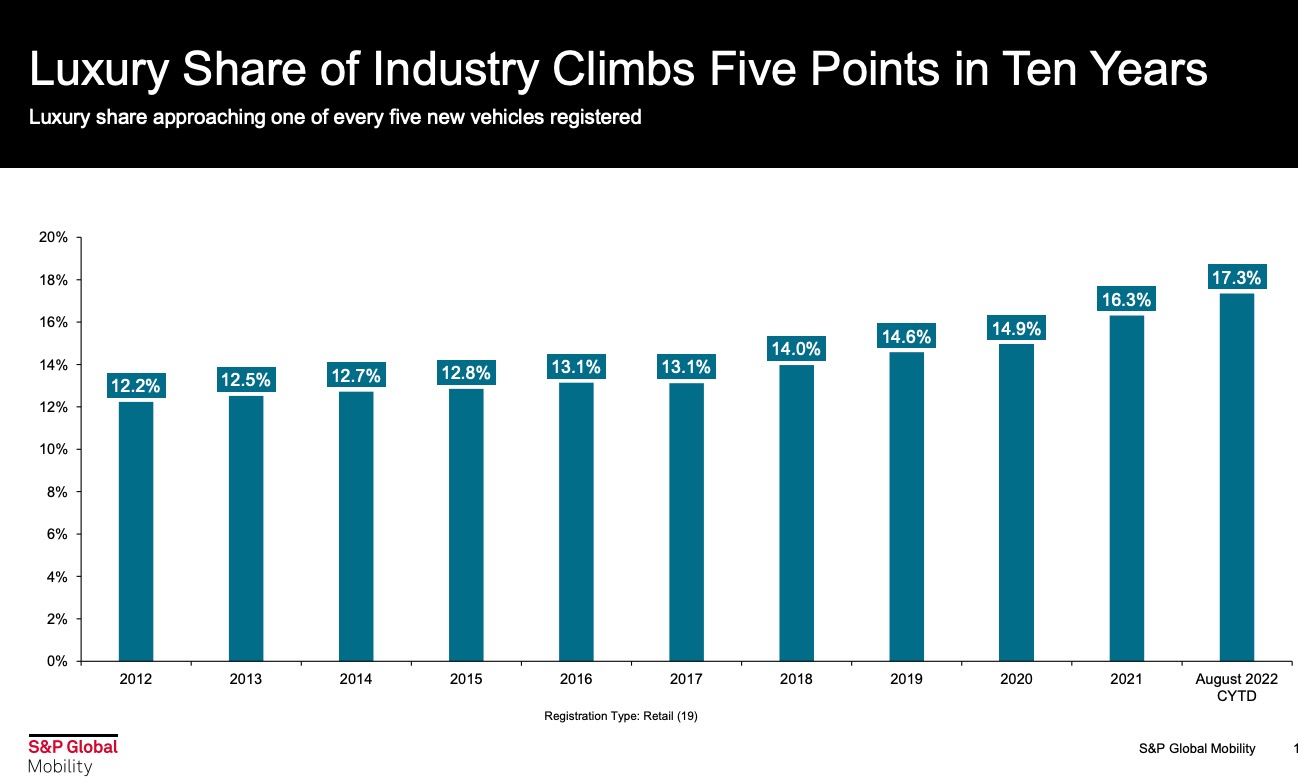
But that’s not the entire clarification. Appear at the increase  in luxurious automobile purchases more than the previous 10 yrs:

It’s almost 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

I am an A to B man when it will come to my vehicle. Some people take pleasure in driving a good vehicle, truck or SUV.

And that is high-quality — assuming you have the relaxation of your funds in order and you are saving dollars.

If you’re not preserving sufficient, your ridiculously high SUV or truck monthly payment is the most likely offender holding back your wealth.

And if it is not your vehicle alternative, it could be housing which is holding you again.

The New York Moments made the situation this 7 days that the housing marketplace is even worse than you feel.

I are likely to agree.

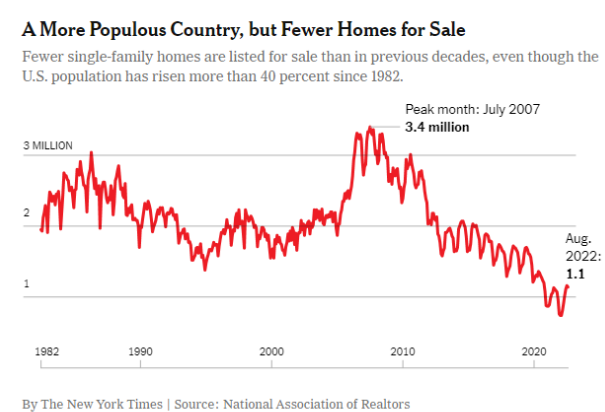
They demonstrate the selection of solitary-spouse and children properties for sale stays around its most affordable degree in 40 a long time:

But this chart is even worse than it appears. The Moments points out the U.S. inhabitants has risen far more than 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} considering that 1982.

There had been close to 230 million individuals in the United States in 1982. There are now additional than 330 million. The ratio for each human being is so much even worse now.

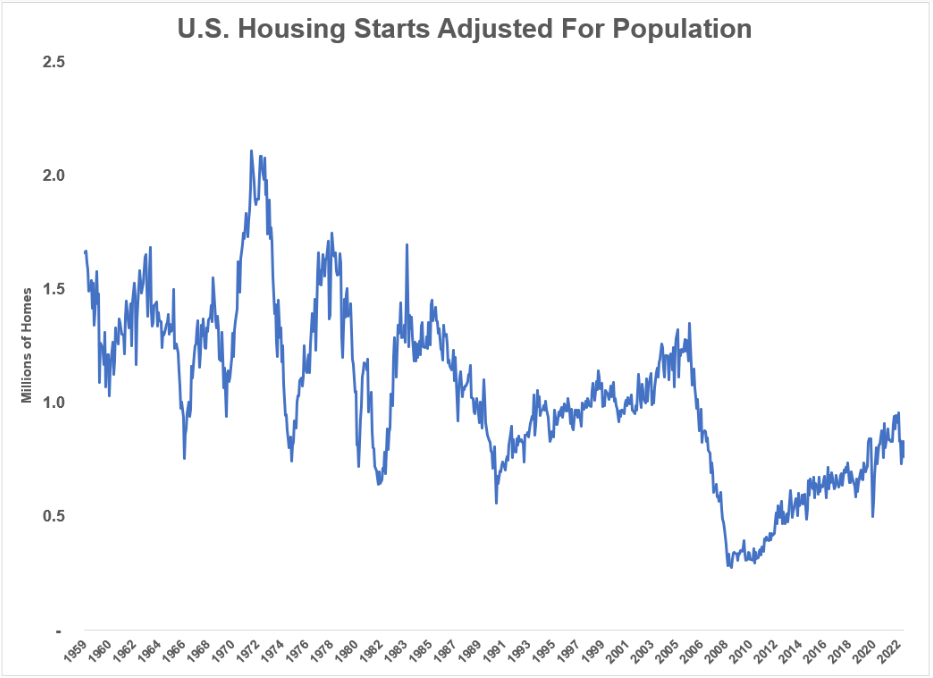
The identical is accurate when it arrives to the range of new homes becoming created. I altered U.S. housing starts (when construction starts on a new dwelling) for the population going again to 1959:

We have been making so a lot of more homes relative to the sizing of the inhabitants back again in the 60s, 70s and 80s. Matters have been quite very good in the 90s as nicely.

Then the serious estate bubble burst in the 2000s and we have not gotten anywhere shut to those degrees yet again.

In 1959 there were approximately 176 million men and women in the U.S. and we were being creating about 1.6 million homes a 12 months.

We now have 333 million men and women and the much more latest looking at reveals we developed 1.4 million houses in the past yr.

Sad to say, there is a great deal of luck involved when it will come to your housing circumstance. Sure, there are individuals who purchase a lot more household than they can pay for but a whole lot of persons get screwed or fortunate based mostly on the timing of when they ended up born and the place we are in the housing cycle.

Housing costs are now rolling over from bigger mortgage loan rates but these quite similar home loan charges have built it even extra highly-priced to obtain a home proper now.

Things will stage out finally and ideally mortgage prices will drop in the many years ahead.

But if we never make much more homes in this state, shopping for a household is going to be more durable and tougher for younger individuals in the long term.

Michael and I talked about car costs, the housing market place and a great deal much more on this week’s Animal Spirits video clip:

https://www.youtube.com/view?v=equIQLJdYH0

Subscribe to The Compound so you never overlook an episode.

Even further Examining:
Is the Ford F-150 Partially Liable For the Retirement Personal savings Disaster?

Now here’s what I have been looking through currently:

1This is as a share of income so following tax.

 &#13
&#13

Finance guru Dave Ramsey speaks at Grace Church

Finance guru Dave Ramsey speaks at Grace Church

A group of 3,500 people today attended an celebration headlined by national own finance temperament Dave Ramsey at Grace Church in Eden Prairie previously this month.

The Nov. 10 “Building Prosperity Live” presentation was the Higher Midwest cease on a tour of the function described on the Ramsey Alternatives web site as teaching “how to develop wealth – and continue to keep it.”

Ramsey’s keynote speech tackled that matter by citing The Nationwide Research of Millionaires. “Typical millionaires set cash in their 401(k) and paid out off their home,” Ramsey said. “It’s dull as crud.” 

Ramsey, a radio host and author, peppered his speech with particular stories, Bible verses, and a retelling of “The A few Tiny Pigs,” in which he when compared the Massive Poor Wolf to “COVID quarantine, midterm elections, inflation,” and a lot more.

Advertisement

Ad for Washburn-McReavy

He also tackled viewers anxieties about inflation fees achieving a 40-12 months high by acknowledging, “The lousy news is it is incredibly genuine. Points we obtain cost more. The selling price of labor has gone up.” Ramsey also predicted, nevertheless, that “in about 36 months, it will have leveled out.”

Ramsey termed the latest inflation a different form than that of earlier a long time, and he pointed to COVID-similar production shutdowns as the lead to. “This inflation was brought about by quarantine, mainly. As soon as items get again in the supply chain, it will level out. It has practically nothing to do with climbing curiosity fees,” he explained. 

Courses and guides by Dave Ramsey and other personalities involved with his organization had been readily available for sale in the Grace Church lobby during the Making Wealth Stay function. Image by Joanna Werch Can take

Psychological health, finance connections

Jesse Parker of Mitchell, South Dakota, explained he traveled to show up at the function to find inspiration in other followers of Ramsey and his staff. Parker, who very first commenced listening to Ramsey’s radio demonstrate to maintain himself awake on an right away travel residence from Michigan in 2016, frequented Ramsey Solutions’ Nashville headquarters before this 12 months to participate in a “debt-no cost scream.”

Attendee Annie Mattson of Chaska claimed of Ramsey’s conversations of personal debt payoff and examples of compound desire, “It’s things I experienced heard ahead of, but we need to have the reminders.”

Her spouse, Bob Mattson, described the couple as “big fans” of Ramsey and claimed they had formerly taken Financial Peace College (FPU), Ramsey Solutions’ 9-lesson training course on personal debt payoff and wealth accrual. In accordance to Ramsey’s statement from the phase based mostly on an audience show of arms, 30 to 40 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of occasion attendees experienced previously taken the course. 

The FPU study course was among lots of Ramsey Options guides and goods for sale in the foyer of Grace Church through the celebration, with quite a few personalities affiliated with the company on hand for e-book signings and photograph possibilities. 

Two of the Ramsey personalities, vocation mentor Ken Coleman and mental wellbeing pro Dr. John Delony, hosted a query-and-answer session prior to Ramsey’s keynote speech. The two also participated in a write-up-keynote panel dialogue together with Ramsey, budgeting qualified Rachel Cruze and Ramsey Demonstrate cohost George Kamel.

In each the panel dialogue and a different interview, Delony spoke about the inclusion of a mental wellbeing aim in a finance-focused team. The two he and Cruze proposed a romantic relationship between superior prices of credit rating card personal debt and large fees of melancholy and stress.

“The main tenets of psychological perfectly-becoming are protection, group, and autonomy,” Delony explained. He indicated that credit card debt owed to creditors impacts emotions of both autonomy and security in the mind. “If you owe somebody cash, you simply cannot depart your occupation. The amygdala knows Toyota Motor Company decides we go to do the job tomorrow,” he said.

“You will by no means heal from panic if you owe somebody income, because the entire body is aware you’re not safe and sound,” Delony explained.

&#13
Be Informed
&#13
Indication up for the Totally free e mail e-newsletter from EPLN&#13

&#13
Subscribe&#13

Opinions

Reviews are not permitted on our internet site, but we do provide numerous techniques to supply responses, and have your voice heard. If you believe that the tale has an mistake, or would like to get in contact with the author, make sure you speak to us. If you would like to answer right to this short article, we welcome and inspire Letters To the Editor. You can obtain information on how to submit a letter on our get hold of web site.