Citibank Partners Yahoo to Enhance Public Literacy on Personal Finance

Citibank Partners Yahoo to Enhance Public Literacy on Personal Finance
yahoo

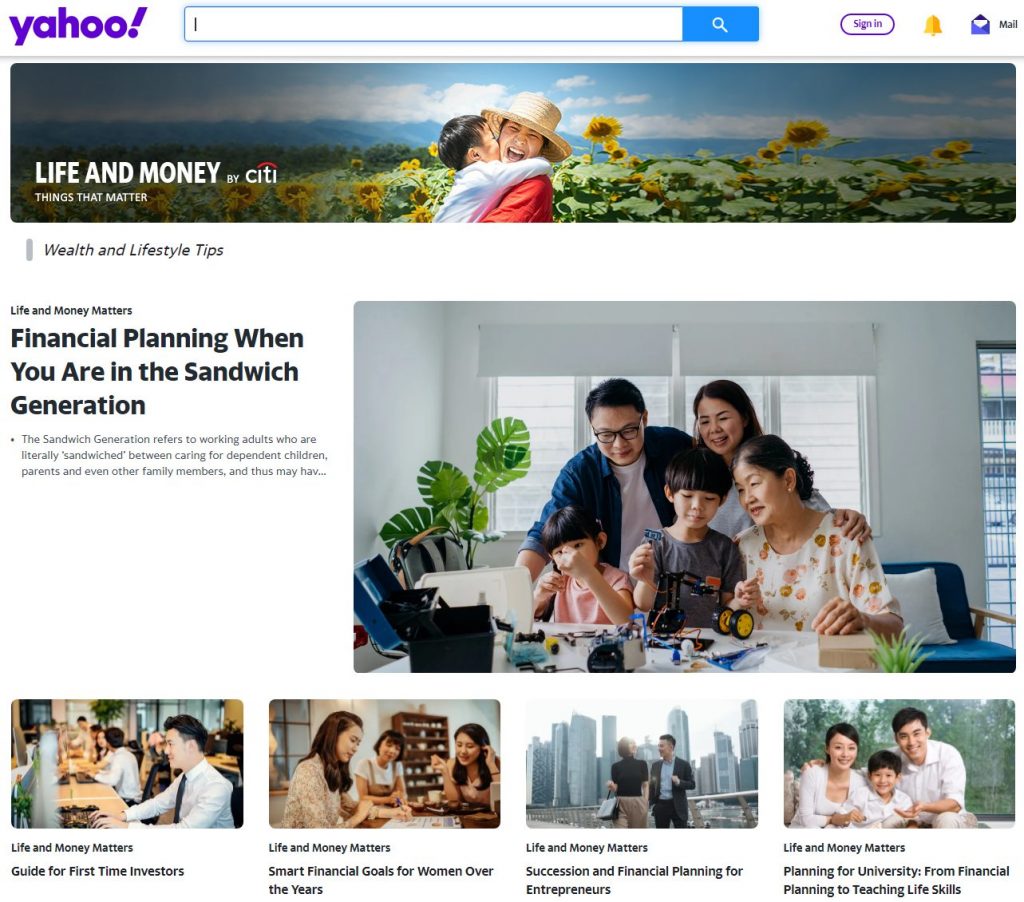
Yahoo and Citibank have teamed up to start Everyday living and Income, a devoted private finance hub geared in the direction of various audiences, providing refreshing perspectives on money, and equipping them for their economical journey across different everyday living phases. Hosted on Yahoo Finance in Singapore – the #1 source for enterprise and finance news in the state – Life and Income will see Citibank share specialist insights and suggestions on private finance with readers.

While financial literacy in Singapore is the greatest in Southeast Asia, swift modifications in the fiscal landscape, technological advances, as perfectly as switching life-style behaviors and lifetime expectancy keep on to gasoline developing fascination in particular finance as they develop their aspirations. While there is no lack of information and facts accessible online, Singaporeans are significantly discerning with their finances and on the lookout for sources and information they can have confidence in.    

Seeking to empower audience as they regulate their funds and assume about their potential, Daily life and Dollars will function a specially curated variety of original information contributed by and jointly with Citibank, as very well as pertinent aggregated material from Yahoo Finance. With insightful explainers accessible in several multimedia formats this kind of as content, films, and podcasts, the hub will include a extensive array of topics all over own finance and way of life. These involve conserving, investing, advancing careers, attaining operate-daily life harmony, sustainable residing, parenting, and other individual finance and life style pursuits. 

With a aim on enabling readers to live richly – economically, bodily, and emotionally – the written content will deal with misconceptions, encourage new lifestyle habits, and deliver actionable tips for viewers of different lifetime stages. Between them are first jobbers searching for economical independence, starter family members purchasing their aspiration residences, mid-vocation professionals progressing by means of milestones, and seasoned achievers organizing their suitable retirement.  

“As a foremost source for finance news, Yahoo is concentrated on giving information and info that will assistance give our visitors the self confidence to make intelligent economic conclusions. We are thrilled to associate with Citibank and establish empowering content on private finance, and enable drive meaningful connections with audiences trying to get rich insights that will help them reach monetary empowerment and lead their wanted lifestyles,” explained Carol Tay, senior director sales Southeast Asia, Yahoo.

“Our partnership will give viewers the chance to obtain Citibank’s hottest particular finance insights and tips, as very well as better provide our purchasers with an additional supply of trustworthy finance-related content material. We hope to offer a fresh and trustworthy economic point of view to those navigating life’s milestones, leveraging Yahoo’s strong editorial experience and sizeable organic and natural database,” mentioned Mylene Ong, head of digital product sales and marketing and advertising, Citibank Singapore.

Scottsdale man wants travel insurance to reimburse him $4,400

Scottsdale man wants travel insurance to reimburse him ,400

SCOTTSDALE, AZ (3Television set/CBS 5) – Bob Stamper is retired and utilizes his time to travel about the planet. “I’ve been to the Galapagos, Italy, Africa, Egypt and Israel. So, 5 of them,” Bob mentioned of the international locations he’s currently visited.

Bob’s most recent vacation was to Israel, a holiday that price tag a very penny. So, prior to leaving, Bob bought travel insurance policy as a result of a company termed Allianz to defend himself financially. “Does journey insurance policies give you a peace of thoughts?” On Your Side’s Gary Harper requested. “Yes, extremely a great deal so,” Stamper claimed. It’s a good point Bob had that journey insurance coverage. As demanded, Bob had to choose a COVID check prior to returning back to the States, and the news was not very good.

“I’m using the COVID examination in advance of we go to evening meal. And constructive!” Stamper mentioned. “They mentioned, ‘You’re not going dwelling. You’re not going to dinner. Go back to your room and remain for 5 times.’” That is what Bob did. He quarantined at his luxurious resort in Tel Aviv, which might not audio bad, but it cost this retiree hundreds of pounds out of pocket paying out for the lodge home and new airline tickets to come household.

“Who foots the bill when you’re quarantined?” Harper questioned. Stamper said, “You shell out for every little thing. But the insurance plan is meant reimburse you for anything at all thanks to the excursion being interrupted.” In all, Bob was out around $4,400, so he turned to his travel insurance enterprise, filled out the claim and furnished receipts asking Allianz to be reimbursed.

Approximately 3 months later and following many cellular phone calls and email messages to the firm, Stamper says he’s continue to waiting around to be reimbursed. “Well, one particular of my biggest issues with the organization, Allianz, you cannot talk to a human currently being who can give you any solutions.” Frustrated, Bob obtained a maintain of On Your Side and asked if I could assist get his money from Allianz.

“They’ll pay a ton much more focus to you than Bob Stamper merely sending them an e-mail.” And that’s exactly what happened. Following I attained out to Allianz and questioned them to assessment Bob’s paperwork, the insurance organization quickly settled the issue by indicating they are mailing Bob a check for $4,400.

Bob suggests he’s grateful to On Your Side for making it occur. He also states when it arrives to long run vacations, he might look at yet another journey insurance plan organization. “There’s other companies that provide vacation insurance that are aggressive with Allianz. So, that is not a problem.”

The insurance company never did say why they have been sitting down on this viewer’s paperwork for so very long. But the moment he receives that look at, I’ll permit you know in a observe up report.

Beaumont-Spectrum to cut 400 jobs amid ‘significant’ financial pressure

Beaumont-Spectrum to cut 400 jobs amid ‘significant’ financial pressure

This audio is auto-produced. Be sure to allow us know if you have responses.

Beaumont Wellbeing and Spectrum Overall health, now BHSH System, plan to lower 400 positions as the Michigan health and fitness procedure faces “significant economical pressures,” the program explained to Healthcare Dive.

The 400 work opportunities are management roles and do not consist of direct client-experiencing roles or wellness prepare member-experiencing roles, in accordance to a statement from the program. The cuts represent fewer than 1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the well being system’s workforce, which employs 64,000 people today. 

“Our wellbeing process, like other individuals all over the country, is facing considerable fiscal pressures from historic inflation, rising pharmaceutical and labor costs, COVID 19, expiration of CARES Act funding and reimbursement not proportional with bills,” the technique mentioned. 

Analysts have warned that the operating natural environment for nonprofit hospitals is deteriorating. Fitch Rankings revised the sector outlook from secure to damaging recently. 

Hospitals across the state proceed to deal with disruption to individual volumes although expenses keep on being elevated thanks to pricier labor among other expense things.  

BHSH’s economic outcomes for the initial 50 percent of the year fell shorter of the new system’s projections, in accordance to its consolidated outcomes. 

BHSH’s working cash flow, like condition and federal funding, was about $120 million for the very first fifty percent of the 12 months, falling short of its $156 million projection. The legacy Beaumont Overall health division posted an functioning loss of $96 million by way of June 30, even though Spectrum Wellbeing division posted working money of about $140 million, and exceeded previously projections. 

Detailed in its outcomes, the procedure mentioned “in purchase to get back again on track, leaders are centered on price tag containment initiatives as very well as size of stay, productivity, access, clinical trend management initiatives and acceleration of integration price savings.”

The procedure blamed the weaker economic benefits on lessen volumes and larger staffing prices in its treatment delivery divisions. Meanwhile, its overall health plan professional larger than usual medical and pharmacy trends.

Beaumont and Spectrum merged creating a combined procedure with $13 billion in once-a-year revenue and 22 hospitals flanking both sides of the point out of Michigan. The process also operates a wellness program that handles 1 million Michiganders.  

An economist studied popular finance tips. Some might be leading you astray : Planet Money : NPR

An economist studied popular finance tips. Some might be leading you astray : Planet Money : NPR

Individual finance smackdown

Pixabay


hide caption

toggle caption

Pixabay


Personal finance smackdown

Pixabay

Controlling your cash is clearly an significant part of remaining a liable adult. But how should really you do that? It turns out that there is a significant gulf amongst the information given by the authors of well-liked finance textbooks and academic economists.

In a new research titled “Well-known Private Fiscal Tips versus the Professors,” the Yale financial economist James Choi rummages by way of 50 of the most well-known textbooks on particular finance to see how their tips sq. with regular economic thinking. It is like a cage match: Finance thinkfluencers vs economists dueling in excess of what you ought to do with your income.

And, sure, Choi is an economist, but he may well be a more neutral referee of this smackdown than you’d think. That is since he’s a behavioral economist who will not swallow the canon of aged-university economics hook, line, and sinker. Classic financial designs portray individuals as hyper-rational, disciplined creatures, who constantly make optimum fiscal decisions for them selves. Behavioral economics, which has fairly much taken over the discipline, emphasizes that men and women are quirky, typically irrational, and susceptible to faults.

In a way, Choi says, behavioral economists like him try out to assistance people defeat their shortcomings and reach their money targets as if they have been the savvy creatures of outdated-school concept. And so, he says, classic economic idea could nonetheless offer a excellent over-all guidebook for how to improve your economical properly-currently being. But, Choi states, the information of well-known finance thinkfluencers, who are likely to concentrate on helping us get over our flaws and foibles, might basically be more successful in some scenarios.

So, who’s right in this monetary royal rumble? The authors of self-aid finance textbooks or the stalwarts of common economic principle? When Choi won’t generally offer definitive answers, this debate may possibly spark some suggestions on how you can much more correctly deal with your finances.

How Need to You Conserve Cash?

When it comes to saving money, quite a few economists supply relatively counterintuitive — and, dare I say, possibly irresponsible — information: if you happen to be younger and on a strong job track, you may possibly contemplate investing far more and saving less suitable now.

Which is mainly because you’re most likely going to receive a bigger paycheck when you are older, and to definitely squeeze the enjoyment out of lifestyle, it may well make feeling to live a little bit past your usually means at the moment and borrow from your long term, richer self. Economists connect with this “usage smoothing,” and it is really a attribute of standard financial styles of how rational men and women preserve and commit more than their life span. The strategy, Choi claims, is “you don’t want to be starving in just one period and overindulged in the upcoming. You want to easy that about time.” The sort of perfect state of affairs: you begin off adulthood saving very little or almost nothing or even using on financial debt, then you conserve a whole lot through your primary-age earning decades, and then you devote all those discounts when you retire.

“I convey to my MBA learners, ‘You of all folks should really feel the minimum sum of guilt of having credit rating card debt, since your earnings is rather low suitable now but it will be, predictably, quite superior in the really around long run,'” Choi suggests. As soon as they commence generating funds, he states, they should probably pay down that credit card debt rapidly due to the fact credit history card companies charge large fascination charges.

Looking through by well-known finance guides, on the other hand, Choi finds that the large the vast majority of well-liked authors provide guidance that contradicts this technique: in the course of your existence, the thinkfluencers say, your intention need to be to are living in just your means and help save a constant share of your income. It would not matter if you happen to be 20 or 30 or 50 they implore you to stash cash away immediately and spend it for your future.

In arguing this, the thinkfluencers frequently cite the energy of compound interest. The more time you preserve money, the more curiosity it accrues. As a end result, wealth snowballs in excess of time, so conserving a huge share earlier could make a ton of feeling.

Of training course, economists also figure out the energy of compound fascination. Exactly where thinkfluencers and aged-school economics actually depart from just about every other, Choi states, is “the usefulness of setting up preserving consistently as a willpower,” Choi says. This commitment, he states, “is nearly normally missing from economic types of ideal preserving — [and is] a likely vital oversight.” In other terms, some of us could possibly have to have to adopt challenging-and-quickly preserving rules at a younger age to create the self-control desired to guide more affluent life, even if which is much less than optimum from a regular financial viewpoint.

So who wins on this point? “I am in fact agnostic about it,” Choi states. “On the one particular hand, I do have a ton of sympathy for the perspective that you might be unnecessarily depriving you in your twenties and even thirties when, really predictably, your revenue will likely be substantially increased in later decades. That being reported, I do assume that there is one thing to this notion of currently being disciplined and understanding to reside in your indicates at a younger age.”

How Should You Consider About Your Price range?

In aged-university economics, funds is dollars. It really is fungible. There is no motive to put labels on it. Absent some economically advantageous purpose to do so (like the potential to get subsidies or a reduced tax fee), it will not make perception to established apart price savings for precise purposes, like a new car or truck or a future holiday vacation or a down payment on a property. A greenback is a dollar.

Of study course, several people today you should not believe this way. They often do what behavioral economists get in touch with “mental accounting,” earmarking particular revenue for this and that. “In much more severe versions of mental accounting, you can’t use the cash that you’re conserving for your Hawaii holiday for the down payment on your potential household,” Choi suggests.

Choi finds that 17 of the 50 textbooks he study by advocate for some type of psychological accounting training. And, he suggests, this information could possibly really make sense. It helps make financial calculations easier for people and may well encourage them to execute their targets.

Need to You Be “Dwelling Abundant, Dollars Bad”?

Quite a few Us residents are living in huge properties and are stretched skinny paying for them. When their home is a beneficial asset, and they are technically rather abundant, they are just squeaking by, living paycheck to paycheck. People today commonly refer to this as “property loaded, hard cash weak.”

Choi claims both equally popular fiscal advisers and most economists are very crystal clear: don’t do this! Do not acquire a property you are not able to truly find the money for. That can be super nerve-racking and perhaps ruinous.

How Considerably Of Your Revenue Should Be In Shares?

Choi says that common advisors and economists also typically concur that when you are younger, you need to commit most of your money in shares and only a little little bit in bonds. In addition, Choi says, each camps concur that as you get more mature, you should really get far more conservative, rebalancing your portfolio away from shares and extra toward bonds simply because shares are riskier than bonds. But, Choi states, even though both of those of these teams recommend people today to do the same factor with their investments around time, their reasoning for accomplishing so is quite diverse.

Usually speaking, well-known financial advisers say that, while stocks are dangerous in the limited run, you should really devote primarily in them when you are youthful for the reason that they gain larger returns than bonds around the long operate. “The well-liked belief is that the inventory industry is form of certain to go up if you just maintain on to it for long adequate,” Choi says. “Now, this is just not correct. And you can see this in Italy and Japan. In Japan, the inventory market place still has not recovered to the level it was again in 1989. So it truly is not accurate that stocks will usually gain about the extended run. Negative points can take place.”

But while well-liked authors may well discount this danger in excess of the long expression, their advice recognizes that keeping shares is risky in the brief phrase. Which is why they argue that, as you get closer to retirement, you should get out of shares and go into bonds, which are normally fewer risky. A preferred rule of thumb: 100 minus your age is the share of your portfolio that ought to be in shares. The remainder should be in bonds. So if you are 30, you need to be 70 per cent in stocks and 30 p.c in bonds.

Though economists concur that you must get a lot more conservative above time with your financial portfolio, Choi claims, their reasoning is extra nuanced.

“For nearly all doing the job people, the key financial asset they have is their future wage income,” Choi claims. In other words and phrases, think of your work competencies (your “human funds”) as element of your economical portfolio. It’s like the largest sort of prosperity you personal, and it can be usually safer than stocks or even bonds. When you happen to be young, this safer sort of wealth is a big portion of your portfolio, so you can balance it with risky stocks. Guaranteed the inventory marketplace could possibly crash, but you still have the security of getting capable to receive income at your career for a lot of extra a long time. As you get closer to retirement, this safer asset, your labor, represents a a great deal more compact portion of your portfolio — and that tends to make it a lot extra frightening to be all-in on dangerous stocks. “Which is why you should come to be much more conservative in your economical portfolio allocation around time,” Choi claims.

Ought to You Treatment No matter whether Stocks Fork out Dividends?

Choi claims there are some well known money publications that suggest people today to acquire shares that pay out dividends. For the uninitiated, dividends are checks that businesses mail to their shareholders generally each quarter. “There seems to be this fascination with making ‘income’ from your investments,” Choi states.

Economists, frequently talking, believe this is dumb. “If I want to devote some money from my prosperity, I do not need to have to wait for the firm to mail me a check out,” Choi says. “I can just provide some shares and use the proceeds from that sale to finance my expenditure wants. And so there ought to be no rationale why I desire shares that pay out dividends versus shares that will not fork out dividends. And in truth, dividends are tax-deprived. So, a inventory that pays dividends is heading to put a larger tax load on you, all else equivalent, than a inventory that doesn’t fork out dividends.”

Choi is with Workforce Economist on this 1.

Really should You Invest In International Inventory Markets?

Economic concept stresses the significance of diversifying your investments. This, Choi states, is true of diversifying the international locations you commit in, too. Theoretically, the more international locations you make investments in, the a lot less risky your financial commitment portfolio will be. Some international locations will do very well. Other folks will do improperly. “So economic theory would say you want a diversified portfolio that retains a bit of every single country’s stock sector in the earth,” Choi says.

But folks will not do this. They show what economists connect with “house bias.” The French are extra most likely to make investments in French firms. The Japanese are far more likely to invest in Japanese providers, and so on. This has extensive been a puzzle to economists. The answer may possibly lie in the pretty much common help for ‘investing at home’ among the thinkfluencers. “The placing thing about the preferred authors is that they all recommend home-biased portfolios,” Choi states. Choi just isn’t definitely positive whether or not this will make a lot feeling. “It just would seem to be a little bit of jingoism, the place folks just like the stocks that they are acquainted with.”

Should really You Make investments In Actively Managed Cash or Passive Index Resources?

Actively managed resources are those in which you shell out an expert to decide and choose shares for you. These fund managers demand big service fees with the promise of increased returns. Index funds have nobody actively finding and deciding upon investments for you. These resources simply just passively keep a little piece of every single big corporation in the inventory market, thereby earning the general typical current market return.

Economists and thinkfluencers concur on this a person, too. “Most people generally claims you should really go with index money,” Choi states. “The information are quite compelling. On average, passive funds outperform actively managed money.”

Choi’s Significant Takeaway

So who wins? The thinkfluencers or the economists? Economists, Choi implies, could know a ton about how people ought to act. But, as an empirically minded behavioral economist, Choi recognizes that men and women normally never act this way. And that is exactly where he has a degree of sympathy for the common authors. “Provided that we have all these quirks and frailties, we could have to vacation resort to approaches that are fewer than fantastic.”

“I assume of it in terms of diet regime,” Choi says. “The best diet regime is the one that you can adhere to. Financial concept might be saying you will need to be taking in skinless hen breasts and steamed vegetables for the relaxation of your daily life and nothing at all else. Which is likely to be the finest for your well being. And, truly, really couple folks will truly do that.”

He certainly has that right.

Nearly Half a Million High Schoolers will Receive Life-Changing Personal Finance Education Funded by a Grant from Michael Jordan and Jordan Brand and Implemented with Next Gen Personal Finance |

Nearly Half a Million High Schoolers will Receive Life-Changing Personal Finance Education Funded by a Grant from Michael Jordan and Jordan Brand and Implemented with Next Gen Personal Finance |

PALO ALTO, Calif., Sept. 14, 2022 /PRNewswire/ — An astounding 498,000 mostly Black and Hispanic students who go to 639 superior universities across the United States will have accessibility to a private finance class thanks to a 1-time grant to nonprofit Subsequent Gen Personalized Finance (NGPF) from Michael Jordan and Jordan Brand.

The grant is modeled immediately after NGPF’s Economic Fairness and Empowerment (Fee) Grant program, which began in 2020 as part of the organization’s determination to improve obtain to financial training in university districts serving greater part Black and Hispanic college students.

Via the Cost Grant system, NGPF partners with the largest U.S. general public college programs who share a determination to growing the money capacity of their pupils. Resources guidance a committed Individual Finance Expert, who will perform regionally to provide curriculum aid and skilled enhancement to academics in their district with ongoing help from NGPF.

Furthermore, the Jordan grant delivers for extras such as an enlargement of NGPF’s on line curriculum choices and the development of college student investment clubs coordinated by way of the private finance specialists in cooperation with lecturers.

Monetary Equity and Empowerment (Price) Grant recipients supported by the 2022 Jordan grant incorporate the Fund for Community Educational facilities, which supports New York Town Public Educational facilities Philadelphia Economic Scholars, which supports public substantial colleges in Philadelphia Charlotte-Mecklenburg Universities Fulton County Educational facilities (Atlanta, Ga.) Guilford County Schools (Greensboro, N.C.) and Detroit Public Educational facilities Neighborhood District.

These faculty programs were decided on not only simply because of their large selection of college students, but also for the reason that the share of Black and Hispanic students ranges from 56-95 per cent, furthering the affect of the grant.

“This grant has the chance to change the economical trajectory of traditionally excluded communities throughout the United States,” stated Tori Mansfield, NGPF’s Senior System Manager, who qualified prospects this grant initiative. “College students will graduate comprehension how to maintain good credit, spend in the stock industry, and put together fiscally for daily life right after large university.”

A review executed by Montana Point out University’s Dr. Carly Urban of practically 12,000 general public substantial faculties serving additional than 12 million superior schoolers demonstrates accessibility to fiscal schooling classes to be inequitable, specially for Black, Hispanic and low-profits students.

Excluding the eight states that have absolutely executed a 1 semester superior faculty personal finance training course ensure for all learners, she identified that just 1 in 9 college students in the rest of the nation will obtain money education prior to graduation.

Having said that, this quantity dips to a single in 20 college students in educational facilities with much more than 75 per cent of students qualified for free of charge or lessened-priced lunch or far more than 3-quarters Black and Hispanic scholar populations.

1 review from economist Daniel Mangrum observed that between 1st-era or reduced-income students who experienced taken these a class, loan compensation was bigger, which implies those students were much more possible to have completed faculty and found a bigger-shelling out occupation. A further research discovered following private finance education and learning is essential, credit rating scores go up and delinquency premiums go down.

“We are stunned by the generosity of Michael Jordan and the Jordan Brand name, which will enhance entry to this important class and create monetary capability for the future technology,” mentioned NGPF Co-Founder Tim Ranzetta.

This institutional grant to NGPF was designed via Michael Jordan and Jordan Brand’s 10-12 months, $100 million Black Neighborhood Commitment (BCC). Founded in 2020, this joint determination is intended to drive sustainable remedies and systemic adjust for Black communities by investments centered in financial justice, education, narrative adjust and social justice. The BCC’s institutional grantees are top the way to create a planet in which Black people can prosper.

About Upcoming Gen Personal Finance

Next Gen Private Finance is a nonprofit corporation with a mission to assurance that by 2030 ALL pupils will consider a just one semester personal finance course just before graduating significant school. To help that mission, NGPF gives center and superior school educators with everything they want to train economical capabilities with self-confidence, at no price tag. This is composed of completely ready-to-use financial literacy curricula—including particular finance, math, and economics collections with Spanish translations—as very well as absolutely free qualified improvement teaching. Understand additional at www.ngpf.org.

Media Speak to:

Tori Mansfield

Senior Method Supervisor

Following Gen Own Finance

Tori@ngpf.org

Cision Check out primary articles:https://www.prnewswire.com/information-releases/just about-50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}-a-million-higher-schoolers-will-obtain-everyday living-modifying-personal-finance-education-funded-by-a-grant-from-michael-jordan-and-jordan-brand-and-executed-with-following-gen-particular-finance-301623825.html

Source Following Gen Private Finance

Should you purchase travel insurance for your vacation rental?

Should you purchase travel insurance for your vacation rental?

Vacation rentals booked through Airbnb and its alternatives have become popular holiday destinations for all types of travelers, from extended families staying in large beachfront homes to couples vacationing in swanky city apartments.

But what happens if these rental properties, especially ones worth millions of dollars, get damaged before you arrive or if your plans unexpectedly change, causing you to need to cancel or shorten your stay?

While the exact outcome will depend on the situation, if you purchase travel insurance, you may find you’re eligible for compensation.

Sign up for our daily newsletter

So how do you know if it’s worth the investment before your next trip? TPG dug into the details to determine what standard travel insurance policies may cover you for when staying at home rentals — and when you may want to purchase some additional coverage.

For more TPG news and tips delivered each morning to your inbox, subscribe to our daily newsletter.

What travel insurance covers for vacation rentals

THOMAS BARWICK/GETTY IMAGES

Traditional travel insurance policies offer features that will cover you and your invested travel costs, whether you’re staying at a hotel, friend’s house or rental property. Although the exact benefits for vacation rentals may vary slightly depending on the policy you choose, there are a few situations that most will cover.

Your vacation is canceled due to sickness, injury or an emergency

Many hotels offer free cancellations until two or three days before arrival so long as you book your rooms with flexible rates. However, this is rarely the case for vacation rentals, which often have strict cancellation policies requiring 30 to 60 days of advance notice to cancel without penalty. Some even go so far as to have completely nonrefundable deposits, regardless of the cancellation circumstances.

Fortunately, there’s a workaround to this conundrum if you find yourself in an unexpected situation involving your health or the health of someone close to you: trip cancellation coverage. If you have insurance with trip cancellation coverage and cannot complete your trip as planned due to select health-related issues, you’ll be able to recoup up to 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your nonrefundable costs.

While the exact cases that are eligible for complete reimbursement vary by policy, know that many pertaining to health are covered. For example, World Nomads‘ trip cancellation insurance policy will cover you in the event you need to cancel your vacation, including any stays at home rentals, due to illness, injury or a death in the family.

You have to cut your vacation short due to a medical reason or natural disaster

In addition to helping you out when you need to cancel your entire vacation, insurance can reimburse you for early departure fees when you find yourself needing to cut your vacation rental stay short. Know, though, that you’ll need to have a policy offering trip interruption protection to be eligible for this perk.

Covered reasons for ending your stay early will vary from plan to plan, but typically, policyholders can expect reimbursement due to health-related issues and natural disasters like hurricanes, wildfires and blizzards. For instance, IMG’s travel insurance covers sickness, injury and natural disaster evacuations when cutting vacation rental stays short.

You cannot stay at the rental due to it being uninhabitable

If you book a vacation rental that is not fit for human habitation, then the booking company or owner should refund all your costs. However, there are rare occasions when this does not happen, so it’s important to have travel insurance as a backup.

To qualify for reimbursement from your travel insurance provider due to uninhabitable conditions, you’ll need to read the fine print of your chosen policy. Allianz, for example, defines uninhabitable as “a natural disaster, fire, flood, burglary or vandalism that has caused enough damage (including extended loss of power, gas or water) to make a reasonable person find their home or destination inaccessible or unfit for use.”

Other situations, such as having an unpleasant or dirty vacation rental, would not be enough to trigger this coverage.

Should you have to find another property or cancel your trip completely due to uninhabitable conditions at your original rental, your travel insurance plan will cover the added costs you incur.

Related: 13 mistakes to avoid on your next vacation home rental

What travel insurance won’t cover for vacation rentals

THOMAS BARWICK/GETTY IMAGES

As you may expect, there are some situations when travel insurance won’t cover extra expenses related to stays at rental properties. To have a solid understanding of what to expect, be sure to read the fine print of any insurance product you choose. Only circumstances listed in the policy will be covered. The following are two key reasons why you wouldn’t be covered.

You accidentally damage the property during a typical stay

Most travel insurance policies will not cover the costs of damage you incur at a rental property, even if it was done by accident. As a result, you must pay for a replacement or repair to any item you accidentally break or damage, such as a work of art, a garage door or wine glasses. Depending on the item in question, this can quickly add up.

If you have a homeowners or renters insurance policy, know that it may include protection beyond regular limits called “umbrella” coverage, which can help cover damage caused at a rental property. Keep in mind, though, that you’ll have to pay your deductible first. Additionally, your home insurance rate may rise if you submit a claim for vacation rental damage.

Should you wish to stick with travel insurance, you may be able to add extra vacation rental coverage to a traditional policy to assist with accidental damage. Faye’s travel insurance, for example, has an add-on feature that offers “coverage if you unintentionally damage the vacation rental property you’re staying in or its contents, while in-trip.” It costs about 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of what you’ll spend on the main policy itself.

You damage the property while hosting a party

Across the board, travel insurance policies are much more strict about damage caused during parties. If you host an unapproved party or event at a rental property and damage any part of the rental, you will be responsible for covering costs associated with repairs and replacements.

Even approved events are not entirely off the hook for any damage caused to the property. Should you decide to use a vacation rental for an approved event like a wedding or family reunion, expect the booking company or owner to require you to purchase an event-specific insurance policy that covers guest liability, home damage and other items that may be specific to the location.

Related: 6 truths and myths about ‘cancel for any reason’ travel insurance

Bottom line

Home rentals can be a great lodging solution when you’re on vacation, especially if you’re traveling with family or friends. However, the high cost of some vacation properties and the cancellation policies often in place mean you should probably purchase some kind of travel insurance to protect your investment.

Typical travel insurance policies will offer coverage for your vacation rental costs should your trip be canceled or delayed for events covered under the policy, but you may be on the hook for other scenarios. As a result, it’s vital you pay careful attention to your policy’s terms. Doing so will ensure you know what to expect should you face an unexpected situation while enjoying your temporary home away from home.

Related: 7 things to look out for when buying travel insurance, according to an expert