

Campaign finance complaint filed against El Paso County GOP | Local News

Campaign finance complaint filed against El Paso County GOP | Local News


Feature1-1.jpg

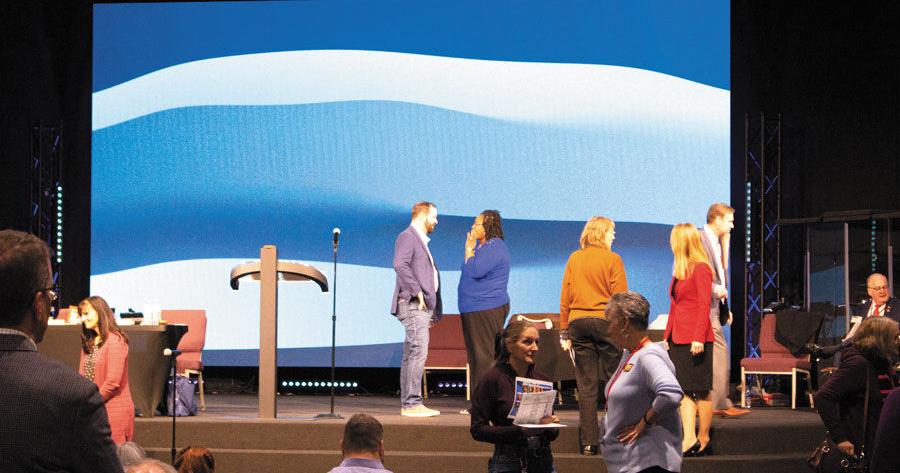
Joe Oltmann and Vickie Tonkins (center) confer during the February El Paso County GOP Central Committee meeting.


The vice chairman of the El Paso County GOP, Karl Schneider, filed a campaign finance complaint form with the Colorado Secretary of State’s Office today, according to documents available on TRACER, a campaign finance disclosure website.

Schneider’s complaint involves donations from the El Paso County GOP’s Aug. 6 Lincoln Day Dinner, which featured Georgia Rep. Marjorie Taylor Greene. According to Schneider’s complaint, “Donations to the Party for the Lincoln Day Dinner were not found,” he wrote. “The [Treasurer] later resigned in part, due to the fact he requested, as did I on 8 October 2021, that we hire an outside accountant and conduct a full audit to help sort this matter out. The Chair [Vickie Tonkins] has refused to provide this support and refused to communicate with myself on the matter and other members of the Executive Committee of the El Paso County GOP which has a fiduciary responsibility w/regard to all financial matters. I am very concerned that the Party has violated and is violating the Fair Campaign Practices Act and, given our current bylaws structure, we are unable to compel compliance of the Act by our Chair. It is the intent of this complaint to report suspected campaign finance law violations and ultimately achieve transparency in our Party financial dealings by requesting the Secretary of the State of Colorado investigate these allegations of campaign finance law violations.”

Attached to the complaint was an Oct. 1 email from former El Paso County GOP Treasurer John Pitchford to the executive committee — Schneider, Chairwoman Vickie Tonkins, Secretary Sheryl Glasgow and Colorado Republican Committee Chairwoman Kristi Burton Brown — bringing attention to the discrepancies. “We need a full inventory of all Lincoln [Day] items sold and unsold,” wrote Pitchford. “I am unable to do any further Tracer reporting until we have accurate records from Aug 6. Jeanine Nelms was the winning bidder for two items. I wanted to get her address so I could enter her data into Tracer. She told me she came to the office to pay for her coffee – NO coffee. She wanted to pay for her necklace – NO necklace. I suggest we hire an accountant to figure this out.”

Also included was an Oct. 8 email between Schneider and Mary Elizabeth Fabian, who ran for the District 5 City Council seat in 2021. Schneider wrote, “Please reach out to John [Pitchford]. I recall he suggested an outside consultant/accountant be hired to help him clear up donation accountability problems as of a week ago. I think there were at least two items, possibly very high dollar value (jewelry), missing and some tracer challenges. There may be other issues but not sure. I do agree with our Treasurer that if he needs additional resources, he should get it.”


Schneider’s Nov. 23 campaign finance complaint.


Schneider also addressed Tonkins, who was copied on the Fabian exchange, requesting an audit be conducted for all tickets and items related to the Lincoln Day Dinner; that a police report be filed if the missing items were over $50 in value; and a Special Executive Committee session be called to address the issues.

An undated message from the El Paso County GOP Executive Committee to Brown was also included in the complaint. Burton Brown wrote, “On Oct. 12, Dr. John Pitchford resigned from his position as Treasurer of the El Paso County Republican Central Committee…. He did this when his request to hire an accountant to investigate discrepancies with the Lincoln Day Dinner was denied by the County Party Chairwoman, Vickie Tonkins…. His resignation was to become effective on October 21 so that he could stay on to train a replacement. Ms. Tonkins informed him she was not giving him the training time that he requested. To her, his resignation was effective immediately and he was to turn in the books and any party related items in his possession…. Based on John Pitchford’s concern, Vice Chair Karl Schneider, also requested a full audit from Ms. Tonkins…. To date, she has refused to respond to his request. Our county bylaws are clear, the Executive Committee has a fiduciary responsibility for the finances of the Central Committee. As such, we, members of the Executive Committee, are concerned there could be discrepancies in the Lincoln Day Dinner records/accounts. We know this was a very successful dinner. It was attended by over 400 people with many auction items, and allegedly grossed approximately $50,000. All receipts should be properly accounted for.”

Tonkins did not immediately respond to the Indy‘s request for comment. Schneider’s complaint is not the first accusation of discrepancies in regards to the El Paso County GOP’s finances. According to a Sept. 4 email sent by Pitchford to members of the Fountain City Council, obtained via a Colorado Open Records Act request, Pitchford accused newly elected Fountain Mayor Sharon Thompson and Colorado Rep. Mary Bradfield (R-HD21) of filing a false report. “In 2019 I became treasurer of the El Paso County GOP and in that capacity, I reviewed our Tracer reports and found one of them to be in my opinion fraudulent,” wrote Pitchford. “I’ve attached this report and it will allow you to do the math so that you can determine for yourself that this particular report is fraudulent on its face. Our CPA put it this way, ‘it just doesn’t add up.’ I began asking questions as to why this report was falsified and who had knowledge of it. I wanted to know why no effort was made to determine why this report was in error by nearly $44,000 and why no efforts were made to correct it before filing it with the Secretary of State. Sharon Thompson had knowledge of this document and assisted state representative Mary Bradfield in preparing it.”


A TRACER report filed by Bradfield that Pitchford claimed was fraudulent.


Thompson, who served as the Republican House District 21 chairwoman since 2012, denied involvement with the TRACER report in question. “I had nothing to do with the books,” she said in a Sept. 12 phone interview. “I’ve never prepared a TRACER Report.”

Bradfield confirmed that Thompson was not involved in the filing of the report, and said the report in question was the result of an adjustment made with the knowledge of the Secretary of State’s Office. “After collaboration with the Secretary of State Tracer Division, a one time adjustment was made in the EPC GOP Tracer account,” she said in an email.

Samsung Plans $17 Billion Texas Chip Plant, Creating 2,000 Jobs

Samsung Plans  Billion Texas Chip Plant, Creating 2,000 Jobs

(Bloomberg) — Samsung Electronics Co. outlined plans for a $17 billion U.S. semiconductor plant that will add more than 2,000 jobs, widen the South Korean giant’s foothold in Texas, and bolster its role as a vital supplier in the global manufacturing supply chain.

Most Read from Bloomberg

“Increasing domestic production of semiconductor chips is critical for our national and economic security,” U.S. Commerce Secretary Gina Raimondo said in a statement Tuesday lauding the deal. White House officials also said they welcomed the investment, saying in a statement that it would help “protect our supply chains” and boost domestic manufacturing.

The project will create more than 2,000 jobs, Texas Governor Greg Abbott said at a press conference announcing the plans. Samsung also said that the plant would indirectly create thousands of additional jobs once it was operational. “The implications of this facility extend far beyond the boundaries of Texas,” Abbott said. “It’s going to impact the entire world.”

Korea’s largest company will build the facility in Taylor, Texas, about 30 miles from Austin, where Samsung has invested billions in a sprawling complex that already houses more than 3,000 employees and fabricates some of the country’s most sophisticated chips. Construction on the new plant is slated to start in the first half of 2022, and production will begin in the second half of 2024.

On Tuesday, Abbott touted Texas’s low taxes and talent pool as major draws for tech companies, and called Samsung’s decision to invest in the state “a testament to the economic environment that we have built.” Samsung could also receive $3 billion in incentives from the $52 billion bill known as the CHIPS Act if it passes, Texas Senator John Cornyn said Tuesday.

Samsung executive Kinam Kim said that the company’s decision to build in Texas was based on several factors including incentive programs, local talent and “infrastructure readiness and stability.” Infrastructure is particularly important for chip operations, which need a stable supply of power. Earlier this year a cold snap in Texas forced Samsung and other companies to pause operations. But Abbott has sought to reassure businesses that power outages won’t happen again, and that the state is now producing more power than it was earlier this year.

Samsung joins Taiwan Semiconductor Manufacturing Co. in making substantial investments in the U.S. The new facilities further the Biden administration’s goal of safeguarding the production of cutting-edge chips that are vital to defense as well as technologies like autonomous cars. It’s part of Washington’s broader effort to counter China’s rising economic power, as well as lure home some of the advanced manufacturing that in past decades has gravitated toward Asia.

A global shortage of chips this year has exposed imbalances in the industry and prompted governments from Brussels to Tokyo to court TSMC and Samsung — the two companies that make most of the world’s most advanced chips for clients like Apple Inc. and Nvidia Corp.

“Samsung’s new plant will help narrow the gap with TSMC’s production capability by making chips at the clients’ home,” said Kim Sunwoo, an analyst at Meritz Securities. “As the U.S. prioritizes domestic chip manufacturing, the company will be able to receive various benefits with its production base in the country.”

Neither the new Texas project nor TSMC’s $12 billion Arizona expansion are likely to alleviate chip shortages immediately. But their construction could lay the groundwork for a future American-centered chip ecosystem by attracting and training the component suppliers that typically spring up around such operations.

In June, President Joe Biden laid out a sweeping effort to secure critical supply chains. His administration has repeatedly voiced the need to increase semiconductor production in the U.S., saying that was the best way to compete with China and mitigate disruptions like those stemming from Covid-19.

Samsung spent months reviewing different sites and incentive packages before landing on Taylor. Samsung’s de facto leader, Jay Y. Lee, who walked free just months ago after serving time for corruption, green-lit the project after a recent trip in the U.S. where he met with prospective clients and partners from Alphabet Inc.’s Sundar Pichai to Amazon.com Inc. and Microsoft Corp.

The local government pulled out the stops, including waiving 90{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of property taxes for a decade, and 85{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for the following 10 years. The project could potentially receive additional tax breaks because it’s in a federal opportunity zone, a program designed to spur investment in poor areas.

“Samsung is targeting American customers aggressively,” said Jeff Pu, an analyst with Haitong International Securities Group.

Read more: White House Spurns Intel Plan to Boost Chip Production in China

The World Is Short of Computer Chips. Here’s Why: QuickTake

(Adds White House statement and other details starting in the second paragraph.)

Most Read from Bloomberg Businessweek

©2021 Bloomberg L.P.

Rate relief for some in excess and surplus lines

Rate relief for some in excess and surplus lines

SAN DIEGO – Excess and surplus insurance buyers will see continued rate increases in 2022, after several years of rate hikes, but there will be some pricing relief as an influx of capacity in the market brings more competition.

Cyber liability and property catastrophe risks remain particularly challenging as insurers reduce limits, according to attendees at the Wholesale & Specialty Insurance Association’s Annual Marketplace in San Diego last week.

Uncertainty over Jan. 1, 2022, reinsurance treaty renewals, developing losses from Hurricane Ida, winter storm Uri and the Astroworld music festival tragedy — in addition to emerging risks from wildfire, ransomware losses and the Florida condominium market — are among factors contributing to the overall continued firming, executives said.

Loss cost trends from so-called social inflation and nuclear verdicts are also showing no signs of abating, as courts reopen out of the pandemic, while rising inflation is adding to insurer claims costs, they said.

Davis Moore, president of WSIA, and vice chairman with Amwins brokerage in Los Angeles, said the E&S market is growing and submissions are still increasing as the standard market continues to reevaluate its business and rates continue to firm across most lines.

“We continue to see markets right-size their capacity at a time when exposures are rising, which creates a little bit of a supply and demand challenge,” Mr. Moore said.

“The good news is we’re seeing new capacity enter the market to fill some of the voids that are being created when carriers reduce their capacity,” he said.

Surplus lines premium reported to U.S. surplus lines stamping and services offices totaled $24.04 billion in the first half of 2021, up 21.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from the year-earlier period, the Kansas City, Missouri-based WSIA said in July.

Alan Jay Kaufman, chairman, president and CEO of H.W. Kaufman Financial Group Inc. in Farmington Hills, Michigan, said ongoing losses from catastrophic events due to wind, water and wildfires will continue to drive property rate increases.

Insurers have “retrenched which means they’re holding back capacity or not using capacity to write business, which means the market gets harder,” Mr. Kaufman said.

“In the casualty area, rates also continue to go up because of jury verdicts. It’s a very difficult environment,” he said.

However, except in catastrophe areas, next year’s rate increases will not be “even close” to where they were last year due to the influx of capacity, he said.

Reduced limits, price variations

Years ago, a broker could put together a large tower, be it property or casualty, with just a handful of insurers, said Joel Cavaness, president of Rolling Meadows, Illinois-based Risk Placement Services Inc., a unit of Arthur J. Gallagher & Co.

“Today you’re piecing deals together with very small limits, stacking them on top of each other, which takes a lot of time. It also puts compression on pricing where people aren’t getting paid for the capacity they’re providing,” Mr. Cavaness said.

Pricing increases will continue, but not at the levels seen over the past couple of years, he said. Single-digit rate increases for better risks are in order, with some exceptions, he said.

Rate increases have decelerated, except in cyber liability due to rising attacks and in fiduciary liability because of excessive fees claims, said Christopher J. Cavallaro, executive chairman of Jericho, New York-based wholesaler ARC Excess & Surplus LLC. To some extent, coastal property rates have accelerated, too.

“It’s a mixed bag. Not everything is going in the same direction. Rates generally on a blended basis for insurers are going up 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} risk to risk,” Mr. Cavallaro said.

For E&S property underwriters, catastrophic property losses arising not just from hurricanes but from convective storms, wildfires and freezes are hitting hard.

It’s been a rough four years, said Ed Mazman, Boston-based executive vice president of the U.S. property unit of Ironshore Insurance Ltd., part of Liberty Mutual Insurance Co. “We’re getting compounded rate increases and still profitability is challenged because of all the different events,” Mr. Mazman said.

Property insurers are placing greater focus on limit size because “if you’re in the primary layers, you’re going to get hit by the smaller losses,” he said. Ironshore offers $5 million to $10 million in limits, sometimes higher, he said.

Health care, wildfire, SPACs, cyber, excess transportation, certain classes of real estate are among the most challenged areas, said James Drinkwater, Atlanta-based president of Amwins brokerage division.

“There is plenty of capacity out there, it’s just at a price,” Mr. Drinkwater said.

Insurers are putting out much smaller limits. “It used to be that layers of $25 million were the norm. Now it is $10 million and oftentimes you have to build a program with layers of $5 million today in certain more difficult classes,” he said.

Moderating rate increases

Casualty rates are still increasing, just not as steeply as they were in the first half of 2021 and in 2020, said Mike Brennan, CEO of CRC Group’s commercial solutions business, based in Chicago.

“We don’t see any carriers ready to come in and deploy big limits in casualty, especially on lead umbrellas; $15 million is still uncommon on specialty business, and $25 million is virtually non-existent,” he said.

Social inflation is real, and the reopening of the courts will continue to generate “significant verdicts,” Mr. Brennan said.

Excess general liability rate increases are still in the double-digit range, said Daniel Smyrl, executive vice president of underwriting at Admiral Insurance Group, a Berkley company, in Mount Laurel, New Jersey. “There’s a need for capacity and limits, so people are willing to pay for that on the excess liability side.”

Professional liability rate increases, depending on the area, are still close to double-digit, he said.

From the primary casualty standpoint, the market is still very firm, but not as firm as it was last year, said Rebecca Gitig, Los Angeles-based head of U.S. primary liability at Aspen Insurance Group.

“We’re seeing decelerating rate increases and expect it will remain firm moving forward into 2022 but just at a slower pace,” Ms. Gitig said.

It’s the same on the excess side, said William McElroy, New York-based portfolio director, casualty, at Aspen. “Our global casualty portfolio is up about 15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} over last year, which is much less so than was the case in 2020. That’s an indication of how underpriced some of the business was previously,” Mr. McElroy said.

Aspen writes $25 million in excess liability capacity but hasn’t been deploying it very often. “It’s more like $10 million max,” he said.

Capacity in the E&S excess casualty sector has reduced in the last few years, said Adrien Robinson, head of global specialty at Hartford Financial Services Group Inc. 

“We’ve always limited judiciously capacity grants and attachment. There is new opportunistic capital coming into the space that will bring additional capacity to the sector,” Mr. Robinson said.

Cyber remains an outlier

The cyber market is “extraordinarily hard,” and prices are going up anywhere from 60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, Mr. Cavallaro said.

Some insurers are trying to sublimit ransomware coverage, but there are other markets that aren’t sub-limiting it. “There are ways around that,” Mr. Cavallaro said.

Cyber is the fastest-growing line of insurance, and “for many insurers they are interested in the future and want to get market share first and understand it later,” said Rotem Iram, CEO and co-founder of cyber risk specialist At-Bay.

That has made volatility in cyber even bigger, Mr. Iram said. “Ransomware has increased significantly and changing rates in 2021 makes sense,” he said.

However, to an extent there’s been an overcorrection in the market to help cover for last year’s losses. “There’s an overcorrection compared to where the risk is. Most underwriters are going to have a strong performance,” Mr. Iram said.

Every primary insurer has reinsurance and it also plays a role in dictating pricing and terms, he said.


Government Seeks To Block Cryptocurrencies In New Bill, Petrol Diesel Prices Unchanged for 20th day in a row

Government Seeks To Block Cryptocurrencies In New Bill, Petrol Diesel Prices Unchanged for 20th day in a row

Government Seeks To Block Cryptocurrencies In New Bill, Petrol Diesel Prices Unchanged for 20th day in a row

Business news of the day: Fuel prices were kept unchanged for 20th day in a row.

The government is likely to bring a bill in the winter session of the parliament, that will begin on November 29, 2021, to bar all cryptocurrencies in India, barring a few exceptions, and create a framework to regulate digital currency issued by the Reserve Bank of India (RBI). In response, all major digital currencies saw a fall of around 15 per cent and more, with Bitcoin down by around 18.53 per cent, Ethereum fell by 15.58 per cent, and Tether down by 18.29 per cent. In other news, petrol and diesel prices were kept unchanged for the 20th consecutive day on Wednesday.

Here are the trending business news stories:

Market Update: Sensex, Nifty Flat; Reliance Infosys Fall, TCS, HDFC Bank Gain

The Indian equity benchmarks were trading on a flat note on Wednesday as gains in HDFC Bank, Tata Consultancy Services, Axis Bank and Larsen & Toubro were offset with losses in Reliance Industries, Infosys, HDFC, ICICI Bank and Hindustan Unilever. The Sensex traded in a band of around 300 points and Nifty 50 index touched an intraday high of 17,561 and low of 17,485 amid mixed global cues. Share markets were jittery in early Asia on Wednesday as trading was buffeted by a step-up in U.S. Treasury yields as well as volatile oil prices in the face of price-cooling moves by the United States and other nations.

MSCI’s broadest index of Asia-Pacific shares outside Japan slid 0.24 per cent, while Japan’s benchmark Nikkei stock price index fell 1.13 per cent, as it returned from holiday and caught up with global falls the day before.

After Paytm Tumble, These Are The Indian IPOs Under Investor Scrutiny

At least a dozen Indian companies working on initial public offerings are now under extra investor scrutiny following the disastrous debut of digital payments startup Paytm, the country’s biggest ever IPO. 

Government Seeks To Block Cryptocurrencies In New Bill To Be Presented In Winter Session

Good Morning! Welcome To NDTV’s Business News LIVE Blog. The Cryptocurrency and Regulation of Official Digital Currency Bill, 2021, is listed for introduction in the Lok Sabha during the winter session, scheduled to start from November 29. The Bill seeks to “create a facilitative framework for the creation of the official digital currency to be issued by the RBI. It also seeks to prohibit all private cryptocurrencies in India, however, it allows for certain exceptions to promote the underlying technology of cryptocurrency and its uses.

Five Personal Finance Thumb Rules To Follow

Five Personal Finance Thumb Rules To Follow

Following certain thumb rules can sort out your finances broadly. Thumb rules may not always give you an accurate picture but can steer you in the right direction as they are usually time-tested processes. They are something that are easily learnt, remembered, and applied.

“Thumb rules help in streamlining our finances. Basically, when we form a rule and follow a time-tested process, our probability to reach financial freedom increases,” says Anant Ladha, founder, Invest Aaj For Kal, a financial planning firm.

Here are five popular personal finance thumb rules that you can follow to sort out your money life. However, ensure they suit your personal circumstances instead of following them blindly.

 1. Maintain an emergency fund equivalent to 6 months of your salary: You know how important it is to create an emergency fund. It always comes to the rescue when you are in crisis. This should include regular expenses, EMIs, and your insurance premiums.

While six months is the general thumb rule, it differs from case to case. For instance, those with secure jobs can look at three months of emergency money, while the self-employed or those into freelance assignments, who face higher uncertainty, can keep aside expenses that can last up to a year.

2. Take a term insurance 10 times of your annual income: The purpose of a life insurance is to replace the income of the insured in case of his or her unfortunate demise. While there are ways to calculate your insurance requirements, the thumb rule is that you should buy life insurance that is equal to at least 10 times your annual income.

It is recommended that you buy a pure term plan as these plans offer a higher coverage at a lower premium.

 3. The rule of 100: This thumb rule suggests that the percentage of equity in your portfolio should be 100 minus your age. So, when you are 30, the equity portion of your portfolio should be 70 per cent. When you are 40, it should be 60 per cent and when you are 50, it should be 50 per cent, and so on. This thumb rule is based on the fact that equity investments deliver good returns over a longer time period as market volatilities even out. So at the start of your career, you should have a higher proportion in equity and reduce your equity exposure as you near retirement.

4. The 35 per cent rule: Some loans like home loans and educational loans are good loans. However, other debt like credit card dues may put a strain on your finances. As a thumb rule, EMI as a percentage of your income should not exceed 35-40 per cent. Anything above that might put a strain on your finances. In case you EMI is more than that, you should avoid taking any more loans.

5. The rule of 72: This thumb rule gives you an indication of how much time it will take you to double your money when you are investing in a certain instrument. It says 72 divided by the rate of return is the time taken for your money to double. So, if your rate of return is 8 per cent, your money will double in nine years and if it is 12 per cent, it will double in six years. Remember, it is important to earn a rate of return that beats inflation. Also, where you invest would depend on your risk appetite and the time to a certain goal.

Thumb rules are meant to act as broad guidelines and are not meant to be followed to the tee. “It is important to remember that everyone is unique. At times according to your financial situation some adjustments need to be made and it’s absolutely acceptable. At times, you may also deviate from the goal, and try to get back on track,” says Ladha.


Family relying on travel insurance hit by big medical bills

Family relying on travel insurance hit by big medical bills

Duy Hoa Tran, a retired Vietnamese schoolteacher, arrived in Los Angeles in February 2020 to visit his daughter and 2-month-old grandson. Two weeks later, the door closed behind him. To prevent the spread of COVID-19, Vietnam shut its borders. No commercial flights would be allowed into the country for the next 18 months.

Tran’s daughter, An Tran, who has a doctorate in business administration and teaches marketing at the University of La Verne, did what she thought was necessary to ensure medical coverage for her then-65-year-old father during the pandemic. But the only option for a visitor on a tourist visa was travel insurance. In early March 2020, An Tran found and purchased a policy, for about $350 a month, from a company called Seven Corners.

She might as well not have bothered.

The elder Tran had been staying at An’s home in Diamond Bar about a year when he told his daughter he was having trouble seeing out of his right eye. A visit to an ophthalmologist produced a solemn verdict: Tran had severe glaucoma and would quickly go blind unless he got surgery.

Seven Corners gave written preapproval for the procedures recommended by Dr. Brian Chen. To be safe, An Tran called the insurer “many times” to confirm it would cover the expense, but no one she spoke with would give her a definitive answer, she said. Chen, however, assured An that insurance companies typically covered the treatment, which was pretty routine.

On April 19, Tran underwent the first of three eye surgeries to resolve the glaucoma. The surgeries — the last was on July 19 — were successful. And then on Aug. 5, Seven Corners sent An Tran a denial of service letter.

The company’s policy excluded coverage for any “preexisting condition,” by which it meant any condition “whether or not previously manifested, symptomatic, known, diagnosed, treated or disclosed,” the letter said.

An Tran and her father were on the hook for nearly $38,000 in medical bills, although Seven Corners had preauthorized the surgery and she had paid around $6,000 for the insurance over the previous year and a half.

As for the bill, “my dad obviously can’t pay it,” Tran said. His $260 monthly pension from the Vietnamese government isn’t enough even for him to live on in Vietnam, she said.

The surgical procedures Duy Hoa Tran received are quite routine in the United States, said Dr. Davinder Grover, an ophthalmologist in the Dallas area and clinical spokesperson for the American Academy of Ophthalmology.

Medicare would generally pay about a quarter of the $37,896.83 that Tran was billed for the surgeries, Grover said. If Tran’s daughter had known beforehand that insurance wouldn’t cover the procedures, the physician’s practice might have been willing to charge something like $12,000, he said.

The policy An Tran purchased had no deductible and offered coverage of up to $100,000 in medical bills, including COVID-19 care. But travel insurance generally covers only emergency or urgent medical expenses, according to the California state insurance commission, which regulates policies in the state.

Megan Moncrief, chief marketing officer for Squaremouth, which aggregates various companies’ travel insurance plans — including some from Seven Corners — and offers them through its website, said the policy language was not unusual for travel insurance. She noted the policy’s stipulation that it covered some acute conditions only if the patient sought treatment within 24 hours of the initial symptoms.

Moncrief said the fact that Tran did not seek treatment immediately may be the reason his surgeries weren’t covered. (Seven Corners refused all comment on the case.) She acknowledged it was hardly surprising he hadn’t dashed to the doctor at the first sign of discomfort: “I don’t know that I would have done that either, if I just had blurry vision.”

As for Seven Corners’ refusal to pay despite precertification, this is not uncommon, she said. By precertifying, the insurer verifies that a procedure is a covered benefit, but doesn’t guarantee the insurer will cover it for that particular patient.

Travel insurance typically offers little protection for any health problem linked to a preexisting condition, regardless of whether that condition has ever been diagnosed, says Susan Yates, general manager in the U.S. for Falck Global Assistance, an international insurer.

“For visitors to the U.S., especially those who are not permanent residents or citizens, it can be difficult to obtain health insurance,” she said. The Affordable Care Act doesn’t cover tourists, though some resident noncitizens can buy coverage.

“It’s usually better for a visitor to buy travel insurance from their country of origin, but in some countries (Vietnam being one), the insurance market is not developed,” Yates wrote in an email.

Tran had tried unsuccessfully for months to fly home to his town near Ho Chi Minh City, where his wife lives with another grandchild. On 14 occasions, An bought him tickets on regular commercial flights that were subsequently canceled. He was also unable to get a seat on charter flights arranged by the Vietnamese government; those tickets generally were available only through third parties charging up to $10,000.

The eye surgeon, Chen, offered to discuss the case with KHN, but his medical group’s counsel said it had a policy against discussing insurance issues with reporters, even with the patient’s consent.

After KHN approached him to discuss the issue, Chen told An Tran that he was waiving his $8,144 fee for the surgeries. The Acuity Eye Group, where he practices, would not immediately confirm Chen’s offer, but told An Tran it was seeking approvals to waive his fee and all other charges as well.

On Sept. 15, Duy Hoa Tran finally managed to get on a charter flight back to Vietnam. He’s happy to be home, An Tran said.

Under California’s filial responsibility laws, she could be liable for his remaining bills.

KHN (Kaiser Health News) is one of the three major operating programs at KFF (Kaiser Family Foundation), an endowed nonprofit organization that provides information on national health issues.