6 Ways to Make Extra Money in Retirement

6 Ways to Make Extra Money in Retirement

More than 1 in 4 retirees say they’re spending more than they can afford, according to an October 2022 survey by the Employee Benefit Research Institute. With inflation at 7.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in November, it’s not surprising that savings aren’t going as far as they used to. But there are ways to bring in extra income without taking on a full-time job. 

Some part-time gigs — such as tutoring, pet sitting or helping with tax prep — allow retirees to work a few hours at a time, and the extra income can make a big difference. 

Here are some ideas to consider. 

People are also reading…

Pet sitting or dog walking

If you have a fenced-in yard and the ability to care for someone else’s furry family members, offering pet services can be lucrative and flexible. According to data analyzed by e-learning platform Preply, dog walking is the best-paid side hustle by average hourly wage. 

“Not to mention, having canine companionship offers many health benefits,” says consumer finance expert Andrea Woroch. “So pet sitting is a great way to get that without the high costs of owning your own dog.”

Teaching

One of the few perks of the pandemic is that online teaching and tutoring have flourished. You can set up shop on an online tutoring site like Preply or Wyzant, or an online teaching site such as Udemy. “Carve out a couple of hours on weeknights to tutor students online,” Woroch says. 

If you have the credentials, consider creating a college-level course that you could teach as an adjunct professor.

“I created and teach on veterans’ issues at the Sanford School of Public Policy at Duke University,” says Paul Dillon, owner of Dillon Consulting Services, which helps veterans who want to start a business. “Whenever the course is offered, I spend about five to 10 hours per week on work related to the course.” 

Consulting or freelancing

Retirees often have decades of valuable experience. Taking on project work can help you stay in the game on your own timeline. 

“Consulting is a great way to continue staying relevant in your field and offering your insights and advice without having to go back to the office full time,” says Jacques Famy Jr., a managing partner and chief marketing officer for merchant funding firm AdvancePoint Capital. “You can either offer the services through a firm or start your own side-hustle business.” 

Filling community needs

Depending on where you live, there may be ample opportunities to pick up side work with your town or city. Your local school may need occasional (or frequent — flu season!) substitute teachers, for instance. 

“Many K-12 schools can use the talents of retirees,” says Janet Heller, president of the Michigan College English Association. Heller points to the need for crossing guards, assistant coaches for athletic teams and recess supervisors, among other things. Contact your local school district to see what part-time spots may be available. 

Hosting guests

Do you have a lot of extra house, and do you live in an area that attracts visitors? 

“Rather than letting that freshly renovated basement or spare room go to waste, rent it out on Airbnb,” says Brian DeChesare, founder of Breaking Into Wall Street, a financial modeling training platform. “You get to set your ideal availability, so you’ll never be stuck with guests at inopportune times.”

One tip: If you winter (or summer) elsewhere, consider hiring a property manager to manage rentals of your space. 

Tax preparation or bookkeeping

Got tax prep skills? You can find work assisting with tax returns in the first few months of the year — then take the rest of the year off. This is a great opportunity for anyone with tax experience, but it’s also possible to take a tax prep course that will qualify you for spots at the big-box tax firms.

The same goes for bookkeeping if you have a finance or accounting background. You can put your previous financial skills to work on a freelance basis or take a bookkeeping skills course to qualify for project work.

“If you’re looking to do an additional job, building your skills — which might mean getting a certification or taking another course to help make yourself more competitive for a specific role — we certainly encourage our clients to look into doing that,” says Toni Frana, career services manager for FlexJobs. “For something that requires some knowledge of financial fields … you do need to have a little bit of experience in those areas.”

This article was written by NerdWallet and was originally published by The Associated Press.

Personal Finance: A look ahead to 2023

Personal Finance: A look ahead to 2023

Most forecasters would relatively overlook 2022. Almost never have so numerous prognosticators been so incorrect as they had been in handicapping the calendar year just finished, which must serve as yet another reminder not to depend far too closely on small-operate predictions in constructing extensive-phrase expense portfolios.

Even now, what entertaining would New Year’s be without having an intrepid preview of coming points of interest? With an considerable dose of humility, below goes.

— Inflation. With couple of exceptions, most economists missed this one particular. A surge in need blended with source chain disruptions caused inflation to warmth up in 2021, but most experts, such as the Federal Reserve, expected price tag disruptions to be “transitory.” As an alternative, 2022 proved to be even hotter. The Philadelphia Fed survey of Expert Forecasters predicted that CPI inflation would ordinary 2.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2022. The true variety is nearer to 7.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and its stubbornness necessary a drastic change in Fed coverage.

Count on inflation to decline through 2023 but not reach the Fed’s 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} target by year’s conclusion, ending up all around 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} by December. Though costs are moderating in durable items and strength, some factors of the CPI like rents, expert services and wages tend to be “sticky” and will just take lengthier to tame.

— Desire costs. At the time the Fed acknowledged the persistence of inflation, it acted aggressively, increasing benchmark fascination charges from .25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} involving March and December, the premier one-year proportion enhance on report. Also, the central financial institution has been allowing its massive stability sheet to shrink as bonds in its portfolio mature, further tightening financial circumstances.

Having said that, the work is not finish. Curiosity rates keep on being underneath the Fed’s chosen inflation measure, which implies that true rates are even now detrimental. Fees will have to rise above the inflation amount and stay bigger for a substantial interval, suggesting extra hikes in February and March, then keeping regular for the rest of the year. Even though markets have fallen sufferer to bouts of magical thinking, the Fed has continuously affirmed its resolve not to repeat the problems that led to the stagflation of the 1970s.

— Recession. Given the properly-documented stubbornness of inflation, the Fed’s steps are probable to guide the U.S. into a economic downturn by mid-2023. Apparently, if it takes place, it would be the most greatly expected downturn in heritage.

Odds are the economic downturn will be rather benign, as the problems are absent for a serious shock like the insolvency in the banking technique top to the 2006 monetary crisis. In reality, the recession could show so delicate that GDP stays flat or declines only somewhat for the total yr 2023 though unemployment rises to 4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}-5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. In the combination, households still have personal savings in the bank, but surging credit rating card balances and larger retail funding costs will retard client shelling out, which tends to make up two-thirds of the financial system.

— Inventory sector. Wall Street analysts choose not to discuss their 2022 market place anticipations, for excellent reason. Folks that forecast inventory costs play an essential function in society: earning weather conditions forecasters glimpse prescient. Goldman Sachs, for case in point, forecasted the S&P 500 to get 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} through 2022, a significantly cry from the double-digit losses finally sustained. In their defense, the foundation circumstance was for reduce interest premiums and transitory inflation that may well have supported additional robust returns but did not happen.

Predicting the degree of stock prices would be similarly futile in 2023, but we can take take note of some headwinds. Better curiosity prices and slowing demand from customers will pinch corporate earnings, estimates of which are arguably too optimistic now. This would increase downward strain on stocks into the new 12 months.

The far better news is that the stock market place normally bottoms ahead of the close of a recession and some of the most rapid gains take place when sentiment is most pessimistic. If certainly the economic climate is rising from economic downturn by 12 months finish, shares might have currently sniffed out the nascent recovery and begun pricing in far better development for 2024. The bottom line for buyers is that chance will be afoot.

— Bitcoin. Severely?

(Disclaimer: the previous should really not be considered as a suggestion to invest in or provide any stability. Seek the advice of your expenditure advisor ahead of investing in Dutch tulip bulbs, Cabbage Patch Dolls or cryptocurrency).

— Politics. Most likely the major hazard for the yr ahead is not inflation or the stock industry but Congress. When each houses passed an omnibus expending invoice very last 7 days steering clear of a authorities shutdown, some members are currently rehearing for the biennial Theater of the Absurd that includes the credit card debt ceiling. An archaic relic from WWI, Congress should periodically boost the statutory debt limit enabling the U.S. Treasury to elevate the income Congress has now used. Failing to do so would precipitate a catastrophic default, but in modern yrs some customers have leveraged this danger to extort attention to their possess priorities. These kinds of brinksmanship previously price tag the U.S. its the moment pristine AAA credit rating ranking. An additional episode could exacerbate a moderate economic downturn into a crash landing and possibly erode the preferential status of the greenback. This horror demonstrate is scheduled to open sometime around September. This is hoping it gets lousy assessments and closes early.

Some of these broad themes may well aid advise traders in rebalancing portfolios or underweighting sure sectors. But it bears repeating that although forecasts are a pleasurable New Year’s custom, they are often completely wrong, and the essential to lengthy-term investing accomplishment is retaining consistency and self-discipline in the deal with of uncertain periods.

Christopher A. Hopkins is a chartered financial analyst and co-founder of Apogee Prosperity Companions.

Why It Pays to Shop Right After the Holidays

Why It Pays to Shop Right After the Holidays
Two women browsing through clothes in a local shop.

Picture source: Getty Photos

It really is a tactic that could actually pay back off.


Crucial factors

  • Many individuals do a lot of shopping in December and reduce back again in January.
  • Loading up on items this thirty day period could operate to your benefit, although.
  • Some suppliers run income in January to unload excessive inventory left from the holidays.

If you put in much of December working to retailers and seeking Amazon for hrs to test gift goods off your record, then the final point you could want to do in January is store on the internet or established foot in a mall. And also, if you racked up a big credit card tab very last month, then you may possibly want to go quick on the purchasing front this thirty day period.

But if you have some fiscal wiggle place and you’re not absolutely struggling from retail fatigue, then it could pay out to do some buying in January. This is why.

It really is all about snagging deals

You’ll typically hear that the finest promotions to be located have a tendency to fall throughout the holiday seasons — particularly in the course of significant purchasing events like Black Friday and Cyber Monday. But which is not normally the situation.

You will usually locate that vendors will provide the deepest savings on products appropriate just after the vacations. The motive? They have extra inventory they’re hunting to unload.

When you feel about it, snagging good deals on goods actually boils down to provide and desire. During the holiday period, need tends to be potent simply because customers have presents they need to have to obtain. And also, numerous persons conclusion up with 12 months-close bonuses they’re eager to devote rather than help save. That, too, can direct to potent desire.

In the meantime, arrive January, the desire for items tends to wane. The holidays are around and many people, unfortunately, stop up starting off off the year with leftover holiday break financial debt. And that tends to make it a wonderful time to hit the retailers and load up on things you want or even want (assuming funds is just not an situation).

What products need to you shop for in January?

Dollars may be tighter than you would like it to be these times because of to variables like inflation and latest holiday break expenditures. If which is the situation, any buying you do in January need to be constrained to requires only.

Did your toaster oven die on you just lately? Which is a very good merchandise to replace this thirty day period, specifically if you can find a person at a lower price. Has your go-to pair of sneakers started off to display significant indicators of have on? You require excellent shoes to stay clear of injuries if you do a large amount of strolling and exercising, so now could be a wonderful time to switch them. But if you’re limited on funds, stick to objects that tumble into the needs category, and help you save your needs for a different time — even if it means forgoing some bargains.

On the other hand, if income is not an situation, then now’s a excellent time to scoop up some wishlist things you may not have ordered earlier. It could be that you bought a giant elevate to kick off 2023, which presents you a lot more choices for paying income. Or maybe you got a 12 months-finish reward final thirty day period that you didn’t dip into yet. In that case, you can have a small additional entertaining with your January procuring. Just do your most effective to continue to be out of financial debt.

All instructed, January can be a good time to purchase points at a discount. And as extensive as you store judiciously, you could land in a terrific posture to take pleasure in some major bargains.

Warn: best income back again card we’ve seen now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR right until 2024

If you are using the wrong credit or debit card, it could be costing you serious revenue. Our qualified enjoys this best choose, which features a 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2024, an crazy hard cash back rate of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all by some means for no yearly price. 

In simple fact, this card is so good that our professional even takes advantage of it individually. Click listed here to go through our whole evaluation for totally free and apply in just 2 minutes. 

Read our free evaluation

Six tips to cut your spending, bust your debt and increase your money in 2023

Six tips to cut your spending, bust your debt and increase your money in 2023

From inflation to superior interest rates and a attainable recession, this year is off to a rough commence for most Canadians, moneywise. But here’s a silver lining: The economical blahs may well give you a tiny more oomph to stick to your New Year’s resolutions in 2023.

Exorbitant costs make it simpler to tame any lingering purchasing impulses after the vacations. Large borrowing costs incorporate urgency to debt-busting targets. Financial uncertainty is a effective motivator for lastly attending to a dwindling wet day fund. And the topsy-turvy monetary current market of 2022, in which each stocks and bonds took a beating, is a excellent reminder of why it pays to be a disciplined investor.

Listed here are 6 techniques to harness the electrical power of financial doom and gloom to condition up your funds:

Use a glass bowl to lower meals waste

Immediately after residing with high foods inflation all through 2022, you have likely already picked up a couple of techniques to trim your grocery bill. If you have presently swapped clean veggies for the frozen type and canned beans for the dried assortment, particular finance expert Kerry Taylor indicates you shift your consideration to what ends up into your compost bin just about every 7 days.

Estimates of how considerably food waste prices the average Canadian residence array from all-around $1,300 to just about $1,800 a yr. To reduce down on what you throw away, think about positioning unused components and leftovers in a glass bowl in your refrigerator, Ms. Taylor explained.

The plan is to rescue uneaten foodstuff from the neglected corners of your fridge – the place it will likely rot absent – and convey it to the forefront, Ms. Taylor explained. “If you see it, you can not ignore it.”

Then, she recommends, decide on a working day of the week to use up what finished up in the bowl. Ms. Taylor’s method is motivated by a Canadian review conducted by behavioural researchers with buyer merchandise huge Unilever. The exploration uncovered that owning a specified “use-up” day, along with an straightforward way to combine leftovers, aided households lower waste by about a 3rd.

The report offers a basic theory for turning your edible odds and finishes into a meal: You will require a base, these kinds of as rice, pasta or bread a fruit or vegetable a protein, these as meat or eggs and a sauce or spices to tie it all collectively.

That is how Ms. Taylor will work her way via her bowl of leftovers. Wraps, stews, soups and stir fries are her family’s go-to recipes for making the most of scraps.

The rate of pasta is surging, but bargains could be upcoming

Feed your unexpected emergency fund even if you have to pause your retirement contributions

If your environmentally friendly bin desires a eating plan, your emergency fund may well need some bulking up.

For yrs, inexpensive borrowing produced it uncomplicated for Canadians to count on traces of credit history to deal with emergency fees. But with interest premiums now all-around 6 per cent on normal for household fairness lines of credit history and 9 for every cent for individual LOCs, that is grow to be a substantially much more expensive proposition.

It’s time to revert to just one of the essential tenets of particular finance, states monetary planner Robb Engen. In an crisis, funds trumps credit score. If your emergency fund is seeking thin, now is the time to feed it a continuous eating plan of money contributions, he claimed. The common rule for an enough wet working day reserve is to established aside in between a few and six months’ truly worth of residing charges.

It’s okay if you have to slow down or pause transfers to your expense accounts when you perform up to the prescribed emergency dollars threshold, mentioned Mr. Engen, creator of particular finance web site Boomer and Echo.

Increasing your dollars buffers could also provide to blunt the effects of any payment shocks that may perhaps be coming your way in 2023, these types of as a house loan renewal at a higher curiosity fee, he added.

How substantially money should really be in my emergency fund?

Acquire refurbished tech

Financial emergencies usually occur in two flavours: the ones where by your cash flow drops and the ones exactly where you operate into unanticipated charges. In the latter predicament, you might be equipped to help you save some revenue by shopping for refurbished products.

If you find on your own acquiring to change a laptop, Television set, vacuum cleaner and essential other residence gizmos, Ms. Taylor recommends checking choices to acquire deeply discounted restored tech.

Apple, Nintendo and Dyson are amongst the corporations that offer their own refurbished products, which are usually diligently inspected and repackaged shopper returns. Also, eBay Canada has a plan for renewed shopper electronics and small domestic appliances. The business suggests its “certified refurbished” label guarantees like-new conditions and buys arrive with a two-calendar year guarantee.

Attack your home loan – but also play defence

If you are a property owner and your rainy day fund is presently properly-stocked, you may well want to deal with your mortgage loan. Supplied the uncertainty of the recent financial outlook, Mr. Engen suggests a approach that allows you to simultaneously assault your major debt when at the similar time leaving the doorway open to a quick retreat if economic emergencies occur.

Rather of making a significant lump sum payment toward your property finance loan, Mr. Engen proposes opting for accelerated payments, which can be stopped at any time. Both equally a 1-off extra contribution to your house loan and dialling up the frequency of your installment payments will lower interest expenses and shorten your amortization. But Mr. Engen sees the to start with solution as riskier: After you’ve sunk a bigger total of dollars into a property finance loan prepayment, “you simply cannot get that back correct if anything goes awry.”

Where by could home loan fees – mounted and variable – head in 2023?

Say sure to GICs – in moderation

Certain investment certificates are a person of the handful of areas wherever bigger fascination prices have turned into a acquire for savers, with banks now presenting returns of 5 for each cent or a lot more on these very low-chance investments.

Placing some funds into GICs at these desirable costs can be a very good way for Canadians in or approaching retirement to crank out continual returns to address a number of years’ worth of around-term residing charges, Mr. Engen mentioned.

But GICs are no substitute for investing in a well-diversified portfolio of stocks and bonds, which has better envisioned for a longer time-expression returns, he warned. And for more youthful Canadians, these supersafe investments have restricted use, he additional. They’re considerably from perfect for an emergency fund, considering the fact that most have to have savers to lock in their cash for a time period of time. Also, you frequently just cannot incorporate contributions to an existing GIC.

Nonetheless, GICs can do the job perfectly for a shorter-phrase goal for which you have already squirrelled absent a important total of cash, these types of as conserving for a marriage ceremony that is still a lot of months absent.

Investing 101: A beginner’s information to increasing your money

Stop yo-yo investing

If you’ve been tempted to provide all your stocks and bonds all through the roller-coaster market of 2022, it might be a indication that you require to re-appraise your risk tolerance, Mr. Engen said.

Loading up on risky belongings this kind of as tech stocks and cryptocurrency when the market place is on an upswing, only to flee to the protection of investments such as GICs for the duration of a downturn, is what Mr. Engen calls yo-yo investing. This generally sales opportunities buyers to soar back into the sector only following some of the large gains in a market rebound have already happened, he included.

A superior tactic is to figure out how significantly industry volatility you can abdomen, create a diversified portfolio that matches your tolerance for chance and adhere with it, Mr. Engen explained.

It’s a lesson Mr. Engen uncovered firsthand as a novice trader almost 14 many years in the past. At the start off of 2009, on the heels of the economic marketplace crash of 2008, he invested a office reward in GICs as a substitute of the inventory current market. Twelve months later, equities had realized a 27-for every-cent obtain. In the meantime, Mr. Engen’s money was locked into GICs that yielded an regular annual return of significantly less than 6 for every cent about five a long time.

Are you a youthful Canadian with income on your thoughts? To set oneself up for success and steer very clear of high-priced mistakes, listen to our award-profitable Stress Examination podcast.

Why Ramit Sethi Said Costco Is ‘an Amazing Business’

Why Ramit Sethi Said Costco Is ‘an Amazing Business’
A man pushing a shopping cart through the aisles of a warehouse store.

Impression resource: Getty Illustrations or photos

A whole lot of men and women confident love it — together with one particular private finance expert.


Crucial points

  • Costco is identified for its dedication to affordable rates.
  • Joining Costco could be 1 of the savviest fiscal selections you make this year, mainly because a membership offers each benefit and great consumer support.

Costco is one of those retailers wherever you truly will not know what you happen to be missing right until you start browsing there. And you are not able to start out buying there until eventually you start spending for a membership.

The charge of a fundamental Costco membership proper now is $60. An upgraded govt membership will value you double, but you are going to also get 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} income again on all Costco purchases you make, form of like how you may possibly get 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} income again on a credit card. So if you store at Costco usually, an govt membership could make a ton of perception.

Now, if you might be new to Costco, you will possibly want to start off with a basic membership and see how it goes. And if you’ve been emotion iffy about becoming a member of Costco, I would completely really encourage you to spring for a membership, particularly if you have a warehouse club retailer near to your residence.

My spouse and children routinely saves a substantial amount of income by buying at Costco. But don’t just choose my term for it. Economical guru Ramit Sethi is a massive supporter of Costco, far too. He even went so much as to tweet about how it’s an amazing organization. And this is why that’s true.

It is all about price

The cause so many people appreciate Costco boils down to the discounts and shopper provider the warehouse club huge is regarded for. Not only does Costco make a place to provide competitive price ranges, but it also goes earlier mentioned and further than to assure that clients are glad with the things they’ve acquired. And if not, Costco has a pretty generous refund coverage.

Costco is so dedicated to giving personal savings that if it are unable to do so, it simply just will not put a supplied item on its shelves. Sethi quoted Jim Sinegal, Costco co-founder and former CEO, in his tweet as getting claimed, “We have to be able to exhibit a cost savings on every little thing we provide. If we are unable to demonstrate a savings we will never carry it.”

That is a fairly reliable approach to supplying value. Several vendors would have no qualms about stocking an item which is overpriced and building a income on it. But it can be clear that Costco won’t want to work that way.

In actuality, if you happen to be an avid Costco shopper and have at any time seen that some of the products and solutions you made use of to purchase there are no lengthier in inventory, a rise in expense could be the purpose why. Costco may well have pulled people objects to prevent a scenario in which you might be not getting excellent worth for your funds.

A wise financial go

When I very first joined Costco, I was skeptical about the price savings associated. But now that I’ve been a member for additional than a decade, I can say with certainty that buying at Costco assists me feed my household and keep my house for a lot less funds.

If you’re on the fence about becoming a member of Costco, it could shell out to spring for a membership, especially at a time when foodstuff expenses are up so considerably owing to inflation. You happen to be possible to uncover that your membership a lot more than pays for itself, and that browsing at Costco aids you stretch your money throughout these economically hoping periods.

Even if you’re not acquiring a challenging time monetarily, all people enjoys saving dollars. And Costco’s main enterprise design is designed to assist you do plenty of that.

Notify: maximum cash back again card we’ve observed now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until finally 2024

If you are applying the wrong credit score or debit card, it could be costing you really serious money. Our specialist loves this best choose, which features a 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2024, an crazy cash again rate of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all somehow for no annual fee. 

In fact, this card is so fantastic that our expert even takes advantage of it personally. Simply click listed here to examine our comprehensive evaluate for free and utilize in just 2 minutes. 

Read our free of charge evaluation

Teenager Promotes Financial Literacy in Youth with Personal Finance Education

Teenager Promotes Financial Literacy in Youth with Personal Finance Education
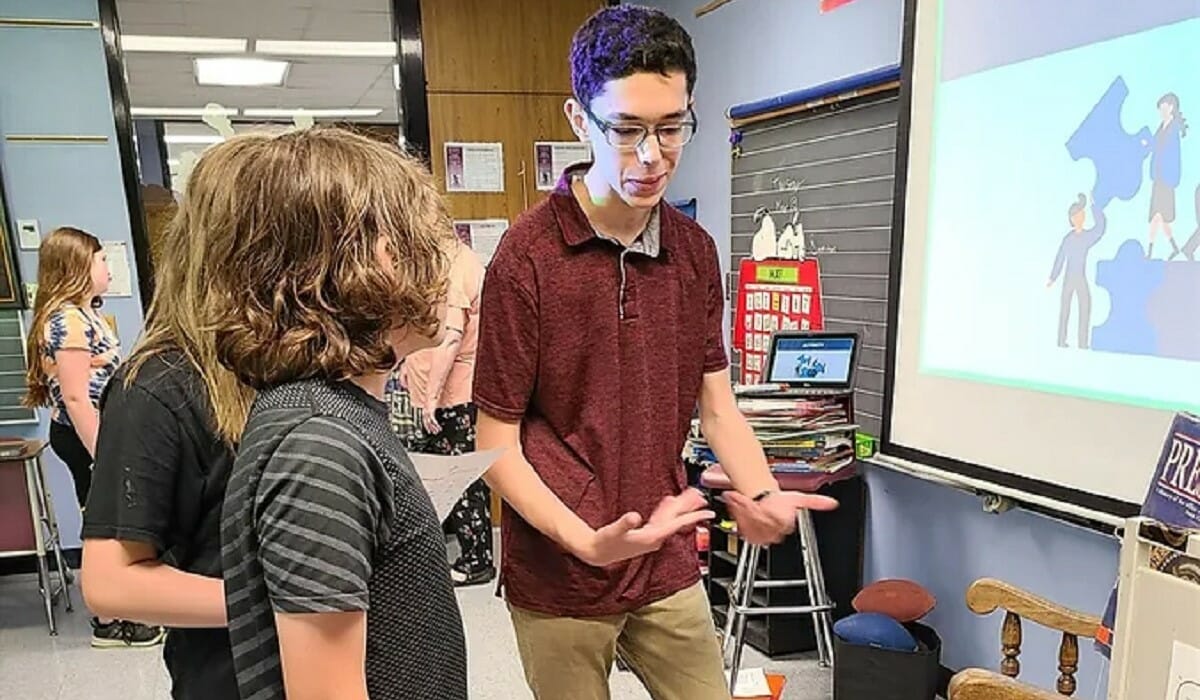
Isaac explains a economical concept to a young learner./Courtesy Isaac Hertenstein

Meet up with Daily Place of Gentle Award honoree Isaac Hertenstein. Examine his story and nominate an remarkable volunteer or family members as a Every day Place of Light-weight.

A lot of adults go away school and are stunned to uncover out how difficult taxes can be and don’t understand matters like how to commit in the stock market. Many thanks to Isaac Hertenstein, pupils in Greencastle, Indiana and further than are graduating with a bigger amount of financial literacy than at any time ahead of.  

You never see many superior schoolers with a fiery passion for personalized finance, but Isaac, a sixteen-year-outdated runner and ethics enthusiast, breaks the mildew. Even in center college, his center university know-how and entrepreneurship trainer, Brittany Labhart, remembers observing his curiosity peaking. 

I saw in sixth and seventh [grade] that he was unquestionably interested in it, but in eighth quality I observed a substantial alter. Which is when we talk about small business and own finance,” she remembers. “He is an wonderful kid who has been driven from a pretty younger age” 

The pretty following calendar year, Isaac resolved to share the understanding he found so intriguing with other folks. So, as a freshman in significant school, he formed his 501(c)(3), Pupils Educating Finance. 

“A large amount of inspiration for Pupils Instructing Finance (STF) was from observing the financial inequality in my neighborhood and the influence of monetary literacy in combatting that as nicely as mending a hole in training,” Isaac suggests. “Indiana is not 1 of the 15 states that necessitates monetary literacy [as part of the curriculum].”  

The states with the necessity commonly require learners to get at minimum a person semester of own finance in purchase to graduate from superior school. With this is head, Isaac took motion. Initially, he delved into dialogue with numerous local community leaders and economic and education and learning specialists. Then, he designed a 30-site curriculum for students from kindergarten by eighth quality with the mission to provide a foundation for results and to motivate young ones to look at economic professions. He also hopes to start discussions in between learners in the classroom and at residence. 

How does it operate? Isaac recruits volunteers amongst his peers to teach quick Lights Classes, just about every concentrating on an age-ideal core notion. Given that he started Pupils Instructing Finance, Isaac has taught around 575 college students in his hometown and has all over 30 volunteers teaching on a common foundation. These classes—and their teachers—leave lasting impressions.

Isaac Hertenstein, founder of Pupils Training Finance./Courtesy Isaac Hertenstein

“He begun off by inquiring them if they’d alternatively have so substantially revenue right now as opposed to so considerably in 10 several years, and he described how compound desire operates,” Brittany states of a lesson Isaac taught in her classroom. “It surely sparked dialogue afterward, and pupils had been definitely intrigued in what he experienced to say.” 

Moms and dads can frequently be listened to telling volunteers that their children have been chatting about the classes for months afterward. Academics are also acquiring in line to implement his lessons on their own. Soon after functioning with Isaac for on STF for the past two years, the economics trainer at his large faculty applied his lessons in her curriculum for seniors. 

And the enthusiasm is creating its way all over the place. 

“I’ve labored with over 250 other volunteers about the place in 14 diverse states who have applied this curriculum and commenced chapters of Learners Instructing Finance in their communities,” Isaac suggests proudly. “ I’m attempting to unfold economic literacy and commence chapters in other superior colleges. Of system, just one of our primary ambitions is advocating for financial literacy legislation.” 

Aiming to have a systemic effect, Isaac and STF has been in talks with several advocacy teams marketing fiscal literacy laws in Indiana.  

In this article in Putnam County, we have a fairly superior poverty price, and to instruct youngsters at all ranges the worth of own finance with basic ideas that it’s possible they are not receiving at residence, he can support them to make clever selections in the potential,” Natalie states. 

Isaac cites that developmental researchers have proven that young ones begin forming a financial mentality at age five. 

“They observe quite a few of the fiscal expending and saving behavior that their dad and mom and people today bordering have them, and they subconsciously undertake all those practices,” he states. 

Isaac hopes his courses and emphasizing the time worth of revenue will aid get ready people kids as they get more mature and deal with economical issues like paying for faculty and retirement. Sad to say, not anyone is so fortunate. 

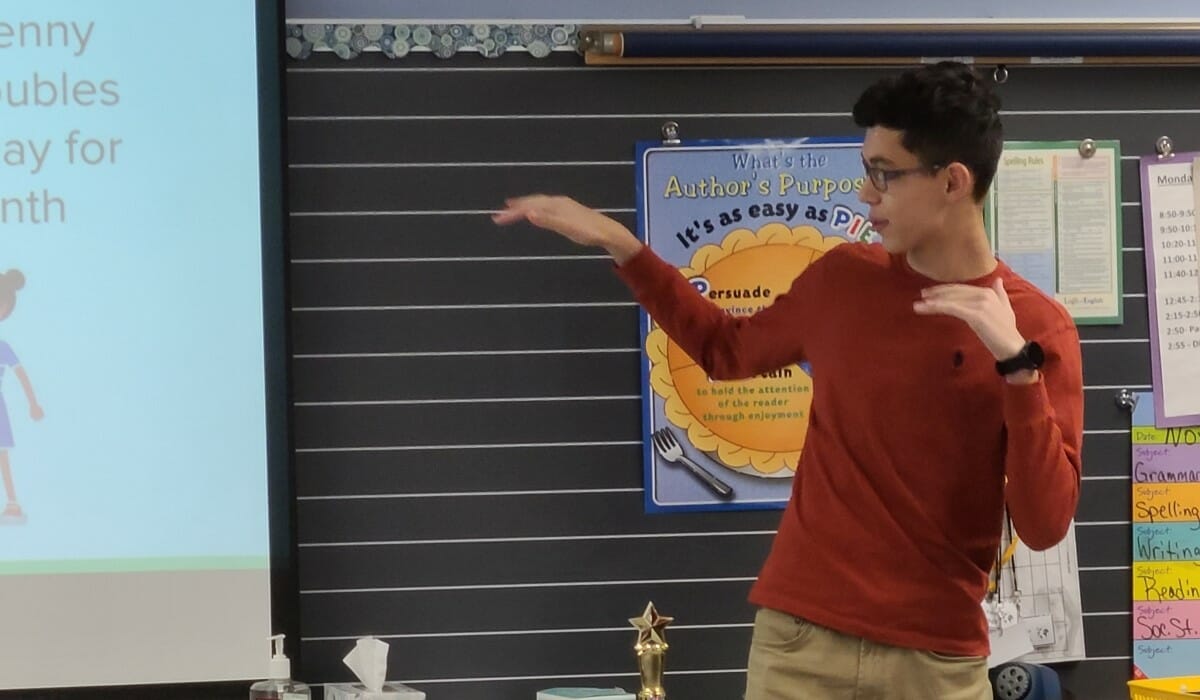
Isaac prospects a class on finance./Courtesy Isaac Hertenstein

In accordance to a research from UPenn Wharton, which arrived out about 5 yrs ago, one particular-thirs of economic inequality is prompted by–not just joined to–differences in monetary literacy,” he cites. “Financial disparities and expertise definitely catalyze a substantial big difference in economic output and effects in the pretty conclusion. A great deal of it has to do with financial sector inclusion and setting up up belongings in excess of time.” 

Impressed by his mom, a very first-grade teacher who styles the minds that will have favourable influence on the long term, Isaac is pretty forward-wondering. As he seeks to build a vocation at the level exactly where ethics, small business, and social effect blend, he typically thinks of the potential of his business. He hopes to grow STF’s attain by teaming up with FinPro Entire world, a company that results in on the internet discovering courses for middle to higher university-aged students, as nicely as recruit more faculty-aged volunteers to educate.  

“72{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of mother and father do not talk to their youngsters about money.” Isaac suggests. “Finance is from time to time a taboo matter, but it is these an vital principle that lots of men and women disregard when meeting other people, and if they have been to examine it, it would actually just catalyze a lot more finding out for all people.“ 

Do you want to make a big difference in your group like Isaac? Come across area volunteer prospects.