Best personal finance software of 2022

Best personal finance software of 2022


Published Jun 18, 2022 9:00 AM

The best personal finance software will fast-track your financial goals while also saving you time and frustration. And there are fantastic options in personal finance software that will make your financial life much easier—whether you are flying solo, keeping your family’s finances in order, or running a small business. 

Despite the technological conveniences of online passwords, bill pay, and ordering, there are too many virtual transactions to keep track of in your head. Personal finance software will help you manage and analyze all your data while keeping your information private, secure, and encrypted. Because let’s face it, don’t we all want a killer credit score? 

Setting and meeting financial goals, staying on budget, and not stressing about bills is important and it sure does help you sleep better at night. When you do spend, changing the ways you decide to spend your money might even truly bring you more happiness. The best personal finance software will provide an easy way to manage your financial goals, keep all your finances in one easy-to-navigate place, while also backing up and securing your personal information.

How we chose the best personal finance software

We arrived at our selected products by reviewing seven top-rated personal finance software brands based on personal experience, peer suggestions, and user impressions. We then narrowed them down to five after we compared and considered the following for each program:

  • Cost: How expensive is the personal finance software?
  • Features: What tools does the program offer?
  • Goal setting: How will the program allow you to set and monitor financial goals?
  • Security features: What steps do they take to ensure your personal information is secure and private?
  • Training and education: How does the software educate you on not only how to use the program, but how to improve your financial literacy?
  • Compatibility: How can you use the program, is the mobile app easy to navigate?
  • Customer reviews: How do actual customers rate the financial software?

What to consider when selecting the best personal finance software

With so many software options on the market for personal finance, it’s important to consider what features are important to you and how you will use the program. Here are some factors:

How much financial tracking do you want?

When it comes to options, you can track it all, just a few things, or somewhere in between. So asking yourself how and why you will be using your personal finance software is an important first consideration. There are software packages that make sense when you want to track all your expenses, credit cards, as well as investments. There are other simpler programs that might be better for beginners that are more focused on coaching and guiding you stay on budget.

Where and when will you track your finances?

Consider how you will use your software. Are you planning on sitting at your office desktop and reviewing it all? Or do you want a program that integrates seamlessly with your smartphone? Your personal finance software should match your lifestyle.

Is cost a factor in deciding on your personal finance software?

Luckily, personal finance software isn’t too expensive, but you should still consider how much you are willing to spend. Do you prefer to pay a lump sum or would it be easier to spread out the cost monthly? How much are you willing to spend on personal finance software, or do you want a free program? If you want to try before you buy many software programs offer a free trial before you commit.

Is tax time your main concern?

If your main goal is getting your finances together for tax time you have some options. You can purchase software that will help you organize, prepare and file. Or, you can also look into software that will automatically turn your financial data into spreadsheets that can be used for tax-time for you or your accountant. If this is important be sure to select software that offers these features.

The best personal finance software: Reviews & Recommendations

Ultimately, it’s best to choose personal finance software that is suited for your individual goals. A little consideration and legwork in advance will set you up to get started and meet your goals quicker. We have analyzed, selected, and given awards to the best software based on the program’s features and how these features will help you meet specific needs. The best personal finance software will streamline your financial life and help you meet your goals painlessly. Here are our top picks.

Best overall: Quicken Premier
Why it made the cut: Quicken Premier is our top choice for best financial software overall because they offer the most features to manage spending, budgeting and bill paying, plan for retirement and manage investments.

Specs

  • Financial tracking includes: Banking, loans, investments, 401(k), IRA, assets including private holdings
  • Bill pay: Pay bills for free through Quicken Premier
  • Tax preparation: Generate Schedule A, B & D tax reports, Export and import data to TurboTax
  • Platforms: Windows, macOS, iOS, Android, Web-based

 Pros

  • The most comprehensive investment analysis tools on the market
  • Allows you to run “what if” scenarios across loans and investments to help inform decision-making
  • Includes Quicken’s Lifetime Planner to help you plan retirement and major life events

Cons 

  • Mobile app isn’t as comprehensive as desktop version

Quicken is one of the most popular brands in personal finance software and brings decades’ worth of experience to the brand’s software design platform. Quicken offers several versions of the software tailored for different needs and price points. The simplest and least expensive version is Quicken Starter, which is tailored for budgeting and planning. The next tier is Quicken Deluxe, which adds on some investment tracking tools. And the third tier is our choice, Quicken Premier, which offers some great additional features targeted toward analyzing your investments as well as tailored advice for investing and loans. 

Quicken Premier helps you with your personal accounting by syncing directly to your financial institution and investment accounts and automatically updating and categorizing new transactions into budgets. If any errors occur, you can always go in and edit but this feature saves you a lot of time. They also use easy-to-read color coding to help you visualize your budgeting. Another great feature included is the ability to pay 12 electronic bills and three check bills per month with no fees.

There is a further price level in Quicken Home & Business, which is a great choice for business owners. Finally, the company’s newest offering is Quicken Simplifi, which is an app-only and allows you to budget, save, track expenses and see all finances in one place. Quicken Premier, however, is the sweet spot for most.

Best for taxes: TurboTax
Why it made the cut: TurboTax is our top choice for personal finance software specific for tax preparation because of its easy-to-use design and multiple version options—from super basic tax returns for free to tiers that address the complexity of your personal financial situation.

Specs

  • Flexibility: File your own taxes, get live advice as you go, or have a tax expert file for you
  • Guarantees: Accurate or TurboTax will pay IRS penalty
  • Platforms: Windows, macOS, iOS, Android, Web-based

Pros 

  • Easy-to-use interface 
  • Get live advice or access their archive of up-to-date resources to help you file and organize your financial documents
  • Free AuditSupport by trained tax professional
  • Guided support with any major life changes

Cons 

Taxes are not only a legal obligation but an important part of your overall financial well-being. TurboTax software is the best choice for filing taxes because it takes a very complicated subject and breaks it down easily for average people to understand. Tax code is not a simple subject, but TurboTax helps by simplifying each section (as well as possible life-change questions that could affect tax returns) into easy question-and-answer subsections.

If you are a freelancer or have a small business, it is worth paying for the more expensive versions of the program and using the live tax preparation help, as well as real tax professional final review. The added benefit is the program also acts as education for what to track and keep for tax years going forward.

Best for habit-building: YNAB
Why it made the cut: YNAB is our top choice for best habit-building personal finance software because of their hands-on proactive approach to budgeting which teaches you healthy financial planning habits.

Specs

  • Learning Opportunities: Live workshops, guides, articles, and a podcast to keep you up to date on all the app features and how to budget
  • Account: Link Banking accounts manually or automatically
  • Platforms: Desktop app, iOS, Apple Watch, Android, Alexa

Pros 

  • Proactive budgeting keeps you building good habits
  • Try the YNAB App for Free for 34 days (no credit card required)
  • 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} money-back guarantee if you aren’t satisfied with the app

Cons 

  • No internal bill pay feature
  • Expensive

YNAB (You Need A Budget) helps take the guesswork out of budgeting. Using its basic structure of four rules, you’ll learn how to stay on budget. The rules involve the following: assign a “job” for your dollars as soon as you get them; plan for bigger true expenses by setting aside a little each month; move around your budget if you overspend; and learn to age your money to stay ahead of your expenses by using money older than 30 days old. These cute, quirky rules are a fun way to build healthy financial habits.

Signing up for YNAB also allows you to have access to personal support and teaching to help continue your financial literacy education. You will be able to sync your accounts and set goals and read reports to monitor your progress. YNAB is a great tool to learn habit-forming behaviors and gives you the motivation to stay focused.

Best for budgeting: Mvelopes
Why it made the cut: Mvelopes is our top choice for budgeting-focused personal finance software because it uses a clear, easy-to-understand system where you break down your income based on categories of expenses, or “envelopes,” and track them with the app.

Specs

  • Membership Options: Basic Plan, Premier, and Plus
  • Sync with accounts: connect financial accounts to have everyday transactions tracked
  • Platforms: App available for iOS and Android devices

Pros 

  • Simple “envelope”-based budgeting philosophy
  • Higher-tiered memberships include perks like live chat support, access to their learning center, sessions with a financial coach, and a personalized financial plan
  • Easy to use for debit and credit card users

Cons 

  • No tracking of investing or retirement

Mvelopes is a budgeting personal finance app offered by Finicity, which is owned by Mastercard. The mvelopes app is designed to help people create realistic, easy-to-understand budgets using the simple tried-and-true method of envelope budgeting, but revisited for the digital age. It works by linking your banking and credit card accounts, entering your income and then breaking down your desired spending by categories, or “envelopes.” The idea is to keep your spending in each category capped at the amount you plan for. The mvelopes app makes this easier by automatically updating your transactions so you can see where your money is going and adjust accordingly.

Mvelopes works best for people who primarily spend using debit and credit cards so, while information can be manually entered if you use cash, it’s not as practical if swiping is not your preferred spending method. While the mvelopes app doesn’t approach your entire financial picture, it can be useful if your main goal is staying on budget in order to save or pay down debts. 

Best free: Mint
Why it made the cut: Mint is our top choice for best free personal finance software because it’s highly rated, has an easy-to-use app platform, and allows you to track your complete financial picture.

Specs

  • Financial tracking includes: Banking, credit cards, investments, 401(k), IRA, as well as other financial accounts.
  • Bill pay: Set up bill pay reminders
  • Platforms: App available for both iOS and Android

Pros 

  • Free access to your credit score without negatively affecting your credit score
  • Free credit monitoring through TransUnion
  • Built-in budgeting tools let you organize and categorize your spending

Cons 

  • No direct bill pay
  • No joint accounts
  • Advertisements

The price is right (free!) for this personal finance software offered by Intuit. While it doesn’t offer nearly as many features as paid personal finance software, it offers a very convenient start. The ability to track and view all your finances in one place, help with budgeting and categorizing expenses, as well as free credit score tracking, are all very useful features.

If you are curious about how using personal finance software apps might affect your financial planning and budgeting, this app is a great way to start. A level of confidence comes from their commitment to security, which is a priority for Mint’s parent company Intuit. The security includes an ever-evolving list of features, including strong encryption, multifactor authentication as well as your own security code on your smartphone. Mint is a great resource for free personal finance software, recommended based on its useful features and high level of security.

FAQs

Q: How much does personal finance software cost?

Personal finance software will cost you on average between $75 – $120 per year, which many companies offer as a flat yearly fee or broken down into a per-month charge. Tax preparation software is between $100 and $175 a year. There are also free programs, which may have advertisements and limits to the variety of features they offer. Most brands offer tiers of memberships depending on how complicated your financial situation is and how many features you want to track.

Q: Is QuickBooks good for personal finances?

Yes, QuickBooks is good for personal finances but, for most average users, it may offer more features than you will really need. QuickBooks is tailored more for business owners, as it includes tools for accounting, inventory, payroll, tax filing, accounts receivable and accounts payable management. Quickbooks is a good choice for personal finance management if you are a business owner.

Q: Can I trust the Mint app?

Absolutely. Mint’s parent company is Intuit, which also develops TurboTax so knows and understands the importance of financial data security. This means bank-level 128-bit encryption, monitoring through third-party sites like TRUSTe and VeriSign, and multifactor authentication are just a couple of the features assuring clients have peace of mind whether using Face ID, Touch ID, or unique PIN. Unusual spending activity is monitored. And, if a device with Mint access is lost or stolen, there are ways to delete information remotely.

Final thoughts on the best personal finance software

Our selection for the best personal finance software is Quicken Premier because, for the cost, it offers the most robust features to not only help you budget and save but also pay bills and set and manage long-term financial goals, including investments. When selecting personal finance software, make sure the software offers useful features that you require. Business owners should opt for higher-level programs, while other people might benefit from simpler budgeting or habit-forming apps that help you organize and motivate spending within limits. Regardless of your needs, the best personal finance software will be secure and offer easy syncing with your financial accounts and help you reach your financial goals.
Four items you should review while doing your midyear personal finance analysis

Four items you should review while doing your midyear personal finance analysis
A good deal can transpire in six months. Which is why, as we near out the initial half of the yr, it will make sense to check out in on your economic existence. With inflation, men and women this year are additional heavily impacted in comparison to before, so it’s a fantastic time to see how things have been heading … as perfectly as plan for what lies forward in the remainder of the 12 months.

So the place must you get started? Incorporate these 4 products to your midyear dollars checklist.

1. Overview YOUR Money, Expenditures AND Aims
You really don’t have to tally up each penny you’ve created and spent around the final six months. But getting a few minutes to examine a lender or finances app can assist you better comprehend your funds and training course-right if necessary.

“Right now with inflation, even if you experienced a budget back in January, it likely is not the very same as it is now. There are some items that are going to need to be improved. So it is just seriously resetting and figuring out the place you stand these days vs . wherever you thought you were being likely to stand these days,” claims Kayla Welte, a money planner.

Glance for prospects to scale back if you’ve put in much more than anticipated. For illustration, you can dine out significantly less or terminate membership solutions you not often use. “Any extra paying out that you’ve been carrying out, you could have to slice down to account for this higher cost of things that you certainly have to obtain,” Welte says.

If you established cash resolutions or other economic aims previously this year, verify on individuals also. Have you saved as substantially towards retirement or an emergency fund as you planned? Are you on monitor to pay back off financial debt?

2. Deal WITH Financial debt

Credit card debt is starting to be far more pricey to have owing to climbing interest costs. Spend down debts quicker, particularly all those with variable fascination prices, to help save funds. These money owed may include credit playing cards, personal financial loans or adjustable-price mortgages.

Focus on minimizing your highest-amount credit card debt 1st, then go on to the up coming maximum. Dall’Acqua also implies switching from variable-price to fixed-rate selections by refinancing, if doable. “If you can lock in the preset price now, you are very likely to be preserving on your own appreciably in fascination expenditures over time,” he says.

Environment apart funds now in a separate discounts fund can assistance soften the blow.

3. Approach Getaway Searching

Inflation could make holiday break gifts a small pricier this year. Develop a searching listing and imagine about how much you can afford to pay for to devote. “Figure out what that would need for you to start off conserving on a weekly or regular monthly basis and commence placing that funds aside ideal now,” Dall’Acqua says.

Starting on purchasing early can also help you control the price tag with out accruing credit card debt. Several merchants host significant sale situations.

4. Analyze YOUR TAXES AND Benefits

Welte recommends working with an on the web tax calculator to examine whether or not you are withholding way too considerably or way too little. This can aid you stay clear of receiving hit with a massive tax invoice unexpectedly or missing out on further cash you might have to have now.

“If you do the math and you are going to get a tax refund, it would be a fantastic time to transform your expense declaration sort, get extra dollars in your pocket now to fork out for these excess charges that are coming up with inflation,” Welte states.

If you need to make adjustments, fill out a new investment decision declaration sort and post it to your employer.

Whilst you are at it, consider your staff reward selections. These added benefits can include wellbeing insurance, lifetime insurance, health savings accounts and adaptable spending accounts, additionally benefits like health club memberships.

Examining your decisions in the summer can reduce you from turning out to be confused in Oct and November, when open enrollment starts for most providers, claims Joe Bautista, a CFP in Lake Oswego,

.

The purpose is to make certain you are deciding upon the most expense-effective possibilities that fit your wants. For case in point, “a PPO has better rates but a reduced cost if you tend to use health and fitness treatment, decrease deductibles and copays typically. But if another person does not use that well being treatment, then they can be overspending,” Bautista suggests.

Never worry about obtaining anything best correct now. As Bautista claims, “financial organizing is dynamic, it’s not static.” Look at in on your cash designs periodically and update as required.

What are current personal loan rates?

What are current personal loan rates?

Our purpose here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” under, is to give you the equipment and self-assurance you require to strengthen your funds. Whilst we do boost products from our spouse creditors who compensate us for our expert services, all viewpoints are our very own.

The fee you get on a loan establishes your month to month payment total and total value of borrowing funds.  (Shutterstock)

A private mortgage can help you deal with just about any price. Whether you need to have a personal loan to consolidate debt, pay a professional medical bill, or fund a property improvement project, it could be a great time to borrow dollars when desire rates are minimal. Dependent on your credit score and funds, as nicely as the type of bank loan you select, you could be ready to conserve some income on desire rates and minimize your general charge of borrowing. 

Go to Credible to see your prequalified personalized bank loan premiums from a variety of lenders, all in a person put.

What are current particular mortgage premiums?

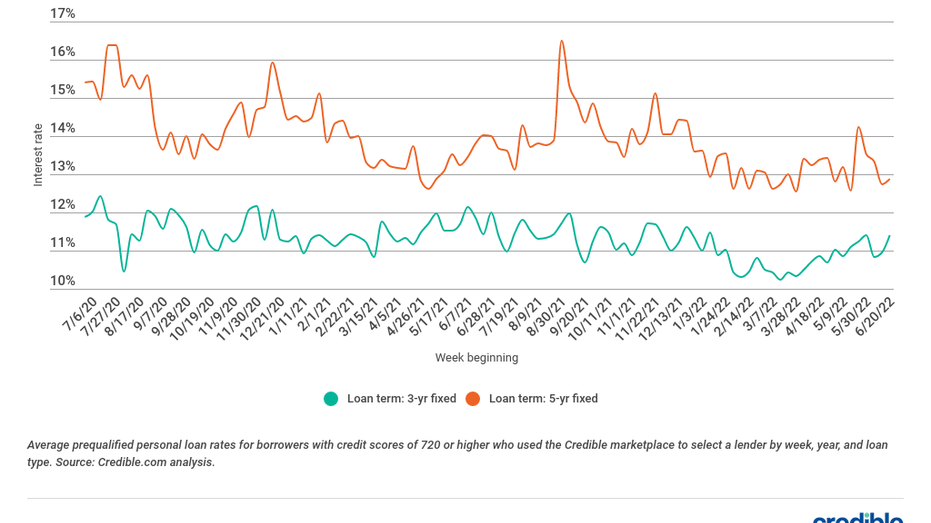
The chart under shows typical prequalified individual loan charges for borrowers with credit rating scores of 720 or better who used the Credible market to select a financial institution:

For the month of June 2022:

  • Prices on 3-calendar year individual financial loans averaged 11.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, down from 11.14{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in May.
  • Costs on 5-yr private financial loans averaged 13.10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, down from 13.27{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in May possibly.

How has inflation impacted private personal loan premiums?

The existing inflation fee in the U.S. is 8.26{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Although it has slowed a bit, it is nonetheless near to the maximum it is been in 40 decades. Because inflation prospects to bigger charges on merchandise and expert services, the desire for credit rating boosts, primary to increased desire rates for new particular loans and other monetary items, like home loans and credit history playing cards. 

Though this rewards loan companies, it means that you are going to spend more to borrow dollars. If you have a current bank loan with a mounted curiosity level, your payments will not be influenced. But if your mortgage has a variable fee, your payments could go up.

Credible makes it uncomplicated to compare personalized financial loan fees from many loan providers, with no affecting your credit.

Typical personal financial loan premiums by credit rating rating

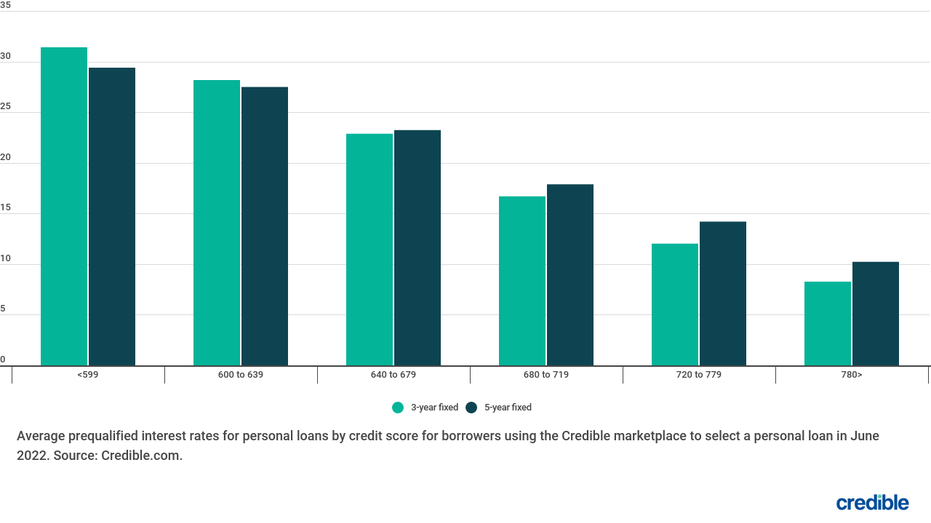
Typical own personal loan rates can fluctuate based on your credit rating and other monetary things. The chart underneath displays normal personal loan costs by credit rating rating:

 In June, the ordinary prequalified level chosen by debtors was: 

  • 8.26{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for borrowers with credit scores of 780 or earlier mentioned selecting a 3-yr mortgage
  • 30.44{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} for borrowers with credit rating scores under 600 choosing a 5-12 months financial loan

How to get a lower personal financial loan interest price

The good news is, you can just take methods to lock in a lower fascination fee and potentially preserve hundreds or even 1000’s of pounds in interest on your private bank loan, such as: 

With Credible, you can immediately and simply compare private financial loan costs to locate 1 that fits your requires.

What if You Can’t ‘Out-Budget’ Inflation? | Smart Change: Personal Finance

What if You Can’t ‘Out-Budget’ Inflation? | Smart Change: Personal Finance

Inflation is a nightmare for the several Us citizens who already stretch their bucks to deal with fundamental requires. What takes place when individuals dollars shed worth?

Their alternative is likely not about no matter if to slice streaming products and services or opt for store-brand groceries. Instead, they may perhaps have to pick concerning acquiring enough foodstuff and paying out lease.

The households hit most difficult by inflation ordinarily have tiny in personal savings and other sources. And that deficiency of entry to wealth can be rooted in a historical past of inequality, says Phuong Luong, a Massachusetts-primarily based licensed fiscal planner and founder of Just Prosperity, a money schooling and consulting organization.

For example, say generations of your family have been underpaid or restricted in where by they can reside, owing in portion to racist procedures. Then inflation results in everything to turn into far more high priced.

You may perhaps have to scrape jointly money to assist not just you, but also family members or community users. Maybe you have to invest dollars and time traveling throughout city to the grocery retail store or doctor’s workplace.

“Your proximity to persons with sources and people today with wealth is going to be distinct dependent on exactly where you reside and who you are,” Luong claims. “There’s a larger sized context than just bills and budgeting.”

Whichever context describes your predicament, here’s how to combat inflation if funds is now restricted.

Prioritize necessities

Goal to spend for costs that permit you to reside safely and securely: housing (mortgage or hire), utilities and food items. Also try out to cover expenses that enable you perform, these kinds of as transportation, mobile cellular phone and little one care.

Next-stage priorities are people that bring about key outcomes if you don’t fork out: taxes, little one assist and coverage.

For credit playing cards, goal to pay out your least at least, because you may have to have that credit rating access.

Faucet area assets

If you’re battling to spend expenses, obtain help. Luong implies Findhelp.org, which lists area systems developed to minimize costs across many classes.

Contacting 211 or visiting 211.org can also help you locate assistance similar to housing, wellbeing, meals and crisis prices.

Select up the cell phone

You may also help save cash by calling credit score card and insurance coverage corporations, lenders, banking institutions, cell phone suppliers and other corporations you fork out.

With the pandemic influencing so quite a few shoppers, these organizations “are a small additional empathetic than they have been,” states Emlen Miles-Mattingly, co-founder of Onyx Advisor Network, a Sacramento, California-based mostly guidance platform for underrepresented economical advisors.

They may pause or lessen payments, for case in point, or forgive overdue charges. Or they could reduce your curiosity amount.

But you have to check with. And normally a affected individual mobile phone call with shopper service yields quicker, far more efficient benefits than an email or online sort.

Link with your local community

To prevail over economical struggles, “community is likely to be big,” states Dasha Kennedy, Atlanta-based monetary activist and founder of The Broke Black Lady Fb community.

Leaning on — or supporting — your spouse and children members, buddies and neighbors can consider a lot of varieties. For illustration, Kennedy factors out how temporarily residing with other individuals can reduce housing bills. Or you can pool assets by sharing a car or truck or splitting a huge price.

To join with supportive locals you have still to fulfill, look to libraries, spiritual corporations and recreation centers. Or use virtual platforms like Facebook and Nextdoor.

In these in-individual and on-line areas, you might locate free or affordable products and solutions. Possibly an individual will give absent secondhand dresses or wander your pet when you get the job done.

Or look for assistance. Your neighbors may perhaps point you toward no cost, close by overall health assets, for instance, or explain what’s helped them stretch their money.

Financial gain from your expertise

Of program, generating more funds allows, far too. If you are currently functioning, Kennedy endorses very first making an attempt to boost earnings via your employer. Contemplate performing time beyond regulation or negotiating raises and part changes, she states.

Or explore side perform — with caution. Plenty of on the web gigs could squander your time, get your money or misuse your own data.

“It’s high time for frauds and ripoffs,” Kennedy suggests. Rely on your gut, and read through opinions. Also verify the Federal Trade Fee and Far better Enterprise Bureau internet websites for ideas to avoid frauds.

The most productive way to make dollars? “Monetize expertise you currently have,” Kennedy states. These could include something from cleaning and arranging to composing and building.

Assuming you begin devoid of purchasers, she suggests tapping your community as soon as once more.

“You might not have the time to establish have confidence in and reputation, so you are likely to have to depend on particular relationships,” she suggests. Request mates, neighbors and loved ones users to encourage and vouch for you.

Intellect your mental overall health

Funds struggles are exhausting. So regularly “connect with on your own,” Miles-Mattingly suggests. Detect what would make you come to feel much better, no matter whether it is strolling outside, calling a mate, meditating or looking through.

If time is tight, make your activity speedy, and take into account Miles-Mattingly’s stage: “People, when pressured, really do not have the finest choice-creating qualities.” And tough moments necessarily mean hard selections. It pays to come to feel centered right before negotiating a reduce bill or agreeing to a aspect work.

To steer clear of emotion overcome through times of fiscal worry, Kennedy attempts not to overthink the unpredictable potential. As an alternative, she indicates “focusing on finding by way of the day.”

This short article was composed by NerdWallet and was at first printed by The Associated Push.

5 Things To Do in a Recession | Smart Change: Personal Finance

5 Things To Do in a Recession | Smart Change: Personal Finance

Any day now, you can hope your newest quarterly 401(k) assertion from your employer that exhibits the existing benefit of your daily life financial savings, and you possibly foresee that the stock and fund portion of your financial savings has shed value considering that your past assertion. Understanding inflation is significantly higher than ordinary, curiosity fees are increasing, and the overall economy could be headed into economic downturn, it is not shocking that your investments are impacted. But for the very first time, in addition to your current 401(k) stability, corporations clearly show projections that illustrate what your lump sum price savings could possibly look like as monthly earnings after you retire. These figures might be lessen than you thought.


Locating a money advisor you can trust who has the expertise you require and is dedicated to working in your ideal passions can be frustrating. Which is why you really should consider Wealthramp’s cost-free fiscal advisor matching company. Each individual advisor in the Wealthramp network is rigorously vetted. Response some brief thoughts, review your advisor matches and timetable a no cost assembly with any or all of your matched advisors. Wealthramp will in no way provide your information. You will not get pushy profits calls from them. If you are all set to see your most effective advisor matches, get started now.


So what’s subsequent? As the Fed tightens into a slowing economic system, there’s a superior hazard of economic downturn, and even a gentle contraction in financial progress can final for months or several years. Telltale indicators of recession amid other items are when retail revenue are falling, manufacturing slows down, organizations end selecting, and extra men and women possibly get rid of their jobs or get laid off. As alarming as the news may well show up, recession is element of the usual company cycle. In its place of reacting, this is a very good time to revisit your money plan to place you to prosper.

No matter whether you might be controlling your funds on your possess or functioning with a dependable economic advisor to aid you control aspect or all of your portfolio, below are five critical actions you should choose now to retain your finances in fighting trim throughout challenging financial instances.

1) Keep Your Credit history Score Large

In a interval of substantial inflation, it charges a lot more for everyone to borrow funds no matter of their credit history rating. On the other hand, men and women with reduced credit history scores will suffer even a lot more. Creditors charge much less to borrowers who’ve shown they will repay financial loans on time as agreed. Banking companies use your credit rating score as a useful way to see what sort of a borrower you are. If more than time you’ve demonstrated a sample of having to pay credit card debt late, loan providers will be cautious of lending you dollars. The shorthand metric employed to measure borrowing conduct is your credit score score — a small one usually means that lenders are anxious you will not spend them back again. To account for that risk, loan companies charge a lot more to lend to iffy borrowers in the form of greater curiosity prices.

This isn’t the time to allow for your credit score to slip. If you do want to borrow money, you are going to want to do it at the lowest probable fascination amount, which is reserved for people who have superior credit rating scores around 700. If you are carrying credit score card balances 12 months in excess of 12 months, have you appeared at the curiosity amount you are shelling out? A typical credit rating card fees you above 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in once-a-year interest. For case in point, consider that you purchased a set of summer patio home furniture on sale for $10,000. If you have an excellent stability of $10,000 on your credit history playing cards and you never pay out it off, it is like incorporating $2,500 on top rated of what you paid for the table and chairs.

2) Manage Your Cash Reserves

It’s crucial to get to the position wherever you know you have preferably six to 12 months of prepared funds in an accessible account for emergencies and sudden expenses. In a economic downturn, that reserve fund results in being even extra critical in case you shed your occupation or any main surprising celebration transpires to you and your family members. If you have more than enough of a price savings cushion, you are going to snooze greater. The draw back is that banking institutions really don’t shell out substantially on their price savings or revenue marketplace accounts, but the gain is that you will be ready to access dollars quickly without having acquiring to possibly market dropping shares to increase dollars when the current market is down. It also provides you the liberty to know you won’t need to have to get out a mortgage when interest costs are likely up. It appears unfair that financial institutions are speedy to elevate borrowing fees and significantly slower to boost rates on financial savings accounts, but the money security that comes with liquid hard cash reserves is truly worth it. The finest way to set aside more dollars is to make the life-style selection to live below your signifies.

3) Devote, But You should not Gamble

Lengthy-phrase inflation eats into your cost savings and expense returns. When inflation is substantial — and not long ago we have noticed inflation strike 8.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} — that indicates you’re paying a lot more but finding nothing a lot more in return. An inflation fee shut to 9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} is four situations bigger than the norm. And above the a long time, even at reduce costs, inflation usually takes a toll. The very best way to stay forward of inflation is remaining invested in a various portfolio of shares because more than time, shares have a tendency to grow quicker than inflation.

If you’re not absolutely sure how to construct a diversified portfolio made to secure and improve your dollars, this is in which an established money advisor who is impartial and totally vetted can support. Finding a economic advisor you can have faith in who has the expertise to satisfy your economic requires and is committed to functioning in your most effective interests can be frustrating. That is why you may well want to take into account Wealthramp’s free economical advisor matching company. Each individual advisor in the Wealthramp network is rigorously vetted. Solution some quick queries, evaluation your advisor matches, and agenda a free of charge conference with any or all of your matched advisors. Wealthramp will never provide your details. You will not get pushy gross sales phone calls from them. If you are completely ready to see your greatest advisor matches, get commenced now.

Just take from the industry experts — investing is the turtle, not the hare. John Bogle of Vanguard Team mentioned investing is supposed to be uninteresting — investment decision guru Ben Stein asks what is completely wrong with normal? — billionaire trader Warren Buffett in no way gambled. Buffett earned his billions by very careful, constant benefit investing. He missed the greatest instant to get into Apple (AAPL). To this day, he is continue to not invested in Tesla (TSLA). He doesn’t recognize Bitcoin and doesn’t want to master. In his full expense occupation, he has seldom experienced a blockbuster acquire. So how did he accumulate so a lot wealth? In addition to very careful investing, an generally-forgotten explanation is that he has lived a really extensive existence.

4) Come across Inflation Hedges

An additional tactic all through a economic downturn is to choose investments that act as hedges in opposition to inflation more than extensive intervals. Gold and commodities are the go-to brief-term investments for shielding your portfolio from inventory industry shocks simply because commodities like gold are likely to move in the reverse course from shares. Nonetheless, gold is a weak lengthy-time period investment, which is why numerous fiduciary monetary advisors advise hedging only about 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your portfolio. When you seek to defeat inflation, one of your very best techniques is to fully diversify your portfolio. That doesn’t indicate randomly choosing exchange-traded resources in distinctive sectors. Diversification demands that you create a strategy that you adhere to and revise when market indicators exhibit you its time. Your finest guess is to hook up with a fiscal advisor who can glimpse at your portfolio and assist you make guaranteed it is diversified.

5) Brush Up Your Resume and Raise Your Techniques

Proper now, unemployment is at a historic reduced in the U.S. Whether it is shallow or deep, recession normally qualified prospects to organizations laying off staff. The most effective way to defend by yourself from dropping your job and to ensure that you do well in obtaining a new task if required is to make you as precious an worker as attainable. If your present-day company delivers schooling reimbursement, leap on that benefit and function on a diploma or a certification that can boost your long term earnings. There are also low-value or no cost teaching classes you can pay back for yourself to increase your resume. Retain a record of your achievements at operate to transform a regular resume and address letter into one that can help you stand out and draw in the right consideration. And continue to be intently linked to your skilled and personalized network.

Steps to Get These days

As you consider defensive action to guard on your own and your spouse and children from recession, make a decision no matter whether to do it on your own applying electronic equipment or collaborate with a rigorously vetted, charge-only fiduciary monetary advisor who operates only for you, not as an agent for a brokerage agency or insurance coverage enterprise. If you’re receiving close to retirement, pick out a fiduciary who has the knowledge and specializes in retirement revenue setting up. They can enable you:

  • Make a tax-targeted prepare on your have or with their guidance
  • Acquire an financial investment method you will be in a position to adhere to around time
  • Devise techniques to spend down high-desire financial debt
  • Shore up funds accounts

Locating the correct fiscal advisor can be complicated. Permit Wealthramp enable you uncover the proper advisor who will enable you with your individual fiscal demands and situation.

Pam Krueger is a identified investor advocate, award-profitable private finance journalist, and founder and CEO of Wealthramp, a no cost advisor matching platform that connects men and women with rigorously vetted rate-only financial advisors. She is also the creator and co-host of MoneyTrack, which aired on PBS from 2005-2019, and Good friends Chat Income podcast for PBS Following Avenue now in its 7th time.

3 Proven Ways to Double Your Money | Smart Change: Personal Finance

3 Proven Ways to Double Your Money | Smart Change: Personal Finance

These times, there are tons of promises floating all-around the online to “double your funds” swiftly. Some offer you means to create even greater returns on your investment decision.

If you’ve been a consumer of the online for extra than 5 minutes, you know most of these promises are developed to do the actual reverse. To use a well timed case in point, it ought to not come as a surprise that obtaining digital pictures of monkeys has a really small return on expense.

But there are confirmed methods to double your money if you are affected individual sufficient.

Impression source: Getty Photos.

S&P 500 index cash

The closest detail to a confident point in the stock sector is basically betting on the market place as a entire heading up about time. In that respect, it has a perfect file.

Irrespective of many bear marketplaces and corrections, the S&P 500 has normally recovered its all-time highs and trudged larger. As a result, by simply just investing in a reduced-expense S&P 500 index fund this kind of as the Vanguard S&P 500 ETF (NYSEMKT: VOO), you happen to be almost assured to double your money presented ample time.

Persons are also reading…

Although you can find always the possibility of investing suitable before a industry crash, the historic details is on your aspect. Dating back again to 1928, the regular bull current market has lasted a lot more than 1,100 days, whilst the ordinary correction/bear marketplace has only lasted 194 days.

So even if you acquire proper at the peak in advance of a crash, all you have to have to do is wait around, and your investment will possible flip out just high-quality. And if you might be intelligent, you can expect to maintain acquiring by the ensuing bearish period of time to make an even higher return.

401(k) employer match

If I could shout it from the mountaintops, I would scream that employer 401(k) matches are quite virtually no cost revenue.

Image resource: Getty Pictures.

Bear in mind how I mentioned the S&P 500 is as close to a assure as it will get? Effectively, the only other detail that comes near is a 401(k) employer match — when the company you get the job done for matches your retirement contributions dollar for greenback up to a specific point. For instance, your employer could possibly match 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your contributions up to 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your income. In other words and phrases, if you set 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your paychecks into your 401(k), your employer will double your contribution.

This is, to my expertise, the best way to double your income, assuming your employer offers this reward.

Regretably, according to advisory business Fiscal Engines, People go away $24 billion in unclaimed 401(k) matches on the desk just about every 12 months. If your employer presents contribution matching, get edge of it! It is really the least complicated double-your-income option you may ever face.

Serious estate

Actual estate can be a great asset to double your money due to the fact it really is almost often in substantial demand, and they aren’t earning any more of it.

With the exception of the housing bubble in 2008, home rates have risen continuously for the past 50 several years. Part of this can be discussed by mounting inflation, but it is really also because of to the fact that housing is a basic will need for each individual individual on the earth.

Like investing in the broader stock industry, the key component for actual estate investing is time. Even though the near time period can be unpredictable, we can pretty much surely rely on authentic estate currently being value much more about time.

The most practical way to achieve exposure to actual estate is as a result of authentic estate expenditure trusts, or REITs. REITs make it possible for you to diversify substantially more very easily than acquiring assets immediately, and they present a great deal larger liquidity.

For example, aside from investing in household housing REITs like Mid-The united states Apartment Communities (NYSE: MAA), you could simply diversify into other sectors of the serious estate sector, this kind of as Crown Castle International (NYSE: CCI), which owns, operates, and leases towers for wireless communications.

Interestingly adequate, if you evaluate both equally of these REITs’ stock charges with the S&P 500’s returns more than the earlier decade, they observe closely.

Uninteresting normally wins

With NFTs, cryptocurrencies, and meme shares dominating the headlines these days, it is uncomplicated to believe they are the route to producing huge returns. But as with all speculative assets, the lofty returns hardly ever very last. As a Foolish investor, you ought to look for resources of extended-expression and steady returns like the illustrations higher than.

10 stocks we like much better than Walmart

When our award-profitable analyst workforce has an investing tip, it can spend to listen. Right after all, the newsletter they have run for above a ten years, Motley Fool Inventory Advisor, has tripled the current market.*

They just unveiled what they believe are the ten greatest stocks for traders to acquire suitable now… and Walmart wasn’t 1 of them! Which is appropriate — they assume these 10 shares are even much better purchases.

Inventory Advisor returns as of 2/14/21

Mark Blank has no place in any of the shares pointed out. The Motley Idiot has positions in and recommends Crown Castle Intercontinental, Mid-The usa Condominium, and Vanguard S&P 500 ETF. The Motley Fool has a disclosure policy.