Tori Dunlap of Her First $100K shares tips to build wealth

Tori Dunlap of Her First 0K shares tips to build wealth

Tori Dunlap wants to remind you: personal finance is particular. In purchase to obtain monetary achievements, you have to do what is ideal for your individual condition — not someone else’s.

Dunlap acquired a subsequent blogging about her journey to help you save $100,000 by the time she turned 25. When she completed that goal a few months right after her 25th birthday, she give up her job and turned the web site into Her Initially $100K, a money literacy brand that aims to assist women struggle fiscal inequality and get manage of their funds.

Most not too long ago, Dunlap, now 28, posted her very first guide, “Economic Feminist,” by now a New York Instances bestseller. 

Alongside the way, she’s discovered a few tips that can support everyone aiming for monetary achievements, regardless of whether that indicates retiring early, setting up a small business or fulfilling an additional desire. Right here are the three largest lessons she claims to find out prior to you can obtain monetary independence, what ever that signifies to you.

1. Having excellent with money takes observe, and you might be on a understanding curve

Superior money administration doesn’t occur normally to every person. For many, it is a talent they have to learn, usually afterwards in lifestyle.

“I think we appear out of the womb anticipating to be magically fantastic at income, but we you should not expect ourselves to be magically very good at just about anything else,” Dunlap tells CNBC Make It. 

She considers herself fortunate that her parents instilled good economical routines in her from a youthful age, but acknowledges that not anyone has the similar foundation. And even if they do, with out regular exertion it is really simple to fall out of exercise and into financial turmoil.

You want to observe and get into the practice of discovering about income right before you can genuinely master applying it successfully, she states.

“Just like everything else which is new, regardless of whether which is participating in the tuba or understanding to converse Italian, you happen to be likely to be negative at it. It can be not going to work out for you for a even though,” Dunlap says. “That would not suggest you cease making an attempt, it suggests you give you a ton of grace.”

2. Pinpointing your values makes all the difference

Prior to location your unique money targets, you will need to fully grasp your private values, no matter of what absolutely everyone else is executing.

“We genuinely have to have to have an understanding of what our values are,” Dunlap says. “We have to get our brains on board to care about everything. And that is not a willpower point.” 

A lot of persons aspire to plans like homeownership or early retirement, but if your values are a lot more aligned with the versatility renting features or the joy your occupation delivers, then these you should not need to have to be your aims.

“You need to connect a ‘why’ and your values powering your economic plans as opposed to just ‘I was informed I should buy a household by my mother and father, perhaps I must do that,'” Dunlap suggests. “If you will not want to do that, really don’t do it. That is Ok. You will need to obtain issues that truly mirror your values.”

3. Your emergency fund ought to generally arrive 1st

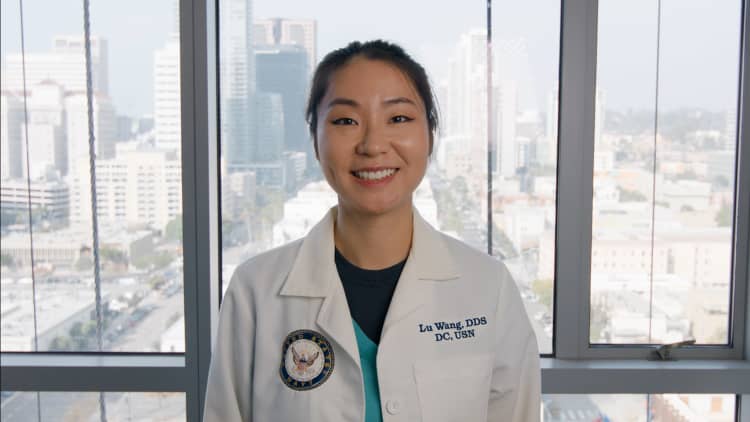
How a 31-year-old U.S. Navy dentist making $157,000 a year spends her money

FINANCE | Add layers of protection to financial strategy | Breaking News

FINANCE | Add layers of protection to financial strategy | Breaking News

To obtain your fiscal stability, and that of your household, you will need to make a thorough strategy. But for this method to realize success, you will require to guard it from several issues – and that signifies you are going to will need to make in distinctive layers of safety.


Jennifer Barrett.jpg

What are these difficulties – and what kinds of protection can be used to defend towards them? Consider the following:

Problem #1: Defending your ability to achieve your plans – To attain your lengthy-expression objectives, this kind of as a comfortable retirement, you can expect to require to construct adequate fiscal resources. And that implies you may have to have to produce an investment decision portfolio which is acceptable for your goals, possibility tolerance and time horizon. And you’ll need to keep your very long-phrase ambitions in intellect when modifying your portfolio all through moments of volatility.

Problem #2: Protecting your family’s foreseeable future if you’re not all-around – Hopefully, you will live a lengthy lifetime and always be around to aid your loved ones. But the long run is not ours to see – and if a thing ended up to happen to you, how would your household cope? Their probabilities could be much much better if you have enough lifetime insurance coverage. Appropriate coverage could help pay out off your mortgage, pay for your children’s larger training and permit your spouse and children to go on its way of life.

Problem #3: Preserving your profits ought to you grow to be quickly disabled – If you were being to come to be unwell or quickly disabled and could not do the job for a although, the disruption in your cash flow could jeopardize your family’s living condition, or, at the minimum, guide to an lack of ability to pay payments in a well timed fashion. To shield against this risk, you could want to consider introducing incapacity coverage. Your employer may perhaps supply a small-phrase incapacity plan as an staff advantage, but it may possibly be insufficient, either in period or in sum of coverage, so you could possibly want to seem at a non-public coverage.

Obstacle #4: Shielding your extensive-term investments from shorter-time period wants – Lifetime is whole of sudden bills – a significant motor vehicle mend, a new furnace, a massive bill from the dentist, and so on. If you did not have the money readily available to offer with these expenses, you may be forced to dip into your extended-term investments, these as your IRA or 401(k). Getting money from these accounts earlier than you intended could incur taxes and penalties, and, even far more importantly, could decrease the total of funds you have readily available for retirement. To help safeguard these investments from brief-time period desires for cash, attempt to make an emergency fund made up of 3 to six months’ worth of residing bills, with the revenue held in hard cash or a liquid account.

Problem #5: Safeguarding your monetary independence – You would most likely do all you could to steer clear of ever turning out to be a stress to your developed little ones – which is why it’s so vital to preserve your monetary independence in the course of your everyday living. One potential menace to this independence is the need for some variety of extended-phrase treatment, these kinds of as an extended nursing property continue to be, which can be really pricey. A economic specialist can advise defense techniques to assistance you prepared for these varieties of charges.

It can be hard to continue to keep your money technique intact – so do whatsoever it normally takes to guard it.

Jennifer Barrett (AAMS) is a regional Edward Jones Economical Advisor.

225-612-0413 | jennifer.barrett@edwardjones.com

Edward Jones. Member SIPC.

Edward Jones, its workforce and monetary advisors are not estate planners and simply cannot provide tax or authorized guidance. You should really seek the advice of your estate-setting up lawyer or experienced tax advisor relating to your situation.

This posting was composed by Edward Jones for use by your community Edward Jones Economical Advisor.

Business attraction, retention/expansion, entrepreneurship keys to economic development | News

Business attraction, retention/expansion, entrepreneurship keys to economic development | News

Choctaw Country Economic Growth Senior Supervisor Kreg Haney instructed members of the Poteau Rotary Club all through its weekly assembly Jan. 4 at Japanese Oklahoma Medical Middle not only his most important responsibility as an economic developer, but the 3 keys to achievement.

“An economic developer’s work is to attempt to retain and grow jobs, increase the excellent of existence for all citizens included and supply a stable tax foundation,” Haney stated. “I do get the job done for (the Choctaw Country), but in all actuality I do the job for the communities. You may find me in (Poteau Mayor) Scotty’s (White) place of work. You can expect to obtain me all more than the put to test to do what I can.”

Global banks cut jobs as cost pressures mount – Business & Finance

Global banks cut jobs as cost pressures mount – Business & Finance

LONDON: Worldwide banking institutions are in the procedure of slicing at minimum 5,000 positions as gains at worthwhile financial investment banking units come less than strain from volatility in capital marketplaces and speedy-climbing fascination premiums, according to a Reuters tally of noted cuts.

Rapidly deteriorating economic disorders have also prompted loan providers to construct rainy-day money to brace for opportunity defaults.

BARCLAYS: Barclays lower its workforce in corporate and expenditure banking by under 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, a supply advised Reuters on Nov. 8, weeks just after reporting a 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} slump in merger advisory service fees.

The British expenditure lender has carried out well in recent quarters, specially in fastened income trading, but a blunder in the United States that noticed it market extra securities than permitted has price it hundreds of millions of pounds in penalties.

CITIGROUP: Citi removed dozens of careers throughout its investment decision banking division, as a dealmaking slump continues to weigh on Wall Street’s greatest banking institutions, Bloomberg Information claimed on Nov. 8.

The US loan provider has, like its peers, boosted its lending profits as desire rates increase, but the intense action by the Federal Reserve and other central banking institutions has sparked fears of a downturn that could hit banks’ mortgage publications in time.

Credit score SUISSE: Credit Suisse is accelerating value cuts, Chairman Axel Lehmann said on Dec. 2, confirming a Reuters report, as the financial institution races to slash its price tag foundation by about 2.5 billion Swiss francs ($2.68 billion).

Credit Suisse had presently mentioned it would lay off some personnel. The price tag financial savings documented are probable to entail far more work cuts than earlier introduced for the 1st wave of reductions, which includes in its wealth organization, Reuters documented. The financial institution is slicing about 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of its private banking headcount in Hong Kong, two resources reported.

DEUTSCHE Financial institution: Deutsche Financial institution, Germany’s premier lender, lower staff members in its financial commitment bank’s origination and advisory groups in October, in a shift than afflicted mainly junior bankers.

The cuts included dozens of employees in New York and London, Reuters reported.

GOLDMAN SACHS: Goldman Sachs began laying off employees on Jan. 11 in a sweeping price-cutting generate, with all around a 3rd of individuals impacted coming from the investment decision banking and world markets division, a supply common with the make any difference informed Reuters.

Just in excess of 3,000 personnel will be enable go, the resource, who could not be named, reported on Jan. 9. A different resource confirmed on Jan. 11 that cuts experienced started out.

The prolonged-envisioned careers cull at the Wall Road titan is expected to stand for the most important contraction in headcount since the fiscal disaster.

HSBC: Below force from his greatest shareholder, China’s Ping An Insurance policy Team, to make improvements to income, HSBC Chief Govt Noel Quinn has in new months accelerated strategies to shrink its world-wide empire and streamline its management.

Reuters noted HSBC is shedding at minimum 200 senior professionals as it prunes the ranks of main operating officers it has across an array of country and business enterprise traces.

The lender also announced it is marketing its Canadian enterprise for $10 billion, getting rid of about 4,000 workforce from its wage monthly bill in a stroke. It also introduced on Nov. 30 the sale of its considerably smaller New Zealand business enterprise, and the closure of a more 114 branches in Britain, leaving it with all around a third of the stores it had as lately as 2016.

MORGAN STANLEY: In December, the investment decision financial institution slashed about 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of its workforce, a supply familiar with the company’s plans explained to Reuters. The cuts reportedly have an effect on about 1,600 positions.

Morgan Stanley is generating modest job cuts all over the world, Main Government James Gorman said at the Reuters Following convention on Dec. 1, with no providing quantities.

Reuters had on Nov. 3 described layoffs had been coming at Morgan Stanley, with dealmakers in its Hong Kong and mainland China organizations among the individuals afflicted, as rigid Chinese lockdown principles weighed on activity. Sources explained the cuts would go beyond regular attrition.

WELLS FARGO & CO: The loan company slashed hundreds of jobs in its property finance loan organization throughout the United States, Bloomberg Information noted in December, citing folks familiar with the bank’s options.

“We routinely evaluation and change staffing stages to align with industry ailments and the wants of our businesses,” the lender had reported in an emailed assertion to Reuters at the time, with no giving any specifics on the range of personnel or units affected.

In a tough year for personal finance, what’s normal for debt and saving?

In a tough year for personal finance, what’s normal for debt and saving?

A whole lot of personalized finance exists in an idealized earth exactly where persons keep debt to a strict minimal and acquire a maximal approach to saving and investing.

We have just started a yr the place a lot of folks will compare their have predicaments to the best and feel like they really don’t measure up. Almost nothing very good will appear of this – just annoyance, disgrace and disengagement.

What we have to have is a benchmark exhibiting what is normal in each age team for personal debt, savings and investments and web really worth. Millennials could review their home finance loan stability to other millennials, Gen Xers in their 50s could look at their retirement cost savings with their peers and boomers could evaluate the worth of their tax-absolutely free cost savings accounts.

We system to construct an online tool that will exhibit you all of this in early 2023. To enable us get started off, please fill out the questionnaire that follows. It’s 100 for each cent anonymous – we just want your age bracket and the particulars of what you owe and what you have in price savings and investments.

With these numbers in hand, we will construct a resource that invitations people today to review their own funds to their friends. Come across out what is typical for your age bracket and see how you compare.


Subscribe to Carrick on Cash

Are you studying this e-newsletter on the internet or did a person ahead the e-mail variation to you? If so, you can sign up for Carrick on Income listed here.


Rob’s private finance reading through list

Finest in banking – credit playing cards, savings accounts and a lot more

MoneyGenius announces its 2023 picks in 7 distinctive money types. Value a look if you want to assess the merchandise you by now have, or if you are on the lookout for some thing new. Here’s a list of the finest credit history playing cards, as chosen by Premiums.ca.

Significant interest prices place a different spin on TFSAs

Right before 2022, it was hip to scoff at the plan of trying to keep cost savings in a tax-free of charge personal savings account as opposed to investments. Higher curiosity charges necessarily mean it’s time to reassess TFSAs for price savings.

A letter to youthful traders

An investing blogger writes a note to young buyers just commencing out about the problems he built and the lesson he figured out. His feedback about having abundant swiftly are particularly critical. This website publish was impressed by a similar letter written by World contributor John Heinzl before this 12 months.

Guides for novices

A checklist of the greatest investing publications for beginners, as picked out by the Savvy New Canadians blog. The first two are a excellent put to start understanding about investing. Now for a straightforward, useful guide for rookie buyers.


Inquire Rob

Q: When folks communicate about safe and sound withdrawal charges in retirement and use, say, a figure of 3.8 for every cent, does that imply only money, or dividends furthermore capital? For instance, my complete portfolio throws off about 4 for every cent in dividends, and I commit that. Does that rely as the 3.8 per cent withdrawal?

A: This is a clever concern for the reason that it asks for more element on a widespread concept of retirement planning, which is the percentage of your price savings that can be withdrawn just about every yr without the need of acquiring to stress about working out of income. I appeared at a number of article content on this topic and they’re not exactly distinct about in which the 3.8 for every cent, or no matter what quantity, is meant to occur from. My just take is that you ought to look at the withdrawal on a total return foundation, which suggests dividends, bond fascination and capital combined. In this scenario, the 4 per cent dividend generate covers the withdrawals. A dividend produce of 2 for each cent would necessarily mean that bond curiosity and the proceeds from advertising belongings are desired to make up the relaxation of the once-a-year RRIF withdrawal.

Do you have a issue for me? Send out it my way. Sorry I can not reply every 1 individually. Inquiries and solutions are edited for length and clarity.


Today’s economic software

An introduction to investing from the B.C. Securities Commission, like a seem at Diy investing, applying an expenditure adviser and robo-advisers.


The Dollars-Cost-free Zone

A Seinfeld scene established to songs from the Tv show Twin Peaks. Just as bizarre as you imagined. A tribute to the operate of composer Angelo Badalamenti, who died recently.


Enjoy this

A established of videos masking private finance and investing fundamentals. The movies were being produced by The Chang School at Ryerson University and the Money Customer Agency of Canada with aid from the Ontario Securities Fee.


In circumstance you missed these Globe and Mail own finance-linked stories
  • Do retirees want to fork out for non-public health coverage?
  • Your New Year’s resolutions ought to include things like the 5 pillars of tax scheduling
  • Dwelling with roommates is no extended just for learners or 20-somethings. Canadians’ strained finances are to blame

Additional Rob Carrick and income protection

Subscribe to Pressure Take a look at on Apple podcasts or Spotify. For far more funds stories, follow me on Instagram and Twitter, and join the dialogue on my Facebook webpage. Millennial viewers, sign up for our Gen Y Funds Facebook group.

Even far more protection from Rob Carrick:

‘Get the blend right’ and we can unlock trillions in finance for Global South, say experts

‘Get the blend right’ and we can unlock trillions in finance for Global South, say experts

January 13 – There’s a big black hole in the finances needed for the climate and energy transition.

Spending today (primarily on mitigation) is around $600 billion. Africa alone needs $3 trillion by 2030, and according to the IMF, the world needs between $3 and $£6 trillion a year until 2050. It sounds like a lot, but private investors have the money: they control assets worth some $210 trillion; banks potentially another $200 trillion. How can they be persuaded to spend some of it?

The answer hinges on risk. Low- and middle-income countries are risky propositions for investors, says Chris Clubb, managing director of Convergence Finance, a non-profit set up to increase investment going into those countries to achieve the sustainable development goals. The country risk and currency risk are so high that investors would be failing in their fiduciary duty to pension-holders, shareholders and stakeholders – or be non-compliant with regulations – if they did invest.

But the appetite is there, suggests Clubb, if risk could be reduced to bring it under the barrier. And this is where blended finance comes in: to use public sector finance to reduce the level of risk to something acceptable to private investors.

Groups like the U.N.-convened Net-Zero Asset Owners Alliance, with $10 trillion assets under management, “are saying three things: one, we have the money that we’re looking to invest. Two, we’ve looked at developing countries, and we would like to invest the money there, but the risk is just simply too high for us. And three, if you can, through blended finance, create fiduciary investments, we will be investing.”

Blended finance is not a new idea, but it hasn’t taken off as anticipated after the launch of the U.N. Sustainable Development Goals (SDGs) in 2015. “We are not blending to scale. We are blending small – project by project. And so, we’ve got to break some glass in order to blend more,” Jay Collins, vice chairman of banking, capital markets, and advisory at Citigroup, told an audience at a side event at COP27 in November.

Convergence has tracked more than 700 blended finance deals that have been put together over the past 15 years. Often, says Clubb, only one donor government provides funding, which limits the size of the blended finance vehicle. On average those deals are around $70 million – too small alone to change the landscape.

Bringing governments, multilateral development banks (MDBs) and the private sector together can change that. One example is the Climate Finance Partnership, announced at COP26 by asset manager BlackRock.

Its focus is on renewables, transmission and energy storage infrastructure in Latin America, Asia and Africa.

The fund was oversubscribed, raising $673 million. Of that, $130 million of so-called catalytic funding – a safety buffer to reduce the risk to the private sector – was raised from Japanese, French and German governments, alongside TotalEnergies and philanthropic donors, including Grantham Environmental Trust. The private investors who are protected from the greatest risk committed five times as much – $523 million. The partnership is soon to ink the first deals.

There were a range of pledges made at COP27 in Sharm el-Sheikh. In a five-year partnership with Kenya, the UK government is committing around £13 million to a new guarantee company that will lower the risk for investors and is expected to unlock another £80 million in climate finance for six projects across energy, agriculture and transport.

The clean energy pillar of Egypt’s newly launched Nexus on Food, Water and Energy programme attracted $500 million from international partners, including the United States, Germany and the EU, to accelerate the country’s renewables deployment.

The financing is expected to unlock at least $10 billion in private investment to install 10 gigawatts (GW) of solar and wind energy by 2028 and retire inefficient gas power capacity.

At COP27 a Just Energy Transition Partnership (JET-P) to help Indonesia transition from coal, committed to mobilise $10 billion in public funding from partner governments. Private sector investors, members of the Glasgow Financial Alliance for Net Zero (GFANZ), will raise another $10 billion. This was followed in December by a $15.5bn JET-P package to help Vietnam achieve its clean energy goals, with the private sector committing to match $7.75 billion in public funding.

The agreements built on the $8.5 billion JET-P for South Africa announced in 2021 at COP26.

But compared to what’s required, these projects barely scratch the surface. South Africa’s investment plan, launched a year after the partnership was announced, suggests $98.7 billion will be needed over the next five years to begin the country’s transition from coal. Funding sources have been identified for about half that figure.

At least a third is expected to come from private sources, but observers of the process say donor countries have not used the past year to mobilise the necessary level of concessional finance that would attract the private investment required. Nor have they addressed the huge debt that has been built up by the state-owned power producer, Eskom, which adds to investor risk.

Scale of funding is one issue. What it’s spent on is another. The bulk of climate finance projects – around 90{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} ‒ target mitigation, not adaptation. That’s partly because mitigation projects (such as renewable energy) can generate cash flows to provide returns to investors, whereas adaptation projects generally don’t produce revenues.

Anjali Viswamohanan, policy director at the Asia Investor Group on Climate Change (AIGCC), says much more innovation, time and effort is needed to come up with projects that build resilience and produce returns.

One example could be the building of a seawall around a low-lying area, with an integrated road project that would generate returns, for example from road taxes. “We need to get all stakeholders – not just the private investors – together to think about the adaptation and resilience issue from a systemic level,” says Viswamohanan.

In any case, investors will have to be thinking about the physical risks posed by climate change to the assets they hold, and how to build resilience for them. The AIGCC has urged governments to clearly lay out a financial strategy to underpin national adaptation plans and bring private and philanthropic funders together with government and multilateral development banks to identify co-investment opportunities.

Clubb argues that the multilateral development banks could easily double or triple their finance commitments from $140 billion a year at present and distribute some of the financial exposure to private investors through blended finance.

MDBs who lend to governments for public sector projects (such as climate adaptation) don’t currently mobilise funds from the private sector, while entities such as the International Finance Corp (part of the World Bank group) who do mobilise private funds for private sector projects don’t generate as much investment as they could.

From the perspective of most experts, “the multilateral development banks are the most systemically under-utilised development tool that the development community has,” he adds.

Speaking at COP27, Nick Holder, chief operating officer for Prudential Africa, said he wanted to see the multi- and bilateral development banks expand their activities and scope of financing to provide more capital.

“We’re really looking for greater scale in concessional capital, in supporting blended finance solutions that de-risk investments, not just on a project-by-project basis, (but) on a much larger scale, both to make it easier to invest, and to ensure diversification.”

He described how its support for a $14 million project for solar energy in Vietnam took a relatively large effort in terms of due diligence and looking for certification. “It was a good thing to do, it was the right thing to do, but it’s not yet scalable.”

Convergence, in collaboration with aid agencies and a range of private and philanthropic investors, has put together an action plan for climate and SDG mobilisation to double investment into developing economies to $530 billion. They say the action plan can be implemented within a year, and without additional public sector resources.

“There needs to be a critical mass of funding that can de-risk the investment if we want to invest at scale … and that needs to be allocated to the best global examples, no matter where they come from,” says Clubb.

Crucially, the catalytic funders like MDBs, need to collaborate to create large enough funds to make an impact on climate and SDG goals.

USAID, the international development arm of the U.S. government, which worked on the plan, has agreed to collaborate with the development agencies of the five Nordic governments to establish a financing vehicle to catalyse $1 billion before COP28 next year in the United Arab Emirates.

Reform of the MDBs is high on the international agenda, with the Sharm el-Sheikh Implementation Plan agreed at COP27 calling for them “to define a new vision and commensurate operational model, channels and instruments that are fit for the purpose of adequately addressing the global climate emergency”.

It also emphasises the need for grant-based resources – as opposed to loans – for adaptation and for the least developed countries, something powerfully argued for by Barbados prime minister, Mia Mottley.

Since 2015, says Clubb, “we’ve had two north stars, the Paris Agreement and the U.N. SDGs, that have allowed us to begin to quantify the amount of investment that’s actually required.

A significant challenge is the multilateral development bank and development finance institution system – legacy mandates and processes are not aligned to the speed required or to increasing financial commitments and mobilising private finance. Their shareholders need to reset their compass towards those north stars.”

A lot is riding on the IMF and World Bank spring meetings to find agreement to chart that new course.

Opinions expressed are those of the author. They do not reflect the views of Reuters News, which, under the Trust Principles, is committed to integrity, independence, and freedom from bias. Ethical Corporation Magazine, a part of Reuters Professional, is owned by Thomson Reuters and operates independently of Reuters News.
Disclaimer: The views expressed in this article are those of the author and may not reflect those of Kitco Metals Inc. The author has made every effort to ensure accuracy of information provided; however, neither Kitco Metals Inc. nor the author can guarantee such accuracy. This article is strictly for informational purposes only. It is not a solicitation to make any exchange in commodities, securities or other financial instruments. Kitco Metals Inc. and the author of this article do not accept culpability for losses and/ or damages arising from the use of this publication.