Strong demand for fries boosts Lamb Weston’s outlook

Strong demand for fries boosts Lamb Weston’s outlook

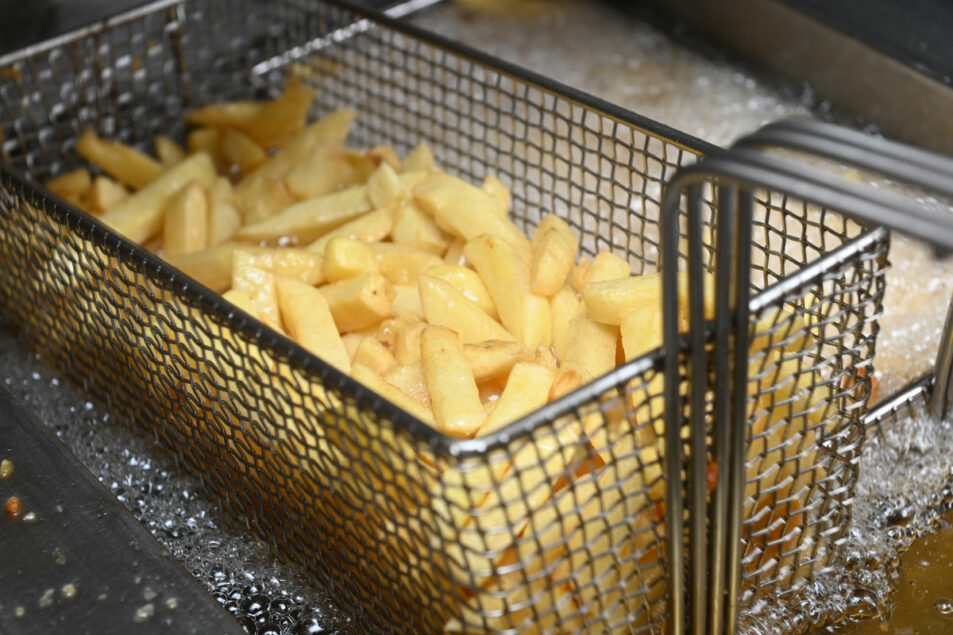
EAGLE, IDAHO — Lamb Weston Holdings, Inc., is benefiting from procedures to counter expense input inflation. Pricing actions and initiatives to strengthen shopper and products blend helped the business deliver document revenue and sturdy earnings in the second quarter, prompting management to enhance its full-year money targets.

Internet revenue for the next quarter ended Nov. 27 was $103 million, equivalent to 72¢ per share on the common inventory, up 217{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from $32.5 million, or 23¢ for every share, in the identical period a yr back. Profits rose to $1.3 billion from $1 billion.

The company now expects complete-year revenue to be in the range of $4.8 billion to $4.9 billion, up from the previous focus on of $4.7 billion to $4.8 billion. It is targeting adjusted internet earnings of $540 million to $580 million, up from the former concentrate on of $360 million to $420 million. Altered diluted earnings per share are anticipated to be in the variety of $3.75 to $4, up from the earlier focus on of $2.45 to $2.85.

Improves in targeted visitors and fry-attachment at speedy-support restaurants (QSRs) drove a 34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} increase in web income for the company’s global section, which consists of the top 100 North American-dependent cafe chain clients and all global profits. Internet revenue for the segment had been $693 million, with pricing actions driving a 31{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} raise in rate/mix. Expansion in worldwide shipments and power in minimal-time solution choices at domestic QSRs drove a 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} raise in quantity.

A year-over-12 months drop in whole-service restaurant visitors had a much more pronounced effects on the company’s foodservice segment, which solutions North American foodservice distributors and prospects generally outside of the leading 100 North American-dependent restaurant chains. Web income for the section increased 14{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $358 million. Rate/blend was up 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} though quantity was down 11{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

Supply chain disruptions on run charges and throughput in the company’s amenities contributed to the decrease in quantity, claimed Thomas P. Werner, president and main executive officer of Lamb Weston.

“These disruptions have largely been connected to the effect of shortages in specific commodities, these as starches and edible oils, as perfectly as manufacturing facility employee shortages and availability,” he reported in the course of a Jan. 5 convention phone with money analysts.

The impression of source chain disruptions also drove a 9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} drop in volume for the company’s retail segment. Product sales of branded and non-public label solutions to retail buyers enhanced 34{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $192 million, with pricing actions driving a 43{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} boost in selling price/mix.

The availability of important commodities and production team members has improved in recent quarters. Still, the issues are most likely to have an effect on volumes for the remainder of the fiscal 12 months, Mr. Werner said.

The enterprise also professional manufacturing constraints just after modifying operating techniques to mirror changes in merchandise and shopper demand from customers, including increased need for retail fries, top quality fries and batter-coated solutions.

“To generate batter-coated fries, we usually operate our strains at slower speeds,” Mr. Werner explained. “This results in reduced throughput. We also involve a lot more frequent and lengthier downtimes to clear and sanitize strains between manufacturing operates when batter is utilised, which has an effect on our run-costs and line availability. With each other, this final results in much less finished kilos developed relative to creating uncoated fries, which ultimately potential customers to stress on shopper buy fill premiums.”

Ongoing commodity shortages, the onboarding of a short while ago hired output team users and changes to running treatments will keep on to strain volume efficiency and the company’s ability to fulfill buyer demand until capability investments in China, Idaho and Argentina become available over the future several years, he included.

Although the excellent of potatoes from final year’s harvest is reliable with historic averages, yields are under Lamb Weston’s preliminary evaluation. To fill its production demands, the business has secured added potatoes in the Columbia Basin and Idaho and is sourcing potatoes from other areas in North America, such as the East Coastline. For next year’s crop, the organization has agreed to a just about 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} raise in deal price ranges for potatoes grown in the Columbia Basin. 

Property insurance rates to keep surging in 2023

Property insurance rates to keep surging in 2023

Business property insurance plan purchasers can be expecting additional fee hikes this 12 months thanks to a confluence of things, with disaster-uncovered and loss-hit accounts bearing the brunt of tightening potential and will increase of 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and larger.

A hard Jan. 1 reinsurance renewal season, in which residence insurers confronted potential constraints and sizeable level hikes, has extra uncertainty in a market place currently hit by Hurricane Ian and other disaster losses and inflation, sector experts say.

Home catastrophe reinsurance rates for reduction-strike U.S. accounts jumped in between 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and 100{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at Jan. 1 renewals, in accordance to a Gallagher Re report issued past 7 days. What the knock-on impact will be for house insurance policyholders this yr remains unclear, brokers stated.

Far more difficult reinsurance treaty renewals and insurance provider and reinsurer worries more than house cat exposures and their price of cash are driving present-day current market ailments, explained Rick Miller, Boston-dependent U.S. residence practice leader at Aon PLC’s industrial danger methods enterprise.

“It’s a bifurcated market place amongst normal disaster-exposed and non-disaster-uncovered organization,” Mr. Miller claimed. Accounts with important wind exposures, primarily in the Southeast, are “extremely challenging,” he explained.

At year-end renewals, some big accounts with Florida exposures purchased lower boundaries than they had purchased previously because of value problems, Mr. Miller stated. “We were being however able to set alongside one another important limit on some Florida bargains, but it was significantly additional challenging,” he mentioned.

The fourth quarter of 2022 was the 20th consecutive quarter of growing prices, based mostly on Aon facts, which is “unprecedented in new heritage,” he mentioned.

Capability is the most significant obstacle, stated Jeff Buyze, Fort Lauderdale, Florida-centered vice president, countrywide residence follow chief at USI Insurance policy Solutions LLC.

“When an incumbent provider pulls back in the present-day line that they’re providing – let’s say they ended up providing $100 million the calendar year prior to, and now they can only provide, say, $5 million or $10 million – which is wherever we are seeing the major charge raises, and the most tricky renewals,” Mr. Buyze said.

The reduction in capability is not just impacting disaster-exposed accounts, Mr. Buyze mentioned. Accounts with a complicated loss background, poor hazard excellent – these kinds of as older body design – and with superb loss regulate suggestions, are observing “the most stress, and the most problem when it will come to capacity and costs,” he reported.

“Traditionally, in this style of market place, you would see new entrants … but the money by itself is not acquiring its way to the reinsurance or the insurance policy market place,” and this cycle is likely to proceed at the very least in the very first six to 10 months of 2023, he mentioned. Fascination in captives and parametric coverages is escalating, he additional.

Catastrophe-exposed residence and non-disaster-uncovered home with inadequate decline heritage or inadequate threat excellent will go on to see rate will increase of 25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} up to 150{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in the 1st half of 2023, unchanged from the end of 2022, USI claimed in a report issued very last 7 days.

Catastrophe-exposed assets with nominal decline historical past and good threat top quality will see charge will increase of concerning 15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, even though assets in non-catastrophic regions with minimum decline background will see premiums up 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, USI explained.

Insurers varied in their quoting at yr-stop renewals, pushed by the traits of the risk and precise geography, said Michael Rouse, New York-dependent U.S. residence exercise chief at Marsh LLC.

“Without a question, the windstorm, hurricane-exposed states like Florida and Louisiana carry on to be a battle, the two from a ability standpoint and pricing, as properly as conditions and problems,” Mr. Rouse reported.

For some much larger house schedules, there had been however bigger charges and tighter conditions and ailments but a more competitive market, he stated. “Outside Florida, charges rose but not always close to the very same diploma. In some scenarios, you could move from carrier A to carrier B to help mitigate premiums,” he reported.

In some situations, policyholders are battling to obtain limitations that they have traditionally, Mr. Rouse explained.

Significant-high quality accounts with superior loss control that are thoroughly valued, reduction-free and not uncovered to catastrophes are viewing both flat fees or possibly slight decreases or slight will increase, explained Peter Fallon, countrywide assets practice chief at brokerage Threat Approaches Co. Inc. in Boston.

Accounts the place residence valuations really don’t accurately mirror the possibility, that have experienced losses or are in catastrophe-exposed spots are having hit hard, he reported.

Following Jan. 1 reinsurance renewals, underwriters have quite a few inquiries more than how reinsurance variations will affect their very own company, he said.

“If the reinsurers are asking for more revenue and building alterations in terms of protection and restrictions, how’s that now going to make its way down to the person insurance firms and then their purchasers?” Mr. Fallon said.

There’s still a ton of uncertainty in the marketplace, and latest responses from insurers implies that price ranges will enhance even if capability stays the exact same, mentioned Christie Weinstein, New York-based director, threat management, at Honeywell International Inc. and a Chance & Insurance plan Administration Society Inc. board director. Honeywell’s assets insurance policy system renews in May possibly.

“As pricing goes up threat professionals are relying extra on brokers to discover unique strategic methods to controlling risk versus real danger transfer,” Ms. Weinstein explained.

“Maybe you can restrict protection or engage in with the way the coverage or limitations are resolved or sublimit specific coverages, alternatively of using a wide-brushed, greater retention,” Ms. Weinstein explained.

Discussions with consumers are altering and there is better target on analytics, reported Kathy Bettencourt, New York-based mostly Northeast property broking leader at Willis Towers Watson PLC.

Just after several several years of fee boosts, lots of policyholders are reevaluating how substantially coverage they require, and whether or not they ought to carry on transferring possibility or commence seeking at risk funding, Ms. Bettencourt claimed.

In phrases of total boundaries “we’re looking at our customers commence to buy significantly less, since they are having the time to consider what they actually need,” she mentioned.


Amazon HR Staffers Turn From Hiring to Seeking Jobs Themselves

Amazon HR Staffers Turn From Hiring to Seeking Jobs Themselves

(Bloomberg) — With job cuts mounting throughout tech, finance and other industries, why wait to get fired when you can skip right to being hired?

Most Browse from Bloomberg

The go, known as “career cushioning,” requires lining up a prepare B when continue to fully utilized, primarily when career cuts are imminent. This is normally finished discreetly — perhaps a networking contact taken throughout lunch, or having the time to connect with previous colleagues.

Some Amazon.com Inc. workers are getting it just one stage further, publicly submitting that they are #OpenToWork on LinkedIn when even now employed by the business. It is all out there for everybody, together with their bosses and bosses’ bosses, to see.

One such Amazonian is Kayla Seem, a recruiting coordinator. In an interview, Glance said her stress was managing higher when layoffs were being declared in November: The holiday seasons ended up coming up, she had just graduated from university the year in advance of and was in the center of preparing a wedding ceremony. The bills and uncertainty were being mounting.

The unease began when the Seattle-primarily based firm froze using the services of a couple months earlier. She thought she could chill out when she survived the initial round of position cuts, but when the enterprise noted it would be slashing 18,000 work opportunities — alternatively than the initial 10,000 — the sensation of relief evaporated.

She knew it was time to be proactive. “It’s been two and a fifty percent months because the get worried of becoming laid off very first started out,” she mentioned. “I’m weary of remaining nervous.” Her managers never know any more than she does, so there’s no one particular to solution her issues, she mentioned.

Amazon says it was a “difficult decision” to do away with work opportunities.

“We really don’t get these conclusions evenly or undervalue how considerably they may well have an impact on the life of individuals who are impacted,” Amazon Main Government Officer Andy Jassy wrote in the most latest observe on the impending cuts, which will be primarily concentrated in its Men and women, Practical experience, and Technologies office. “We are doing work to help all those who are impacted and are giving deals that involve a separation payment, transitional well being insurance policy positive aspects, and exterior position placement assistance.” Amazon declined to remark further more.

When one particular of the supervisors on Look’s crew posted that she was #OpenToWork on LinkedIn very last week, it was like a inexperienced gentle. “She’s 1 of my leaders — I ought to comply with right after her if she doesn’t look self-confident in our odds,” she said. “Because I’m continue to new to the workforce, I felt like if I do this I’m not demonstrating loyalty and hence I’m heading to get slice. But no — it gave me reassurance that it’s ok to seem out for by yourself.”

The banner, which LinkedIn launched in 2020 following Covid-19 strike, has turn into an increasingly popular sight on the platform as layoffs ripple via the tech market.

Even even though she in the end desires to keep at Amazon, Search has been sending out resumes.

Robin Ryan, who is effective as a vocation coach throughout the lake from the e-commerce giant and has endorsed lots of looking to sign up for (or go away) the business, states she sees the posts as a kind of pushback — a way of indicating “‘Hey, I can go somewhere else.’”

At Amazon, which has 1.5 million personnel, the recruiter’s work is challenging: “The churn there is unbelievable. Most of it is quitting, it is a really stress filled area to do the job,” Ryan reported. Recruiters have plenty of roles to fill — lots of of which are really specialized and include in-depth sourcing and rigorous interviews.

Individuals subjected to months of uncertainty are apt to come to feel some measure of resentment, Ryan stated. And like Glance, quite a few in recruiting are entry-level professionals that aren’t paid the monumental salaries acquired by seasoned engineers. Just after hire, car or truck payments and other expenses, they frequently really don’t have substantially left above — building the prospect of losing their position that significantly additional unnerving.

Look’s was 1 of a lot more than 50 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} a dozen #OpenToWork posts from recent Amazon workforce viewed by Bloomberg Information. Other staff members, some of whom acknowledged voluntary buyouts, wrote equivalent messages last month.

“In this case, you are seeking to provide men and women into the firm, and they’ve just kicked you out,” Ryan reported.

Look is hopeful the waiting around match will quickly appear to an conclusion. “They’re supposed to get started sending out letters following week,” she mentioned. “Honestly, I’m psyched for that, for the reason that I’m completely ready to discover out no matter if I’m in this article or not so I can shift on.”

Most Examine from Bloomberg Businessweek

©2023 Bloomberg L.P.

Here Are 5 Finance Apps You Should Try Now

Here Are 5 Finance Apps You Should Try Now
A young businessperson does paperwork in coffee shop and checks their phone.

Image source: Getty Illustrations or photos

The greatest apps can assist you streamline your finances.


Essential factors

  • There are a number of finance apps out there that can support you deal with your income extra simply.
  • These apps can assistance you with budgeting, reducing your credit history card personal debt, investing, and a lot more.

Retaining keep track of of your funds isn’t going to have to be a complicated endeavor. Fortunately we now are living in an period exactly where engineering and finance go hand in hand. From budgeting apps to financial investment monitoring equipment, these valuable apps can preserve you time and money when helping you make more educated fiscal decisions. In this article are some of the finest finance applications readily available right now.

1. For budgeting: Mint

Mint is the number 1 most downloaded own finance application. It helps you monitor your investing, build budgets, and produce a economic program. It calculates your net really worth in true time and even screens your credit score rating. Mint analyzes your investing and provides suggestions on where you can save additional cash as well as support uncover financial savings you skipped, so you can shell out down your credit card debt more rapidly.

The app makes it possible for you to produce customized alerts for payment owing dates, delivers updates on your regular monthly budget, and reveals your progress to assembly your fiscal plans. One of its leading capabilities is its membership management and invoice negotiation services. You can use Mint to cancel subscriptions for you or negotiate payments on your behalf to decreased them. With a 65{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} results amount, Mint’s BillShark has saved associates in excess of $2 million.

2. For maximizing credit score card benefits: MaxRewards

Have numerous credit history playing cards? MaxRewards is an application that aids you deal with all of your credit card points and miles. It can also support you increase benefits from your credit history cards. A person of MaxRewards’ important options is recommending the best credit rating card to use at nearby merchants so you can get paid the most benefits on buys. You can swiftly see the very best credit card to use for just about every investing classification and see all of the gives you qualify for. Credit history playing cards usually present reward rewards and offers that you may well not know about. The app immediately activates them for you so you can make more rewards.

3. For spending down credit card credit card debt: Tally

Tally is a debt payoff application that can help save you up to $4,300 in 7 a long time. Tally consolidates all of your regular credit rating card charges into one particular payment, supporting you simplify the process of lessening your credit rating card credit card debt. After downloading the app, you increase your credit score playing cards. Tally then conducts a gentle credit history check, which will not likely effect your rating, to see if you might be eligible for Tally’s low desire line of credit history. After you are authorised and settle for the present, Tally right away pays off your cards and you pay out Tally back in a single regular monthly invoice. Tally may perhaps be a great alternative if you can make your monthly Tally payments and the interest level presented to you is lessen than the curiosity prices on your credit history playing cards.

4. For energetic traders: WeBull

WeBull is not as very well recognised as some of the major names like Robinhood or TD Ameritrade, but the application presents state-of-the-art resources and capabilities that several other investing apps absence. Both equally the application and desktop edition have state-of-the-art charting abilities, strong screening equipment, in-depth charting, and dozens of complex indicators, all for absolutely free. WeBull has an quick-to-use slick interface and presents you entry to sophisticated orders, as properly as sector data from numerous resources. If you are seeking to trade extra actively, WeBull may perhaps be truly worth thinking of.

5. For passive traders: Acorns

Acorns is an investing app that would make it straightforward to make investments your spare improve into stocks and ETFs with nominal effort. It really is fantastic for those people who want to start investing but do not have the time or awareness. Acorns presents pro-designed diversified portfolios customized to you. The app delivers a number of distinct tiers of services based on your desires, and presents funds again at certain vendors, generating it a great selection for anyone from inexperienced persons to experienced buyers.

You will find no lack of finance applications out there that can enable streamline your funds and make handling them simpler than at any time just before. Whether you’re on the lookout for budgeting tools or automated investing options, you will find an app that suits your requirements properly. With the suitable finance applications in tow, controlling your funds has never ever been easier!

Notify: best funds again card we’ve witnessed now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until eventually 2024

If you’re working with the wrong credit or debit card, it could be costing you serious cash. Our professional enjoys this leading select, which features a 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2024, an crazy income again fee of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all somehow for no annual price. 

In fact, this card is so superior that our skilled even utilizes it personally. Click listed here to study our entire assessment for no cost and utilize in just 2 minutes. 

Read our cost-free assessment

What economists get wrong about personal finance

What economists get wrong about personal finance

In my defence, I didn’t get into economic problems right away soon after finishing my master’s degree in economics. It took months. I had a decently compensated graduate work and was dwelling inside my usually means, so how did it materialize? Easy: I experienced “cleverly” set all my price savings in a 90-day discover account to maximise the desire I attained. When I was shocked by my initial tax bill, I experienced no way of assembly the payment deadline. Oops.

The good thing is, my father was capable to bridge the gap for me. He had no economics education, but 3 many years of more experience had taught him a straightforward lesson: things takes place, so it is ideal to maintain some prepared dollars in reserve if you can. It was not the to start with collision among official economics and the university of life, and it won’t be the very last.

My eye was caught not long ago by James Choi’s scholarly report “Popular Personalized Financial Assistance compared to the Professors”. Choi is a professor of finance at Yale. It’s traditionally a formidably technical willpower, but following Choi agreed to train an undergraduate class in personalized finance, he dipped into the current market of popular financial self-aid books to see what gurus such as Robert Kiyosaki, Suze Orman and Tony Robbins experienced to say on the subject.

Following surveying the 50 most well-known own finance books, Choi located that what the ivory tower recommended was often extremely different to what tens of tens of millions of viewers were becoming instructed by the monetary gurus. There were occasional outbreaks of settlement: most well-liked finance textbooks favour minimal-value passive index resources more than actively managed money, and most economists imagine the same. But Choi found additional distinctions than similarities.

So what are people distinctions? And who’s correct, the gurus or the professors?

The response depends on the guru, of training course. Some are in the company of dangerous get-wealthy-swift techniques, or the energy of beneficial wondering, or scarcely offer any coherent guidance at all. But even the more sensible economical tips books depart strikingly from the ideal options calculated by economists.

Often the well known books are simply incorrect. For illustration, a prevalent declare is that the longer you keep equities, the safer they turn out to be. Not accurate. Equities provide both far more chance and more reward, no matter whether you hold them for weeks or for many years. (Around a long time horizon, they are additional probable to outperform bonds, but they are also additional possible to hit some disaster.) But Choi reckons that there is small hurt accomplished by this error, due to the fact it generates affordable financial investment methods even if the logic is muddled.

But there are other discrepancies that must give the economists some pause. For case in point, the standard financial assistance is that one should really repay higher-desire debts right before much less expensive debts, of training course. But quite a few personal finance guides advise prioritising the smallest money owed 1st as a self-assist life hack: grab these compact wins, say the gurus, and you are going to begin to realise that a route out of credit card debt is possible.

If you think that this makes any sense, it suggests a blind location in the conventional economic advice. Persons make errors: they are subject to temptation, misunderstand pitfalls and prices, and can’t compute sophisticated investment guidelines. Good economical advice will acquire this into account, and ideally defend against the worst errors. (Behavioural economics has lots to say about such faults, but has tended to concentration on policy alternatively than self-help.)

There’s another issue that the common financial guidance tends to get completely wrong: it copes badly with what the veteran economists John Kay and Mervyn King phrase “radical uncertainty” — uncertainty not just about what may possibly transpire, but the types of factors that might materialize.

For illustration, the typical financial assistance is that we ought to smooth intake more than our everyday living cycle, accumulating credit card debt even though youthful, piling up cost savings in prosperous center age, then paying that wealth in retirement. High-quality, but the notion of a “life cycle” lacks creativeness about all the issues that may well come about in a lifetime. People die youthful, go through high-priced divorces, quit very well-paid work opportunities to comply with their passions, inherit tidy sums from rich aunts, acquire unpredicted promotions or endure from long-term ill wellness.

It is not that these are unimaginable outcomes — I just imagined them — but that existence is so unsure that the notion of optimally allocating usage around quite a few many years starts to seem extremely peculiar. The very well-worn economic guidance of conserving 15 for every cent of your profits, no matter what, may be inefficient but has a certain robustness to it.

And there is a final omission from the conventional economic check out of the environment: we may possibly simply squander revenue on factors that do not subject. Lots of economical sages, from the ultra-frugal Financial Independence, Retire Early (Hearth) motion to my possess colleague at the Fiscal Times, Claer Barrett (her reserve What They Do not Instruct You About Funds will hopefully quickly be outselling Kiyosaki), emphasise this pretty standard concept: we shell out mindlessly when we ought to spend mindfully. But though the notion is crucial, there is no way even to categorical it in the language of economics.

My teaching as an economist taught me lots of benefit about dollars, giving me justified self esteem in some spots and justified humility in other folks: I am significantly less possible to tumble for get-rich-swift schemes, and less likely to feel I can outguess the inventory industry. Still my education skipped a great deal too. James Choi justifies credit score for realising that we economists have no monopoly on economical knowledge.

Tim Harford’s new e-book is ‘How to Make the Environment Increase Up’

Observe @FTMag on Twitter to uncover out about our hottest stories initial

Business Beat: Farm business program to resume | Business News

Business Beat: Farm business program to resume | Business News

The Institute for Rural Vitality at SUNY Cobleskill and the Centre for Agricultural Advancement & Entrepreneurship have introduced the 2nd cohort of entrepreneur contributors of SUNY Cobleskill’s USDA-funded Farm and Food Business Accelerator.

Accelerator individuals “will launch new price-included items to the regional marketplace and capitalize on a collective $500,000 expense into solution advancement and enterprise growth” above the future 18 months, as a result of entry to strategic assistance companies and specialist facilities, according to a media launch.

Individuals are selected dependent on their potential for progress and affect on the nearby farm and foods sector, the launch stated. They involve:

• Empty Pockets Ranch, Cobleskill

• King Creek Farms, Delanson

• Previous Homestead Farm, Richfield Springs

• Lovin’ Mama Farm, Amsterdam

• Van-Dale Farms, Central Bridge

• Broadwell Dairy, Carlisle.

The initially accelerator cohort included 9 contributors and introduced in December 2021, the release reported. Considering the fact that then, 21 new goods have been introduced to the neighborhood farm-to-desk market.

“Through the results of our to start with cohort, we have evidence of notion of the transformative potential of this Accelerator program, and its potential to create positive effects for smaller enterprise on an personal scale, and on a bigger scale, the whole regional foodstuff program,” reported Scott Ferguson, executive director of the Institute for Rural Vitality at SUNY Cobleskill. “The members of this up coming cohort clearly show the exact same promise, and we are energized to get underway and once all over again broaden our attain and capabilities by doing work alongside one another and sharing methods.”

Participants will receive entry to expert services and methods from SUNY Cobleskill and CADE, which includes help with new solution improvement from food items science experts, completion of a scheduled method from the Cornell Food items Venture Middle, specialized aid on promoting technique, legal and economical advisory products and services, and outreach aid to create a community of distributors, suppliers and wholesalers, institutions and dining places.

Cohort members also have obtain to SUNY Cobleskill’s on-campus, shared-use amenities, which involve a dairy processing heart, USDA-inspected meat processing facility, commercial kitchens, packaging products, and use of the Carriage House Café & Basic Retail store for conducting retail pilots and marketplace investigation.

The Farm and Food stuff Organization Accelerator is made possible via a $741,271 grant from the USDA Agriculture Innovation Centre. By additional funding from other resources, the program signifies a whole financial investment of $1,121,002, in accordance to the release.