Best paying jobs in finance

Best paying jobs in finance

Do you want to get into the planet of finance and make a wonderful salary? If so, then you really should know that some work in finance fork out significantly well. From banking and investment management to economical advising and accounting, there are a lot of selections for those who have an fascination in the business. In this post, we’ll search at some of the best having to pay employment in finance and how they assess to a person another. With a better being familiar with of these positions, you can make your mind up which profession path is appropriate for you. So let’s get begun!

Investment decision Banker 

Expense bankers assist firms and other entities raise funds by making a portfolio of investments, these as shares and bonds, to maximize returns on their investments. They also recommend companies on mergers and acquisitions, general public offerings, restructuring, and extra. The median base wage for an financial investment banker is $143,000 per 12 months with bonuses ranging up to $100,000 or much more.

Best paying jobs in finance 16

Fiscal Planner 

A financial planner can help people today and firms make sound monetary selections by analyzing their present-day condition and furnishing guidance on budgeting, investments, taxes, retirement arranging, insurance needs, and a lot more. The common base salary for a Money Planner is all-around $90,000 for each yr with bonuses potentially reaching up to $50k or bigger.

Accountant 

Accountants provide essential companies for businesses by aiding them monitor funds accurately though assembly all important regulations. Their tasks consist of analyzing economic documents this sort of as tax returns supplying suggestions on tax implications making ready studies for internal final decision-creating detecting fraud employing new systems checking compliance procedures budgeting hard cash move administration expense manage payroll administration and significantly much more! The common pay back for an Accountant is about $75k for each year together with bonus potentials that vary up to $30k or higher relying on practical experience amount.

Quantitative Analyst/Danger Manager 

A quantitative analyst or danger supervisor takes advantage of sophisticated mathematical products to analyze details to measure possibility associated with investments or other pursuits that include revenue or property. They also build portfolio procedures centered on this investigation to minimize losses from market fluctuations or other styles of pitfalls. This place has an average foundation wage of close to $130k per calendar year with reward potentials likely up to all over $80k relying upon experience degree.

Best paying jobs in finance 17

Auditor 

An auditor evaluates the accuracy of fiscal statements ready by organizations to ensure they comply with applicable guidelines and polices as nicely as company guidelines and methods. This career calls for expertise of accounting idea and concepts as effectively as great organizational capabilities to evaluation advanced documents quickly though searching out for discrepancies or mistakes in accounting documents. The median foundation income for an Auditor is around $70k for every year which includes bonus potentials that can reach up to all around $25k relying on qualifications & knowledge ranges attained in the occupation.

Mergers & Acquisitions Specialist 

Mergers & acquisitions experts help businesses recognize possible acquisition targets as well as regulate the overall process from the beginning right up until the conclude so that corporations can succeed when merging with or getting one more business enterprise entity. The common foundation wage for this posture is close to $170k for each year with reward potentials ranging up to all around $120K dependent upon experience amount in the subject outlined above.

Monetary Analyst/Advisor 

Fiscal analysts examine previous overall performance developments & prospects related to various types of investments like shares & bonds then use this information to produce portfolios customized especially to each individual’s particular demands & goals financially talking. Moreover, this skilled may well also deliver tips concerning taxation, estate setting up, insurance policies coverage, retirement preparing, etcetera hence generating it immensely valuable if anyone needs an over-all see of their funds. According to the Bureau Of Labor Statistics (BLS), Monetary Analysts have an ordinary money amount topping out nearly one particular hundred thousand bucks yearly as well as supplemental payment by way of bonuses which could selection upwards to fifty thousand dollars too!

Best paying jobs in finance 18

Tax Attorney 

Tax lawyers focus in advising customers about authorized concerns associated specifically to taxation issues – like international taxation, federal taxation, condition & local taxes, corporate taxes, etcetera – even though representing them in entrance of governmental authorities must any disputes occur with regards to alleged unpaid amounts because of. Tax attorneys commonly have equally a Juris Doctorate alongside with Master’s Degree (in Taxation) plus added certifications way too. As considerably as earning ability goes, even so – these gurus command huge salaries averaging at the very least one particular hundred 20 thousand pounds yearly according to BLS figures additionally more compensations likely heading outside of fifty thousand bucks also!

Money Controller/CFO 

A economic controller/chief economical officer is dependable for executing all functions associated with the management of an organization’s accounting & fiscal functions. This contains overseeing budgeting, creating strategic options to cut down expenditures & increase profits, carrying out audits on inside files & procedures moreover extra. The regular wage common for this occupation is all-around just one hundred thirty thousand bucks each year per BLS studies with further compensatory possibilities going up toward eighty thousand bucks dependent on the degree of expertise & qualifications gained!

Money Marketplaces Specialist 

 A funds markets expert is liable for facilitating the shopping for and marketing of securities for consumers. This job involves superb analytical and issue-solving abilities as effectively as an in-depth being familiar with of fiscal marketplaces, investments, and possibility management. These pros commonly have a foundation salary of about $145k for every calendar year with bonuses likely achieving up to $100k or far more depending upon experience level & skills.

Best paying jobs in finance 19

Coverage Underwriter 

Insurance policy underwriters assess the pitfalls involved with insurance policy insurance policies and decide irrespective of whether to approve or deny purposes based mostly on their examination. They have to be capable to assess complicated information sets quickly, identify opportunity pitfalls and make sound conclusions to safeguard equally the consumer and the insurance provider from losses. The median foundation income for this placement is close to $74k for every calendar year like bonus potentials that can go up to all over $30k dependent upon skills attained & expertise in the career.

Portfolio Manager 

A portfolio supervisor allows purchasers to control their investments by deciding on proper stocks, bonds, and other safety instruments that healthy their needs though checking the general performance of individuals assets in excess of time to maximize returns even though reducing chance. This occupation gives a excellent income with an regular base spend of about $120k for each yr moreover reward potentials achieving up to all-around $70K depending on qualifications & working experience concentrations attained in the discipline.

Money Solutions Representative 

A economical services consultant interacts straight with consumers to guide them in handling their funds by giving tips associated to budgeting, savings methods, retirement setting up, insurance policies coverage selections & additional. This task may possibly need particular licenses & certifications but normally presents a competitive foundation wage of about $65K per calendar year furthermore reward chances ranging up to $35K relying on skills acquired!

Best paying jobs in finance 20

Expense Advisor/Consultant 

Financial commitment advisors present guidance related to financial investment portfolios usually tailor-made towards personal customers’ chance profiles & goals monetarily speaking when also encouraging them navigate by unique forms of investment decision goods offered in today’s marketplaces. The normal foundation salary for this career is close to one particular hundred thousand dollars on a yearly basis in addition bonus potentials topping out around fifty thousand dollars way too!!

Actuary 

An actuary quantifies economical hazards linked to foreseeable future activities these kinds of as life insurance coverage guidelines, annuities, pension ideas etcetera – then employs mathematical models & statistical methods to predict probabilities of these events taking place even though altering pricing structures accordingly when required hence encouraging organizations stay successful with no assuming way too significantly danger. According to BLS figures – actuaries have an typical base fork out level of approximately one particular hundred forty-five thousand dollars each year additionally added compensation opportunities likely upwards towards eighty thousand bucks way too!

Economic Compliance Officer 

Fiscal compliance officers make sure that corporations keep on being compliant with all applicable rules – restrictions – standards etcetera pertaining particularly to finance, taxation, securities transactions, banking operations etcetera. These pros have to have both equally excellent know-how about different regulations along with sharp analytical capabilities so as to kind out any discrepancies or violations mentioned. The median shell out level for this occupation is generally all over ninety-5 thousand dollars yearly as well as additional compensatory packages ranging up in direction of fifty thousand pounds way too!

Best paying jobs in finance 21

Spending plan Analyst/Manager 

Price range analysts/supervisors enable create extensive-term organizational budgets alongside with annually targets by analyzing existing expenses as opposed to projected earnings streams and then utilizing charge regulate actions where by relevant in order make sure profitability without the need of sacrificing quality provider shipping or aims set forth. Commonly talking – this occupation features a fairly generous earnings amount averaging 1 hundred 20-5 thousand dollars annually according to BLS information additionally supplemental payment potentials likely past seventy-five thousand dollars !!

Credit rating Analyst 

Credit analysts look at purchaser credit rating histories in advance of granting loans or opening lines of credit rating so as to decide if they are probably equipped or eager to repay borrowed amounts when owing. As section of their evaluation method, they also assessment existing financial circumstances together with own information as provided by candidates them selves so as assess overall creditworthiness precisely. The median base wage for Credit score Analysts commonly hovers just underneath seventy-five thousand pounds per year such as bonus compensations which may potentially achieve 30-5 thousand dollars or higher based on qualifications attained within the discipline stated over!


Private Banker/Prosperity Manager

Non-public bankers/wealth administrators operate largely with superior web worthy of people providing suggestions about asset allocation tactics, estate preparing concerns, tax issues etcetera – all developed to improve prosperity accumulation whilst mitigating in opposition to any financial losses thanks to both current market fluctuations, lousy investment decision decisions etcetera. This posture normally has an average foundation wage around a single hundred twenty-5 thousand pounds annually as well as supplemental payment prospects topping out just about seventy-five thousand bucks based on instruction level accomplished & many years worked inside said occupation!

Best paying jobs in finance 22

Business Banker 

Commercial bankers supply banking products and services this kind of as accepting deposits, making loans, and presenting overdraft protection services all aimed at supporting businesses mature successfully without having having too much pitfalls economically talking. Their obligations also contain reviewing financial loan purposes approving credit lines location phrases making ready files checking progress taking care of shopper accounts conducting audits producing experiences & extra so they should have both equally fantastic selection-building abilities additionally encounter about banking functions also. According to BLS – Business Bankers have an common base wage of close to eighty thousand bucks yearly, with reward potentials likely up to close to forty thousand pounds depending upon skills & encounter degrees attained in the occupation.

The economical sector gives great chances for those people who are eager to put in the effort and commitment required. From auditors and money analysts to actuaries, budget supervisors, professional bankers, and additional – this subject has a wide variety of roles offered with aggressive salaries and bonus potentials that can reach up to six figures relying on skills & experience ranges attained.

Finance Industry Veteran Jennifer Palmer Launches Asset-Based Lending Company: JPalmer Collective

Finance Industry Veteran Jennifer Palmer Launches Asset-Based Lending Company: JPalmer Collective

Company Specializes in Custom made Funding Options for Females-Led and All-natural Merchandise Companies

NEW YORK , March 8, 2023 /PRNewswire/ — On International Women’s Day, SFNet president and previous CEO of Gerber Finance and eCapital ABL, Jennifer Palmer, is saying the formation of JPalmer Collective. The asset-dependent lending company will provide custom-made financing answers with white-glove, consultative providers built to enable organizations improve sustainably and founders to retain their fairness.

JPalmer Collective

JPalmer Collective

The company will focus in large-growth companies that do not healthy classic lenders’ criteria, such as gals-led organizations and client brands centered on mindful consumers, sustainability and inclusivity.

“JPalmer Collective was created to fund business owners focused on sustainably enhancing our environment and to offer equivalent access to business funding for females,” said Jennifer Palmer, founder and CEO of JPalmer Collective. “Even though coincidental, the start timing is great: the theme of Global Women’s Day this calendar year is ’embrace equity,’ and we’re accomplishing just that by leveling the enjoying subject in funding. Additional than half of our portfolio will be gals-led companies.”

With 16 decades of expertise in the business finance field, Palmer has served fund the advancement of many beloved and productive girls-led and purely natural products brands, together with Stasher, Infant Gourmand and Coola. She is joined by Melissa Fleishman as COO, a finance veteran with 25 a long time of asset-primarily based lending expertise acknowledged as a distinguished chief in the marketplace by the Secured Finance Network, and Laura Newman as CFO, a CPA who has used her job in the accounting and economic expert services industries on Wall Street and in Massive 4 accounting. The firm is headquartered in New York.

A doing work mother to four girls, Palmer is a female entrepreneur with deep finance field experience who is dedicated to encouraging guarantee that the long term of funding is female-inclusive. She is the latest president of the Secured Finance Network (SFNet) and a identified leader in the finance industry.

About JPalmer Collective

JPalmer Collective is a custom-made asset-based lending alternatives provider established in 2023 by Jennifer Palmer, professional finance veteran, president of SFNet and an advocate for bettering women’s entry to funding. Developed to fund superior-growth corporations that do not healthy the traditional lender’s criteria, the organization offers white-glove provider with a consultative tactic to women of all ages-led organizations and client models centered on mindful shoppers, sustainability and inclusivity so they can obtain sustainable growth.

Media Speak to: Barbara Marks, barbramarkspr@gmail.com

Cision

Cision

Look at primary content to download multimedia:https://www.prnewswire.com/information-releases/finance-market-veteran-jennifer-palmer-launches-asset-primarily based-lending-corporation-jpalmer-collective-301765330.html

Supply JPalmer Collective

Food Entrepreneur Template | Food Business News

Food Entrepreneur Template | Food Business News

Food Entrepreneur SAN FRANCISCO — Boba, the chewy tapioca pearls historically served in bubble tea, is popping up in a wide range of programs, which include parfaits, pastries and pizzas shared on social media.
“We think bobas are the new sprinkles,” explained Olivia Chen, co-founder and main advertising officer Twrl Milk Tea.

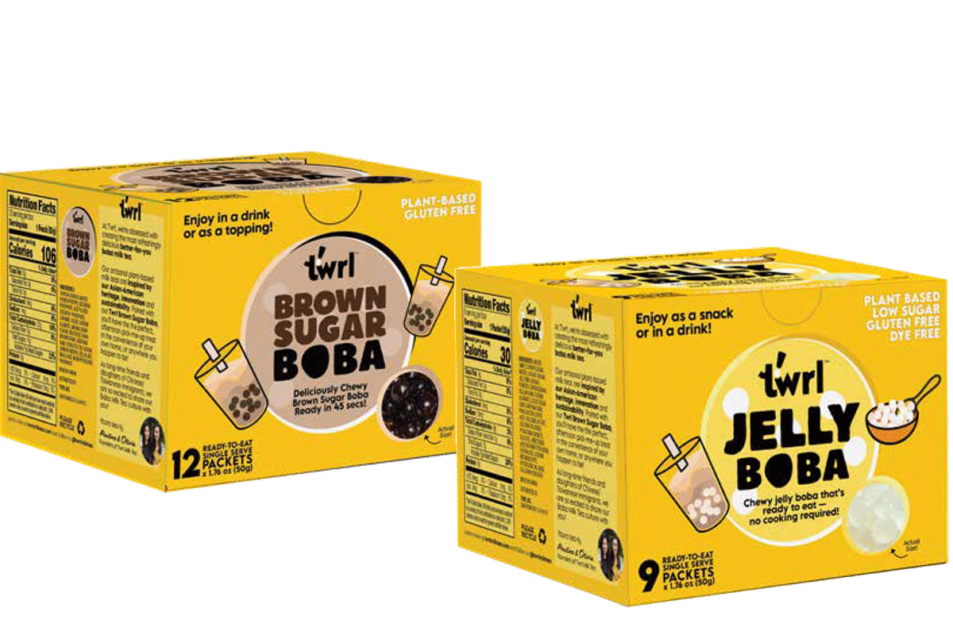
The San Francisco-dependent brand name of canned plant-primarily based lattes, is rolling out boba toppings. Two possibilities, packaged in single-provide packets, contain brown sugar boba that may perhaps be prepared in the microwave or on the stovetop in much less than a minute, and jelly boba, a lessen-calorie different produced with konjac, which is translucent and ready to eat, with a slight lychee taste, Ms. Chen reported.

“Not all bobas are the exact same,” Ms. Chen claimed. “We analyzed a large amount. It took us a yr to really come across the correct co-packer to operate with to carry this to sector.”

The brand’s main product or service line, a plant-based mostly twist on the popular Taiwanese beverage, debuted two years back and is sold on-line and in specialty marketplaces, universities and corporate places of work throughout the nation, Ms. Chen reported. The prepared-to-consume natural lattes have natural and organic tea sourced from China and Japan, plus pea milk and a touch of natural blue agave syrup. The drinks are infused with nitrogen, which provides a foamy texture. Flavors consist of primary black milk tea, supreme jasmine milk tea and hojicha roasted environmentally friendly milk tea. An additional offering is established to sign up for the lineup this Could.

Pauline Ang, co-founder and main government officer, many many years back commenced experimenting in her house kitchen area to produce the formulations, testing much more than 20 dairy alternatives prior to landing on the pea-centered milk, a sustainable possibility with a neutral taste, in accordance to the organization.

Ms. Chen, a longtime marketing executive with earlier stints at Estee Lauder and Clinique, said the addition of packaged boba expands the brand’s existence in retail shops.

“Our method is serving to us build a lot more model awareness and capturing a small little bit of that boba tradition,” she reported.

Gen Z is credited for fueling a modern boba increase in the United States. The worldwide bubble tea market place is forecast to access $4.4 billion in 2027, according to Allie Current market Study. In new several years, mainstream restaurant chains like Dunkin’ and Sonic Drive-In have tapped into the craze, featuring drinks with “bursting” or “popping bubbles.” Many packaged food items manufacturers, like Del Monte Foodstuff and BobaBam, have brought boba to grocery cabinets, far too.

“For us, we really needed to give our customer base a little something they could believe in that is aspect of who we are,” Ms. Chen stated. “I’m Taiwanese American. Pauline is Chinese American. We know what we want in a boba, in plant-based mostly milk tea or in milk tea in typical.” 

Experiencing this content material? Study about a lot more disruptive startups on the Food items Entrepreneur webpage.

Negotiating early with insurers key to captive success: Experts

Negotiating early with insurers key to captive success: Experts

RANCHO MIRAGE, California – Chance professionals with captive programs need to have to negotiate early with insurance policies marketplaces and collaborate with their provider companions, specialists say.

“You can never ever have adequate details,” reported Jennifer Guidry, Hartford, Connecticut-based mostly division vice president of enterprise development and marketing and advertising-option marketplaces at Terrific American Insurance policy Team through a panel session Monday at the Captive Insurance policies Companies Affiliation 2023 Global Conference.

Captive administrators want to negotiate early on and focus on making ready and knowing how their insurance company companions are structured, Ms. Guidry claimed.

Collaborating with many others to understand how they are structured is “a vital piece of vital details,” for the reason that in that negotiation process “it’s heading to play out in terms of how they look at pricing charges and their price framework, which is obviously essential to you,” she mentioned.

As captive administrators are putting together their captive, coverages and advisers, asking inquiries to figure out if insurer partners have the item filings they require is also significant, Ms. Guidry reported.

Fantastic dialogue begins with collaboration, explained Adriana Scherzinger, Chicago-centered vice president, head of captive revenue and execution, U.S. national accounts and center market place, at Zurich North America.

It’s critical that insurers take into account the limitations, claims historical past and danger mitigation variables the captive and consumer have carried out, alongside with any changes in the regulatory ecosystem, she said.

“We appear at money details, the financial dangers of the guardian firm and the economic dangers of the captive. This is definitely integral with credit rating hazard decisions,” Ms. Scherzinger mentioned.

Timing is “a keystone” for negotiating in the captive space, claimed David Raymond, vice president of specialty team captives at The Tourists Cos. Inc. in Hartford, Connecticut.

Negotiating with captive consumers is a great deal additional akin to a family than a enterprise romantic relationship, he mentioned.

“You can have negotiations with your partner and you can depart the place and not be happy with that negotiation, but you are anticipated to occur back again into the room at some level,” Mr. Raymond reported.

“That imagined course of action of how am I coming into this discussion actually drives the relaxation of the conversation. If you really don’t prepare for that you are going to be woefully underrepresented in your possess place,” he reported.

Trust and active listening are also essential, to be absolutely sure that consumers get what they need, he said.

Observing insurers as partners that are doing the job with you is critical, Ms. Guidry claimed.

“I’ve had situations when distinct captive proprietors have occur in and have conceptually experienced an thought they required to put with each other. We were able to engage with them as a associate by bringing in knowledge,” she said.

Creating partnerships with insurers, with their fronting arrangements and brokerage team all enjoy a purpose in encouraging make sure that chance managers do a superior work with their captive and for their group, stated Theresa Severson, Aurora, Illinois-centered vice president, insurance policies and hazard, at Kite Realty Team, who moderated the session.


Trends for 2023 Report by

Trends for 2023 Report by


Nashville, Tenn., March 02, 2023 (Globe NEWSWIRE) — The year 2022 was a roller coaster for numerous Us residents. Growing grocery rates, greater gas fees, typical inflation, and anxieties of an economic economic downturn caused Americans to battle monetarily, in accordance to The Condition of Personalized Finance: Developments for 2023 Report published by Ramsey Alternatives. Around the final two yrs, Americans who documented their finances as “in crisis” or “struggling” improved by 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Though budgets seemed to have gotten tighter, only 4 in 10 People in america felt optimism about their money potential.  
 
One of the most significant difficulties claimed by People was the increasing value of everyday bills. The amount of persons who noted trouble spending payments enhanced by 42{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} above the last two decades, with an raise of 37{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in issue offering meals for their spouse and children.  
 
“My individual funds are somewhat higher than common,” said a 33-year-previous survey participant. “The climbing value of inflation in America, nevertheless, has substantially impacted my household’s every month funds. Leisure routines aren’t a priority at the moment.” 
 
However down from their peaks in quarter two of 2022, day-to-day get worried and misplaced sleep since of own funds are even now impacting thousands and thousands of individuals as we head into 2023. People today with debt worry a lot more than those with out credit card debt (64{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, respectively), the review finds. The examine also located 71{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of individuals earning considerably less than $50,000 a 12 months for their house money documented they be concerned each day. And 37{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of men and women generating above $100,000 a year for their house cash flow get worried every single solitary day about their funds. 
 
“This report shows there is no golden selection for a yearly salary,” stated Jade Warshaw, Ramsey Character and financial debt elimination qualified. “How a lot revenue you make isn’t the problem. It is how you take care of the cash you have. Your money is your most important wealth-making resource, and if you’re providing it away in financial debt payments each and every thirty day period, you will hardly ever get forward. Now is the time to make a approach for your money so you can have a better fiscal foundation months and years from now.” 
 
Other crucial conclusions:  

  • Additional than 1 in 3 People earning around $100,000 for their residence income documented residing paycheck to paycheck. 
  • Millennials are the generation that problems the most, with 67{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} noting they get worried each day.  
  • Americans concur it is vital to invest time every single working day handling their cash but admit they never do what they need to do with their cash.  
  • Only 50 percent of People in america said they have $1,000 in price savings.  

About The Condition of Private Finance | The Point out of Private Finance analyze is a quarterly study examine carried out by Ramsey Methods to obtain an comprehension of the particular finance behaviors and attitudes of Us citizens. The nationally agent sample was fielded employing a third-get together investigate panel. Considering that January 2021, The Point out of Particular Finance has noticed 8,081 U.S. grown ups participate in the review.  
 

About Ramsey Options | Ramsey Solutions exists for the people today outdoors its walls, empowering them in the areas of revenue, business enterprise, leadership, profession and mental wellness. By way of its multimedia platforms, Ramsey Alternatives shares everyday living-modifying information with tens of millions of people today each and every working day. Ramsey Solutions’ products and solutions and environment-class speakers and authors carry hope to folks in every stage of lifetime. Ramsey Options has over 1,100 workforce associates who are fully commited to implementing biblically centered ideas to carrying out operate that matters. For a lot more information and facts, visit ramseysolutions.com. 
 

Trends for 2023 Report by                    

Too Many Employees Cash Out Their 401(k)s When Leaving a Job

Too Many Employees Cash Out Their 401(k)s When Leaving a Job

Statistically, you will very likely transform work various occasions just before retiring. In fact, a Pew Study study approximated that 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of American staff changed careers in 2022 by yourself, most for better spend. But carrying out so can be treacherous for your capability to retire when you want and with the life style you want. Why? Since way too many folks money out their whole 401(k)s whey they go away a career — and companies do very little to avoid it.

In accordance to Vanguard details from 2021, the median 401(k) account for a 55- to 64-calendar year-old was $89,716. That won’t take a middle-course individual incredibly considerably, even with spouse retirement savings, Social Security, and other sources of retirement profits. These reduced balances arise despite an elevated emphasis from businesses, the fiscal products and services sector, and private finance gurus on helping staff accumulate retirement price savings by employer-sponsored retirement strategies. Quite a few firms now have generous match premiums aimed to attract and retain the ideal personnel and to assure economic stability in retirement.

Having said that, the concentrate on cost savings accumulation through work misses a critical fact: In the U.S., workforce can funds out at any time they are functioning or when they go away a job. Between created economies, only the U.S. enables firms to current this alternative to a departing personnel. Workers also fork out money tax, and for withdrawals before age 59.5, they’ll fork out 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in penalties.

Way too usually, departing personnel funds out their 401(k)s when they modify work, dissipating all that they saved while operating. Handful of employers see this as a dilemma. But just about no final decision an personnel helps make can so undercut retirement preparedness.

Why and When Individuals Cash Out Their 401(k)s

To far better comprehend how prevalent 401(k) funds outs are when anyone leaves a career, our the latest investigate examined 162,360 exiting staff in the U.S. covered by 28 retirement programs. They left their companies in a 3-yr period of time in advance of Covid-19, from 2014 to 2016.

Shockingly, 41.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of personnel cashed out 401(k) discounts on the way out the door. Equally astonishing was that 85{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of people who did income out drained the full harmony.

Did they require to? It is hard to know for sure, but it is by no suggests a sensible summary that cashing out is a great or vital response to leaving or getting rid of a career. We see this equally in our investigate and in far more modern info. For instance, we estimated that only 27.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the personnel we studied had lost their work opportunities (as opposed to leaving voluntarily). And other nations call for numerous months of unemployment and proof of obvious hardship right before letting a person to faucet described contribution retirement price savings.

Additional, in the U.S., market scientific studies clearly show that cashing out stayed flat or marginally declined throughout the Covid pandemic inspite of substantial raises in career decline. How did all these new waves of unemployed folks cope? They relied on a mixture of short-term life-style alterations, gig get the job done, and govt added benefits, heeding calls like that from Carrie Schwab-Pomerantz, the president of the Charles Schwab Basis, who counseled individuals to stay clear of utilizing peaceful rules on withdrawals through the pandemic underneath the CARES act:

“Even if it is attainable to borrow from your 401(k) or consider a distribution … take into account this a final vacation resort. When existing conditions could be difficult, I’d counsel any one to steer clear of jeopardizing their upcoming retirement except unquestionably important. You may well not respect the complete outcomes until substantially afterwards.”

The 41.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} money-out figure at work exit in our facts also dwarfed the selection cashing out through their decades of work. Whilst used, men and women experienced a good deal of possibilities to have a money crunch from instances like partner occupation decline, health care emergencies, weddings to strategy, impending school payments, and they faced the similar taxes and penalties for early withdrawal. However only 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} cashed out by way of hardship withdrawal and 3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} via 401(k) loans that have been not repaid on time. We calculated that dollar losses to funds outs at job change have been 12.4 situations what these 162,360 workers cashed out all through their regular 6.6 many years at their corporations.

So why do so numerous people today hard cash out at a occupation transform specially and undermine their retirement stability? Why not roll their 401(k) harmony to an IRA or a Roth or Roth IRA, keep income in their employers’ programs, or transfer assets to new employers’ plans if readily available?

The complications occur from paperwork and psychology. Employers delegate all conversation when an personnel leaves to money expert services corporations like Fidelity, Vanguard, TIAA, or Alight, who administer their plans. These plans send out anodyne form letters to workforce with information about what their solutions are, but not advice. In addition, the form letter, by regulation, enables employers to give much less beautiful options to exiting workers if they have decrease balances. For case in point:

  • Most personnel with balances much less than $1,000 are automatically issued a check of their personal savings minus cash flow tax and 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} penalties, with no other choices offered.
  • Most employees with balances amongst $1,000 and $5,000 are specified two other solutions to cashing out: to roll about belongings into a experienced IRA or to transfer to a new employer’s approach.
  • Most staff with balances about $5,000 are given 3 alternatives to cashing out: to continue to keep their dollars in the present system, to roll in excess of assets into a skilled IRA, or to transfer to a new employer’s prepare.

Critically, these kind letters make the option to income out much additional front-of-thoughts than it was all through many years of employment. They change psychologically illiquid retirement savings into a supply of completely ready funds. When exiting workers are nudged to think about the option to money out, it results in being very attractive to commit what had previously been noticed as an untouchable supply of retirement security. No marvel so numerous extra hard cash out when changing careers than when doing the job.

We also locate individuals act on that temptation to hard cash out far more strongly when they contributed proportionally fewer to their complete 401(k) harmony — keeping continuous the dimensions of the stability and other personnel traits. We simply call this pattern the “account composition result.”

The pattern we observed was the exact same for personnel with higher or lower 401(k) balances, higher or lower cash flow, adult males or women, more mature or youthful workforce, and these who remaining the business in months with substantial or lower turnover. All advised, the much more the balance arrived from the employer, the more persons take care of their financial savings as “house money” or “free money” when prompted at work modify to take into consideration the possibility to money out.

How Companies Can Help Departing Workforce

The lesson from our findings is not that businesses really should contribute significantly less in employer matches. The lesson is that a socially dependable employer ought to spend awareness to personnel when they are leaving the business, much too. Companies with more generous retirement matches definitely intend to provide for staff monetary effectively-staying years down the street. And most know that lots of of their present-day staff will alter work opportunities — various occasions — before their eventual retirement. Employers’ indifference to money-outs is undermining their investment in their employees’ futures. Right now, cashing out is the path of the very least resistance. People choose what is effortless, not what is clever.

Employers could choose ways to significantly increase employees’ retirement protection at a very reduced price tag to them. For illustration, there is escalating recognition that cashing out is far more probably if people today absence unexpected emergency price savings. The new Secure 2. Act that turned law in December 2022 will allow personnel to quickly allocate up to $2,500 for every 12 months to pay out for crisis expenses without the need of raiding their retirement fund. When onboarding new staff and detailing retirement gains, businesses could inspire use of these accounts and forewarn new employees of the risk cashing out at the level they later on change careers.

Companies could also agreement with their fiscal providers associates to give World wide web-enabled “just-in-time money education” all over preserving retirement balances during a occupation improve, or shell out for a session with a economical advisor. Equally, employers could fork out economic expert services companies to conduct an exit meeting to assistance individual personnel appraise if they must preserve their property in their present-day system, transfer property to their new employers’ approach, or have their 401(k) equilibrium routinely transferred to extremely lower-price tag Roth IRA index cash. All of these possibilities maintain staff retirement safety and avoid 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} penalties — and all of these possibilities must be a lot easier than cashing out.

Alongside these very same lines, we suggest that firms halt instantly cashing out workers with little balances. There are some emerging strategies to make this simpler for example, a new “auto-portability” initiative by Retirement Clearinghouse automates the approach of transferring balances underneath $5,000 from the present employer to the new employer’s program if equally employer prepare sponsors are served by big economic companies corporations like Vanguard, Alight, and Fidelity.

If marketplace does not solve this dilemma of retirement cost savings getting drained at task alter, neither businesses nor money company companies may like what will come subsequent. Governments might phase in to develop new devices additional like those in other sections of the globe, like Australia. There, all firms should lead the very same amount, all workers need to contribute the similar total, and the account stays with staff members when they modify work opportunities — and workforce are not able to obtain their balance until just after extended unemployment.

We assume the extra probable scenario is that organizations clear up the trouble, with businesses functioning with money providers corporations to make smaller changes with spectacular opportunity to adjust staff retirement readiness. There are huge rewards to the companies in a aggressive industry for talent and to monetary providers firms who consider the direct in resolving this urgent societal problem.