How to Achieve All Your Financial and Career Goals

How to Achieve All Your Financial and Career Goals

Views expressed by Entrepreneur contributors are their own.

Did you know that in the early 1900s, only 6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of married women worked outside the house the home? It wasn’t till the Very first Earth War that women of all ages joined the workforce in masses, only since adult males had been essential in the armed forces. Fast forward to a century afterwards, ladies currently stand for 58.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the workforce and 35{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of senior leadership positions. More than that century, women of all ages have experienced to get the job done twice as hard to triumph in the place of work.

Growing up, I was taught that performing challenging was the only way to get in advance. For some time, all I was targeted on was function, operate, function. There was no time to unplug or disconnect. Operate-lifestyle harmony did not exist. If I required to succeed, I had to give each ounce of myself to my vocation. I under no circumstances stopped wondering that I could get in advance although however acquiring a lifetime.

Currently, girls are putting their time into a lot more than just do the job. They are prioritizing not only their professions but also their families and hobbies. Almost two-thirds of respondents of a study of women below 30 explained they would be extra eager to progress in their occupations if they saw senior leaders with the operate-existence balance they preferred. It is really not about choosing a single or the other but obtaining the appropriate stability for each of us. So how can you achieve the ideal stability without having sacrificing your financial goals?

Linked: Get the job done-Daily life Harmony Is Uncomplicated. To Thrive at Function, Get a Existence.

1. Spending budget your time

Effective time administration qualified prospects to extra productivity, significantly less anxiety and a lot more results. Time administration is a little something I have expended my life perfecting and go on to do so. By handling your time proficiently, you can work toward your goals, have time for on your own and appreciate the things you like without having shedding track of your priorities.

Start off by making a everyday agenda. Include things like all factors operate and individual. A visible illustration of your working day will help you stay clear of wandering into other tasks. Understand to prioritize and established time boundaries. Some things won’t be able to be still left for the next day, so make certain they are at the leading of your to-do checklist. When needed, make sure to mute notifications on your cell phone and computer system so you can make certain that you are not acquiring distracted. Schedule any casual meetings or contact bases through your commute to be certain that you might be maximizing your time.

Lastly, and most likely the most complicated detail for me is generating time to unplug and really accomplishing it! A great deal of the time, we go to watch Television or expend time with our relatives, and we aren’t totally current simply because our intellect is nevertheless at perform. A component of function-daily life stability is studying when to shut down your performing mind. I uncover that when I can control my time proficiently, I can unplug at the end of the working day mainly because I acquired everything I had to when I planned to. Incorporating young children and partner time to the agenda is not undesirable because it exhibits you are prioritizing them!

Related: You are Not Crunched for Time, You are Just Making These 8 Time-Administration Errors

2. Spending plan your finances

We all have financial milestones we hope to realize. It could possibly be paying off your pupil loans, getting a house or saving for retirement. What ever your ambitions, you really don’t have to make millions to accomplish them. It is not automatically about how a great deal you make but how disciplined you are with your funds. In accordance to PYMNTS.com, about 45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of people creating extra than $100,000 say they stay paycheck to paycheck, 47{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of these generating among $150,000 and $200,000, and 28{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of those people earning above $200,000 are also residing paycheck to paycheck.

Regretably, many thanks to inflation and the soaring price tag of items, our cash does not go as much as it used to. To ensure that you’re dwelling inside your usually means, commencing by setting up a spending plan is important. Obtaining a visual finances will also support you see wherever your income is heading and wherever you ought to minimize again on or make investments extra. Your price range is never established in stone, so modify when required. The moment you have an first system that will work for you, stick with it. Utilizing automated withdrawals from your paycheck will assist you save with no even noticing.

It really is essential not just to help save your money but to mature it. Not at ease with investing? Uncover a financial advisor to help you commence or learn about it you. Program some time in your working day to even further your know-how. Generally, persons miss out on the option to make investments due to the fact they worry it may possibly be too “dangerous.” But it is only a sizeable hazard if we do not understand it.

Related: 10 Techniques You Ought to Commit Your Company’s 1st Income

When you take the time to teach oneself on it, you can make informed selections lowering the risk involved. So, browse a reserve, hear to a podcast or subscribe to a publication – there are loads of sources out there.

Never overlook out on the chance to spend your money and achieve fiscal flexibility. Immediately after all, economic flexibility means you are going to be in a position to invest extra of your time determining what to do alternatively of emotion burdened by any obligations to continue to be in a career you are not taking pleasure in.

The days when women experienced to decide on concerning their occupations and loved ones are lengthy gone. When it will never be easy, you can have the best of both worlds. Accomplishing the best operate-existence balance whilst continue to operating in direction of monetary independence is doable with the suitable amount of money of self-discipline.
Governor Lamont Announces Global Atlantic Financial Group Is Expanding Operations and Adding Jobs in Hartford

Governor Lamont Announces Global Atlantic Financial Group Is Expanding Operations and Adding Jobs in Hartford

Push Releases

Governor Ned Lamont

&#13
01/09/2023

Governor Lamont Announces International Atlantic Financial Team Is Expanding Functions and Including Work opportunities in Hartford

(HARTFORD, CT) – Governor Ned Lamont today introduced that International Atlantic Monetary Team, a leading insurance policies enterprise assembly the retirement and existence insurance plan demands of folks and establishments, is developing its functions in Hartford in an expansion approach that incorporates leasing an extra 11,500 sq. toes of office area to help around 100 new staff.

With this addition, World Atlantic will now occupy the entire 10th and 24th floors of The Gold Setting up at One Financial Plaza in downtown Hartford. This is the second time that Global Atlantic has expanded its footprint in Connecticut’s money metropolis – the to start with was in 2019 right after it moved into The Gold Developing in 2018. The firm will now have a complete footprint of a lot more than 46,000 sq. ft in the constructing with the means to assistance far more than 300 personnel.

“Since relocating to downtown Hartford four many years in the past, World-wide Atlantic has observed a sizeable progress in its organization and its work stages,” Governor Lamont explained. “Now, as this renowned coverage firm that has places of work all through the state is hunting for a spot to broaden, they’ve made the decision that Hartford is the ideal put to guidance this advancement. I congratulate Worldwide Atlantic on their choice to commit and improve here, and I appear ahead to strengthening our partnership with this firm for years to arrive.”

In 2022, World-wide Atlantic grew its whole employee foundation by 325 employees. This consists of the addition of 75 new personnel in Hartford, which represents the finest concentration of progress among the its places of work.

“The enlargement of our existence in Hartford, one particular of the leading insurance coverage marketplaces in the United States, is a testament to Global Atlantic’s growth and situation within the insurance industry,” Dan O’Shea, chief administrative officer for International Atlantic, stated. “We are happy to continue on increasing in a state with such a various talent pool and vibrant community and value the assist of the Connecticut Office of Financial and Community Growth.”

The Connecticut Department of Economic and Community Growth (DECD) is supporting the enlargement by offering up to $695,640 in grants in arrears that are contingent on the business making and retaining 100 comprehensive-time work over seven several years.

“Global Atlantic is a valued member of our business enterprise group, and it is excellent to see them expanding their physical footprint and continuing to include careers in our money town,” Alexandra Daum, commissioner designate of DECD, and Peter Denious, CEO of the nonprofit economic enhancement organization AdvanceCT, reported in a joint statement. “Connecticut’s insurance coverage sector is acknowledged about the planet for its proficient workforce, foremost providers, and dedication to innovation. Announcements like this a single enhance our aggressive strengths in this sector and the truth that Connecticut is dwelling to the premier insurance policy sector cluster in North America.”

World Atlantic Fiscal Team is a foremost insurance enterprise conference the retirement and daily life coverage demands of folks and establishments. With a strong money basis and possibility and investment management skills, the enterprise provides tailored methods to build extra safe financial futures. The company’s general performance has been driven by its culture and main values targeted on integrity, teamwork, and the relevance of setting up lengthy-expression customer associations. World-wide Atlantic is a the greater part-owned subsidiary of KKR, a foremost world wide investment agency. By its romance, the firm leverages KKR’s investment abilities, scale, and entry to cash markets to improve the value it presents purchasers. KKR’s father or mother corporation is KKR & Co. Inc. (NYSE: KKR).

&#13

Twitter: @GovNedLamont

&#13

Facebook: Place of work of Governor Ned Lamont

&#13
&#13

Financial Actions Speak Louder Than Resolutions | Business News

Financial Actions Speak Louder Than Resolutions | Business News

If financial resolutions are intentions — “I want to help you save a lot more cash this yr” — then financial plans are a far more precise purpose — “I system to cut discretionary expending by 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} just about every month.” 

Money actions are the true actions you consider to make progress — “I will log in and cancel any subscription provider I haven’t utilized in the earlier 30 days.”

The aim is the expendable piece of that system, says Peter Bregman, executive mentor and CEO of Bregman Associates, an govt coaching organization.

As a coach, he can help leaders emphasis on what is actually essential. He claims folks usually overlook the intention of the improve they want to make due to the fact it is considered to be implicit. That can guide to tunnel eyesight and inflexibility on distinct targets. 

Skip goals, and go suitable from intention to action, he suggests.

Let us say your fiscal intention (call it a resolution) for 2023 is to spend much less dollars and pay off financial debt. Say it out loud to another person who’ll hear, claims Bobbi Rebell, licensed money planner and creator of “Launching Financial Grownups.” Now, with a feeling of way and accountability, you can make revenue moves, no goals needed.

Cash go 1: Appear at the quantities

Get a modern paycheck and a piece of paper, or get extravagant with a absolutely free spending plan planner. Generate your every month, after-tax cash flow at the major, then listing our your fiscal obligations, states Rebell. Think rent, utilities, groceries, baby treatment, transportation and any other costs and debt you have to shell out no subject what.

Subtract people crucial charges from your month-to-month earnings. The dollars that remains is what you have for discretionary expenses and preserving. 

“It’s typically not as terrible as you assumed,” suggests Rebell. This exercise tends to uncover that a lot of expenses are discretionary, she claims.

Use bank and credit score card applications to tally up all the other scattered shelling out. From there, you can in all probability find a number of points to lower. If you are not absolutely sure exactly where to get started, acquire the budgetary ax to a streaming service. You may well be shocked at the joy it provides. 

Money transfer 2: Make it more challenging to acquire items on the internet

Debit playing cards, credit playing cards, funds apps and electronic wallets make expending pain-free on the entrance close. The uninteresting ache hits later however when the charges are because of, especially if you have a credit card equilibrium.

It is time to make purchasing inconvenient. Delete retailer apps, unsubscribe from their mailing lists and remove stored credit history playing cards from browsers and internet websites, states Rebell. It may perhaps audio trivial, but accomplishing so adds friction to the buy process. You will almost certainly feel 2 times about that new pair of shoes if you have to seize a credit card and hand jam the numbers into your telephone at checkout. 

“It’s in essence a modern-day version of ‘freeze your credit rating card in the ice dice,’” she states. And certainly, the virtually frozen credit card is a detail.

Income go 3: Select an solution to spend down personal debt

Just take a different glimpse at your list of obligations and target on the financial debt this time. Observe the quantity you owe and curiosity fee for any money borrowed. Believe items like a vehicle payment, pupil financial loans or a balance carried on a credit rating card. Now, decide on a prioritization method. 

Take into account applying a debt snowball or credit card debt avalanche technique to pay off what you owe. With financial debt snowball, you emphasis on your smallest balances first, and hope to rack up brief wins as you near out financial loans. 

With credit card debt avalanche, you prioritize financial loans with better curiosity rates to wipe out the most high priced credit card debt very first. Credit history card costs are a excellent spot to commence with personal debt avalanche thanks to exorbitant APRs. 

Both equally techniques have benefit. The significant stage is to select a path and make the 1st move.

New yr, new economical you

If plans are what get you from position A to B, then by all implies, established them. But do not enable location percentage targets keep you back again from basic steps that enable you attain manage of your funds.   

The smaller steps genuinely can make a big impression, suggests Rebell. “Do what you can, and do not be also really hard on your self.” 

Teenager Promotes Financial Literacy in Youth with Personal Finance Education

Teenager Promotes Financial Literacy in Youth with Personal Finance Education
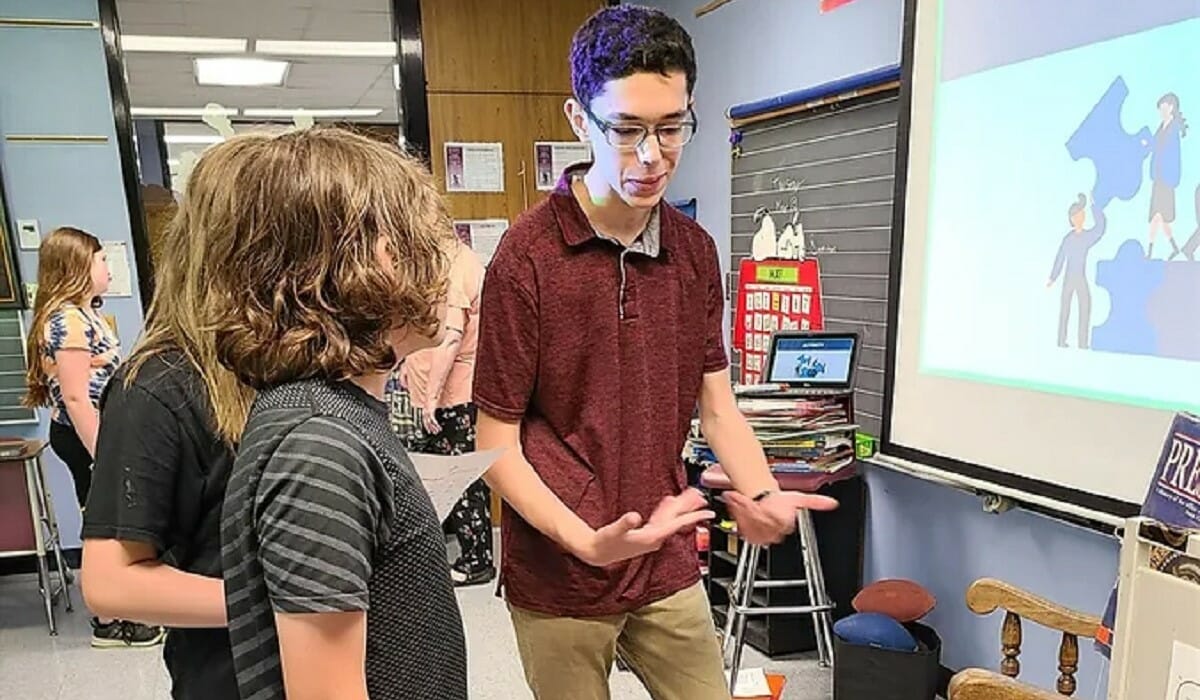
Isaac explains a economical concept to a young learner./Courtesy Isaac Hertenstein

Meet up with Daily Place of Gentle Award honoree Isaac Hertenstein. Examine his story and nominate an remarkable volunteer or family members as a Every day Place of Light-weight.

A lot of adults go away school and are stunned to uncover out how difficult taxes can be and don’t understand matters like how to commit in the stock market. Many thanks to Isaac Hertenstein, pupils in Greencastle, Indiana and further than are graduating with a bigger amount of financial literacy than at any time ahead of.  

You never see many superior schoolers with a fiery passion for personalized finance, but Isaac, a sixteen-year-outdated runner and ethics enthusiast, breaks the mildew. Even in center college, his center university know-how and entrepreneurship trainer, Brittany Labhart, remembers observing his curiosity peaking. 

“I saw in sixth and seventh [grade] that he was unquestionably interested in it, but in eighth quality I observed a substantial alter. Which is when we talk about small business and own finance,” she remembers. “He is an wonderful kid who has been driven from a pretty younger age” 

The pretty following calendar year, Isaac resolved to share the understanding he found so intriguing with other folks. So, as a freshman in significant school, he formed his 501(c)(3), Pupils Educating Finance. 

“A large amount of inspiration for Pupils Instructing Finance (STF) was from observing the financial inequality in my neighborhood and the influence of monetary literacy in combatting that as nicely as mending a hole in training,” Isaac suggests. “Indiana is not 1 of the 15 states that necessitates monetary literacy [as part of the curriculum].”  

The states with the necessity commonly require learners to get at minimum a person semester of own finance in purchase to graduate from superior school. With this is head, Isaac took motion. Initially, he delved into dialogue with numerous local community leaders and economic and education and learning specialists. Then, he designed a 30-site curriculum for students from kindergarten by eighth quality with the mission to provide a foundation for results and to motivate young ones to look at economic professions. He also hopes to start discussions in between learners in the classroom and at residence. 

How does it operate? Isaac recruits volunteers amongst his peers to teach quick Lights Classes, just about every concentrating on an age-ideal core notion. Given that he started Pupils Instructing Finance, Isaac has taught around 575 college students in his hometown and has all over 30 volunteers teaching on a common foundation. These classes—and their teachers—leave lasting impressions.

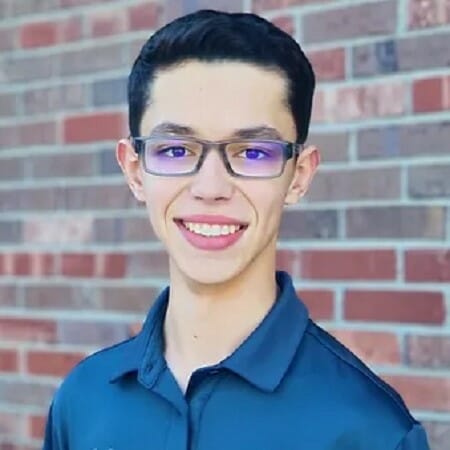
Isaac Hertenstein, founder of Pupils Training Finance./Courtesy Isaac Hertenstein

“He begun off by inquiring them if they’d alternatively have so substantially revenue right now as opposed to so considerably in 10 several years, and he described how compound desire operates,” Brittany states of a lesson Isaac taught in her classroom. “It surely sparked dialogue afterward, and pupils had been definitely intrigued in what he experienced to say.” 

Moms and dads can frequently be listened to telling volunteers that their children have been chatting about the classes for months afterward. Academics are also acquiring in line to implement his lessons on their own. Soon after functioning with Isaac for on STF for the past two years, the economics trainer at his large faculty applied his lessons in her curriculum for seniors. 

And the enthusiasm is creating its way all over the place. 

“I’ve labored with over 250 other volunteers about the place in 14 diverse states who have applied this curriculum and commenced chapters of Learners Instructing Finance in their communities,” Isaac suggests proudly. “ I’m attempting to unfold economic literacy and commence chapters in other superior colleges. Of system, just one of our primary ambitions is advocating for financial literacy legislation.” 

Aiming to have a systemic effect, Isaac and STF has been in talks with several advocacy teams marketing fiscal literacy laws in Indiana.  

“In this article in Putnam County, we have a fairly superior poverty price, and to instruct youngsters at all ranges the worth of own finance with basic ideas that it’s possible they are not receiving at residence, he can support them to make clever selections in the potential,” Natalie states. 

Isaac cites that developmental researchers have proven that young ones begin forming a financial mentality at age five. 

“They observe quite a few of the fiscal expending and saving behavior that their dad and mom and people today bordering have them, and they subconsciously undertake all those practices,” he states. 

Isaac hopes his courses and emphasizing the time worth of revenue will aid get ready people kids as they get more mature and deal with economical issues like paying for faculty and retirement. Sad to say, not anyone is so fortunate. 

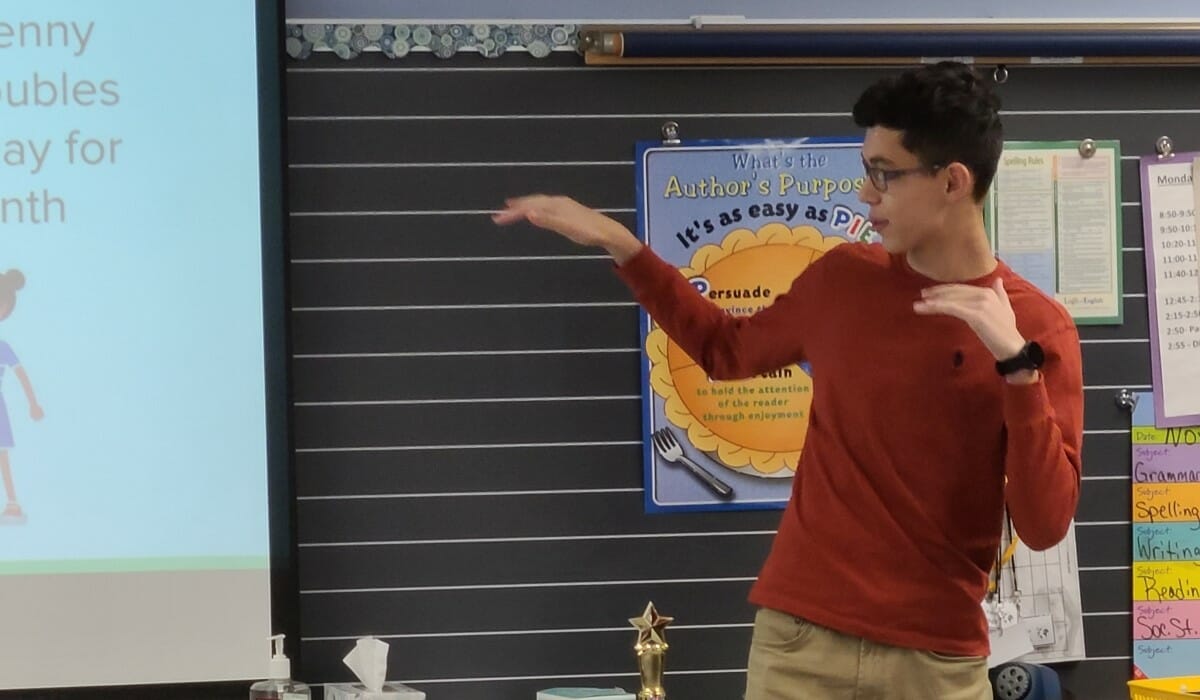
Isaac prospects a class on finance./Courtesy Isaac Hertenstein

“In accordance to a research from UPenn Wharton, which arrived out about 5 yrs ago, one particular-thirs of economic inequality is prompted by–not just joined to–differences in monetary literacy,” he cites. “Financial disparities and expertise definitely catalyze a substantial big difference in economic output and effects in the pretty conclusion. A great deal of it has to do with financial sector inclusion and setting up up belongings in excess of time.” 

Impressed by his mom, a very first-grade teacher who styles the minds that will have favourable influence on the long term, Isaac is pretty forward-wondering. As he seeks to build a vocation at the level exactly where ethics, small business, and social effect blend, he typically thinks of the potential of his business. He hopes to grow STF’s attain by teaming up with FinPro Entire world, a company that results in on the internet discovering courses for middle to higher university-aged students, as nicely as recruit more faculty-aged volunteers to educate.  

“72{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of mother and father do not talk to their youngsters about money.” Isaac suggests. “Finance is from time to time a taboo matter, but it is these an vital principle that lots of men and women disregard when meeting other people, and if they have been to examine it, it would actually just catalyze a lot more finding out for all people.“ 

Do you want to make a big difference in your group like Isaac? Come across area volunteer prospects. 

North Miami Funk Fest mixes Rick Ross with financial literacy community event

North Miami Funk Fest mixes Rick Ross with financial literacy community event

North

South Florida rapper RIck Ross performs all through Jazz in the Gardens at Difficult Rock Stadium Arena in Miami Gardens, Florida, on Sunday, March 13, 2022.

dvarela@miamiherald.com

Songs and private finance commonly really don’t go alongside one another. To be sure, they are kind of a funky combine.

However, the North Miami’s Neighborhood Redevelopment Agency made the decision to team with Funk Fest Songs Tour, showcasing Miami rapper Rick Ross and Mary J. Blige who will execute here this weekend at Funk Fest, to provide Miami people with a no cost group discussion board Wednesday to aid them increase their economic health.

The fifty percent-working day Monetary Literacy Summit will attribute panel discussions on making generational wealth and girls in genuine estate.

Selection Enjoyment CEO and Funk Fest Audio Tour founder Leo Burnett assume it’s significant to capitalize on the notice the event has acquired, due to headliners this sort of as Blige and Ross, by incorporating an instructional discussion board that can contribute to closing the wealth gap amongst white and Black residents in Miami.

“I had a vision of making an attempt to create other academic activities all over leisure,” Burnett explained. “We want to master to improve in other elements. Enjoyment is fantastic, but we also have to have to do anything with the local community that can advantage absolutely everyone that wants to go to.”

Florida indigenous Dr. Natasha Hampton is the govt producer of the fiscal party. Citing a 2019 Miami Herald report about Miami-Dade County’s wealth hole that confirmed the median internet well worth of Black homes to be $3,700 in comparison to $107,000 for white homes, she mentioned it’s vital to exhibit Black people how to establish generational wealth.

“That’s an extraordinary disparity,” she said, chatting additional about the figures in the posting. “It’s probably that the important Black ethnic groups are Haitian American and African American in Miami-Dade. We have some perform to do. We surely understand the need for greater employment, but which is just the start out, not the conclusion-all. … You don’t have to be a six determine earner to make prosperity.”

Burnett thinks big activities like this weekend’s Funk Fest present a unique possibility to get information to inhabitants that can considerably profit from it. Honored at the economic literacy summit at Miami-Dade County Good & Expo Heart for their neighborhood accomplishments will be OneUnited Financial institution CEO Teri Williams, Miami entertainment mogul Luther “Uncle Luke” Campbell and Ross, the Miami rapper and entrepreneur, and county Mayor Daniella Levine Cava.

“Let’s modify the frame of mind on what generational prosperity is,” Burnett mentioned. “It does not have to be the property you move down from a few generations.”

The financial literary discussion board will be held from 8 a.m. till 12:30 p.m. at 1600 NE 126th St. in North Miami. While the Funk Fest site shows the discussion board is bought out, organizers said no person who exhibits up will be turned absent.

This story was at first printed December 27, 2022 4:10 PM.

Profile Image of Michael Butler

Michael Butler writes about the residential and business authentic estate industry and traits in the neighborhood housing current market. Just like Miami’s numerous population, Butler, a Temple College graduate, has both of those area roots and a Panamanian heritage.

5 Smart Financial Goals for 30-Year-Olds

5 Smart Financial Goals for 30-Year-Olds
A woman working on her laptop by a window in her home.

Image supply: Getty Photographs

Your 30s are the time to begin producing moves fiscally.


Key points

  • To make the most of your 30s, look for means to maximize your profits, and attempt to save at the very least 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of what you earn.
  • Consider care of any significant-curiosity debt that’s holding you back and operate on getting a credit rating rating of at least 760.
  • Preserving 1 year’s salary is a common advice for 30-12 months-olds and a superior intention to set for on your own.

As you enter your 30s, which is normally when issues start off trending up fiscally. You may uncover yourself earning additional funds than you did when you ended up young, getting additional established in your profession, and remaining equipped to create your price savings.

Because your circumstance has modified, your ambitions need to, as properly. If your 20s have been about laying a foundation, the up coming decade is all about development and putting you in a comfy placement heading ahead. To attain that, right here are 5 personal finance targets for 30-year-olds.

1. Increase your income

Ideally, your earning likely improves as you get older. You have a lot more encounter, and you develop extra abilities. That is why your biggest priority in your 30s need to be to increase your money. Set reasonable but ambitious aims, like earning yet another $5,000 to $10,000 upcoming 12 months.

The very best way to do this is going to rely on your skillset and your present work situation. In this article are some various options to contemplate:

  • Allow your employer know that you want a increase and inquire what you can do to advance.
  • Try out career browsing to see if you could get a larger salary from a new employer.
  • Start out a tiny company or start out performing for your self as a freelancer.
  • Examine out aspect hustles that could match your routine and assist you provide in added revenue.

2. Pay off high-desire personal debt

Saving funds although you have substantial-curiosity financial debt is type of like managing a 5K with ankle weights. Guaranteed, you can do it, but it really is going to be much more durable. These monthly financial debt payments cut into what you can put toward your cost savings objectives and retirement.

Where a good deal of individuals have difficulty is credit rating card personal debt, considering the fact that it really is effortless to overspend with credit history cards. If which is an problem for you, concentrate on having out of credit card debt and averting it likely forward. And if you have any other credit card debt with substantial desire fees, like payday loans, make absolutely sure to assault people, also.

Minimal-interest debt typically isn’t really a massive offer. If you have a reasonable auto financial loan or a mortgage, you never want to shell out those off ASAP — although you can if you want.

3. Preserve just one year’s salary

A lot of private finance professionals advocate saving at minimum a person year’s income by the time you might be 30. If you make $50,000 for each year, then your target would be $50,000.

To clarify, this does not mean you require all that money in just your cost savings account. You can involve the dollars in all the financial institution accounts, retirement plans, and brokerage accounts you have.

This can be a complicated intention, and a great deal of 30-12 months-olds you should not have a year’s income saved. If you are not there nonetheless, make it one particular of your monetary ambitions to strike throughout your 30s. You’re likely to need to have a number of situations your once-a-year wage to be at ease in retirement. Just one year’s salary is a great beginning place you can develop on.

4. Get a credit score score of at minimum 760

Your credit score score is a evaluate of your credit history worthiness, or how probable you are to repay cash you borrow. The sort of rating that is most commonly employed by loan companies is your FICO® Rating, and it truly is on a scale of 300 to 850.

There are rather a couple benefits of a higher credit score rating. The perk that may possibly be particularly critical to you at this phase of life is that your credit rating rating determines your property finance loan fee. If you’re planning to purchase a household, improving upon your credit history rating could conserve you $10,000 or much more more than the lifetime of a mortgage.

Consumers with a FICO® Rating of at minimum 760 get the lowest home loan fees, so that is a great target to aim for. Even if you do not strategy to get a house, your credit history rating could also make it less complicated to get permitted for an apartment and open a single of the major credit rating cards, between many other fiscal perks.

5. Help you save 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your money

Preserving dollars constantly will allow you to be ready for huge expenses and set dollars away for retirement. When you were being in your 20s, saving 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your income might not have been possible. Money’s generally tight in that age bracket.

In your 30s, it’s really vital that you conserve a good chunk of your earnings. You don’t want to enjoy catch-up with your retirement personal savings in your 40s and 50s. It’s stressful, and when you are nearer to retirement, your cash has fewer time to increase. That usually means you need to have to preserve even additional than you would’ve if you experienced began now.

Begin saving at minimum 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your cash flow if you are not already. If you can help you save additional, that is even superior. As far as where by to set that revenue, divide it concerning your savings and your retirement accounts. You can do an even break up or weigh it extra closely toward just one or the other, based on your latest priorities.

Your 30s could be a 10 years of enjoyable economic developments. Obtaining the objectives shown above will enable you stay on monitor and put you in a excellent placement for the many years to arrive.

Notify: maximum cash back card we have found now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR right up until 2024

If you might be utilizing the wrong credit history or debit card, it could be costing you severe income. Our professional loves this prime choose, which features a 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2024, an crazy dollars back price of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all in some way for no annual cost. 

In actuality, this card is so good that our expert even works by using it personally. Click in this article to read our comprehensive critique for absolutely free and implement in just 2 minutes. 

Read our free of charge overview