SAN FRANCISCO (KGO) — The new travel restrictions announced Thursday may be just the beginning of tightened rules — not only in the United States, but other countries too. If you’re traveling in the next few weeks, especially abroad, experts say be ready for more limits, even border closures that can disrupt your trip.
So will travel insurance cover you?
This may be a time to get some insurance. There are specific COVID-19 policies that cover everything from a potential quarantine, to medical expenses to canceled tours. And with the new rule requiring a negative test result within 24 hours to come back home, experts say plan now.
RELATED: How omicron COVID-19 variant is changing holiday travel plans
Globetrotters were just beginning to come out of isolation, when the new variant brought a fresh set of travel restrictions. And experts say be ready for even more rules during the holiday travel rush ahead.
Travel insurance CEO Omar Kaywan says some countries may enact new restrictions, or even close borders if the new variant spreads.
“We are walking into the next six weeks of complete uncertainty. There’s a lot of last-minute decisions that are being made, a lot of restrictions are being put in place by many countries,” he says.
VIDEO: Travelers react to ‘stress’ of new omicron variant, possibility of new restrictions
New rules already require passengers to show a negative COVID test within 24 hours of their flight back to the U.S.
“This is something that they need to plan, and they need to start as soon as possible, wherever their destination is to book their appointments ASAP, because this is a requirement. and you will not be essentially getting on a plane coming back home, if you don’t have your proof of negative COVID-19 test,” Kaywan says.
A positive result could mean being stranded overseas in quarantine. Border restrictions may mean losing money for tours, lodging and transportation.
However, many companies offer specific COVID-19 travel insurance.
If you’re going overseas, check for policies that cover:
Expenses in case you are quarantined
Medical coverage if you get sick from COVID
Cancelations for lodging, tours transportation and airfare
Finally, look for policies that let you cancel for any reason, such as not wanting to travel during a COVID surge.
“From what we’ve seen in the last couple days people are continuing with their travel plans and they’ll see how it goes and what it’s going to end up being,” Kaywan says.
One thing that’s still to be announced: what type of rapid test will be acceptable within that 24-hour window. 7 On Your Side will keep checking so you’re ready if you’re traveling over the holidays.
Take a look at more stories and videos by Michael Finney and 7 On Your Side.
Have a question for Michael and the 7 On Your Side team? Fill out the form HERE!7OYS’s consumer hotline is a free consumer mediation service for those in the San Francisco Bay Area. We assist individuals with consumer-related issues; we cannot assist on cases between businesses, or cases involving family law, criminal matters, landlord/tenant disputes, labor issues, or medical issues. Please review our FAQ here. As a part of our process in assisting you, it is necessary that we contact the company / agency you are writing about. If you do not wish us to contact them, please let us know right away, as it will affect our ability to work on your case. Due to the high volume of emails we receive, please allow 3-5 business days for a response.
Michelin-starred chef Marcus Wareing said there have never been more jobs available in the restaurant industry as he backed our Christmas appeal to help upskill unemployed youngsters to get them into the workplace.
The Masterchef judge said the large number of vacancies in hospitality offered opportunities, but “the key is knowing how to get those jobs”.
He added: “Because of Brexit there are more vacancies than ever. I have never, ever, ever seen a time like the staff shortage we have now. Every single chef, every single manager and every single hotelier is saying exactly the same thing.”
Mr Wareing was speaking at Marcus, his restaurant in the Berkeley Hotel in Knightsbridge, as he met the latest cohort of unemployed people being trained by Springboard, an organisation that helps young people be “work ready” for careers in the hospitality industry.
Springboard is one of the charities we are funding in our £1 million Skill Up Step Up campaign in partnership with Barclays LifeSkills. The new recruits were on a three-week course that will culminate with interviews for jobs with catering company Compass.
Mr Wareing, 51, gave a rousing speech to encourage them, and revealed that his son, a student at Durham University, has chosen to work in McDonald’s rather than in the Marcus kitchen. He said: “Do you know what McDonald’s gives you? It gives you a career…my son went there because he wanted life skills, he wanted to see a different side.”
Referring to his kitchen at Marcus, he said: “This here is posh, this is luxury, that kitchen is a Formula One car, it’s the crème de la crème of kitchens. Not all kitchens are like that. I worked hard to build that kitchen, it didn’t just arrive here. I had to pay for it and build it. I started off in the lowest kitchens.”
Referring to staff shortages, he said restaurants had started poaching staff and paying “humungous” amounts of money for people to work for them. Others are having to open for fewer hours to enable them to keep running.
Springboard recruit Chisom Thomas, 19, said he was surprised to hear Mr Wareing’s son had turned down the Marcus kitchen for McDonald’s. But Mr Wareing said “from a job offer and career point of view, they offer a lot”.
He spoke about the importance of working hard, describing himself as “a young man from Southport who worked hard at his career. That’s it. I don’t believe I am gifted, I just worked hard at an industry and a job that I absolutely love.” He said the recruits would have no reason not to have a job once they had completed the Springboard course, telling them: “There’s a job for everyone somewhere, you just have to go and find it. Don’t be afraid to bang on those doors. I have a daughter and two sons and I say exactly the same to them.” Temi, 27, who hopes to become a pastry chef, said Mr Wareing’s encouragement was exactly what she wanted to hear after being rejected from several jobs. “I needed that, I really did.”
Bokuma Ebengo, 34, a carer who studied health and social care management, said she, too, was inspired. “Cooking is my passion,” she said. The mother of two wants to become a chef.
Mr Wareing emphasised the importance of continuing to learn throughout adult life, saying: “I still have a lot of food I want to learn, a lot of flavours I haven’t tasted and a lot of people I want to meet. I am excited about the future.”
As the recruits left his restaurant, it was obvious they were just as excited, now they are being helped by Springboard.
WASHINGTON — Lawmakers of both parties came out swinging in a hearing on Wednesday with Adam Mosseri, the head of Instagram, expressing deep skepticism and anger toward the company for not doing enough to protect young users.
In a hearing held by a Senate subcommittee on consumer protection, lawmakers grilled Mr. Mosseri on internal research leaked by a whistle-blower that showed Instagram had a toxic effect on some teenagers. They pressed him to commit to share data with researchers on algorithmic ranking systems and to support legislation for stronger privacy and security protections for children online.
Even Instagram’s announcements this week on new safety tools for children were too little and too late, they said.
“Facebook’s own researchers have been warning management, including yourself, Mr. Mosseri, for years,” said Senator Richard Blumenthal, Democrat of Connecticut and chairman of the subcommittee. “Parents are asking, what is Congress doing to protect our kids and the resounding bipartisan message from this committee is that legislation is coming. We can’t rely on self-policing.”
The hearing is part of a growing effort in Washington to rein in the power of Silicon Valley’s biggest companies. Antitrust regulators are seeking to break up Google and Meta, the parent company of Facebook and Instagram, and lawmakers have introduced dozens of data privacy, speech and competition bills.
Calls for legislative changes have intensified in recent weeks, after a whistle-blower at Facebook leaked internal research that said Instagram led one out of three teenagers to feel worse about their body image and for as many as 16 percent of some teenagers in Britain to have thoughts of suicide. The documents obtained by the whistle-blower, Frances Haugen, often contradicted public statements made by Meta officials, who have long underplayed or rebutted criticism that Instagram harms the mental and emotional well-being of younger users.
“You better tell the truth,” Senator Amy Klobuchar, a Democrat of Minnesota, told Mr. Mosseri. “You’re under oath.”
Mr. Mosseri, 38, was appearing before Congress for the first time. He is a longtime executive at Facebook and is considered a close lieutenant of the company’s chief executive, Mark Zuckerberg. He joined the company in 2008 as a designer and gradually rose in the ranks to run the News Feed, a central feature of the Facebook app. In October 2018, he was named head of Instagram, weeks after the sudden resignations of the app’s founders, Kevin Systrom and Mike Krieger.
He told lawmakers that Instagram often had a positive role in the lives of teenagers, such as by helping them establish connections during difficult times. He tried to direct attention at rivals, noting that more teenagers use TikTok and YouTube. He also acknowledged the skepticism among members of Congress toward Meta.
“I recognize that many in this room have deep reservations about our company,” Mr. Mosseri said. “But I want to assure you that we do have the same goal. We all want teens to be safe online.”
On Tuesday, Instagram announced new safety features for children. Mr. Mosseri mentioned those changes in the hearing, which include tools like a “take a break” function that is meant to help limit time spent online. (TikTok has a similar function that appears when users are spending too much time on the app.)
But Senator Marsha Blackburn of Tennessee, the ranking Republican member of the subcommittee, said even the basic promises of privacy and security from the company had failed users.
This week, her staff set up an experimental account for a fictional 15-year-old and were surprised to find the profile automatically set to public exposure. Instagram says teenage accounts automatically default to the private setting.
Mr. Mosseri acknowledged the error and said Ms. Blackburn’s office exposed a flaw in Instagram’s controls that sets teenage accounts that were created on a web browser — and not on a mobile app — to public. “We will correct that,” Mr. Mosseri said.
Mr. Blumenthal’s office has received hundreds of calls and emails from parents about their negative experiences with Instagram, he has said. One parent recounted how her daughter’s interest in fitness on Instagram led the app to recommend accounts on extreme dieting, eating disorders and self-harm.
Mr. Blumenthal has homed in on the algorithms, which he called “800-pound gorillas in black boxes,” that push such recommendations.
Lawmakers, including Mr. Blumenthal and Ms. Blackburn, have proposed stronger data privacy rules aimed at protecting children and greater enforcement of age restrictions. They have also called for young users to be able to delete information online. Lawmakers have pursued similar legislation before, with little success. Though lawmakers often show bipartisan unity in the hearings, dozens of data privacy bills have been stymied by intense industry lobbying and partisan disagreement over how stringent laws should be.
Senator John Thune, a Republican of South Dakota, has introduced a bill that would force companies to reveal more about their algorithmic ranking system. He asked if Instagram would allow users to rank their content chronologically, instead of through opaque decisions based purely on engagement.
Mr. Mosseri said the company was working on the feature, which could be available next year.
Though Mr. Mosseri repeated his support for regulations, he demurred when asked about specific proposals. He said he hadn’t read a bill introduced by Mr. Blumenthal and other lawmakers that could hold Meta liable for hosting harmful content. He wouldn’t commit to give up completely on the idea of building a version of the Instagram app for users under the age of 13. And he didn’t directly answer questions as to whether victims should be able to sue Meta for hosting sex-trafficking content.
Child advocacy groups said Mr. Mosseri failed to provide any greater assurances that Instagram would prioritize child safety.
“Today’s hearing was just more of the same: evasions, empty promises, and too-little, too-late gestures aimed at forestalling congressional action instead of meaningfully addressing Instagram’s harmful business model and design choices,” said Josh Golin, executive director of Fairplay.
Leaders of the subcommittee said they would hold additional hearings, which may include more executives of Meta. Mr. Blumenthal said Mr. Mosseri’s vague commitment for “directional” support on laws “doesn’t cut it.”
“This industry has said it is in favor of government regulation but they have opposed specific measures with armies of lawyers and lobbyists and tons of money,” Mr. Blumenthal said.
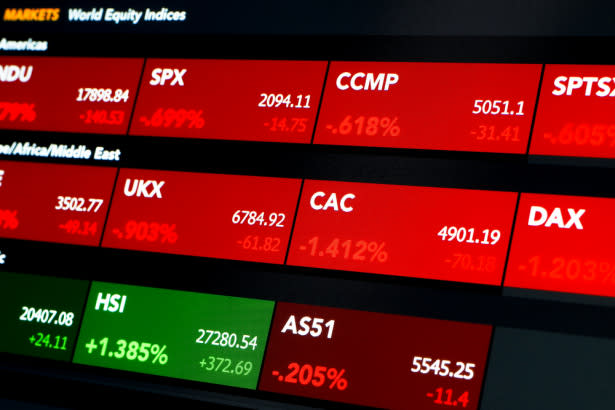
It was a bearish end to the week for the European majors on Friday.
The DAX30 slipped by 0.10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, with the CAC40 and EuroStoxx600 ending the day down by 0.24{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and by 0.30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} respectively.
Finalized inflation figures from Germany had a muted impact on the majors, with the markets focused on U.S inflation on the day.
Later in the European session, another pickup in inflationary pressure supported a more hawkish set of interest rate projections next week. What remains unclear, however, is how the FED sees inflation and the new Omicron strain impacting growth.
Away from the economic calendar, news updates from labs across the world remained a key area of interest. While early tests showed that vaccine efficacy was materially lower, there were also indications that the new strain was a milder form.
The Stats
It was a quiet day on the Eurozone economic calendar. Finalized German inflation figures were in focus going into the European open.
In November, German consumer prices fell by 0.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, which was in line with prelim figures. Consumer prices had risen by 0.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in October.
Germany’s annual rate of inflation accelerated from 4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 5.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, which was also in line with prelim figures.
The inflation rate increased for the 6th time in a row, reaching the highest level recorded in 2021.
A higher inflation rate was last recorded in Jun-1992, when the rate of inflation was 5.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
Compared with Nov-2020, energy prices were up 22.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, with prices for food up 4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
Excluding energy, Germany’s annual rate of inflation stood at 3.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
Prices for services increased by 2.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} compared with the same month a year earlier.
From the U.S
Inflation and consumer sentiment figures were in focus late in the European session.
In November, the U.S core annual rate of inflation picked up from 4.6{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 4.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, which was in line with forecasts. For the month of November, core consumer prices rose by 0.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, with consumer prices up 0.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
In spite of the pickup in inflation, consumer sentiment unexpectedly improved in December.
According to prelim figures, the Michigan Consumer Sentiment Index climbed from 67.4 to 70.4 versus a forecasted fall to 67.1. Hopes of a pickup in wage growth amidst rising prices supported improved sentiment.
The Market Movers
For the DAX: It was a mixed day for the auto sector on Friday. Continental rose by 1.10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to buck the trend.
Daimler tumbled by 13.82{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, however, with Volkswagen and BMW ending the day down by 1.00{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and by 0.73{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} respectively.
It was also a mixed day for the banks. Deutsche Bank fell by 0.82{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, while Commerzbank rose by 0.17{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
From the CAC, it was a bearish day for the banks. Soc Gen and Credit Agricole fell by 0.50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and by 0.65{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} respectively, with BNP Paribas declining by 1.24{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
The French auto sector had a mixed session, however. Stellantis NV rose by 0.26{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, while Renault ended the day down by 0.45{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.
Air France-KLM and Airbus SE avoided the red, rising by 0.43{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and by 0.08{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} respectively.
On the VIX Index
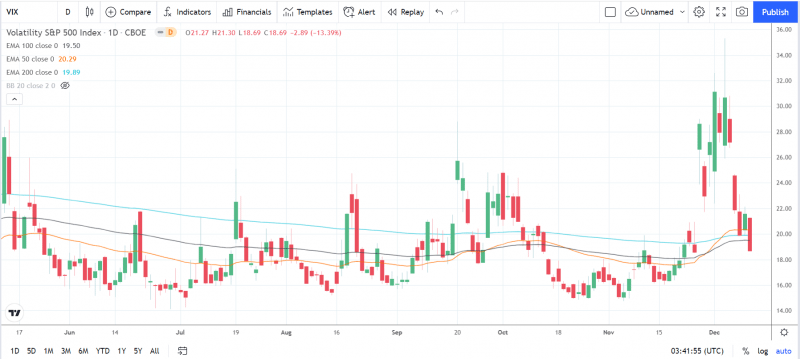
It was back into the red for the VIX on Friday, marking a 4th day in the red for the week.
Reversing an 8.44{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} rise on Thursday, the VIX slid by 13.39{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to end the day at 18.69.
The Dow ended the day up by 0.60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, with the NASDAQ and the S&P500 gaining 0.73{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} and by 0.95{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} respectively.
The Day Ahead
It’s a quiet day ahead on the Eurozone’s economic calendar. There are no material stats due out of the Eurozone to provide the majors with direction.
From the U.S, there are also no stats to consider, leaving the majors in the hands of OPEC’s monthly report and Omicron news updates.
With the FED in action on Wednesday and the ECB in focus on Thursday, it could be a testy start to the week.
The Futures
In the futures markets, at the time of writing, the Dow Mini was up by 31 points.
For a look at all of today’s economic events, check out our economic calendar.
The best personal finance advice is tailored to your individual situation. That said, a few rules of thumb can cut through the confusion that often surrounds money decisions and help you build a solid financial foundation.
The following guidelines for saving, borrowing, spending and protecting your money are culled from nearly three decades of writing about personal finance.
1. PRIORITIZE SAVING FOR RETIREMENT
In an ideal world, you’d start saving with your first paycheck and keep going until you’re ready to retire. You also wouldn’t touch that money until retirement. Even if you can’t save 15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your pre-tax income for retirement, as recommended by Fidelity and other financial services firms, anything you put aside can help give you a more comfortable future. Aim to take full advantage of any company match you get from a 401(k) at work — that’s free money — and borrow against or cash out retirement funds only as a last resort.
2. SAVE FOR A RAINY DAY
You may have read that you need an emergency fund equal to three to six months of expenses, but it can take years to save that much. That’s too long to put off other priorities, like saving for retirement. A starter emergency fund of $500 can be your first goal, and then you can build it up. While you’re saving, try to create other sources of emergency cash, such as a Roth IRA (you can pull out your contributions at any time without taxes or penalties), space on your credit cards or an unused home equity line of credit.
3. SAVE FOR COLLEGE
Got kids? Open a 529 college savings plan and contribute at least the minimum, which is typically $15 to $25 a month. Retirement savings comes first, but anything you can save will reduce how much your child may need to borrow. Also, research shows the simple act of saving for college increases the chances that a child from a low- to moderate-income family will go to college.
4. BORROW SMART FOR COLLEGE
A college degree can pay off in higher earnings, but lenders may allow you to borrow far more than you can comfortably repay. If you’re borrowing for your own education, consider limiting your total debt to what you expect to make your first year out of school. If you’re a parent borrowing for a child’s education, aim for payments that are no more than 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your after-tax income and that still allow you to save for retirement. If your payments are higher than 10{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of your after-tax income, investigate income-driven repayment plans that could bring down your costs.
5. USE CREDIT CARDS AS A CONVENIENCE
Credit cards offer convenience and can protect you from fraud and disputes with merchants. But credit card interest tends to be high, so don’t carry credit card balances if you can avoid it. If you routinely pay your balances in full, look for a rewards card with a sign-up bonus that returns at least 1.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of what you spend.
6. FINANCE YOUR HOME SMARTLY
If you want to be a homeowner, the best time to buy your first home is when you’re financially ready and in a position to stay put for a few years. Opt for a mortgage rate that’s fixed for as long as you plan to remain in the home, and don’t make extra payments against the principal until you’ve paid off all other debt and are on track for retirement.
7. BUY USED VEHICLES AND DRIVE THEM FOR YEARS
Buying a car right now isn’t a great idea; supply-chain kinks and other pandemic-related issues have inflated the cost of both new and used cars. In general, though, buying a used car can save you a ton of money over your driving lifetime, as can driving your car for many years before replacing it. These days, a well-maintained car can last 200,000 miles without major issues, according to J.D. Power. This means you can get roughly 13 years of service out of your car if you drive it 15,000 miles a year. Ideally, you would pay cash for cars. If you need to borrow, try to limit the term of your loan to a maximum of five years.
8. INSURE AGAINST CATASTROPHIC EXPENSES
Use insurance to protect yourself against catastrophic expenses rather than smaller costs that you can easily pay out of pocket. If you have sufficient savings, consider raising the deductibles on your policies to save money on premiums. Be careful about high-deductible health insurance policies, though. Having a high deductible could cause you to put off medical care, and it’s better to err on the side of safety when it comes to health.
This column was provided to The Associated Press by the personal finance site NerdWallet. The content is for educational and informational purposes and does not constitute investment advice. Liz Weston is a columnist at NerdWallet, a certified financial planner and author of “Your Credit Score.” Email: lweston@nerdwallet.com. Twitter: @lizweston.
RELATED LINK:
NerdWallet: Personal finance defined: The guide to maximizing your money https://bit.ly/nerdwallet-personal-finance-defined
While the pandemic has depressed travel, it may have encouraged travel insurance, say those in the industry.
“The biggest question we get from customers is: ‘What happens if I get COVID during travel and what if I have to quarantine?’” said Jeremy Murchland, the president of Seven Corners, a travel insurance management company. “COVID has created a much broader awareness of travel insurance.”
But will it help you in light of the new omicron variant, which has already led to new travel restrictions and requirements? In the early days of the pandemic, travel insurance largely failed to protect travelers who wanted or needed to cancel as the world shut down.
The following are answers to common questions about travel insurance now.
Does travel insurance cover COVID-19, including the new omicron variant? For the most part, yes, travel insurance policies now treat COVID-19 in all its variants — including omicron — like any other medical emergency.
“Consumers should know that most travel insurance plans with medical benefits now treat COVID like any other illness that you could contract while traveling or that could prohibit you from going on your trip,” said Carol Mueller, a vice president of Berkshire Hathaway Travel Protection. “If you become ill before your trip, you’ll need a doctor’s note confirming your illness and that you are unable to travel in order to be eligible for benefits. The benefits are the same regardless of whether you contract omicron, another variant of COVID or any illness for that matter.”
Buyers should read the policies carefully and look out for those that exclude pandemics, COVID-19 and its variants. To make a claim, you must have had travel insurance before becoming ill.
“We always say, you can’t buy auto insurance after you’ve already had an accident,” said Meghan Walch, the product manager of InsureMyTrip, an insurance sales site. “It is designed for unforeseen issues. You have to purchase it before an event.”
I am traveling internationally. If borders close because of omicron, am I covered through travel insurance?
No, most policies do not cover you if your foreign destination closes its borders to visitors, as Israel did recently. With a few exceptions, that also goes for a government-issued travel warning to a destination, which is generally not a covered reason to make a claim.
Given the added uncertainties of omicron, should I consider a ‘Cancel for Any Reason’ policy?
Cancel for Any Reason, or CFAR, provisions would allow you to claim some of your nonrefundable costs if you decide not to go on a trip for any reason, including border closures or fear of contracting COVID-19. The rub is that this form of insurance — in addition to being more expensive — must generally be purchased within a few weeks of booking the trip and will return only 50{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 75{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of nonrefundable trip costs.
“Most travel insurance policies do not cover you for wanting to cancel out of fear of COVID. We say this 10 times a week,” said Sarah Groen, the owner of the agency Bell and Bly Travel.
She counsels clients to consider their worst fears — illness, for example, or quarantine — in troubleshooting travel insurance.
“We’ve become like therapists,” she said.
What about quarantine and medical expenses? Make sure the policy you choose covers these. In the case of medical coverage, check with your regular health insurer; many policies will not cover you abroad, which is an additional reason to consider coverage if you are traveling internationally.
“What travel insurance can do is cover additional hotel stays if you are able to self-quarantine and additional airfare when you’re able to come home,” said Megan Moncrief, the chief marketing officer for Squaremouth, a travel insurance sales site.
She added that most policies will extend to seven days past your originally scheduled return date, effectively covering only about seven days in case of quarantine.
Do some destinations require travel insurance? Yes, primarily to cover medical care or quarantine accommodations in the event that a traveler tests positive for COVID-19. For example, Singapore requires medical insurance with a minimum coverage of 30,000 Singapore dollars, or about $22,000. Fiji requires travel insurance to cover potential treatment for COVID-19, and makes it available from about $30. Some destinations, such as Anguilla, recommend rather than require travel insurance. InsureMyTrip.com has a page devoted to countries that require travel insurance.
It bears thinking about what it would take to get home for treatment should you contract COVID-19 abroad. Thailand, for example, requires travelers to have medical insurance with the minimum coverage of $50,000.
“Evacuation out of Thailand would be higher,” said Sasha Gainullin, the CEO of Battleface, a travel insurance startup that unbundles benefits.
In the case of a Thailand trip, he advised taking medical coverage up to $100,000 for treatment locally and $500,000 for medical evacuation and repatriation.
Do I need insurance if I have bookings with flexible cancellation policies? Probably not, if you have hotel reservations that allow free cancellation 24-48 hours in advance. The same with flights; if your flight is changeable and will provide a voucher or refund in case of cancellation, you’re covered.
I have rented a house with restrictive cancellation penalties. Can I insure against those?
Yes. Vacation home rentals from Airbnb and the like can be treated just like other accommodations that do not offer refunds. In this case, you would want to get a policy in the amount you would forfeit if you had to cancel for a covered reason like illness. Again, fear of travel is not a covered reason; for that, you would need CFAR.