AZ Big Media Keys to selecting your business insurance broker

AZ Big Media Keys to selecting your business insurance broker

Getting suited coverage at the appropriate stage of protection is an critical aspect of every small business. Becoming underinsured or acquiring the erroneous small business insurance coverage broker can have devastating penalties.

The eyesight of a high quality small business coverage broker is to carry and restore rely on and religion in the approach empower shoppers to interact in the decision-earning system and know their advisor of alternative is doing work in their ideal fascination. 


Read through ALSO: Rating Arizona: Major 10 insurance plan brokers for 2022


It is not frequent for enterprises to routinely put their attorney and CPA out to bid, so why is it some corporations rely on this method when choosing their insurance broker?  There is substantial worth to the enterprise when the right broker is in location.

Enterprise insurance policy is complicated. It involves compliance and sector expertise. It must also adapt as the business enterprise evolves. Firms count on small business insurance policies to be there in the most dire of predicaments.

In get to restore believe in and faith in the system, hand choose your advisor relatively than enabling the most affordable bid insurance policies provider to determine your broker. 

Good reasons to operate with an impartial broker

Andrew Martinez is an Insurance policies Marketing consultant with The Arizona Group.

Doing the job with an impartial broker offer you with obtain to a large selection of coverage businesses to meet up with the needs of your organization. An impartial broker will tailor and negotiate protection on behalf of the client.

They are gurus in analyzing possibility and remain on best of latest market place situations. An impartial broker will often be there for you.

Good reasons to pick out a broker vs. the bid system

This is a experienced marriage very similar to what you have with your CPA and lawyer. An insurance policy broker is not just one more seller. He or she will also be a valued organization advisor.

Hold in head that a capable broker and his or her group will nutritional supplement your own administrative group. By undertaking so you will prevent hurrying in the ultimate days to challenge binders, certificates, vehicle ID cards, and payment, to title a several organization products.

You will experience as even though your organization is currently being taken treatment of for the fiscal financial investment you are producing. Instead than only sensation relieved that this exhausting system is around you will really feel self-assured about your determination and who you have decided on to operate with. 

Recommendations when deciding upon a broker

Just take command and commence the approach about five to 6 months prior to renewal of your coverage. Satisfy with brokers you would look at functioning with on a working day-to-day basis individuals with whom you can forge a partnership.

Through the job interview process question them about their experience, amount of client involvement, providers, abilities, the insurance coverage organizations they symbolize, and market-similar shoppers they presently serve. Slender the field to not far more than two brokers (including your incumbent).

At this issue you will have just one to two certified brokers from which to decide on. Allow each individual broker to assemble their proposal for your insurance method and include things like new concepts and ideas. Meet up with the broker’s service staff. These people today are essential to the variety procedure and will cope with most of the working day-to-day processes.

Last but not least, discuss with your crew which broker you favor. Do not allow for the low bid to establish who you find. Decide on the broker you sense will ideal complement your group.


Writer: Andrew Martinez is an Insurance Advisor with The Arizona Group. For extra data simply call Andrew at (480) 633-6679 or take a look at arizonagroup.com.
Why Ramit Sethi Said Costco Is ‘an Amazing Business’

Why Ramit Sethi Said Costco Is ‘an Amazing Business’
A man pushing a shopping cart through the aisles of a warehouse store.

Impression resource: Getty Illustrations or photos

A whole lot of men and women confident love it — together with one particular private finance expert.


Crucial points

  • Costco is identified for its dedication to affordable rates.
  • Joining Costco could be 1 of the savviest fiscal selections you make this year, mainly because a membership offers each benefit and great consumer support.

Costco is one of those retailers wherever you truly will not know what you happen to be missing right until you start browsing there. And you are not able to start out buying there until eventually you start spending for a membership.

The charge of a fundamental Costco membership proper now is $60. An upgraded govt membership will value you double, but you are going to also get 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} income again on all Costco purchases you make, form of like how you may possibly get 2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} income again on a credit card. So if you store at Costco usually, an govt membership could make a ton of perception.

Now, if you might be new to Costco, you will possibly want to start off with a basic membership and see how it goes. And if you’ve been emotion iffy about becoming a member of Costco, I would completely really encourage you to spring for a membership, particularly if you have a warehouse club retailer near to your residence.

My spouse and children routinely saves a substantial amount of income by buying at Costco. But don’t just choose my term for it. Economical guru Ramit Sethi is a massive supporter of Costco, far too. He even went so much as to tweet about how it’s an amazing organization. And this is why that’s true.

It is all about price

The cause so many people appreciate Costco boils down to the discounts and shopper provider the warehouse club huge is regarded for. Not only does Costco make a place to provide competitive price ranges, but it also goes earlier mentioned and further than to assure that clients are glad with the things they’ve acquired. And if not, Costco has a pretty generous refund coverage.

Costco is so dedicated to giving personal savings that if it are unable to do so, it simply just will not put a supplied item on its shelves. Sethi quoted Jim Sinegal, Costco co-founder and former CEO, in his tweet as getting claimed, “We have to be able to exhibit a cost savings on every little thing we provide. If we are unable to demonstrate a savings we will never carry it.”

That is a fairly reliable approach to supplying value. Several vendors would have no qualms about stocking an item which is overpriced and building a income on it. But it can be clear that Costco won’t want to work that way.

In actuality, if you happen to be an avid Costco shopper and have at any time seen that some of the products and solutions you made use of to purchase there are no lengthier in inventory, a rise in expense could be the purpose why. Costco may well have pulled people objects to prevent a scenario in which you might be not getting excellent worth for your funds.

A wise financial go

When I very first joined Costco, I was skeptical about the price savings associated. But now that I’ve been a member for additional than a decade, I can say with certainty that buying at Costco assists me feed my household and keep my house for a lot less funds.

If you’re on the fence about becoming a member of Costco, it could shell out to spring for a membership, especially at a time when foodstuff expenses are up so considerably owing to inflation. You happen to be possible to uncover that your membership a lot more than pays for itself, and that browsing at Costco aids you stretch your money throughout these economically hoping periods.

Even if you’re not acquiring a challenging time monetarily, all people enjoys saving dollars. And Costco’s main enterprise design is designed to assist you do plenty of that.

Notify: maximum cash back again card we’ve observed now has {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until finally 2024

If you are applying the wrong credit score or debit card, it could be costing you really serious money. Our specialist loves this best choose, which features a 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} intro APR until 2024, an crazy cash again rate of up to 5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, and all somehow for no annual fee. 

In fact, this card is so fantastic that our expert even takes advantage of it personally. Simply click listed here to examine our comprehensive evaluate for free and utilize in just 2 minutes. 

Read our free of charge evaluation

MLO Jobs; Reverse Mortgage Product; Consumer Finance Protection Bureau on ARMS and HELOCs

MLO Jobs; Reverse Mortgage Product; Consumer Finance Protection Bureau on ARMS and HELOCs

&#13

MLO Work opportunities Reverse Property finance loan Product Customer Finance Security Bureau on ARMS and HELOCs

&#13

My cat Myrtle (she/her/hers) does not have a lot of economical savvy, and to the very best of my know-how has no 401(k). In a different reminder not to place all of your internet worth, or retirement dollars, in a person place, Tesla has observed all-around $720B of shareholder worth vaporize this calendar year. Rivian truck stock, usually seen as in excess of-valued when it went community (audio familiar?), is down 89 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Rivian had a goal of production 50,000 electric pickup vans this year, perhaps hitting 25,000. Talking of producing, in our biz, a couple times a yr anyone wakes up to the point that made housing, like that built in a manufacturing facility under managed circumstances and a stable workforce, is a viable alternate to “regular” onsite construction. This time around it was Time Journal to emphasize this, a strategy that helps make so a lot feeling. (Ken S. studies that “We finance Modulars, but it is extremely challenging with the factory to basis process. We only fund after installation whilst the manufacturing facility expects payment when the home is on the truck.) We need something to spark points and was reminded by Barron’s that 2023 may deliver economic suffering extra pronounced than that in 2022. Inflation and curiosity costs are predicted to continue to be elevated, and the sustained strength of purchaser funds is predicted to wane. Nonetheless, economists say that any recession likely would be brief-lived and that favourable financial traits, these types of as amplified productiveness and industrial financial commitment, could arise. (Today’s podcast is coming from Candor Engineering. Dwelling of the A single Contact Underwrite, supporting loan companies from Point of Sale to Article Near QC, to reduce repurchase threat, increase underwriter efficiency by 400 per cent, and lower turn-situations by 10 times.

Broker Equipment

The retirement crisis is not going away! Sign up for Finance of The us Reverse LLC (Much) and incorporate reverse home loans to your business in 2023 so you can capture the mounting desire from a single of the major groups of homeowners in the US, guard your company in opposition to current market fluctuations with a solution that’s attractive in all level environments, and provide a product with designed-in protections. Much can assistance you stabilize your business and satisfy borrowers in which they are now with exclusive property equity goods that can assist debtors struggle inflation and continue being in their homes. Study more about Much and reverse home loans.

“Looking to get your items in entrance of far more folks and serve much more debtors in 2023? Obtain accessibility to countless numbers of new wholesale brokers rapidly and very easily with Lender Rate Marketplace. Developed to match loan providers with thousands of property finance loan brokers looking to locate the finest costs and plans for their debtors, Marketplace is just one of the most significant communities of wholesale brokers and loan providers in the mortgage market. Provide all of your products to the forefront and make it a lot easier for new brokers to find you. Loan providers of all sizes use Lender Marketplace to generate new leads, extend their reach inside the broker community, and showcase all of their financial loan programs like non-QM, non-company, different documentation, DSCR, HELOCs, and HELOANs. A number of leading banking companies and wholesale lenders are utilizing Marketplace to assist them present merchandise to added brokers outside of their network and acquire further insights on broker pricing habits via in-depth analytics. Go to our website to learn much more or ask for a demo right now to see it in action.”

Shopper Finance Security Bureau: What Holidays?

The CFPB just lately dealt with property finance loan financing options in look at of the latest bigger house loan loan curiosity fee atmosphere. The CFPB reviews on adjustable-price home loan (ARM) loans, momentary buydowns, property fairness strains of credit (HELOCs) and home equity financial loans, personal loan assumptions, and option financing alternatives. Though the CFPB notes the availability and characteristics of the distinct financing possibilities, it also warns consumers of prospective hazards. The CFPB notes that shoppers may perhaps be “wary of ARMs since of their purpose in the housing crisis and 2008 economic downturn.” Even so, the CFPB states that, when ARM loans are not chance-free, “ARMs these days appear really various than those of the before era. Right before the 2008 economic downturn, a lot of ARMs experienced mounted-price intervals of 3 yrs or much less. Right now most ARMs have set durations of 5, 7, or even 10 decades.”

Weiner Brodsky Kider studies that the CFPB issued a Recognize of Intent to Make TILA Preemption Determinations. The CFPB just lately revealed a detect of intent to decide no matter whether selected New York industrial financial law provisions are preempted by TILA, immediately after acquiring a ask for to do so from a organization trade affiliation.

The Purchaser Monetary Safety Bureau has issued a last rule amending the formal interpretations for Regulation Z, which implements the Fact in Lending Act (TILA). The Bureau is essential to compute yearly the greenback amounts for numerous provisions in Regulation Z. This closing rule evaluations greenback quantities for sure provisions applying TILA and amendments to TILA impacting HOEPA financial loans and competent home loans. These adjustments are relevant January 1, 2023, constant with pertinent statutory or regulatory provisions.

Cash Markets

Yesterday noticed some imbalanced actions involving the entrance and back ends of the generate curve, influencing adjustable level as opposed to 30-calendar year fixed level home loan pricing. The entrance finish confronted some mild providing pressure whilst the again finish captivated customers, leaving the 2s10s distribute now inverted by 54-foundation details. Yesterday’s trade involved a $35 billion 7-calendar year be aware auction that was satisfied with normal need. This week’s Main Mortgage Market place Study from Freddie Mac saw the 30-yr mortgage charge growing for the initially time given that the week ending November 10. For the week ending December 29, the common 30-year level rose to 6.42 percent.

As stated yesterday in the commentary, the labor current market continues to demonstrate resilient in spite of other steps of weak point. Original Jobless statements ticked up 9k to 225k last 7 days. Continuing jobless promises improved by 41k to 1.71 million, the optimum since February and up noticeably since September when continuing promises had been hovering all over 1.35 million. The most recent report suggests that the limited labor sector is demonstrating some indicators of loosening centered on the time it is having for displaced staff to discover new positions.

Today’s lone financial facts position of take note just before the early close is Chicago PMI for December. We commence the previous buying and selling working day of 2022 with Company MBS rates unchanged from Thursday night and the 10-yr yielding 3.84 immediately after closing yesterday at 3.83 {1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

Employment and Transitions

“It’s a New Calendar year and a new start off! To contend in 2023, Personal loan Officers will want to improve their efficiency and reduced their prices by using D1C, SSV, DVS, and CU scores in their bank loan workflow. Do not know those acronyms? Your level of competition does! Get in touch with MegaStar to see how our superior-tech and high touch assists our profitable Personal loan Officers. Aggressive rates count on acquiring a low price-to-create. We want to display you how we can help you improve your business enterprise in 2023. MegaStar is actively recruiting Loan Officers and Department Managers. We really do not have any recruiting gimmicks we just want to empower you to compete and increase your business! If you want the finest tech, aggressive pricing, and special programs, speak to us or pay a visit to us.”

From Seattle comes information that Flyhomes has appointed Andrea Collins as Chief Internet marketing Officer and Dan Richards as Executive Vice President of Mortgage. Richards will “lead the Flyhomes Home loan and Closing enterprises, overseeing solutions and products and services including the Flyhomes Money Offer you, which turns daily buyers into all-income customers, and Get Before You Offer, which allows customers to invest in their future home just before marketing their recent property, saving time, power and revenue.”

Why average investors got crushed in 2022: Morning Brief

Why average investors got crushed in 2022: Morning Brief

This article first appeared in the Morning Brief. Get the Morning Brief sent directly to your inbox every Monday to Friday by 6:30 a.m. ET. Subscribe

Friday, December 30, 2022

Today’s newsletter is by Myles Udland, senior markets editor at Yahoo Finance. Follow him on Twitter @MylesUdland and on LinkedIn. Read this and more market news on the go with Yahoo Finance App.

The most challenging year for investors since the financial crisis will mercifully come to an end on Friday.

All manner of superlatives can capture the damage done to portfolios the world over, but we think two charts from LPL Research circulated earlier this week show why no one had it harder than mom and pop in 2022.

And the biggest challenge for the average saver came in two forms from one place: the bond market.

The bond market hasn’t had a year this bad in two generations.

The Bloomberg Aggregate U.S. Bond Index was down 13.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2022 through December 28, its worst year since inception in 1976.

And it’s not even close.

Before 2022, the index’s worst year came in 1994… when it dropped just 2.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

The U.S. bond market has never had a year worse than 2022, according to the most popular index for tracking the overall market. (Source: LPL Research)

The U.S. bond market has never had a year worse than 2022, according to the most popular index for tracking the overall market. (Source: LPL Research)

As investors well know by now, the dominant market story this year was the Federal Reserve’s historic increase in interest rates.

The central bank raised interest rates by a cumulative 4.25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in 2022 — from a range of 0{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}-0.25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in January to 4.25{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}-4.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} as of December — the most since 1980. And further increases are expected next year.

As a result, yields across the Treasury curve rose sharply, weighing on prices in both government and private bond markets. At the outset of 2022, the yield on the U.S. 10-year Treasury stood at just north of 1.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}; by late October, the 10-year yield was closer to 4.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. As of this week, the 10-year yield was around 3.85{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

And the move in 2-year yields, which tend to be more sensitive to the path of Fed rate hikes, was even more dramatic, rising from around 0.75{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} at the beginning of the year to 4.3{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} as of this week.

Which raises another challenge for investors and the economy heading into 2023: the inversion of the yield curve. Ahead of each of the last 8 recessions in the U.S. the yield on the 2-year Treasury note has eclipsed the yield on the 10-year.

Today, the 2-year yield is about 0.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} above the 10-year, signaling trouble for the economy in 2023. But recession risks and whether the bond market will ultimately be “right” about the economy’s path is a topic that will get plenty of run in 2023.

Because whether the economy turns south or not, the damage has already been done to average portfolios in 2022.

With bonds suffering their worst year on record, it follows that the classic “60/40 portfolio” comprised of 60{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} stocks and 40{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} would also struggle.

And according to LPL, 2022 marks the second-worst year on record for this strategy going back to the inception of the Bloomberg Agg in 1976. Through the close on December 28, a hypothetical 60/40 portfolio comprised of the S&P 500 and the Bloomberg Agg would be down 16.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, a decline only topped by 2008’s 20.1{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

The classic

The classic “60/40” portfolio with a mix of stocks and bonds has only suffered losses larger than 2022’s decline once in the last 45 years. (Source: LPL Research)

Eclipsed only by 2008’s losses — a year in which the S&P 500 fell 38{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}, which makes this year’s 20{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} decline feel quaint — the decline suffered by 60/40 portfolios will hit average investors hard because of the predominance of this strategy as relatively safe way to earn a modest return.

Moreover, 2008’s decline was more than entirely driven by the drop in stocks — in 2008, the Bloomberg Agg actually rose 5.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Bonds, in other words, did offer some support against a plunge in stocks. In 2022, the story has been anything but.

Writing earlier this year about why the so-called “death” of the 60/40 portfolio is overstated, Roger Aliaga-Díaz, chief economist, Americas and head of portfolio construction at Vanguard, wrote: “The goal of the 60/40 portfolio is to achieve long-term annualized returns of roughly 7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. This is meant to be achieved over time and on average, not each and every year.”

Aliaga-Díaz’s work showed that since 1976, investors have never seen a three-year rolling period in which stocks and bonds lost money. Over that period, only 6.5{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of the time has any trailing three-year period for 60/40 portfolios shown negative returns.

Source: Vanguard

Source: Vanguard

As ever, time in the market outweighs efforts to time the market.

But a one-year drop over 16{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in one of the most widely-used ways average investors organize their portfolios is hardly overcome by assurances that market history is on their side.

With thousands of Americans retiring every day, many will find their financial standing notably degraded relative to the optimism put forth by market returns in 2019, 2020, and 2021.

And left hoping Wall Street’s downbeat view on 2023 is proven wrong.

What to Watch Today

Economy

Earnings

—

Click here for the latest stock market news and in-depth analysis, including events that move stocks

Read the latest financial and business news from Yahoo Finance

Download the Yahoo Finance app for Apple or Android

Follow Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, and YouTube

Cal-Maine Foods income, sales reach record highs

Cal-Maine Foods income, sales reach record highs

RIDGELAND, Overlook.  — Cal-Maine Food items obtained record highs in internet profits and internet income in the second quarter finished Nov. 28 as no positive assessments for very pathogenic avian influenza (HPAI) were being identified at manufacturing services.

Net earnings of $198.6 million, equal to $4.08 per share on the frequent stock, in comparison with $1.17 million, or 2¢ for every share, in the preceding year’s next quarter. Web sales of $801.7 million ended up up 110{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from $381.7 million.

“These outcomes replicate the existing market place natural environment characterised by record typical providing rates for regular eggs, principally because of to lowered offer relevant to the outbreak in the US of remarkably pathogenic avian influenza (HPAI), and excellent shopper need,” claimed Sherman Miller, chief government officer, when final results were being declared Dec. 28. “There have been no beneficial exams for HPAI at any of Cal-Maine Foods’ owned or contracted production services as of Dec. 28, 2022. Client demand for shell eggs continued to be fantastic in the quarter, especially major up to the Thanksgiving holiday, and we skilled file quarterly volume ranges for specialty eggs bought.”

Irrespective of the outcomes, Cal-Maine Foods’ stock on the Nasdaq was investing at $54.51 per share late in the morning on Dec. 29, down 12{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from a near of $62.19 on Dec 28 and down 15{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} from a close of $63.78 on Dec. 27. Media experiences mentioned next-quarter outcomes came in underneath Wall Street forecasts.

HPAI ongoing to impression the sector negatively in the quarter. The complete number of birds, like chickens and turkeys, culled in the United States stood at 52.5 million by the finish of November, which was over the approximated 50 million birds in 2015, according to the US Office of Agriculture’s Animal and Plant Health and fitness Inspection Services.

Dozens of eggs sold at Cal-Maine Meals in the next quarter greater 5.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to 284.1 million from 269.6 million. While standard egg volumes offered lowered 2.2{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} when when compared with the past year’s 2nd quarter, specialty egg volumes increased 24{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}. Cage-free of charge mandates that went into outcome on Jan. 1, 2022, in California and Massachusetts even more supported need.

“Conventional egg web normal marketing cost for each dozen amplified to $2.883 when compared with $1.151 a year in the past, and both conventional and specialty egg earnings reached file degrees for the 2nd quarter of fiscal 2023,” stated Max Bowman, chief economic officer for Cal-Maine Meals. “Net typical offering price for specialty eggs rose 24.9{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $2.370 per dozen, in comparison with $1.898 for every dozen for the next quarter of 2022. We observed our maximum at any time quarterly profits of specialty eggs of $227.8 million, or 29.4{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of total shell egg income. Specialty dozens bought had been 33.8{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of full dozens bought as opposed with 28.7{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in the prior-yr period of time.”

Cal-Maine Food items dealt with increased expenditures across inputs these as feed, labor, packaging and distribution in the quarter. Farm product expenditures per dozen eggs rose 22{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} in contrast to the prior year’s next quarter, primarily since feed fees elevated 30{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a}.

Cal-Maine Food items expects the HPAI outbreak will keep on to effects the offer of eggs negatively. The duration of the influence will depend in component by how prolonged it can take to replenish the layer hen flock in the United States. The five-12 months typical for the layer hen flock from 2017-21 was about 328 million hens. A LEAP Industry Analytics report issued on Dec. 8, 2022, tasks the layer hen inventory to not exceed 382 million hens right until December 2023.

Around the 1st two quarters of the fiscal year, Cal-Maine Foods had web income of $323.9 million, or $6.66 per share on the prevalent inventory, which when compared with a decline of $16.9 million in the exact same time of the prior 12 months. Web revenue over the to start with two quarters rose 106{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} to $1.46 billion from $706.7 million.

Teenager Promotes Financial Literacy in Youth with Personal Finance Education

Teenager Promotes Financial Literacy in Youth with Personal Finance Education
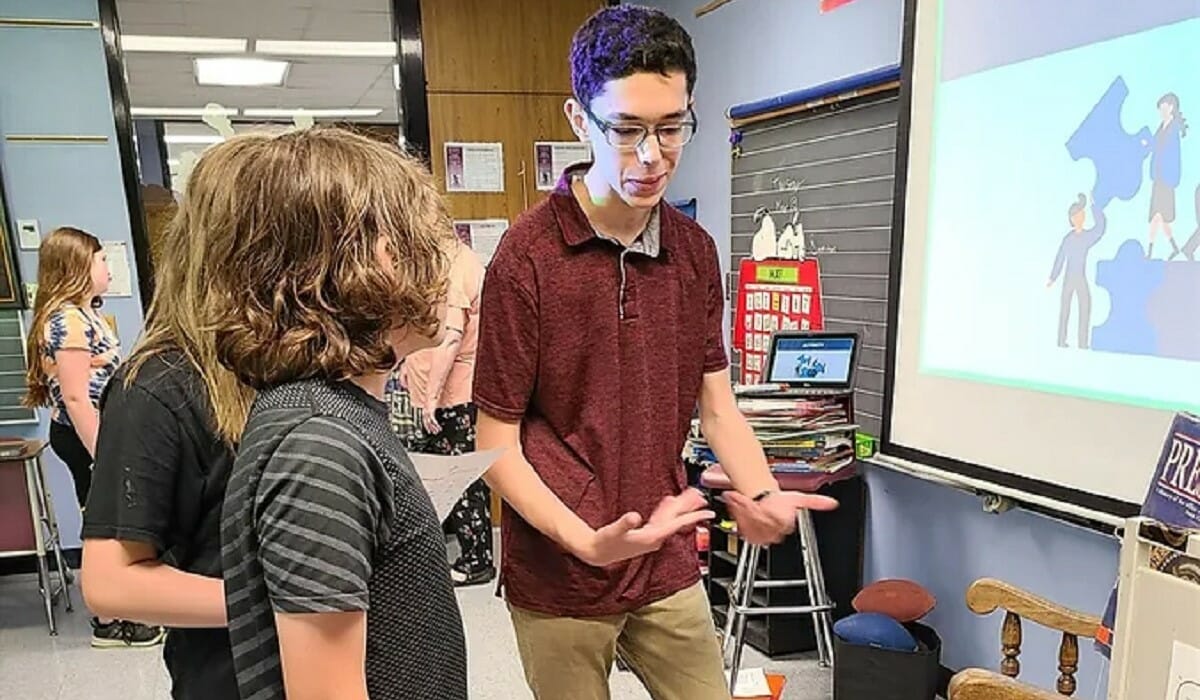
Isaac explains a economical concept to a young learner./Courtesy Isaac Hertenstein

Meet up with Daily Place of Gentle Award honoree Isaac Hertenstein. Examine his story and nominate an remarkable volunteer or family members as a Every day Place of Light-weight.

A lot of adults go away school and are stunned to uncover out how difficult taxes can be and don’t understand matters like how to commit in the stock market. Many thanks to Isaac Hertenstein, pupils in Greencastle, Indiana and further than are graduating with a bigger amount of financial literacy than at any time ahead of.  

You never see many superior schoolers with a fiery passion for personalized finance, but Isaac, a sixteen-year-outdated runner and ethics enthusiast, breaks the mildew. Even in center college, his center university know-how and entrepreneurship trainer, Brittany Labhart, remembers observing his curiosity peaking. 

“I saw in sixth and seventh [grade] that he was unquestionably interested in it, but in eighth quality I observed a substantial alter. Which is when we talk about small business and own finance,” she remembers. “He is an wonderful kid who has been driven from a pretty younger age” 

The pretty following calendar year, Isaac resolved to share the understanding he found so intriguing with other folks. So, as a freshman in significant school, he formed his 501(c)(3), Pupils Educating Finance. 

“A large amount of inspiration for Pupils Instructing Finance (STF) was from observing the financial inequality in my neighborhood and the influence of monetary literacy in combatting that as nicely as mending a hole in training,” Isaac suggests. “Indiana is not 1 of the 15 states that necessitates monetary literacy [as part of the curriculum].”  

The states with the necessity commonly require learners to get at minimum a person semester of own finance in purchase to graduate from superior school. With this is head, Isaac took motion. Initially, he delved into dialogue with numerous local community leaders and economic and education and learning specialists. Then, he designed a 30-site curriculum for students from kindergarten by eighth quality with the mission to provide a foundation for results and to motivate young ones to look at economic professions. He also hopes to start discussions in between learners in the classroom and at residence. 

How does it operate? Isaac recruits volunteers amongst his peers to teach quick Lights Classes, just about every concentrating on an age-ideal core notion. Given that he started Pupils Instructing Finance, Isaac has taught around 575 college students in his hometown and has all over 30 volunteers teaching on a common foundation. These classes—and their teachers—leave lasting impressions.

Isaac Hertenstein, founder of Pupils Training Finance./Courtesy Isaac Hertenstein

“He begun off by inquiring them if they’d alternatively have so substantially revenue right now as opposed to so considerably in 10 several years, and he described how compound desire operates,” Brittany states of a lesson Isaac taught in her classroom. “It surely sparked dialogue afterward, and pupils had been definitely intrigued in what he experienced to say.” 

Moms and dads can frequently be listened to telling volunteers that their children have been chatting about the classes for months afterward. Academics are also acquiring in line to implement his lessons on their own. Soon after functioning with Isaac for on STF for the past two years, the economics trainer at his large faculty applied his lessons in her curriculum for seniors. 

And the enthusiasm is creating its way all over the place. 

“I’ve labored with over 250 other volunteers about the place in 14 diverse states who have applied this curriculum and commenced chapters of Learners Instructing Finance in their communities,” Isaac suggests proudly. “ I’m attempting to unfold economic literacy and commence chapters in other superior colleges. Of system, just one of our primary ambitions is advocating for financial literacy legislation.” 

Aiming to have a systemic effect, Isaac and STF has been in talks with several advocacy teams marketing fiscal literacy laws in Indiana.  

“In this article in Putnam County, we have a fairly superior poverty price, and to instruct youngsters at all ranges the worth of own finance with basic ideas that it’s possible they are not receiving at residence, he can support them to make clever selections in the potential,” Natalie states. 

Isaac cites that developmental researchers have proven that young ones begin forming a financial mentality at age five. 

“They observe quite a few of the fiscal expending and saving behavior that their dad and mom and people today bordering have them, and they subconsciously undertake all those practices,” he states. 

Isaac hopes his courses and emphasizing the time worth of revenue will aid get ready people kids as they get more mature and deal with economical issues like paying for faculty and retirement. Sad to say, not anyone is so fortunate. 

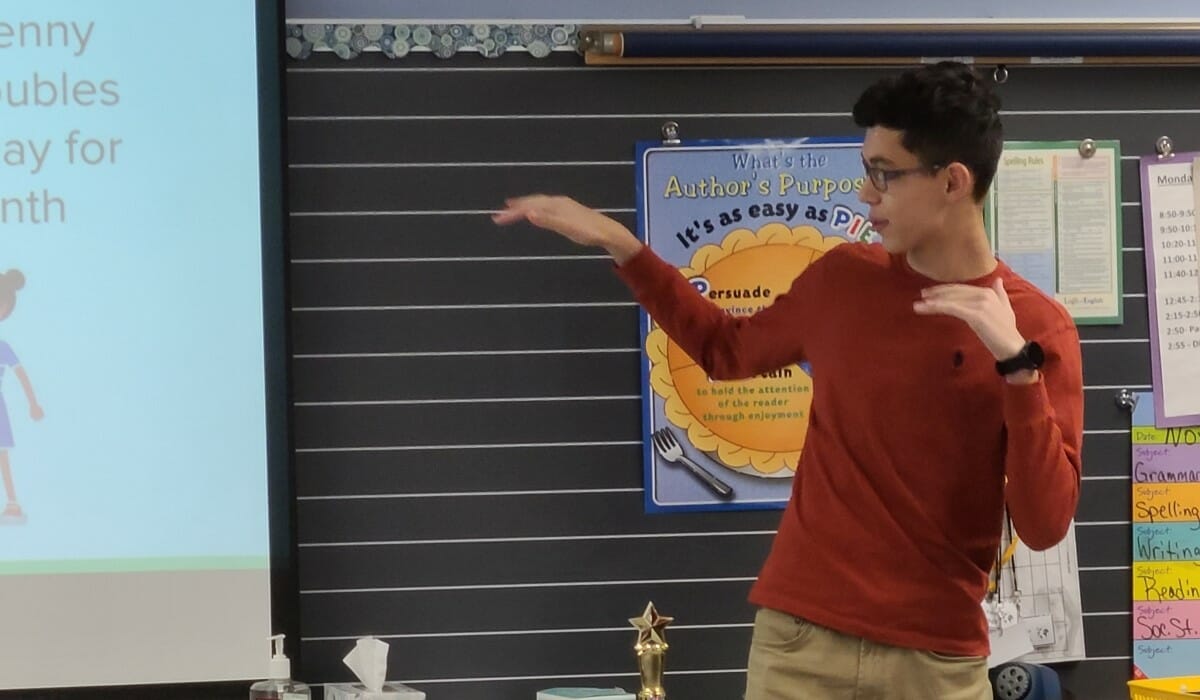
Isaac prospects a class on finance./Courtesy Isaac Hertenstein

“In accordance to a research from UPenn Wharton, which arrived out about 5 yrs ago, one particular-thirs of economic inequality is prompted by–not just joined to–differences in monetary literacy,” he cites. “Financial disparities and expertise definitely catalyze a substantial big difference in economic output and effects in the pretty conclusion. A great deal of it has to do with financial sector inclusion and setting up up belongings in excess of time.” 

Impressed by his mom, a very first-grade teacher who styles the minds that will have favourable influence on the long term, Isaac is pretty forward-wondering. As he seeks to build a vocation at the level exactly where ethics, small business, and social effect blend, he typically thinks of the potential of his business. He hopes to grow STF’s attain by teaming up with FinPro Entire world, a company that results in on the internet discovering courses for middle to higher university-aged students, as nicely as recruit more faculty-aged volunteers to educate.  

“72{1b90e59fe8a6c14b55fbbae1d9373c165823754d058ebf80beecafc6dee5063a} of mother and father do not talk to their youngsters about money.” Isaac suggests. “Finance is from time to time a taboo matter, but it is these an vital principle that lots of men and women disregard when meeting other people, and if they have been to examine it, it would actually just catalyze a lot more finding out for all people.“ 

Do you want to make a big difference in your group like Isaac? Come across area volunteer prospects.